
 Global IoT Solutions and Services Market | 2026-2036
Global IoT Solutions and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT Solutions and Services Market Foresight
The shift from single-source to multi-source IoT platform procurement is expanding as enterprises diversify vendor risk across cloud and edge infrastructure. Microsoft Corporation leverages its Azure IoT ecosystem to anchor hybrid deployment contracts with industrial clients. Cisco Systems, Inc. competes through specialized network connectivity layers that integrate with legacy operational technology. Amazon Web Services, Inc. dominates cloud-based device management with serverless architectures that reduce latency for connected vehicle fleets.
IoT solutions and services encompass sensor-integrated hardware, connectivity protocols, data processing platforms, and managed security frameworks that transmit operational telemetry between physical assets and centralized analytics engines. Edge computing deployments process data locally using sub-50 millisecond latency thresholds to support real-time industrial control loops. Security services command premium positioning as manufacturing end users confront ransomware exposure across unpatched legacy controllers. Data analytics segments sustain above-average margins where predictive maintenance algorithms reduce unplanned downtime for utilities and transportation operators.
The EU AI Act classifies autonomous IoT decision systems as high-risk applications requiring conformity assessments before market placement. Japan's METI enforces JIS standards for industrial IoT interoperability that shape procurement specifications for precision agriculture and energy management deployments. Stakeholders must monitor how divergent data sovereignty frameworks fragment cross-border platform architectures and force localized edge infrastructure investments.
Market Dynamics
Edge-native architectures are compressing latency thresholds below 50 milliseconds, forcing platform vendors to reconfigure data processing workflows and security frameworks around distributed compute nodes rather than centralized cloud ingestion.
Growth Catalysts
- EU AI Act compliance mandates:High-risk classification of autonomous IoT decision systems accelerates demand for conformity-assessed edge security modules in manufacturing and transportation deployments.
- Japan METI JIS standards:Industrial interoperability specifications for precision agriculture and energy management create procurement pull for certified sensor networks and protocol gateways.
- Predictive maintenance algorithms:Utilities and transportation operators deploy machine-learning models on vibration and thermal telemetry to compress unplanned downtime intervals.
Market Restraints
- Silicon supply concentration:Advanced sensor microcontrollers and edge AI accelerators depend on fabrication capacity concentrated in Taiwan and South Korea, exposing procurement timelines to geopolitical friction.
- GDPR data localization:Cross-border telemetry flows face sovereignty fragmentation, forcing redundant edge infrastructure investments that inflate total deployment costs.
- Legacy controller patching gaps:Unpatched operational technology systems in industrial facilities create ransomware exposure that constrains insurance coverage availability.
Strategic Opportunities
- India precision agriculture:BIS certification pathways and PLI scheme incentives for IoT-enabled irrigation and crop monitoring systems open underpenetrated rural deployment channels.
- Digital twin convergence:Real-time sensor feeds fused with physics-based simulation models enable closed-loop optimization in German automotive and Japanese robotics manufacturing.
- Serverless device management:Cloud-native architectures reduce latency for connected vehicle fleets, creating white space in fleet telematics and autonomous logistics orchestration.
Industry Challenges
- Embedded security engineering talent:Shortage of firmware developers with cryptographic implementation expertise delays edge-native security architecture rollouts.
- Multi-protocol integration complexity:Industrial facilities must bridge OPC-UA, MQTT, and proprietary legacy fieldbus standards without disrupting continuous production cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT Solutions and Services Market |
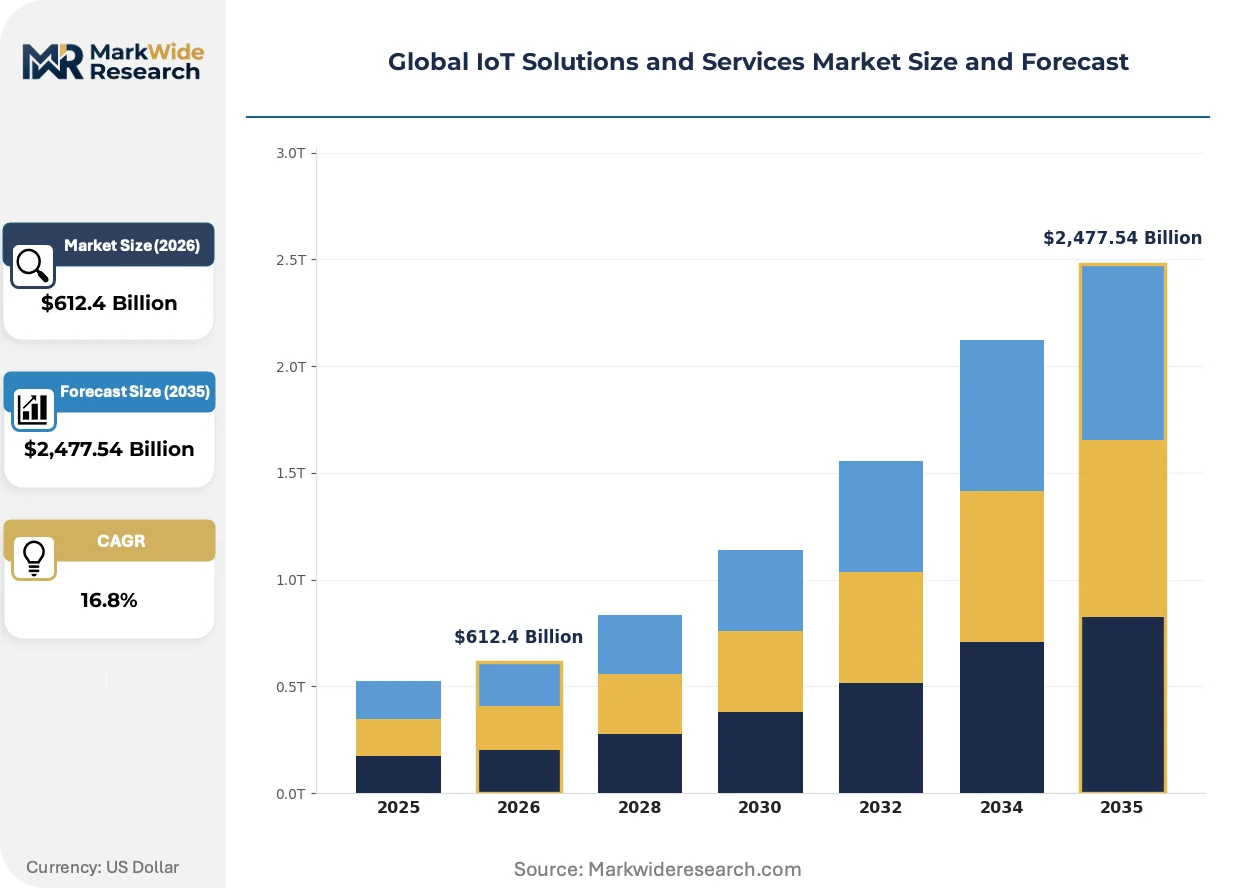
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $2,477.54 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution/Offering: Device Management, Data Analytics, Security Services, Network Connectivity, Application Enablement, Consulting Application: Smart Cities, Precision Agriculture, Energy Management, Supply Chain Monitoring, Connected Vehicles, Smart Retail End User: Manufacturing, Telecommunications, Transportation, Public Sector, Utilities, Consumer Electronics |
| Companies Covered | Microsoft Corporation, Cisco Systems, Inc., IBM Corporation, Amazon Web Services, Inc., Siemens AG, Oracle Corporation, SAP SE, Intel Corporation, Accenture plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT Solutions and Services Market Shifts & Advancements
Platform vendors are rearchitecting around distributed compute nodes as latency requirements tighten and regulatory data sovereignty fragments cross-border cloud architectures into localized edge deployments.
Time-sensitive networking (TSN) standards are overtaking proprietary industrial Ethernet protocols in automotive and semiconductor manufacturing facilities. German automotive OEMs and Japanese precision equipment makers are adopting IEEE 802.1 TSN for sub-millisecond motion control synchronization. This convergence is compressing vendor lock-in and enabling multi-vendor sensor interoperability that previously required gateway translation layers.
The EU AI Act's high-risk system classification is reshaping conformity assessment workflows for autonomous IoT decision systems. Industrial automation vendors must complete notified body evaluations before market placement of predictive quality control and safety-critical robotics controllers. German manufacturing integrators and French energy utilities are front-loading compliance documentation to secure first-mover positioning in regulated European deployments.
Enterprise buyers are consolidating device management under hybrid cloud-edge contracts rather than single-source platform subscriptions. Industrial clients in the United States and Japan are negotiating multi-vendor agreements that split telemetry ingestion between Azure IoT and specialized edge orchestrators. This unbundling is visible most acutely in smart manufacturing RFPs where procurement teams separate connectivity layer contracts from analytics platform licenses.
Global IoT Solutions and Services Market Segmentation
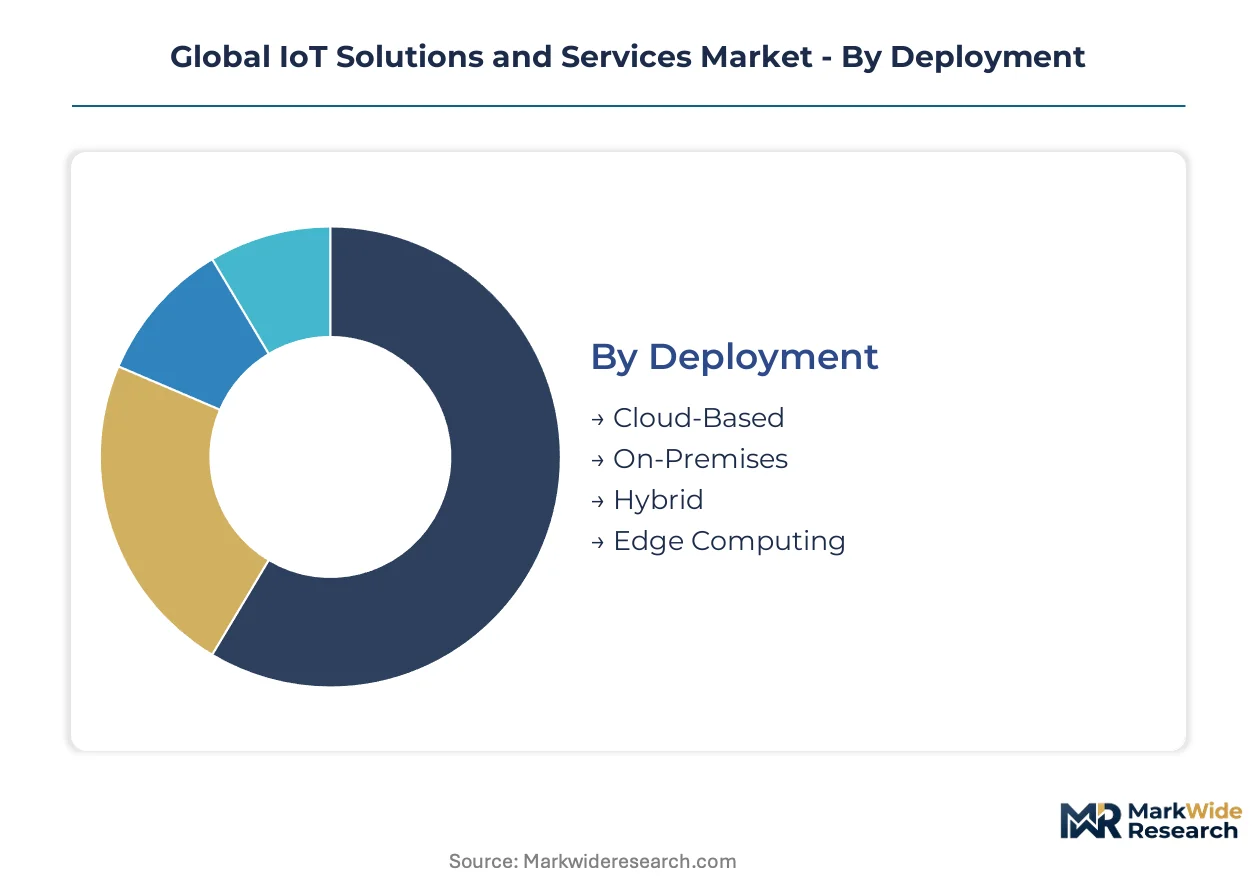
Deployment architecture determines latency performance and regulatory compliance scope for IoT implementations. Solution portfolios differentiate between commodity connectivity and high-margin predictive analytics. Application focus and end-user verticals shape procurement specifications and integration complexity.
Deployment:
Volume concentrates in centralized cloud ingestion while premium positioning shifts toward distributed edge nodes that compress response times below 50 milliseconds.
- Cloud-Based:Centralized telemetry ingestion using hyperscale serverless architectures reduces infrastructure overhead for connected vehicle fleets and smart retail deployments. Demand clusters with transportation operators in the United States and Japan seeking elastic scaling without capital-intensive edge hardware.
- Edge Computing:Localized data processing on sub-50 millisecond thresholds supports real-time industrial control loops and autonomous decision systems. German automotive OEMs and Japanese robotics manufacturers drive procurement for EU AI Act-compliant edge-native security modules.
- Hybrid:Split workloads between cloud analytics and edge preprocessing balance cost against latency requirements for utilities and telecommunications operators.
- On-Premises:Fully isolated infrastructure serves defense and critical infrastructure operators with data sovereignty mandates.
Today's leader: Cloud-Based. Tomorrow's challenger: Edge Computing.
Solution/Offering:
Margin stratification separates commodity device management from predictive analytics and security services that command premium positioning.
- Security Services:Embedded cryptographic frameworks and firmware hardening address ransomware exposure across unpatched legacy controllers in industrial facilities. Manufacturing end users in Germany and Japan pay premiums for conformity-assessed modules meeting EU AI Act and METI JIS standards.
- Data Analytics:Machine-learning models processing vibration and thermal telemetry compress unplanned downtime for utilities and transportation operators. German energy utilities and Japanese precision agriculture deployers represent concentrated demand for predictive maintenance algorithms.
- Device Management:Lifecycle orchestration for sensor fleets at scale.
- Network Connectivity:Protocol translation and gateway integration bridging OPC-UA, MQTT, and legacy fieldbus standards.
- Application Enablement:Low-code platforms accelerating vertical solution development.
- Consulting:Integration services navigating multi-protocol complexity and compliance documentation.
Security Services and Data Analytics capture expanding share as manufacturing clients unbundle connectivity from intelligence layers.
Application:
Procurement maturity varies sharply between established smart city frameworks and emerging precision agriculture channels.
- Precision Agriculture:IoT-enabled irrigation and crop monitoring systems leverage India's BIS certification pathways and PLI scheme incentives to penetrate underdeveloped rural deployment channels. METI JIS standards shape specifications for Japanese energy management and agricultural automation procurement.
- Smart Cities:Integrated sensor networks for traffic, waste, and environmental monitoring deploy at scale in German municipal frameworks and United States metropolitan utilities. GDPR data localization requirements fragment cross-border architectures and force redundant edge infrastructure investments.
- Energy Management:Grid optimization and demand response systems for utilities.
- Supply Chain Monitoring:Asset tracking and condition monitoring across logistics networks.
- Connected Vehicles:Fleet telematics and autonomous logistics orchestration.
- Smart Retail:Inventory optimization and customer analytics for commercial operators.
Precision Agriculture is climbing the fastest as subsidy frameworks activate rural deployment.
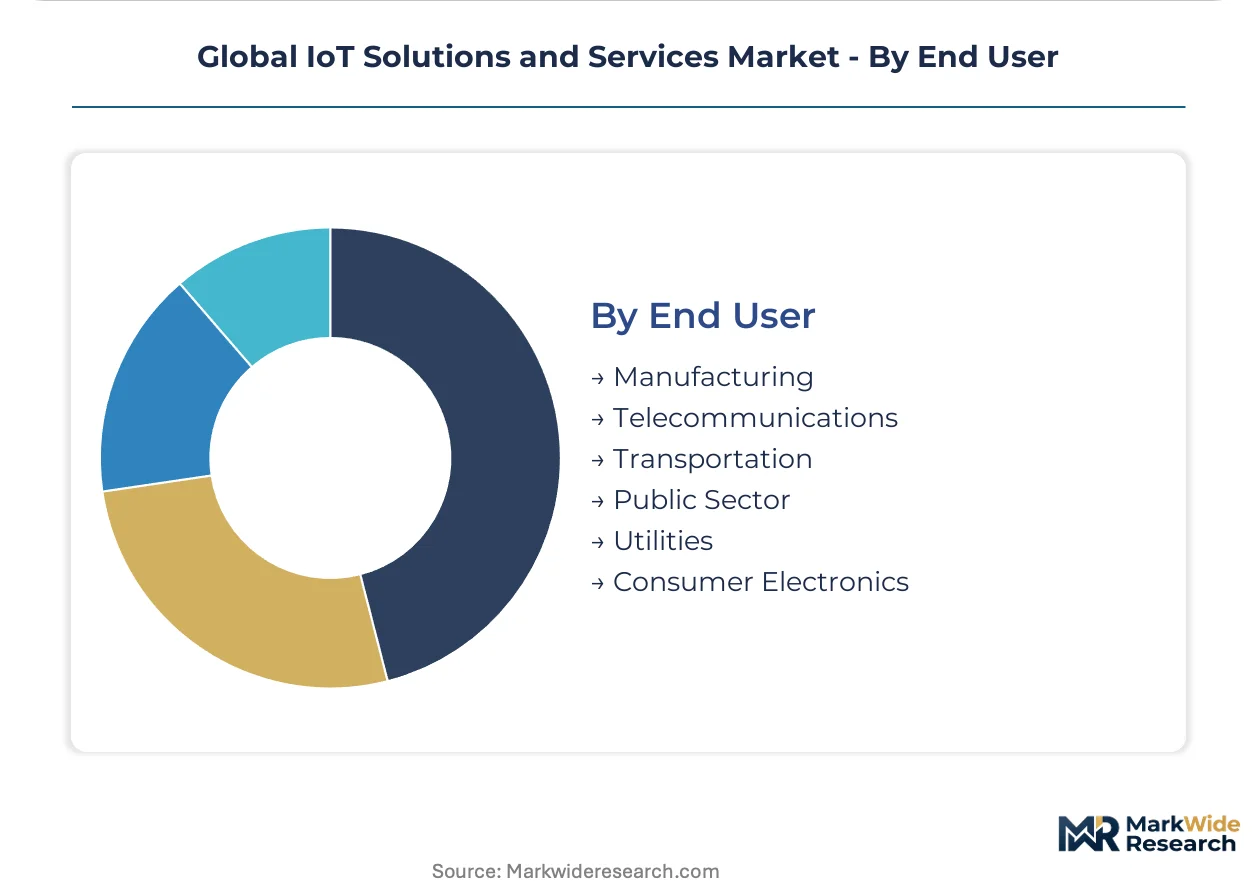
End User:
Vertical integration depth and procurement sophistication separate industrial automation leaders from consumer electronics volume plays.
- Manufacturing:Smart factory deployments integrate connected sensor networks for predictive maintenance workflows and digital twin convergence with physics-based simulation models. German automotive and Japanese robotics manufacturing represent the most advanced procurement specifications for TSN-standard motion control synchronization.
- Transportation:Connected vehicle fleets and logistics orchestration demand sub-50 millisecond latency thresholds. United States fleet operators and Japanese autonomous logistics developers drive serverless device management procurement.
- Telecommunications:Network infrastructure monitoring and edge computing enablement.
- Utilities:Grid modernization and predictive maintenance for generation and distribution assets.
- Public Sector:Smart city and critical infrastructure deployments with sovereignty requirements.
- Consumer Electronics:Mass-market connected devices with standardized connectivity protocols.
Manufacturing anchors current value capture. Transportation is gaining share fastest as autonomous systems mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions creates compliance-cost arbitrage that steers IoT platform deployment toward markets with clearer certification pathways. Enterprises optimize edge infrastructure location against data sovereignty mandates and conformity assessment timelines.
United States
Transportation operators and utilities drive serverless device management procurement for connected vehicle fleets and grid modernization. FCC spectrum allocations for industrial IoT and NHTSA autonomous vehicle guidance shape connectivity specifications. Fleet telematics clusters in Michigan and California compress latency thresholds below 50 milliseconds for logistics orchestration.
Germany
Automotive OEMs and precision equipment manufacturers anchor demand for time-sensitive networking standards and digital twin convergence. EU AI Act high-risk system classification accelerates conformity assessments for predictive quality control systems. Industrial automation corridors in Bavaria and Baden-Württemberg deploy TSN-standard motion control synchronization across multi-vendor sensor networks.
Japan
Robotics manufacturers and precision agriculture deployers concentrate procurement for METI JIS-certified interoperability modules. METI enforces industrial IoT standards that shape specifications for energy management and agricultural automation. Manufacturing clusters in Nagoya and Osaka integrate edge-native security architectures for autonomous decision systems.
India
Rural deployment channels for precision agriculture expand under BIS certification pathways and PLI scheme incentives for IoT-enabled irrigation systems. CEA grid codes and TRAI spectrum frameworks enable smart metering and demand response infrastructure. Agricultural technology hubs in Maharashtra and Karnataka penetrate underdeveloped rural markets with subsidized sensor networks.
South Korea
Semiconductor and electronics manufacturers drive edge AI accelerator procurement for sub-50 millisecond industrial control loops. MFDS medical device regulations and MIIT-aligned industrial standards shape smart factory specifications. Advanced manufacturing complexes in Gyeonggi-do and Seoul Capital Area deploy predictive maintenance algorithms on vibration telemetry.
Global IoT Solutions and Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized edge orchestration and sector-specific analytics layers. The vendor base stratifies between hyperscale cloud platforms, industrial automation incumbents, and network connectivity specialists. Three archetypes dominate: infrastructure-anchored ecosystems, protocol-centric connectivity vendors, and vertical solution integrators. Competitive moves concentrate on hybrid contract unbundling and multi-vendor partnership structures that split telemetry ingestion between cloud and edge layers.
Within the infrastructure-anchored tier, Microsoft Corporation and Amazon Web Services, Inc. represent hyperscale platform providers that negotiate hybrid deployment contracts with industrial clients. Cisco Systems, Inc. exemplifies the connectivity-specialist archetype, occupying a position between legacy operational technology integration and emerging time-sensitive networking standards. These three entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Cisco Systems, Inc. |
| IBM Corporation |
| Amazon Web Services, Inc. |
| Siemens AG |
| Oracle Corporation |
| SAP SE |
| Intel Corporation |
| Accenture plc |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between EU AI Act-compliant edge security modules and commodity device management tiers splits both pricing power and component sourcing strategies across the vendor base. Premium positioning for conformity-assessed firmware draws from specialized semiconductor foundries in Taiwan and South Korea, while standard connectivity layers compete on volume scale from broader Asian assembly networks.
Pricing Analysis
Distributor margins for edge-native security modules run 35-50% above commodity device management due to embedded cryptographic engineering requirements and METI JIS certification costs. Three-tier pricing structure across premium conformity-assessed, standard interoperable, and economy connectivity-only levels reflects divergent buyer sophistication. Cost compression in the standard tier is intensifying because hyperscale cloud providers bundle basic device management below standalone vendor economics. Transportation operators in the United States exhibit lowest price sensitivity for sub-50 millisecond latency guarantees, while Indian precision agriculture deployers prioritize subsidized hardware acquisition.
Supply Chain Analysis
Advanced sensor microcontrollers and edge AI accelerators rest on fabrication capacity concentrated in Taiwan, South Korea, and the United States. Silicon wafer supply, specialty memory components, and precision analog front-ends feed from concentrated foundry networks with limited second-source alternatives. Single-source vulnerability for sub-10nm process nodes exposes procurement timelines to geopolitical friction and export control uncertainty. Distribution runs through authorized component distributors serving industrial automation OEMs, with direct contracts anchoring volume for German automotive and Japanese robotics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
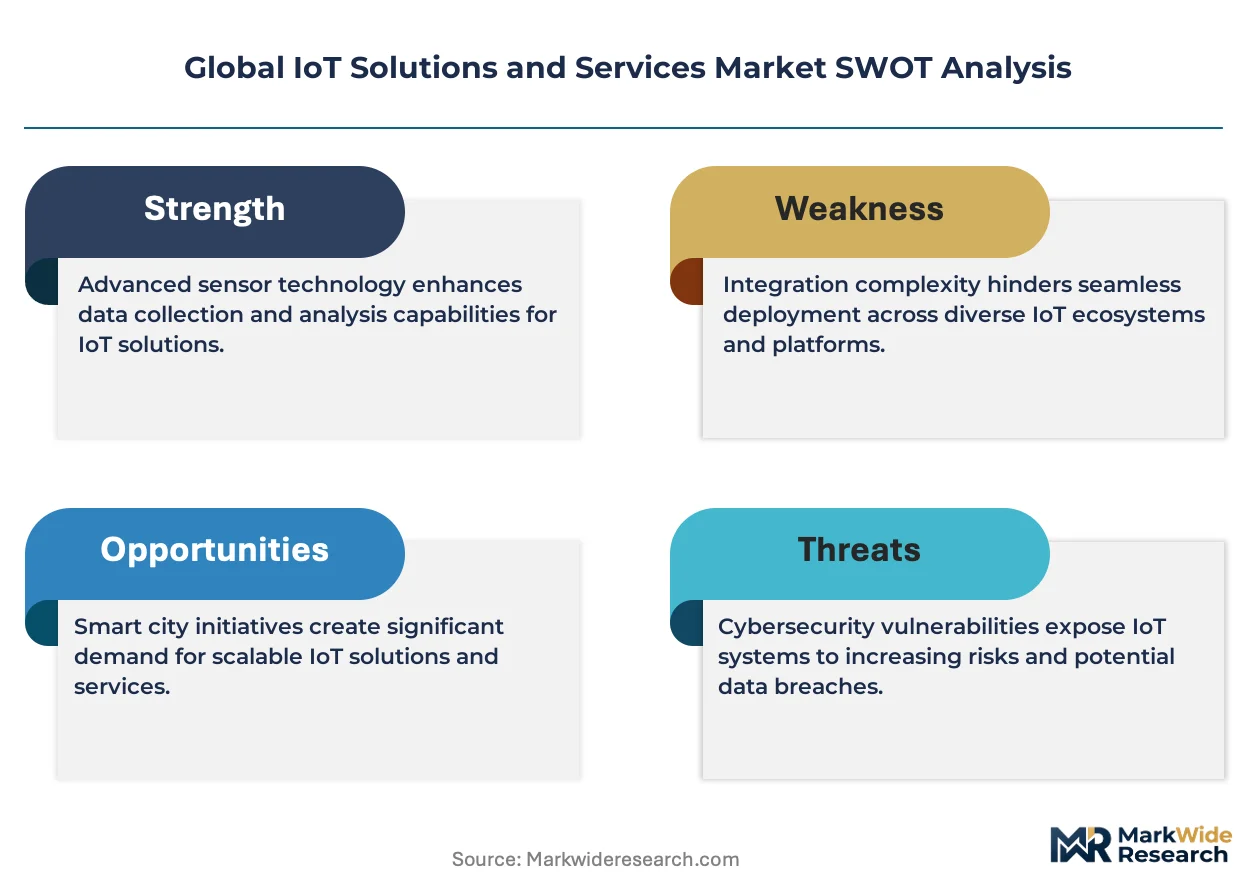
This market reads as a late-cycle quality story where procurement teams unbundle intelligence layers from connectivity, favoring vendors with demonstrable EU AI Act conformity documentation and METI JIS certification depth.
For Market Incumbents: Cement hybrid contract structures that lock telemetry ingestion across Azure IoT and specialized edge orchestrators before emerging platform vendors capture manufacturing RFP unbundling momentum. Prioritize backward integration into edge AI accelerator design to reduce foundry concentration exposure in Taiwan and South Korea. Defend margin position through firmware hardening capabilities that address ransomware exposure in unpatched legacy controllers.
For New Entrants and Emerging Players: Enter via India's precision agriculture channels where BIS certification pathways and PLI scheme incentives lower barrier-to-entry against established industrial automation incumbents. Target underpenetrated rural irrigation monitoring deployments in Maharashtra and Karnataka with subsidized sensor network economics. Pursue serverless device management white space in connected vehicle fleet telematics through direct partnerships with United States logistics operators seeking elastic scaling without capital-intensive edge hardware.
For Investors and Strategic Acquirers: Consolidation pressure builds where embedded security engineering talent scarcity delays edge-native architecture rollouts for mid-tier industrial automation vendors. Long-term viability favors platforms with demonstrated multi-protocol integration expertise bridging OPC-UA, MQTT, and legacy fieldbus standards. Acquisition target archetype: vertical solution integrators with METI JIS-certified module portfolios and established German automotive OEM relationships. Monitor EU AI Act notified body evaluation backlogs as inflection indicator for first-mover compliance positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Hybrid cloud-edge contracts split telemetry ingestion between hyperscale infrastructure and specialized orchestrators for manufacturing clients. |
| Certification Investment | EU AI Act conformity assessments and METI JIS standard compliance anchor premium positioning in regulated European and Japanese deployments. |
| Strategic Partnership | Multi-vendor agreements separate connectivity layer contracts from analytics platform licenses in smart manufacturing procurement. |
| Acquisition of Specialist Firm | Edge-native security architecture vendors with cryptographic firmware expertise address ransomware exposure in industrial facilities. |
| Geographic Expansion | India precision agriculture channels leverage BIS certification pathways and PLI scheme incentives for rural sensor network penetration. |
Research Methodology
Direct dialogue with IoT platform engineering directors, industrial automation procurement leads, edge security firmware developers, and hyperscale cloud solution architects grounded qualitative assessment. Secondary validation drew from SEC filings of infrastructure-anchored ecosystem providers, METI JIS standard documentation, EU AI Act regulatory texts, and customs data for semiconductor component trade flows. Bottom-up and top-down triangulation cross-checked deployment volume estimates against solution provider revenue disclosures and end-user procurement survey responses.
Segmentation outputs across deployment architecture, solution portfolio, application vertical, and end-user industry dimensions structured the analytical framework over the projection horizon. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory mandate acceleration effects and silicon supply constraint scenarios. Model inputs incorporated edge computing latency threshold requirements, EU AI Act high-risk system classification timelines, and precision agriculture subsidy framework activation schedules.
Inputs from industrial automation OEMs and cloud platform providers were available through the study window; gaps in unpatched legacy controller inventory data and ransomware incident reporting introduce uncertainty bands around security services demand forecasts. A small set of triggers—including EU AI Act notified body capacity constraints, Taiwan semiconductor export control developments, and India PLI scheme disbursement pacing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Europe Cellular IoT Market
Internet of Things (IoT)
Wireless Connected Devices Market
Internet of Things (IoT)
North America Industrial IoT Market
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
IoT Software Engineering Market
Internet of Things (IoT)
IoT Services Market
Internet of Things (IoT)
IoT in Manufacturing Market
Internet of Things (IoT)
IOT in Aviation Market
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
US Smart Thermostat Market
Internet of Things (IoT)
IoT at Workplace Market
Internet of Things (IoT)
Satellite IoT Communication Market
Internet of Things (IoT)
Global Embedded Security for Internet of Things Market