
 IoT Smart Poles Market | 2026-2036
IoT Smart Poles Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Smart Poles Market Insights
Transportation authorities is repositioning as the fastest-rising buyer vertical, displacing traditional municipal procurement patterns in early-adopter corridors. Signify Holding leverages its luminaire heritage to dominate European retrofit cycles. Telensa anchors large-scale UK deployments through managed-service contracts. Valmont Structures extends its structural steel expertise into integrated pole-electronics assemblies for North American highway corridors.
IoT smart poles are steel or aluminum mast structures embedding sensors, communication modules, and edge computing nodes, typically supporting 30-150W LED arrays with power-over-Ethernet or hybrid solar-grid feeds; they function as distributed urban infrastructure nodes for traffic management, public safety, and connectivity densification. LED poles and smart surveillance poles carry the deepest margin pools due to component integration complexity and software layering requirements. Cellular technology backhaul now outpaces Wi-Fi for highway and suburban installations where mesh density proves uneconomical.
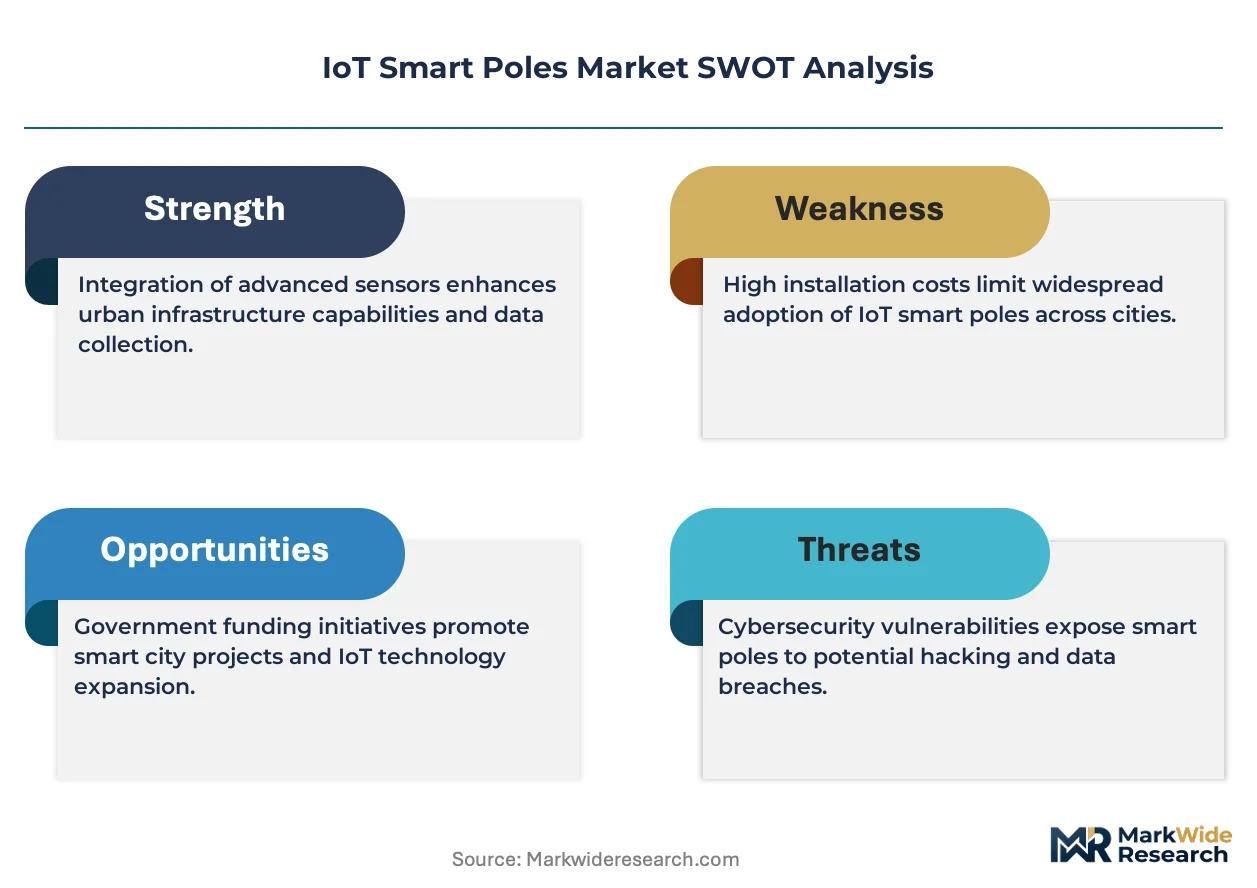
FCC broadband infrastructure rulings shape US deployment timelines, while EU Green Deal efficiency thresholds and CE marking mandates filter market access for European tenders. India's BIS certification and Smart Cities Mission procurement frameworks create structured demand pathways for foreign suppliers. Stakeholders must monitor which regulator moves first on standardizing open-interoperability protocols, as this will determine whether integrated-platform vendors or modular component suppliers capture the next wave of municipal contracts.
Market Dynamics
Cellular backhaul integration is forcing a wholesale reconfiguration of pole-electronics architecture, as transportation authorities and municipal buyers demand carrier-grade connectivity density over legacy Wi-Fi mesh economics.
Growth Catalysts
- Urban energy efficiency mandates:EU Green Deal thresholds and India's Smart Cities Mission procurement frameworks create binding compliance pathways that accelerate LED-retrofit timelines and sensor-node deployment.
- Edge computing densification:Traffic management authorities in South Korea and Vietnam now specify on-pole GPU modules for real-time video analytics, expanding addressable hardware attach rates.
- FCC broadband infrastructure rulings:US pole-access pricing reforms and dig-once mandates compress deployment timelines for highway corridor densification projects.
Market Restraints
- Aluminum and steel input volatility:Structural mast fabrication costs fluctuate with commodity indexes, squeezing margin pools on fixed-price municipal tenders.
- CE marking complexity:EU electromagnetic compatibility and radio equipment directive testing extends certification cycles by 4-8 months for multi-radio pole assemblies.
- Legacy sodium-vapor substitution ceiling:Rural and secondary road networks in India retain functional HPS infrastructure with limited near-term replacement economics.
Strategic Opportunities
- India's BIS certification pathway:Foreign suppliers securing domestic testing laboratory partnerships gain preferential access to state-level smart city tenders.
- Power-over-Ethernet convergence:Integrated LED-driver and sensor-power architectures reduce cabling complexity and enable solar-hybrid retrofits in grid-unreliable zones.
- Transportation authority procurement:Highway corridor deployments in Vietnam and South Korea now outpace traditional municipal streetlight volumes for connected infrastructure.
Industry Challenges
- Multi-protocol integration complexity:Municipal IT departments lack embedded systems expertise to harmonize legacy SCADA, new 5G small cell, and edge-AI workloads on unified pole controllers.
- Open-interoperability standardization delays:Fragmented IEEE, ETSI, and TIA working groups prolong procurement uncertainty as buyers defer to proprietary integrated platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Smart Poles Market |
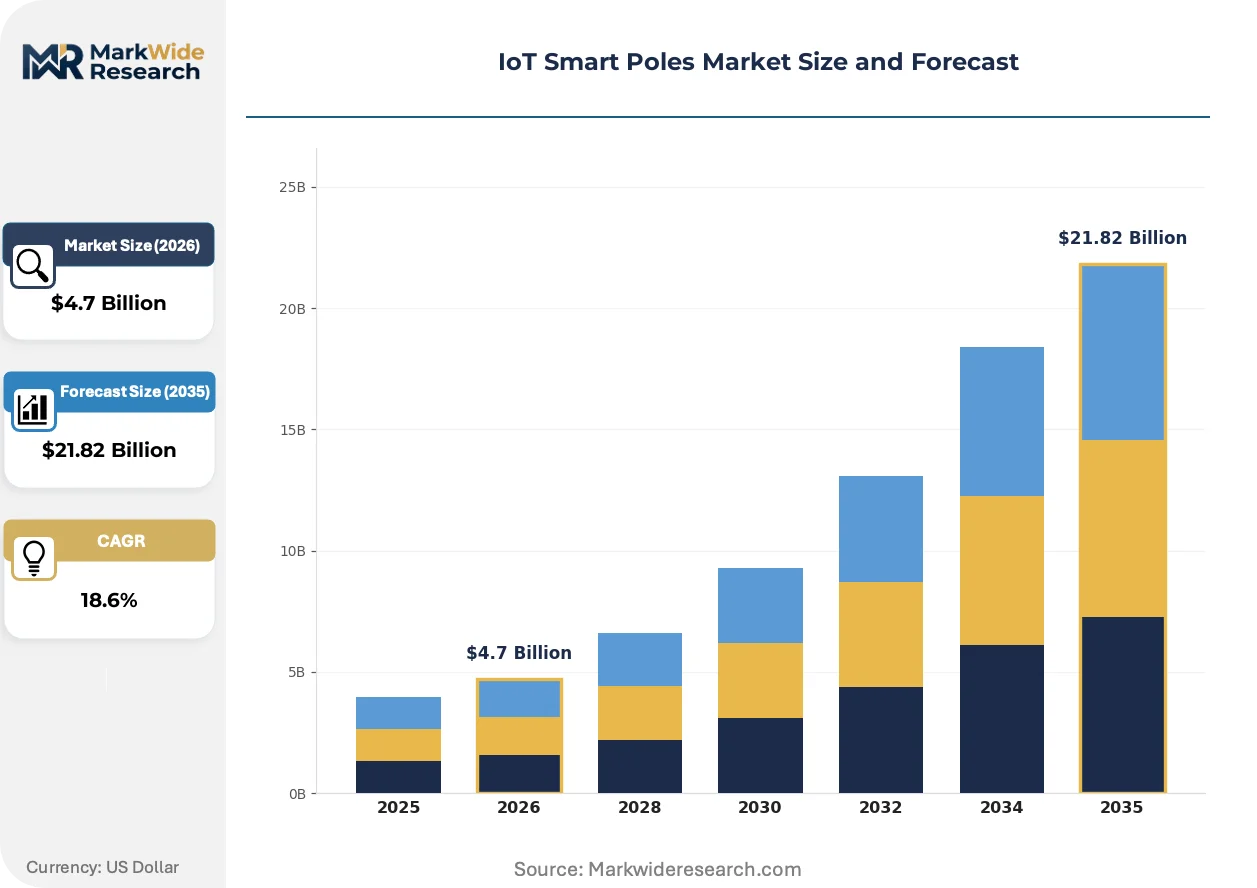
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Poles, LED Poles, Access Control Poles, Smart Surveillance Poles Technology: Wi-Fi, LoRaWAN, Zigbee, Cellular Technology Installation Type: Urban Areas, Suburban Areas, Highways, Parks End User: Municipalities, Transportation Authorities, Smart City Developers, Private Enterprises |
| Companies Covered | Silver Spring Networks, Omniflow, Signify Holding, Zumtobel Group, Valmont Structures, Cree, Schréder, Iram Technologies, Telensa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Smart Poles Market Trends and Innovations
Hardware disaggregation and software-layer monetization are redrawing competitive boundaries, as pole vendors reposition from luminaire suppliers to distributed infrastructure platform operators.
Edge-AI video analytics modules are modularizing pole-mounted computing architectures, enabling transportation authorities to upgrade inference capability without mast replacement. South Korean highway operators now specify hot-swappable GPU sleds for seasonal traffic-pattern retraining. This modularity is compressing hardware refresh cycles from seven-year luminaire lifespans to three-year compute upgrade intervals.
EU AI Act risk-classification rules now capture public-space facial recognition deployments, forcing pole-integrators to document algorithmic transparency and human-in-the-loop governance. German traffic authorities have paused biometric analytics tenders pending clarity on high-risk system designations. The compliance burden is favoring European vendors with established data-governance engineering teams over Asian hardware specialists.
Managed-service contracting is displacing capital-purchase models in UK and Australian deployments, with municipalities paying per-connected-node monthly fees. Telensa and infrastructure funds now capture recurring revenue streams that hardware vendors forfeit. This shift concentrates buyer relationships with platform operators capable of end-to-end SLA underwriting across 10-15 year contract horizons.
IoT Smart Poles Market Segmentation
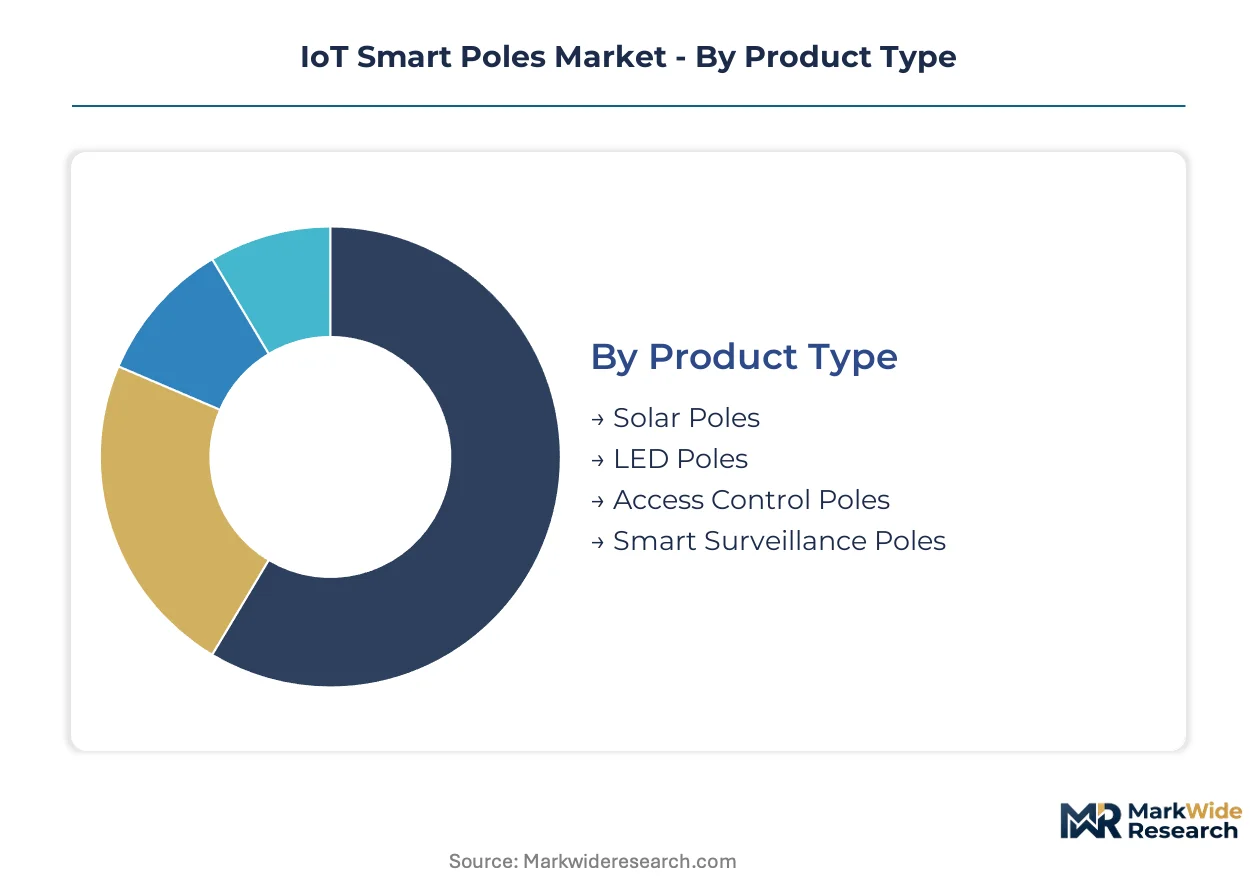
Product architecture, connectivity protocol, deployment environment, and procurement authority each reshape margin structures and vendor selection criteria across the IoT smart poles landscape. Understanding how demand fragments across these dimensions clarifies where platform vendors can capture recurring revenue versus one-time hardware sales.
Product Type:
Supply concentration tilts toward integrated assemblies that bundle luminaire heritage with embedded electronics capability.
- LED Poles:These assemblies combine high-efficiency solid-state lighting with sensor mounting infrastructure and power distribution architectures, typically supporting 30-150W arrays with PoE or hybrid solar-grid feeds. Demand clusters in European retrofit cycles driven by EU Green Deal efficiency mandates, where municipal tenders specify multi-function pole platforms over single-purpose replacements.
- Smart Surveillance Poles:Purpose-built masts integrate edge computing nodes, thermal cameras, and acoustic sensors for real-time public safety analytics. Transportation authorities in South Korea and Vietnam now specify these for highway corridor densification, displacing traditional municipal streetlight procurement volumes.
- Solar Poles:Off-grid-capable structures with integrated photovoltaic panels and battery storage for deployment in grid-unreliable zones.
- Access Control Poles:Pedestrian and vehicle entry management nodes with credential readers, barrier controls, and intercom systems.
LED poles absorb the bulk of installed capacity; smart surveillance poles are expanding most quickly.
Technology:
Cost tier differentiation separates legacy mesh protocols from carrier-grade backhaul investments.
- Cellular Technology:4G LTE and 5G small cell backhaul modules mounted directly on pole structures enable dense connectivity coverage without fiber trenching. Highway deployments in North America and suburban corridors across India favor this technology where Wi-Fi mesh density proves uneconomical and FCC pole-access rulings accelerate deployment timelines.
- LoRaWAN:Low-power wide-area networking modules support long-range sensor telemetry with minimal energy draw, ideal for environmental monitoring and parking management. Smart city developers in Vietnam leverage LoRaWAN for cost-constrained urban sensor networks where high-bandwidth applications remain secondary.
- Wi-Fi:Legacy public access and municipal mesh networking standard, now losing share to cellular in greenfield highway projects.
- Zigbee:Short-range protocol for localized device clustering and building-automation integration at pole edge.
Cellular technology commands the highest attachment rates in new-build corridors; LoRaWAN is gaining share fastest in retrofit sensor overlay projects.
Installation Type:
Application context determines structural load requirements, foundation specifications, and electronics environmental hardening.
- Highways:High-mast installations with reinforced steel structures, vibration resistance, and extended spacing between nodes. Transportation authorities specify these for corridor densification projects, with procurement volumes now outpacing traditional municipal streetlight tenders in Vietnam and South Korea.
- Urban Areas:Dense pole spacing with multi-sensor integration, pedestrian-scale lighting, and traffic signal coordination requirements.
- Suburban Areas:Intermediate density deployments balancing coverage extension with infrastructure cost constraints.
- Parks:Lower-priority installations with aesthetic design requirements and limited connectivity density needs.
Highway installations concentrate the steepest expansion trajectory; urban areas retain the largest installed base.
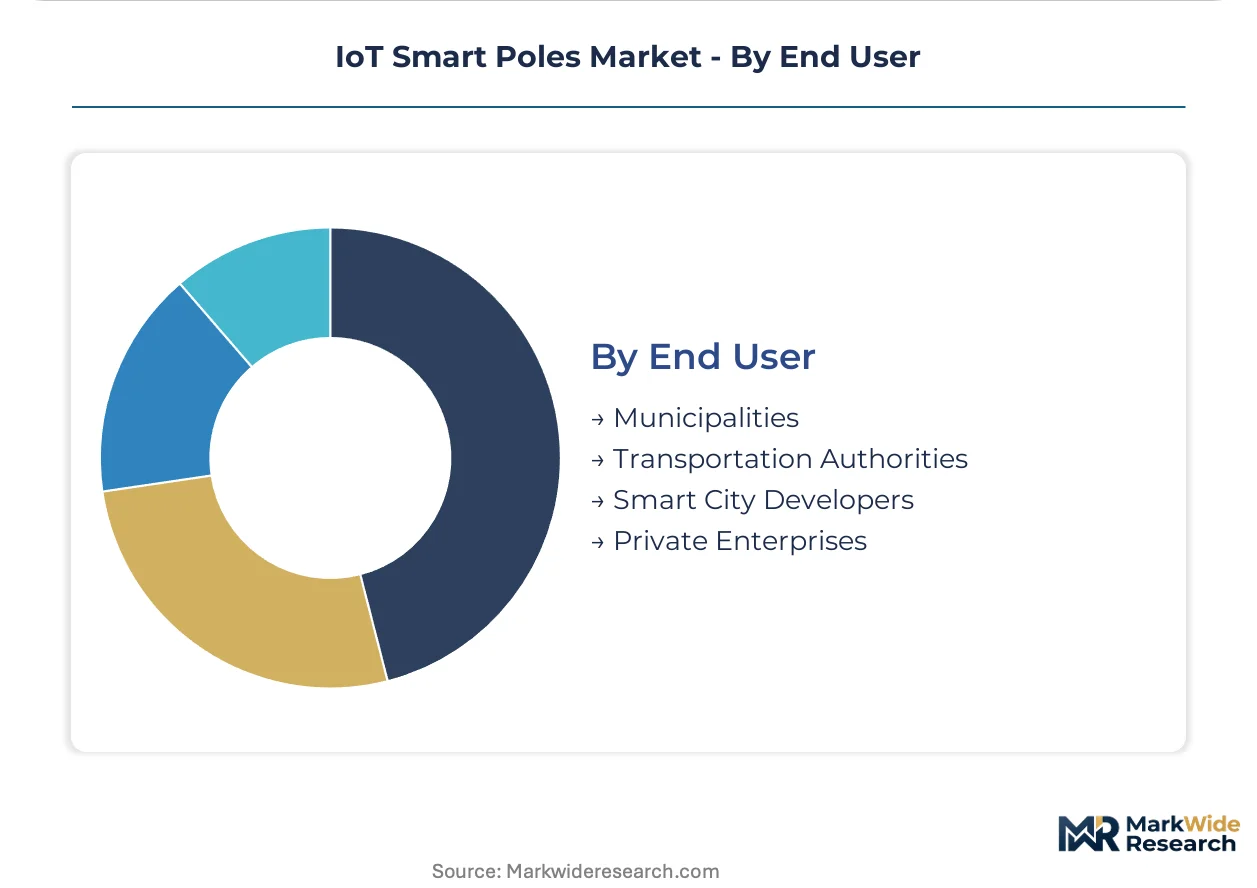
End User:
Customer type dictates contract structure, financing mechanisms, and vendor relationship longevity.
- Transportation Authorities:Highway and corridor operators with dedicated infrastructure budgets and long-term maintenance contracts. These buyers now drive the fastest procurement acceleration, specifying carrier-grade connectivity and edge-AI video analytics for traffic management in South Korea and Vietnam.
- Municipalities:Traditional streetlight operators with fragmented procurement and constrained capital cycles, increasingly shifting to managed-service models in UK deployments.
- Smart City Developers:Integrated platform operators bundling pole infrastructure with data services and urban operating systems.
- Private Enterprises:Campus and facility operators deploying captive networks with limited interoperability requirements.
Transportation authorities are climbing the fastest; municipalities still account for the greatest cumulative deployment volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for IoT smart poles tilts toward European luminaire heritage and North American structural steel expertise, while deployment demand clusters in Asian smart city corridors. Consumption patterns diverge sharply between retrofit-driven European municipalities and greenfield highway densification across South Korea, Vietnam, and India.
United States
FCC pole-access pricing reforms and dig-once mandates compress deployment timelines for highway corridor densification. Transportation authorities in Texas and California now specify carrier-grade cellular backhaul for interstate smart infrastructure. The I-35 corridor through Austin and San Antonio anchors the steepest procurement acceleration for integrated pole-electronics assemblies.
Germany
EU Green Deal efficiency thresholds and CE marking mandates filter market access for European tenders. German traffic authorities have paused biometric analytics tenders pending clarity on EU AI Act high-risk system designations. The Ruhr industrial corridor and Bavarian automotive clusters drive retrofit demand for multi-function pole platforms with embedded edge computing.
India
BIS certification and Smart Cities Mission procurement frameworks create structured demand pathways for foreign suppliers. State-level tenders in Maharashtra and Gujarat concentrate the bulk of new installation volumes for LED-solar hybrid poles. Mumbai and Ahmedabad municipal corporations now require domestic testing laboratory partnerships as preferential bid criteria.
South Korea
Highway operators specify hot-swappable GPU sleds for seasonal traffic-pattern retraining, compressing hardware refresh cycles. National transport ministry mandates for real-time video analytics accelerate edge-AI pole deployment across the Seoul-Busan expressway corridor. Daegu-Gyeongbuk cluster anchors manufacturing for modular pole-mounted computing architectures.
Vietnam
Smart city developers leverage LoRaWAN for cost-constrained urban sensor networks where high-bandwidth applications remain secondary. Ho Chi Minh City and Hanoi concentrate procurement for highway corridor smart poles outpacing traditional municipal streetlight volumes. National infrastructure funds prioritize cellular backhaul integration for suburban connectivity densification projects.
IoT Smart Poles Market Competitive Landscape
Top-tier vendors anchor integrated platform positions, while mid-tier specialists compete on modular component supply and regional certification speed. The vendor base stratifies across luminaire heritage players, structural steel fabricators, and managed-service platform operators. Three archetypes dominate: lighting-origin integrators extending into sensor electronics, infrastructure contractors backward integrating into pole-electronics assembly, and telecom-focused platform operators capturing recurring revenue through long-term service contracts. Competitive moves concentrate on certification partnerships for BIS and CE marking acceleration, plus managed-service contract structuring to displace capital-purchase procurement.
Within the lighting-heritage tier, Signify Holding and Zumtobel Group exemplify European retrofit-cycle dominance through luminaire-to-electronics integration. Telensa occupies a position among UK-based managed-service specialists underwriting end-to-end SLAs across decade-long municipal contracts. Valmont Structures represents North American structural steel expertise extending into integrated pole-electronics assemblies for transportation authority highway deployments.
| Leading Market Players |
|---|
| Silver Spring Networks |
| Omniflow |
| Signify Holding |
| Zumtobel Group |
| Valmont Structures |
| Cree |
| Schréder |
| Iram Technologies |
| Telensa |
| Others |
Pricing and Supply Chain Analysis
Captive integration of LED driver electronics with structural mast fabrication anchors both supply security and pricing power for tier-one pole assemblers serving transportation authority contracts. This backward control over power distribution architectures insulates vendors from commodity volatility while enabling premium positioning on managed-service contracts.
Pricing Analysis
Short lead-time premiums now separate emergency procurement tiers from standard municipal tender cycles in the IoT smart poles landscape. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE-marked and BIS-certified assemblies commanding substantial uplifts over uncertified alternatives. Cost compression in standard-tier LED poles is intensifying because aluminum and steel input volatility squeezes fixed-price contract margins. Municipalities exhibit the highest price sensitivity, deferring sensor-node upgrades when capital cycles tighten, while transportation authorities prioritize carrier-grade connectivity density over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese LED chip foundries and South Korean GPU module suppliers for edge-AI pole assemblies. Manufacturing concentrates in China for photovoltaic integration components, Germany for precision luminaire optics, and the United States for structural steel mast fabrication. Raw material dependencies span high-grade aluminum extrusions, silicon carbide power semiconductors, and lithium-ion battery cells for solar-hybrid configurations. Tariff exposure on Chinese electronics imports threatens margin stability for European and North American integrators. Distribution runs through municipal procurement portals, transportation authority framework agreements, and smart city developer consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT smart poles sector functions as a vertical-integration race where control over power-electronics design and edge-computing module sourcing determines who captures recurring platform revenue versus commoditized hardware sales.
For Market Incumbents: Anchor platform stickiness through long-term managed-service contracts with transportation authorities, locking in 10-15 year SLA horizons that entrench incumbent positions against modular component challengers. Deepen backward integration into power-over-Ethernet driver manufacturing to insulate margins from semiconductor supply volatility. Defensive patenting around hot-swappable GPU sled architectures preserves technical differentiation as South Korean highway operators accelerate compute refresh cycles. For New Entrants and Emerging Players: Direct-to-municipality SaaS pricing models bypass capital-budget constraints that stall traditional hardware procurement in Indian Smart Cities Mission tenders. White-space concentration sits with LoRaWAN sensor overlay retrofits in Vietnamese urban corridors where high-bandwidth cellular backhaul remains uneconomical. Target BIS certification partnerships with Maharashtra and Gujarat testing laboratories to unlock preferential bid scoring on state-level tenders. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-operator acquisitions by infrastructure funds seeking contracted recurring revenue streams. Long-term viability hinges on whether vendors can transition from luminaire suppliers to distributed infrastructure platform operators with end-to-end data service capabilities. Watch for FCC pole-access pricing reform implementation as the inflection signal determining whether integrated-platform vendors or modular component suppliers capture the next wave of US highway corridor densification.| Strategic Initiative | Industry Significance |
|---|---|
| Managed-Service Contract Structuring | Telensa and infrastructure funds capture recurring revenue that hardware vendors forfeit under capital-purchase models. |
| BIS Certification Partnership | Foreign suppliers securing domestic Indian testing laboratory partnerships gain preferential access to state-level smart city tenders. |
| Power-over-Ethernet Convergence | Integrated LED-driver architectures reduce cabling complexity and enable solar-hybrid retrofits in grid-unreliable zones. |
| Hot-Swappable GPU Module Development | South Korean highway operators specify sled-based architectures that compress hardware refresh cycles from seven to three years. |
| CE Marking Acceleration Investment | EU electromagnetic compatibility testing extends certification cycles by 4-8 months for multi-radio pole assemblies. |
Research Methodology
Independent corroboration across municipal procurement databases, transportation authority framework agreements, and smart city developer consortium disclosures underwrites the qualitative findings in this study. Primary interviews with smart city procurement officers, transportation authority infrastructure planners, pole-electronics engineering leads, and managed-service platform operators combined with secondary validation from FCC rulings, EU Green Deal threshold documentation, and BIS certification registries. Bottom-up unit economics modeling and top-down market sizing triangulate volume and value estimates.
Comparable-period anchoring to historical LED retrofit cycles and cellular infrastructure densification waves structured the projection horizon across the analysis window. Segmentation dimensions span product architecture, connectivity protocol, installation environment, and procurement authority type, with edge-AI compute attach rates modeled as a cross-cutting variable. CAGRs derive from logistic diffusion curves fitted to technology adoption patterns in highway corridor and urban deployment contexts. Forecast inputs incorporate aluminum and steel commodity index trajectories, plus regulatory mandate implementation schedules.
The model holds under stable FCC pole-access pricing and EU CE marking enforcement; deviation in trade tariff regimes or BIS certification reciprocity agreements would shift supplier competitive positioning. Forecasts reflect documented assumptions about transportation authority budget allocation priorities and municipal capital cycle recovery. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Communication Protocol Market
Internet of Things (IoT)
Private Narrowband IoT Market
Internet of Things (IoT)
Wifi IoT Market
Internet of Things (IoT)
IoT Operating System Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market
Internet of Things (IoT)
IOT in Aviation Market
Internet of Things (IoT)
Automotive Internet of Things (IoT) Market
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Services Market
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
IoT at Workplace Market
Internet of Things (IoT)
Global Military IoT Market
Internet of Things (IoT)
Global Agile IoT Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
Global Narrowband IoT Market