
 Smart Home M2M Market | 2026-2036
Smart Home M2M Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home M2M Market Outlook
Residential property management is consolidating as the fastest-expanding end-use vertical for machine-to-machine home connectivity. AT&T Inc. leverages its cellular network infrastructure to anchor managed connectivity services for multi-unit dwellings. Siemens AG specializes in building automation protocols that extend into smart thermostat and lighting control systems. Schneider Electric SA dominates energy management integration, competing on interoperability across Zigbee and Z-Wave ecosystems.
Smart Home M2M denotes networked device-to-device communication within residential environments, typically operating over sub-1 GHz or 2.4 GHz radio bands with latency thresholds below 250 milliseconds for real-time automation triggers. These systems enable remote monitoring, predictive maintenance, and autonomous control of HVAC, lighting, and security infrastructure without human intermediary commands. Smart Meter product types lead installation volumes but Home Security System applications capture higher margin pools due to recurring monitoring fees. Wi-Fi technology sustains broad compatibility while Z-Wave competes on mesh reliability for whole-home coverage in larger dwellings.
The FCC governs spectrum allocation for unlicensed IoT transmissions in the United States, while the EU Green Deal and F-Gas Regulation mandate minimum efficiency thresholds for connected climate control devices sold across Europe. REACH compliance adds material disclosure burdens for manufacturers sourcing semiconductor components and battery assemblies. Stakeholders must monitor evolving cybersecurity certification requirements from ETSI and NIST as regulatory bodies tighten resilience standards for residential networks handling biometric and occupancy data.
Market Dynamics
EU Green Deal enforcement is compressing device certification timelines while accelerating replacement cycles for legacy HVAC controllers across European residential stock. Property managers now face dual pressure from F-Gas phase-down mandates and tenant demand for automated climate systems.
Growth Catalysts
- EU F-Gas Regulation:Mandates refrigerant phase-down for connected heat pumps, forcing hardware refresh cycles across German and French multi-family housing portfolios.
- Smart grid infrastructure:Utilities in Texas, California, and Guangdong province deploy time-of-use pricing APIs that reward M2M-enabled load shifting.
- Mesh protocol maturation:Z-Wave Long Range and Zigbee Direct specifications eliminate proprietary hub dependencies, reducing installation friction for retrofit deployments.
Market Restraints
- Semiconductor supply concentration:Sub-1 GHz RF transceiver fabrication concentrates in Taiwan and South Korea foundries, exposing lead time volatility.
- Lithium battery chemistry costs:Cellular-connected sensors and door locks face input price pressure from cathode material sourcing constraints.
- Interoperability fragmentation:Competing Matter, Zigbee, and proprietary stacks force manufacturers to maintain multiple SKUs, diluting R&D efficiency.
Strategic Opportunities
- India smart city mandates:Ministry of Housing and Urban Affairs directives for energy-efficient residential towers create first-mover advantage for M2M-integrated building management.
- Insurance-channel bundling:US property and casualty underwriters embed connected water leak and fire detection hardware into premium discount programs.
- AI-driven predictive maintenance:Convergence of edge inference chips with occupancy sensors enables fault anticipation before tenant complaint escalation.
Industry Challenges
- Cybersecurity certification backlog:ETSI EN 303 645 and NIST IR 8259A testing queue delays product launches by 4-8 months.
- Legacy BACnet integration:Commercial-to-residential retrofit projects require protocol translation layers that inflate commissioning costs and failure rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home M2M Market |
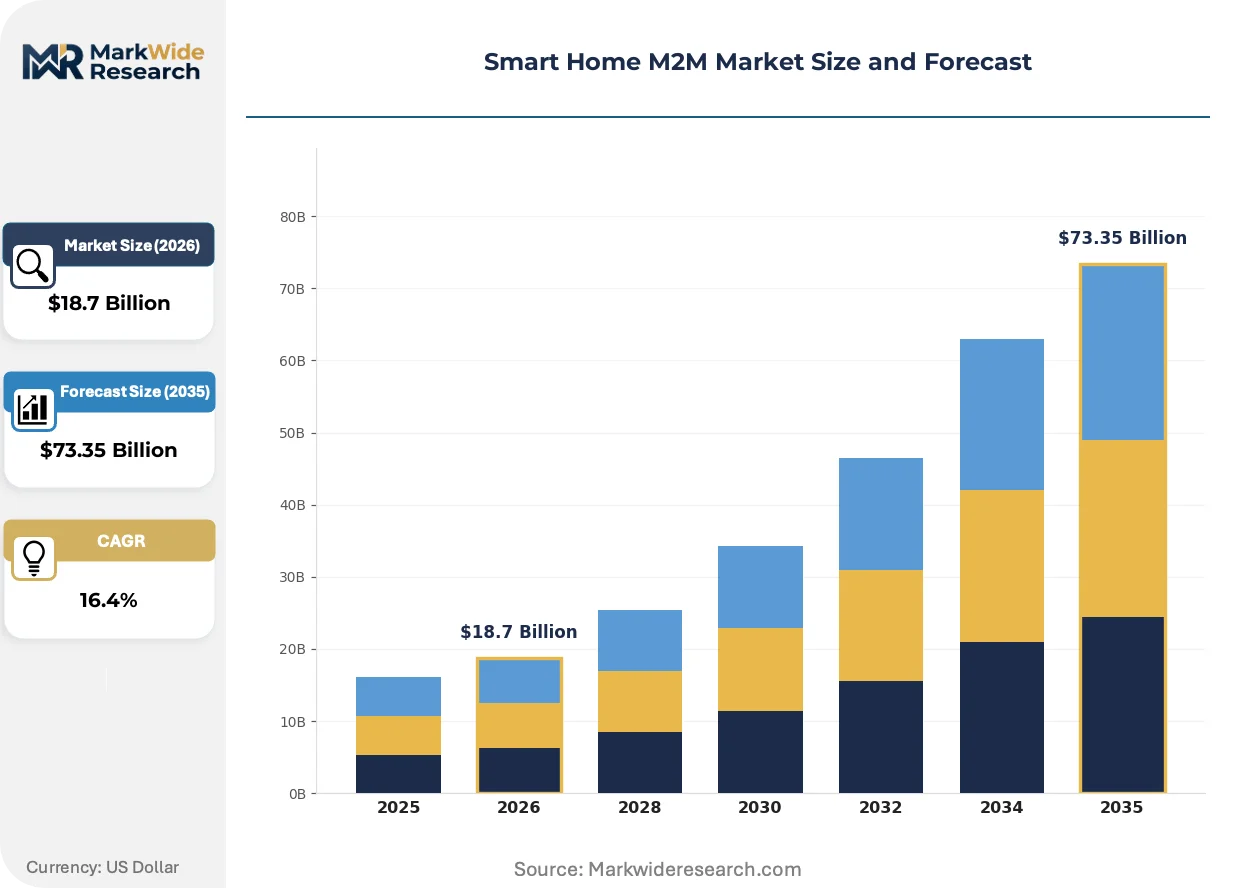
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meter, Smart Lighting, Smart Thermostat, Home Security System Technology: Zigbee, Z-Wave, Wi-Fi, Bluetooth Application: Energy Management, Home Automation, Health Monitoring, Security Surveillance End User: Homeowners, Renters, Property Managers, Real Estate Developers |
| Companies Covered | AT&T Inc., Deutsche Telekom AG, Cisco Systems Inc., Honeywell International Inc., Samsung Electronics Co., Ltd., Schneider Electric SA, Siemens AG, Intel Corporation, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home M2M Market Strategic Shifts
Device intelligence is migrating from cloud dependency to edge processing, while regulatory pressure on embodied carbon reshapes hardware design priorities. Procurement patterns favor vertically integrated platform providers over component specialists.
Matter 1.2 specification adoption is unifying previously fragmented smart home ecosystems under a single application-layer protocol. Multi-family property developers in Germany and the Netherlands now specify Matter-certified devices as standard to reduce tenant onboarding friction. This convergence is unifying control interfaces across lighting, climate, and access systems that previously required separate apps.
REACH substance restrictions are forcing reformulation of flame-retardant plastics and solder alloys used in PCB assemblies for European market entry. Manufacturers must resubmit technical documentation for existing SKUs, compressing product refresh budgets. Battery-powered sensors and motorized blinds face the tightest compliance scrutiny due to cadmium and lead content thresholds.
Subscription fatigue among US renters is compressing willingness to pay for standalone monitoring services. Property technology platforms now bundle M2M hardware into base rent rather than itemizing connectivity fees. This shift is most visible in Atlanta and Phoenix build-to-rent developments where all-inclusive pricing drives lease conversion rates.
Smart Home M2M Market Segmentation
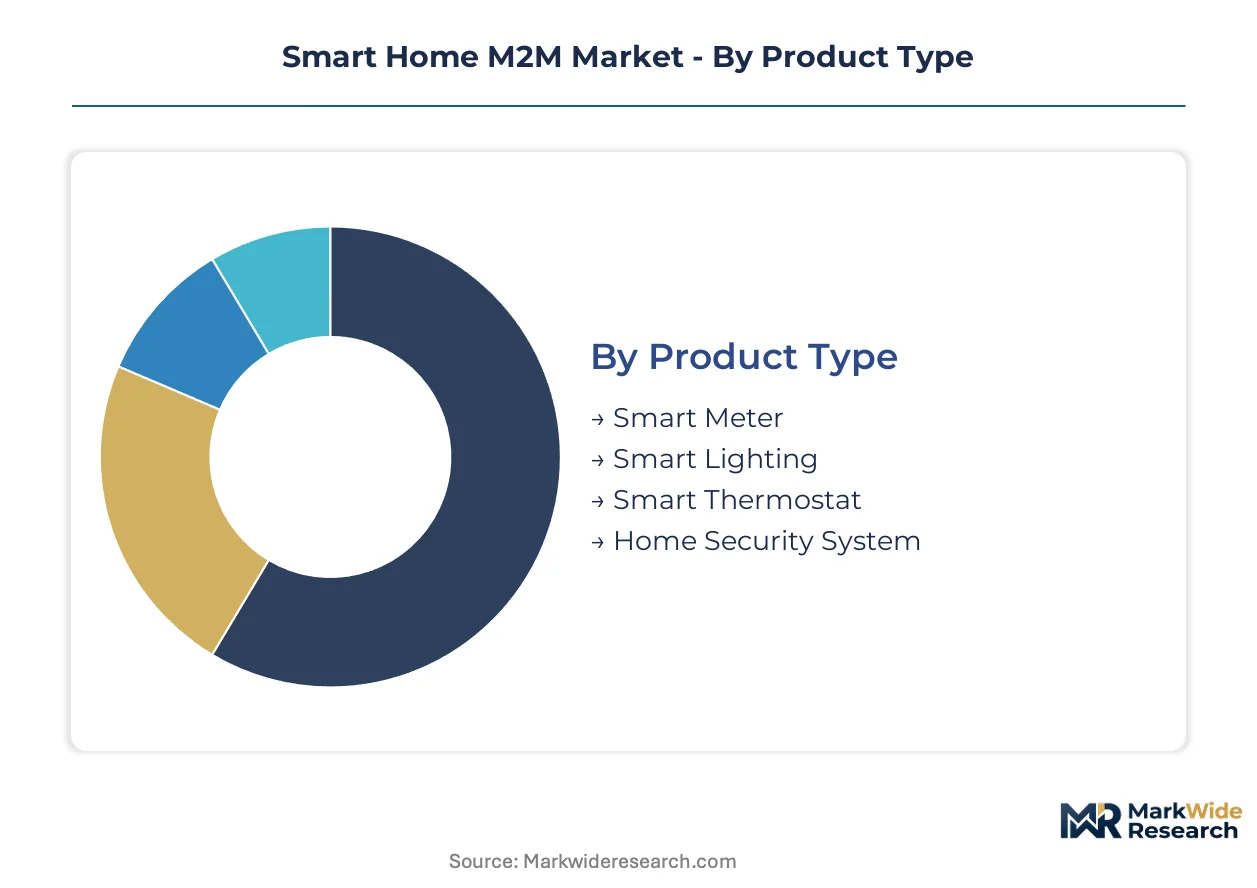
Smart Home M2M market segmentation reveals distinct capital requirements and margin profiles across hardware, connectivity, and service layers. Product type and technology choices dictate upfront infrastructure investment, while application and end-user segments determine recurring revenue durability and customer acquisition costs.
Product Type:
Capital intensity varies sharply across device categories, with utility-facing hardware demanding the heaviest upfront certification and deployment investment.
- Smart Meter:These devices incorporate sub-1 GHz RF modules and tamper-evident enclosures for utility-grade metrology. German and Texan utilities are mandating M2M-enabled meters for time-of-use pricing programs, compressing installation timelines. Smart Meter absorbs the bulk of installed capacity; Home Security System is expanding most quickly.
- Smart Lighting:LED driver circuits with integrated Zigbee or Thread radios enable circadian scheduling and occupancy-responsive dimming. Dutch and German multi-family developers specify these as base build features to meet EU Green Deal efficiency thresholds.
- Smart Thermostat:Motorized valve control and multi-zone temperature sensing support F-Gas-compliant heat pump optimization. REACH substance restrictions are forcing PCB solder reformulation for European market entry.
- Home Security System:Cellular-connected panels with encrypted sensor networks command recurring monitoring fees. Atlanta and Phoenix build-to-rent operators bundle these into all-inclusive rent structures to reduce tenant churn.
Smart Meter deployments dominate unit volumes through utility procurement; Home Security System subscriptions yield the highest lifetime customer value.
Technology:
Protocol selection determines mesh reliability, power budget, and interoperability certification burden for device manufacturers.
- Zigbee:Mesh networking at 2.4 GHz with 65,000-node addressing supports whole-building automation. Schneider Electric and Siemens anchor ecosystem development, competing on interoperability across lighting and climate controllers.
- Z-Wave:Sub-1 GHz operation avoids Wi-Fi congestion in dense residential environments. Z-Wave Long Range specification eliminates proprietary hub dependencies, reducing retrofit installation friction in larger dwellings.
- Wi-Fi:Native IP connectivity minimizes gateway hardware but elevates power consumption for battery-operated sensors. Broad compatibility sustains adoption in DIY consumer channels.
- Bluetooth:Low-energy beaconing enables proximity-based automation triggers with minimal component cost. Matter 1.2 specification adoption is consolidating Bluetooth into unified control interfaces.
Zigbee and Z-Wave together anchor professional installer preference; Wi-Fi sustains the broadest consumer accessibility.
Application:
Application segmentation maps directly to regulatory pressure points and insurance-channel integration opportunities.
- Energy Management:Load-shifting algorithms respond to real-time pricing signals from Texas, California, and Guangdong utilities. EU F-Gas Regulation mandates refrigerant phase-down for connected heat pumps, forcing hardware refresh cycles.
- Home Automation:Cross-device orchestration of HVAC, lighting, and motorized shading reduces embodied carbon in new construction. German and Netherlands property developers specify Matter-certified systems as standard.
- Health Monitoring:Fall detection and air quality sensing target aging-in-place demographics. HIPAA compliance requirements constrain data handling architectures for US deployments.
- Security Surveillance:Video verification and water leak detection embed into US property and casualty premium discount programs. ETSI EN 303 645 certification queues delay product launches.
Energy Management captures the steepest expansion trajectory as grid-interactive buildings become code-mandated; Security Surveillance offers the most mature recurring revenue models.
End User:
End-user segmentation reveals divergent procurement authority and technology sophistication across residential market tiers.
- Homeowners:Single-family purchasers prioritize DIY installation and app-based control. Subscription fatigue is compressing willingness to pay for standalone monitoring services.
- Renters:Tenant populations in Atlanta and Phoenix build-to-rent developments favor all-inclusive pricing that bundles M2M hardware into base rent.
- Property Managers:Multi-unit operators face dual pressure from F-Gas phase-down mandates and tenant demand for automated climate systems.
- Real Estate Developers:German and Netherlands new construction specifies interoperable platforms to reduce tenant onboarding friction and accelerate lease conversion.
Property Managers control the fastest-growing procurement channel; Real Estate Developers set specifications that lock in ecosystem choices for decade-long building lifecycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Guangdong province concentrate smart grid infrastructure investment, while German industrial clusters drive F-Gas compliance hardware demand. Texas and California utilities deploy time-of-use pricing APIs that reward M2M-enabled load shifting. Dutch property developers specify Matter-certified systems as standard in new construction.
United States
Texas and California utilities lead smart grid API deployment for residential load shifting. FCC spectrum allocation governs unlicensed IoT transmissions across the 2.4 GHz and sub-1 GHz bands. Atlanta and Phoenix build-to-rent developments bundle M2M hardware into all-inclusive rent structures to accelerate lease conversion.
Germany
F-Gas Regulation mandates refrigerant phase-down for connected heat pumps across multi-family housing portfolios. EU Green Deal enforcement compresses device certification timelines for HVAC controllers. Industrial automation clusters in Bavaria and Baden-Württemberg anchor building protocol development for residential extensions.
China
Guangdong province utilities deploy time-of-use pricing infrastructure that rewards M2M-enabled demand response. MIIT governs radio frequency allocations for smart home device certification. Yangtze River Delta manufacturing clusters produce sub-1 GHz RF transceiver modules for export markets.
Netherlands
Multi-family property developers in Randstad cities specify Matter-certified devices as standard build features. EU Green Deal efficiency thresholds mandate automated climate and lighting systems in new residential towers. Eindhoven-region technology firms anchor Zigbee ecosystem development for professional installer channels.
India
Ministry of Housing and Urban Affairs directives for energy-efficient residential towers create procurement opportunities for M2M-integrated building management. BIS certification requirements govern RF device market entry for connected home hardware. Bangalore and Hyderabad technology clusters develop edge inference chips for predictive maintenance applications.
Smart Home M2M Market Competitive Environment
Top-tier vendors anchor cellular and semiconductor infrastructure, while mid-tier specialists compete on building automation protocols and energy management integration. The vendor base stratifies across telecommunications carriers, industrial automation conglomerates, and component semiconductor suppliers. Three archetypes dominate: network infrastructure providers, building technology integrators, and silicon platform suppliers. Capacity expansion in RF transceiver fabrication and strategic partnerships for protocol interoperability represent the primary competitive moves.
Within the network infrastructure tier, AT&T Inc. and Deutsche Telekom AG exemplify carrier-led managed connectivity approaches for multi-unit dwellings. Schneider Electric SA and Siemens AG occupy positions as building technology integrators competing on interoperability across competing radio ecosystems. Samsung Electronics Co., Ltd. represents the diversified electronics conglomerate archetype with vertical control over component supply and finished device assembly.
| Leading Market Players |
|---|
| AT&T Inc. |
| Deutsche Telekom AG |
| Cisco Systems Inc. |
| Honeywell International Inc. |
| Samsung Electronics Co., Ltd. |
| Schneider Electric SA |
| Siemens AG |
| Intel Corporation |
| Robert Bosch GmbH |
| Others |
Value Chain & Pricing Dynamics
Sub-1 GHz RF transceiver fabrication costs in Taiwan and South Korea foundries cascade through three pricing tiers: premium SKUs for F-Gas-compliant heat pump controllers, standard Matter-certified lighting modules, and economy Wi-Fi sensors for DIY channels. Buyers in German multi-family housing portfolios absorb premium pricing for REACH-certified PCB assemblies, while Atlanta build-to-rent operators negotiate volume discounts on cellular-connected security panels.
Pricing Analysis
Short lead-time premiums concentrate in Z-Wave Long Range modules for retrofit deployments, where German property managers pay above-list pricing to compress installation windows. Three-tier pricing structure across premium, standard, and economy levels separates F-Gas-compliant thermostats from basic Wi-Fi sensors and white-label Bluetooth beacons. Cost compression in cellular connectivity modules is intensifying because lithium cathode sourcing constraints persist. DIY homeowners exhibit highest price sensitivity, while real estate developers lock in decade-long supply agreements at fixed pricing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Schneider Electric and Siemens for Zigbee ecosystem components, while distributor networks serve installer-led retrofit markets. Taiwan, South Korea, and China concentrate sub-1 GHz RF transceiver fabrication, lithium battery cell production, and LED driver assembly respectively. The chain draws from semiconductor wafers, rare-earth magnet stock, and flame-retardant plastic resins. Single-source vulnerability concentrates in Taiwan foundry capacity for utility-grade smart meter chipsets. Distribution runs through authorized installer channels in Germany and the Netherlands, direct procurement in Texas utilities, and e-commerce platforms for US consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF transceiver foundry capacity constraints in Taiwan and South Korea prop pricing power for incumbent semiconductor suppliers. Supply scarcity favors vendors with captive fabrication or long-term offtake agreements.
For Market Incumbents: Extend protocol interoperability investments to capture Matter 1.2 specification mandates from Dutch and German developers. Deepen backward integration into sub-1 GHz module production to offset Taiwan foundry lead-time volatility. Defend against Z-Wave Long Range displacement by accelerating Zigbee Direct certification timelines. For New Entrants and Emerging Players: Edge inference chip integration for predictive maintenance creates entry pathways into Indian smart city mandates. Target Ministry of Housing and Urban Affairs procurement for energy-efficient residential towers in Bangalore and Hyderabad. Pursue insurance-channel bundling partnerships with US property and casualty underwriters for water leak detection hardware. For Investors and Strategic Acquirers: ETSI EN 303 645 certification queue lengths are the leading indicator that cybersecurity-compliant vendors command scarcity premiums. Five-to-ten year viability favors vertically integrated platform providers over component specialists. Monitor NIST IR 8259A testing backlog clearance as signal for product launch acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Unifies control interfaces across Schneider Electric and Siemens ecosystems for Dutch developers. |
| Cellular Connectivity Partnership | AT&T and Deutsche Telekom anchor managed services for multi-unit dwelling deployments. |
| Edge Inference Chip Development | Enables fault anticipation in HVAC systems before tenant complaint escalation in German housing. |
| REACH Compliance Investment | Reformulates solder alloys and flame-retardant plastics for European market entry. |
| Insurance Channel Integration | Embeds water leak hardware into US property and casualty premium discount programs. |
Study Parameters
Independent corroboration across utility procurement officers, smart home platform engineers, and real estate development executives underwrites the qualitative findings. Primary interviews with RF semiconductor product managers, building automation system integrators, and property technology procurement leads combined with secondary validation from FCC spectrum allocation filings, EU Green Deal implementation reports, and MIIT radio certification databases. Bottom-up installation volume estimates and top-down utility capex disclosures triangulate market sizing.
Comparable historical periods anchored the projection framework to pre-Matter protocol adoption baselines and post-F-Gas Regulation enforcement trajectories. The model segments by product type, technology protocol, application use case, and end-user archetype across the analysis window. CAGRs derive from utility smart meter deployment schedules, multi-family construction permitting data, and semiconductor foundry capacity expansion announcements. Edge AI chip shipment forecasts and time-of-use pricing API rollouts inform demand-side inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Taiwan geopolitical disruption or accelerated EU refrigerant phase-down timelines. Projections reflect assumptions on Matter adoption velocity, Z-Wave Long Range retrofit penetration, and REACH substance restriction enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Edge Computing in IoT Market
Internet of Things (IoT)
Global IoT Based Asset Tracking and Monitoring Market
Internet of Things (IoT)
Global IoT Node and Gateway Market
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
Europe IoT Market
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
IoT Infrastructure Market
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
Global 5G Industrial IOT Market
Internet of Things (IoT)
Global Embedded Security for Internet of Things Market
Internet of Things (IoT)
Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
IoT in Automotive Market
Internet of Things (IoT)
Global IoT Managed Services Market