
 Europe Speech Analytics Market | 2026-2036
Europe Speech Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Speech Analytics Market Foresight
Buyer concentration among European telecommunications providers is restructuring procurement patterns for speech analytics platforms. NICE Ltd. leverages its established presence in workforce optimization to anchor deployments across major carrier networks. Verint Systems Inc. competes through specialized compliance monitoring modules tailored to financial services. Speechmatics differentiates by advancing multilingual automatic speech recognition capabilities that address Europe's linguistic fragmentation.
Speech analytics encompasses technologies that capture, transcribe, and analyze spoken language to extract operational intelligence, employing acoustic modeling, natural language processing, and sentiment classification algorithms to process audio streams at scale. Its primary commercial purpose centers on transforming unstructured voice interactions into searchable, measurable data assets for quality assurance and risk management. Cloud-based solutions now lead product type adoption as enterprises prioritize elastic scalability and reduced infrastructure overhead. Compliance monitoring applications command premium pricing due to regulatory complexity, while customer service deployments represent the broadest installed base across BFSI and telecommunications end users.
The EU AI Act and GDPR impose stringent requirements on automated processing of biometric and conversational data, compelling vendors to embed explainability and consent management into platform architectures. EMA guidelines on pharmacovigilance and the EU Green Deal's digitalization mandates further shape sector-specific demand patterns across healthcare and public administration. Stakeholders must monitor evolving conformity assessment procedures under the AI Act's risk-based classification system to anticipate certification barriers and competitive positioning shifts.
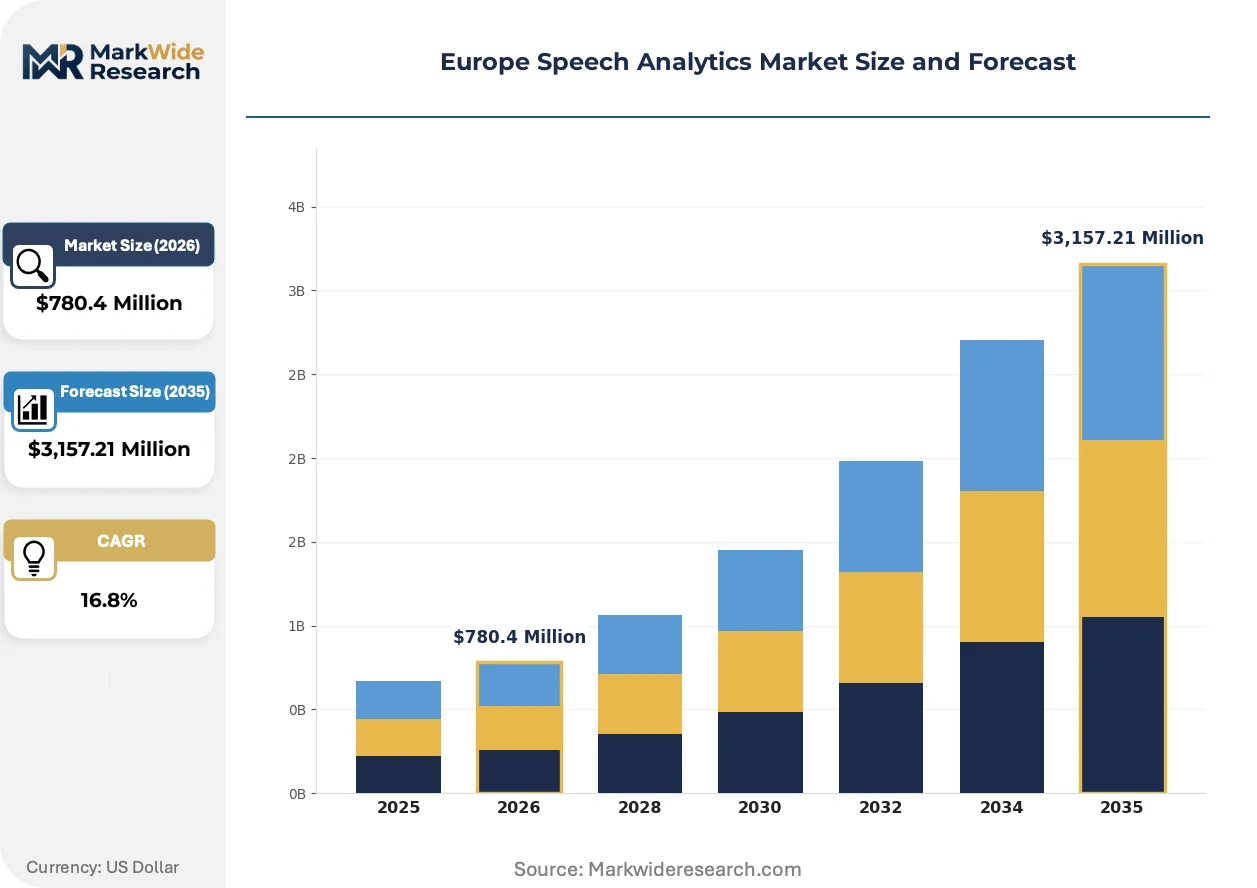
Market Dynamics
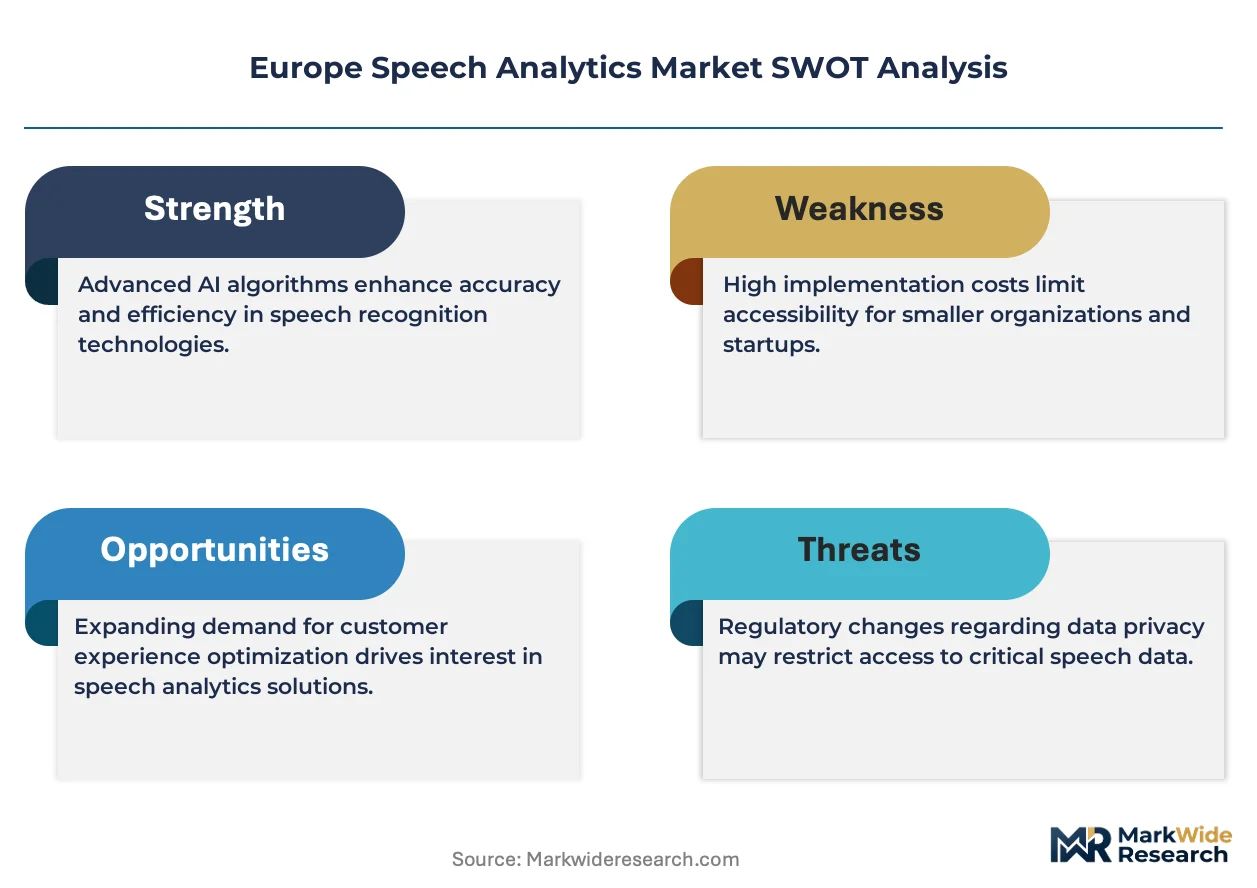
The EU AI Act's risk-based classification system is electrifying procurement urgency among European financial institutions and telecom carriers, forcing platform vendors to re-architect products for explainability and auditability before enforcement deadlines crystallize.
Growth Catalysts
- GDPR Article 22:Automated decision-making restrictions compel banks to deploy speech analytics with human-in-the-loop safeguards, expanding addressable market for compliance-grade platforms.
- Cloud elasticity:Telecommunications providers prioritize SaaS deployments to handle seasonal call volume spikes without capital-intensive infrastructure buildouts.
- France:ANSM pharmacovigilance mandates accelerate healthcare adoption for adverse event detection from patient hotlines.
Market Restraints
- GPU supply concentration:Training large acoustic models depends on NVIDIA hardware subject to US export controls, creating procurement bottlenecks for European AI labs.
- Data localization costs:GDPR's territoriality principle forces redundant infrastructure across Germany, France, and Ireland, inflating total cost of ownership.
- Accent fragmentation:Low-resource European dialects lack training corpora, degrading transcription accuracy for Iberian Portuguese and Eastern European variants.
Strategic Opportunities
- Poland and Romania:Nearshoring of multilingual customer service hubs creates greenfield demand for speech analytics in underpenetrated markets.
- Real-time agent coaching:Streaming sentiment analysis converges with workforce optimization to displace post-call quality review entirely.
- EU Green Deal digitalization:Public administration modernization funds unlock municipal contact center deployments previously blocked by budget constraints.
Industry Challenges
- Computational linguist scarcity:European universities produce insufficient PhD-level talent in low-resource language modeling, constraining vendor R&D velocity.
- CE marking complexity:Medical device classification under MDR delays healthcare platform launches by 18-24 months versus general enterprise deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Speech Analytics Market |
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $3,157.21 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hosted Solutions, On-Premises Solutions, Hybrid Solutions, Cloud-Based Solutions End User: BFSI, Retail, Healthcare, Telecommunications Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Deployment Application: Customer Service, Market Research, Quality Assurance, Compliance Monitoring |
| Companies Covered | Verint Systems Inc., NICE Ltd., Avaya Inc., Callminer Inc., Genesys Telecommunications Laboratories Inc., Calabrio Inc., OpenText Corporation, Micro Focus International PLC, Speechmatics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Speech Analytics Market Shifts & Advancements
Transformer-based architectures are electrifying accuracy benchmarks while regulatory pressure fuses compliance features into core platform design, compressing the gap between transcription utility and risk management functionality.
Self-supervised learning on unlabeled European audio corpora is electrifying multilingual model performance without expensive manual annotation. Tier-one carriers in Germany and the United Kingdom deploy these systems to handle code-switched conversations. The technology is electrifying competitive differentiation around dialect coverage rather than baseline word error rate.
The EU AI Act's conformity assessment procedures are restructuring vendor roadmaps toward documented algorithmic transparency. High-risk system providers must maintain technical documentation and human oversight protocols. Financial services procurement teams now require CE marking readiness as a gate criterion, filtering out non-compliant bidders.
Subscription pricing with usage-based tiers is displacing perpetual licensing in enterprise sales cycles. German insurers and Dutch telecommunications operators favor this model for predictable operational expenditure alignment. France exhibits the fastest uptake of outcome-based contracts tied to measurable quality assurance improvements.
Europe Speech Analytics Market Segmentation
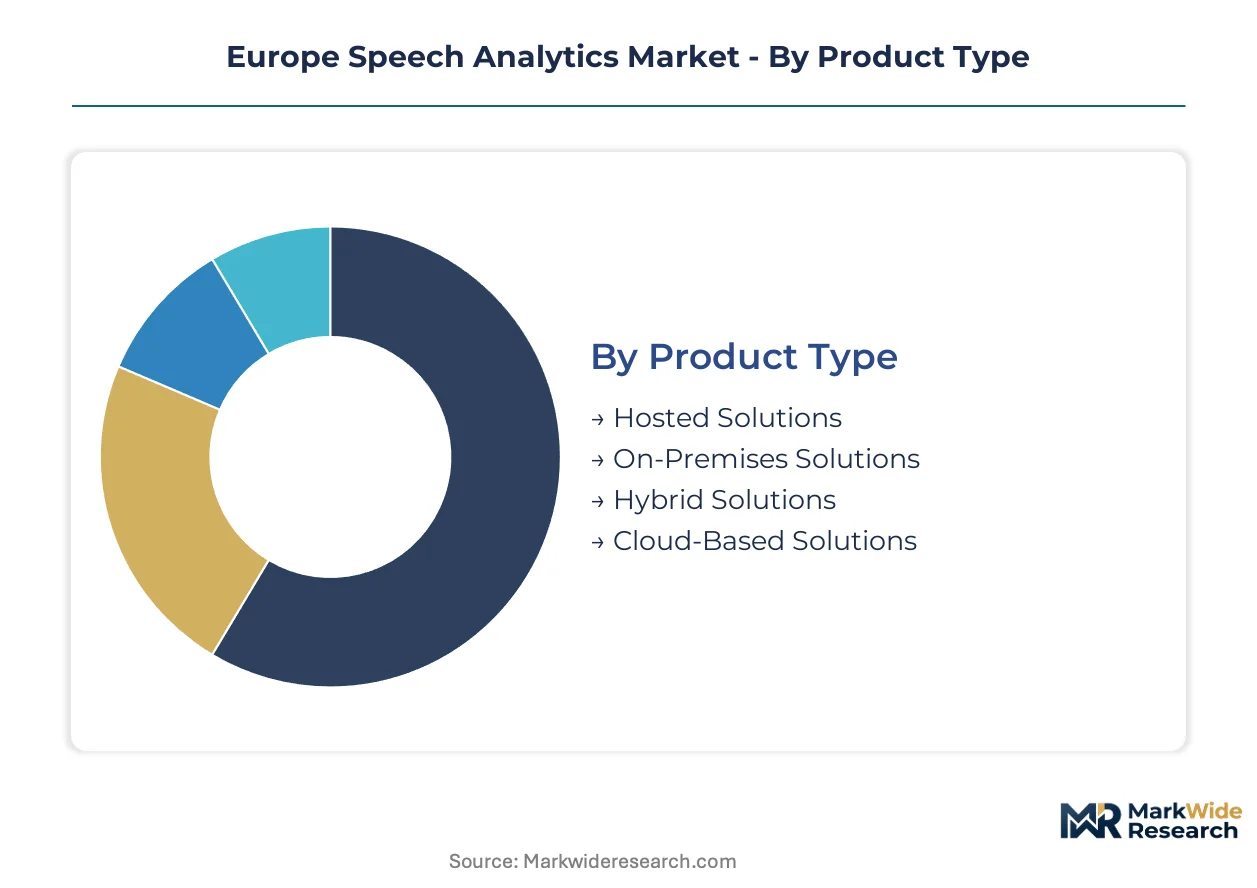
Speech analytics procurement across Europe diverges sharply by infrastructure maturity and regulatory exposure. Buyers replace legacy on-premises installations with elastic cloud architectures while compliance-grade applications command pricing premiums.
Product Type:
Upgrade cycles accelerate as enterprises shed capital-intensive hardware for consumption-based alternatives. GDPR data residency requirements complicate cloud migration timelines for sensitive verticals.
- Cloud-Based Solutions:Multi-tenant SaaS architectures with automatic scaling and API-first integration. German insurers and Dutch telecommunications operators favor this model for predictable operational expenditure alignment and rapid deployment across distributed agent pools.
- Hosted Solutions:Vendor-managed single-tenant deployments maintaining client isolation without on-site hardware ownership. French healthcare providers select this path to satisfy ANSM pharmacovigilance data sovereignty mandates while avoiding infrastructure management burdens.
- Hybrid Solutions:Split architectures processing sensitive transcription on-premises while leveraging cloud analytics for non-regulated workloads.
- On-Premises Solutions:Fully captive installations retained by defense contractors and certain banking entities with legacy security certifications.
Volume placements concentrate in Cloud-Based Solutions; the faster expansion belongs to Hybrid Solutions as regulated sectors seek intermediate compliance postures.
End User:
Customer interaction intensity and regulatory burden determine adoption velocity across verticals. Sectors with high call volumes and strict oversight show disproportionate platform investment.
- BFSI:Compliance monitoring for MiFID II conduct standards and automated dispute resolution. GDPR Article 22 restrictions on automated decision-making compel banks to deploy human-in-the-loop safeguards, expanding demand for explainable transcription platforms.
- Telecommunications:Real-time sentiment analysis for churn prediction and workforce optimization. Seasonal volume spikes drive preference for elastic cloud consumption models over fixed-capacity licensing.
- Healthcare:Adverse event detection from patient hotlines under EMA pharmacovigilance guidelines.
- Retail:Post-purchase voice-of-customer analysis and returns processing automation.
Revenue concentration sits with BFSI; telecommunications exhibits the steepest expansion trajectory as carriers modernize legacy quality assurance infrastructure.
Deployment:
Infrastructure location decisions hinge on data classification tiers and latency requirements for real-time applications. Procurement teams evaluate residual risk against operational flexibility trade-offs.
- Private Cloud:Dedicated tenant environments with customizable encryption and access controls. UK financial institutions prioritize this model for FCA audit trail requirements and granular data lineage documentation.
- Public Cloud:Shared infrastructure with standardized security certifications and rapid provisioning. Polish and Romanian nearshoring hubs select public deployments for multilingual customer service operations requiring fast scale-out.
- Hybrid Cloud:Workload-specific routing of sensitive versus general processing across boundary architectures.
- On-Premises Deployment:Air-gapped installations for classified government communications and certain critical infrastructure operators.
Contract value aggregates in Private Cloud; Hybrid Cloud is climbing the fastest as enterprises pursue phased migration strategies.
Application:
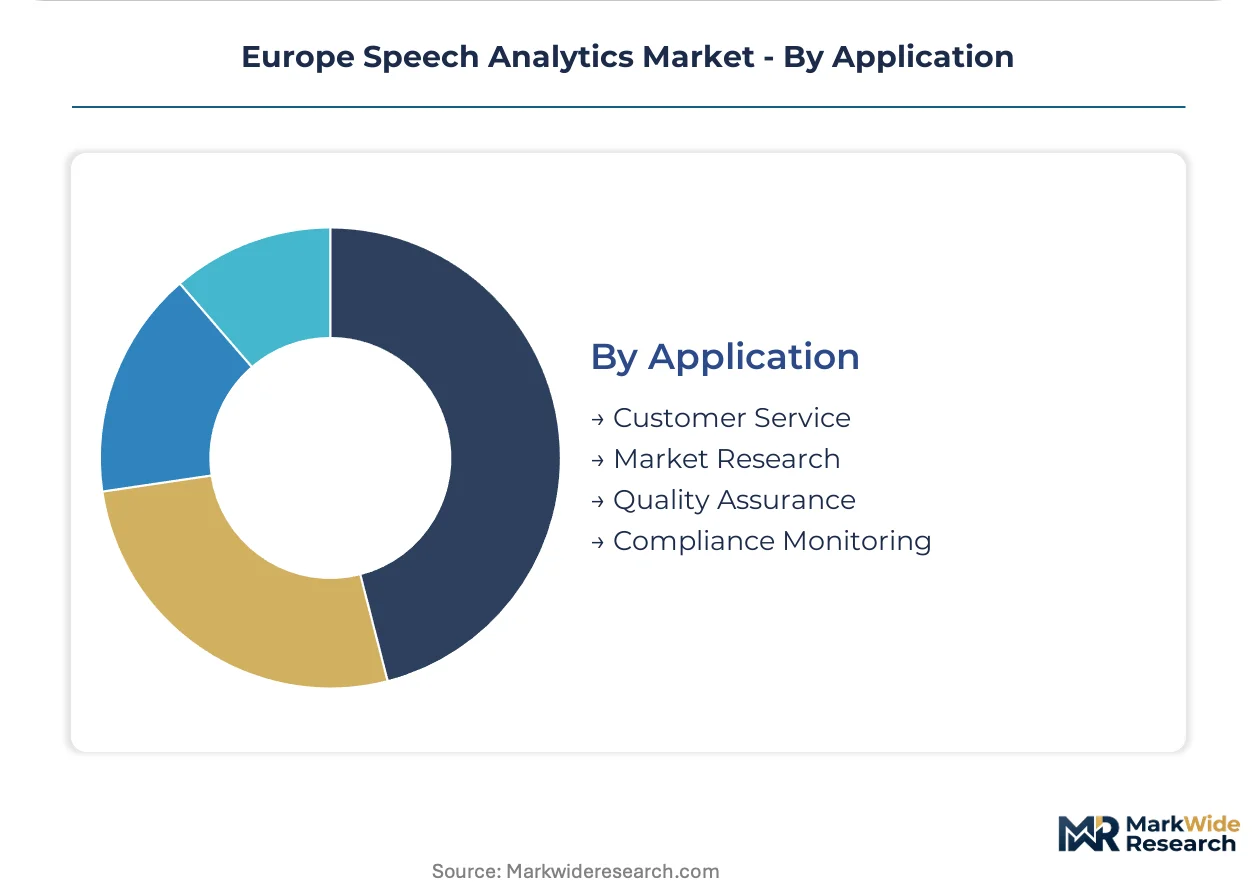
Functional use cases stratify by analytical sophistication and integration depth with operational workflows. Premium pricing attaches to applications with direct regulatory exposure.
- Compliance Monitoring:Automated detection of prohibited sales practices and mandated disclosure verification. EU AI Act conformity assessment procedures and GDPR biometric data restrictions force vendors to embed explainability and consent management, supporting sustained pricing premiums.
- Customer Service:Real-time agent guidance and post-interaction quality scoring. Streaming sentiment analysis converges with workforce optimization platforms to displace batch-processed review cycles entirely.
- Quality Assurance:Systematic call sampling and performance benchmarking against standardized rubrics.
- Market Research:Unsolicited feedback aggregation and competitive intelligence from recorded interactions.
Deployment scale favors Customer Service; Compliance Monitoring is gaining share fastest as enforcement deadlines for automated processing regulations crystallize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center infrastructure in Frankfurt anchors European speech analytics deployment. Amsterdam and Dublin process substantial transcription workloads under GDPR territoriality requirements.
Germany
BaFin conduct supervision and MiFID II compliance obligations drive banking procurement of explainable transcription platforms. The KBA automotive regulator influences connected vehicle voice data standards. Frankfurt's financial district concentrates insurer deployments for automated claims verification.
United Kingdom
FCA audit trail mandates and post-Brexit data adequacy negotiations reshape cloud architecture decisions. The Information Commissioner's Office enforces biometric data processing restrictions on call center operators. London's fintech cluster accelerates real-time agent coaching adoption among neobanks.
France
ANSM pharmacovigilance requirements and CNIL consent management rules structure healthcare platform specifications. The EU AI Act's high-risk system classification affects national procurement timelines. Parisian insurance groups deploy adverse event detection for policyholder hotlines.
Netherlands
AFM market conduct supervision and seasonal tourism call volumes drive elastic SaaS preferences. The Dutch Data Protection Authority scrutinizes automated decision-making in credit applications. Amsterdam's nearshoring hubs process multilingual customer service for German and Belgian markets.
Poland
Multilingual workforce availability and EU structural fund digitalization grants expand contact center capacity. The Polish Financial Supervision Authority aligns with EU-wide conduct standards. Kraków and Wrocław host voice operations for Western European telecommunications carriers.
Europe Speech Analytics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized compliance modules and low-resource language coverage. The vendor base clusters around three maturity levels: legacy workforce optimization providers, cloud-native transcription specialists, and vertical-focused compliance platforms. Consolidation pressure intensifies as GDPR Article 22 and EU AI Act deadlines force smaller vendors toward partnership or acquisition. Dominant competitive moves include strategic alliances with hyperscale cloud providers and geographic expansion into underpenetrated Eastern European markets.
Within the established tier, NICE Ltd., Verint Systems Inc., and Speechmatics occupy positions reflecting distinct strategic archetypes. NICE Ltd. exemplifies workforce optimization incumbents leveraging installed base relationships. Verint Systems Inc. represents specialized compliance monitoring heritage. Speechmatics anchors the multilingual automatic speech recognition specialization segment addressing European linguistic fragmentation.
| Leading Market Players |
|---|
| Verint Systems Inc. |
| NICE Ltd. |
| Avaya Inc. |
| Callminer Inc. |
| Genesys Telecommunications Laboratories Inc. |
| Calabrio Inc. |
| OpenText Corporation |
| Micro Focus International PLC |
| Speechmatics |
| Others |
Supply & Pricing Matrix
The EU Green Deal's digitalization mandates gate qualified supply and premium-tier pricing access for speech analytics platforms, as vendors must demonstrate carbon-neutral data center operations and circular hardware lifecycles to serve public sector procurement in Germany and France. Compliance-grade platforms command sustained premiums while non-certified competitors face exclusion from municipal and healthcare tenders across the continent.
Pricing Analysis
Volume concentrates in standardized SaaS tiers while margins accrue to compliance-embedded offerings. Subscription pricing with usage-based tiers dominates enterprise sales, with differentiation driven by CE marking readiness and explainability documentation depth. Pricing pressure stems from GPU supply bottlenecks inflating inference costs for real-time transcription. Tier-one financial institutions show lowest price sensitivity; mid-market retailers exhibit highest.
Supply Chain Analysis
Computational linguist scarcity in Eastern European manufacturing geographies constrains model development velocity for low-resource dialects. Supply concentrates in Ireland, Germany, and the Netherlands for GDPR-compliant data center infrastructure, with NVIDIA GPU hardware and specialized acoustic sensors as critical inputs. Single-source vulnerability runs through Taiwan-dependent semiconductor fabrication. Distribution feeds from hyperscale cloud marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's conformity assessment deadlines construct a cost-of-compliance barrier that entrenches incumbent positions and filters speculative entrants from high-risk system categories.
For Market Incumbents: Deepen vertical integration into low-resource language modeling by acquiring specialized European NLP labs in Poland and Romania. Anchor installed base relationships through CE marking readiness and documented human-in-the-loop protocols before enforcement crystallizes. GPU supply concentration poses margin pressure; secure allocation agreements with authorized distributors. For New Entrants and Emerging Players: Self-supervised learning on unlabeled European audio corpora offers technology-first wedge against annotation-dependent incumbents. Target nearshoring hubs in Kraków and Wrocław for greenfield multilingual customer service deployments. Lead with API-first integration and rapid dialect coverage expansion rather than competing on baseline accuracy. For Investors and Strategic Acquirers: First CE marking certifications under the AI Act's high-risk system classification are the leading indicator that consolidation momentum will accelerate among sub-scale compliance platforms. Viable acquisition targets cluster around vertical-focused healthcare pharmacovigilance specialists and cloud-native transcription engines with documented algorithmic transparency. Watch ANSM and BaFin enforcement patterns as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Completion | Unlocks high-risk system procurement in French healthcare and German banking under EU AI Act deadlines. |
| Low-Resource Language Acquisition | Captures nearshoring demand in Poland and Romania for Iberian and Eastern European dialect coverage. |
| Hyperscale Cloud Partnership | Secures elastic GPU allocation through AWS, Azure, or GCP marketplaces for inference cost control. |
| Pharmacovigilance Module Development | Addresses ANSM adverse event detection mandates in Parisian insurance and pharmaceutical hotlines. |
| Real-Time Agent Coaching Integration | Displaces post-call quality review entirely in Dutch telecommunications and UK neobank deployments. |
Research Methodology
Document review covered EMA pharmacovigilance guidelines, EU AI Act conformity assessment procedures, BaFin conduct supervision circulars, and hyperscaler capex disclosures, complemented by interviews with CTOs at Tier 1 telecommunications carriers, compliance officers at German insurers, platform engineers at cloud-native transcription vendors, and procurement leads at French healthcare providers. Secondary validation drew from SEC filings of publicly traded workforce optimization providers, GDPR enforcement actions by national data protection authorities, and ANSM adverse event reporting databases. Bottom-up deployment estimates triangulated against top-down addressable market calculations.
Segmented outputs across product type, end user vertical, deployment model, and application use case were generated through elasticity modeling of cloud consumption patterns and regulatory compliance premiums. CAGRs were derived from regression analysis of historical platform procurement cycles against enforcement deadline proximity. Industry-specific inputs included GPU availability indices, low-resource language corpus expansion rates, and conformity assessment queue lengths at notified bodies.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor supply, unilateral GDPR enforcement escalation by individual member states, and breakthrough advances in unsupervised multilingual modeling. Forecasts reflect documented assumptions regarding regulatory timeline adherence and cloud infrastructure expansion. Material deviation in GPU export controls, AI Act implementation delays, or data localization mandate expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Europe Operational Intelligence Market
Analytics
Europe Network and Location Analytics Market
Analytics
Global Data Prep Market
Analytics
Global Data Analysis Software Market
Analytics
Cloud-Based Business Analytics Software Market
Analytics
Global Talent Intelligence Software Market
Analytics
North America HR Analytics Market
Analytics
Lead Intelligence Software Market
Analytics
Crowd Analytics Market
Analytics
Hadoop Big Data Analytics Solution Market
Analytics
Global in-Memory Analytics Market
Analytics
Sentiment Analytics Market
Analytics
App Analytics Market
Analytics
Canada Contact Center Analytics Market
Analytics
UAE Geospatial Analytics Market
Analytics
Content Analytics and Discovery Software Market