
 North America IoT Software Market | 2026-2036
North America IoT Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America IoT Software Market Intelligence
The push for compliance with standards like the US IoT Cybersecurity Improvement Act is consolidating the vendor landscape around platforms with certified security features. Microsoft Corporation leverages its Azure IoT suite to provide end-to-end encrypted solutions for enterprise clients. Amazon Web Services sustains its market position through extensive cloud infrastructure and a vast partner ecosystem. Cisco Systems competes on the strength of its networking hardware and integrated security software for edge deployments.
IoT software comprises the platforms, middleware, and applications that manage connected devices, process telemetry data, and deliver analytics. These systems utilize communication protocols like MQTT to enable efficient data exchange between endpoints and cloud services. The primary purpose is to convert raw sensor data into actionable intelligence for industrial and commercial use cases. Cloud-based deployment models remain dominant, but edge computing is gaining significant share in applications requiring low latency, such as predictive maintenance. Within solution types, data analytics and security software represent the highest-value segments.
The regulatory environment is a critical factor shaping market access and product design. In the United States, the Federal Communications Commission (FCC) sets standards for wireless device connectivity and spectrum allocation. In Canada, regulations from bodies like Health Canada dictate the validation and security requirements for software embedded in connected medical devices. Consequently, vendor selection increasingly depends on a platform's demonstrated ability to navigate the fragmented regulatory requirements across different end-user industries.
Market Dynamics
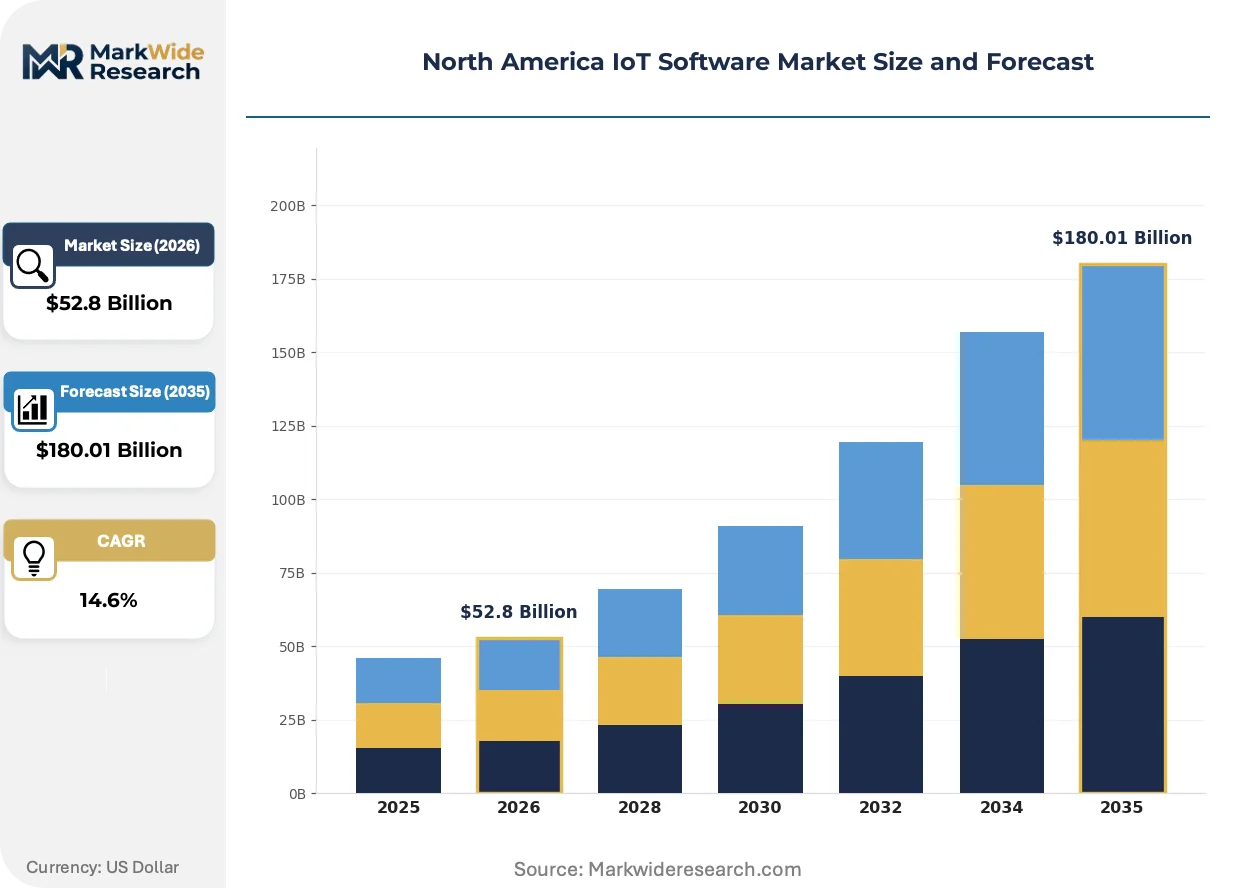
The convergence of industrial automation requirements with stringent cybersecurity mandates defines the market's structure. Demand for predictive maintenance in manufacturing, coupled with the enforcement of standards like the US IoT Cybersecurity Improvement Act, compels vendors to prioritize secure, industry-specific platform development.
Growth Catalysts
- Predictive Maintenance Demand:The manufacturing sector in the United States and Canada requires sophisticated software for monitoring industrial assets, reducing downtime, and optimizing maintenance schedules, creating a powerful demand signal for advanced analytics platforms.
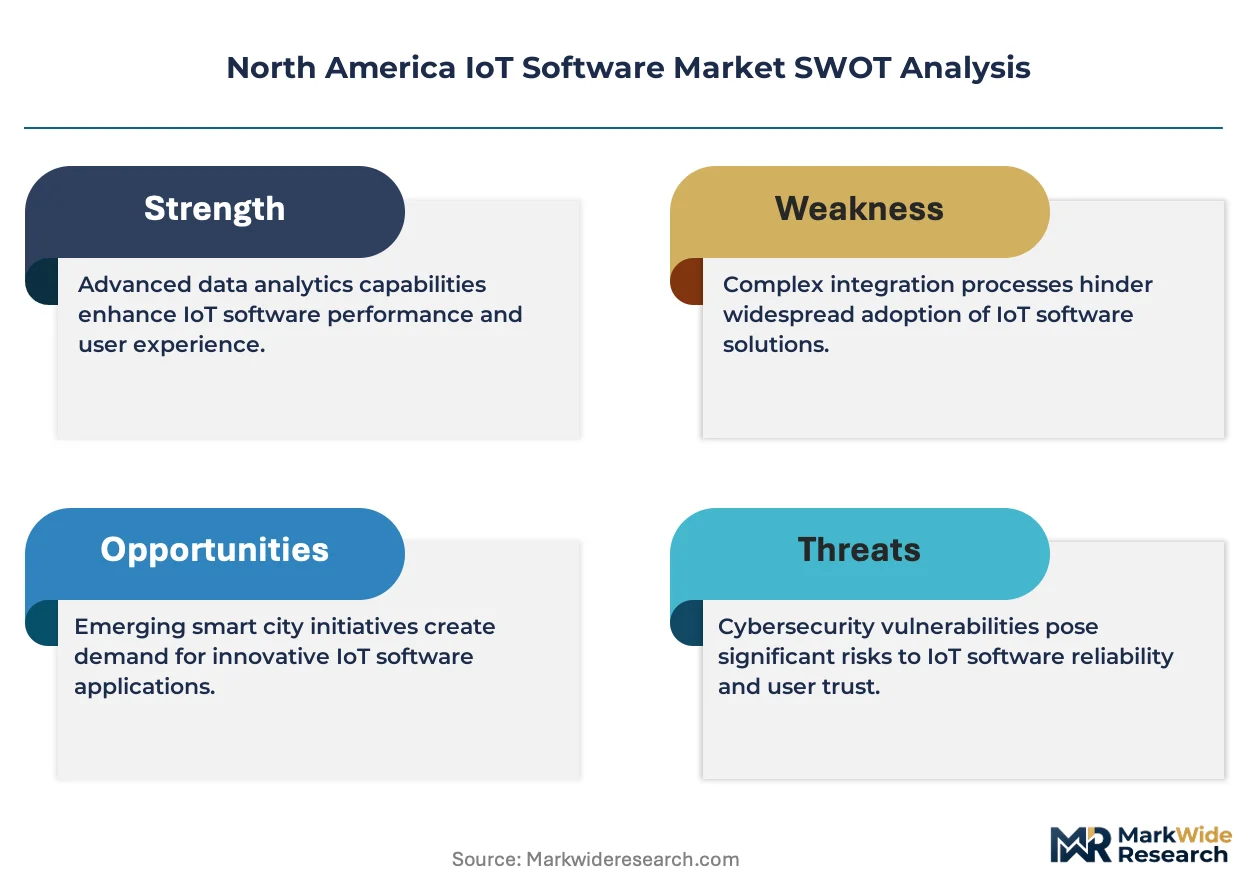
- Regulatory Security Mandates:The US IoT Cybersecurity Improvement Act and adherence to NIST frameworks are pushing public and private sector entities to adopt software with certified, built-in security features, favoring vendors with proven compliance.
- Edge Computing Adoption:The need for low-latency data processing in applications like industrial robotics and automated quality control is driving investment in edge software solutions that can analyze data locally without sending it to the cloud.
Market Restraints
- Legacy System Integration:High costs and technical complexities associated with integrating modern IoT software platforms with aging, proprietary operational technology (OT) and industrial control systems (ICS) hinder widespread adoption in established facilities.
- Fragmented Regulatory Environment:Navigating disparate requirements, such as FCC rules for wireless connectivity and Health Canada standards for medical device software, increases development costs and time-to-market for vendors targeting multiple industries.
- Cloud Provider Dependency:A heavy reliance on a small number of large-scale public cloud providers for backend infrastructure creates risks of vendor lock-in, limited negotiating power, and potential service disruptions for IoT software companies.
Strategic Opportunities
- Specialized Agricultural Solutions:Canada’s agricultural sector presents an underpenetrated market for IoT software tailored to precision farming, crop monitoring, and automated irrigation systems, offering significant growth potential for specialized vendors.
- Smart Grid and EV Infrastructure:The expansion of electric vehicle (EV) adoption creates a need for sophisticated software to manage charging networks, optimize energy consumption, and ensure grid stability across North America.
- Digital Twin Convergence:Combining IoT data streams with digital twin technology offers a major opportunity in sectors like aerospace and automotive, enabling highly accurate, real-time simulations for design, testing, and operational management.
Industry Challenges
- Cyber-Physical Skills Gap:A persistent shortage of professionals with expertise in both operational technology (OT) environments and modern IT cybersecurity practices complicates the secure deployment and management of industrial IoT systems.
- Interoperability Across Protocols:Ensuring seamless data exchange and interoperability between devices and platforms using diverse communication protocols, such as MQTT, CoAP, and legacy industrial standards, remains a significant operational hurdle for developers.
- Lengthy Certification Cycles:The time and expense required to achieve compliance with critical security frameworks, including those from NIST, can create substantial barriers to entry and slow down innovation cycles for new software providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America IoT Software Market |
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $180.01 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Type: Device Management, Data Analytics, Security, Network Management, Application Enablement Use Case: Smart Buildings, Predictive Maintenance, Asset Tracking, Energy Management, Environmental Monitoring End User Industry: Manufacturing, Agriculture, Transportation, Smart Cities, Utilities |
| Companies Covered | Microsoft Corporation, Amazon Web Services, IBM Corporation, Cisco Systems, Oracle Corporation, PTC, Siemens, SAP, MongoDB, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America IoT Software Market Strategic Shifts & Innovations
Platform evolution is accelerating toward specialized, secure-by-design architectures. This movement responds directly to industrial-scale data processing needs and heightened regulatory scrutiny over connected device ecosystems across the United States and Canada, fundamentally altering software design principles.
Edge computing platforms process data locally on or near a device, reducing reliance on centralized cloud servers for immediate analysis. The manufacturing and logistics sectors are adopting this technology to power low-latency applications like real-time asset tracking and automated quality control. This technology is expanding into new domains such as smart city traffic management and remote healthcare monitoring, where instantaneous data processing is essential.
The US IoT Cybersecurity Improvement Act establishes baseline security standards for IoT devices procured by the federal government. This legislation compels software vendors to integrate security features, such as vulnerability disclosure programs and secure update mechanisms, into the development lifecycle. The industrial automation segment is most affected, with platforms now prioritizing NIST framework compliance to access government and critical infrastructure contracts.
A definitive transition is occurring from one-time perpetual software licensing toward flexible, subscription-based consumption models. This trend disrupts traditional sales channels, favoring direct digital marketplaces and cloud provider ecosystems over conventional value-added resellers. This model is most prominent within the United States, where small and medium-sized enterprises seek lower initial capital expenditure and scalable solutions.
North America IoT Software Market Segmentation
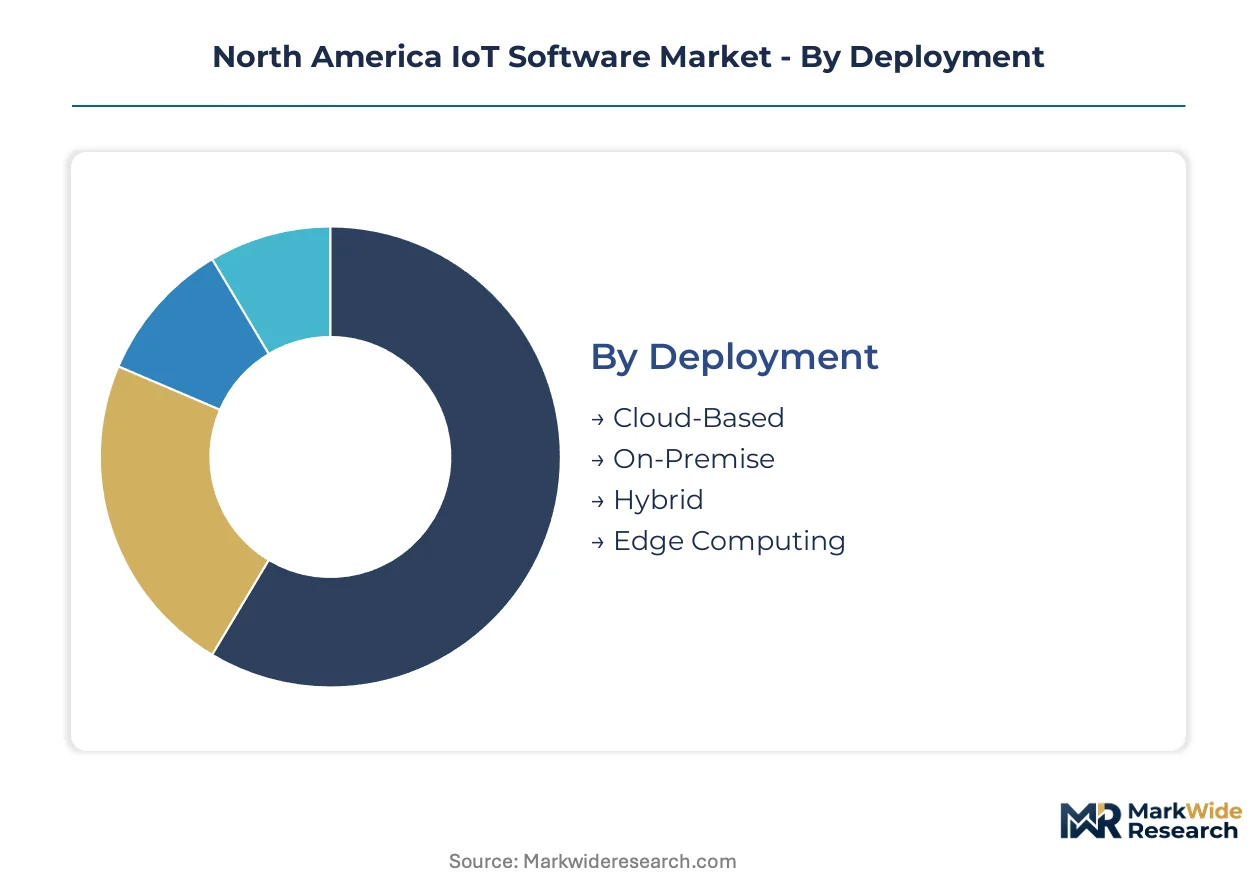
Understanding the North America IoT software market through its segmentation reveals how diverse operational needs and regulatory pressures shape product development and adoption. This granular view clarifies where specialized solutions are gaining traction and how different deployment models address specific enterprise requirements across the United States and Canada.
Deployment:
The North America IoT software market's deployment segmentation highlights varying compliance burdens, with certain models needing stringent adherence to frameworks like NIST for federal contracts and critical infrastructure. This influences architectural choices, particularly for government and defense applications.
- Cloud-Based:This model leverages public or private cloud infrastructure to host IoT platforms and applications, offering scalability, managed services, and broad accessibility. Its dominance stems from reduced upfront capital expenditure and the ability to process large datasets for analytics across diverse industries in North America.
- Edge Computing:Edge computing involves processing data closer to the source, on or near devices, reducing latency and bandwidth requirements for real-time applications. This model is gaining significant share in industrial settings across the US and Canada for applications like automated quality control and predictive maintenance.
- On-Premise:On-premise deployments involve installing and running IoT software on local servers within an organization's own data center. This model provides maximum control over data security and customization, often favored by entities with strict data governance policies or legacy infrastructure.
- Hybrid:Hybrid deployments combine elements of both cloud-based and on-premise models, allowing organizations to maintain sensitive data locally while leveraging cloud resources for scalability and advanced analytics. This approach balances control with flexibility for North American enterprises.
Leading the category by volume: Cloud-Based. Growing fastest: Edge Computing.
Solution Type:
Solution type segmentation delineates the core functionalities IoT software provides, with each category addressing distinct operational challenges for end-users across the region. This classification helps identify where development efforts are concentrated to deliver tangible business value.
- Data Analytics:This software processes raw telemetry from connected devices, applying machine learning and statistical methods to extract actionable insights. It enables predictive maintenance, operational optimization, and business intelligence across industrial corridors in the United States and Canada.
- Security:Security software provides authentication, encryption, threat detection, and vulnerability management for IoT devices and platforms, addressing stringent regulatory mandates like the US IoT Cybersecurity Improvement Act. It protects sensitive data and critical infrastructure from cyber threats.
- Device Management:Device management solutions enable the provisioning, configuration, monitoring, and remote control of IoT devices throughout their lifecycle. These tools ensure optimal performance and health for large fleets of connected assets.
- Network Management:Network management software oversees the connectivity and communication protocols between IoT devices, gateways, and cloud platforms. It ensures reliable data flow and efficient utilization of network resources, which is crucial for large-scale deployments.
- Application Enablement:Application enablement platforms (AEPs) provide tools and services for developers to build, deploy, and manage IoT applications quickly. They abstract away underlying complexities, accelerating time-to-market for specialized solutions.
Market dynamics indicate that Data Analytics commands substantial revenue, while Security is experiencing rapid expansion.
Use Case:
The segmentation by use case highlights the specific problems IoT software is designed to solve for various industries, revealing the practical applications driving demand. Each use case addresses unique challenges in terms of efficiency, safety, or resource management.
- Predictive Maintenance:This use case involves monitoring equipment performance data to anticipate potential failures, allowing for proactive maintenance and minimizing costly downtime. The manufacturing sector in the United States and Canada drives significant demand for these advanced analytics platforms.
- Smart Buildings:Smart building solutions integrate IoT software to optimize energy consumption, enhance occupant comfort, and improve security within commercial and residential structures. These systems manage HVAC, lighting, and access control for operational efficiency.
- Asset Tracking:Asset tracking solutions utilize IoT sensors and software to monitor the location and status of physical assets in real-time. This enhances supply chain visibility and inventory management across logistics and transportation sectors.
- Energy Management:Energy management software optimizes power consumption in industrial facilities, commercial buildings, and smart grids. It analyzes usage patterns to identify savings opportunities and improve sustainability.
- Environmental Monitoring:This use case involves deploying IoT sensors to collect data on environmental conditions such as air quality, water levels, and temperature. It supports regulatory compliance and resource conservation efforts.
The largest share is held by Predictive Maintenance, with Smart Buildings showing significant momentum.
End User Industry:
End user industry segmentation categorizes the primary sectors adopting IoT software, reflecting how different industry-specific needs influence market penetration. Each industry presents unique operational contexts and regulatory landscapes for software providers.
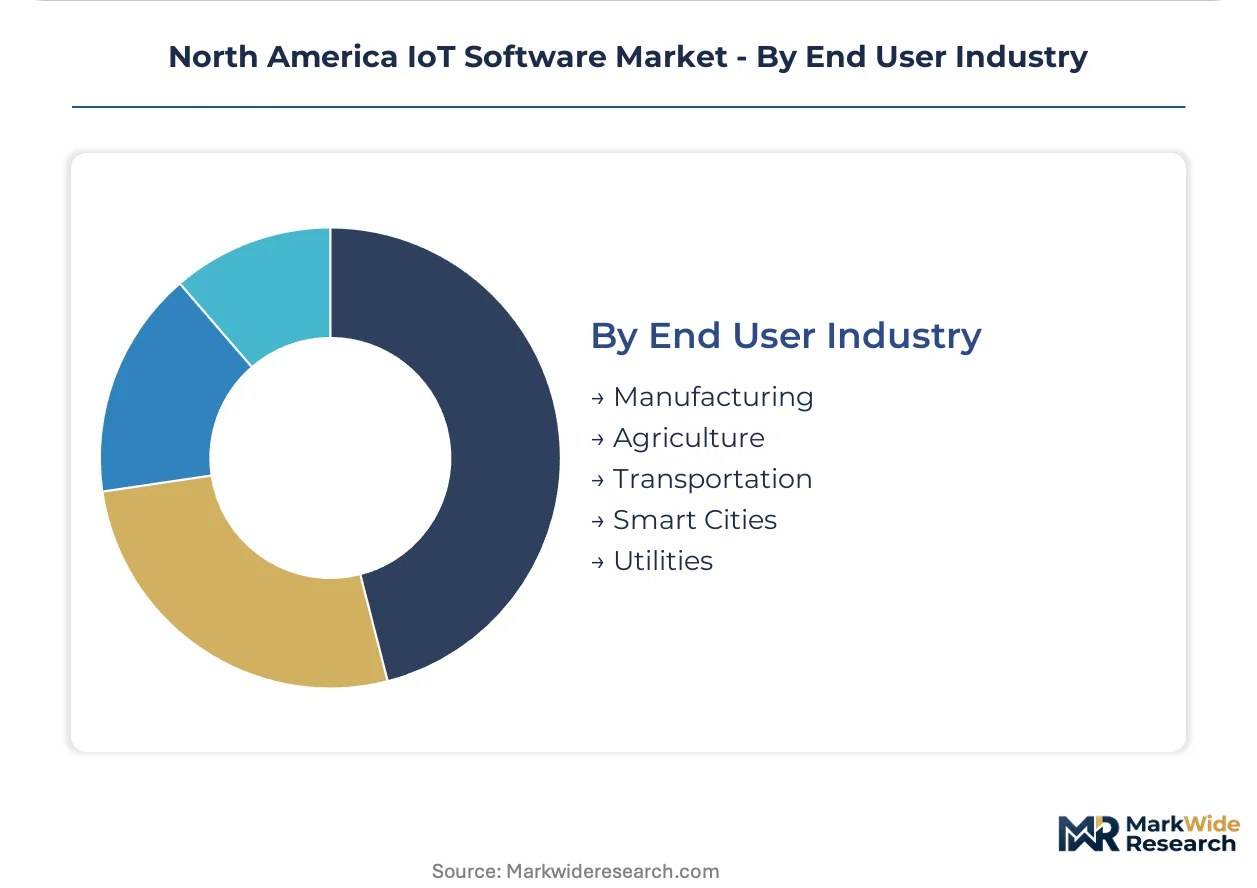
- Manufacturing:The manufacturing sector uses IoT software for factory automation, quality control, and predictive maintenance of industrial machinery. Its demand for sophisticated platforms is a primary growth engine across North America.
- Agriculture:Canada’s agricultural sector leverages IoT software for precision farming, crop monitoring, automated irrigation, and livestock management. This represents a significant growth opportunity for specialized solutions.
- Transportation:The transportation industry adopts IoT software for fleet management, logistics optimization, smart traffic systems, and connected vehicle applications. These solutions improve efficiency and safety.
- Smart Cities:Smart cities utilize IoT software for urban infrastructure management, including public safety, waste management, and environmental monitoring. These deployments enhance citizen services and urban sustainability.
- Utilities:The utilities sector employs IoT software for smart grid management, remote monitoring of infrastructure, and optimizing energy distribution. This supports grid stability and operational resilience.
Revenue concentration is highest in Manufacturing, and Agriculture exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The concentration of IoT software demand in North America is significantly influenced by established industrial corridors and emerging technology hubs. These zones attract substantial investment in advanced manufacturing and smart infrastructure. Government incentives and strategic initiatives further bolster the adoption of IoT solutions.
United States
The United States drives significant demand for IoT software, particularly for predictive maintenance in its vast manufacturing sector and for smart grid initiatives. The US IoT Cybersecurity Improvement Act and adherence to NIST frameworks shape development priorities for secure solutions. Industrial clusters in the Midwest, like those around Detroit, are adopting advanced analytics for factory automation and operational efficiency.
Canada
Canada's agricultural sector generates demand for specialized IoT software in precision farming and automated irrigation systems. Health Canada regulations influence software development for connected medical devices, ensuring stringent validation and security. Technology hubs in Ontario, particularly Toronto and Waterloo, foster innovation in IoT platforms for various industrial applications.
Mexico
Mexico's automotive manufacturing sector fuels demand for IoT software in supply chain optimization and factory automation. The country's evolving regulatory landscape for data protection and industrial safety influences software deployment. Industrial zones in the Bajío region leverage IoT for efficient production lines and enhanced logistics within the automotive supply chain.
Texas (United States)
Texas exhibits strong demand for IoT software in energy management, particularly within its oil and gas sector and expanding renewable infrastructure. State regulations governing grid stability and environmental monitoring drive compliance for utility-focused solutions. Major metropolitan areas like Houston serve as centers for energy technology firms developing sophisticated IoT platforms.
North America IoT Software Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists to capture market share in North America's IoT software landscape. The market structure exhibits a blend of consolidation among major cloud providers and fragmentation among niche solution developers. Strategic archetypes include established enterprise software vendors, cloud infrastructure giants, and specialized vertical solution providers. Companies frequently engage in strategic partnerships to expand their ecosystem reach and pursue targeted acquisitions to integrate advanced functionalities.
Within the enterprise technology segment, Microsoft Corporation exemplifies a cloud-centric approach, leveraging its Azure IoT suite for end-to-end encrypted solutions. Amazon Web Services, a US-based entity, anchors a significant portion of the market through its extensive cloud infrastructure and broad partner ecosystem. Cisco Systems, another major US corporation, occupies a strong position by integrating its networking hardware with security software for edge deployments, addressing critical infrastructure needs.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| IBM Corporation |
| Cisco Systems |
| Oracle Corporation |
| PTC |
| Siemens |
| SAP |
| MongoDB |
| Others |
Cost & Logistics Intelligence
Divergence between highly certified and generic IoT software platforms manifests in both pricing and supply chain configurations. Secure, compliant solutions command premium pricing, while basic offerings face commoditization, influencing vendor investment in specialized development and cloud infrastructure.
Pricing Analysis
Premium pricing for immediate deployment of secure, certified IoT software reflects its critical role in industrial and government applications. The dominant pricing model is subscription-based SaaS, often tiered by features and data volume. Price differentiation stems from NIST framework compliance and the level of managed services bundled with the software. Pricing pressure stems from the availability of open-source components and increasing competition among platform providers. Small and medium-sized enterprises exhibit the highest price sensitivity, while critical infrastructure operators prioritize security and compliance over cost.
Supply Chain Analysis
Dual-sourcing requirements for critical components and services shape the IoT software supply chain, particularly for federal contracts. The supply chain concentrates heavily in the United States and Canada, reflecting the density of cloud infrastructure and skilled software developers. Key dependencies include cloud infrastructure services from major providers like Amazon Web Services and Microsoft Azure, alongside specialized cybersecurity modules. A structural risk is vendor lock-in with dominant cloud providers, potentially limiting negotiating power for software companies. Distribution runs through direct digital marketplaces and cloud provider ecosystems, increasingly displacing traditional value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America IoT software market is consolidating, with stringent regulatory compliance from the US IoT Cybersecurity Improvement Act forcing smaller, non-compliant players to exit or be acquired.
For Market Incumbents: Acquire specialized vertical solution providers focusing on specific industrial use cases like predictive maintenance or smart grid management. This defensive move counters niche specialists emerging with highly tailored offerings. Incumbents should invest heavily in certification for NIST frameworks and R&D for edge AI capabilities to maintain a competitive edge against evolving technological landscapes.
For New Entrants and Emerging Players: System integrators and specialized industrial consultants offer crucial market access. Target underpenetrated segments such as Canada's agricultural sector for precision farming or smart grid solutions for electric vehicle infrastructure. A focused go-to-market angle involves developing highly compliant, secure-by-design software platforms tailored to specific regulatory mandates within these niche industries.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by major cloud infrastructure providers or established enterprise software vendors seeking to expand their IoT portfolios. The long-term viability of platforms addressing critical infrastructure needs and stringent regulatory compliance remains strong. A key signal to watch is the increasing volume of M&A activity for niche security or edge AI software firms.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Seamlessly combining diverse IoT functionalities enhances user experience and reduces deployment complexity for enterprise clients. |
| Strategic Partnership | Collaborating with hardware manufacturers or industry-specific solution providers expands market reach and accelerates product development. |
| Acquisition of Specialist Firm | Integrating targeted cybersecurity or advanced analytics capabilities strengthens a vendor's offering and intellectual property portfolio. |
| Product Launch | Introducing innovative edge computing solutions addresses low-latency requirements for industrial automation and real-time processing. |
| Geographic Expansion | Extending market presence into underserved regions within North America captures new demand from specific industrial corridors. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, providing a comprehensive market overview. Primary interviews with CTOs, industrial automation engineers, IT procurement officers, and cybersecurity specialists across North America validated market trends. This approach combined bottom-up data aggregation with top-down market sizing for robust triangulation.
The forecast framework modeled market dimensions at a granular level, including deployment model, solution type, use case, end-user industry, and regional adoption pattern across the analysis window. Volume and value outputs reflected a triangulated approach, deriving CAGRs from segment-specific growth rates. Key industry-specific forecast inputs included IoT device shipment data and industrial automation investment levels.
Caveats apply where unforeseen regulatory changes, rapid technological disruptions, or major economic downturns could materially shift the outlook. Forecasts reflect assumptions regarding current regulatory trajectory and technological adoption curves. Deviation in industrial investment patterns would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
US Smart Thermostat Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
Global IoT Battery Market
Internet of Things (IoT)
IoT Software Engineering Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
Global IoT Solutions and Services Market
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
Europe Cellular IoT Market
Internet of Things (IoT)
IoT Connected Machines Market
Internet of Things (IoT)
IoT Device Management Platform Market
Internet of Things (IoT)
Internet of Medical Things (Iomt) Market
Internet of Things (IoT)
IoT Data Management Market
Internet of Things (IoT)
LTE IoT Market
Internet of Things (IoT)
Global IoT Based Asset Tracking and Monitoring Market
Internet of Things (IoT)
Internet of Things (IoT) Connected Cars Market