
 Massive IoT Market | 2026-2036
Massive IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Massive IoT Market Outlook
The EU AI Act is decoupling compliance costs from hardware margins for device manufacturers deploying autonomous edge analytics. Cisco Systems leverages its networking infrastructure to sustain enterprise-grade security architectures across distributed sensor grids. Qualcomm Technologies anchors its position through integrated modem-to-cloud silicon stacks purpose-built for low-power wide-area specifications.
Massive IoT denotes large-scale deployments of billions of low-complexity, low-power connected devices transmitting small data payloads across extended coverage areas, typically operating on sub-gigahertz spectrum with ten-year battery life targets and sub-fifty-dollar unit economics. Its primary purpose is enabling pervasive machine-to-machine telemetry for operational visibility in asset tracking, environmental monitoring, and predictive maintenance workflows. The LPWAN technology segment dominates connectivity volumes for rural and indoor penetration scenarios where cellular density remains uneconomical. Industrial Automation applications within the deployment category generate the densest margin pools due to integration complexity and uptime guarantees.
The Federal Communications Commission in the United States governs unlicensed spectrum allocations for IoT radios, while the European Telecommunications Standards Institute mandates interoperability benchmarks under EN 303 645 cybersecurity frameworks. China's Ministry of Industry and Information Technology enforces GB-standard certification for networked devices entering domestic infrastructure tenders. Stakeholders must weigh spectrum licensing trajectories against silicon roadmap commitments when committing to multi-decade deployment architectures.
Market Dynamics
The EU AI Act is forcing device manufacturers to architect algorithmic audit trails into firmware layers, decoupling compliance engineering from hardware margin structures and redistributing R&D budgets toward explainable edge analytics.
Growth Catalysts
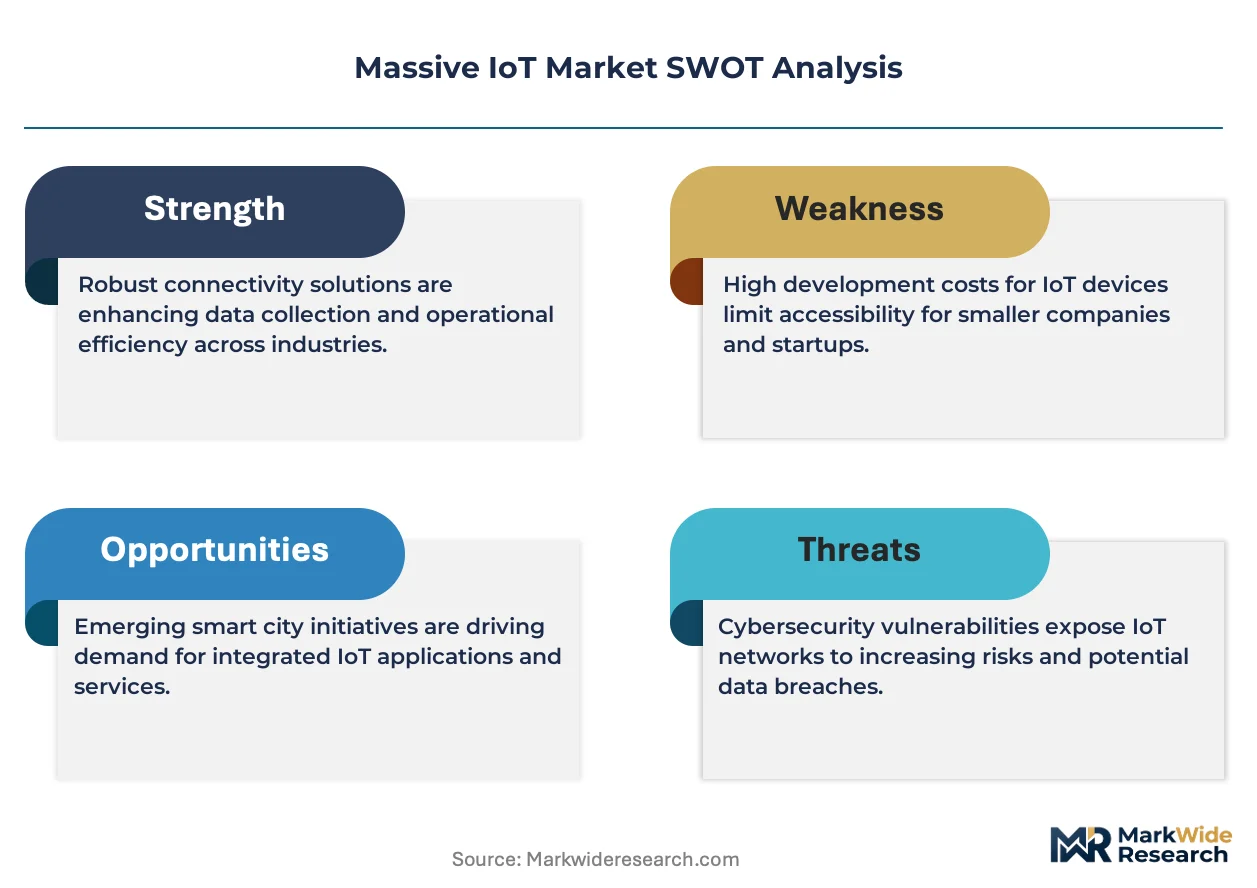
- LPWAN spectrum liberalization:The FCC's unlicensed sub-gigahertz allocations in the United States are enabling ten-year battery-life targets for rural asset-tracking deployments without cellular licensing overhead.
- Industrial predictive maintenance:German automotive clusters around Stuttgart are mandating machine-to-machine telemetry integration to compress unplanned downtime intervals below four hours.
- EN 303 645 cybersecurity frameworks:ETSI's interoperability benchmarks are accelerating procurement standardization across European smart home energy management platforms.
Market Restraints
- Silicon supply concentration:Taiwan-based foundry capacity for sub-fifty-dollar modem-to-cloud chipsets creates exposure to geopolitical friction and allocation rationing.
- GB-standard certification timelines:China's MIIT enforcement of networked device tenders extends product launch cycles by eight to fourteen months for foreign entrants.
- Cellular density economics:Urban LPWAN substitution by 5G RedCap is compressing addressable market boundaries for rural-penetration business models.
Strategic Opportunities
- India's industrial corridor expansion:The PLI scheme for electronics manufacturing is attracting module assembly capacity to Gujarat and Tamil Nadu for export-scale production.
- Agricultural soil monitoring:Sub-saharan African cotton and coffee cooperatives are piloting low-power moisture telemetry without legacy cellular infrastructure dependency.
- CSRD-aligned carbon accounting:European asset-intensive sectors are procuring sensor grids to automate Scope 3 emissions tracking for supply chain disclosure mandates.
Industry Challenges
- Firmware security engineering scarcity:Embedded systems architects with cryptographic implementation expertise command premium compensation that mid-scale device OEMs cannot absorb.
- Legacy SCADA integration:Brownfield industrial automation sites in Germany's Ruhr region require protocol translation layers that degrade real-time telemetry reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Massive IoT Market |
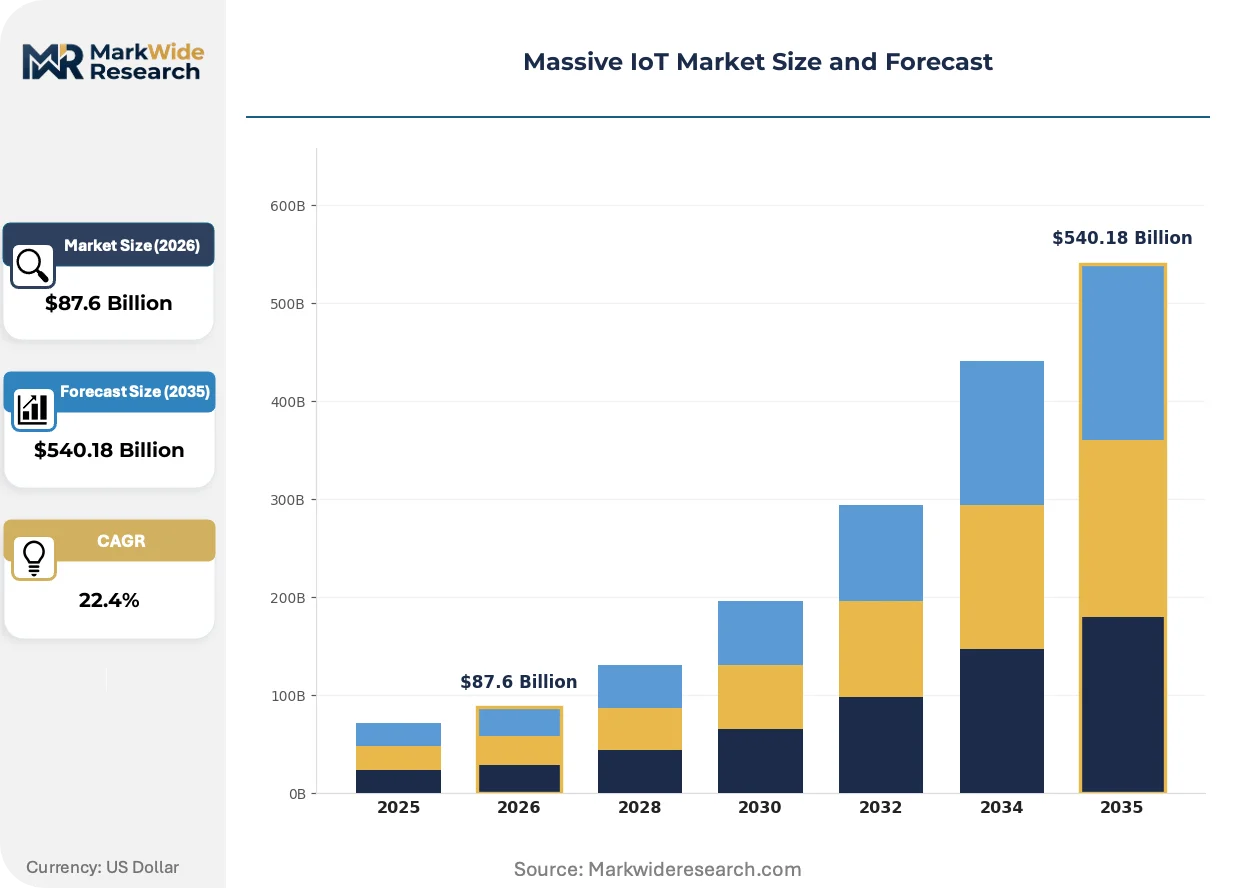
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $540.18 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Application: Smart Home, Industrial Automation, Transportation, Healthcare Technology: LPWAN, Cellular, Wi-Fi, Bluetooth End User: Utilities, Manufacturing, Retail, Agriculture |
| Companies Covered | Microsoft, Amazon Web Services, Cisco Systems, Intel Corporation, Huawei Technologies, IBM, Qualcomm Technologies, Texas Instruments, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Massive IoT Market Strategic Shifts
Edge-native artificial intelligence is collapsing the latency budget for autonomous sensor decisions, compressing the traditional cloud-reliant architecture into localized inference clusters that operate on intermittent connectivity.
Ultra-narrowband modulation is converging with satellite backhaul to extend coverage into maritime and remote mining corridors where terrestrial LPWAN infrastructure remains uneconomical. Offshore logistics operators in Norway's North Sea oil fields are deploying hybrid terrestrial-satellite sensor grids for vessel tracking. This convergence is eliminating the historical trade-off between power consumption and geographic reach in Massive IoT connectivity procurement.
The EU AI Act's algorithmic transparency requirements are mandating documentation standards for edge inference models deployed in critical infrastructure networks. Industrial automation vendors serving Germany's automotive sector are restructuring firmware development workflows to embed audit logging at the silicon layer. This regulatory pressure is accelerating consolidation among device manufacturers lacking in-house compliance engineering capacity.
Buyer procurement for sensor deployments is fragmenting from centralized IT departments toward operational technology managers with direct P&L accountability for uptime metrics. Manufacturing facilities in Japan's Kansai region are delegating vendor selection to plant-level maintenance teams rather than corporate technology procurement functions. This behavioral shift is compressing sales cycles for vendors with localized service presence while disadvantaging pure-play hardware distributors.
Massive IoT Market Segmentation
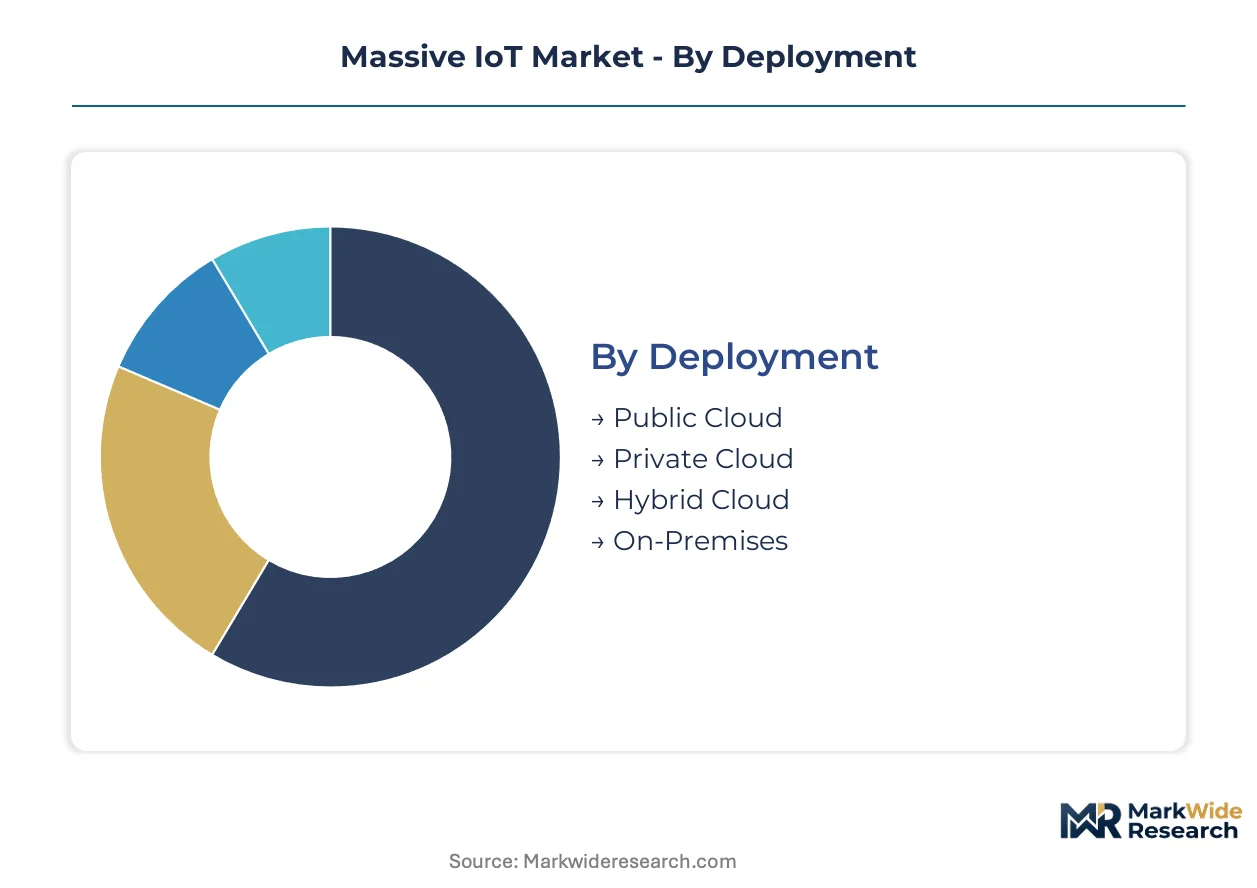
Massive IoT deployments require precise matching between connectivity economics and operational constraints. Segmentation reveals where sub-fifty-dollar unit costs intersect with ten-year battery life mandates across divergent infrastructure maturity levels.
Deployment:
Buyers diverge based on data sovereignty requirements and latency tolerance for autonomous edge decisions.
- Public Cloud:Multi-tenant infrastructure delivers elastic compute for sensor data lakes without capital deployment. Demand concentrates among smart home energy management platforms in Germany's industrial corridor seeking rapid scaling without facility investment.
- Private Cloud:Dedicated tenant environments enforce cryptographic isolation for predictive maintenance telemetry. German automotive clusters around Stuttgart mandate this architecture to satisfy EN 303 645 cybersecurity frameworks for machine-to-machine uptime guarantees.
- Hybrid Cloud:Burst capacity bridges on-premises inference with cloud analytics for intermittent connectivity scenarios.
- On-Premises:Air-gapped deployments serve critical infrastructure with zero external data egress.
Volume sits with Public Cloud; growth tilts toward Hybrid Cloud.
Application:
Margin concentration tracks integration complexity and contractual uptime penalties.
- Industrial Automation:Dense sensor grids compress unplanned downtime below four-hour thresholds through predictive maintenance workflows. Demand concentrates in Germany's Ruhr region brownfield sites requiring protocol translation layers for legacy SCADA integration.
- Smart Home:Residential energy management platforms leverage LPWAN for sub-gigahertz penetration through building materials. EU AI Act algorithmic transparency requirements are restructuring firmware development for connected device networks.
- Transportation:Asset tracking across maritime corridors exploits satellite-LPWAN convergence.
- Healthcare:Remote patient monitoring operates under HIPAA and GDPR dual compliance for biometric telemetry.
Revenue concentrates in Industrial Automation; expansion accelerates fastest in Smart Home.
Technology:
Spectrum licensing economics determine rural versus urban deployment feasibility.
- LPWAN:Ultra-narrowband modulation achieves ten-year battery life on unlicensed sub-gigahertz allocations. FCC liberalization in the United States enables rural asset tracking without cellular overhead; Norway's North Sea oil fields deploy hybrid terrestrial-satellite variants.
- Cellular:Licensed spectrum guarantees quality-of-service for critical infrastructure with defined service level agreements.
- Wi-Fi:High-throughput local area coverage serves dense indoor environments with existing infrastructure.
- Bluetooth:Short-range mesh topologies optimize for consumer proximity applications with smartphone integration.
Connectivity volume favors LPWAN; Cellular gains share where 5G RedCap substitutes for density economics.
End User:
Procurement authority is fragmenting from centralized IT toward operational technology managers with direct P&L accountability.
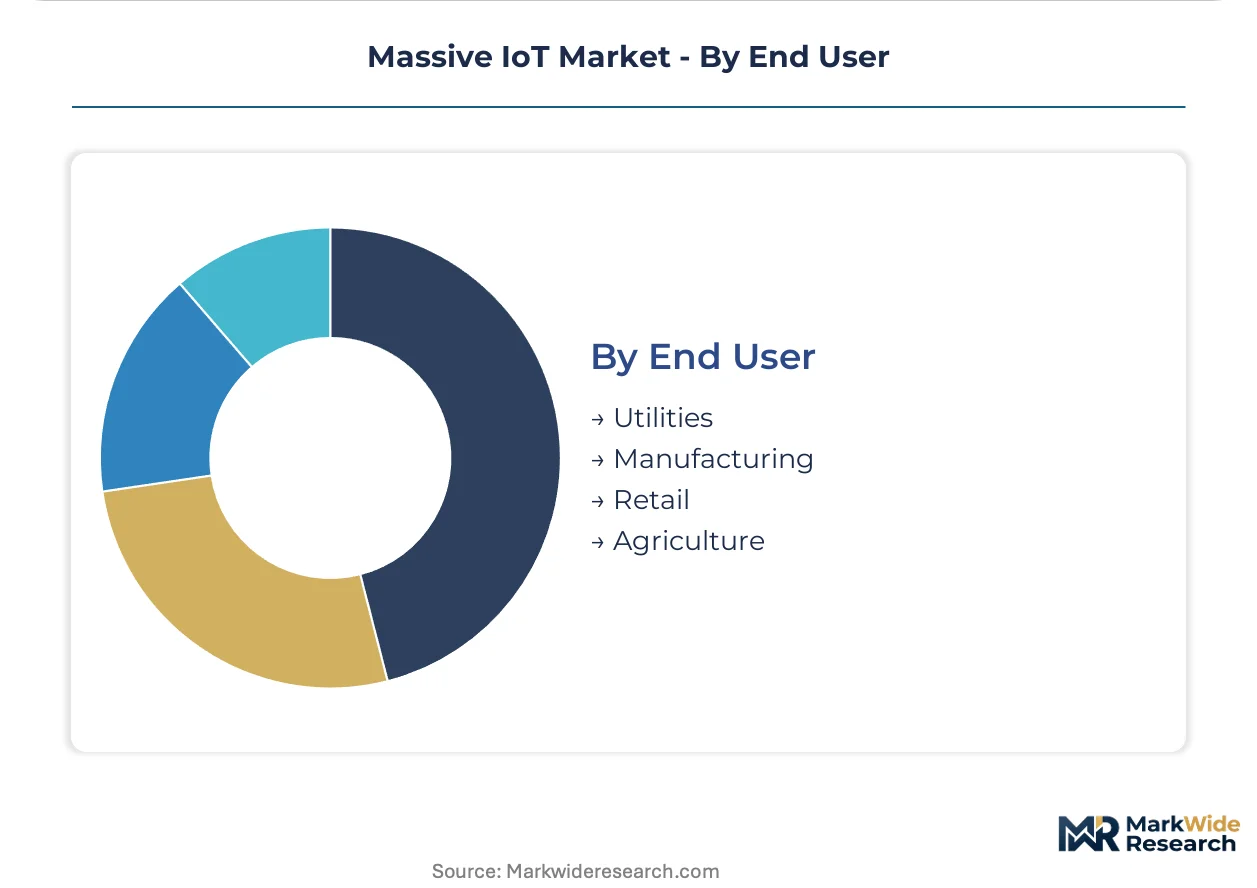
- Utilities:Grid modernization mandates drive smart meter deployments with CSRD-aligned carbon accounting for Scope 3 disclosure.
- Manufacturing:Plant-level maintenance teams in Japan's Kansai region now control vendor selection for uptime metrics.
- Retail:Cold chain monitoring exploits low-power tags for inventory visibility without infrastructure investment.
- Agriculture:Sub-saharan African cotton cooperatives pilot soil moisture telemetry without legacy cellular dependency.
Installed base dominates Manufacturing; Agriculture climbs fastest as satellite backhaul eliminates infrastructure gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's electronics manufacturing clusters in Gujarat and Tamil Nadu concentrate module assembly capacity under the PLI scheme, drawing export-scale production away from traditional East Asian hubs.
United States
FCC unlicensed sub-gigahertz allocations enable rural asset-tracking deployments with ten-year battery-life targets. The Federal Communications Commission governs spectrum economics without cellular licensing overhead. Midwest agricultural cooperatives pilot soil moisture telemetry across Iowa and Nebraska corn belts.
Germany
Automotive clusters around Stuttgart mandate machine-to-machine telemetry integration to compress unplanned downtime below four hours. The EU AI Act tightens algorithmic transparency requirements for connected device networks deployed in critical infrastructure. Brownfield industrial sites in the Ruhr region require protocol translation layers for legacy SCADA integration.
China
MIIT enforces GB-standard certification for networked devices entering domestic infrastructure tenders, extending foreign product launch cycles. The Ministry of Industry and Information Technology controls domestic market access through mandatory testing protocols. Yangtze River Delta manufacturing corridors concentrate silicon packaging capacity for modem-to-cloud chipsets.
Norway
North Sea oil field operators deploy hybrid terrestrial-satellite sensor grids for offshore vessel tracking. ESA-aligned space agencies support ultra-narrowband modulation convergence with satellite backhaul. Stavanger-based logistics consortia eliminate the historical power-versus-reach trade-off in maritime connectivity procurement.
India
PLI scheme incentives attract module assembly capacity to Gujarat and Tamil Nadu for export-scale production. The Telecom Regulatory Authority of India governs spectrum allocation for low-power wide-area deployments. Bangalore hardware accelerators prototype edge-native inference clusters for intermittent connectivity scenarios.
Massive IoT Market Competitive Environment
United States producers anchor one tier; Chinese specialists hold cost-optimized silicon fabrication. The vendor base fragments across networking infrastructure providers, semiconductor designers, and cloud platform operators. Three archetypes dominate: integrated modem-to-cloud stack suppliers, enterprise security architecture vendors, and hyperscale cloud telemetry platforms. Consolidation pressure favors M&A among compliance-engineering-constrained device manufacturers; capacity expansion concentrates in India under electronics manufacturing incentive schemes.
Within the integrated silicon tier, Qualcomm Technologies and Texas Instruments exemplify modem-to-cloud stack specialization. Cisco Systems occupies a position among enterprise-grade security architecture providers for distributed sensor grids. These three represent distinct competitive vectors: silicon integration depth, networking infrastructure leverage, and firmware-layer compliance engineering capacity.
| Leading Market Players |
|---|
| Microsoft |
| Amazon Web Services |
| Cisco Systems |
| Intel Corporation |
| Huawei Technologies |
| IBM |
| Qualcomm Technologies |
| Texas Instruments |
| STMicroelectronics |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed electronics manufacturing incentives in India and Vietnam are reshaping ownership patterns across module assembly tiers, tightening pricing discipline among legacy East Asian suppliers while compressing margin buffers for mid-scale device OEMs lacking captive silicon access.
Pricing Analysis
Short-lead-time premiums command fifteen to twenty percent uplifts over standard-cycle contracts, while spot inventory liquidations in Taiwan-based foundry channels trade at distressed discounts. The dominant structure runs on volume-scaled per-unit transactional pricing with tiered certification premiums—EN 303 645 compliance adds measurable cost, GB-standard certification extends timelines. Cost compression in sub-fifty-dollar modem chipsets intensifies as India's PLI scheme attracts alternative assembly capacity. Agricultural cooperatives in Sub-Saharan Africa exhibit highest price sensitivity; German automotive clusters absorb premiums for four-hour uptime guarantees.
Supply Chain Analysis
Dual-sourcing mandates from European industrial automation buyers now require qualified secondary suppliers for sub-gigahertz modem silicon, forcing qualification overhead onto mid-tier device manufacturers. Geographic concentration centers on Taiwan for foundry capacity, China for GB-standard certification testing, and India for export-scale module assembly under PLI incentives. Raw material dependencies span rare earth substrates for RF front-ends, lithium-ion cell chemistries for decade-life power budgets, and epoxy molding compounds for environmental sealing. Single-source vulnerability runs through Taiwan-based foundry allocation rationing. Distribution feeds from contract manufacturers through systems integrators to plant-level OT procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LPWAN-to-satellite convergence is displacing pure terrestrial connectivity architectures, creating transition-phase positioning windows for vendors with hybrid backhaul capabilities and firmware-layer compliance engineering.
For Market Incumbents: Anchor enterprise-grade security architectures through backward integration into cryptographic firmware layers, countering Qualcomm's modem-to-cloud silicon dominance. Defend against 5G RedCap substitution by embedding ten-year battery-life guarantees into service contracts. Prioritize EN 303 645 pre-certification pipelines to compress German automotive procurement cycles. For New Entrants and Emerging Players: Direct-to-OT procurement channels bypass entrenched distributor relationships in Japan's Kansai manufacturing belt. Target agricultural soil monitoring in Sub-Saharan Africa where satellite backhaul eliminates cellular infrastructure dependency. Lead with CSRD-aligned carbon accounting sensor grids to capture European asset-intensive sector procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-engineering-constrained device manufacturers in Germany's industrial corridor facing EU AI Act restructuring costs. Long-term viability hinges on firmware-layer audit trail capabilities across intermittent connectivity scenarios. Watch India's PLI scheme capacity absorption rates as inflection indicator for East Asian supply rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native AI Firmware Development | Compresses latency budgets for autonomous sensor decisions below cloud-reliant thresholds. |
| Hybrid Terrestrial-Satellite Certification | Opens maritime and remote mining corridors to ultra-narrowband LPWAN deployments. |
| EU AI Act Compliance Engineering | Mandates algorithmic audit trails for critical infrastructure network tenders. |
| India PLI Scheme Manufacturing Expansion | Attracts export-scale module assembly capacity to Gujarat and Tamil Nadu clusters. |
| Legacy SCADA Protocol Translation | Enables brownfield industrial automation integration in Germany's Ruhr region. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with semiconductor procurement leads, OT maintenance directors at German automotive facilities, LPWAN network operators, and firmware security architects. FCC spectrum allocation dockets, ETSI EN 303 645 implementation guidelines, and MIIT GB-standard certification timelines provided regulatory trajectory inputs. Bottom-up unit economics modeling triangulated against top-down connectivity volume projections from national telecom regulators.
Data-stream reconciliation across deployment model segmentation, application complexity tiers, and spectrum licensing economics generated consistent volume and value outputs across the projection horizon. CAGRs derived from fitted growth curves against historical LPWAN connection density trajectories and cellular substitution elasticity parameters. Modeled dimensions included public-private-hybrid-on-premises deployment splits, industrial automation versus smart home application margins, and LPWAN-cellular-WiFi-Bluetooth technology shares.
Inputs from ETSI working group disclosures and Indian PLI scheme beneficiary lists were available through the study window; gaps in real-time foundry allocation data from Taiwan-based suppliers introduce uncertainty bands around silicon cost assumptions. Deviation in FCC unlicensed spectrum policy or MIIT certification timeline enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
AI in IoT Market
Internet of Things (IoT)
Cellular Internet of Things (IoT) Devices Market
Internet of Things (IoT)
Airline IoT Market
Internet of Things (IoT)
Iot-Enabled Devices Market
Internet of Things (IoT)
Global IoT in Aerospace and Defense Market
Internet of Things (IoT)
Global Open IoT Platform Market
Internet of Things (IoT)
Maritime Internet of Things Market
Internet of Things (IoT)
North America Internet of Things Devices Market
Internet of Things (IoT)
Global Internet of Behaviors Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market
Internet of Things (IoT)
IoT Device Management Platform Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
IoT in Retail Market