
 Cloud-Based POS Market | 2026-2036
Cloud-Based POS Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud-Based POS Market Outlook
Mid-sized restaurant chains is reorganizing demand away from legacy retail deployments toward hospitality-centric platforms. Toast leverages deep vertical integration into kitchen display systems and payroll modules to anchor its position in full-service dining. Block sustains brand strength among quick-service operators through its Cash App ecosystem and hardware-software bundling. Lightspeed competes aggressively in multi-location hospitality groups across North America and Europe with inventory-management specialization.
Cloud-based POS systems process transactions through internet-connected terminals, tablets, or mobile devices, with data stored on remote servers rather than local hard drives; typical architectures require TLS 1.3 encryption, 99.99% uptime SLAs, and API-first design for third-party integrations. The primary commercial purpose centers on unifying sales, inventory, and customer data across distributed locations while reducing on-premise IT overhead. Mobile POS leads transaction volume growth in tableside and curbside service environments, while integrated POS captures the deepest margin pools through subscription add-ons for payroll, loyalty, and accounting. Terminal POS remains mature in big-box retail, where replacement cycles stretch past five years and hardware durability outweighs software agility.
PCI DSS governs payment card data security across all deployments, with Level 1 merchants undergoing annual on-site audits that shape vendor selection criteria. The EU AI Act and GDPR impose algorithmic transparency and data-localization requirements on European deployments, particularly for automated fraud-detection features. In the United States, state-level biometric privacy laws in Illinois and Texas restrict how facial-recognition loyalty tools integrate with POS workflows. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs become a decisive factor in vendor consolidation.
Market Dynamics
PCI DSS Level 1 audit mandates are compressing vendor selection cycles for mid-sized restaurant chains, forcing consolidation toward platforms with pre-certified encryption stacks and documented TLS 1.3 implementations.
Growth Catalysts
- PCI DSS Compliance Mandates:Level 1 merchant audit requirements tighten data security standards for payment processing, elevating demand for certified cloud architectures with documented encryption protocols.
- Mobile POS Hardware:Tableside and curbside service environments drive transaction volume growth through tablet-based terminals that reduce server transit time and improve table turnover rates.
- API-First Platform Design:Open integration frameworks enable seamless connectivity between POS systems, kitchen display systems, and third-party payroll modules, reducing IT overhead for multi-location operators.
Market Restraints
- Internet Dependency Risk:Cloud architectures require persistent connectivity; outages breach 99.99% uptime SLAs and halt transaction processing, exposing merchants to revenue loss during network failures.
- Data Localization Requirements:GDPR and EU AI Act impose algorithmic transparency and server-location constraints on European deployments, increasing infrastructure costs for cross-border hospitality groups.
- Legacy Terminal Replacement Inertia:Big-box retail segments exhibit extended hardware cycles exceeding five years, delaying cloud migration where durability concerns outweigh software agility benefits.
Strategic Opportunities
- Biometric Loyalty Integration:Facial-recognition payment authentication creates frictionless checkout experiences, though Illinois and Texas state privacy laws require explicit consent frameworks for deployment.
- Payroll Module Bundling:Subscription add-ons for tip distribution and labor scheduling capture deeper margin pools within full-service dining segments seeking unified workforce management.
- Multi-Location Inventory Synchronization:Real-time stock visibility across distributed kitchens and warehouses addresses chronic waste reduction priorities for hospitality groups operating centralized procurement.
Industry Challenges
- TLS 1.3 Migration Complexity:Legacy payment terminals lack native support for modern encryption protocols, requiring hardware refresh cycles that strain capital allocation for smaller operators.
- Cross-Jurisdictional Compliance Burden:Divergent state-level biometric privacy laws and federal PCI DSS requirements create fragmented implementation roadmaps for national restaurant chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud-Based POS Market |
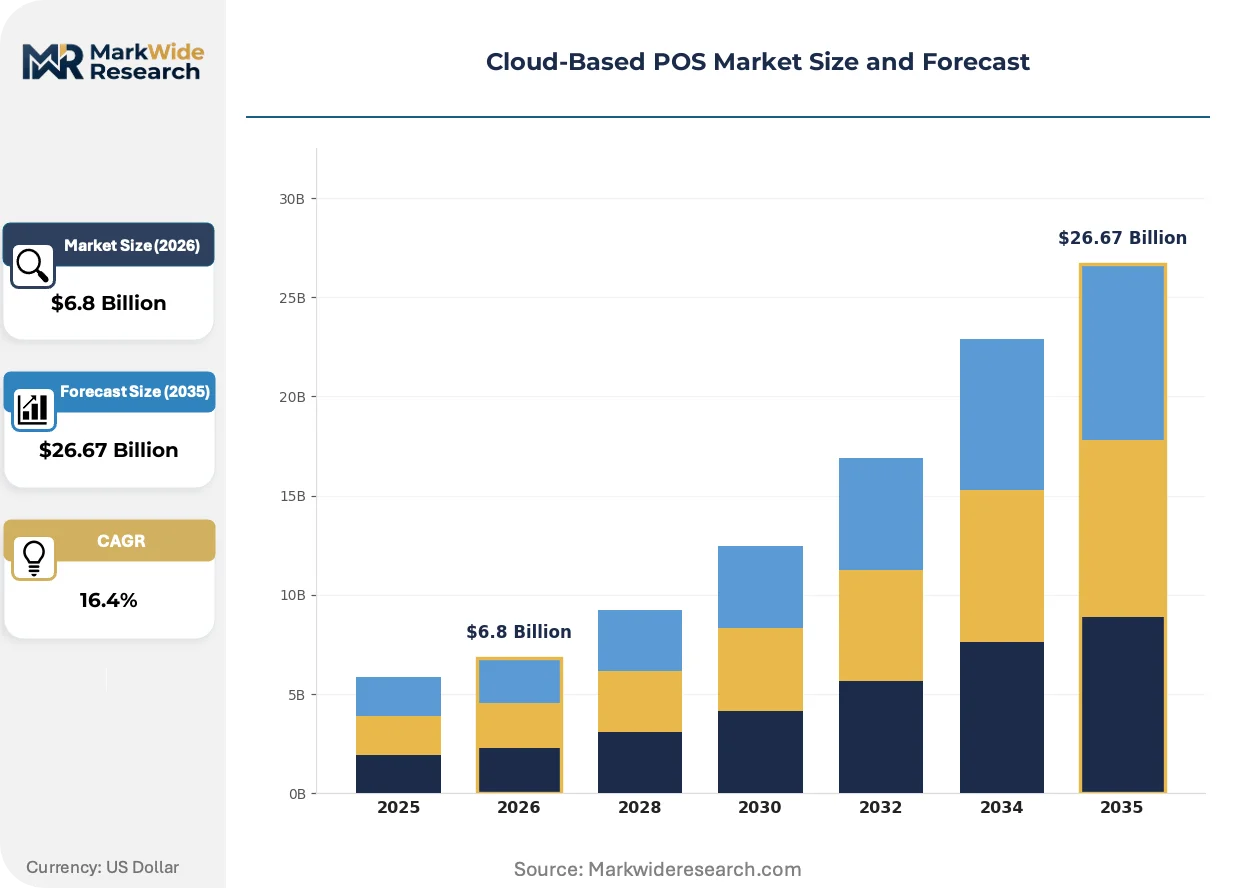
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile POS, Tablet POS, Terminal POS, Integrated POS Industry Vertical: Retail, Hospitality, Healthcare, Entertainment Payment Method: Credit Card, Debit Card, Mobile Wallet, Contactless Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Tenant |
| Companies Covered | Block, Inc., Toast, Inc., Shopify Inc., Lightspeed Commerce Inc., Oracle Corporation, NCR Corporation, Fiserv, Inc., Intuit Inc., Clover Network Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud-Based POS Market Strategic Shifts
Architectural specialization is reshaping competitive positioning across deployment models, with hardware-software bundling strategies and vertical integration into adjacent modules determining margin capture rates.
API-first design is fragmenting the traditional POS stack into composable microservices. Developers now assemble transaction processing, inventory tracking, and customer data management from discrete cloud components rather than monolithic platforms. Quick-service operators adopt this modular approach fastest, piecing together best-of-breed solutions that reduce vendor lock-in while increasing integration complexity.
The EU AI Act imposes algorithmic transparency requirements on automated fraud-detection features embedded in European POS deployments. Merchants must document decision logic for transaction risk scoring, adding compliance overhead that favors established vendors with dedicated regulatory teams. Automated chargeback prevention tools face the strictest scrutiny, with hospitality groups in France and Germany restructuring workflows to maintain audit trails.
Curbside and tableside service models compress server-to-kitchen communication cycles, displacing fixed-terminal workflows with roaming tablet deployments. Full-service restaurants in urban United States corridors lead this transition, equipping staff with mobile devices that transmit orders directly to kitchen display systems. Labor cost pressures accelerate adoption where reduced table-touch frequency enables higher guest-to-staff ratios without service degradation.
Cloud-Based POS Market Segmentation
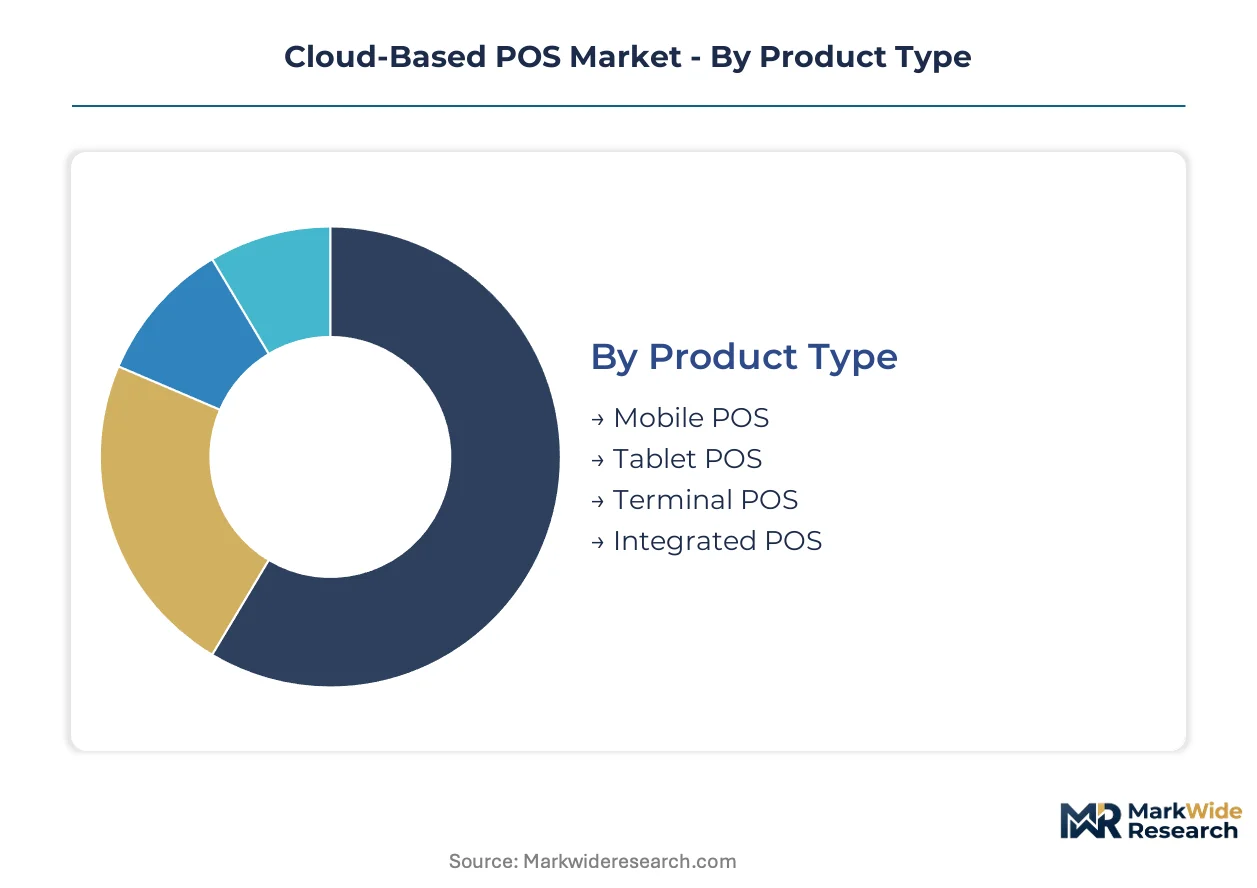
Cloud-based POS architectures fragment across hardware form factors, industry workflows, payment rails, and infrastructure tenancy models. Each dimension carries distinct substitution pressures from adjacent technologies and competing deployment philosophies. Vendors must calibrate R&D allocation across these axes to defend margin pools against modular disaggregation.
Product Type:
Tablet POS faces the most acute substitution threat from smartphone-based mPOS solutions, while Terminal POS confronts extended replacement cycles that compress upgrade revenue windows.
- Mobile POS:Smartphone and dedicated handheld devices process transactions through cellular or Wi-Fi connectivity, with lightweight apps displacing dedicated hardware in micro-merchant and pop-up environments. Demand concentrates among food trucks and market vendors across United States urban corridors, driven by Square and SumUp hardware subsidies that eliminate upfront capital barriers.
- Tablet POS:iPad and Android tablet configurations dominate tableside service workflows in full-service restaurants, where roaming order entry reduces server transit time. Adoption accelerates in United States coastal metropolitan areas facing labor cost compression, with Toast and Revel Systems anchoring merchant density.
- Terminal POS:Fixed countertop hardware with integrated card readers and receipt printers persists in big-box retail and grocery, where durability requirements outweigh software agility.
- Integrated POS:All-in-one systems unifying payment processing, inventory, payroll, and loyalty modules capture the deepest subscription revenue per merchant.
Terminal POS anchors the volume base among legacy retail installations while Mobile POS gains share at the steepest rate through zero-hardware-cost onboarding programs.
Industry Vertical:
Margin capture varies dramatically across verticals, with Hospitality yielding the highest software attach rates and Retail exhibiting the longest hardware depreciation schedules.
- Retail:Inventory synchronization and omnichannel order management drive platform selection, with grocery and apparel chains prioritizing SKU-level tracking across distributed locations. United States big-box operators favor integrated suites from NCR and Oracle, where five-to-seven-year replacement cycles slow cloud migration.
- Hospitality:Full-service restaurants and quick-service operators demand kitchen display system integration, tip distribution automation, and real-time labor scheduling. North American urban dining corridors concentrate vendor competition, with PCI DSS Level 1 compliance mandates compressing selection cycles toward pre-certified platforms.
- Healthcare:HIPAA-compliant payment processing for patient billing and pharmacy retail requires encrypted data architectures with audit trail documentation.
- Entertainment:Stadiums, cinemas, and event venues prioritize high-throughput transaction processing with offline queueing capabilities during network congestion.
Hospitality generates the highest revenue per merchant through payroll and loyalty module bundling, while Retail contributes the largest absolute terminal installed base despite slower cloud conversion.
Payment Method:
Contactless infrastructure investments are displacing magstripe and chip-and-signature workflows, reshaping hardware refresh priorities across merchant tiers.
- Credit Card:Traditional card-present and card-not-present transactions remain the dominant revenue rail, with interchange fee structures influencing processor selection. United States merchants face pressure from Visa and Mastercard mandate timelines accelerating EMV and contactless terminal deployment.
- Debit Card:PIN-based and signature debit networks process lower interchange transactions, with regional debit networks like Star and Pulse maintaining merchant loyalty through cost advantages.
- Mobile Wallet:Apple Pay, Google Pay, and Samsung Pay tokenization requires NFC-enabled terminals, driving hardware obsolescence among legacy installations.
- Contactless:Tap-to-pay cards and wearable devices reduce transaction friction, with European markets leading penetration due to earlier regulatory mandates.
Credit Card processing anchors transaction volume while Contactless climbs fastest as terminal refresh cycles incorporate NFC as default capability.
Deployment Model:
Data sovereignty requirements and latency sensitivity are fragmenting tenancy preferences across merchant scale and geographic exposure.
- Public Cloud:Shared infrastructure with AWS, Azure, or GCP backend delivers lowest per-merchant cost, attracting small and mid-sized operators without dedicated IT staff. United States hospitality groups under fifty locations favor this model for zero-capital scaling.
- Private Cloud:Dedicated single-tenant environments satisfy enterprise security requirements and custom compliance frameworks, with healthcare and financial services subsidiaries mandating isolated infrastructure.
- Hybrid Cloud:Sensitive payment data resides on-premise while analytics and reporting sync to cloud backends, balancing PCI DSS scope reduction with operational visibility.
- Multi-Tenant:Shared application instances with logical data separation enable vendor economies of scale, though GDPR data localization requirements constrain European configurations.
Public Cloud hosts the broadest merchant count while Hybrid Cloud expands most quickly among mid-sized chains seeking PCI DSS scope optimization without full infrastructure commitment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based vendors export cloud POS architectures to hospitality operators across Canada, the United Kingdom, and Australia, with PCI DSS certification serving as the primary cross-border qualification standard.
United States
Mid-sized restaurant chains in New York, California, and Texas drive platform consolidation as PCI DSS Level 1 audit mandates compress vendor selection cycles. The FTC enforces data security standards for consumer financial protection. Toast and Block anchor dense merchant networks across urban dining corridors in Chicago, Los Angeles, and Miami.
Canada
Cross-border hospitality groups demand seamless integration with US-based payment rails and payroll modules. Health Canada oversees medical device classifications for POS hardware used in pharmacy retail settings. Toronto and Vancouver concentrate multi-location restaurant deployments seeking real-time inventory synchronization across provincial boundaries.
United Kingdom
Hospitality operators navigate GDPR data localization requirements alongside emerging FCA guidance on open banking integrations. London's dense restaurant ecosystem favors tablet-based tableside service workflows. Manchester and Edinburgh follow with adoption concentrated in independent full-service dining segments.
Germany
The EU AI Act imposes algorithmic transparency requirements on automated fraud-detection features embedded in POS deployments. Berlin and Munich lead hospitality technology adoption among multi-location groups. The KBA does not regulate this sector; instead, BSI technical standards govern encryption implementations.
Australia
Contactless payment infrastructure investments accelerate terminal refresh cycles in Sydney and Melbourne hospitality markets. The Australian Competition and Consumer Commission monitors payment system access and interchange fee structures. Regional chains in Brisbane and Perth adopt cloud architectures to unify procurement across distributed kitchen operations.
Cloud-Based POS Market Competitive Environment
Listed leaders compete with private specialists across payment processing and software integration dimensions, producing a tiered structure where scale-driven platforms and vertical specialists coexist. The market consolidates around three strategic archetypes: full-stack hospitality platforms, financial services incumbents with POS extensions, and modular API-first specialists. Dominant competitive moves include M&A for vertical capability acquisition and strategic partnerships for payment rail access.
Within the full-stack hospitality tier, Toast and Block exemplify platform-centric positioning, while Lightspeed occupies a specialist role among multi-location operators. Oracle and NCR represent legacy technology conglomerates extending enterprise infrastructure downward into mid-market segments. These five entities anchor the competitive spectrum from born-in-cloud challengers to incumbent diversification plays.
| Leading Market Players |
|---|
| Block, Inc. |
| Toast, Inc. |
| Shopify Inc. |
| Lightspeed Commerce Inc. |
| Oracle Corporation |
| NCR Corporation |
| Fiserv, Inc. |
| Intuit Inc. |
| Clover Network Inc. |
| Others |
Value Chain & Pricing Dynamics
PCI DSS Level 1 certification gates supply qualification for mid-sized restaurant chains while simultaneously stratifying price tiers across encryption-grade tiers, with certified architectures commanding subscription premiums that uncertified competitors cannot match.
Pricing Analysis
Next-generation TLS 1.3-native hardware commands 40-60% subscription premiums over legacy terminal refresh cycles, while prior-generation tablet deployments face cost compression from smartphone-based mPOS substitution. SaaS-tiered pricing stratifies across premium, standard, and economy levels based on module bundling depth and API call volume allowances. Price differentiation hinges on PCI DSS certification tier and vertical integration depth into payroll and inventory modules. Pricing pressure stems from Square and SumUp zero-hardware-cost onboarding programs in micro-merchant segments. Quick-service operators exhibit highest price sensitivity due to thin margin structures, while full-service dining groups prioritize feature depth over unit economics.
Supply Chain Analysis
Inbound logistics costs through Los Angeles and Long Beach port complexes shape hardware landed costs for tablet and terminal assemblies sourced from Taiwan, China, and Vietnam. Cloud POS hardware draws from Taiwanese semiconductor fabs for payment processors, Chinese Shenzhen electronics corridors for tablet enclosures, and Mexican assembly plants for North American terminal fulfillment. Single-source vulnerability concentrates in NFC chip supply from Samsung and NXP Semiconductors. Distribution runs through direct-to-merchant vendor portals and value-added reseller networks serving multi-location hospitality groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based POS markets reward defensive moats built on regulatory entrenchment, where PCI DSS certification creates switching costs that lock mid-sized chains into pre-qualified vendor ecosystems.
For Market Incumbents: Fortify certification moats by accelerating TLS 1.3 migration roadmaps before audit mandate deadlines compress selection windows. Deepen backward integration into kitchen display system hardware to capture margin pools threatened by API-first modular specialists. Prioritize payroll module bundling in full-service dining segments where labor scheduling complexity drives retention.
For New Entrants and Emerging Players: Lead with biometric loyalty authentication in Texas and Illinois markets where state privacy laws have slowed incumbent deployment timelines. Target independent full-service restaurants in secondary United States metropolitan areas underserved by Toast and Block merchant density. Pursue white-label partnerships with regional payment processors lacking in-house software capabilities.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across API-first modular platforms as microservices architectures reduce infrastructure overhead relative to monolithic legacy stacks. Five-to-ten-year viability favors vendors with dedicated regulatory compliance teams capable of navigating EU AI Act algorithmic transparency requirements. Monitor PCI DSS audit failure rates among mid-tier vendors as consolidation trigger signal.
| Strategic Initiative | Industry Significance |
|---|---|
| PCI DSS Level 1 Pre-Certification Investment | Eliminates vendor selection friction for mid-sized chains facing compressed audit timelines. |
| Payroll Module Vertical Integration | Captures recurring revenue from tip distribution automation in full-service dining segments. |
| API-First Platform Architecture | Enables third-party developer ecosystems that reduce customer acquisition costs. |
| Biometric Loyalty Partnership | Navigates Illinois BIPA and Texas CUBI consent frameworks for facial-recognition checkout. |
| Multi-Tenant European Data Localization | Addresses GDPR server-location constraints for hospitality groups operating across France and Germany. |
Study Parameters
Cross-validation between primary interviews with POS platform executives and secondary validation through SEC filings anchors the qualitative findings. Stakeholder engagement spanned CTOs at multi-location hospitality groups, IT procurement officers at quick-service chains, integration specialists at payment processors, and regulatory compliance leads at PCI DSS audit firms. Secondary sources included Visa and Mastercard mandate documentation, FTC data security enforcement actions, EU AI Act implementation guidance, and hyperscaler infrastructure capex disclosures. Bottom-up merchant count estimates triangulated against top-down payment processing volume allocations.
Sensitivity analysis tested forecast robustness across alternative adoption curves for mobile POS penetration and terminal refresh cycle compression. Segmentation dimensions modeled deployment model, organization size, industry vertical, integration complexity, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical cloud migration patterns in adjacent enterprise software categories. Forecast inputs incorporated PCI DSS audit timeline acceleration scenarios and contactless terminal mandate compliance deadlines.
Forecasts assume regulatory continuity in PCI DSS, GDPR, and EU AI Act enforcement regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Infrastructure As Code (Iac) Market
Digital Solutions
Docketing Solution Market
Digital Solutions
Turkey ICT Market
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
HIPAA-Compliant Messaging Services Market
Digital Solutions
Global Client Virtualization Market
Digital Solutions
Landing Page Builders Market
Digital Solutions
Deviation Management and CAPA Platforms for Cold Chain Logistics Market
Digital Solutions
Legaltech Market
Digital Solutions
Cloud Monetization Market
Digital Solutions
Cloud Project Portfolio Management (CPPM) Market
Digital Solutions
Content Moderation Services Market
Digital Solutions
Global Tag Management System Market
Digital Solutions
Mock Interview Platforms Market
Digital Solutions
Assortment and Space Optimization (ASO) Market