
 Interactive Digital Signage Software Market | 2026-2036
Interactive Digital Signage Software Market Size, Share, and Industry Trends Forecast 2026-2036
Interactive Digital Signage Software Market Foresight
Enterprise-grade 4K touch responsiveness is collapsing the performance gap between consumer tablets and commercial displays. BroadSign International leverages its programmatic advertising backbone to dominate transit and retail media networks across North America. Navori Labs differentiates through real-time data integration layers that sustain premium pricing in corporate campus deployments. Intuface specializes in no-code content authoring tools that occupy a growing niche among mid-market hospitality buyers.
Interactive digital signage software encompasses platforms that manage, schedule, and render touch-responsive or sensor-driven visual content across distributed display networks, typically requiring sub-100ms latency for gesture recognition and supporting 4K resolution at 60 frames per second for seamless user engagement. Cloud-based deployments lead volume growth as subscription models reduce capital barriers for multi-site retailers, while hybrid architectures capture margin pools from enterprises requiring local failover with remote management. LED technology segments expand fastest in outdoor and high-ambient-light environments, whereas LCD retains cost advantages in indoor corporate and education settings where backlight uniformity standards remain paramount.
The FCC governs wireless connectivity protocols for networked signage installations, while the EU AI Act shapes biometric and camera-based audience analytics permissible in European deployments. OSHA workplace safety standards in the United States influence screen placement and electrical installation requirements for interactive kiosks in manufacturing and logistics facilities. Stakeholders must weigh cloud dependency against data sovereignty mandates as municipalities tighten procurement rules for publicly accessible digital infrastructure.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for multi-site retailers while fragmenting vendor competitive positions between subscription platforms and legacy perpetual-license incumbents.
Growth Catalysts
- OSHA workplace safety mandates:Manufacturing and logistics facilities in the United States must replace static safety signage with interactive kiosks that deliver real-time hazard alerts and training modules, accelerating hardware refresh cycles.
- Edge computing maturation:Sub-50ms latency thresholds for gesture recognition now deployable without dedicated server rooms enable quick-service restaurants to roll out touch-ordering interfaces at franchise scale.
- Transit hub modernization:Municipalities across Germany, France, and the United Kingdom are procuring networked digital infrastructure to replace paper timetables with real-time passenger information systems.
Market Restraints
- Bandwidth cost volatility:Cloud-dependent architectures face margin pressure from carrier pricing fluctuations in markets lacking fiber infrastructure redundancy.
- EU AI Act biometric restrictions:Camera-based audience analytics for demographic profiling face compliance friction that limits deployment in European retail and public space networks.
- LCD panel supply concentration:Commercial display manufacturing concentrates among Korean and Taiwanese suppliers, exposing procurement teams to single-source risk during component allocation cycles.
Strategic Opportunities
- India smart city infrastructure:Municipal digital kiosk deployments under the country's urban renewal programs present underpenetrated demand for outdoor-rated interactive wayfinding systems.
- Healthcare wayfinding convergence:Integration of appointment scheduling, navigation, and payment into single interactive surfaces opens new deployment categories in hospital campus expansions.
- CSRD sustainability reporting:European corporate sustainability mandates are driving procurement preference for energy-efficient LED-based signage with embedded power consumption telemetry.
Industry Challenges
- UX design talent scarcity:Enterprises struggle to staff teams capable of authoring gesture-responsive interfaces that maintain sub-100ms latency budgets across 4K render pipelines.
- Legacy CMS integration complexity:Mid-market hospitality buyers face extended deployment timelines when bridging no-code content tools with existing property management system databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interactive Digital Signage Software Market |
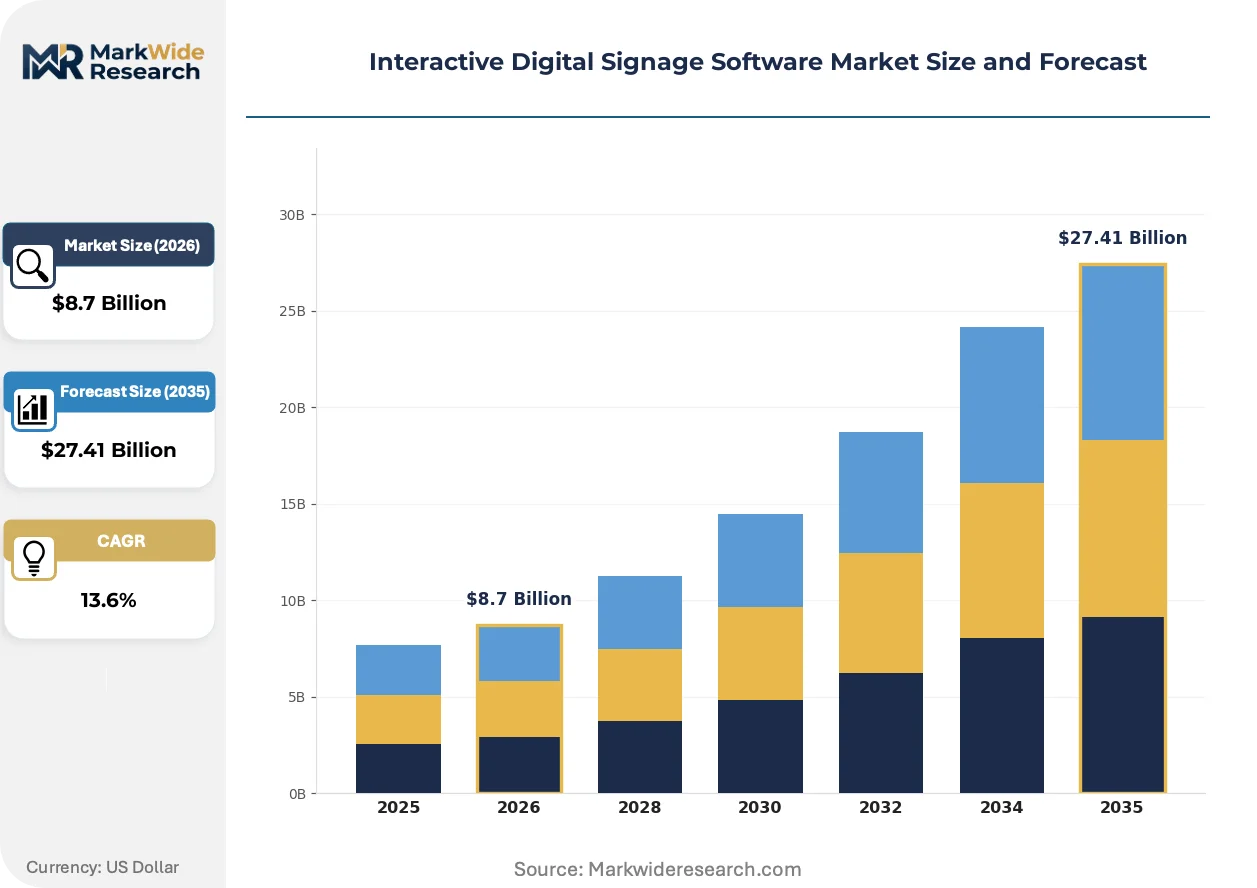
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Kiosk End User: Retail, Hospitality, Corporate, Education Technology: LCD, LED, Projection, OLED Deployment: Single-Site, Multi-Site, International, Local |
| Companies Covered | BroadSign International, Intuface, NoviSign, Navori Labs, SignStix, PandaSuite, Four Winds Interactive, Signagelive, Xibo Signage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interactive Digital Signage Software Market Shifts & Advancements
Software-defined content delivery is fragmenting the traditional value chain between display hardware, media players, and cloud management platforms, enabling new competitive entry points.
Containerized microservices architecture is decomposing monolithic digital signage platforms into modular components that quick-service restaurants and retail chains can deploy selectively. Franchise operators adopt container-based media players at pace, replacing all-in-one appliances with software-only licenses running on generic compute hardware. This decomposition collapses hardware margin pools while expanding addressable market for pure-play software vendors.
The EU AI Act's biometric identification restrictions are reshaping permissible audience measurement techniques in European deployments. Retail media networks must now deploy thermal or radar-based alternatives to camera analytics for footfall counting and dwell-time measurement. Transit operators in France and Germany are accelerating procurement of privacy-preserving sensor arrays that comply with the regulation's proportionality requirements.
Subscription-based procurement is compressing traditional three-year capital replacement cycles into continuous refresh models. Mid-market hospitality buyers now favor monthly software fees bundled with hardware-as-a-service over perpetual license purchases. This shift is most visible in United States hotel chains where property-level IT budgets favor operational expenditure classification over capital allocation requests.
Interactive Digital Signage Software Market Segmentation
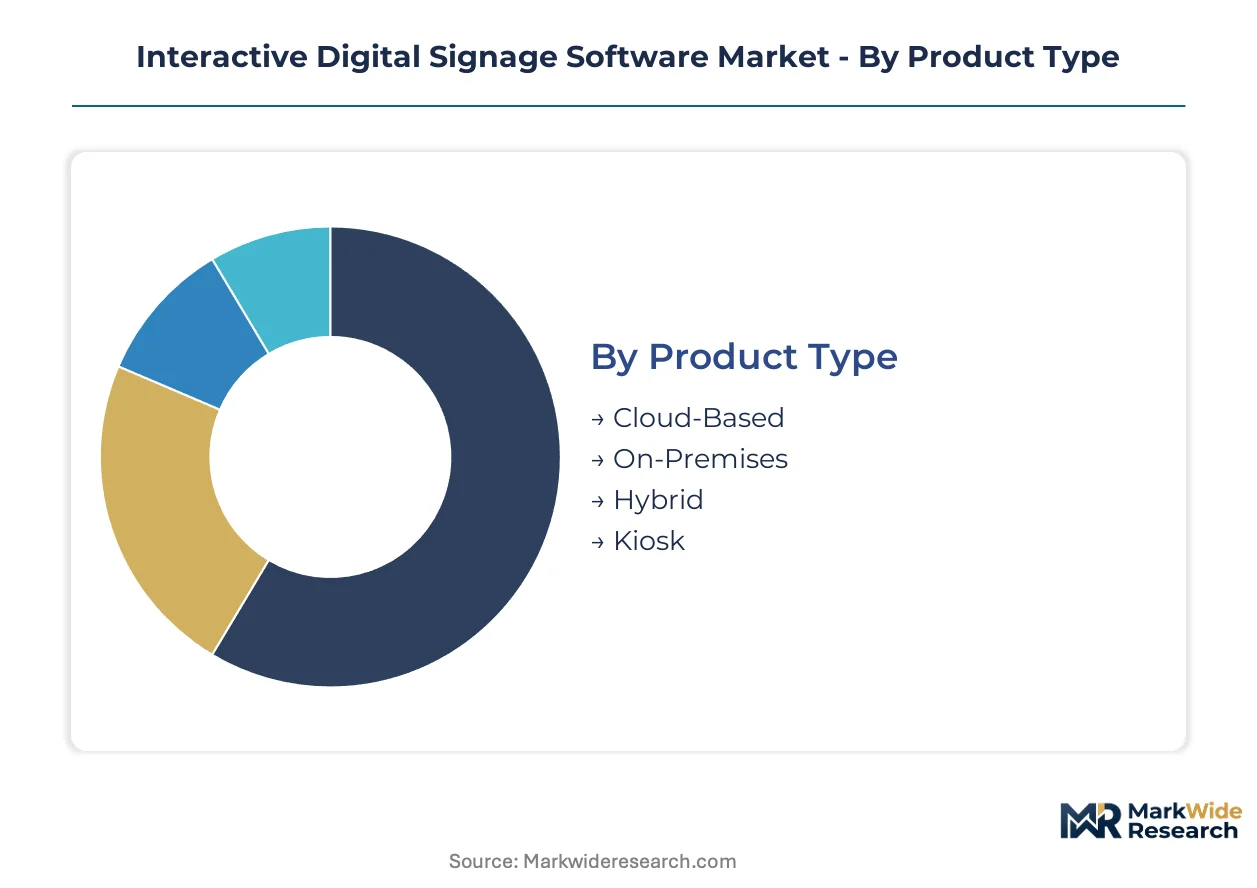
Deployment architecture and display technology choices in interactive digital signage software determine latency budgets, compliance exposure, and total cost of ownership across retail, transit, and corporate use cases. Procurement teams weigh cloud dependency against data sovereignty mandates while selecting hardware form factors matched to ambient light conditions and touch interaction intensity.
Product Type:
FCC wireless protocol compliance applies to all networked installations, though cloud-based and hybrid architectures face heightened scrutiny under EU GDPR data localization requirements and emerging municipal procurement rules for public infrastructure.
- Cloud-Based:Subscription delivery models reduce capital barriers for multi-site retailers through browser-based content management and over-the-air firmware updates. Quick-service restaurants in the United States favor this architecture for franchise-scale rollouts where property-level IT budgets prefer operational expenditure classification.
- On-Premises:Dedicated server installations maintain full data custody within facility boundaries, satisfying healthcare and financial sector compliance requirements. German corporate campuses and French transit authorities specify on-premises deployments to satisfy CNIL and BfDI guidance on biometric data processing.
- Hybrid:Local failover with remote management captures margin pools from enterprises requiring sub-50ms gesture recognition latency during cloud outages.
- Kiosk:Self-contained interactive terminals integrate payment, printing, and sensor arrays for wayfinding and transactional applications.
Established volume favors on-premises legacy installations; emerging adoption favors cloud-based subscription platforms.
End User:
OSHA workplace safety mandates in manufacturing facilities and CSRD sustainability reporting requirements in European corporate headquarters reshape procurement specifications across verticals.
- Retail:Flagship store networks deploy 4K touch-responsive displays to bridge online and offline customer journeys, with LED technology segments expanding fastest in high-ambient-light environments.
- Hospitality:Mid-market hotel chains adopt containerized microservices for property-level content authoring, though UX design talent scarcity extends deployment timelines when integrating with property management system databases.
- Corporate:Campus deployments sustain premium pricing through real-time data integration layers for meeting room scheduling and visitor management.
- Education:LCD retains cost advantages in classroom and library settings where backlight uniformity standards remain paramount and touch interaction intensity is moderate.
Corporate and education sectors anchor replacement demand; hospitality represents the steepest expansion trajectory as operational expenditure models displace capital allocation cycles.
Technology:
Supply concentration among Korean and Taiwanese panel manufacturers exposes procurement teams to single-source risk, while EU AI Act biometric restrictions accelerate thermal and radar-based sensor alternatives to camera analytics.
- LCD:Thin-film transistor liquid crystal displays with LED backlighting dominate indoor corporate and education deployments where cost per square inch and color calibration consistency outweigh brightness requirements.
- LED:Direct-view light-emitting diode arrays deliver 5,000+ nit brightness for outdoor transit hubs and retail facades, with municipal digital kiosk deployments under India's smart city programs driving volume in underpenetrated markets.
- Projection:Short-throw and ultra-short-throw projectors enable large-format interactive surfaces in temporary event installations and museum exhibitions.
- OLED:Organic light-emitting diode panels offer infinite contrast ratios and flexible form factors for premium retail and automotive showroom applications.
LCD commands installed base dominance; LED gains share fastest as outdoor-rated specifications climb procurement priority lists.
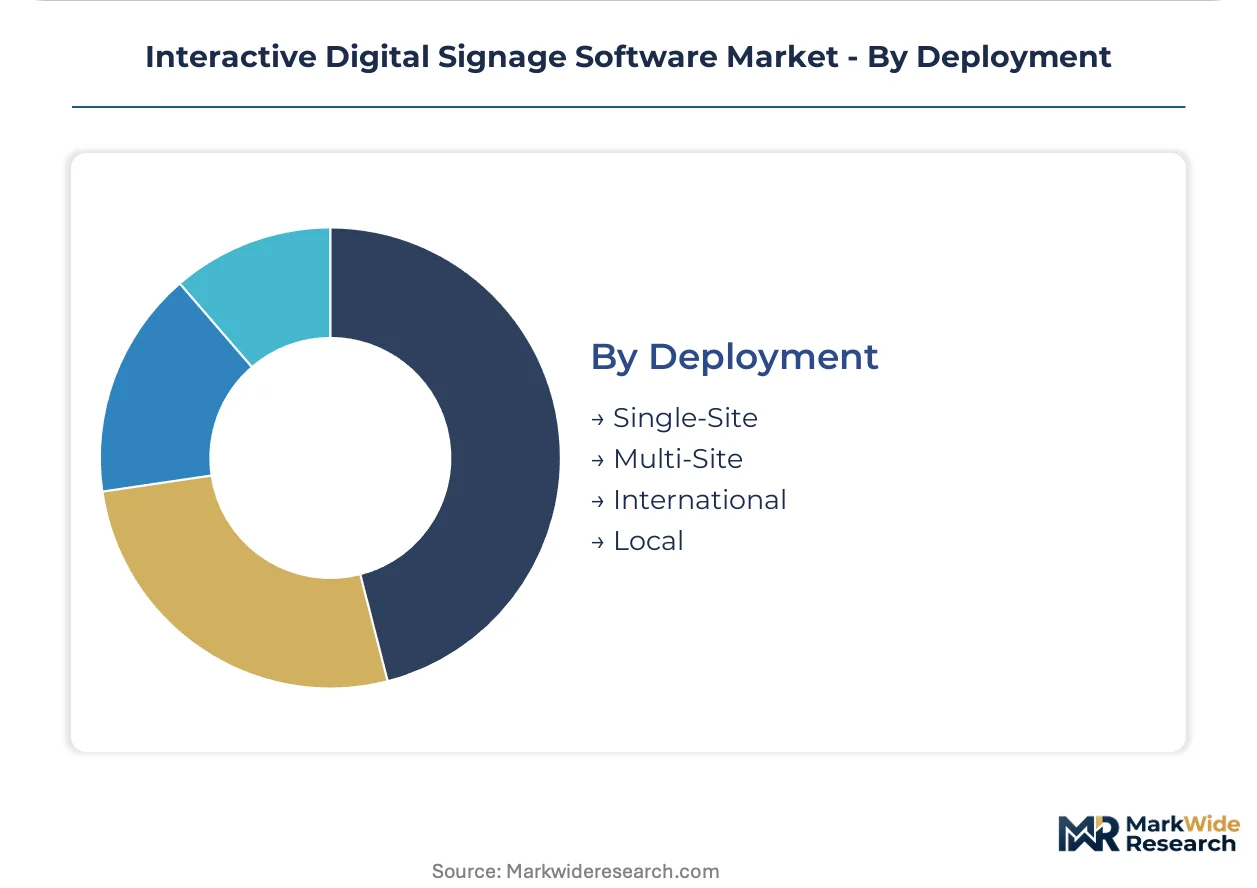
Deployment:
Bandwidth cost volatility in fiber-limited markets fragments competitive positioning between centralized management platforms and distributed edge computing architectures.
- Single-Site:Localized content management serves standalone installations in small-format retail and independent hospitality properties with limited IT staffing.
- Multi-Site:Centralized scheduling and device orchestration across regional or national footprints enables brand consistency for quick-service restaurant chains and retail media networks.
- International:Cross-border deployments require navigation of data sovereignty mandates, with municipalities tightening procurement rules for publicly accessible digital infrastructure.
- Local:Municipality-specific installations prioritize domestic vendor qualification and local language content requirements over global platform standardization.
Multi-site deployments anchor current revenue concentration; international expansion faces regulatory friction that favors localized partnership models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software exports from the United States and Germany exceed import volumes for interactive signage platforms, while India and China remain net importers of enterprise-grade content management systems. Cross-border data flows concentrate licensing revenue in North American and European headquarters.
United States
Quick-service restaurant chains and transit authorities drive replacement cycles for static displays across the country. OSHA workplace safety mandates compel manufacturing facilities to deploy interactive kiosks for real-time hazard alerts. Dallas-Fort Worth anchors a cluster of retail media network operations bridging online and offline customer journeys.
Germany
Municipal transit operators procure networked digital infrastructure to replace paper timetables with real-time passenger information systems. BfDI guidance on biometric data processing shapes deployment specifications for camera-based audience analytics. Berlin-Brandenburg hosts corporate campuses specifying on-premises installations to satisfy data custody requirements.
United Kingdom
Transit hub modernization programs accelerate procurement of privacy-preserving sensor arrays for footfall counting. The country's national data protection authority influences procurement rules for publicly accessible digital infrastructure. London anchors retail flagship store networks deploying 4K touch-responsive displays.
India
Municipal digital kiosk deployments under urban renewal programs present demand for outdoor-rated interactive wayfinding systems. The country's national standards body certifies equipment for smart city infrastructure. Maharashtra concentrates system integrators serving campus and hospitality verticals.
France
CNIL oversight of biometric identification restricts camera analytics deployment in retail media networks. Transit operators accelerate procurement of thermal and radar-based alternatives for demographic profiling. Paris anchors luxury retail deployments specifying LED technology for high-ambient-light environments.
Interactive Digital Signage Software Market Competitive Landscape
Concentration sits with programmatic advertising backbone providers and real-time data integration specialists. The vendor base spans three tiers: cloud-native subscription platforms, hybrid architecture incumbents, and no-code content authoring tool specialists. Strategic moves center on containerized microservices decomposition and edge computing partnerships that collapse hardware margin pools.
Within the programmatic advertising tier, BroadSign International and Signagelive exemplify scale-driven positioning for transit and retail media networks. Navori Labs and Intuface occupy distinct specialization vectors—enterprise data integration and no-code authoring respectively—each sustaining premium pricing through differentiated capability layers. NoviSign represents the mid-market cloud-native archetype.
| Leading Market Players |
|---|
| BroadSign International |
| Intuface |
| NoviSign |
| Navori Labs |
| SignStix |
| PandaSuite |
| Four Winds Interactive |
| Signagelive |
| Xibo Signage |
| Others |
Supply & Pricing Matrix
Cloud-native subscription models displacing perpetual-license installations simultaneously redistribute supply geography toward SaaS infrastructure hubs and compress pricing economics across deployment tiers. This substitution collapses upfront capital barriers while fragmenting vendor margin pools between hardware-agnostic software licenses and bundled hardware-as-a-service offerings.
Pricing Analysis
Quick-service restaurant chains anchor subscription-tiered pricing across the market. Three-tier pricing structure across premium, standard, and economy levels separates enterprise data integration capabilities from no-code authoring tools and basic content management. Price differentiation rests on certification grade for FCC wireless compliance and volume scale across franchise footprints. Pricing pressure stems from bandwidth cost volatility in fiber-limited markets. Mid-market hospitality buyers exhibit highest price sensitivity, while corporate campuses with CSRD mandates show lowest.
Supply Chain Analysis
Taiwan Strait shipping lanes underpin commercial display panel procurement for North American and European deployments. Korean and Taiwanese manufacturers concentrate LCD and LED panel supply, with Chinese assembly plants feeding downstream integration. Raw material dependencies span indium tin oxide for touch layers, gallium nitride for LED drivers, and high-purity glass substrates. Single-source vulnerability concentrates during component allocation cycles. Distribution runs through systems integrators serving vertical-specific deployment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
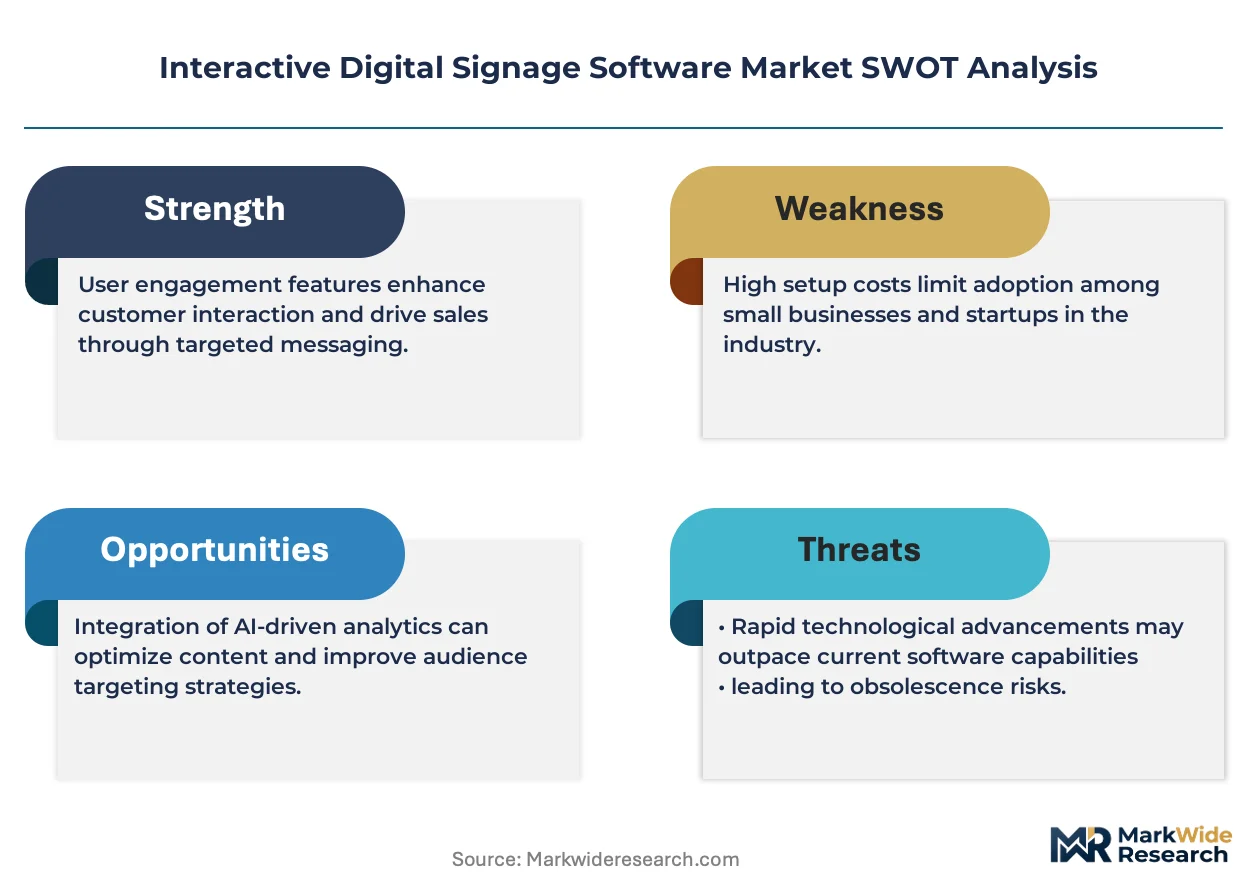
Containerized microservices architectures threaten incumbent hardware-software bundles, forcing established vendors to defend integrated positions against modular substitution.
For Market Incumbents: Shield enterprise relationships by deepening real-time data integration capabilities that sustain premium pricing against no-code competitors. Acquire edge computing partnerships to collapse gesture recognition latency below 50ms thresholds. Vertical integration into LED panel sourcing mitigates Korean-Taiwanese supply concentration risk. For New Entrants and Emerging Players: Healthcare wayfinding convergence represents the most penetrable white-space target, with hospital campus expansions requiring unified appointment-navigation-payment surfaces. India's smart city municipal kiosk deployments offer geographic entry with limited incumbent saturation. Partner with systems integrators possessing domestic vendor qualification credentials. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed programmatic advertising backbone providers serving transit and retail media networks. Five-to-ten year viability hinges on cloud-native transition completion and biometric analytics compliance adaptation. Watch EU AI Act enforcement patterns as inflection indicator for privacy-preserving sensor array demand.| Strategic Initiative | Industry Significance |
|---|---|
| Containerized Microservices Migration | Decomposes monolithic platforms into modular components that franchise operators deploy on generic hardware. |
| Edge Computing Partnership | Enables sub-50ms gesture recognition latency for quick-service restaurant touch-ordering interfaces. |
| Privacy-Preserving Sensor Development | Addresses EU AI Act biometric restrictions through thermal and radar-based footfall measurement alternatives. |
| Hardware-as-a-Service Bundling | Captures mid-market hospitality buyers shifting from capital allocation to operational expenditure models. |
| Smart City Systems Integration | Positions vendors for India's urban renewal program municipal kiosk deployments with domestic certification. |
Research Methodology
Operator-level perspectives from quick-service restaurant IT directors, retail media network operations managers, hospital facilities planners, and municipal procurement officers anchored the qualitative base. Primary interviews combined with secondary validation from FCC equipment authorization databases, EU AI Act implementation guidance, OSHA workplace safety directives, and cloud infrastructure capex disclosures. Bottom-up deployment counts triangulated against top-down software revenue estimates across the analysis window.
Sensitivity analysis tested forecast outputs against bandwidth cost volatility scenarios and regulatory enforcement intensity variations. Segmentation dimensions modeled include deployment architecture, display technology, end-use vertical, and geographic adoption pattern. CAGRs derived from installation base growth rates and average revenue per unit trajectories. Edge computing latency thresholds and LED brightness specifications served as technology-specific forecast inputs throughout the projection horizon.
Forecasts assume regulatory continuity in FCC wireless protocols and EU AI Act biometric restrictions; material policy shifts would require re-modeling. Specific risk factors include LCD panel supply allocation disruptions, GDPR data localization mandate expansion, and municipal procurement rule tightening for public infrastructure. Practitioners should keep alternative scenarios live as cloud dependency and data sovereignty tensions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Claims Processing Software Market
Software & Services
Low Code Development Platform Market
Software & Services
Parks and Playground Inspection Software Market
Software & Services
Global Automation Software Market
Software & Services
Stock Control Software Market
Software & Services
Global Data Entry Software Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Cursor Reviewer Market
Software & Services
Landscaping Engineering Software Market
Software & Services
Recruitment Software Market
Software & Services
Electronic Batch Records Market
Software & Services
Productivity Software Publishing Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
Interior Design Software Market
Software & Services
Global Decision Making Software Market