
 Global Photogrammetry Software Market | 2026-2036
Global Photogrammetry Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Photogrammetry Software Market Foresight
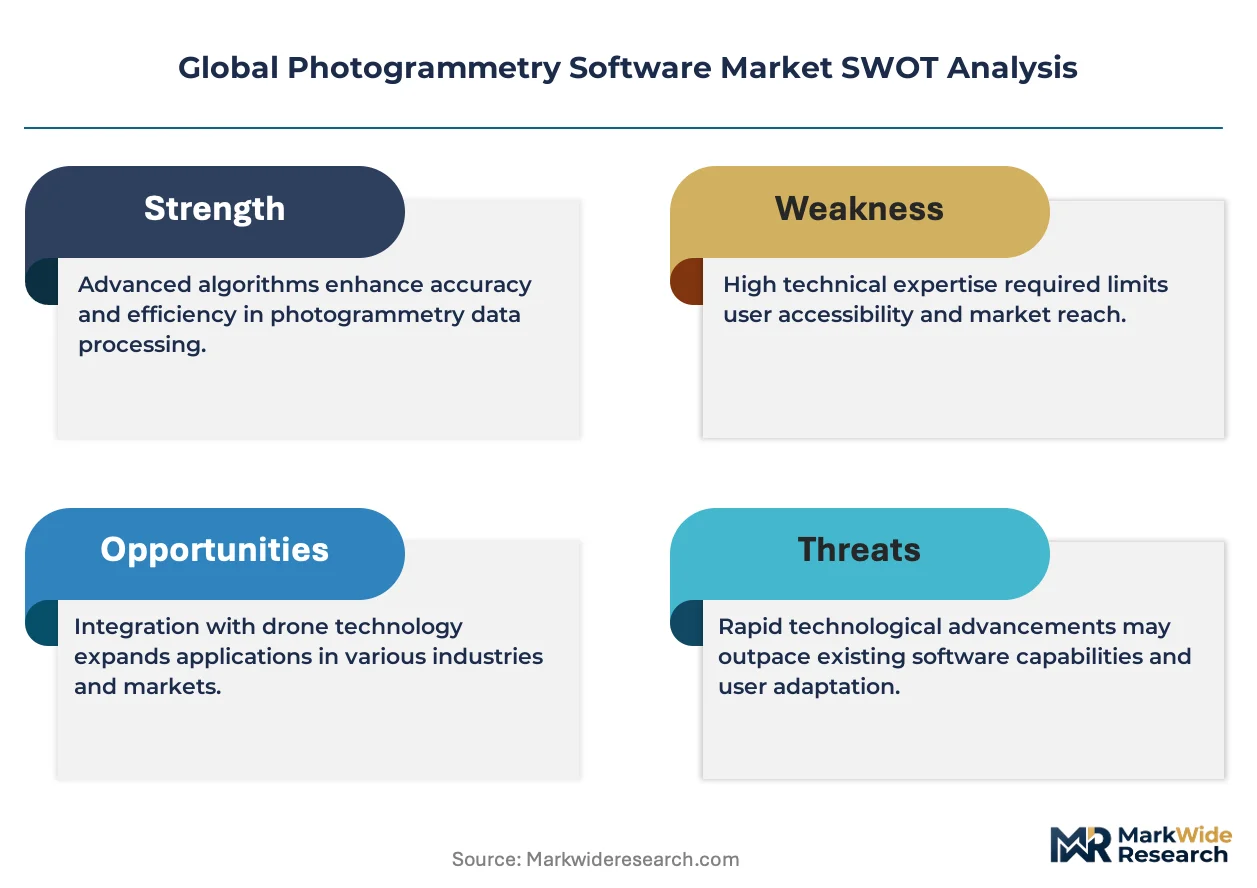
European software engineering clusters is repositioning photogrammetry development toward GPU-native architectures and real-time mesh generation. Pix4D SA leverages its Lausanne-based research hub to sustain leadership in drone-to-cloud reconstruction pipelines. Autodesk Inc. anchors its competitive stance through deep integration with civil engineering design suites. Bentley Systems Inc. differentiates by embedding photogrammetry directly into digital twin infrastructure for heavy construction clients.
Photogrammetry software comprises computational platforms that extract three-dimensional measurements from overlapping two-dimensional photographs using bundle adjustment algorithms and dense image matching, serving primarily to generate georeferenced point clouds and orthomosaics for spatial analysis. Cloud-based deployment now leads in new customer acquisition because subscription economics lower barriers for mid-sized surveying contractors, while on-premise installations retain preference among defense and critical infrastructure operators with strict data sovereignty requirements. Feature extraction capabilities within the solution layer command premium pricing as AI-augmented classification reduces manual vectorization labor in forestry and archaeological documentation workflows.
FAA Part 107 rules in the United States govern commercial drone operations that feed image capture into photogrammetry pipelines, while EASA open-category frameworks across Europe standardize unmanned aerial system deployment altitudes and beyond-visual-line-of-sight permissions for survey missions. ISO 19115 metadata standards and the EU Green Deal's biodiversity monitoring mandates shape product roadmaps by requiring interoperable geospatial reporting formats and carbon-stock measurement traceability. Stakeholders must monitor how emerging national drone traffic management systems and data localization statutes will fragment cloud-hosting strategies across jurisdictions.
Market Dynamics
GPU-native reconstruction pipelines are compressing processing timelines from hours to minutes, forcing incumbents to rewrite core algorithms or cede mid-market surveying contracts to cloud-native challengers.
Growth Catalysts
- FAA Part 107 commercial drone rules:Standardized pilot certification and operational altitudes across the United States have unlocked predictable aerial data capture workflows for infrastructure inspection teams.
- EU Green Deal biodiversity mandates:Carbon-stock measurement traceability requirements are compelling forestry agencies to adopt photogrammetry for canopy volume quantification and ecosystem monitoring.
- Dense image matching algorithms:Advances in multi-view stereo processing now enable sub-centimeter ground sampling distance from consumer-grade camera payloads.
Market Restraints
- GPU compute cost volatility:Cloud rendering fees for large-format photogrammetry projects fluctuate with NVIDIA data center pricing, squeezing margins for project-based surveying firms.
- Data localization statutes:National requirements in Germany, France, and Switzerland fragment cloud-hosting strategies and force redundant infrastructure investment.
- Lidar substitution in precision applications:Time-of-flight sensors penetrate topographic mapping where vegetation penetration demands exceed multi-view stereo capabilities.
Strategic Opportunities
- India infrastructure digitization:The country's National Master Plan for multi-modal connectivity creates demand for corridor mapping at scales beyond current vendor capacity.
- Digital twin convergence:Photogrammetry pipelines are integrating with Building Information Modeling workflows to automate as-built verification for heavy construction.
- Subscription channel expansion:Per-project pricing models face displacement by metered cloud platforms that lower entry barriers for mid-sized environmental consultancies.
Industry Challenges
- Bundle adjustment expertise scarcity:Universities produce computer vision PhDs oriented toward neural networks rather than classical photogrammetric geometry, narrowing hiring pools.
- EASA open-category compliance timelines:Beyond-visual-line-of-sight permissions require operational authorizations that delay survey mission deployment by 60-90 days.
- Legacy CAD integration friction:Point cloud formats from photogrammetry suites require manual translation for Autodesk Civil 3D and Bentley MicroStation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Photogrammetry Software Market |
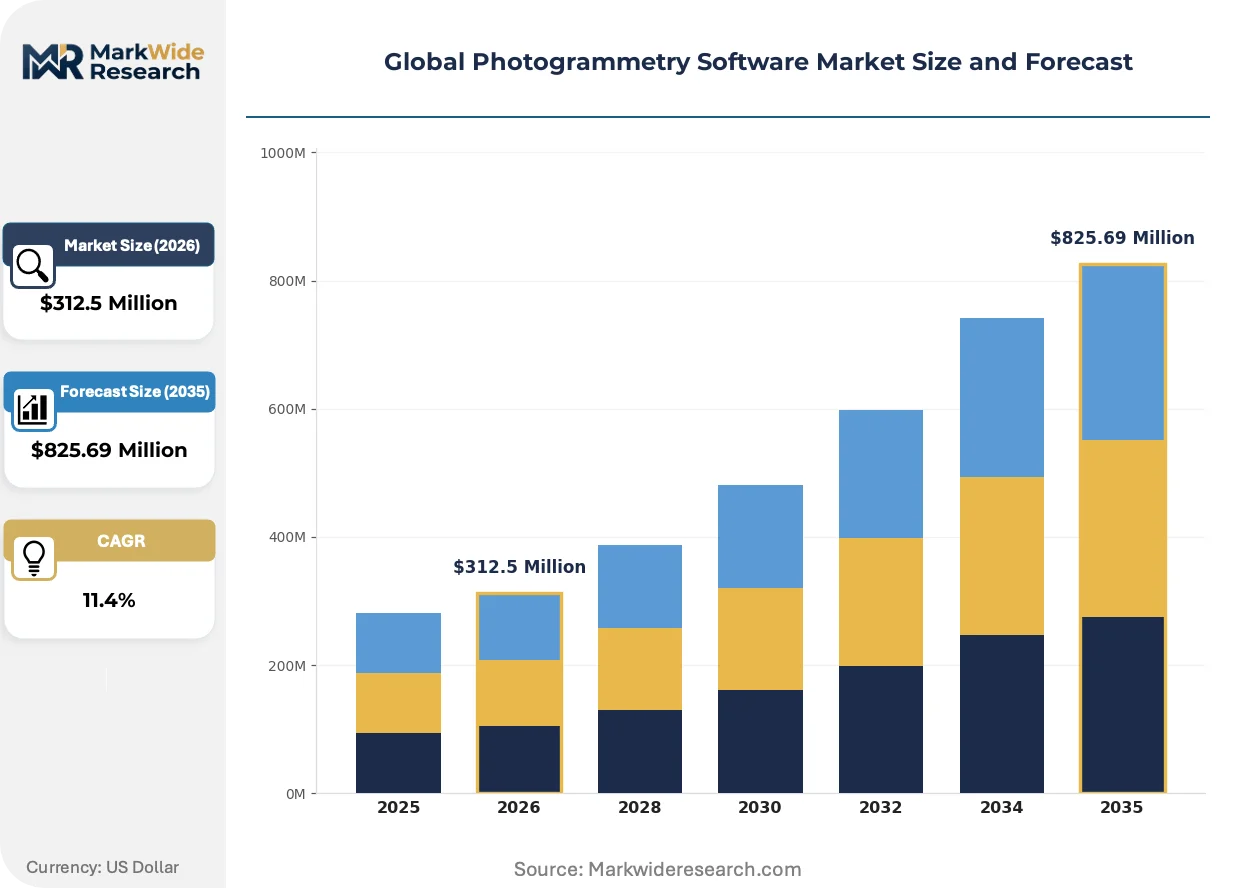
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $825.69 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution/Offering: 3D Mapping, Terrain Modeling, Volume Calculation, Orthophoto Generation, Feature Extraction Application: Surveying, Construction Monitoring, Forestry Management, Mining Operations, Archaeological Documentation End User: Engineering Firms, GIS Specialists, Environmental Agencies, Research Institutions |
| Companies Covered | Pix4D SA, Agisoft LLC, Autodesk Inc., Bentley Systems Inc., DroneDeploy Inc., Hexagon AB, Trimble Inc., Esri Global Inc., 3Dflow SRL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Photogrammetry Software Market Shifts & Advancements
Neural radiance fields and Gaussian splatting techniques are rewriting the cost-performance frontier for real-time 3D reconstruction, compressing the gap between capture and actionable mesh.
Gaussian splatting is expanding into heritage documentation and accident reconstruction where real-time visualization accelerates stakeholder decision cycles. Museum conservation teams in Italy and Japan now deploy portable multi-camera rigs that generate explorable scenes within minutes rather than overnight batch processing. This compression of reconstruction latency is forcing established vendors to rearchitect cloud pipelines around instantaneous preview generation.
The EU AI Act's risk classification framework for biometric and geospatial AI systems is imposing documentation burdens on photogrammetry platforms that automate feature extraction. Providers must now maintain model cards and training data provenance for algorithms that classify vegetation, structures, or terrain types. German engineering consultancies report 15-20% overhead increases in compliance documentation for cross-border projects.
Environmental agencies now specify outcome-based deliverables rather than raw data products in procurement tenders. Australian state forestry departments and Canadian provincial conservation authorities contract for "carbon stock change detection" rather than orthomosaic square kilometers. This specification shift rewards vendors with embedded analytics capabilities and displaces pure-play processing services.
Global Photogrammetry Software Market Segmentation
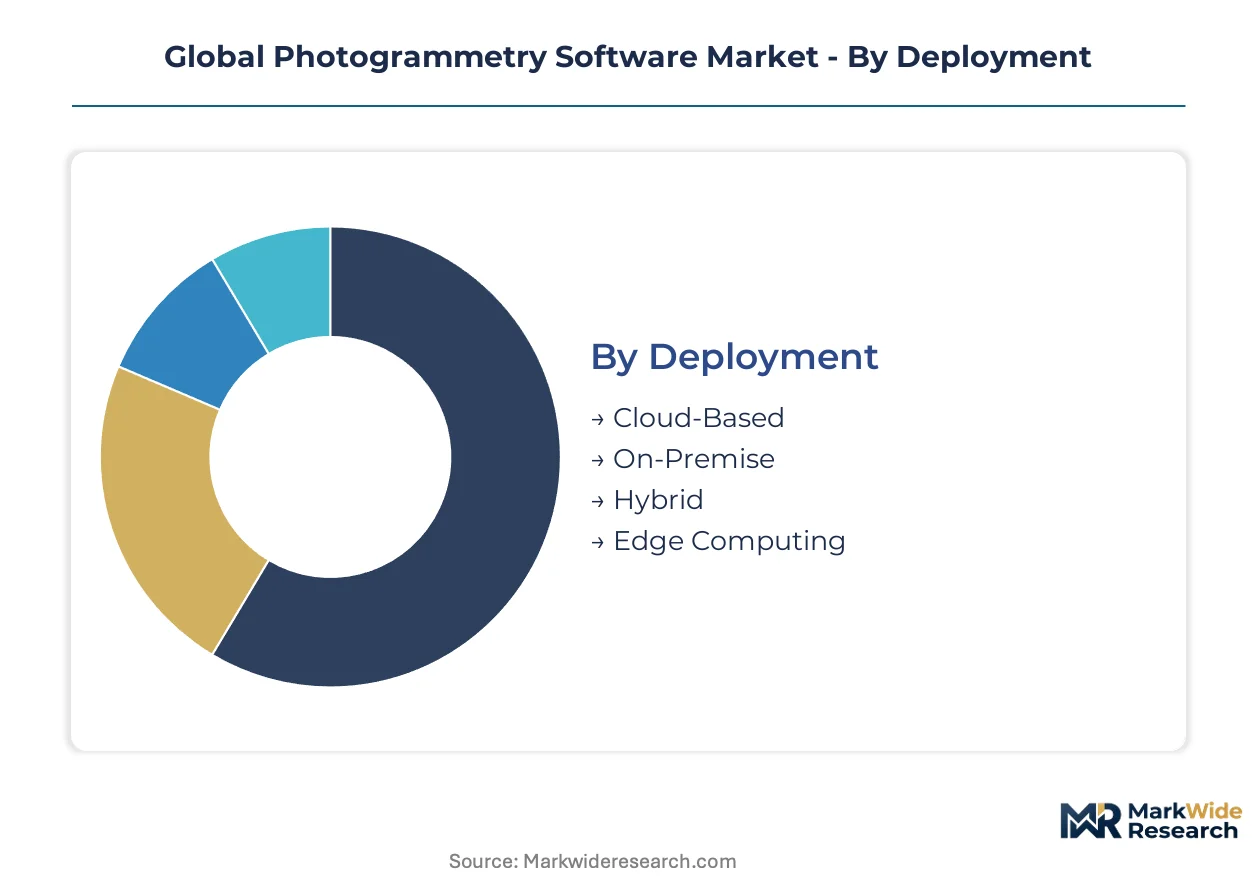
Photogrammetry software segments fracture along data sovereignty requirements and computational intensity. Deployment models determine infrastructure spend, while solution layers differentiate by automation depth and manual processing overhead.
Deployment:
Capital intensity peaks with on-premise installations requiring dedicated GPU clusters and redundant storage arrays.
- Cloud-Based:Subscription economics eliminate server procurement cycles for mid-sized surveying contractors. German environmental agencies and Australian state forestry departments now mandate cloud processing for cross-jurisdictional collaboration, though GDPR Article 44 transfer mechanisms add compliance overhead.
- On-Premise:Defense contractors and Swiss critical infrastructure operators deploy air-gapped installations to satisfy data localization statutes. Upfront licensing and hardware procurement typically exceed cloud lifetime costs within 18-24 months for high-volume operations.
- Hybrid:Preprocessing at the edge with cloud-based dense matching balances latency against elasticity.
- Edge Computing:Field-deployable reconstruction on drone-mounted NVIDIA Jetson modules enables real-time mission adaptation.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Edge Computing.
Solution/Offering:
Feature extraction commands the steepest pricing gradients due to AI-augmented automation reducing manual vectorization labor.
- Feature Extraction:Automated classification of vegetation, structures, and terrain types using convolutional neural networks trained on labeled orthomosaics. EU AI Act risk classification mandates model cards and training data provenance, adding 15-20% documentation overhead for German engineering consultancies.
- 3D Mapping:Dense image matching pipelines generate textured mesh models for urban planning and heritage documentation. Italian museum conservation teams and Japanese disaster response units drive demand for sub-hour reconstruction latency.
- Terrain Modeling:Digital elevation model generation with breakline enforcement for hydrological analysis.
- Volume Calculation:Cut-and-fill quantification for mining stockpiles and construction earthworks.
- Orthophoto Generation:Geometrically corrected aerial imagery with uniform scale for cadastral mapping.
Revenue concentrates in Feature Extraction workflows. 3D Mapping gains share fastest in heritage and emergency response verticals.
Application:
Construction monitoring absorbs the largest professional services attach rates due to as-built verification complexity.
- Construction Monitoring:Progress tracking and quality assurance through sequential photogrammetric surveys integrated with Building Information Modeling workflows. FAA Part 107 certified pilots capture structured data for heavy infrastructure projects across the United States.
- Surveying:Cadastral boundary determination and topographic mapping for land registration systems. EASA open-category frameworks standardize deployment altitudes across Germany, France, and Switzerland, though beyond-visual-line-of-sight permissions delay mission authorization by 60-90 days.
- Forestry Management:Canopy volume quantification for carbon-stock measurement under EU Green Deal biodiversity mandates.
- Mining Operations:Pit wall stability monitoring and ore stockpile inventory with weekly survey frequencies.
- Archaeological Documentation:Sub-centimeter recording of excavation stratigraphy and artifact positioning.
Surveying maintains the largest installed base. Construction monitoring climbs the fastest as digital twin convergence accelerates.
End User:
Engineering firms consolidate the highest annual contract values through multi-year enterprise agreements.
- Engineering Firms:Multidisciplinary infrastructure consultancies deploying photogrammetry across transportation, water resources, and urban development practices. German firms report scaling GPU-native pipelines to compress reconstruction timelines from overnight batches to near-real-time previews.
- GIS Specialists:Geospatial data managers requiring ISO 19115 metadata compliance and interoperable format export for enterprise spatial databases.
- Environmental Agencies:Carbon-stock and biodiversity monitoring procurement now specifies outcome-based deliverables rather than raw orthomosaic products.
- Research Institutions:Academic computer vision labs advancing neural radiance field and Gaussian splatting techniques for heritage documentation.
Engineering firms dominate current spending. Environmental agencies are expanding most quickly under regulatory measurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction digitization in Germany outpaces regulatory compliance overhead in France, while cloud-native deployment in Australia accelerates faster than on-premise retention in Switzerland.
United States
FAA Part 107 certified pilot networks and commercial drone service providers drive platform adoption across infrastructure inspection verticals. The FAA mandates operational altitude ceilings and beyond-visual-line-of-sight waivers that shape mission planning software requirements. Engineering consultancies in Texas and California deploy GPU-native pipelines to compress reconstruction timelines for heavy civil projects.
Germany
Environmental agencies and precision surveying contractors concentrate demand for dense image-matching workflows under EU Green Deal biodiversity mandates. GDPR Article 44 transfer mechanisms and data localization statutes fragment cloud-hosting strategies across federal states. Engineering clusters in Munich and Stuttgart scale photogrammetry platforms for corridor mapping and digital twin integration.
France
Heritage documentation teams and museum conservation units deploy real-time mesh generation for sub-hour reconstruction latency. The EU AI Act risk classification framework imposes documentation burdens on automated feature extraction algorithms. Research institutions in Paris and Lyon advance neural radiance field techniques for archaeological site recording.
Australia
State forestry departments specify outcome-based carbon-stock measurement contracts rather than raw orthomosaic deliverables. ISO 19115 metadata standards govern interoperable geospatial reporting formats for cross-jurisdictional collaboration. Environmental consultancies in New South Wales and Victoria migrate to metered cloud platforms to lower procurement barriers.
Japan
Disaster response units and heritage conservation teams drive demand for portable multi-camera rigs with instantaneous preview generation. METI industrial digitization programs subsidize adoption of 3D reconstruction platforms for infrastructure resilience planning. Technology development concentrates in Tokyo-Osaka corridors where Gaussian splatting research accelerates stakeholder decision cycles.
Global Photogrammetry Software Market Competitive Landscape
Swiss and US producers anchor one tier; German specialists hold differentiated positions in precision surveying workflows. The vendor base organizes around three strategic archetypes: cloud-native challengers rewriting core algorithms for GPU-native pipelines, established engineering software houses embedding photogrammetry into design suite workflows, and geospatial platform providers integrating reconstruction with enterprise spatial databases. Dominant competitive moves include strategic partnerships with drone hardware manufacturers and portfolio diversification into digital twin infrastructure.
Within the cloud-native tier, Pix4D SA exemplifies European research-to-product pipeline translation, while DroneDeploy Inc. represents US-based vertical specialization in aerial operations management. Autodesk Inc. and Bentley Systems Inc. anchor the engineering software integration archetype, each embedding reconstruction capabilities into civil design workflows. These four entities collectively illustrate the market's bifurcation between standalone processing platforms and embedded infrastructure components.
| Leading Market Players |
|---|
| Pix4D SA |
| Agisoft LLC |
| Autodesk Inc. |
| Bentley Systems Inc. |
| DroneDeploy Inc. |
| Hexagon AB |
| Trimble Inc. |
| Esri Global Inc. |
| 3Dflow SRL |
| Others |
Supply & Pricing Matrix
Computer vision PhD concentrations in Lausanne and Zurich widen pricing-tier spreads between premium GPU-native suites and entry-level cloud subscriptions, as bundle-adjustment expertise scarcity forces vendors to bid aggressively for specialized talent or absorb margin compression in mid-market tiers.
Pricing Analysis
Capacity additions in Swiss and German engineering clusters are reshaping price floors for on-premise installations, though cloud-native challengers maintain subscription advantages. Three-tier pricing structure across premium, standard, and economy levels separates defense-grade air-gapped deployments from metered SaaS offerings and freemium entry points. Cost compression in mid-market surveying tiers is intensifying because GPU compute volatility squeezes project-based margins. Environmental agencies exhibit lowest price sensitivity due to regulatory compliance mandates, while independent surveying contractors face acute pressure from per-project bidding cycles.
Supply Chain Analysis
NVIDIA data center GPU supply rests on Taiwanese foundry capacity and South Korean memory packaging, with cloud rendering infrastructure drawing from US hyperscaler networks. Dense image-matching algorithm development hinges on labeled training datasets sourced from German forestry agencies and Japanese heritage documentation teams. Single-source vulnerability concentrates in NVIDIA A100/H100 allocations for reconstruction pipelines. Distribution runs through direct enterprise sales for defense and critical infrastructure accounts, with cloud marketplaces capturing mid-sized environmental consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Procurement is shifting toward outcome-based carbon-stock and digital-twin deliverables rather than raw orthomosaic products, rewarding vendors with embedded analytics capabilities.
For Market Incumbents: Lock in bundle-adjustment engineering talent through captive hiring pipelines in Lausanne and Stuttgart research clusters. Deepen upstream control over GPU allocation contracts to insulate margins from NVIDIA data center pricing volatility. Defend against Gaussian-splatting challengers by accelerating real-time preview generation in cloud pipelines.
For New Entrants and Emerging Players: Metered cloud platforms targeting Australian state forestry departments offer the most penetrable entry vector. White-space concentrates in edge-computing reconstruction modules for drone-mounted NVIDIA Jetson deployments. Lead with subscription economics that eliminate server procurement cycles for mid-sized environmental consultancies.
For Investors and Strategic Acquirers: Civil engineering software houses are the most active acquirer in this space, seeking photogrammetry capabilities to embed within BIM workflows. Long-term viability favors vendors with AI-augmented feature extraction and EU AI Act compliance documentation infrastructure. Watch EASA beyond-visual-line-of-sight authorization timelines as inflection indicator for aerial survey mission velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| GPU-Native Pipeline Migration | Pix4D SA and DroneDeploy Inc. compress reconstruction from hours to minutes for competitive differentiation. |
| Digital Twin Integration | Bentley Systems Inc. embeds photogrammetry directly into infrastructure lifecycle management for heavy construction clients. |
| EU AI Act Compliance Investment | German engineering consultancies absorb documentation overhead to maintain cross-border project eligibility. |
| Edge Computing Module Development | Field-deployable NVIDIA Jetson reconstruction enables real-time mission adaptation for disaster response units. |
| Outcome-Based Contracting Pivot | Australian forestry departments now procure carbon-stock change detection rather than raw orthomosaic deliverables. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined through bottom-up and top-down triangulation. Primary interviews engaged photogrammetry software CTOs, civil engineering procurement leads at infrastructure consultancies, environmental agency geospatial data managers, and drone service provider operations heads. Secondary validation drew from FAA Part 107 regulatory filings, EASA operational authorization databases, EU AI Act implementation guidance, ISO 19115 metadata standards documentation, and hyperscaler GPU capex disclosures.
Rate-of-change decomposition across deployment models, solution layers, application verticals, and end-user categories structured the analytical framework over the projection horizon. CAGRs were derived from segment-level sizing with cross-validation against vendor-reported subscription metrics and enterprise licensing patterns. Modeled inputs included GPU-native adoption curves, EASA beyond-visual-line-of-sight authorization velocities, and EU Green Deal biodiversity monitoring procurement cycles.
The model assumes a particular technology adoption path; alternative pathways for neural radiance fields and Gaussian splatting would alter the outlook if real-time reconstruction latency compresses faster than projected. Forecasts reflect assumptions about regulatory compliance timelines, GPU supply availability, and drone traffic management system deployment. A small set of triggers—EASA authorization velocity, NVIDIA data center pricing volatility, and EU AI Act enforcement patterns—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global DevOps Software Market
Software & Services
Content Curation Software Market
Software & Services
Global Construction Management Software Market
Software & Services
Neurodiverse Workforce Productivity Tools Market
Software & Services
Online Lottery Software Market
Software & Services
Lighting Control Software Market
Software & Services
Braking Systems Software Market
Software & Services
MRP Software Market
Software & Services
Global Intelligent Apps Market
Software & Services
Codeless Testing Market
Software & Services
Movie Editing Software Market
Software & Services
Global Disk Imaging Software Market
Software & Services
Preschool Education Software Market
Software & Services
Application Server Market
Software & Services
Global Polling Software Market
Software & Services
Global Headless CMS Software Market