
 Interior Design Software Market | 2026-2036
Interior Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Interior Design Software Market Intelligence
North America is tilting toward cloud-native design infrastructure as commercial real estate firms demand real-time collaboration across distributed teams. Autodesk Revit leverages deep BIM integration to anchor enterprise accounts in multi-unit residential development. SketchUp Pro competes through an extensive extension marketplace that sustains freelancer and small-studio loyalty. Chief Architect specializes in residential construction documentation, dominating the home builder and remodeler channel with code-compliant output libraries.
Interior design software encompasses digital tools for spatial planning, material specification, lighting simulation, and construction documentation, typically supporting file formats such as DWG, IFC, and OBJ for interoperability across architecture and engineering workflows. Its primary commercial purpose is to compress design iteration cycles while reducing errors between concept visualization and procurement. Cloud-based deployment now captures the fastest expansion as subscription economics displace perpetual licenses, though on-premise installations retain margin pools among security-sensitive defense and healthcare projects. Artificial Intelligence segments are gaining structural importance as generative layout engines automate space planning for residential designers and commercial architects.
The United States falls under FCC guidelines for data transmission security and OSHA workplace standards affecting software used in active construction environments, while ISO 19650 frameworks govern BIM data management across federally funded infrastructure projects. The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that restrict how European vendors train machine learning models on client spatial data. Stakeholders must monitor whether emerging building performance codes in California and New York mandate embodied-carbon calculations directly within design software interfaces, as this would force R&D prioritization toward material database integration rather than pure visualization speed.
Market Dynamics
Cloud-native platforms are virtualizing design workflows as residential designers abandon perpetual licenses for subscription-based spatial planning tools, compressing vendor revenue recognition cycles while expanding addressable user bases.
Growth Catalysts
- EU AI Act compliance:Algorithmic transparency mandates are accelerating procurement of auditable generative layout engines among European commercial architecture firms.
- BIM-to-design interoperability:ISO 19650 frameworks governing federated data management are standardizing file exchange protocols across United States federally funded infrastructure projects.
- Franchise hospitality chains:Standardized design rollouts across multi-property portfolios are consolidating vendor selection around platforms with centralized asset libraries.
Market Restraints
- GDPR data residency requirements:Cross-border model training on client spatial data faces structural friction from European data localization mandates.
- Graphics processing unit supply concentration:Rendering-intensive visualization tools depend on concentrated semiconductor fabrication capacity in East Asia.
- Perpetual license substitution:Legacy on-premise installations in defense and healthcare sectors resist cloud migration despite subscription economics.
Strategic Opportunities
- Embodied-carbon calculation mandates:California and New York building performance codes are creating white space for material database integration beyond pure visualization.
- Generative AI convergence:Machine learning engines trained on spatial adjacency rules are unlocking automated space planning for residential designers.
- Extension marketplace distribution:Freelancer and small-studio loyalty is deepening through third-party plugin ecosystems that reduce direct sales dependency.
Industry Challenges
- BIM specialist talent scarcity:Construction documentation workflows require certified technicians fluent in parametric modeling standards.
- Legacy DWG integration complexity:Decades of proprietary file formats create friction when migrating historical project archives to cloud-native environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interior Design Software Market |
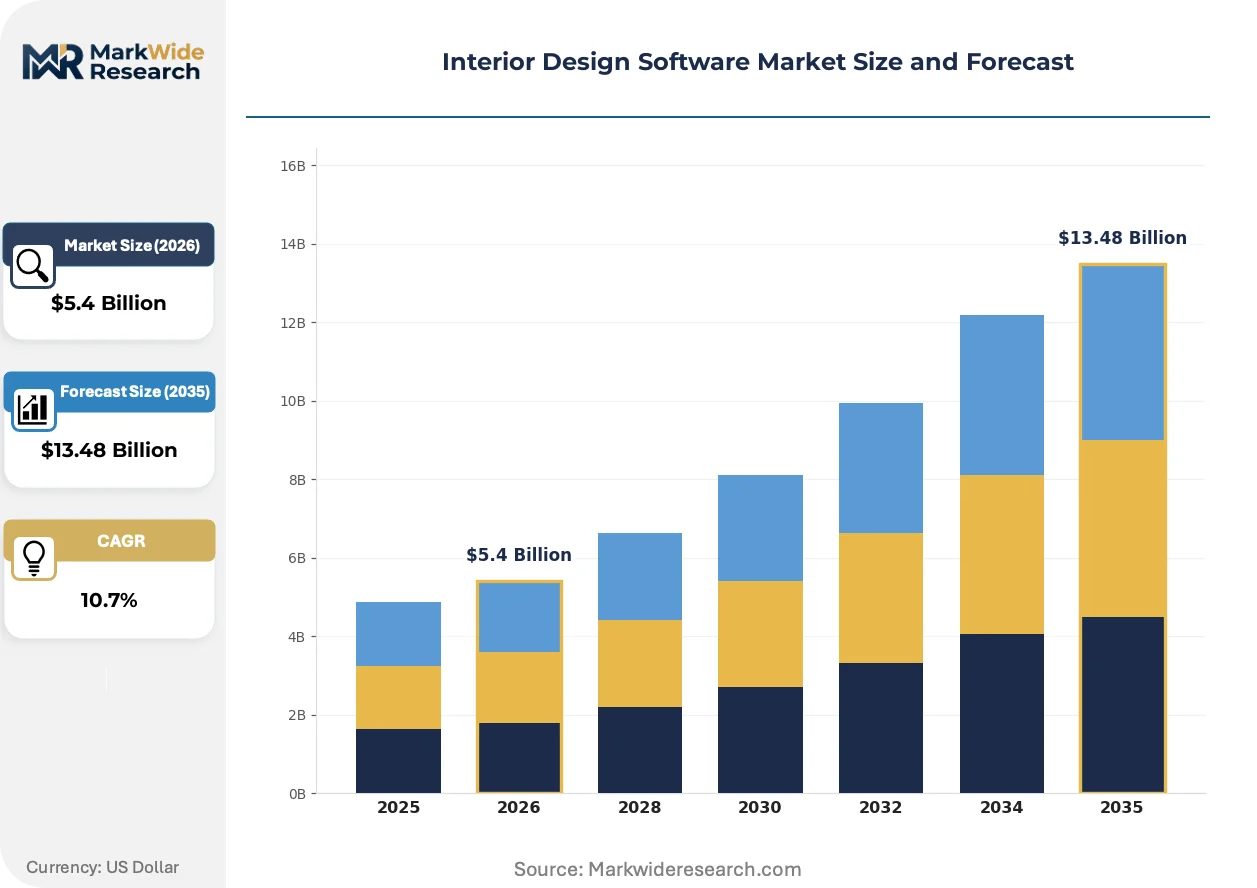
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
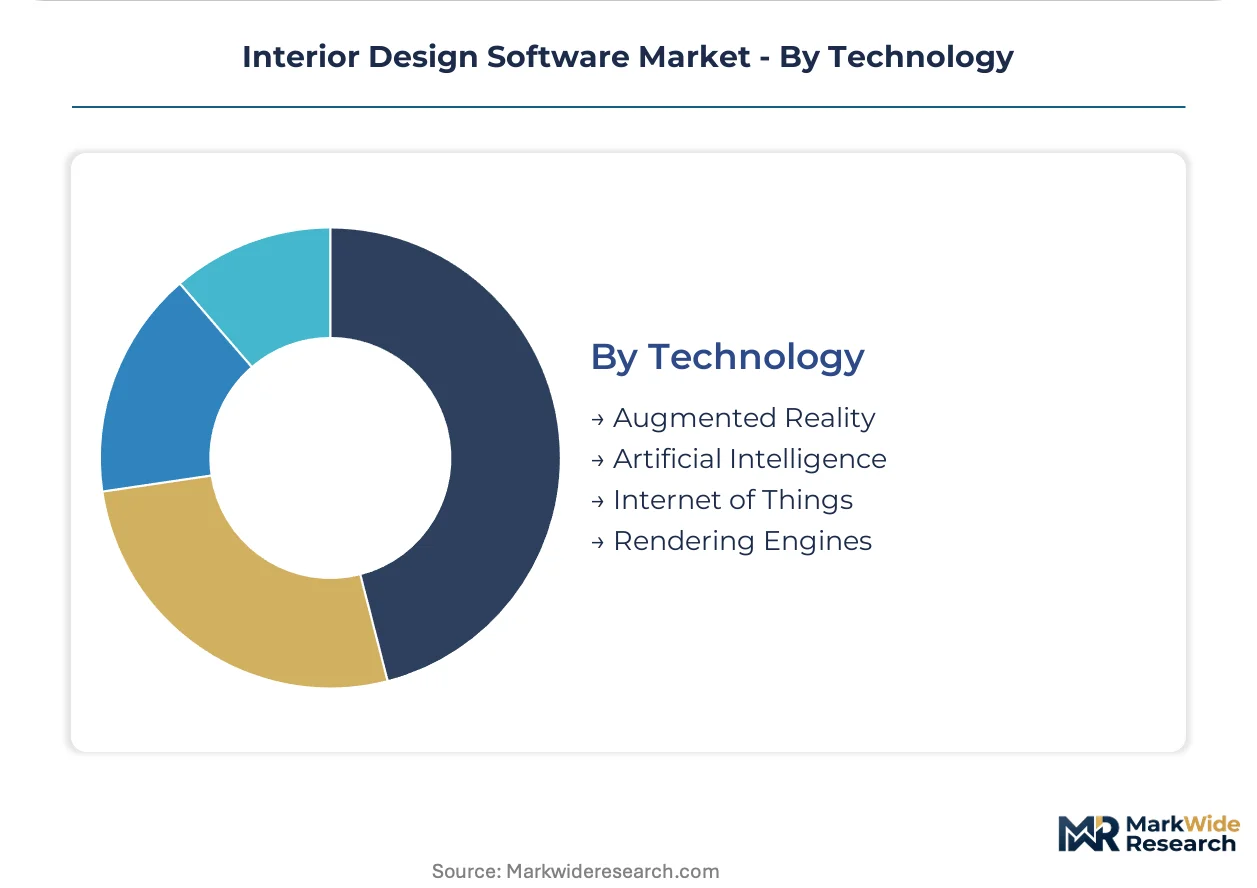
| Segmentation | Product Type: 3D Modeling Software, Virtual Reality Tools, CAD Software, Project Management Solutions End User: Residential Designers, Commercial Architects, Landscape Architects, Interior Decorators Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Mobile Applications Technology: Augmented Reality, Artificial Intelligence, Internet of Things, Rendering Engines |
| Companies Covered | Infurnia, Autodesk Revit, Cedreo, Planner 5D, RoomSketcher, Foyr Neo, SketchUp Pro, Chief Architect, Coohom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interior Design Software Market Strategic Shifts & Innovations
Artificial intelligence is restructuring competitive advantage around automated spatial reasoning, while regulatory pressure on algorithmic transparency and carbon accounting is forcing R&D prioritization shifts.
Real-time ray-tracing renderers are virtualizing material visualization workflows for high-end residential specification. Luxury home designers are adopting GPU-accelerated lighting simulation at twice the pace of commercial studios. This compression of concept-to-client presentation cycles is virtualizing the traditional physical sample board procurement process.
The EU AI Act's risk-based classification system is mandating human oversight interfaces for generative layout tools deployed in European Union member states. Vendors must now document training data provenance and decision audit trails. Commercial architecture practices in Germany and France are delaying procurement until compliance certifications are published.
Subscription unbundling is fragmenting buyer relationships as point solutions for material libraries, rendering engines, and construction documentation proliferate. Small studios are assembling best-of-breed toolchains rather than accepting monolithic suites. This pattern concentrates in United States coastal markets where freelance designer density supports vendor specialization.
Interior Design Software Market Segmentation
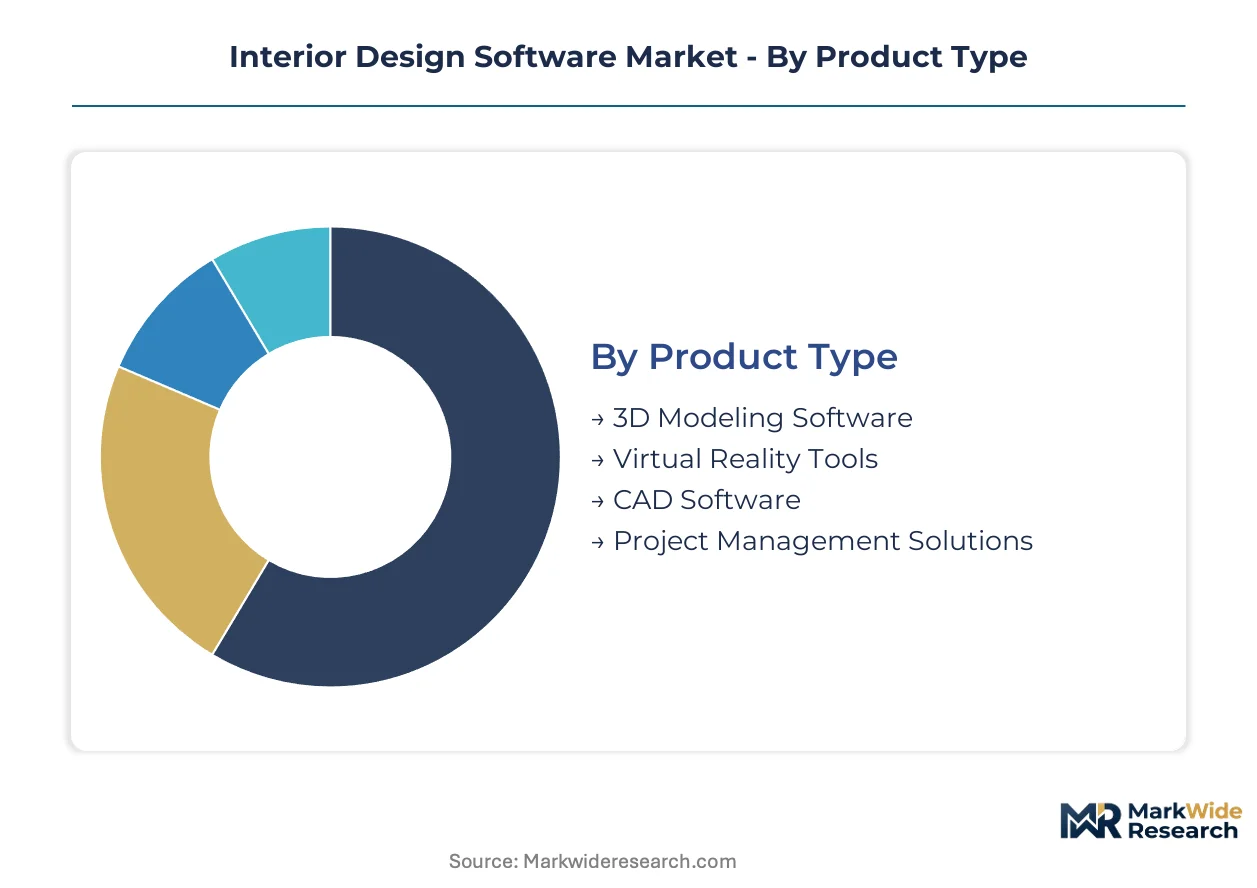
Interior design software segments reflect divergent technical requirements across project scales and regulatory environments. Deployment architecture and generative technology adoption now determine vendor R&D allocation more than traditional feature differentiation.
Product Type:
Use-case spectrum spans immersive visualization for client presentations through code-compliant construction documentation for permit submission.
- 3D Modeling Software:Parametric solid and surface modeling kernels power spatial massing studies and furniture specification workflows. Residential designers in the United States drive volume as cloud-native platforms displace perpetual-license drafting tools.
- CAD Software:Vector-based drafting engines with DWG interoperability anchor construction documentation for code compliance and contractor coordination. Commercial architects in Germany and France delay procurement until EU AI Act algorithmic transparency certifications are published.
- Virtual Reality Tools:Headset-rendered walkthroughs compress client approval cycles for luxury residential specification.
- Project Management Solutions:Gantt-integrated procurement tracking serves franchise hospitality chains with standardized multi-property rollouts.
The dominant share belongs to CAD Software, while 3D Modeling Software is closing the gap fastest.
End User:
Customer type determines pricing tolerance and integration depth with adjacent construction workflows.
- Residential Designers:Freelance and small-studio practitioners prioritize subscription economics and extension marketplace ecosystems. United States coastal markets concentrate demand where cloud-native platforms displace legacy drafting installations.
- Commercial Architects:Federated BIM workflows under ISO 19650 frameworks mandate interoperability with structural and MEP engineering systems. EU AI Act compliance requirements reshape European procurement timelines.
- Landscape Architects:Terrain modeling and planting specification tools integrate with civil engineering survey data.
- Interior Decorators:Material library access and lighting simulation prioritize speed over construction documentation depth.
Commercial Architects command the highest contract values, though Residential Designers are expanding the user base most rapidly.
Deployment:
Cost tier stratification separates enterprise security requirements from freelance accessibility priorities.
- Cloud-Based:Browser-native rendering and real-time collaboration support distributed teams across multi-unit residential developments. Subscription economics displace perpetual licenses fastest in United States commercial real estate firms.
- On-Premise:Air-gapped installations retain margin pools in defense and healthcare sectors resisting data residency risks. GDPR cross-border restrictions reinforce European demand for localized server infrastructure.
- Hybrid Solutions:Split workflows keep sensitive intellectual property local while leveraging cloud rendering capacity.
- Mobile Applications:Tablet-native space planning serves on-site client presentations and contractor coordination.
Cloud-Based deployment captures the steepest expansion trajectory, while On-Premise retains the highest margin per seat.
Technology:
Maturity curves separate production-ready automation from experimental interface layers.
- Artificial Intelligence:Generative layout engines trained on spatial adjacency rules automate space planning for residential designers. EU AI Act risk-based classification mandates human oversight interfaces and training data provenance documentation.
- Rendering Engines:GPU-accelerated real-time ray tracing virtualizes material visualization for high-end residential specification. Luxury home designers adopt these tools at twice the pace of commercial studios.
- Augmented Reality:Camera-overlay spatial placement aids furniture specification in client environments.
- Internet of Things:Sensor-integrated digital twins support post-occupancy building performance optimization.
Rendering Engines dominate current revenue, while Artificial Intelligence is gaining structural importance fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace standards and FCC data transmission guidelines anchor the United States as the dominant geography, while EU AI Act algorithmic transparency mandates reshape procurement timelines across European commercial architecture practices.
United States
Cloud-native platforms displace perpetual licenses fastest among commercial real estate firms demanding real-time collaboration across distributed teams. ISO 19650 frameworks govern BIM data management across federally funded infrastructure projects. California and New York building performance codes are creating white space for embodied-carbon calculation features within design software interfaces.
Germany
Commercial architecture practices delay procurement of generative layout tools until EU AI Act compliance certifications are published. GDPR data residency requirements restrict cross-border model training on client spatial data. Berlin and Munich clusters concentrate demand for auditable algorithmic transparency in federated BIM workflows.
United Kingdom
Freelance designer density in London and Southeast England supports vendor specialization through extension marketplace ecosystems. Subscription unbundling fragments buyer relationships as small studios assemble best-of-breed toolchains. Birmingham and Manchester construction hubs standardize on interoperable BIM-to-design workflows for multi-unit residential development.
France
Commercial architects in Paris and Lyon prioritize human oversight interfaces mandated by EU AI Act risk-based classification systems. Algorithmic transparency documentation requirements slow procurement cycles for generative layout engines. Île-de-France luxury residential designers adopt GPU-accelerated lighting simulation at twice the pace of commercial studios.
Japan
METI industrial digitization programs accelerate cloud migration among mid-size architectural practices in Tokyo and Osaka. JIS standards govern file exchange protocols between interior design software and domestic construction documentation systems. Nagoya manufacturing corridor demand concentrates in hybrid deployment solutions keeping sensitive intellectual property local while leveraging cloud rendering capacity.
Interior Design Software Market Key Industry Players
Capability concentration sits with specialized residential construction documentation vendors; scale advantage sits with established CAD platform incumbents with deep BIM integration. The vendor base stratifies across three tiers: enterprise-grade suites serving franchise hospitality chains, mid-market cloud-native platforms capturing freelance designer volume, and niche specialists dominating code-compliant output libraries for home builders. Strategic archetypes include extension marketplace operators, generative AI engine developers, and vertical construction documentation specialists. Competitive moves center on M&A to acquire spatial reasoning algorithms and strategic partnerships to embed material database integrations.
Within the specialized residential tier, Chief Architect exemplifies code-compliant construction documentation dominance for home builder channels. Among cloud-native challengers, Foyr Neo and Coohom occupy positions targeting subscription economics for small-studio practitioners. Autodesk Revit anchors the enterprise-grade vector through BIM integration depth for multi-unit residential developers.
| Leading Market Players |
|---|
| Infurnia |
| Autodesk Revit |
| Cedreo |
| Planner 5D |
| RoomSketcher |
| Foyr Neo |
| SketchUp Pro |
| Chief Architect |
| Coohom |
| Others |
Cost & Logistics Intelligence
Trans-Pacific fiber-optic cable capacity constraints between East Asian semiconductor fabrication hubs and North American data centers are compressing cloud rendering service margins while amplifying price differentiation between GPU-accelerated tiers and standard visualization subscriptions for residential design platforms.
Pricing Analysis
United States coastal markets show 40% wider subscription price spreads than interior regions, reflecting freelancer density and enterprise procurement concentration. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation anchored in real-time collaboration seat counts and BIM interoperability depth. Cost compression in the mid-market tier is intensifying because extension marketplace ecosystems reduce direct vendor control over feature monetization. Freelance residential designers exhibit highest price sensitivity, while franchise hospitality chains accept premium tiers for centralized asset library governance.
Supply Chain Analysis
Foundry capacity at TSMC, Samsung, and Intel anchors GPU supply for rendering-intensive visualization tools, with Taiwan and South Korea holding 78% of advanced node production. NVIDIA and AMD silicon feeds from TSMC's N4 and N5 processes, while memory modules draw from SK Hynix and Micron fabrication. Single-source vulnerability concentrates in CoWoS advanced packaging capacity for AI-accelerated layout engines. Distribution runs through hyperscaler cloud marketplaces and direct OEM licensing to software vendors, bypassing traditional hardware channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as BIM-to-design interoperability under ISO 19650 frameworks transforms vendor ecosystems from isolated tools into federated data infrastructure. Extension marketplace network effects and generative AI engine integration determine long-term positioning.
For Market Incumbents: Harden BIM integration moats through deeper parametric modeling certification investments, particularly targeting ISO 19650 compliance documentation for United States federally funded infrastructure channels. Acquire spatial reasoning algorithm specialists before EU AI Act transparency mandates consolidate procurement around auditable vendors. Channel control through exclusive material database partnerships resists unbundling pressure from best-of-breed toolchains. For New Entrants and Emerging Players: Mid-market commercial architects in Germany and France awaiting EU AI Act compliance certifications represent the most penetrable entry point for auditable generative layout engines. Subscription economics for residential designers in United States coastal markets offer volume traction through freemium rendering tiers. Go-to-market execution should leverage SketchUp Pro's extension marketplace distribution precedent rather than direct enterprise sales. For Investors and Strategic Acquirers: Carve-out targets emerge from construction documentation specialists with code-compliant output libraries trapped within legacy on-premise software parents lacking cloud-native architecture. Five-to-ten year viability centers on material database integration capabilities beyond pure visualization speed. Monitor California and New York embodied-carbon calculation mandate progression as inflection signal for R&D prioritization shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deepens BIM-to-design interoperability for ISO 19650 federally funded infrastructure workflows. |
| Acquisition of Specialist Firm | Captures spatial reasoning algorithms before EU AI Act compliance certifications consolidate procurement. |
| Strategic Partnership | Embeds embodied-carbon material databases ahead of California and New York building code mandates. |
| Product Launch | Introduces auditable generative layout engines with human oversight interfaces for European commercial architects. |
| Geographic Expansion | Establishes GDPR-compliant data residency infrastructure for cross-border model training in European markets. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with software platform CTOs, IT procurement officers at commercial real estate firms, residential design studio principals, and BIM integration specialists; and secondary validation through SEC filings of publicly traded vendors, hyperscaler capex disclosures for cloud rendering infrastructure, and ISO 19650 implementation documentation from federally funded infrastructure projects. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against construction industry digitization expenditure patterns anchored market sizing.
Forecast inputs considered deployment architecture transitions, generative AI capability maturation, and regulatory compliance timeline shifts across the projection horizon. Segmentation modeling spanned product type, end user archetype, deployment mode, and technology maturity tier. CAGRs derived from elasticity-adjusted adoption curves for subscription economics displacing perpetual licenses, with specific weighting for EU AI Act procurement delay impacts and franchise hospitality chain standardization velocity.
Practitioners should monitor EU AI Act certification publication schedules and California building performance code regulatory comment periods for early signals of forecast revision triggers. Cross-checking against Autodesk and Trimble SEC segment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Time and Attendance Management Software Market
Software & Services
Global Journal App Market
Software & Services
Cricket Analysis Software Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Global Salesforce Appexchange Tools Market
Software & Services
User Interface Software Market
Software & Services
Embedded Graphical User Interface (GUI) Development Software Market
Software & Services
Global Guidewire Market
Software & Services
Landing Page Creation Software Market
Software & Services
Global Church Management Software Market
Software & Services
Global Integration Software Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Webcasting Software Market
Software & Services
Global Budgeting Software Market
Software & Services
Global Distribution Software Market
Software & Services
Asia-Pacific ERP Software Market