
 Stock Control Software Market | 2026-2036
Stock Control Software Market Size, Share, and Industry Trends Forecast 2026-2036
Stock Control Software Market Analysis
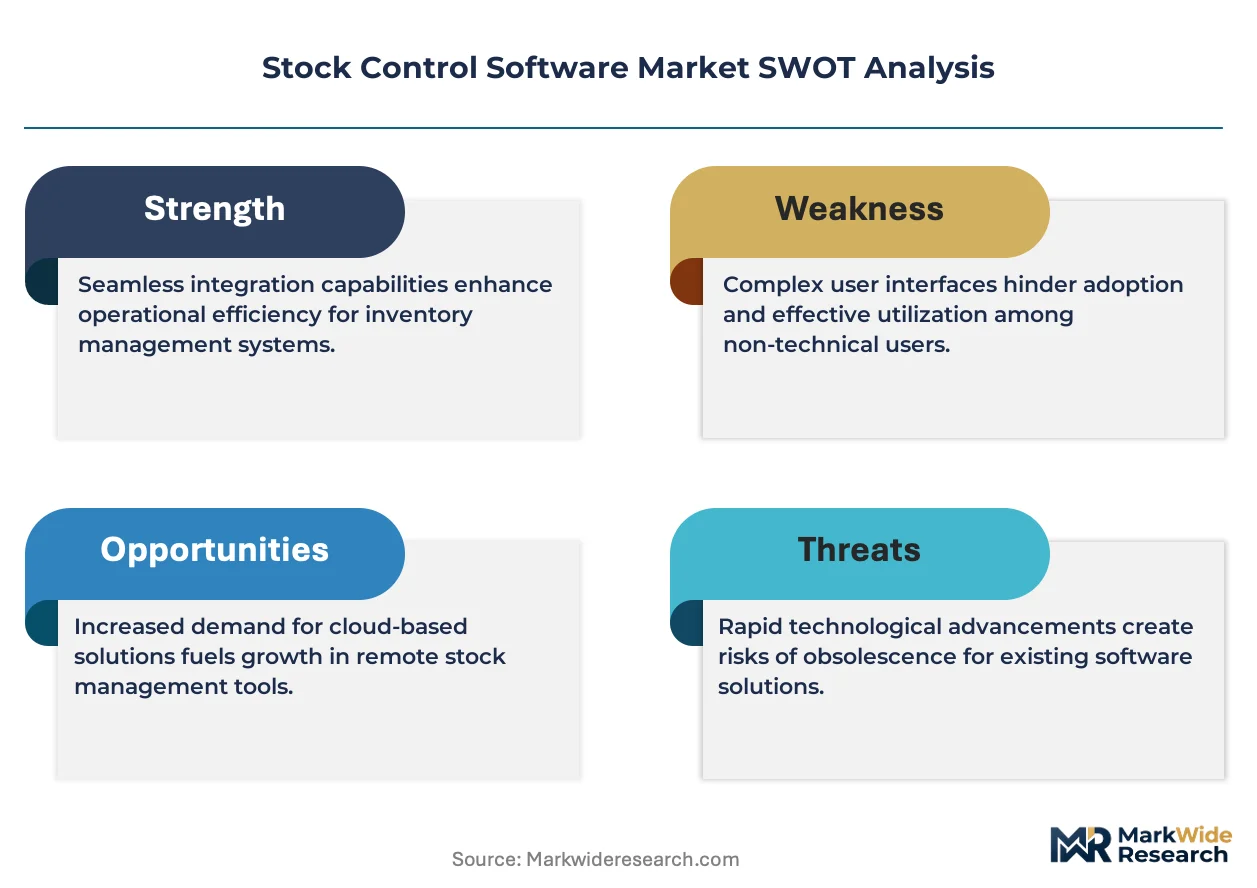
GDPR is realigning the cost-of-entry calculus for stock control software vendors targeting European enterprises. SAP SE leverages its embedded compliance architecture to sustain long-term contracts with multinational manufacturers. Oracle Corporation anchors its competitive stance through deep database integration and advanced analytics capabilities. Zoho Corporation differentiates by offering modular subscription tiers that appeal to mid-market wholesalers seeking rapid deployment without heavy infrastructure investment.
Stock control software encompasses systems that track inventory levels, orders, deliveries, and sales across supply chain nodes through barcode scanning, RFID integration, and automated reorder point algorithms. Cloud-based deployment dominates structural growth as retailers and distributors prioritize remote accessibility and automatic updates over capital-intensive on-premise installations. Multi-tenant architectures command expanding share among small-to-mid enterprises due to lower per-seat economics, while single-tenant configurations retain preference among manufacturers with stringent data sovereignty requirements.
The EU AI Act, ISO 27001, and HIPAA shape compliance burdens that filter vendor eligibility and inflate implementation timelines for regulated sectors. FDA traceability rules for pharmaceutical distributors and FERC reporting standards for energy-sector procurement further fragment certification requirements across verticals. Stakeholders must weigh jurisdictional compliance stacking against platform consolidation benefits when selecting long-term inventory management partners.
Market Dynamics
Cloud migration is compressing deployment timelines while GDPR and the EU AI Act impose compliance architectures that reshape vendor eligibility across European enterprises.
Growth Catalysts
- RFID Integration:Pharmaceutical distributors deploy item-level tracking to satisfy FDA traceability mandates, compressing recall response windows from weeks to hours.
- Germany's Manufacturing Density:Automotive and precision engineering clusters generate concentrated demand for real-time inventory synchronization across multi-tier supplier networks.
- ISO 27001 Certification:Cloud providers achieving this standard unlock procurement pipelines from defense contractors and financial institutions with stringent data sovereignty requirements.
Market Restraints
- Input Cost Volatility:Semiconductor shortages inflate RFID tag and sensor module prices, squeezing hardware-dependent deployment budgets.
- Technical Limitation:Legacy warehouse management systems lack API-native architectures, forcing expensive middleware development for hybrid cloud-on-premise configurations.
- Regulatory Friction:HIPAA compliance timelines extend implementation cycles for healthcare distributors by four to eight months versus non-regulated verticals.
Strategic Opportunities
- Underpenetrated Japan:Small-to-mid manufacturers remain dependent on spreadsheet-based tracking, creating whitespace for modular SaaS platforms with rapid deployment models.
- Technology Convergence:Edge computing paired with computer vision enables autonomous cycle counting without fixed infrastructure, opening greenfield warehouse deployments.
- CSRD Reporting Mandate:The EU's Corporate Sustainability Reporting Directive forces Scope 3 emissions disclosure, driving demand for inventory systems with embedded carbon accounting modules.
Industry Challenges
- Integration Complexity:ERP migration projects stall when stock control modules fail to reconcile historical batch records with real-time API feeds.
- Certification Bottleneck:ISO 27001 audit backlogs extend vendor onboarding timelines, freezing procurement decisions for risk-averse enterprises.
- Talent Scarcity:Supply chain data engineers command premium compensation, constraining mid-market software vendors' implementation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stock Control Software Market |
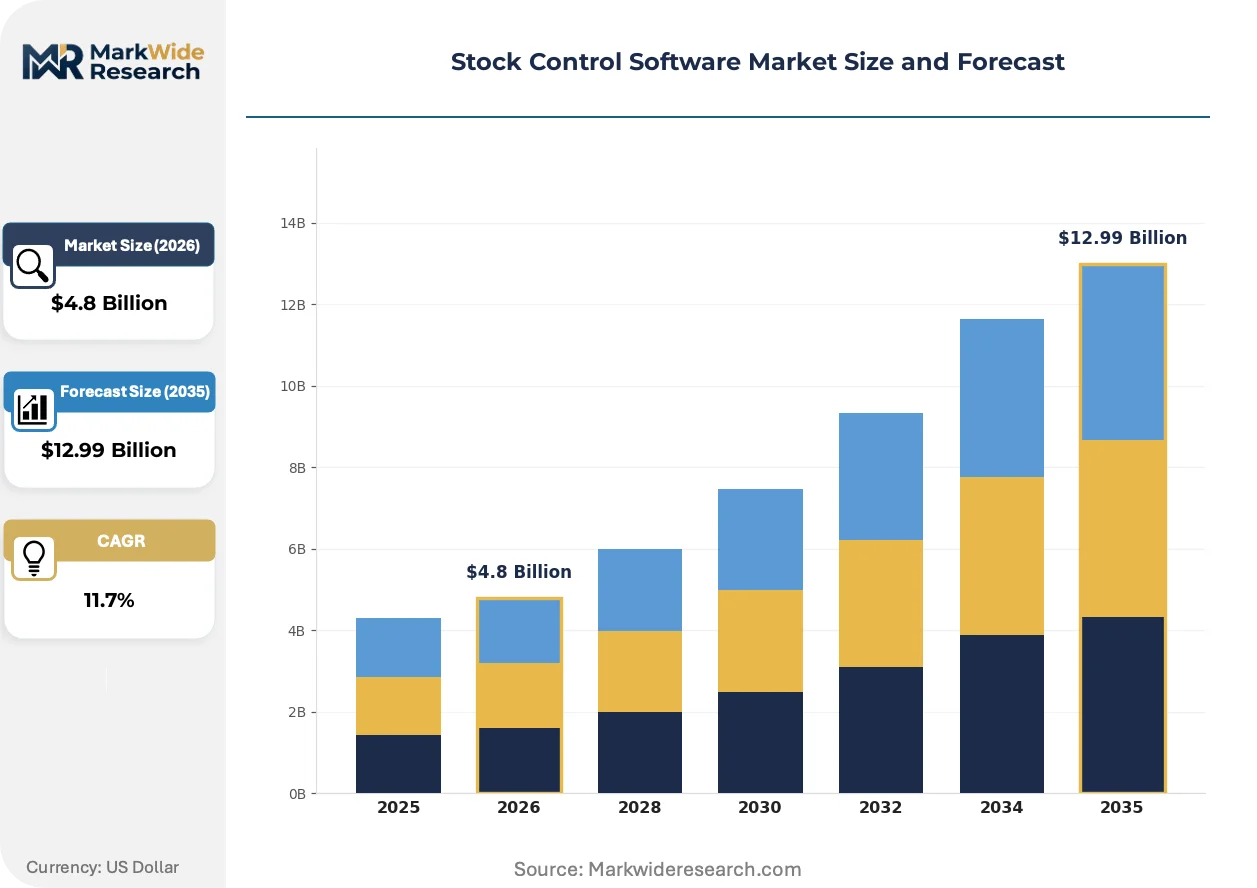
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Mobile End User: Retailers, Manufacturers, Wholesalers, Distributors Deployment Model: Single Tenant, Multi-Tenant, Private Cloud, Public Cloud Service Type: Subscription, License, Maintenance, Support |
| Companies Covered | SAP SE, Oracle Corporation, Fishbowl Inventory, Zoho Corporation, Microsoft Corporation, NetSuite, Cin7, Manhattan Associates, Unleashed Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stock Control Software Market Emerging Trajectories
Artificial intelligence is penetrating inventory forecasting while regulatory pressure hardens data architecture requirements and buyer procurement models compress vendor evaluation cycles.
Machine learning demand forecasting is rewriting how distributors buffer safety stock. Third-party logistics providers in the United States are deploying neural network models that ingest point-of-sale telemetry, weather patterns, and port congestion signals. This capability is compressing working capital requirements by fifteen to twenty-five percent for early adopters while raising performance benchmarks for competing vendors.
The EU AI Act's risk classification framework is mandating algorithmic audit trails for automated reorder systems. High-risk inventory decisions—particularly in pharmaceutical and medical device distribution—now require documented human oversight protocols. German and French wholesalers are restructuring procurement committees to satisfy these governance requirements, creating specification advantages for vendors with embedded compliance tooling.
Subscription-based procurement is displacing perpetual license purchases among mid-market retailers. Buyers in Japan and the United States now prioritize vendors offering usage-based tiers with rapid scaling provisions over capital-intensive on-premise installations. This shift favors multi-tenant cloud architectures and compresses sales cycles for platforms with transparent API documentation and self-service onboarding workflows.
Stock Control Software Market Segmentation
Stock control software vendors configure pricing and feature architectures around deployment complexity, data sovereignty requirements, and customer procurement maturity. Segment boundaries shift as cloud economics restructure total-cost-of-ownership calculations across buyer tiers.
Product Type:
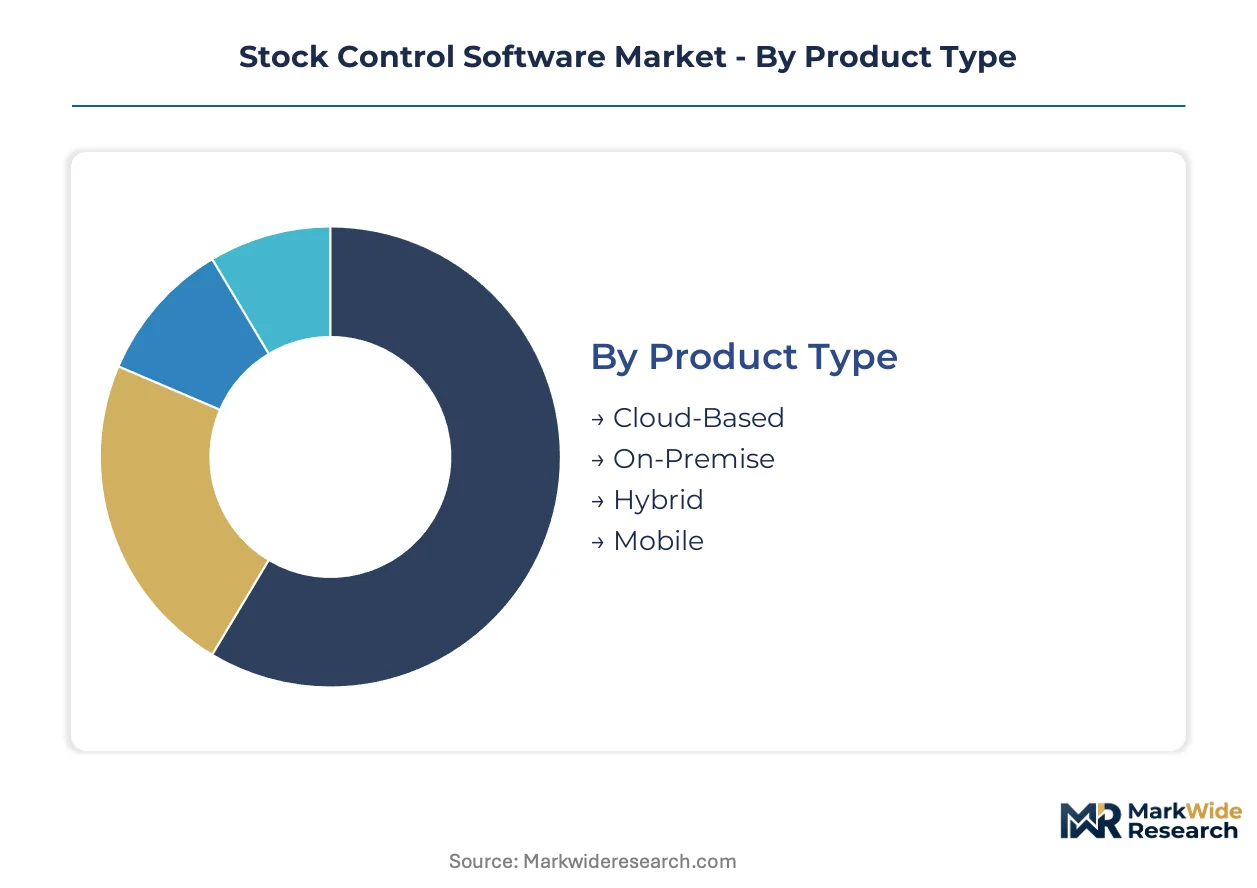
Cloud-based platforms command volume leadership while on-premise installations retain premium pricing power in regulated verticals.
- Cloud-Based:Multi-tenant architectures deliver automatic updates and remote accessibility through browser interfaces. Pharmaceutical distributors in Germany and the United States prioritize these platforms to satisfy FDA and EMA traceability mandates without infrastructure overhead.
- On-Premise:Single-instance deployments run on customer-managed servers with full data localization. Defense contractors and financial institutions in Switzerland and Japan specify these configurations to meet ISO 27001 and domestic data sovereignty laws.
- Hybrid:Split architectures synchronize edge warehouse operations with centralized cloud analytics. Manufacturers with legacy ERP investments use these to bridge batch-record systems with real-time API feeds.
- Mobile:Native iOS and Android applications enable floor-level cycle counting and receiving workflows. Third-party logistics providers in the United States deploy these for driver inventory verification without fixed terminal infrastructure.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
End User:
Application context determines integration depth and compliance module requirements across buyer categories.
- Retailers:Omnichannel sellers require real-time inventory visibility across storefronts, warehouses, and drop-ship partners. Subscription-based procurement dominates as mid-market chains prioritize rapid scaling over capital expenditure.
- Manufacturers:Discrete and process producers synchronize raw material buffers with production schedules. Automotive clusters in Germany generate concentrated demand for multi-tier supplier network visibility.
- Wholesalers:Bulk distributors manage high-velocity SKUs with seasonal demand volatility. These buyers favor modular SaaS platforms with usage-based tiers that align costs with transaction volumes.
- Distributors:Specialty and broad-line distributors navigate complex lot-tracking and expiration-date requirements. Pharmaceutical and medical device distributors in France and Germany restructure procurement committees to satisfy EU AI Act governance protocols.
Manufacturers anchor current revenue concentration. Retailers are expanding most quickly as digital commerce penetration deepens.
Deployment Model:
Tenant architecture selection reflects data isolation requirements and per-seat economics tradeoffs.
- Single Tenant:Dedicated infrastructure instances serve one customer with complete resource isolation. Energy-sector procurement teams in the United States specify these to satisfy FERC reporting standards without commingled data environments.
- Multi-Tenant:Shared resource pools drive lower per-seat costs through economies of scale. Small-to-mid enterprises in Japan select these for rapid deployment without heavy infrastructure investment.
- Private Cloud:Customer-dedicated cloud environments balance accessibility with controlled infrastructure. Healthcare distributors facing HIPAA compliance timelines favor these for documented data boundary enforcement.
- Public Cloud:Shared hyperscaler infrastructure delivers maximum elasticity and geographic redundancy. Retail chains with seasonal demand spikes leverage auto-scaling provisions to avoid over-provisioning.
Multi-Tenant dominates transaction volume. Private Cloud is gaining share fastest as regulated verticals migrate from pure on-premise estates.
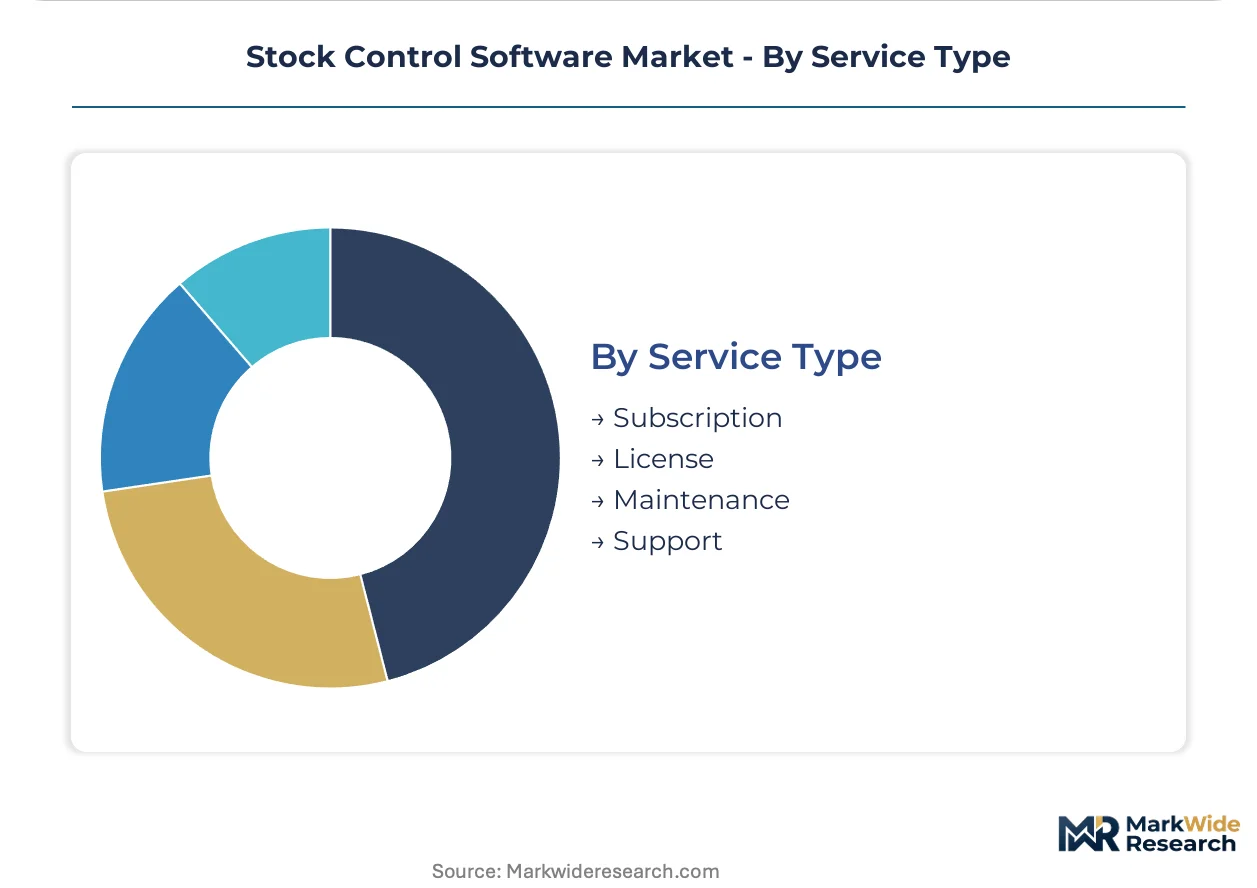
Service Type:
Procurement model preferences are compressing vendor sales cycles and restructuring recurring revenue profiles.
- Subscription:Recurring fees based on user count, transaction volume, or module activation. Mid-market buyers in Japan and the United States now prioritize these with rapid scaling provisions over perpetual alternatives.
- License:One-time perpetual purchases with annual maintenance fees. Large manufacturers with capital budgeting cycles continue specifying these for multi-year total-cost predictability.
- Maintenance:Technical support, bug fixes, and minor version updates. Defense contractors treat these as mandatory for operational continuity assurance.
- Support:Implementation assistance, training, and custom integration services. Buyers with legacy warehouse management systems require extensive middleware development support for hybrid configurations.
Subscription captures expanding share. Support services represent the fastest-climbing margin contributor as integration complexity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply chain data engineers concentrate in Germany, the United States, and Japan, anchoring regional innovation capacity for inventory synchronization platforms. Cloud infrastructure investments and regulatory compliance mandates are redrawing procurement priorities across these talent hubs.
United States
Third-party logistics providers deploy neural network demand forecasting models that ingest point-of-sale telemetry and port congestion signals. FDA traceability mandates for pharmaceutical distributors compress recall response windows from weeks to hours. The Chicago and Dallas metropolitan areas host concentrated warehouse automation clusters where edge computing paired with computer vision enables autonomous cycle counting.
Germany
Automotive and precision engineering clusters generate concentrated demand for real-time inventory synchronization across multi-tier supplier networks. The EU AI Act's risk classification framework mandates algorithmic audit trails for automated reorder systems in pharmaceutical and medical device distribution. Stuttgart and Munich anchor manufacturing density where wholesalers restructure procurement committees to satisfy governance requirements.
Japan
Small-to-mid manufacturers remain dependent on spreadsheet-based tracking, creating whitespace for modular SaaS platforms with rapid deployment models. METI standards and domestic data sovereignty laws shape vendor certification requirements for financial institutions. The Nagoya and Osaka industrial corridors concentrate precision engineering firms seeking cloud-based traceability without heavy infrastructure investment.
United Kingdom
Mid-market retailers prioritize subscription-based procurement with rapid scaling provisions over capital-intensive on-premise installations. GDPR compliance architectures reshape vendor eligibility across enterprise procurement pipelines. The London metropolitan area and Midlands logistics corridor concentrate omnichannel sellers requiring real-time inventory visibility across storefronts, warehouses, and drop-ship partners.
France
Pharmaceutical and medical device distributors navigate complex lot-tracking and expiration-date requirements under EMA oversight. The EU's Corporate Sustainability Reporting Directive forces Scope 3 emissions disclosure, driving demand for inventory systems with embedded carbon accounting modules. The Lyon and Paris metropolitan areas concentrate specialty distributors restructuring governance protocols to satisfy algorithmic audit mandates.
Stock Control Software Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment complexity tiers. The market structure fragments between enterprise-scale platforms with embedded compliance architectures and modular SaaS vendors targeting rapid mid-market deployment. Three archetypes dominate: database-anchored technology conglomerates, cloud-native inventory specialists, and ERP-integrated platform providers. Competitive moves concentrate on M&A for API-native capabilities and strategic partnerships to bridge legacy warehouse management systems with real-time analytics.
Within the enterprise platform tier, SAP SE and Oracle Corporation occupy positions defined by deep infrastructure integration and long-term contract structures. Zoho Corporation exemplifies the modular SaaS archetype, anchoring mid-market appeal through subscription tier flexibility. These three entities represent contrasting strategic postures on compliance embedding, deployment velocity, and customer scale segmentation.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Fishbowl Inventory |
| Zoho Corporation |
| Microsoft Corporation |
| NetSuite |
| Cin7 |
| Manhattan Associates |
| Unleashed Software |
| Others |
Supply Flow & Price Mechanics
Cloud-native architecture migration simultaneously compresses marginal delivery costs and concentrates vendor bargaining power among hyperscale infrastructure providers. Subscription-based procurement models now dominate mid-market transactions, while single-tenant deployments retain premium positioning for defense contractors and financial institutions facing stringent data sovereignty requirements.
Pricing Analysis
Bundled compliance modules versus unbundled core platform splits now define vendor pricing architecture. SaaS tiering stratifies across enterprise, professional, and starter levels with ISO 27001 certification grade as the primary price differentiation driver. Cost compression in starter tiers intensifies because multi-tenant economies of scale commoditize basic inventory tracking functionality. Mid-market wholesalers exhibit highest price sensitivity, while pharmaceutical distributors under FDA traceability mandates demonstrate lowest sensitivity due to non-negotiable audit trail requirements.
Supply Chain Analysis
Freight cost volatility in semiconductor component shipping exerts downstream pressure on RFID hardware pricing. Software development concentrates in the United States, Germany, and India, with cloud infrastructure provisioning anchored in hyperscale data centers across Ireland, Singapore, and Virginia. Raw material dependencies span silicon wafers for edge sensors, lithium for mobile device batteries, and rare earth elements for server rack magnetics. Single-source vulnerability in Taiwan-based semiconductor fabrication creates supply chain risk for hardware-dependent deployment budgets. Distribution runs through direct vendor sales for enterprise accounts and channel partner networks for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stock control software has matured into a late-cycle quality story as pharmaceutical and medical device distributors prioritize EU AI Act-compliant platforms over cost-optimized alternatives. Premium specification demand now favors vendors with embedded algorithmic audit trails and documented human oversight protocols.
For Market Incumbents: Deepen ISO 27001 certification investment to defend procurement pipelines from defense contractors and financial institutions. Expand API-native middleware capabilities to capture hybrid cloud-on-premise migration demand from legacy warehouse management system users. Cloud-native specialists with rapid deployment models represent the primary competitive threat to long-term contract structures.
For New Entrants and Emerging Players: Launch via modular SaaS platforms targeting Japan's spreadsheet-dependent small-to-mid manufacturers. Prioritize rapid self-service onboarding workflows with transparent API documentation to compress sales cycles. Edge computing paired with computer vision for autonomous cycle counting offers the most penetrable greenfield application whitespace.
For Investors and Strategic Acquirers: Valuations sit cheapest among on-premise legacy vendors with stranded customer bases but embedded compliance expertise. Long-term viability favors platforms with multi-tenant architectures capable of serving both regulated and non-regulated verticals through tenant isolation features. Watch CSRD reporting mandate adoption velocity as the inflection indicator for carbon accounting module demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native middleware bridges legacy ERP batch records with real-time cloud analytics for hybrid deployments. |
| Acquisition of Specialist Firm | Computer vision startups enable autonomous cycle counting without fixed warehouse infrastructure investment. |
| Strategic Partnership | Hyperscaler alliances unlock auto-scaling provisions for retail chains with seasonal demand spikes. |
| Geographic Expansion | Japan's Nagoya and Osaka corridors concentrate precision engineering firms seeking rapid cloud deployment. |
| Product Launch | Embedded carbon accounting modules satisfy EU CSRD Scope 3 emissions disclosure mandates for distributors. |
Methodological Framework
Bottom-up enterprise deployment modeling reconciled against top-down cloud infrastructure tracking forms the analytical core of this study. Primary interviews with supply chain data engineers, IT procurement officers at pharmaceutical distributors, platform integration specialists, and warehouse operations directors combined with secondary validation from SEC filings, hyperscaler capex disclosures, FDA traceability guidance documents, and EU regulatory filings. Triangulation across these sources ensures segmentation outputs reflect actual procurement behavior rather than vendor-reported metrics.
Input-output matrix framing maps deployment model adoption patterns, organization size tiering, vertical compliance intensity, and regional cloud maturity across the projection horizon. CAGRs derive from modeled segment trajectories weighted against infrastructure investment cycles and regulatory implementation timelines. Forecast inputs incorporate RFID hardware cost curves, ISO 27001 certification audit backlog dynamics, and EU AI Act enforcement phase transitions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or accelerated GDPR enforcement escalation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Webinar Software Market
Software & Services
Global Product Lifecycle Management Software Market
Software & Services
Ecommerce Software and Platform Market
Software & Services
Productivity Management Software Market
Software & Services
Streaming Server Software Market
Software & Services
France HR Payroll Software Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
OCR Scanning Software Market
Software & Services
Global Calendar Scheduling Software Market
Software & Services
Bridge Analysis Software Market
Software & Services
Automotive Hypervisor Market
Software & Services
PCB Design Software Market
Software & Services
Global Ad Server Software Market
Software & Services
Sales Enablement Software Market
Software & Services
Sales Training and Onboarding Software Market
Software & Services
Cloud-Based Payroll Software Market