
 Digital Workplace Market | 2026-2036
Digital Workplace Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Workplace Market Intelligence
GDPR enforcement is broadening the cost-of-entry calculus for digital workplace vendors serving European enterprises. IBM leverages its security-centric platform architecture to sustain enterprise trust in regulated environments. Cognizant anchors its competitive position through deep vertical specialization in financial services compliance workflows. Wipro differentiates via integrated managed services that bundle endpoint governance with cloud migration.
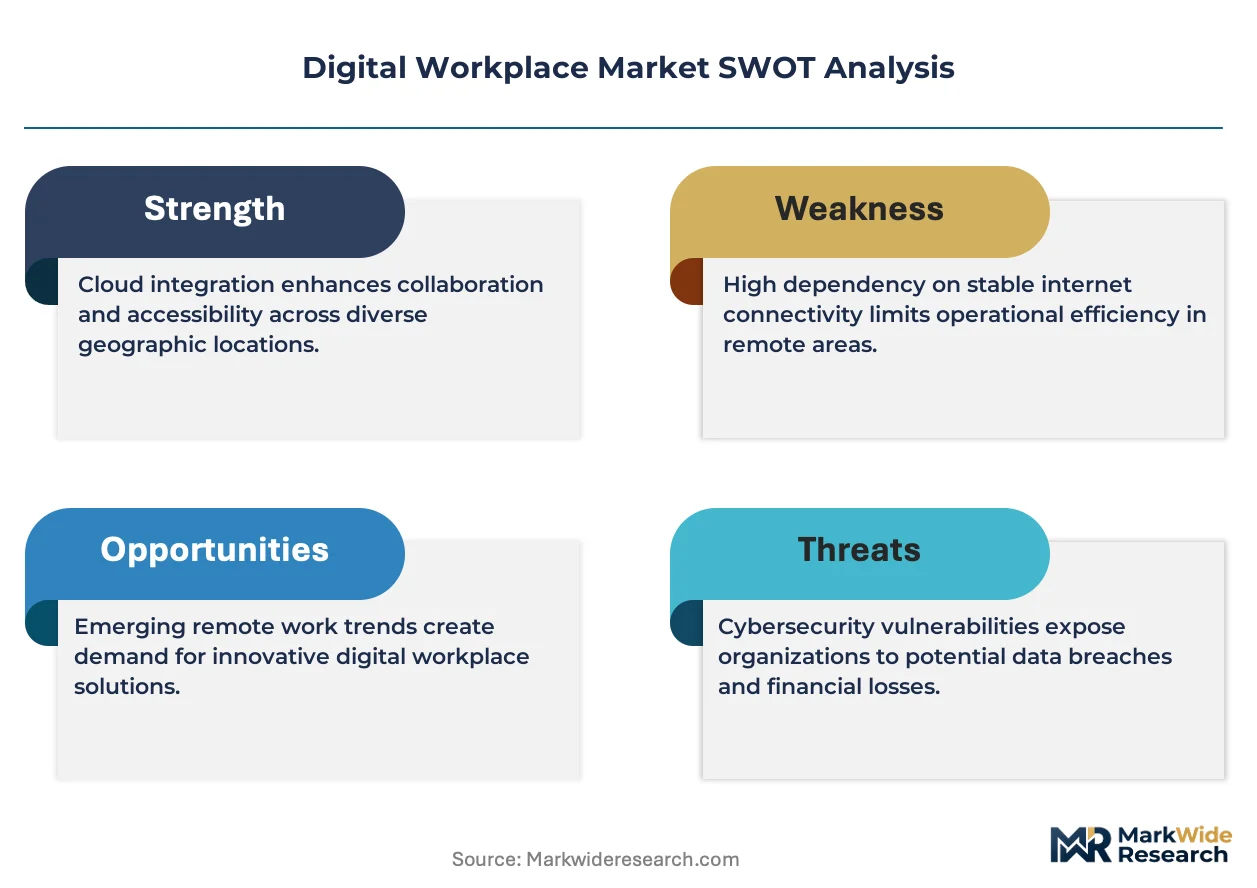
A digital workplace comprises the integrated hardware, software, and network infrastructure that enables employees to perform tasks from any location through secure access to enterprise applications, typically requiring zero-trust architecture with continuous authentication protocols and sub-100-millisecond latency thresholds for real-time collaboration. Its primary purpose is replacing fixed-location productivity models with location-agnostic operational continuity. Cloud-based deployment captures the dominant margin pool as enterprises abandon capital-intensive on-premises refresh cycles. Collaboration Platforms lead solution adoption while Virtual Workspace offerings represent the fastest-expanding segment as GPU-enabled streaming protocols mature. Employee Engagement applications within financial services generate disproportionate vendor profitability due to strict audit-trail requirements.
The EU AI Act, GDPR, and ISO 27001 collectively impose algorithmic transparency, data residency, and information-security benchmarks that filter out uncertified vendors and extend procurement timelines for compliant platforms. India's TRAI guidelines on data localization and the US SEC's cybersecurity disclosure rules add jurisdictional complexity for multinational deployments. Stakeholders must evaluate whether their vendor's certification portfolio spans all operational geographies before committing to multi-year workplace transformation contracts.
Market Dynamics
Zero-trust security architectures are compressing procurement timelines as financial services firms race to meet hybrid-work compliance mandates before EU AI Act certification deadlines. Vendors must now bundle continuous authentication protocols with sub-100-millisecond latency guarantees to remain qualified.
Growth Catalysts
- GPU-Enabled Streaming Protocols:Virtual workspace solutions leverage graphics processing unit acceleration to deliver desktop-as-a-service experiences that match on-premises performance. Financial services traders in Frankfurt and London now demand these capabilities for real-time market data visualization.
- GDPR Article 32 Mandates:European enterprises face escalating fines for inadequate endpoint governance, forcing accelerated replacement of legacy access management systems. Germany's federal data protection authority has issued record penalties to non-compliant workplaces.
- Financial Services Audit-Trail Requirements:Strict documentation protocols for employee communications and document access create durable demand for integrated digital workplace platforms with native compliance logging.
Market Restraints
- Cloud Concentration Risk:Hyperscaler dominance in Western European infrastructure creates single-point-of-failure exposure for multi-tenant workplace platforms dependent on AWS, Azure, or Google Cloud regions.
- EU AI Act Certification Friction:Algorithmic transparency requirements for AI-powered collaboration tools extend vendor approval cycles by 12-18 months, freezing procurement decisions for risk-averse enterprises.
- Legacy ERP Integration Costs:Custom middleware development to connect modern zero-trust gateways with decades-old SAP and Oracle systems consumes 40-60% of implementation budgets for industrial conglomerates.
Strategic Opportunities
- India's TRAI Data Localization:Mandated in-country storage for enterprise communications creates opening for domestic cloud providers to capture workplace transformation contracts from multinational subsidiaries operating in Mumbai and Bangalore.
- ISO 27001 Convergence:Information security certification is becoming table stakes for vendor shortlists, allowing certified specialists to displace generalist IT service providers in regulated verticals.
- Employee Engagement Analytics:Sentiment analysis and productivity measurement tools represent underexploited attach-rate potential for platforms already deployed at financial institutions with strict supervisory requirements.
Industry Challenges
- Zero-Trust Architecture Skills Gap:Shortage of engineers certified in continuous authentication protocol implementation delays enterprise rollouts and inflates professional services costs.
- Multi-Jurisdiction Compliance Stacking:Vendors must simultaneously satisfy GDPR, EU AI Act, India's TRAI guidelines, and US SEC cybersecurity disclosure rules, fragmenting product roadmaps and engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Workplace Market |
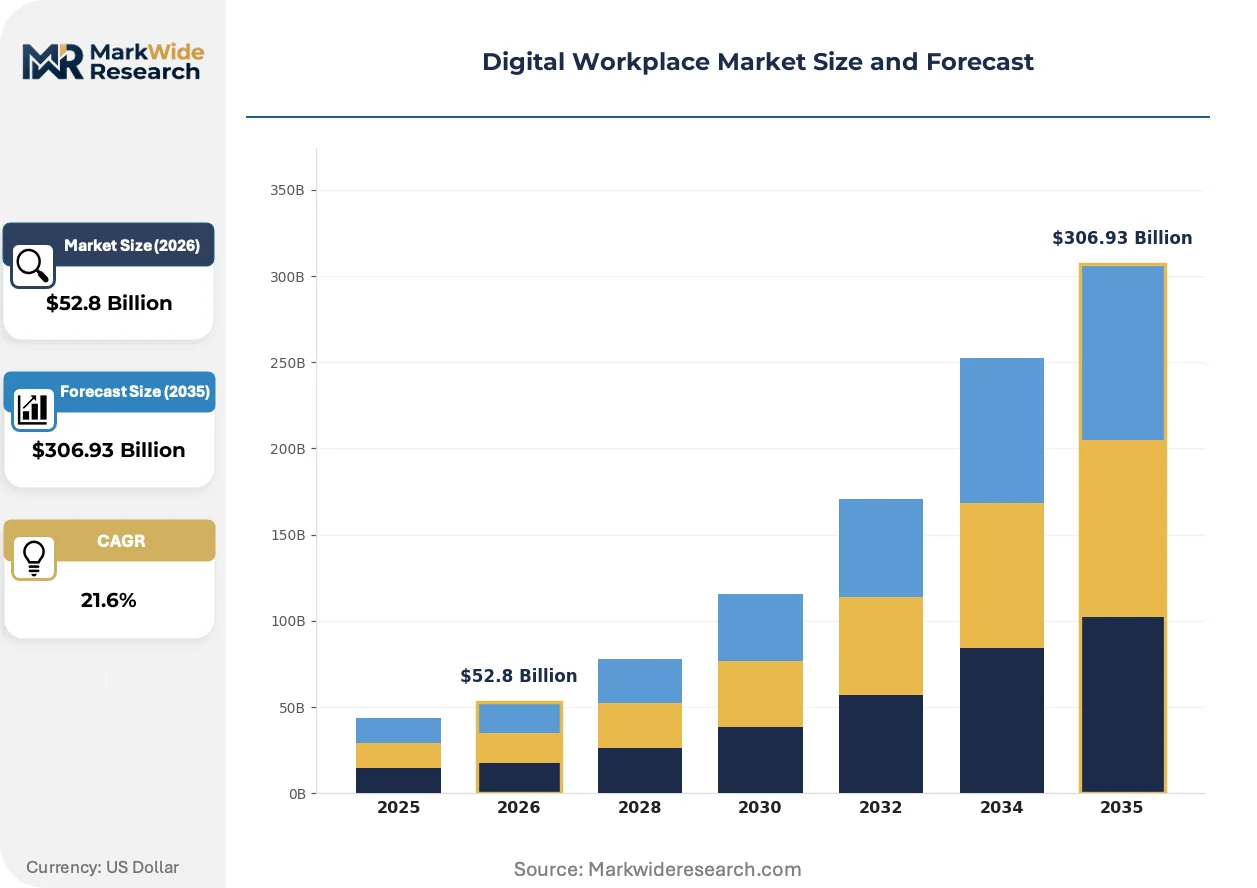
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $306.93 Billion |
| CAGR (2026 – 2036) | 21.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Collaboration Platforms, Digital Experience Monitoring, Virtual Workspace, Content Management, Unified Communications, Identity Management Deployment Type: Cloud-Based, On-Premises, Hybrid, Managed Services, SaaS End User Industry: Financial Services, Information Technology, Manufacturing, Education, Government, Telecommunications Application: Remote Work, Business Process Automation, Employee Engagement, Knowledge Management, Project Management, Training & Development |
| Companies Covered | Atos, Cognizant, IBM, Wipro, TCS, Capgemini, HCL Technologies, Fujitsu, Infosys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Workplace Market Strategic Shifts & Innovations
Secure access service edge frameworks are absorbing standalone virtual private network and firewall markets as enterprises consolidate distributed security stacks. This convergence is redrawing competitive boundaries between networking and collaboration vendors.
Secure access service edge architecture is unifying software-defined wide area networking, cloud access security brokers, and zero-trust network access into single-vendor deployments. Mid-market financial services firms in Germany and the Netherlands are adopting these consolidated stacks fastest. This unification is compressing procurement cycles from multi-year best-of-breed evaluations to single-source decisions.
The EU AI Act's risk-based classification system for algorithmic workplace tools is forcing vendors to document training data provenance and decision logic. High-risk applications including biometric authentication and emotion recognition now require conformity assessments before market entry. Collaboration platform providers serving French and German banking clients are restructuring product development to pre-certify features.
Enterprise buying committees are demanding consumption-based pricing tied to monthly active users rather than perpetual seat licenses. This shift is displacing upfront capital expenditure models that dominated pre-pandemic procurement. US-headquartered technology and professional services firms are piloting these arrangements most aggressively, pressuring vendors to restructure revenue recognition.
Digital Workplace Market Segmentation
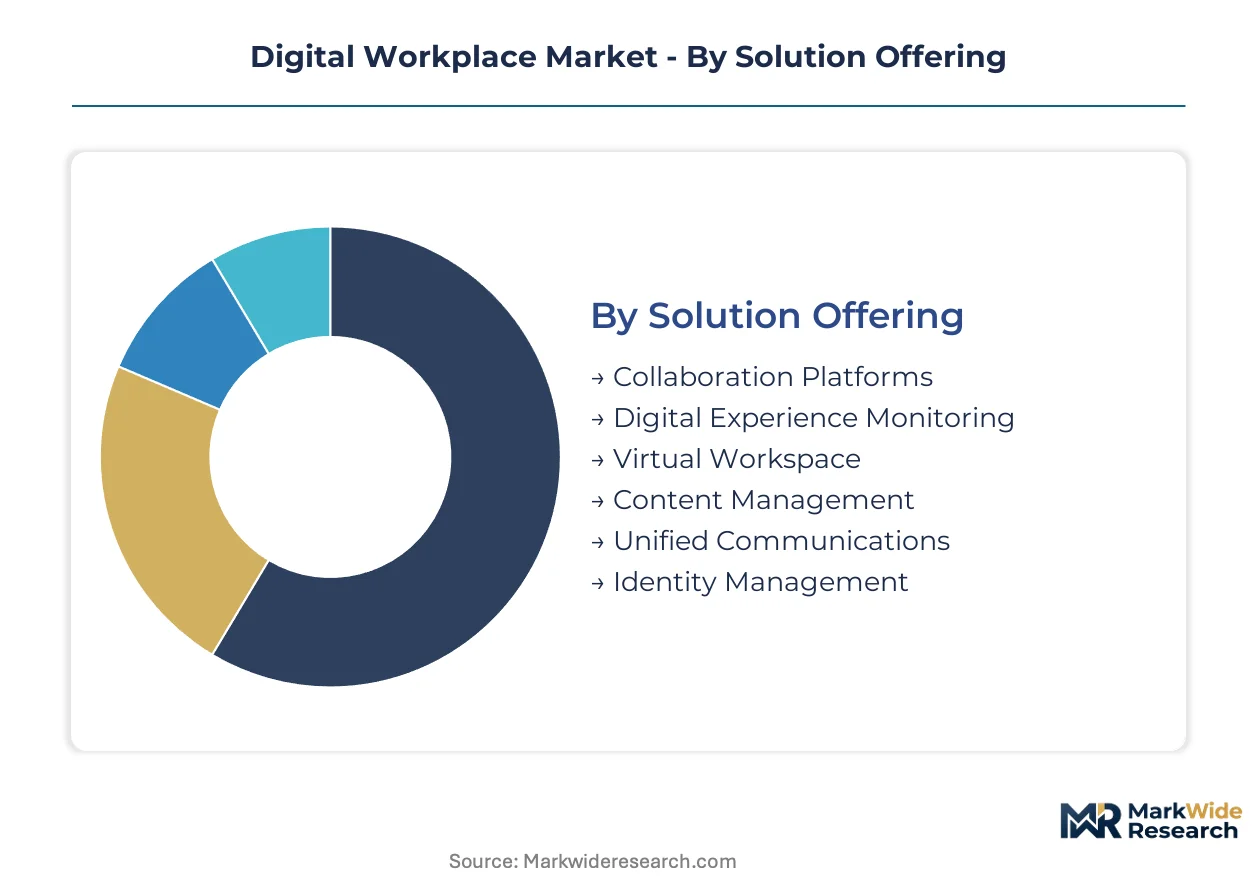
Segmentation in the digital workplace market reveals how procurement priorities diverge across technical architectures, regulatory exposure, and workforce distribution models. Vendors must align solution packaging with specific compliance burdens and latency requirements rather than pursuing horizontal universalism.
Solution Offering:
Standardized collaboration tools anchor volume sales while specialized monitoring and virtualized infrastructure command premium pricing through technical differentiation.
- Collaboration Platforms:Integrated messaging, video conferencing, and document co-editing suites form the foundational layer of enterprise digital workplace stacks. Financial services firms in Frankfurt and London drive demand for real-time market data collaboration with sub-100-millisecond synchronization requirements.
- Virtual Workspace:GPU-accelerated desktop-as-a-service delivery matches on-premises performance for graphics-intensive applications. Traders and quantitative analysts in banking clusters now mandate these capabilities for remote access to proprietary visualization tools.
- Digital Experience Monitoring:Real-time telemetry on application performance and user behavior enables proactive IT intervention.
- Content Management:Document lifecycle governance with version control and audit trails satisfies regulatory documentation mandates.
- Unified Communications:Voice, video, and messaging convergence reduces vendor fragmentation for mid-market enterprises.
- Identity Management:Continuous authentication protocols enforce zero-trust access policies across distributed endpoints.
Leading the category by volume: Collaboration Platforms. Expanding most quickly: Virtual Workspace.
Deployment Type:
Capital structure preferences and data residency obligations determine whether enterprises absorb infrastructure risk or transfer it to managed service providers.
- Cloud-Based:Hyperscaler-hosted platforms eliminate capital refresh cycles while introducing concentration risk in AWS, Azure, or Google Cloud regions. Germany's federal data protection authority has intensified scrutiny of cross-border data flows, complicating pure-cloud strategies for regulated entities.
- Managed Services:Bundled endpoint governance with professional support addresses skills gaps in zero-trust architecture implementation. Industrial conglomerates in the Ruhr Valley favor this model to offset legacy ERP integration complexity.
- On-Premises:Air-gapped infrastructure persists where classified or critical operational technology demands physical control.
- Hybrid:Selective cloud burst capacity supplements retained on-premises core systems for workload flexibility.
- SaaS:Consumption-based pricing tied to monthly active users displaces perpetual licensing in professional services sectors.
Cloud-Based deployments dominate current contract value. Managed Services is gaining share fastest among risk-averse regulated verticals.
End User Industry:
Regulatory intensity and workforce mobility requirements create divergent technology specifications across vertical procurement committees.
- Financial Services:Strict audit-trail mandates for employee communications and document access create durable demand for integrated platforms with native compliance logging. EU AI Act certification deadlines are compressing procurement timelines for algorithmic workplace tools in Paris and Frankfurt banking headquarters.
- Information Technology:Early adoption of consumption-based pricing and GPU-enabled streaming protocols establishes technical reference architectures for cross-industry diffusion.
- Manufacturing:Legacy ERP integration costs consume disproportionate implementation budgets as industrial conglomerates connect modern zero-trust gateways to decades-old SAP systems.
- Government:Sovereign cloud requirements and classified information handling restrict vendor eligibility to domestically certified providers.
- Education:Cost sensitivity and dispersed user bases favor lightweight collaboration tools over comprehensive platform investments.
- Telecommunications:Network operator expertise in latency optimization creates internal development alternatives to commercial virtual workspace offerings.
Financial Services generates the highest vendor profitability per seat. Information Technology provides the steepest expansion trajectory for emerging protocol adoption.
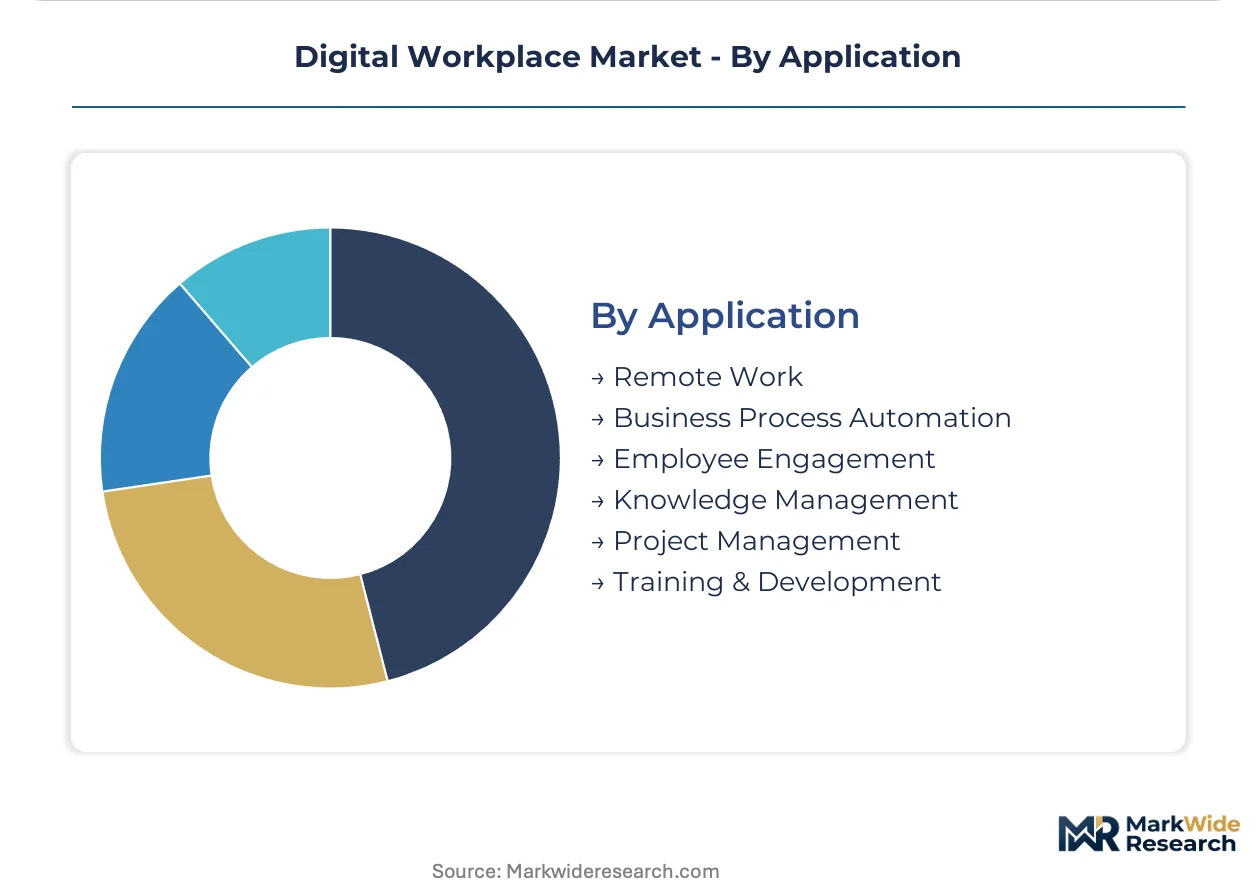
Application:
Functional use cases determine whether deployments prioritize real-time performance, automation throughput, or longitudinal data capture.
- Remote Work:Location-agnostic operational continuity requires zero-trust architecture with continuous authentication and sub-100-millisecond latency thresholds. GDPR Article 32 enforcement on endpoint governance accelerates system replacement across European enterprises.
- Employee Engagement:Sentiment analysis and productivity measurement tools attach to existing platforms in financial institutions with strict supervisory requirements. This application generates disproportionate vendor profitability through analytics upsell.
- Business Process Automation:Workflow orchestration reduces manual handoffs in document-intensive administrative functions.
- Knowledge Management:Institutional memory preservation and expertise location address workforce turnover challenges.
- Project Management:Task coordination and resource allocation tools compete with standalone SaaS offerings in less regulated sectors.
- Training & Development:Virtual classroom delivery and competency tracking support distributed workforce upskilling mandates.
Remote Work anchors deployment scale. Employee Engagement analytics is climbing the fastest as attach-rate potential materializes in regulated verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr Valley special economic zones and India's Software Technology Parks of India scheme concentrate digital workplace demand through tax-advantaged infrastructure investments. Financial services compliance mandates and data localization requirements reshape vendor qualification criteria across these jurisdictions.
United States
SEC cybersecurity disclosure rules and hybrid-work mandates from New York and San Francisco banking headquarters accelerate zero-trust procurement. The Sarbanes-Oxley Act's internal control requirements extend to digital workplace audit trails. Manhattan's financial district generates concentrated demand for sub-100-millisecond latency collaboration platforms among trading operations.
Germany
GDPR Article 32 enforcement and EU AI Act certification deadlines compress procurement timelines for Frankfurt banking consortia. The federal data protection authority's record penalties on endpoint governance violations force legacy system replacement. Munich and Frankfurt clusters lead adoption of GPU-enabled virtual workspaces for quantitative analytics teams.
India
TRAI data localization guidelines and RBI's cybersecurity frameworks for financial institutions create domestic cloud provider opportunities. The Software Technology Parks of India scheme incentivizes workplace transformation investments in Mumbai and Bangalore. Hyderabad's Gachibowli technology corridor concentrates managed services demand from multinational subsidiary operations.
United Kingdom
Financial Conduct Authority operational resilience requirements and post-Brexit data adequacy negotiations reshape vendor selection criteria. The UK GDPR maintains alignment with EU enforcement patterns while permitting divergence. London's Canary Wharf banking cluster drives demand for integrated compliance logging in collaboration platforms.
Japan
METI's Society 5.0 digitization targets and amended Personal Information Protection Act obligations accelerate workplace modernization. Financial Services Agency guidelines on operational continuity mandate redundant infrastructure for systemically important institutions. Tokyo's Marunouchi financial district concentrates demand for secure remote access to legacy mainframe systems.
Digital Workplace Market Key Industry Players
US-headquartered technology conglomerates anchor the premium platform tier; Indian IT services specialists hold the managed services integration tier. The vendor base organizes around three strategic archetypes: security-centric platform architects, vertical compliance workflow specialists, and bundled endpoint governance providers. Consolidation pressure intensifies as zero-trust certification requirements filter out uncertified competitors. Strategic moves center on ISO 27001 certification stacking and SASE framework convergence partnerships.
Within the security-centric platform tier, IBM exemplifies architecture-driven positioning for regulated European environments. Cognizant and Wipro occupy complementary positions among compliance workflow specialists and integrated managed services providers respectively. These three anchors represent divergent approaches to multi-jurisdiction certification burdens—platform depth versus vertical specialization versus service bundling.
| Leading Market Players |
|---|
| Atos |
| Cognizant |
| IBM |
| Wipro |
| TCS |
| Capgemini |
| HCL Technologies |
| Fujitsu |
| Infosys |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up managed services specialists now anchor mid-market pricing discipline, compressing margins for pure-play platform vendors while consolidating procurement leverage across fragmented European enterprise accounts. Their bundled endpoint governance offerings tether pricing power to ISO 27001 certification depth, forcing competitors to absorb compliance engineering costs or retreat to lower-margin SaaS tiers.
Pricing Analysis
Short lead-time premiums now separate qualified vendors from spot-market alternatives, with EU AI Act certification delays extending procurement cycles and inflating urgency pricing for pre-certified platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by zero-trust architecture maturity and GDPR audit-trail granularity. Cost compression in the standard tier intensifies because hyperscaler resale agreements commoditize baseline collaboration features. Mid-market financial services firms in Germany exhibit the sharpest price sensitivity, while Frankfurt banking headquarters pay premiums for sub-100-millisecond latency guarantees.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based GPU foundries supplying graphics acceleration hardware for virtual workspace streaming protocols. Hyperscaler infrastructure in Ireland, Germany, and the Netherlands dominates cloud-based deployment capacity, drawing from concentrated data center construction pipelines. NVIDIA A100 and H100 chip dependencies, alongside specialized encryption hardware modules, create procurement bottlenecks for zero-trust gateway vendors. Tariff exposure on Chinese-manufactured networking equipment fragments supply security strategies. Distribution runs through direct enterprise sales teams for large accounts and certified systems integrators for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over zero-trust certification workflows determines margin capture, with upstream leverage residing in managed services bundling and downstream leverage in direct hyperscaler partnerships.
For Market Incumbents: Hedge against SASE framework convergence by acquiring niche continuous-authentication specialists before networking vendors absorb their functionality. Lock in multi-year managed services contracts with Germany's federal data protection authority-mandated compliance refresh cycles. Capacity addition in Mumbai and Bangalore addresses India's TRAI data localization requirements while capturing multinational subsidiary demand.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in employee engagement analytics offers white-space entry for API-first sentiment analysis tools that attach to incumbent collaboration platforms. India's domestic cloud provider ecosystem remains the most penetrable geography, with Software Technology Parks of India incentives lowering customer acquisition costs. A compliance-co-sell go-to-market angle partners with ISO 27001 auditors to bypass lengthy enterprise procurement committees.
For Investors and Strategic Acquirers: Distressed-cycle entries favor managed services specialists with pre-built GDPR Article 32 compliance modules in the United Kingdom post-Brexit regulatory divergence. Long-term viability across the analysis window hinges on EU AI Act certification portfolio breadth rather than feature velocity. The signal to watch is Germany's federal data protection authority penalty velocity accelerating legacy system replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Certification Pre-Loading | EU AI Act conformity assessments now gate market entry for biometric authentication features in French banking deployments. |
| SASE Framework Partnership | Secure access service edge convergence redraws boundaries between IBM's networking alliances and standalone collaboration vendors. |
| Managed Services Bundling | Wipro's integrated endpoint governance model captures Ruhr Valley industrial conglomerates facing legacy ERP integration complexity. |
| GPU-Accelerated Virtual Workspace Expansion | NVIDIA streaming protocol partnerships enable Frankfurt quantitative analysts to access proprietary visualization tools remotely. |
| India Domestic Cloud Infrastructure | TRAI data localization compliance creates captive demand for Mumbai-based providers serving multinational subsidiary operations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with chief information security officers, enterprise procurement leads, zero-trust architecture engineers, and managed services delivery heads. SEC cybersecurity disclosure filings, EU AI Act implementation guidance, Germany's federal data protection authority enforcement bulletins, and India's TRAI spectrum allocation records provided validation anchors. Bottom-up deployment sizing across cloud, managed services, and hybrid architectures triangulated against top-down IT services market aggregates from technology advisory consortiums.
Granularity-level modeling segmented the digital workplace market by solution offering, deployment type, end-user industry, and application use case, with regional regulatory cluster intensity as an overlay dimension. CAGR derivation incorporated technology diffusion curves for GPU-enabled streaming protocols and compliance-driven replacement cycles for legacy access management systems. Workforce mobility indices and financial services audit-trail mandate enforcement velocity served as industry-specific forecast inputs across the projection horizon.
Underlying measurement precision varies by segment; cloud-based deployment and collaboration platform volumes carry tighter precision than emerging virtual workspace GPU-acceleration demand. Forecasts reflect documented assumptions around EU AI Act certification timeline adherence and GDPR Article 32 enforcement continuity, with outcomes best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Middle East Smart Card Market
Digital Solutions
AI Marketing Tool Market
Digital Solutions
North America Data Virtualization Market
Digital Solutions
Container Orchestration Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
E-Ink E-Reader Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
Next Generation Search Engines Market
Digital Solutions
US Supply Chain Management Software Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Digital Commerce Platform Market
Digital Solutions
Global Capacity Management Market
Digital Solutions
Global Software Defined Everything (SDE) Market
Digital Solutions
Japan E-Invoicing Market