
 Enterprise MLC (Emlc) Market | 2026-2036
Enterprise MLC (Emlc) Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise MLC (Emlc) Market Foresight
OEM direct procurement is fragmenting as hyperscale buyers diversify supplier rosters and second-source requirements harden. Samsung Electronics leverages captive NAND fabrication to sustain cost leadership across enterprise SSD lines. SK Hynix anchors supply through advanced 176-layer process nodes that tighten performance consistency. Micron Technology competes on vertical integration from wafer to module, controlling quality gates that enterprise buyers demand.
Enterprise MLC (Emlc) denotes multi-level cell NAND flash memory engineered for commercial workloads, typically rated for 10,000 to 30,000 program/erase cycles with enhanced error-correction and power-loss protection circuitry. These modules serve as primary storage in servers, storage arrays, and edge devices where read-intensive and mixed-use patterns dominate. The Solution Type dimension shows Hybrid deployments capturing margin pools as enterprises balance latency requirements against cloud elasticity. Deployment Model segmentation reveals Edge Computing as the fastest-expanding category, driven by factory-floor analytics and autonomous system data pipelines.
FCC equipment authorization rules shape electromagnetic compatibility standards for storage modules deployed in US infrastructure, while REACH compliance in Europe restricts hazardous substances in semiconductor packaging materials. China's GB standards and MIIT certification requirements create discrete market access barriers for imported modules. Stakeholders must monitor how divergent data-sovereignty regimes reshape local content requirements and supplier qualification timelines.
Market Dynamics
Hyperscale cloud operators are consolidating procurement authority while fragmenting supplier rosters, forcing NAND vendors to absorb volume volatility without guaranteed allocation commitments. This structural tension between buyer concentration and supply-base diversification defines current competitive pressure.
Growth Catalysts
- China MIIT data-localization mandates:On-premises storage architectures gain regulatory preference, expanding demand for high-endurance enterprise modules in domestic data centers.
- Factory-floor analytics proliferation:Edge Computing deployments require localized flash storage with power-loss protection, driving module specifications toward industrial-grade endurance ratings.
- 176-layer process node maturity:Advanced 3D NAND fabrication tightens performance consistency, enabling broader qualification across mission-critical server workloads.
Market Restraints
- Wafer input cost volatility:Silicon substrate and specialty gas prices fluctuate with energy markets, compressing gross margins for non-captive fabricators.
- Geographic supply concentration:Advanced NAND fabrication clusters in South Korea and Taiwan create single-source exposure for module assemblers elsewhere.
- QLC substitution pressure:Quad-level cell technology encroaches on read-intensive workloads, threatening EMLC volume in secondary storage tiers.
Strategic Opportunities
- India data center buildout:PLI scheme incentives for electronics manufacturing attract module packaging investments to serve domestic cloud infrastructure.
- Automotive edge storage:Autonomous vehicle data pipelines require NVMe-compliant flash with extended temperature tolerance, opening new qualification pathways.
- EU CSRD reporting requirements:Supply-chain transparency mandates favor vendors with verified conflict-mineral sourcing and carbon-footprint documentation.
Industry Challenges
- Firmware engineering scarcity:Error-correction algorithm development and power-loss protection circuitry design face talent shortages in mature semiconductor markets.
- Multi-regulatory qualification timelines:Concurrent FCC, REACH, and GB standard certification extends product launch cycles by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise MLC (Emlc) Market |
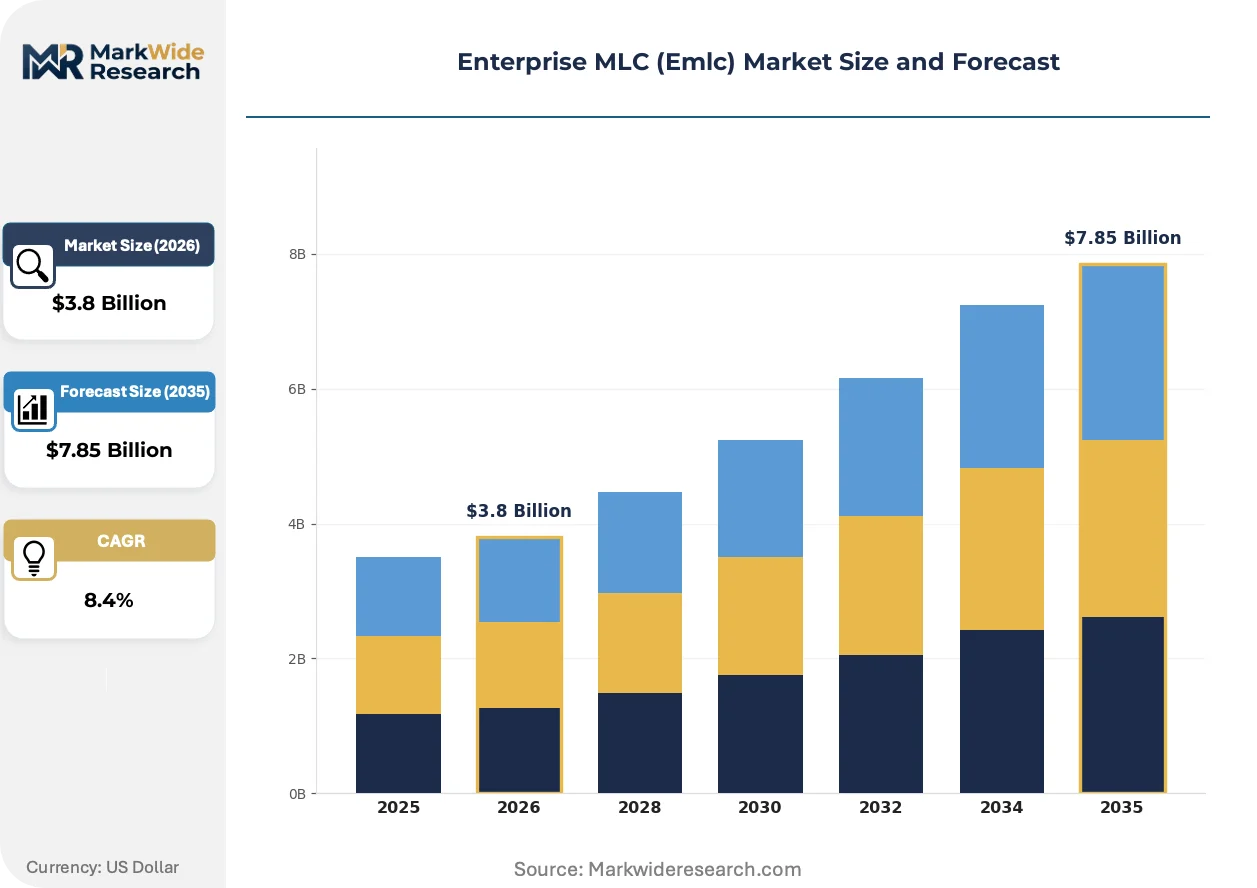
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-Based, On-Premises, Hybrid, Managed Services Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Edge Computing End User: Enterprise, SMB, Government, Non-Profit Service Type: Consulting, Support, Integration, Training |
| Companies Covered | Micron Technology, Samsung Electronics, SK Hynix, Kingston Technology, ADATA Technology, Innodisk Corporation, Apacer Technology, Transcend Information, Western Digital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise MLC (Emlc) Market Shifts & Advancements
Storage-class memory hierarchies are restructuring as latency requirements collide with cost constraints, forcing architectural decisions that favor hybrid deployments. Vendors respond with firmware-defined endurance management and modular form-factor flexibility.
Controller firmware is migrating from fixed wear-leveling algorithms toward machine-learning-based predictive degradation modeling. Hyperscale operators deploy these adaptive modules in mixed-use server tiers, compressing the performance gap between consumer and enterprise NAND categories. The technology is migrating from premium storage arrays into mainstream rack servers.
REACH substance restrictions in Europe now cover additional flame-retardant compounds in PCB substrates, forcing laminate supplier transitions. Module packagers must requalify thermal interface materials and solder mask formulations, extending engineering validation cycles. Enterprise SSD product lines face the tightest compliance deadlines given their higher material complexity.
Hyperscale buyers now unbundle drive procurement from server OEM chassis contracts, establishing direct relationships with NAND module vendors. Channel distributors lose margin capture on high-volume transactions as second-source requirements harden. This disintermediation concentrates most visibly in United States cloud regions where procurement teams maintain dedicated supplier engineering staff.
Enterprise MLC (Emlc) Market Segmentation
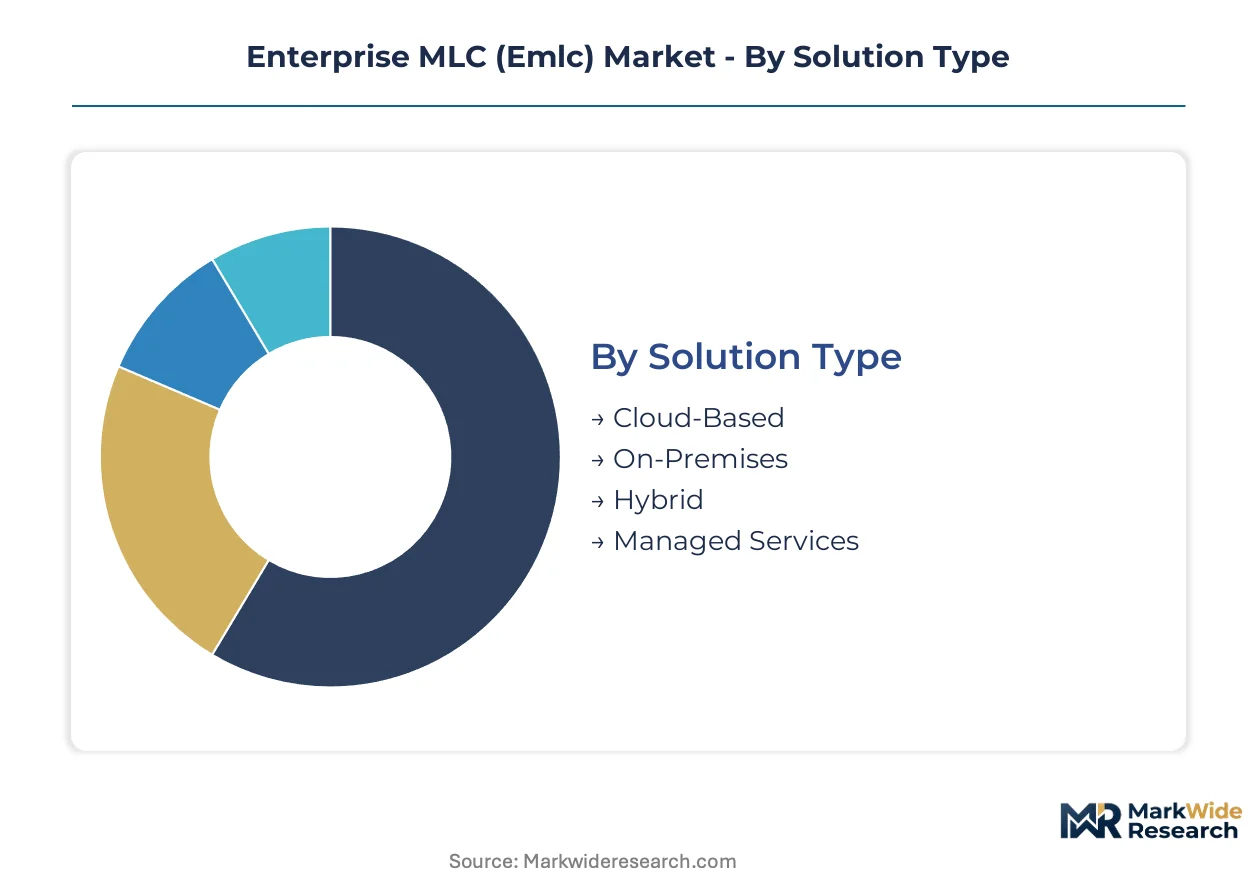
Enterprise MLC procurement cycles vary dramatically across deployment configurations, with edge installations refreshing every 18-24 months while on-premises arrays extend to 5-year cycles. Understanding these velocity differentials helps suppliers calibrate inventory exposure and firmware support timelines.
Solution Type:
Cloud-based deployments turn over fastest as hyperscale operators refresh infrastructure continuously, while managed services contracts lock in longer procurement horizons.
- Cloud-Based:Hyperscale operators deploy NVMe EMLC modules in direct-attached storage configurations for virtualized compute instances. Procurement concentrates in United States cloud regions where Amazon Web Services and Microsoft Azure drive qualification volumes for high-endurance NAND.
- Hybrid:Enterprises balance latency-sensitive on-premises tiers with cloud burst capacity, creating dual sourcing requirements that complicate supplier consolidation. Financial services firms in Frankfurt and Singapore lead adoption of tiered flash hierarchies spanning colocation facilities and public cloud.
- On-Premises:Dedicated storage arrays in regulated industries favor 3D NAND modules with power-loss protection and hardware encryption. China's MIIT data-localization mandates accelerate domestic procurement for state-owned enterprise data centers.
- Managed Services:Third-party infrastructure operators aggregate demand across mid-market clients, negotiating enterprise-grade SLAs on standardized module specifications.
On-Premises anchors the volume base while Hybrid gains share at the steepest rate.
Deployment Model:
Edge Computing commands premium pricing per gigabyte due to environmental hardening requirements, whereas Public Cloud procurement optimizes strictly for cost per IOPS.
- Edge Computing:Factory-floor analytics and autonomous vehicle data pipelines require industrial-grade temperature tolerance and vibration resistance. German automotive suppliers specify extended-range modules for production line quality systems.
- Multi-Cloud:Enterprises distribute workloads across AWS, Azure, and Google Cloud to avoid vendor lock-in, demanding firmware portability across controller architectures. This fragmentation complicates supplier qualification programs.
- Private Cloud:Single-tenant infrastructure in healthcare and defense sectors prioritizes supply-chain security and domestic assembly verification.
- Public Cloud:Shared infrastructure economics drive procurement toward highest-density QLC-EMLC hybrid configurations with software-defined endurance management.
Public Cloud generates the highest absolute petabyte shipments while Edge Computing expands most quickly.
End User:
Government procurement cycles stretch longest due to budget appropriation timelines, whereas SMB demand responds immediately to NAND spot pricing movements.
- Enterprise:Fortune 500 data centers specify 30,000 program-erase cycle ratings for mixed-use database workloads. Direct procurement teams now bypass channel distributors for high-volume transactions.
- Government:Federal agencies in the United States and ministries in China mandate domestic content verification and conflict-mineral documentation. India's National Informatics Centre drives standardization for state-level data center consolidation.
- SMB:Mid-market buyers rely on server OEM bundled configurations with limited firmware customization options.
- Non-Profit:Grant-funded infrastructure projects prioritize upfront cost minimization over endurance specifications.
Enterprise dominates procurement value while Government exhibits the most rigid qualification barriers.
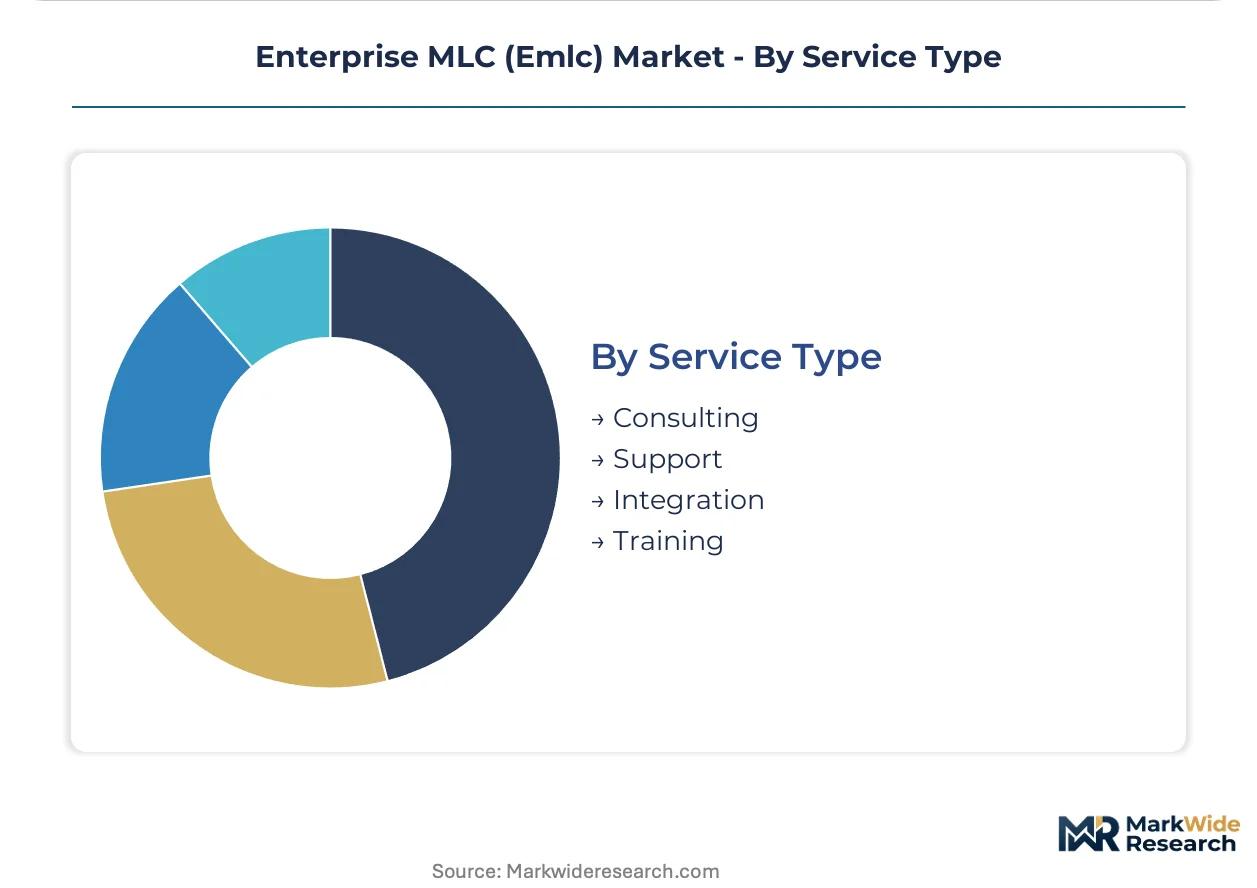
Service Type:
Integration services carry the highest gross margins due to scarce firmware engineering talent, while Training revenue concentrates in initial deployment phases.
- Integration:System architects configure hybrid storage tiers balancing EMLC performance against QLC capacity economics. South Korean system integrators specialize in Samsung and SK Hynix module optimization.
- Consulting:Workload characterization studies identify endurance requirements for database consolidation projects. Japanese trading houses bundle consulting with long-term maintenance contracts.
- Support:24/7 hardware replacement SLAs require regional spare depots and field engineering networks.
- Training:Administrator certification programs cover error-correction monitoring and predictive failure analysis.
Integration commands the highest service margins while Support generates the most recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT data-localization mandates in China are redirecting procurement toward domestic module vendors, while India's PLI scheme for electronics manufacturing attracts packaging investments to serve cloud infrastructure buildouts. These policy instruments reshape regional supply chain configurations faster than pure market forces.
United States
Hyperscale cloud operators in Virginia and Oregon data center clusters drive qualification volumes for high-endurance NAND modules. FCC equipment authorization rules govern electromagnetic compatibility standards for storage modules deployed in federal infrastructure. Seattle and San Jose host dedicated supplier engineering teams that manage direct procurement relationships bypassing traditional channel distributors.
China
State-owned enterprise data centers accelerate procurement of on-premises storage architectures under tightening MIIT certification requirements. GB standards create discrete market access barriers for imported modules, favoring domestic assembly verification. Yangtze River Delta fabrication clusters supply captive NAND to local module packagers serving government and financial services verticals.
South Korea
Advanced 176-layer process node production concentrates in Seoul Capital Area and Busan-Ulsan corridors, tightening performance consistency for mission-critical server workloads. METI-equivalent industrial policy supports memory semiconductor R&D tax credits. Pangyo and Hwaseong host system integrators specializing in Samsung and SK Hynix module optimization for hybrid cloud deployments.
Japan
Trading houses in Tokyo and Osaka bundle consulting services with long-term maintenance contracts for enterprise storage consolidation projects. JIS standards govern industrial-grade temperature tolerance specifications for factory-floor analytics deployments. Nagoya automotive suppliers specify extended-range modules for production line quality systems requiring vibration resistance.
Germany
REACH compliance deadlines for flame-retardant compound restrictions force laminate supplier transitions across Bavaria and Baden-Württemberg manufacturing zones. Frankfurt financial services firms lead adoption of tiered flash hierarchies spanning colocation facilities and public cloud. Berlin-Brandenburg hosts firmware engineering talent pools developing error-correction algorithms for mixed-use database workloads.
Enterprise MLC (Emlc) Market Competitive Landscape
On the supply side, the industry is consolidating around captive NAND fabricators while fragmenting at the module packaging tier. Tier-one memory semiconductor conglomerates control wafer input and controller silicon, forcing independent packagers to compete on firmware customization and regional certification speed. Two strategic archetypes dominate: vertically integrated memory conglomerates with captive fabrication, and specialized module packagers with industrial-grade qualification expertise. Competitive moves center on second-source supplier roster diversification by hyperscale buyers, and concurrent multi-regulatory certification investments to compress product launch cycles.
Among Asia-Pacific-based fabricators, Samsung Electronics, SK Hynix, and Micron Technology exemplify the consolidated tier. Samsung Electronics leverages captive NAND fabrication to sustain cost leadership across enterprise SSD lines. SK Hynix anchors supply through advanced process node maturity that tightens performance consistency. Micron Technology occupies a position emphasizing control over quality gates from wafer to module that enterprise buyers demand. These three conglomerates represent the supply-side concentration that defines procurement dynamics for hyperscale operators.
| Leading Market Players |
|---|
| Micron Technology |
| Samsung Electronics |
| SK Hynix |
| Kingston Technology |
| ADATA Technology |
| Innodisk Corporation |
| Apacer Technology |
| Transcend Information |
| Western Digital |
| Others |
Supply & Pricing Matrix
South Korean captive NAND fabrication clusters concentrate wafer input control, anchoring margin pools in module packaging and firmware customization tiers where non-captive assemblers compete. Hyperscale procurement consolidation extracts volume discounts that compress packager margins while rewarding suppliers with multi-regulatory certification speed.
Pricing Analysis
Volume-discount tiering structures dominate hyperscale direct procurement, with three-tier pricing separating mission-critical 30,000 P/E modules from standard enterprise and read-intensive economy tiers. Price differentiation hinges on endurance certification grade and controller firmware customization depth. Cost compression in economy tiers intensifies because QLC substitution threatens EMLC positioning for secondary storage. SMB buyers exhibit highest price sensitivity, while government and financial services verticals prioritize supply-chain security over unit cost.
Supply Chain Analysis
Extended payment terms from hyperscale buyers force module packagers to rely on supply-chain finance facilities, tightening working capital requirements for non-captive assemblers. Advanced NAND fabrication concentrates in South Korea, Taiwan, and the United States, drawing from silicon wafer substrates, specialty etching gases, and controller ASICs. Single-source vulnerability in 176-layer process node equipment creates qualification bottlenecks. Distribution runs through direct procurement channels for hyperscale operators and OEM bundling for mid-market enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise MLC markets function as service-attach opportunities where integration and support revenue expands faster than hardware shipments. Firmware engineering scarcity elevates recurring service margins above commodity module economics.
For Market Incumbents: Insulate qualification moats by accelerating concurrent FCC, REACH, and GB standard certification to compress product launch cycles. Deepen captive controller silicon development to offset QLC substitution pressure in read-intensive tiers. Vertical integration into firmware-defined endurance management preserves margin pools as hyperscale buyers disintermediate channel distributors.
For New Entrants and Emerging Players: Pursue automotive edge storage qualification pathways where NVMe-compliant modules with extended temperature tolerance face limited incumbent penetration. Target India's data center buildout under PLI scheme incentives, where domestic packaging investments serve cloud infrastructure expansion. Lead with industrial-grade endurance ratings and vibration-resistant form factors to differentiate from hyperscale-optimized commodity supply.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed module packagers holding regional certification expertise but lacking captive NAND supply. Long-term viability across the projection horizon favors targets with verified conflict-mineral sourcing and carbon-footprint documentation aligned to EU CSRD requirements. Monitor QLC-EMLC hybrid configuration adoption rates as the inflection signal for endurance-tier demand elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Regulatory Certification Investment | Concurrent FCC, REACH, and GB qualification compresses launch cycles for hyperscale supplier rosters. |
| Firmware-Defined Endurance Development | Machine-learning-based predictive degradation modeling differentiates premium modules from commodity QLC supply. |
| Automotive Edge Storage Qualification | Extended temperature tolerance modules open new revenue streams in autonomous vehicle data pipelines. |
| India Packaging Footprint Expansion | PLI scheme incentives attract module assembly investments serving domestic cloud infrastructure buildout. |
| Supply-Chain Transparency Documentation | Verified conflict-mineral sourcing meets EU CSRD mandates and accelerates government procurement approval. |
Research Methodology
A standing panel of NAND procurement directors at hyperscale operators, storage array product managers, and firmware engineering leads provided ongoing calibration across the study period. Primary interviews with module packaging executives, system integrators specializing in Samsung and SK Hynix optimization, and regulatory compliance officers at semiconductor distributors combined with secondary validation from SEC filings, MIIT certification databases, and hyperscaler capex disclosures. Bottom-up shipment data and top-down wafer input analysis triangulate market sizing across the analysis window.
Scenario-bracketing framed the projection horizon, with demand elasticity tested against QLC substitution velocity and data-localization mandate enforcement intensity. Segmentation dimensions modeled include solution type, deployment model, end user vertical, and service attach rate. CAGRs derive from regression analysis of historical procurement cycles and forward-looking qualification pipeline visibility. Forecast inputs incorporate 176-layer process node yield trajectories and edge computing refresh velocity differentials.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or energy market volatility would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timelines and technology substitution elasticities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Office Software Market
Software & Services
Partner Ecosystem Platform Software Market
Software & Services
Content Curation Software Market
Software & Services
Inventory Management Software Market
Software & Services
B2B Gateway Software Market
Software & Services
Real Estate Software Market
Software & Services
SMS Marketing Software Market
Software & Services
Information Technology Service Management (ITSM) Market
Software & Services
Webcasting Software Market
Software & Services
Global Neural Network Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Online Lottery Software Market
Software & Services
Global Text to Speech (TTS) Software Market
Software & Services
Channel Management Software Market
Software & Services
Global Contract Management Software Market
Software & Services
Laser Engraving Software Market