
 Global Claims Processing Software Market | 2026-2036
Global Claims Processing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Claims Processing Software Market Foresight
Legacy COBOL-based infrastructure is shifting toward cloud-native microservices architectures across the insurance technology stack. Guidewire Software leverages its vertically integrated platform to anchor property and casualty workflows across North America. SAP competes through deep ERP connectivity that extends claims data into broader enterprise resource planning. Oracle dominates in data-intensive environments where its database technology sustains high-volume transactional throughput.
Claims processing software encompasses the integrated application suites that automate intake, adjudication, payment, and recovery workflows for insurance and related financial institutions, typically incorporating rules engines, document management, and API connectivity to third-party data sources. Cloud-based deployments now lead product type segmentation as carriers abandon capital-intensive on-premises data centers, while workflow automation functionality captures the fastest expansion within the functionality dimension due to labor cost pressures and straight-through processing targets. Third-party administrators represent a growing end-user segment as insurers outsource non-core claims operations to specialized service providers.
FDA oversight of software-as-medical-device intersects with health claims processing, while HIPAA mandates govern protected health information flows within healthcare claims platforms. The EU AI Act imposes risk-classification requirements on automated decision systems used in European insurance claims adjudication, shaping product development priorities for vendors serving EEA carriers. Stakeholders must monitor how divergent regulatory timelines for AI governance across the United States, European Union, and Japan will fragment compliance roadmaps and strain engineering resources.
Market Dynamics
Cloud-native microservices architectures are systematically dismantling COBOL-based legacy stacks as property and casualty insurers face simultaneous pressure from regulatory mandates for faster claim resolution and the operational impossibility of maintaining aging mainframe infrastructure.
Growth Catalysts
- EU AI Act risk-classification mandates:European carriers must deploy auditable automated decision systems, forcing modernization of adjudication engines to meet compliance deadlines.
- Third-party administrator outsourcing surge:Insurers shedding non-core claims operations create dedicated demand for multi-tenant SaaS platforms with API-native interoperability.
- Straight-through processing targets:Labor cost pressures in the United States and Japan are accelerating workflow automation adoption for routine property and casualty claims.
Market Restraints
- Legacy system integration tax:Data migration from mainframe environments to cloud architectures consumes 40-60% of implementation budgets and extends deployment timelines.
- Specialized talent scarcity:COBOL expertise is retiring faster than cloud-native engineering capacity scales, creating bidirectional skills gaps.
- Cybersecurity liability exposure:Centralized cloud platforms concentrate breach risk, with HIPAA and GDPR penalties amplifying carrier reluctance to migrate sensitive health claims data.
Strategic Opportunities
- Underpenetrated German Mittelstand insurers:Mid-tier carriers lagging behind large peers in automation present a concentrated upgrade opportunity for modular, API-first platforms.
- Embedded insurance convergence:IoT-enabled real-time claims triggers from connected vehicles and smart property devices demand event-driven architecture capabilities.
- Japan's Fintech Sandbox accelerants:METI regulatory forbearance for AI-powered claims adjudication pilots lowers entry barriers for experimental deployment models.
Industry Challenges
- Data sovereignty fragmentation:Divergent cloud residency requirements across the United States, EU, and Japan force multi-region infrastructure replication that strains engineering resources.
- Interoperability standardization gaps:Absence of universal claims data exchange protocols between carriers, TPAs, and repair networks perpetuates manual handoff points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Claims Processing Software Market |
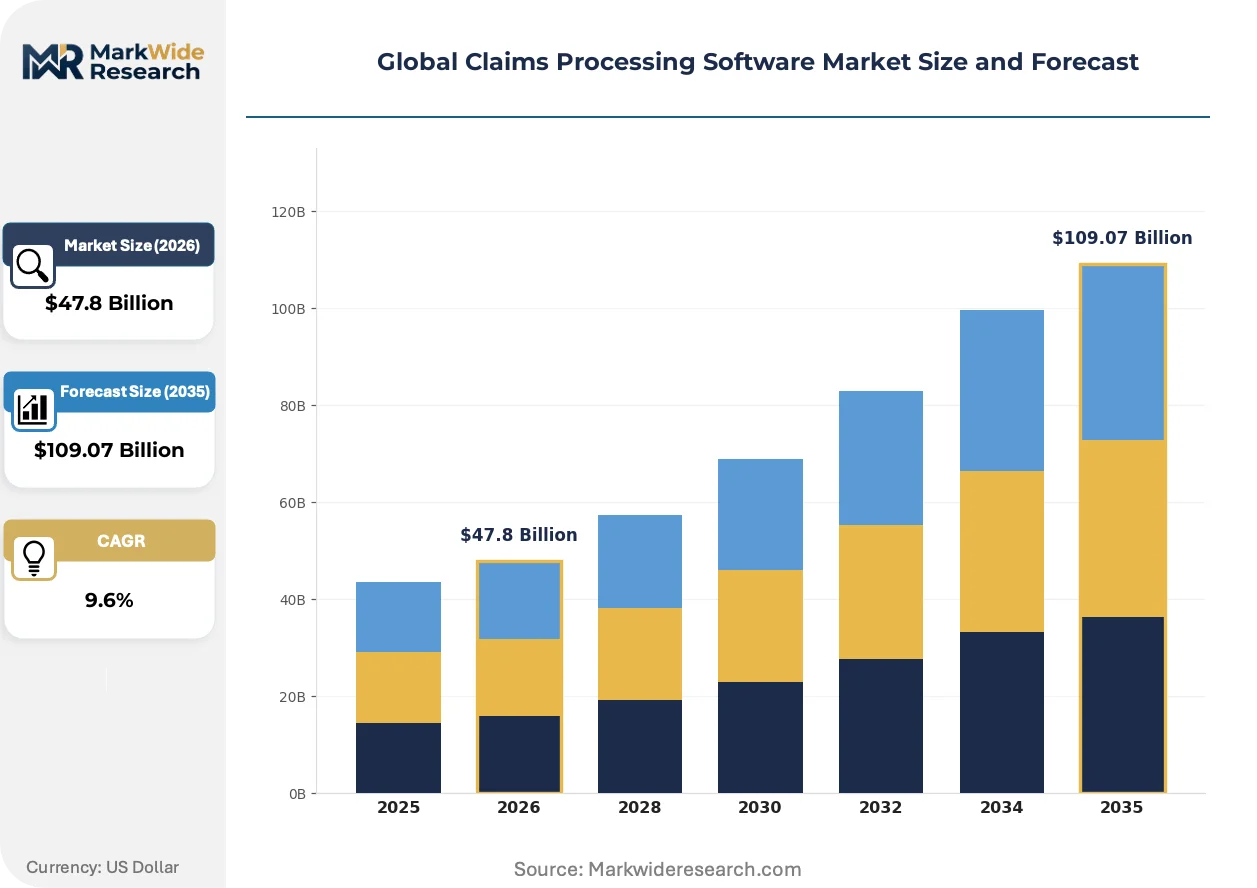
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $109.07 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premises, Cloud-Based, Hybrid, Open Source End User: Insurance Companies, Third-Party Administrators, Healthcare Providers, Financial Institutions Deployment: Public Cloud, Private Cloud, Managed Services, Self-Hosted Functionality: Fraud Detection, Claims Management, Workflow Automation, Reporting & Analytics |
| Companies Covered | Guidewire Software, Oracle, SAP, Cognizant, Duck Creek Technologies, Verisk Analytics, Pegasystems, BriteCore, ClaimVantage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Claims Processing Software Market Shifts & Advancements
Claims processing technology is pivoting from record-keeping systems to real-time decision engines, with artificial intelligence, embedded connectivity, and outcome-based commercial models converging to redefine carrier-vendor relationships and operational economics.
Generative AI is electrifying claims intake and fraud detection workflows by extracting structured data from unstructured documents and flagging anomalies across historical pattern libraries. Mid-size property and casualty carriers in the United States are piloting these capabilities most aggressively, compressing initial reserve-setting cycles from days to hours. The technology is electrifying competitive positioning by decoupling processing speed from headcount scaling.
The EU AI Act's risk-tier classification system for automated decision-making is forcing European insurers to retrofit algorithmic transparency and human-in-the-loop requirements into existing adjudication engines. Vendors serving EEA markets must now document training data provenance and model drift monitoring protocols as standard product features. German and French carriers face the steepest compliance curves given their early automation investments in opaque legacy rule engines.
Outcome-based pricing models are displacing traditional seat-license arrangements as carriers demand vendor accountability for claim cycle time and accuracy metrics. Third-party administrators in Japan and the United States are leading this commercial restructuring, tying platform fees to measurable operational improvements rather than software availability. This shift concentrates vendor risk while aligning implementation incentives with carrier performance targets.
Global Claims Processing Software Market Segmentation
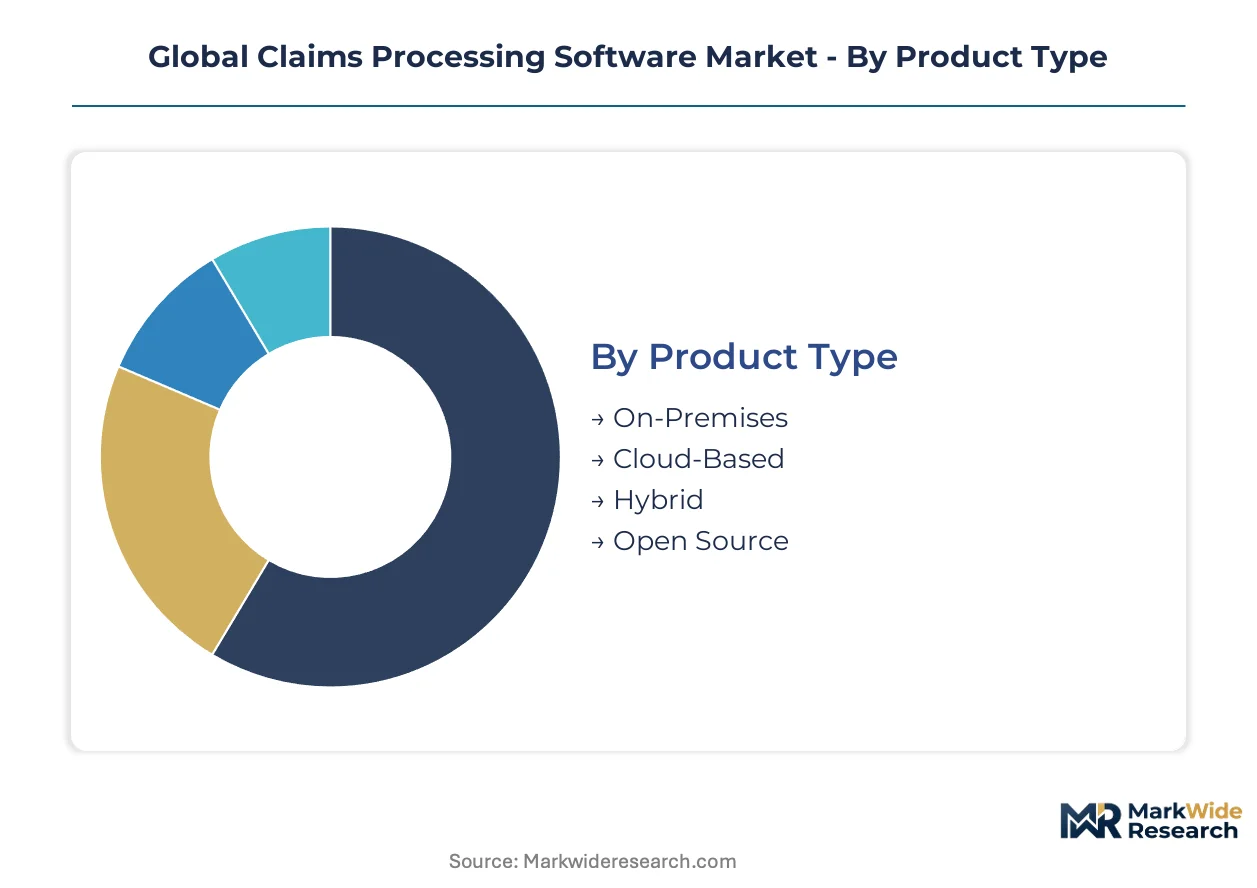
Segmentation in claims processing software reveals how capital allocation, compliance burdens, and operational complexity fragment purchasing decisions across carrier types and technology architectures. Procurement patterns diverge sharply between legacy-dependent insurers and cloud-native entrants.
Product Type:
Cloud-based deployments demand the lowest upfront capital outlay, while on-premises installations require substantial data center investment and specialized infrastructure teams.
- On-Premises:Deployed within carrier-owned data centers with dedicated hardware stacks. Large property and casualty insurers in the United States and Germany maintain these installations for regulatory control over sensitive claimant data, though maintenance costs escalate as COBOL expertise retires.
- Cloud-Based:Delivered via multi-tenant SaaS architectures with subscription pricing. Mid-tier carriers across Japan and the United States are migrating here fastest to escape mainframe dependency and accelerate straight-through processing targets.
- Hybrid:Combines on-premises core systems with cloud-native extensions for specific workflows. Appeals to carriers with mixed regulatory requirements across jurisdictions.
- Open Source:Community-developed platforms with customizable codebases. Niche adoption among specialized mutual insurers with internal engineering capacity.
Most installed capacity flows through On-Premises. Expansion is steepest in Cloud-Based.
End User:
Third-party administrators operate on thinner margins than primary carriers, driving demand for modular, API-first platforms that minimize implementation overhead.
- Insurance Companies:Primary carriers underwriting risk and managing claims lifecycle. Property and casualty specialists in the United States, Germany, and Japan dominate procurement volumes as they modernize adjudication engines.
- Third-Party Administrators:Outsourced claims service providers handling intake and settlement for insurers shedding non-core operations. United States and Japanese TPAs are expanding fastest as carriers pursue operational flexibility.
- Healthcare Providers:Hospitals and clinic networks processing patient claims against insurers. HIPAA compliance mandates shape platform selection here.
- Financial Institutions:Banks and credit unions with embedded insurance products. Emerging segment as bancassurance models integrate claims workflows into core banking platforms.
Insurance Companies retain the largest installed base. Third-Party Administrators are climbing the fastest.
Deployment:
Public cloud configurations minimize infrastructure ownership, while private deployments preserve data sovereignty for cross-border operations.
- Public Cloud:Shared infrastructure with elastic scaling. Dominant among United States carriers prioritizing speed-to-market over granular control.
- Private Cloud:Dedicated cloud environments with single-tenant isolation. Preferred by German and Japanese insurers facing strict data residency requirements.
- Managed Services:Vendor-operated infrastructure with outsourced operational responsibility. Appeals to mid-tier carriers lacking internal cloud engineering depth.
- Self-Hosted:Complete carrier control over hardware and software stacks. Persists among specialized mutuals with legacy compliance frameworks.
Public Cloud carries the heaviest existing deployment. Private Cloud is gaining share fastest.
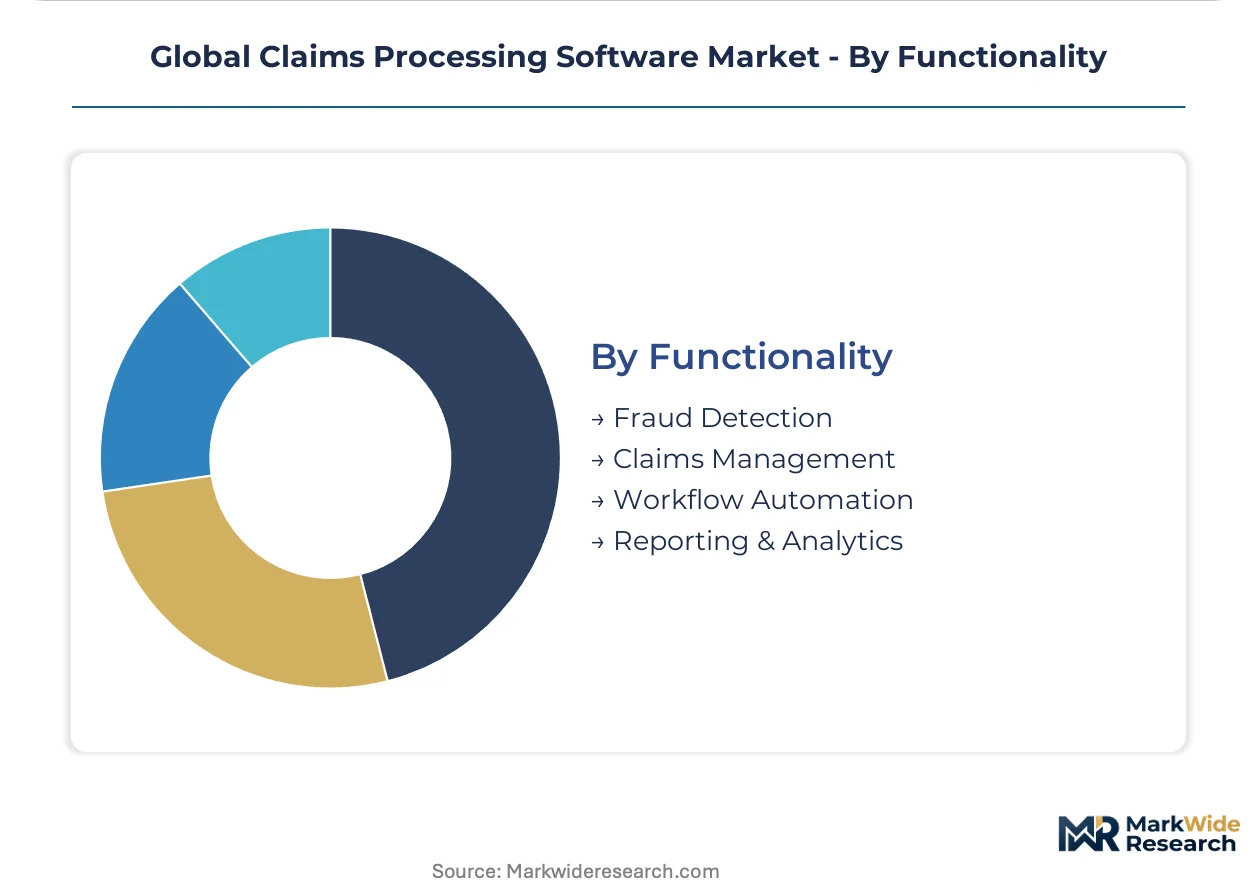
Functionality:
Fraud detection modules command premium pricing due to specialized AI training and regulatory scrutiny, while workflow automation spreads fastest as labor cost pressures intensify.
- Fraud Detection:AI-powered anomaly identification across historical claims patterns. United States carriers invest here most aggressively to combat organized fraud rings and meet state regulatory reporting.
- Workflow Automation:Rules-driven routing and straight-through processing for routine claims. Expanding most quickly in Japan and the United States as carriers target headcount reduction.
- Claims Management:Core intake, adjudication, and payment orchestration. Universal requirement across all carrier segments.
- Reporting & Analytics:Regulatory filing support and operational dashboards. Mandatory for EU AI Act documentation and state insurance department submissions.
Claims Management anchors current installations. Workflow Automation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors cloud-native claims platform development, while Hartford's insurance corridor sustains legacy modernization demand across property and casualty lines.
United States
HIPAA compliance mandates and state-level speed-to-resolution regulations drive carrier investment in automated adjudication engines. The Department of Health and Human Services enforces breach notification rules that accelerate secure cloud migration timelines. Hartford's insurance technology corridor hosts concentrated vendor development activity serving Northeastern property and casualty carriers.
Germany
Mittelstand insurers face simultaneous pressure from EU AI Act transparency requirements and aging core systems. BaFin supervision of algorithmic decision-making forces retrofitting of existing rule engines with auditable documentation protocols. Munich's insurance cluster concentrates vendor engineering resources for German-speaking European markets.
Japan
Labor cost pressures and straight-through processing targets push carriers toward workflow automation platforms. METI's Fintech Sandbox regulatory forbearance enables experimental AI-powered claims pilots with reduced compliance friction. Tokyo's Marunouchi financial district hosts the regional headquarters of major international platform vendors.
United Kingdom
Lloyd's of London market participants demand real-time claims visibility across complex international risk placements. The Prudential Regulation Authority's operational resilience requirements mandate system redundancy investments. London's InsurTech cluster drives API-native platform innovation for specialty and commercial lines.
India
Third-party administrator outsourcing growth creates demand for cost-efficient, scalable SaaS architectures. IRDAI's regulatory sandbox permits limited-scale testing of automated claims solutions before full licensing. Bengaluru's technology corridor hosts development centers serving global insurance software vendors.
Global Claims Processing Software Market Competitive Landscape
Global majors compete with regional champions across platform architecture approaches, with consolidated leadership in North American property and casualty segments and fragmented competition in European mid-tier markets. Three archetypes dominate: vertically integrated suite vendors anchoring enterprise carriers, modular specialists serving TPAs and insurtech entrants, and database-centric incumbents leveraging existing enterprise relationships. Competitive moves concentrate on strategic partnerships with IoT device manufacturers and geographic expansion through localized compliance adaptations.
Within the vertically integrated tier, Guidewire Software and Oracle exemplify contrasting approaches to carrier workflow automation, with the former representing purpose-built insurance specialization and the latter anchoring database-centric enterprise integration. SAP occupies a position bridging ERP connectivity with claims-specific functionality, particularly among European carriers with deep existing enterprise resource planning investments. These three companies collectively represent the dominant architectural philosophies shaping procurement decisions across tier-one property and casualty insurers.
| Leading Market Players |
|---|
| Guidewire Software |
| Oracle |
| SAP |
| Cognizant |
| Duck Creek Technologies |
| Verisk Analytics |
| Pegasystems |
| BriteCore |
| ClaimVantage |
| Others |
Supply & Pricing Matrix
Cloud-native microservices migration is simultaneously collapsing legacy maintenance costs and redistributing vendor pricing power toward specialized engineering talent pools in the United States, Germany, and India. This architectural transition concentrates premium pricing among vendors with proven mainframe-to-cloud migration expertise while compressing margins for commoditized workflow modules.
Pricing Analysis
Input-cost pass-through from specialized cloud engineering talent and HIPAA-compliant infrastructure certification is reshaping vendor economics across deployment tiers. Subscription-based SaaS pricing dominates, with differentiation driven by EU AI Act compliance certification and customization depth for legacy system integration. Pricing pressure stems from outcome-based commercial models tying fees to claim cycle-time improvements, making third-party administrators the most price-sensitive buyers while large property and casualty carriers absorb premium tiers for regulatory risk mitigation.
Supply Chain Analysis
Workforce availability constraints in Bengaluru, Hyderabad, and Pune are anchoring offshore development capacity for platform engineering, while onshore talent scarcity in Hartford and Munich drives premium labor costs. The supply chain draws from cloud infrastructure providers, specialized AI training data vendors, and legacy COBOL maintenance specialists. Single-source vulnerability concentrates in hyperscaler cloud platforms, with distribution running through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications around EU AI Act auditability and HIPAA breach-notification readiness are filtering procurement toward vendors with demonstrated compliance engineering, favoring established platforms over unproven entrants.
For Market Incumbents: Anchor defensive positioning through captive COBOL-to-cloud migration expertise and exclusive partnerships with third-party administrators seeking multi-tenant SaaS scale. Consolidation opportunities concentrate among German Mittelstand carriers lacking internal engineering depth. Vertical integration into AI training data provenance documentation addresses emerging EU regulatory requirements. For New Entrants and Emerging Players: METI's Fintech Sandbox regulatory forbearance in Japan opens a window for experimental AI-powered claims adjudication pilots with reduced compliance friction. White-space targets include embedded insurance workflows for IoT-enabled property devices and modular API-first platforms for United States TPAs. Go-to-market execution should emphasize straight-through processing benchmarks against legacy vendor performance gaps. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier modular specialists with proven API interoperability and limited legacy maintenance exposure. Long-term viability hinges on sustained R&D investment in generative AI intake capabilities and cross-border data sovereignty compliance. Monitor Japan's Fintech Sandbox expansion and EU AI Act enforcement calibration as inflection signals for regulatory-arbitrage window duration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates fragmented carrier workflows into unified cloud-native architectures, reducing HIPAA compliance audit burden. |
| Strategic Partnership | Aligns vendor roadmaps with IoT device manufacturers for real-time claims trigger capabilities in embedded insurance. |
| Acquisition of Specialist Firm | Captures scarce COBOL migration expertise and accelerates mainframe modernization timelines for property and casualty carriers. |
| Geographic Expansion | Establishes localized engineering presence in Germany to address BaFin algorithmic transparency mandates for EU AI Act compliance. |
| Product Launch | Introduces outcome-based pricing modules that tie platform fees to measurable claim cycle-time reductions for third-party administrators. |
Research Methodology
Multiple input streams — executive interviews with property and casualty carrier CTOs, platform engineering directors, and third-party administrator operations leads; secondary validation through SEC 10-K filings, IRDAI regulatory sandbox disclosures, and EBA stress-test documentation; plus hyperscaler capex and partnership announcements — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement decision criteria, implementation timeline constraints, and vendor switching cost structures across the United States, Germany, and Japan.
Data-stream reconciliation anchored the analytical framework across deployment model, carrier size tier, vertical specialization, integration complexity, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth trajectory analysis incorporating straight-through processing adoption curves, EU AI Act compliance deadline impacts, and cloud migration capex release patterns from legacy mainframe environments.
Revisions become necessary when EU AI Act enforcement intensity diverges from baseline assumptions, HIPAA breach penalty escalation alters cloud migration risk calculus, or Japan's Fintech Sandbox regulatory forbearance expires without extension. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
E-Invoicing Software Market
Software & Services
IT Professional Services Market
Software & Services
Enterprise Resource Planning (ERP) Software Market
Software & Services
Global Childcare Management Software Market
Software & Services
Procure to Pay Software Market
Software & Services
Global Data Governance Software Market
Software & Services
Global Contract Lifecycle Management Software Market
Software & Services
Quick Service Restaurants (QSR) IT Market
Software & Services
Global Accreditation Management Software Market
Software & Services
Push Notifications Software Market
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
Global Document Control Software Market
Software & Services
Car-Hailing Software Market
Software & Services
Lead Management Software Market
Software & Services
Enterprise Capture Software Market
Software & Services
Global Software Composition Analysis Market