
 Global Automation Software Market | 2026-2036
Global Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automation Software Market Foresight
The capability gap between cloud-native platforms and legacy on-premises stacks is rotating competitive capital allocation across the sector. Siemens AG leverages its digital twin portfolio to anchor premium positioning in manufacturing workflow automation. Rockwell Automation, Inc. sustains dominance through deep domain expertise in programmable logic controller ecosystems. Microsoft competes by extending Azure's industrial IoT layer into edge computing deployments.
Automation software encompasses programmable systems that execute, monitor, and optimize industrial and business processes with minimal human intervention, typically integrating real-time data acquisition with machine learning inference at sub-100-millisecond latencies for closed-loop control. Its primary purpose is to replace manual intervention in repetitive, high-volume, or hazardous operational workflows across discrete and process manufacturing environments. Cloud-based deployment is capturing the fastest expansion as pharmaceutical and energy utilities buyers prioritize elastic compute for batch analytics and predictive maintenance workloads. Robotic process automation remains the largest solution offering by installed base, though intelligent process automation is displacing it in greenfield financial services and telecommunications implementations where cognitive document processing delivers measurable labor arbitrage.
The EU AI Act and FDA's software-as-a-medical-device framework are forcing automation vendors to embed algorithmic audit trails and human-in-the-loop safeguards into pharmaceutical and diagnostic production lines. China's SAMR and GB standards for industrial control system cybersecurity are reshaping market access requirements for foreign platform providers serving energy and transportation infrastructure. Stakeholders must monitor whether regulatory fragmentation around autonomous decision-making creates divergent product architectures or drives consolidation toward compliant modular platforms.
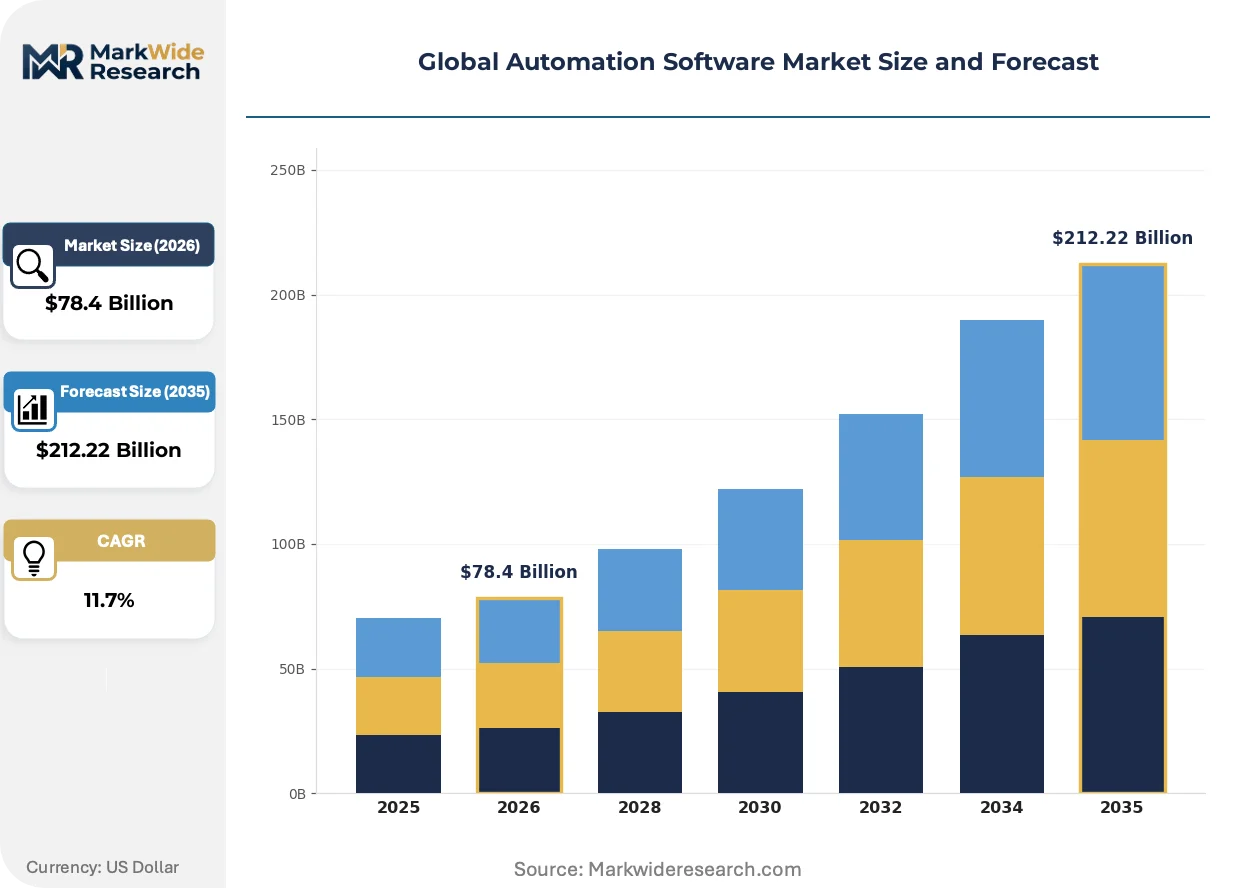
Market Dynamics
The capability gap between cloud-native platforms and legacy on-premises stacks is rotating competitive capital allocation across the sector, as pharmaceutical and energy utilities buyers prioritize elastic compute for batch analytics workloads.
Growth Catalysts
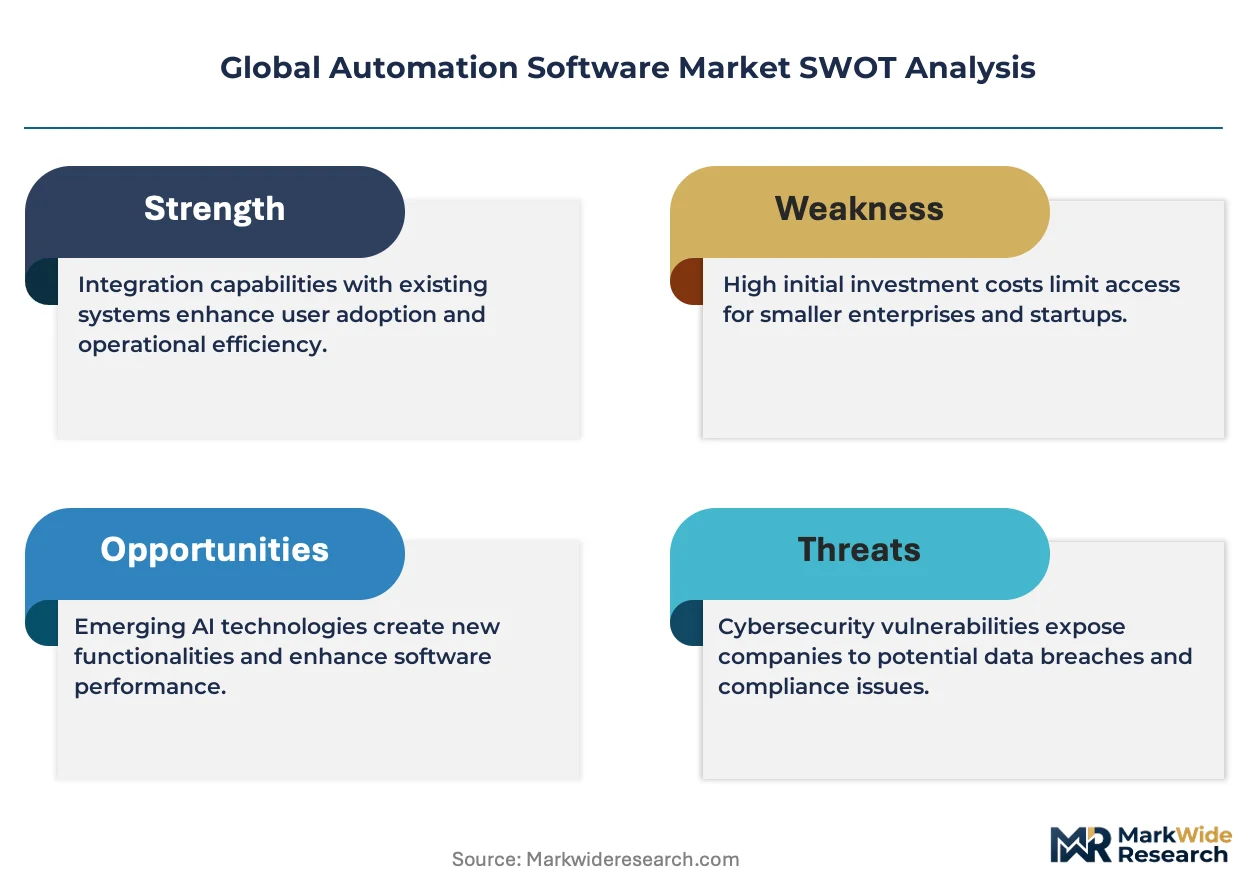
- EU AI Act compliance mandates:The regulation tightens requirements for autonomous decision-making systems, forcing automation vendors to embed algorithmic audit trails into pharmaceutical and diagnostic production lines.
- Automotive robotic process automation:Manufacturers are expanding adoption on assembly lines to execute repetitive, high-volume workflows with minimal human intervention.
- Munich-Stuttgart industrial corridor:Demand is concentrating in Germany's industrial software corridor, anchoring premium positioning for manufacturing workflow automation.
Market Restraints
- Legacy system integration costs:Technical debt in programmable logic controller ecosystems creates friction for cloud migration and extends deployment timelines.
- Regulatory fragmentation:Divergent requirements between the EU AI Act, FDA's software-as-a-medical-device framework, and China's SAMR standards force parallel product architectures.
- Edge computing hardware dependencies:Sub-100-millisecond latency requirements for closed-loop control necessitate specialized silicon with concentrated supplier bases.
Strategic Opportunities
- Intelligent process automation in financial services:Cognitive document processing delivers measurable labor arbitrage in greenfield implementations.
- India's industrial digitization:The PLI scheme and BIS standards for industrial control systems create compliant market access for modular platform providers.
- Digital twin convergence with industrial IoT:Real-time data acquisition combined with machine learning inference enables predictive maintenance workloads in energy utilities.
Industry Challenges
- OT-IT security skill scarcity:Industrial control system cybersecurity expertise remains concentrated among specialists familiar with both operational technology protocols and cloud-native architectures.
- Human-in-the-loop safeguard engineering:Embedding compliant oversight mechanisms without degrading sub-100-millisecond response times requires novel hardware-software co-design.
- Certification timeline compression:Multiple concurrent regulatory frameworks demand simultaneous compliance documentation across FDA, EMA, and NMPA pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automation Software Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $212.22 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Solution Offering: Robotic Process Automation, Intelligent Process Automation, Business Process Management, Workflow Automation, Integration Platform Use Case: Manufacturing Workflow, Supply Chain Optimization, Customer Service Automation, Financial Process Automation, IT Operations Management End User Industry: Consumer Electronics, Telecommunications, Energy & Utilities, Pharmaceutical, Transportation & Logistics |
| Companies Covered | Siemens AG, ABB Ltd, Schneider Electric SE, Emerson Electric Co., Rockwell Automation, Inc., Honeywell International Inc., Mitsubishi Electric Corporation, OMRON Corporation, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automation Software Market Shifts & Advancements
Cloud-based deployment architectures are actively restructuring how automation software is procured, deployed, and monetized across discrete and process manufacturing environments.
Intelligent process automation is supplanting robotic process automation in greenfield financial services and telecommunications implementations. Cognitive document processing capabilities now deliver measurable labor arbitrage that rule-based automation cannot match. Buyers are reallocating budgets toward platforms integrating machine learning inference with sub-100-millisecond latency for closed-loop control.
The EU AI Act is mandating algorithmic audit trails and human-in-the-loop safeguards for autonomous decision-making systems in pharmaceutical production. FDA's software-as-a-medical-device framework imposes parallel documentation requirements on diagnostic automation. Vendors are responding with modular platforms designed for multi-jurisdiction compliance rather than region-specific builds.
Outcome-based service contracts are displacing perpetual licensing in energy utilities and pharmaceutical manufacturing procurement. Buyers now prioritize elastic compute consumption models for batch analytics and predictive maintenance workloads. Germany's industrial software corridor around Munich and Stuttgart exhibits the most advanced adoption of consumption-based pricing for manufacturing workflow automation.
Global Automation Software Market Segmentation
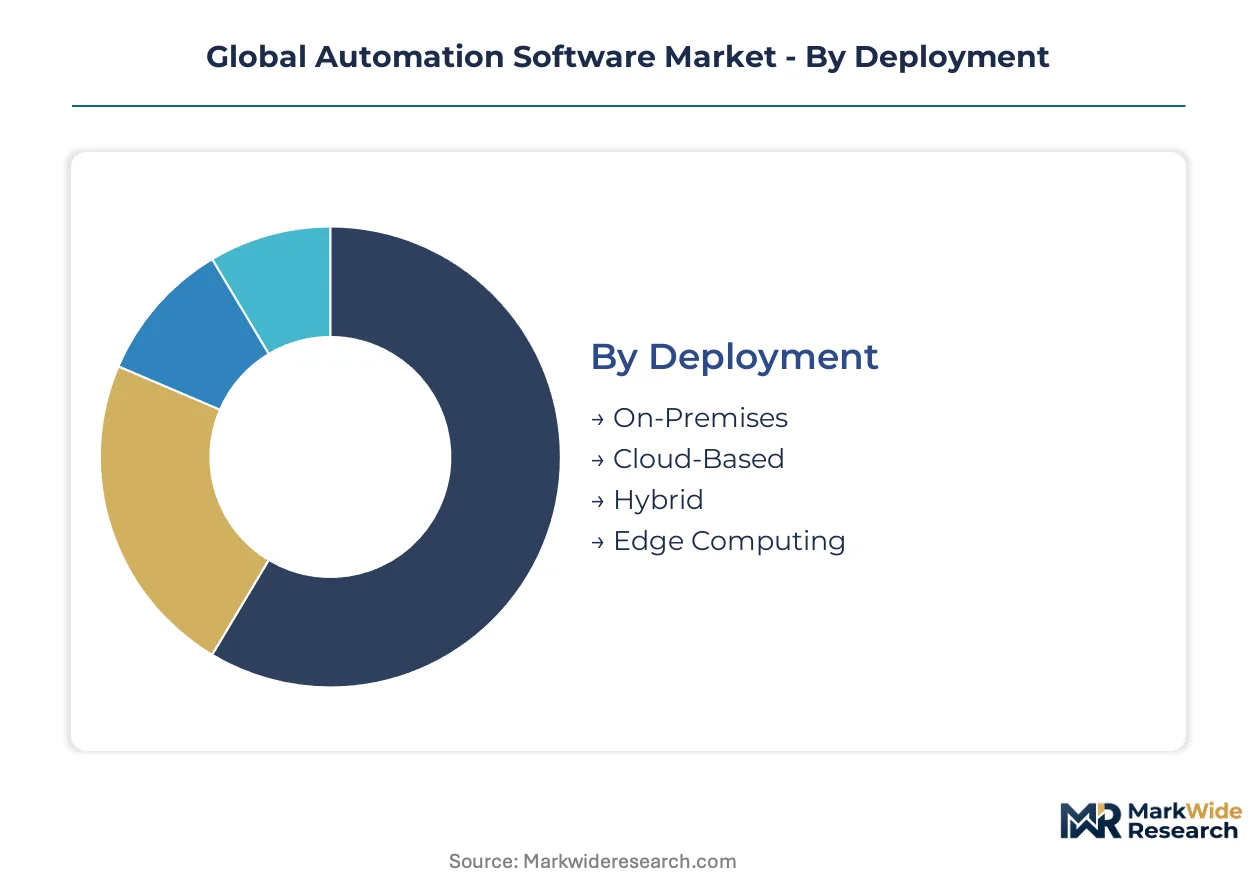
Automation software vendors must architect distinct go-to-market strategies for each deployment mode and solution type. Segment-level differentiation determines pricing power, implementation complexity, and regulatory exposure across discrete manufacturing and process industries.
Deployment:
Cloud-based architectures dominate North American and Western European procurement, while on-premises installations retain primacy in China's energy infrastructure and India's pharmaceutical corridors. Edge computing deployments concentrate around Germany's automotive belt and Japan's precision manufacturing zones.
- On-Premises:Legacy installations persist in facilities requiring air-gapped operational technology environments for cybersecurity compliance. Demand clusters in China's SAMR-regulated energy infrastructure and India's BIS-certified pharmaceutical manufacturing corridors where data sovereignty mandates predominate.
- Cloud-Based:Elastic compute consumption models enable batch analytics and predictive maintenance workloads without capital-intensive infrastructure. Pharmaceutical buyers in Switzerland and energy utilities in the United States prioritize SaaS procurement for rapid scaling across distributed asset bases.
- Hybrid:Split architectures balance latency-sensitive control loops at the edge with centralized analytics in cloud environments. German automotive manufacturers and Japanese electronics assemblers favor this model for production lines requiring sub-100-millisecond response times alongside enterprise-wide visibility.
- Edge Computing:Specialized silicon deployments support closed-loop control with minimal cloud dependency. Concentrated adoption in Germany's Munich-Stuttgart industrial corridor and Japan's METI-supported smart factory initiatives where bandwidth constraints or latency requirements preclude centralized processing.
Cloud-based holds the largest share; momentum sits with edge computing.
Solution Offering:
Procurement patterns diverge sharply between rule-based automation for established workflows and cognitive platforms requiring machine learning infrastructure.
- Robotic Process Automation:Rule-based bots execute repetitive, high-volume tasks with deterministic logic. Retains the largest installed base across financial services in the United States and back-office operations in India's IT services sector.
- Intelligent Process Automation:Cognitive document processing and natural language capabilities deliver labor arbitrage beyond rule-based systems. Expanding most quickly in greenfield financial services implementations across the United Kingdom and telecommunications customer operations in Germany.
- Business Process Management:End-to-end workflow orchestration platforms integrate human tasks with automated decision points. Strong demand in France's ANSM-regulated pharmaceutical quality management and Switzerland's precision manufacturing documentation requirements.
- Workflow Automation:Departmental tools streamline approval chains and document routing without enterprise-scale complexity. Adopted widely in mid-market manufacturing across Italy and Spain where IT resource constraints favor lighter deployment models.
- Integration Platform:API-centric middleware connects disparate operational technology and information technology systems. Critical for Germany's automotive suppliers integrating supplier networks and the United States' energy utilities consolidating distributed generation assets.
Robotic process automation retains dominant share; intelligent process automation gains share fastest.
Use Case:
Application priorities track regional industrial specialization and regulatory intensity.
- Manufacturing Workflow:Digital twin integration with programmable logic controllers optimizes discrete and process production. Concentrated investment in Germany's automotive assembly lines and Japan's electronics fabrication facilities.
- Supply Chain Optimization:Real-time inventory positioning and demand sensing across multi-tier supplier networks. Priority use case for United States retail distributors and Netherlands-based European logistics hubs managing cross-border customs complexity.
- Customer Service Automation:Conversational AI and ticket routing reduce human agent dependency. Rapid deployment in India's telecommunications sector and the United Kingdom's banking call center operations.
- Financial Process Automation:Invoice processing, reconciliation, and compliance reporting with audit trail generation. Essential for Switzerland's private banking sector and France's insurance regulatory reporting under ACPR guidelines.
- IT Operations Management:Automated incident response and infrastructure monitoring reduce mean-time-to-resolution. Standard procurement in United States technology sector and Germany's industrial software providers managing multi-tenant SaaS environments.
Manufacturing workflow holds the largest share; supply chain optimization shows steepest expansion trajectory.
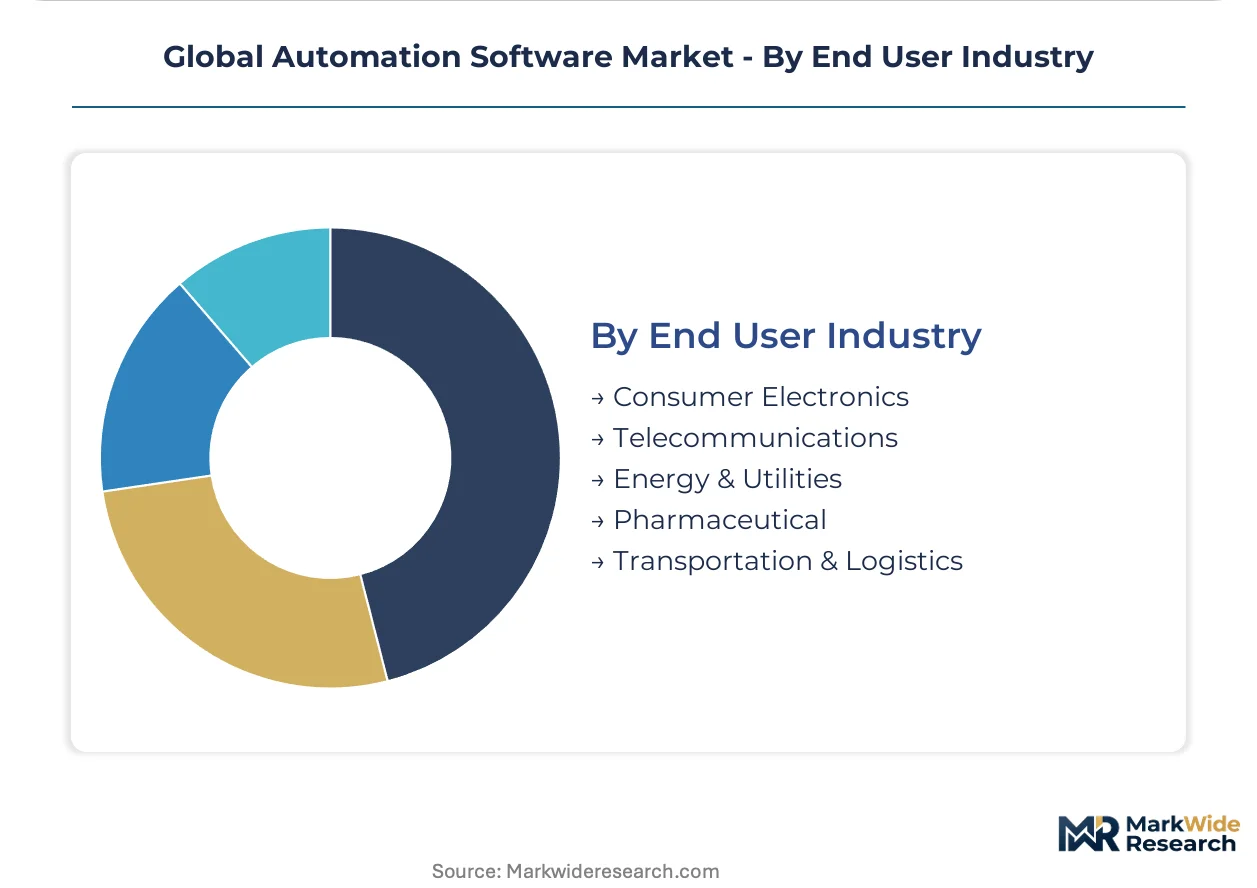
End User Industry:
Industry-specific compliance frameworks and operational technology maturity dictate solution architecture requirements.
- Consumer Electronics:High-mix, low-volume production lines demand flexible automation for rapid product changeovers. South Korea's Samsung and LG supply chains and China's Shenzhen manufacturing cluster drive specification requirements.
- Telecommunications:Network operations automation and customer service platforms manage massive subscriber bases. India's Reliance Jio and Bharti Airtel operations and Germany's Deutsche Telekom infrastructure represent anchor demand.
- Energy & Utilities:Predictive maintenance and grid optimization require sub-second control loop performance. United States FERC-regulated transmission operators and Germany's E.ON distribution networks prioritize resilient automation architectures.
- Pharmaceutical:FDA, EMA, and NMPA compliance mandates enforce algorithmic audit trails and human-in-the-loop safeguards. Switzerland's Roche and Novartis manufacturing and India's CDSCO-regulated generic drug production set stringent validation standards.
- Transportation & Logistics:Warehouse robotics and fleet optimization platforms coordinate physical movement with software orchestration. Netherlands' Rotterdam port automation and United States Amazon fulfillment networks define throughput benchmarks.
Energy and utilities holds the largest share; pharmaceutical climbs the fastest on regulatory compliance investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automation software commands 40-50% pricing premiums over Indian equivalents, reflecting divergent regulatory complexity and OT-IT integration depth. This asymmetry shapes capital flows and vendor prioritization across development roadmaps.
United States
FERC-regulated transmission operators and pharmaceutical manufacturers drive demand for predictive maintenance and algorithmic audit trail capabilities. FDA's software-as-a-medical-device framework imposes documentation requirements on diagnostic automation deployments. Boston's Route 128 corridor hosts concentrated development of industrial IoT platforms serving energy utilities.
Germany
Automotive OEMs and Mittelstand machinery builders prioritize sub-100-millisecond control loop performance for assembly line robotics. EU AI Act compliance mandates force embedding of human-in-the-loop safeguards into production software. Munich-Stuttgart industrial corridor anchors premium consumption of digital twin-integrated workflow automation.
China
State Grid Corporation and Shenzhen electronics manufacturers scale edge computing deployments for closed-loop manufacturing control. SAMR cybersecurity standards and GB industrial control system regulations reshape market access for foreign platform providers. Yangtze River Delta concentration of battery and semiconductor fabs drives specialized automation procurement.
India
Reliance Jio's network operations and CDSCO-regulated generic drug production create dual demand streams for RPA and validated automation. PLI scheme incentives and BIS standards for industrial control systems open compliant market access for modular platform providers. Bengaluru-Hyderabad corridor concentrates SaaS-native automation development for financial services export.
Japan
Precision electronics assemblers and METI-supported smart factory initiatives favor hybrid cloud-edge architectures. PMDA pharmaceutical regulations and JIS standards enforce rigorous validation protocols on production software. Nagoya-Tokyo industrial belt leads adoption of consumption-based pricing for manufacturing workflow automation.
Global Automation Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Industrial conglomerates with century-long operational technology heritage dominate premium manufacturing segments, while cloud-native platforms capture fastest-growing SaaS procurement. Two strategic archetypes define the field: OT-originated automation specialists with deep PLC ecosystem integration, and IT-originated hyperscalers extending infrastructure into edge deployments. M&A activity concentrates on acquiring domain-specific algorithm libraries, while geographic expansion targets India's PLI corridors and Germany's automotive belt.
Among European industrial conglomerates, Siemens AG and ABB Ltd exemplify the OT-heritage archetype, anchoring premium positioning through digital twin portfolios and deep manufacturing domain expertise. Microsoft represents the IT-originated challenger, competing via Azure's industrial IoT layer extension into edge computing. These three occupy positions across the technology-cost spectrum without overlapping core customer relationships.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Schneider Electric SE |
| Emerson Electric Co. |
| Rockwell Automation, Inc. |
| Honeywell International Inc. |
| Mitsubishi Electric Corporation |
| OMRON Corporation |
| Microsoft |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with edge-computing silicon foundries lock in supply access and price visibility for automation vendors serving Germany's automotive corridor and Japan's precision manufacturing zones. These arrangements insulate buyers from spot-market volatility in semiconductor substrates while committing capital to specialized fabrication nodes.
Pricing Analysis
The customization-premium spread between configured-to-order digital twin implementations and standard SaaS workflow automation separates Siemens AG's premium positioning from Microsoft's volume-tier offerings. Subscription-tiered pricing dominates cloud-based deployments, while project-based licensing persists for on-premises programmable logic controller integrations. Price differentiation rests on FDA validation documentation and EU AI Act compliance certification rather than raw compute capacity. Cost compression in standard RPA modules is intensifying because Indian SaaS providers are undercutting legacy vendors on implementation services. Mid-market manufacturers in Italy and Spain exhibit the highest price sensitivity, whereas Swiss pharmaceutical buyers prioritize compliance-grade solutions regardless of cost.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg container terminals directly impact edge-computing hardware landed costs for European automation deployments. Supply concentrates in Taiwan's semiconductor foundries, South Korea's memory fabrication, and Germany's precision mechanical components. Raw material dependencies span silicon wafers, rare earth magnets for servo motors, and specialized aluminum alloys for industrial enclosures. Single-source vulnerability in sub-100-millisecond latency chipsets creates chokepoint exposure for closed-loop control systems. Distribution runs through authorized system integrator networks in Germany's Munich-Stuttgart belt and direct hyperscaler marketplaces for cloud-native procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automation software market is exiting a cyclical trough as capital expenditure cycles in automotive and energy utilities rebound from prior-year deferrals. Inventory restocking in Germany's industrial corridor signals the recovery phase.
For Market Incumbents: Shield installed-base revenue by embedding EU AI Act compliance modules into existing digital twin deployments before challengers can displace them with native-compliant alternatives. Prioritize backward integration into edge-computing silicon design to reduce dependency on concentrated foundry suppliers. Channel control through exclusive system integrator partnerships in Japan's Nagoya-Tokyo belt defends premium positioning against Microsoft's Azure industrial IoT expansion.
For New Entrants and Emerging Players: Anchor in India's PLI-subsidized pharmaceutical automation corridor where CDSCO validation requirements have kept hyperscalers at bay. Target white-space demand for cognitive document processing in greenfield financial services implementations across the United Kingdom. A compliance-first go-to-market angle—pre-certified algorithmic audit trails—bypasses the incumbent advantage in legacy manufacturing accounts.
For Investors and Strategic Acquirers: Domain-specialist algorithm libraries with embedded regulatory compliance represent the most defensible acquisition archetype in this market. OT-heritage automation vendors with deep PLC ecosystem integration and existing FDA 510(k) clearances command scarcity premiums. Watch for inflection when pharmaceutical manufacturers accelerate software-as-a-medical-device procurement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure's industrial IoT layer extension into edge deployments challenges Siemens' digital twin dominance. |
| Regulatory Pre-Certification | EU AI Act algorithmic audit trail modules open pharmaceutical procurement doors ahead of compliance deadlines. |
| Acquisition of Specialist Firm | Machine learning inference libraries with sub-100-millisecond optimization address latency-critical manufacturing. |
| Geographic Expansion | India's PLI corridors and BIS-compliant modular platforms capture pharmaceutical and electronics demand. |
| Strategic Partnership | System integrator exclusivity in Germany's Munich-Stuttgart belt locks out cloud-native competitors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with automation software CTOs, industrial IT procurement officers, pharmaceutical validation engineers, and energy utility grid operations directors; and secondary validation through SEC filings of listed automation vendors, EMA regulatory submission databases, FDA software-as-a-medical-device premarket notifications, and hyperscaler industrial IoT capex disclosures. Bottom-up triangulation across deployment-mode segmentation and top-down cross-check against end-user industry expenditure patterns anchored volume estimates.
Across the analysis window, the forecasting framework modeled deployment architecture, solution complexity tier, integration depth, and regional regulatory cluster as primary segmentation dimensions. CAGRs were derived from elasticity-adjusted adoption curves calibrated against historical PLC replacement cycles and cloud-migration velocity in comparable industrial software categories. Industry-specific inputs included pharmaceutical compliance investment trajectories under FDA and EMA frameworks, plus automotive capital expenditure intentions from Germany's VDMA member surveys.
Material uncertainties — regulatory timeline slippage for EU AI Act enforcement, foundry capacity constraints in Taiwan, and pharmaceutical buyer budget freezes — sit outside the modeled envelope. Forecasts reflect documented assumptions about substitution elasticity between on-premises and cloud-native architectures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Construction Suites Software Market
Software & Services
On-Call Scheduling Software Market
Software & Services
Europe Integration Platform As a Service Market
Software & Services
Asia-Pacific Digital Signage Software Market
Software & Services
Japan HR Payroll Software Market
Software & Services
Deck Software Market
Software & Services
Global Electronic Design Automation Tools (EDA) Market
Software & Services
Data Preparation Tools Market
Software & Services
PCB CAD Software Market
Software & Services
Content Distribution Software Market
Software & Services
US Software Consulting Market
Software & Services
Global Workforce Management Software Market
Software & Services
Enterprise Backup and Recovery Software Market
Software & Services
Device Tracking Software Market
Software & Services
Computer Backup Software Market
Software & Services
Meditation Software Market