
 Productivity Software Publishing Market | 2026-2036
Productivity Software Publishing Market Size, Share, and Industry Trends Forecast 2026-2036
Productivity Software Publishing Market Analysis
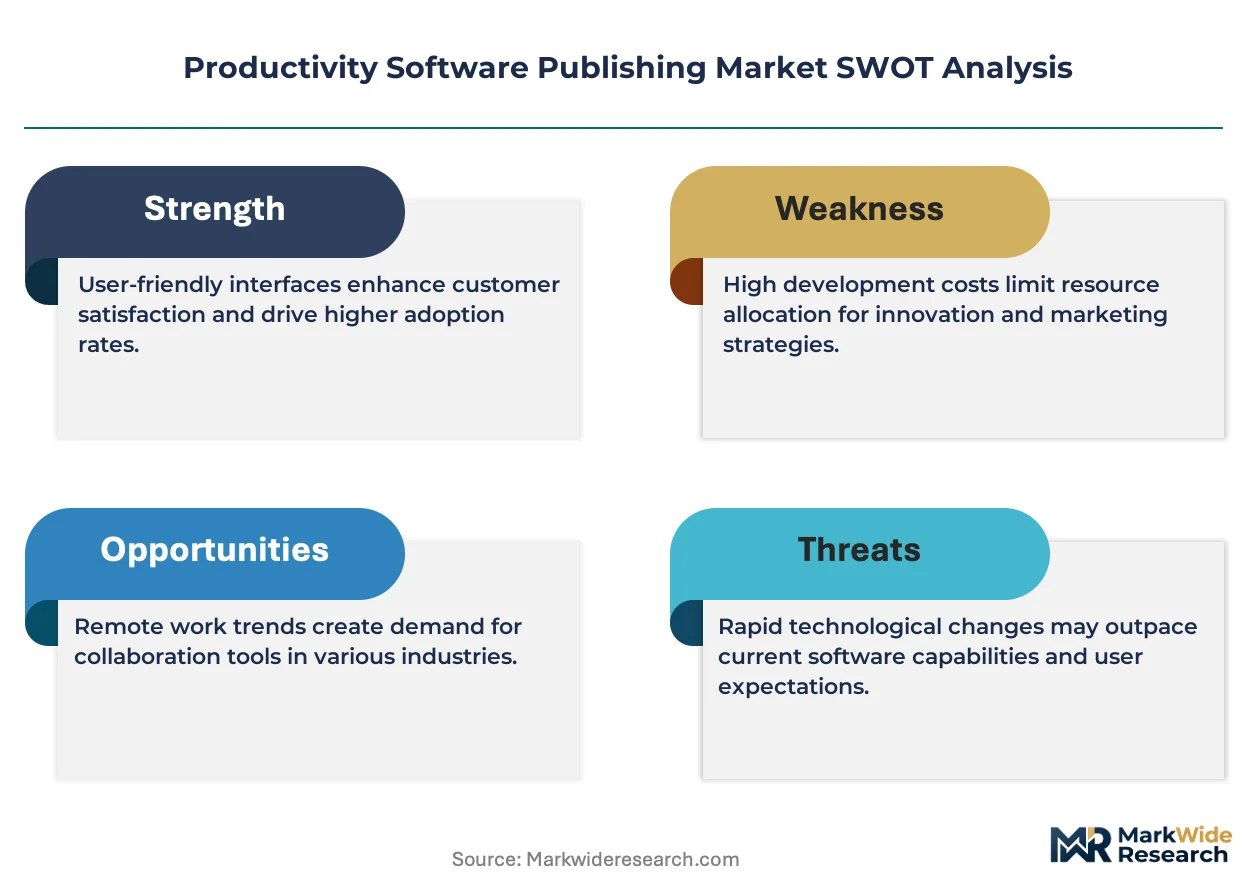
The EU AI Act is recalibrating how productivity software vendors architect algorithmic transparency and risk-classification features into core platforms. Microsoft Corporation leverages its Azure compliance infrastructure to pre-certify Copilot integrations across regulated European industries. Google LLC anchors its competitive stance through deep Workspace interoperability with sovereign cloud deployments in Germany and France. Atlassian Corporation differentiates by embedding granular audit trails into Jira and Confluence workflows that satisfy emerging algorithmic accountability requirements.
Productivity software publishing encompasses the design, distribution, and continuous update of applications that enable document creation, data analysis, visual communication, and collaborative task orchestration, typically delivered through cloud-native architectures with API-first extensibility. The primary commercial purpose centers on compressing cycle times across knowledge-work pipelines while reducing friction in cross-functional coordination. Cloud-based deployment now captures the dominant margin pool as subscription economics displace perpetual licensing, while project management software represents the fastest-expanding product type as agile methodologies penetrate non-technology sectors. SMEs constitute an underpenetrated end-user tier where freemium-to-paid conversion mechanics are sharpening vendor acquisition efficiency.
GDPR and the EU AI Act shape European demand by mandating data-residency controls and explainability documentation that elevate engineering costs for non-compliant entrants. The Federal Risk and Authorization Management Program (FedRAMP) and SEC cybersecurity disclosure rules in the United States impose comparable barriers that favor incumbents with dedicated compliance teams. Stakeholders must monitor whether emerging sovereign AI regulations fragment platform architectures into geography-specific instances or sustain the current model of unified global codebases with modular compliance overlays.
Market Dynamics
The hybrid work protocol hardening into permanent operational policy is compressing refresh cycles for collaborative platforms and forcing vendors to embed real-time synchronization and AI-assisted workflow orchestration as baseline capabilities rather than premium add-ons.
Growth Catalysts
- Cloud-migration mandates:Federal directives in the United States are accelerating platform replacements across civilian agencies and defense contractors, creating immediate procurement windows for compliant SaaS providers.
- EU AI Act risk-classification requirements:Algorithmic accountability frameworks are elevating procurement criteria for explainability features and audit trails across European enterprise buyers.
- Agile methodology penetration:Non-technology sectors including construction, healthcare administration, and professional services are adopting project management software to compress cycle times in cross-functional coordination.
Market Restraints
- Compliance engineering cost inflation:GDPR data-residency controls and FedRAMP authorization requirements are elevating fixed costs for vendors lacking dedicated regulatory infrastructure.
- API dependency concentration:Critical workflow automation capabilities rely on a narrow set of cloud infrastructure providers, creating single-point-of-failure exposure.
- Perpetual license displacement friction:Enterprise IT procurement functions in regulated industries face internal resistance to subscription economics due to capital expenditure approval workflows.
Strategic Opportunities
- SME freemium conversion mechanics:Sharpening onboarding flows and usage-based upgrade triggers in underpenetrated mid-market segments across Germany and France.
- Sovereign cloud interoperability:German and French national cloud deployments create demand for productivity suites with modular data-residency overlays.
- Natural language processing convergence:Generative interfaces are automating document drafting and data analysis workflows, opening new pricing tiers for AI-augmented seats.
Industry Challenges
- Algorithmic transparency engineering:EU AI Act documentation requirements demand specialized machine-learning operations talent that remains scarce in European labor markets.
- Legacy system integration complexity:On-premise enterprise resource planning systems in manufacturing and financial services resist API-native connectivity, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Productivity Software Publishing Market |
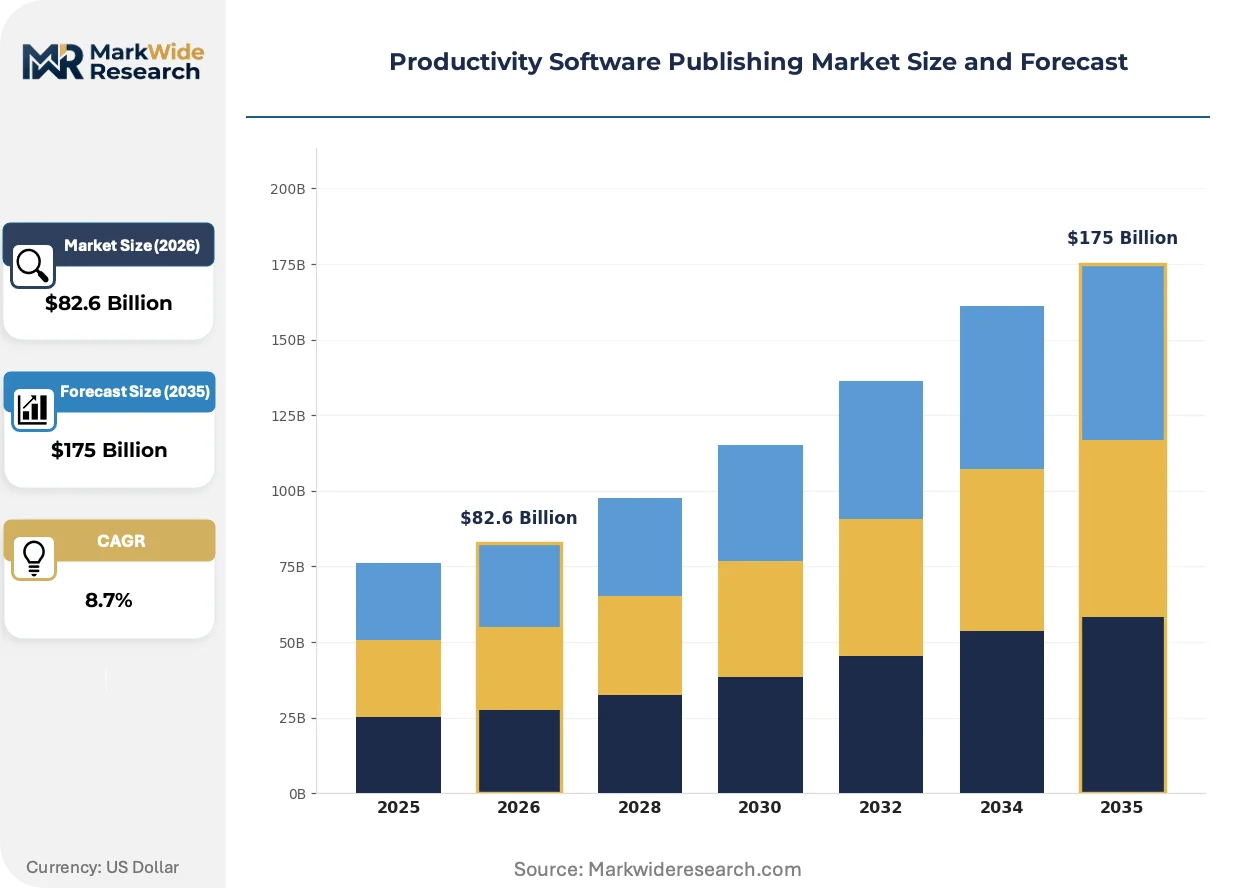
| Market Size in 2026 | $82.6 Billion |
| Market Size in 2035 | $175 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Word Processors, Spreadsheets, Presentation Tools, Project Management Software Deployment Model: On-Premises, Cloud-Based, Hybrid, Mobile Applications End User: SMEs, Enterprises, Educational Institutions, Government Agencies Pricing Model: Subscription-Based, One-Time Purchase, Freemium, Pay-As-You-Go |
| Companies Covered | Microsoft Corporation, Google LLC, Apple Inc., Oracle Corporation, SAP SE, Adobe Inc., Salesforce.com Inc., Atlassian Corporation, Zoho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Productivity Software Publishing Market Emerging Trajectories
Generative AI capabilities are embedding into core productivity workflows, shifting competitive differentiation from feature breadth to inference quality and contextual relevance within existing document and communication environments.
Large language models are automating routine knowledge-work tasks including email composition, meeting summarization, and spreadsheet formula generation. Enterprise legal and financial services segments are adopting these capabilities fastest, compressing the time required for document review cycles by embedding generative assistance directly into familiar interfaces.
The EU AI Act's algorithmic transparency mandates are recalibrating vendor development roadmaps toward explainability-by-design. High-risk system classifications now require conformity assessments before deployment, prompting productivity software publishers to pre-certify modules through notified bodies in Germany and France rather than retrofit compliance post-launch.
Subscription fatigue among mid-market buyers is fragmenting procurement authority away from centralized IT departments toward line-of-business leaders with discretionary software budgets. This shift is most visible in United States professional services firms, where practice group heads now directly evaluate and adopt specialized collaboration tools without enterprise-wide standardization.
Productivity Software Publishing Market Segmentation
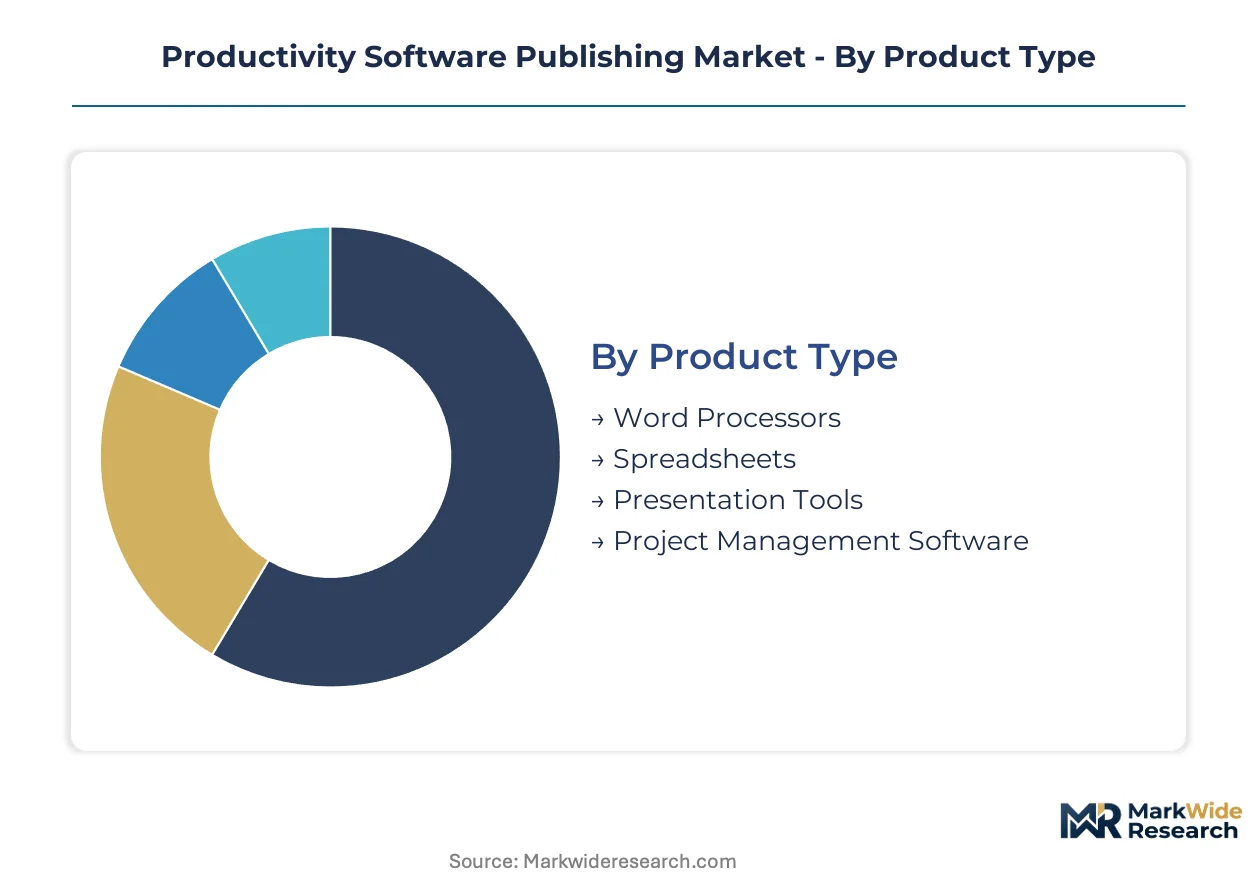
Segmentation in productivity software publishing reveals divergent monetization mechanics and compliance burdens across deployment architectures. Cloud-native delivery models command premium pricing while legacy on-premises installations retain sticky revenue pools in regulated verticals.
Product Type:
Volume concentration favors collaboration-centric tools over individual productivity suites, with premium margins attaching to workflow orchestration capabilities.
- Word Processors:Core document creation platforms now embed generative drafting assistance as baseline functionality. Demand from legal and financial services firms in the United States drives upgrade cycles for AI-augmented contract and report generation features.
- Project Management Software:Workflow orchestration platforms with real-time synchronization and resource allocation algorithms. Construction and healthcare administration sectors in Germany and France adopt these tools fastest as agile methodologies penetrate non-technology industries.
- Spreadsheets:Data analysis environments with formula automation and visualization capabilities. Retains entrenched position in financial modeling workflows across enterprise segments.
- Presentation Tools:Visual communication platforms with templated design assistance. SME adoption accelerates through freemium conversion mechanics in underpenetrated mid-market tiers.
Mature deployment sits with word processors and spreadsheets. Newer deployment is concentrated in project management software.
Deployment Model:
Margin distribution skews toward recurring-revenue architectures, though sovereign data-residency requirements sustain hybrid configurations in European regulated industries.
- Cloud-Based:Multi-tenant SaaS delivery with API-first extensibility and automatic feature updates. Federal cloud-migration mandates in the United States accelerate procurement across civilian agencies and defense contractors.
- Hybrid:Split architectures maintaining sensitive data on-premises while leveraging cloud collaboration layers. German and French national cloud deployments create demand for modular data-residency overlays satisfying GDPR and EU AI Act requirements.
- On-Premises:Self-hosted installations with manual patch management. Persists in financial services and manufacturing segments with legacy ERP integration constraints.
- Mobile Applications:Native or responsive interfaces for smartphone and tablet workflows. Expanding fastest among field-service and distributed workforce configurations.
Established revenue pools sit with on-premises deployments. Cloud-based delivery is gaining share fastest as subscription economics displace perpetual licensing.
End User:
Procurement authority fragmentation reshapes sales motion complexity, with line-of-business budgets displacing centralized IT standardization.
- Enterprises:Large organizations with dedicated procurement functions and compliance teams. FedRAMP authorization and SEC cybersecurity disclosure requirements favor vendors with established regulatory infrastructure.
- SMEs:Mid-market organizations with discretionary software budgets held by practice group heads. Freemium-to-paid conversion mechanics sharpen acquisition efficiency across Germany and France.
- Government Agencies:Public-sector entities with sovereign data-residency mandates. United States federal directives create immediate procurement windows for compliant SaaS providers.
- Educational Institutions:Universities and K-12 systems with volume licensing agreements. Price sensitivity drives preference for bundled productivity suites over specialized point solutions.
Institutional standardization sits with government agencies. SME procurement is expanding most quickly as departmental software budgets proliferate.
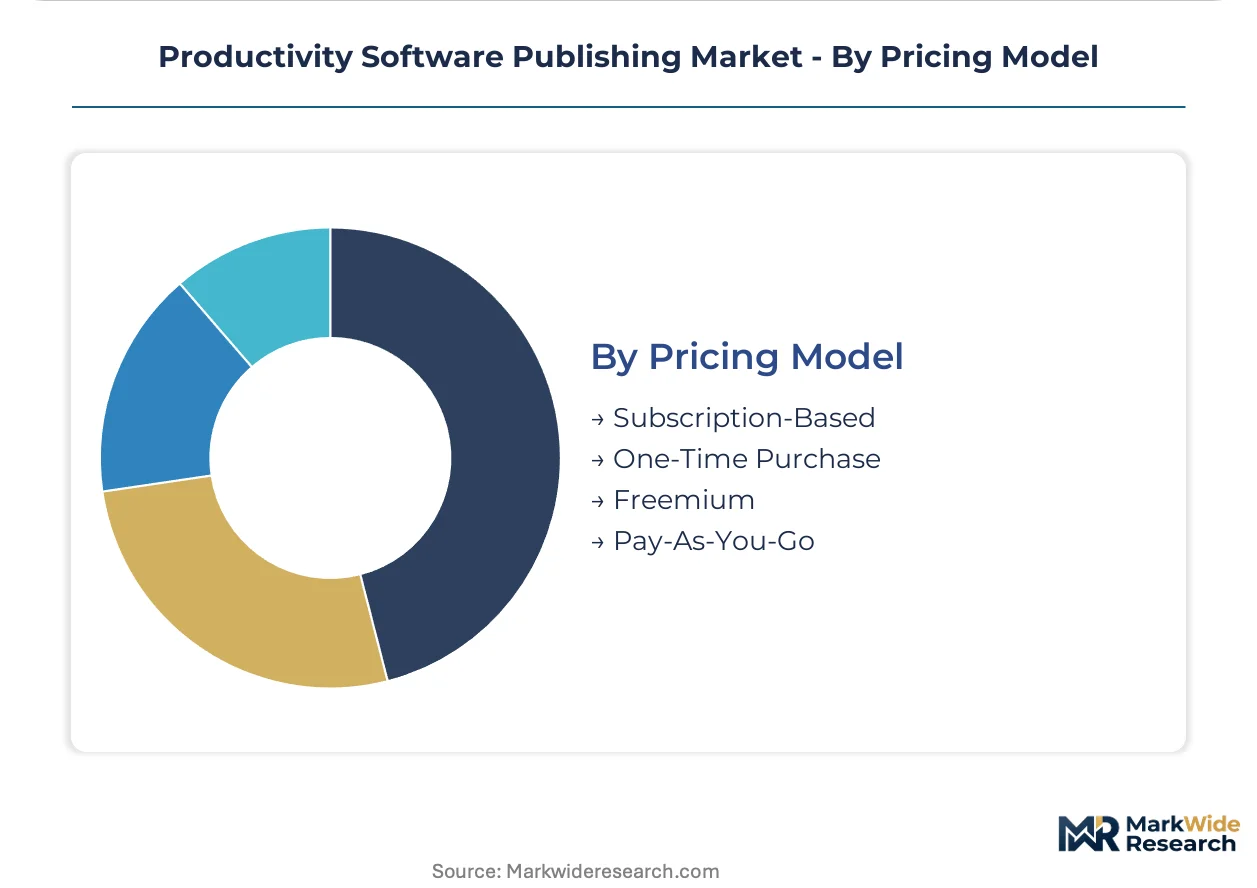
Pricing Model:
Revenue predictability trade-offs define competitive positioning, with usage-based experimentation emerging in AI-augmented seat tiers.
- Subscription-Based:Recurring monthly or annual fees with tiered feature access. Dominates cloud-native delivery, though enterprise IT functions in regulated industries resist due to capital expenditure approval workflow friction.
- Freemium:Zero-cost entry with usage or feature thresholds triggering paid conversion. Sharpening onboarding flows target underpenetrated mid-market segments with discretionary budgets.
- One-Time Purchase:Perpetual licenses with optional maintenance contracts. Retains sticky revenue in on-premises installations resistant to subscription economics.
- Pay-As-You-Go:Consumption-based billing tied to actual usage metrics. Emerging for AI-augmented seats where inference costs vary with utilization intensity.
Revenue stability sits with subscription-based contracts. Pay-as-you-go experimentation is climbing fastest among generative AI feature tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors global productivity software publishing, hosting headquarters clusters for cloud-native platform developers and venture capital flows that seed generative AI integration across document and workflow applications.
United States
Federal cloud-migration mandates and defense-sector productivity investments accelerate platform refresh cycles across civilian agencies. FedRAMP authorization requirements elevate procurement barriers that favor established vendors with dedicated compliance infrastructure. Washington D.C. and Northern Virginia host dense concentrations of government contractors integrating sovereign cloud deployments.
Germany
Industrial manufacturing and automotive knowledge workers drive demand for project management software as agile methodologies penetrate non-technology sectors. The EU AI Act and GDPR data-residency controls mandate algorithmic transparency features that recalibrate vendor development roadmaps. Munich and Stuttgart industrial corridors adopt sovereign cloud interoperability overlays for sensitive engineering workflows.
France
Professional services firms and healthcare administration segments expand procurement of collaborative platforms with embedded audit trails. National cloud deployments through Bleu and other sovereign infrastructure initiatives create demand for modular compliance architectures. Paris and Lyon financial services clusters prioritize explainability documentation for high-risk AI system classifications.
United Kingdom
London's professional services and fintech ecosystems compress cycle times for document automation and contract analysis tools. Post-Brexit regulatory divergence creates parallel compliance tracks for data-residency and algorithmic accountability standards. The Cambridge-Oxford technology corridor seeds specialized workflow orchestration startups targeting legal and research institutions.
India
IT services and business process outsourcing centers drive volume demand for cloud-based productivity suites with mobile-first interfaces. The country's national data protection framework and emerging AI governance standards reshape vendor localization requirements. Bangalore and Hyderabad technology parks concentrate mid-market SaaS adoption among distributed workforce configurations.
Productivity Software Publishing Market Vendor Landscape
The competitive structure tilts toward platform consolidators with established cloud infrastructure and compliance certifications. Tier-one vendors leverage Azure and AWS compliance overlays to pre-certify AI-augmented features across regulated European and North American industries. Strategic archetypes include hyperscale platform providers, vertical workflow specialists, and mid-market freemium converters. Dominant competitive moves center on sovereign cloud partnership formations and generative AI seat-tier pricing experimentation.
Within the hyperscale tier, Microsoft Corporation and Google LLC anchor positions through deep enterprise integration and pre-certified compliance architectures. Atlassian Corporation exemplifies the workflow specialist archetype, embedding granular audit trails that satisfy emerging algorithmic accountability requirements. Zoho Corporation occupies a distinct position among mid-market-focused vendors sharpening freemium conversion mechanics across underpenetrated SME segments in Germany and France.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Apple Inc. |
| Oracle Corporation |
| SAP SE |
| Adobe Inc. |
| Salesforce.com Inc. |
| Atlassian Corporation |
| Zoho Corporation |
| Others |
Supply Flow & Price Mechanics
Federal cloud-migration mandates in the United States are compressing procurement timelines for compliant SaaS providers, forcing supply chains to prioritize FedRAMP-authorized infrastructure and elevating pricing power for vendors with pre-certified compliance architectures over those retrofitting authorization post-sale.
Pricing Analysis
Seat-based subscription tiers anchored to workflow throughput outcomes dominate cloud-native delivery, with premium pricing attaching to AI-augmented inference quotas and granular audit-trail capabilities. Price differentiation stems from FedRAMP authorization tier and vertical integration depth into sovereign cloud deployments. Pricing pressure intensifies in the mid-market as freemium conversion mechanics sharpen acquisition competition. Government agencies exhibit lowest price sensitivity due to mandate-driven procurement, while SME practice groups show highest elasticity to subscription fatigue.
Supply Chain Analysis
Reverse-logistics flows for data-residency compliance—including workload repatriation from non-sovereign clouds and modular overlay redeployment—are expanding as German and French national cloud mandates proliferate. Supply concentration rests on hyperscaler infrastructure in the United States, Ireland, and Singapore for primary compute, with edge nodes multiplying across Frankfurt, Paris, and Mumbai to satisfy latency and residency requirements. Critical dependencies include GPU clusters for generative inference, API gateway services, and encryption key management systems. Single-source vulnerability concentrates in narrow cloud infrastructure provider sets. Distribution runs through direct enterprise sales, hyperscaler marketplaces, and channel partners serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compliance engineering talent scarcity is constraining vendor capacity to satisfy EU AI Act documentation requirements, propping pricing for explainability-by-design modules and sustaining margin premiums for pre-certified architectures.
For Market Incumbents: Deploy sovereign cloud partnership formations to defend European public-sector procurement positions against emerging regional specialists. Consolidate API-gateway control through exclusive integration certifications with hyperscaler marketplaces. Counter threat from vertical workflow specialists embedding granular audit trails by accelerating pre-certification through notified bodies in Germany and France. For New Entrants and Emerging Players: The premium-to-economy pricing gap in AI-augmented project management software creates entry space for mid-market-focused vendors sharpening freemium conversion mechanics. Target underpenetrated SME segments in German industrial manufacturing corridors and French healthcare administration clusters. Pursue line-of-business procurement authority fragmentation as go-to-market angle, bypassing centralized IT standardization. For Investors and Strategic Acquirers: The window for entry favors workflow specialists with pre-built algorithmic transparency documentation and existing notified body relationships. Long-term viability hinges on sustained regulatory fragmentation across sovereign AI frameworks. Acquisition target archetype: vertical specialists with embedded audit-trail IP and European compliance infrastructure. Signal to watch: divergence in national cloud certification timelines accelerating geographic winner-take-most dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding generative AI capabilities into existing document workflows compresses user retraining cycles and anchors retention. |
| Strategic Partnership | Sovereign cloud alliances with Bleu and German national cloud providers unlock regulated European public-sector procurement windows. |
| Acquisition of Specialist Firm | Vertical workflow specialists with pre-built EU AI Act documentation accelerate compliance roadmap execution for platform consolidators. |
| Geographic Expansion | Localized data-residency overlays in India satisfy emerging national data protection framework requirements for IT services outsourcing centers. |
| Product Launch | Usage-based AI seat tiers with inference metering capture consumption variability while defending margin against flat-rate subscription fatigue. |
Methodological Framework
Multi-period observation of vendor compliance roadmap disclosures, hyperscaler capex allocations, and sovereign cloud partnership formations anchored the trend analysis, supplemented by interviews with CTOs at enterprise productivity software deployers, IT procurement officers in federal agencies, platform engineers at cloud infrastructure providers, and integration specialists serving regulated verticals. Secondary validation drew from SEC 10-K filings, hyperscaler quarterly capex disclosures, EU AI Act implementation guidance, and FedRAMP authorization databases. Bottom-up segment sizing and top-down macro constraint triangulation were applied throughout.
Segment-weighting across deployment models, organization size tiers, vertical industry clusters, and regional regulatory frameworks structured the analytical approach. CAGRs were derived from fitted growth curves calibrated to procurement cycle data and compliance deadline phasing. Industry-specific forecast inputs included FedRAMP authorization pipeline velocity and EU AI Act notified body certification capacity constraints.
Inputs from hyperscaler infrastructure disclosures and vendor compliance filings were available through the study window; gaps in SME departmental procurement spend visibility introduce uncertainty bands in mid-market penetration trajectories. Forecasts reflect documented assumptions regarding hybrid work protocol permanence and regulatory fragmentation persistence. Material deviation in sovereign AI certification timelines or hyperscaler capacity expansion trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
B2B Gateway Software Market
Software & Services
Compensation Software Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Cloud-Based Payroll Software Market
Software & Services
App Development Software Market
Software & Services
Worldwide Persuasive Content Management Software Market
Software & Services
Landscaping Engineering Software Market
Software & Services
Global Home Inspection Software Market
Software & Services
US Digital Marketing Software Market
Software & Services
Dropshipping Software Solutions Market
Software & Services
Tableau Services Market
Software & Services
Application Server Market
Software & Services
Load Balancing Software Market
Software & Services
Global Architect Software Market
Software & Services
Sales Training and Onboarding Software Market
Software & Services
Integration Brokerage Software Market