
 Electronic Batch Records Market | 2026-2036
Electronic Batch Records Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Batch Records Market Foresight
Buyer concentration among pharmaceutical contract manufacturers is pivoting toward integrated digital platforms that unify quality and production data. Siemens leverages its automation hardware heritage to anchor integrated batch execution systems across European manufacturing sites. Korber competes through specialized pharmaceutical software modules that extend MES functionality into regulatory submission workflows. Thermo Fisher Scientific dominates laboratory-to-production data handoffs with chromatography and batch record integration.
Electronic batch records are digital systems that capture, store, and manage manufacturing execution data with timestamped audit trails, electronic signatures, and automated deviation flagging to replace paper-based production logs. These systems enforce ALCOA+ data integrity principles while enabling real-time release and continuous process verification in regulated industries. Software deployments currently occupy the largest value share as legacy paper systems require modular replacement, while cloud solutions represent the fastest-expanding segment driven by multi-site pharmaceutical rollouts needing centralized quality oversight. IoT integration is displacing legacy standalone architectures as sensor-rich bioreactors and continuous manufacturing lines demand automated data capture.
FDA enforces 21 CFR Part 11 electronic records requirements through periodic warning letters that directly shape vendor product roadmaps and customer procurement priorities. EMA coordinates with national inspectors across EU member states under the EU GMP Annex 11 framework, creating dual-compliance burdens for suppliers serving both markets. WHO guidelines on data integrity provide a baseline that India's CDSCO and China's NMPA incorporate into national GMP inspections, expanding addressable demand beyond traditional FDA-regulated buyers. Stakeholders must monitor how AI-driven batch analytics will trigger new validation requirements from major regulators before committing to platform architectures.
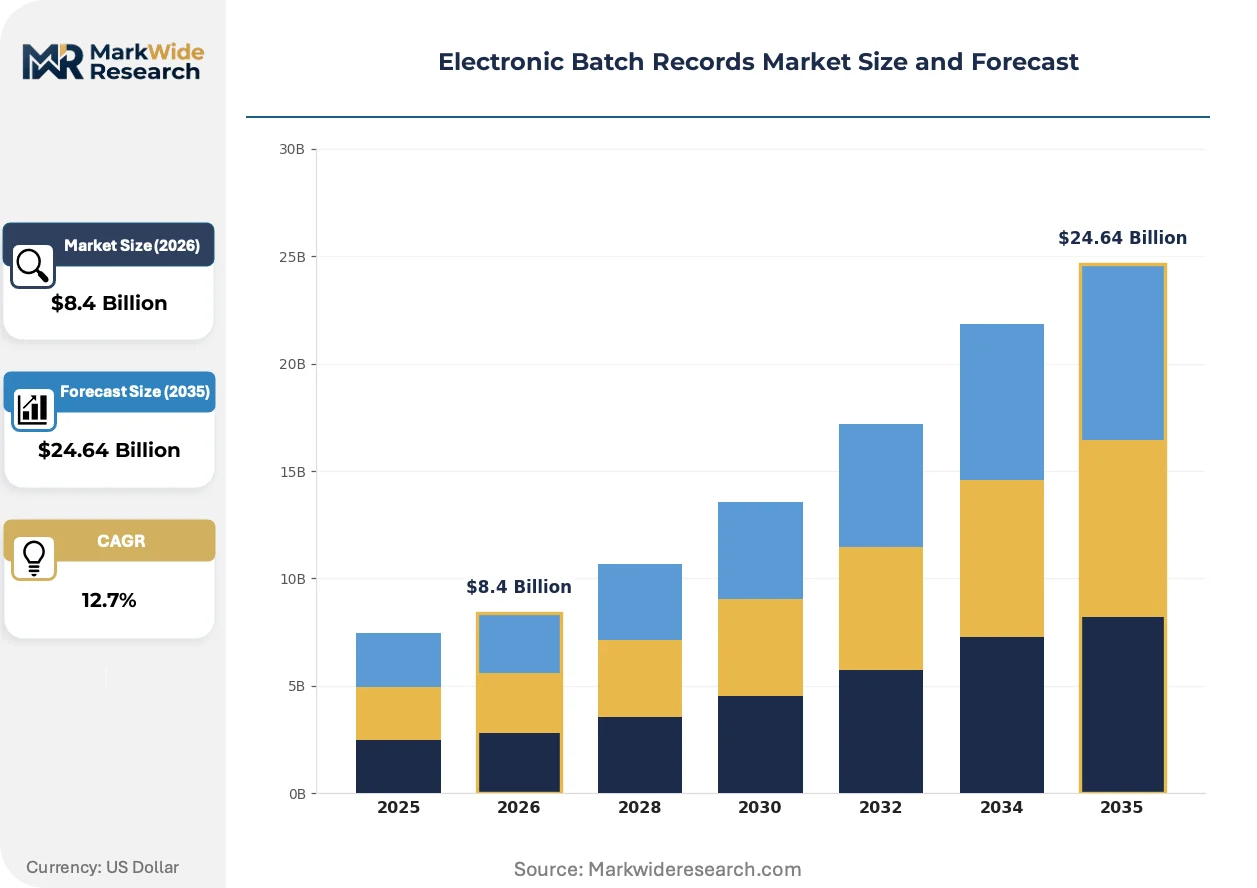
Market Dynamics
Cloud-native electronic batch record architectures are compressing validation cycles and forcing incumbent vendors to restructure platform roadmaps around continuous deployment models. This shift is redistributing competitive advantage toward software-as-a-service specialists with modular API ecosystems.
Growth Catalysts
- FDA 21 CFR Part 11 enforcement:Warning letters targeting data integrity violations in sterile injectable manufacturing are accelerating replacement of hybrid paper-digital systems with fully electronic workflows.
- Continuous manufacturing adoption:Real-time release testing requirements in biologics production demand automated batch documentation that paper processes cannot support.
- India:CDSCO's alignment with WHO data integrity guidelines is expanding mandatory electronic record requirements beyond export-oriented facilities to domestic pharmaceutical producers.
Market Restraints
- Validation cost concentration:Computer system validation for cloud deployments consumes 18-24 months of implementation timelines, freezing capital in qualification protocols rather than functional capability.
- EU MDR technical documentation:Device manufacturers must maintain parallel batch record systems for pharmaceutical and medical device regulations, duplicating compliance infrastructure.
- Legacy MES lock-in:Proprietary data formats from 1990s-era manufacturing execution systems obstruct migration to open-architecture electronic batch record platforms.
Strategic Opportunities
- Cell and gene therapy manufacturing:Personalized medicine batch sizes of one require electronic records that dynamically configure workflows around patient-specific parameters.
- EU AI Act compliance tooling:Automated batch analytics platforms can embed explainability documentation required for high-risk AI systems in pharmaceutical quality decision-making.
- Contract development manufacturing organizations:Multi-tenant cloud architectures enable CDMOs to segregate client data while centralizing infrastructure investment across pharmaceutical sponsors.
Industry Challenges
- CSV talent scarcity:Qualified computer system validation professionals command premium compensation, constraining deployment velocity for mid-tier pharmaceutical manufacturers.
- Hybrid system integration:Electronic batch records must synchronize with chromatography data systems, LIMS, and ERP platforms through non-standard interfaces, multiplying validation scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Batch Records Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $24.64 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Cloud Solutions, Hardware, Services End User: Pharmaceuticals, Biotechnology, Food & Beverage, Cosmetics Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Technology: Legacy Systems, IoT Integration, AI Driven, Blockchain |
| Companies Covered | Siemens, Korber, ABB, MasterControl, Rockwell Automation, SAP SE, Emerson Electric, Thermo Fisher Scientific, Yokogawa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Batch Records Market Shifts & Advancements
Artificial intelligence is penetrating batch record systems through automated deviation classification and predictive quality alerts, compressing the gap between data capture and decision-making. This convergence is redefining competitive differentiation around analytics depth rather than document management functionality.
Edge computing architectures are expanding into bioreactor control networks, enabling timestamped data capture at the sensor level before transmission to centralized batch record repositories. Single-use bioprocessing equipment suppliers are embedding validation-ready software modules that pharmaceutical sponsors adopt at accelerated procurement cycles. This distributed computing model is compressing infrastructure requirements for multi-site manufacturing networks while elevating cybersecurity validation scope.
EMA's draft guidance on artificial intelligence in medicinal product lifecycle management is forcing batch record vendors to document algorithm training datasets and decision logic for regulatory inspection. Pharmaceutical quality units must now maintain audit trails for machine learning model versions alongside traditional manufacturing parameters. Small-molecule generic manufacturers in Eastern Europe are experiencing the steepest compliance preparation burden due to limited in-house data science capabilities.
Quality agreements between pharmaceutical sponsors and contract manufacturers are specifying real-time batch record visibility as a standard contractual term, displacing periodic report submission. CDMOs are investing in customer-specific dashboard portals to satisfy this transparency expectation and defend contract renewal rates. This behavioral shift is most pronounced among mid-cap biotechnology companies outsourcing commercial manufacturing to facilities in Germany and Switzerland.
Electronic Batch Records Market Segmentation
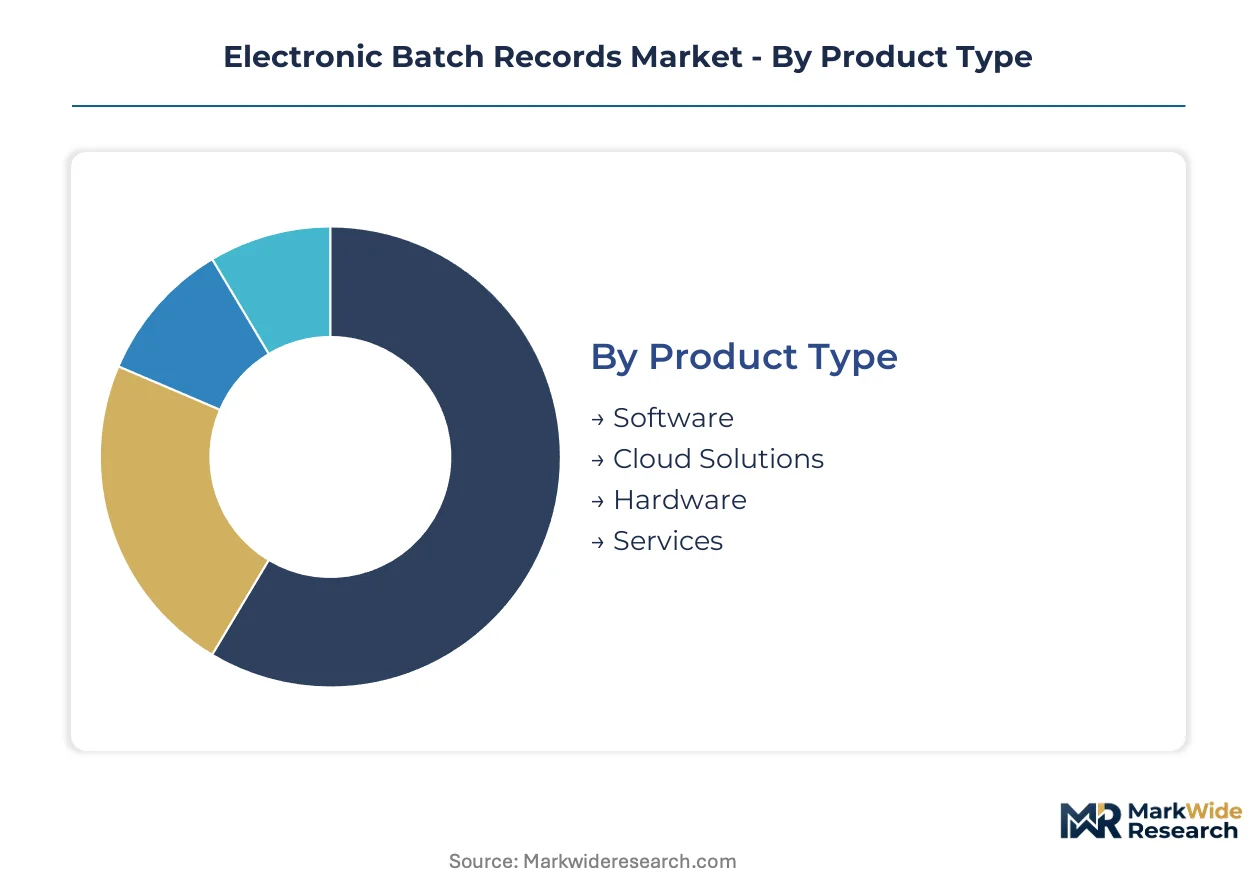
Electronic batch record procurement varies sharply by infrastructure maturity and regulatory exposure. Buyers select deployment architectures and technology tiers based on validation burden tolerance, legacy system entanglement, and real-time data requirements.
Product Type:
Technology sophistication determines replacement cycles and vendor switching costs across pharmaceutical manufacturing.
- Software:Modular applications enforce ALCOA+ data integrity principles through configurable workflows and electronic signature capture. Demand concentrates among mid-tier generic manufacturers in India replacing hybrid paper-digital systems under CDSCO inspection pressure.
- Cloud Solutions:Multi-tenant SaaS architectures compress validation timelines through pre-qualified infrastructure and continuous deployment pipelines. Germany's contract manufacturing sector adopts these most aggressively to serve multiple pharmaceutical sponsors from centralized quality systems.
- Hardware:Industrial tablets, barcode scanners, and biometric signature pads extend electronic workflows onto production floors. Validation-ready peripherals reduce procurement friction for facilities upgrading from paper batch folders.
- Services:Computer system validation, change control documentation, and periodic requalification support address chronic talent scarcity. CDMOs in Switzerland outsource validation protocol development to defend audit readiness.
Software leads on scale; Cloud Solutions lead on momentum.
End User:
Regulatory stringency and batch complexity create divergent functional requirements across verticals.
- Pharmaceuticals:Small-molecule and biologics manufacturers deploy electronic batch records to satisfy FDA 21 CFR Part 11 and EMA Annex 11 inspection protocols. Sterile injectable facilities face the steepest compliance pressure following recent warning letter enforcement.
- Biotechnology:Cell and gene therapy producers require dynamic workflow configuration for patient-specific batch sizes of one. United States-based ATMP manufacturers prioritize systems with embedded chain-of-identity tracking.
- Food & Beverage:FSMA preventive controls and FSSC 22000 certification drive adoption among dairy and infant formula processors. Electronic records reduce recall response time through rapid lot traceability.
- Cosmetics:EU Cosmetics Regulation (EC) 1223/2009 and emerging MoCRA requirements in the United States push documentation digitization. Color cosmetics manufacturers with complex multi-component formulations see strongest system interest.
Pharmaceuticals dominates absolute spend; Biotechnology climbs the fastest.
Deployment:
Infrastructure ownership models reflect risk tolerance for data residency and vendor dependency.
- On-Premise:Perpetual-licensed servers behind facility firewalls satisfy data sovereignty requirements for national security-sensitive production. Russian and Chinese pharmaceutical manufacturers mandate this architecture under local data localization laws.
- Cloud-Based:Subscription access to vendor-managed infrastructure eliminates capital expenditure and shifts validation burden to shared responsibility models. India's export-oriented API manufacturers favor this to accelerate FDA pre-approval inspection readiness.
- Hybrid:Critical quality data resides on-premise while analytics and reporting leverage cloud elasticity. Large pharmaceutical conglomerates with multi-site networks deploy this to balance control with central oversight.
- Mobile:Tablet-based execution on wireless shop floor networks enables real-time deviation capture at bioreactor and filling line stations. Single-use bioprocessing equipment suppliers pre-integrate these modules for accelerated deployment.
On-Premise retains installed base dominance; Cloud-Based gains share fastest.
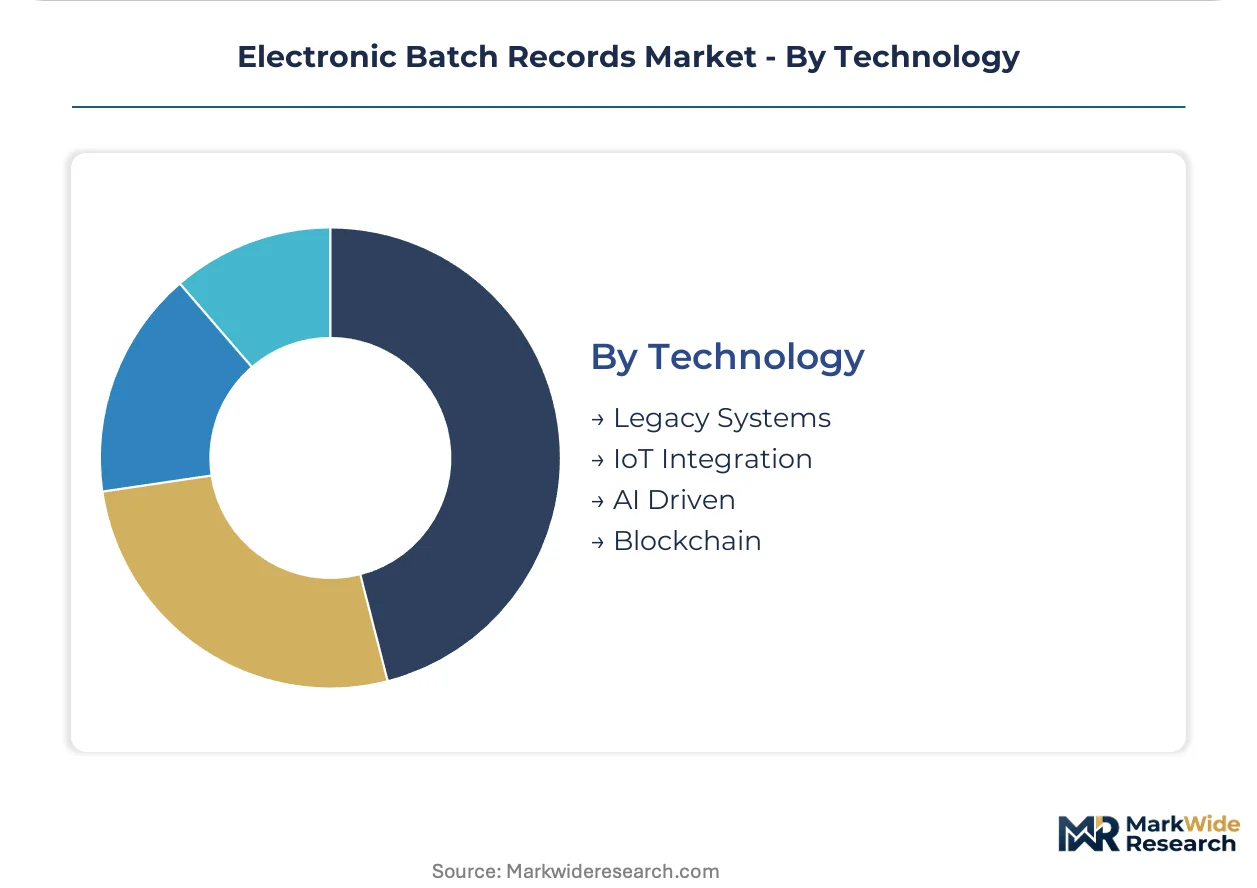
Technology:
Architectural generations compete on integration depth, audit trail immutability, and predictive capability.
- Legacy Systems:Client-server applications from the 1990s and 2000s persist through sunk validation investment and change control paralysis. Eastern European generic manufacturers face the steepest migration burden due to limited technical resources.
- IoT Integration:Edge computing nodes timestamp sensor data at bioreactor and continuous manufacturing line sources before transmission to centralized repositories. Real-time release testing requirements in biologics production mandate this architecture.
- AI Driven:Machine learning models classify deviations and predict quality excursions, compressing decision latency from days to hours. EMA draft guidance on AI in medicinal product lifecycle management forces vendors to document training datasets and algorithm versions.
- Blockchain:Distributed ledger architectures create tamper-evident audit trails for high-value biologics and cell therapy chain-of-custody documentation. Early pilots concentrate among personalized medicine manufacturers in the United States and Switzerland.
Legacy Systems anchor current deployment value; AI Driven shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Computer system validation specialists cluster in Germany, Switzerland, and Massachusetts, anchoring deployment velocity across pharmaceutical manufacturing corridors. FDA warning letter enforcement in the United States and CDSCO inspection intensity in India are redistributing implementation timelines toward these talent-dense regions.
United States
Sterile injectable manufacturers in New Jersey and Puerto Rico face accelerated FDA 21 CFR Part 11 compliance deadlines following recent data integrity warning letters. Boston's cell and gene therapy cluster demands electronic batch records with embedded chain-of-identity tracking for patient-specific batches. Thermo Fisher Scientific anchors laboratory-to-production data integration from its Massachusetts base.
Germany
Contract manufacturing organizations in Baden-Württemberg and Bavaria adopt cloud-native architectures to serve multiple pharmaceutical sponsors from centralized quality systems. EMA Annex 11 revisions force replacement of hybrid paper-digital workflows across the Rhine-Neckar pharmaceutical corridor. Siemens leverages its automation heritage to anchor integrated batch execution systems across European manufacturing sites.
India
API manufacturers in Hyderabad and Ahmedabad accelerate FDA pre-approval inspection readiness through cloud-based deployments. CDSCO's alignment with WHO data integrity guidelines expands mandatory electronic record requirements to domestic pharmaceutical producers beyond export-oriented facilities. Generic manufacturers in Gujarat replace legacy paper batch folders under intensifying regulatory scrutiny.
Switzerland
Biologics producers in Basel and Zurich invest in validation-ready software modules for single-use bioprocessing equipment. Swissmedic coordinates with EMA on AI-driven batch analytics inspection protocols, elevating documentation requirements for machine learning model versions. CDMOs outsource validation protocol development to defend audit readiness against sponsor quality agreements.
China
NMPA incorporation of WHO data integrity guidelines drives electronic batch record adoption among domestic biologics manufacturers in Shanghai and Suzhou. Data localization requirements mandate on-premise architectures for national security-sensitive production. Yangtze River Delta pharmaceutical clusters face steepest migration burden from 1990s-era manufacturing execution systems.
Electronic Batch Records Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across electronic batch record procurement cycles. Industrial automation conglomerates leverage hardware heritage to anchor integrated batch execution systems, while software specialists extend manufacturing execution functionality into regulatory submission workflows. Three archetypes dominate: automation-hardware anchors, pharmaceutical software specialists, and laboratory-to-production integrators. Strategic moves concentrate on modular API ecosystem expansion and pre-qualified cloud infrastructure partnerships to compress validation timelines.
Among automation-centric conglomerates, Siemens and ABB occupy positions anchoring integrated batch execution systems across European pharmaceutical manufacturing sites. Rockwell Automation and Emerson Electric exemplify the hardware-to-software extension archetype, leveraging industrial control heritage into regulatory-compliant documentation workflows. Within the pharmaceutical software specialist tier, Korber represents focused modular extension of manufacturing execution functionality, while MasterControl sits within the quality management convergence segment. Thermo Fisher Scientific anchors the laboratory-to-production integration archetype, bridging chromatography data systems with batch record repositories. SAP SE exemplifies the enterprise resource planning extension pattern, embedding batch execution within broader manufacturing operations platforms.
| Leading Market Players |
|---|
| Siemens |
| Korber |
| ABB |
| MasterControl |
| Rockwell Automation |
| SAP SE |
| Emerson Electric |
| Thermo Fisher Scientific |
| Yokogawa |
| Others |
Supply & Pricing Matrix
FDA warning letter enforcement against sterile injectable manufacturers is compressing procurement timelines and forcing buyers toward pre-validated cloud architectures, which elevates vendor switching costs and anchors price premiums to compliance velocity rather than feature depth.
Pricing Analysis
Capacity additions in Germany and Switzerland are reshaping price floors for validation-ready software modules as Siemens and Korber expand pre-qualified infrastructure partnerships. Pricing stratifies across premium, standard, and economy tiers based on FDA 21 CFR Part 11 certification completeness and embedded AI analytics capability. Cost compression in the standard tier is intensifying because Indian CDSCO inspection pressure is commoditizing basic electronic signature functionality. Mid-tier generic manufacturers in India exhibit highest price sensitivity; biotechnology sponsors in the United States demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with German automation hardware suppliers and Swiss validation protocol developers. Component sourcing draws from Taiwan for industrial tablets, Germany for precision sensors, and the United States for biometric signature pads. Tariff exposure runs through semiconductor-dependent edge computing nodes. Distribution feeds from direct vendor-to-manufacturer contracting with limited systems integrator intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electronic Batch Records Market compounds steadily as regulatory inspection intensity tightens compliance deadlines across pharmaceutical manufacturing corridors.
For Market Incumbents: Anchor integrated batch execution systems through expanded API ecosystems that lock in CDMO multi-tenant deployments. Invest in pre-qualified cloud infrastructure partnerships to compress validation timelines below competitor reach. Defend against SaaS specialists by embedding regulatory submission workflow functionality that extends beyond document management into EMA and FDA filing automation. For New Entrants and Emerging Players: Contract manufacturing organizations in Eastern Europe present the most penetrable white-space target due to legacy MES lock-in and limited in-house validation talent. Cell and gene therapy batch-size-of-one configurations offer specialized workflow configuration opportunities. Pursue partnerships with single-use bioprocessing equipment suppliers for accelerated procurement cycles through pre-integrated software modules. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-driven batch analytics specialists possessing documented algorithm training datasets for EMA inspection readiness. Long-term viability centers on platforms that embed explainability documentation for high-risk AI systems in pharmaceutical quality decision-making. Monitor EMA final guidance on artificial intelligence in medicinal product lifecycle management as the inflection signal for validation requirement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Qualified Cloud Infrastructure Partnership | Compresses FDA 21 CFR Part 11 validation timelines for multi-site pharmaceutical rollouts. |
| AI-Driven Batch Analytics Platform Launch | Embeds EMA-mandated explainability documentation for high-risk quality decision-making systems. |
| Single-Use Bioprocessing Equipment Integration | Accelerates procurement cycles through validation-ready software modules for bioreactor networks. |
| Multi-Tenant SaaS Architecture Expansion | Enables CDMOs to segregate client data while centralizing infrastructure across sponsors. |
| Regulatory Submission Workflow Extension | Extends MES functionality into EMA and FDA filing automation for competitive differentiation. |
Research Methodology
Bottom-up pharmaceutical manufacturer modeling reconciled against top-down vendor deployment tracking forms the analytical core of this study. Primary interviews with validation protocol developers, regulatory affairs directors at CDMOs, quality unit heads, and computer system validation consultants combined with secondary validation from FDA warning letter databases, EMA inspection outcome reports, CDSCO compliance circulars, and vendor SEC filings. Triangulation across these sources anchored market sizing and growth trajectory assessment.
Historical trendline analysis of electronic batch record procurement cycles informed projection framework construction across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user vertical, technology generation, and regional regulatory cluster. CAGRs derived from validated vendor booking data and pharmaceutical manufacturer capital expenditure disclosures. Forecast inputs incorporated CDSCO inspection intensity trajectories and EMA AI guidance implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AI validation requirement finalization and continuous manufacturing adoption velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Mobile Middleware Market
Software & Services
Global License Management Market
Software & Services
India Software Services Export Market
Software & Services
Data Preparation Tools Market
Software & Services
Enterprise Search Software Market
Software & Services
Sports League Management Software Market
Software & Services
Software Containers Market
Software & Services
Global Salesforce Appexchange Tools Market
Software & Services
Global User Interface Service Market
Software & Services
Global ITSM Software Market
Software & Services
Global Brand Management Software Market
Software & Services
Global Smartphone Operating System (OS) Market
Software & Services
Product Optimization Software Market
Software & Services
Information Technology Service Management (ITSM) Market
Software & Services
Software Licensing Market
Software & Services
Computer Backup Software Market