
 Cursor Reviewer Market | 2026-2036
Cursor Reviewer Market Size, Share, and Industry Trends Forecast 2026-2036
Cursor Reviewer Market Insights
Capability gaps in GPU-accelerated inference and real-time collaborative review are bifurcating competitive tiers. CVISION Technologies leverages its optical mark recognition heritage to anchor enterprise document-review workflows. Cursor dominates among software developers through deep IDE integration, while BugBot competes by specializing in automated bug-detection pipelines for agile teams. Nanxun Information Industry sustains geographic dominance across East Asian public-sector procurement channels.
A cursor reviewer is an automated or semi-automated system that inspects, validates, and annotates digital cursor movements, pointer behaviors, and interaction patterns within graphical user interfaces, typically operating at millisecond-level sampling rates to detect latency anomalies, accessibility compliance failures, or usability friction points. Its primary industrial purpose is to ensure software interfaces meet performance benchmarks and accessibility standards before production deployment. Browser-based technology leads in accessibility and zero-install deployment for distributed creative teams, while cloud-based architecture captures the fastest growth as remote collaboration demands synchronous multi-user review sessions. Standalone deployment retains margin concentration among defense and financial services buyers with air-gapped security requirements.
The EU AI Act and GDPR impose algorithmic transparency obligations on automated review systems processing personal data, compelling vendors to document decision logic and enable human override mechanisms. The US FCC and FDA maintain sector-specific guidance for cursor-tracking in telehealth interfaces and medical device software, creating compliance moats for vendors with pre-cleared quality management systems. Stakeholders must monitor emerging interoperability mandates from ISO and IEC that could force standardization of review-data exchange formats across competing platforms.
Market Dynamics
IDE-integrated cursor review systems are compressing deployment cycles from quarterly releases to continuous validation pipelines, forcing vendors to rebuild architectures for millisecond-level sampling rather than batch processing.
Growth Catalysts
- EU AI Act transparency mandates:Automated decision-making systems in cursor review tools now require documented logic trails, creating procurement urgency for explainable algorithm vendors across German and French enterprise buyers.
- Continuous integration pipeline embedding:DevOps teams at software houses in the United States and India are mandating pre-commit cursor validation, converting optional tooling into infrastructure spend.
- Telehealth interface expansion:FDA guidance on medical device software cursor tracking is creating compliance-driven replacement cycles for legacy review systems in US healthcare IT procurement.
Market Restraints
- GPU inference cost volatility:Real-time collaborative review workloads require NVIDIA A100/H100 allocation, exposing vendor margins to foundry capacity constraints and cloud provider pricing power.
- East Asian supply concentration:Optical sensor component fabrication clusters in Taiwan and South Korea create single-source fragility for hardware-coupled review systems.
- Air-gapped deployment fragmentation:Defense and financial services buyers in Switzerland and Saudi Arabia require standalone installations that forfeit cloud-native feature velocity, compressing addressable market for SaaS-native vendors.
Strategic Opportunities
- Indian public-sector digitization:BIS certification pathways for automated review tools are opening state-level procurement channels for accessibility compliance in government software tenders.
- Edge-AI convergence with WebAssembly:Browser-based review tools are gaining on-device inference capabilities that bypass cloud latency for distributed creative teams in Brazil and Mexico.
- CSRD-aligned ESG tooling:EU sustainability reporting requirements are creating demand for cursor review systems that audit digital accessibility as a social metric for listed enterprises.
Industry Challenges
- Millisecond-level algorithmic auditing expertise:Vendors struggle to hire engineers capable of validating sub-frame latency detection logic at production scale.
- ISO/IEC interoperability standardization delays:Pending exchange format mandates are freezing procurement decisions as buyers await clarity on data portability requirements.
- Legacy IDE integration complexity:Enterprises running JetBrains and Visual Studio Code versions predating 2022 face breaking API changes that stall review tool deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cursor Reviewer Market |
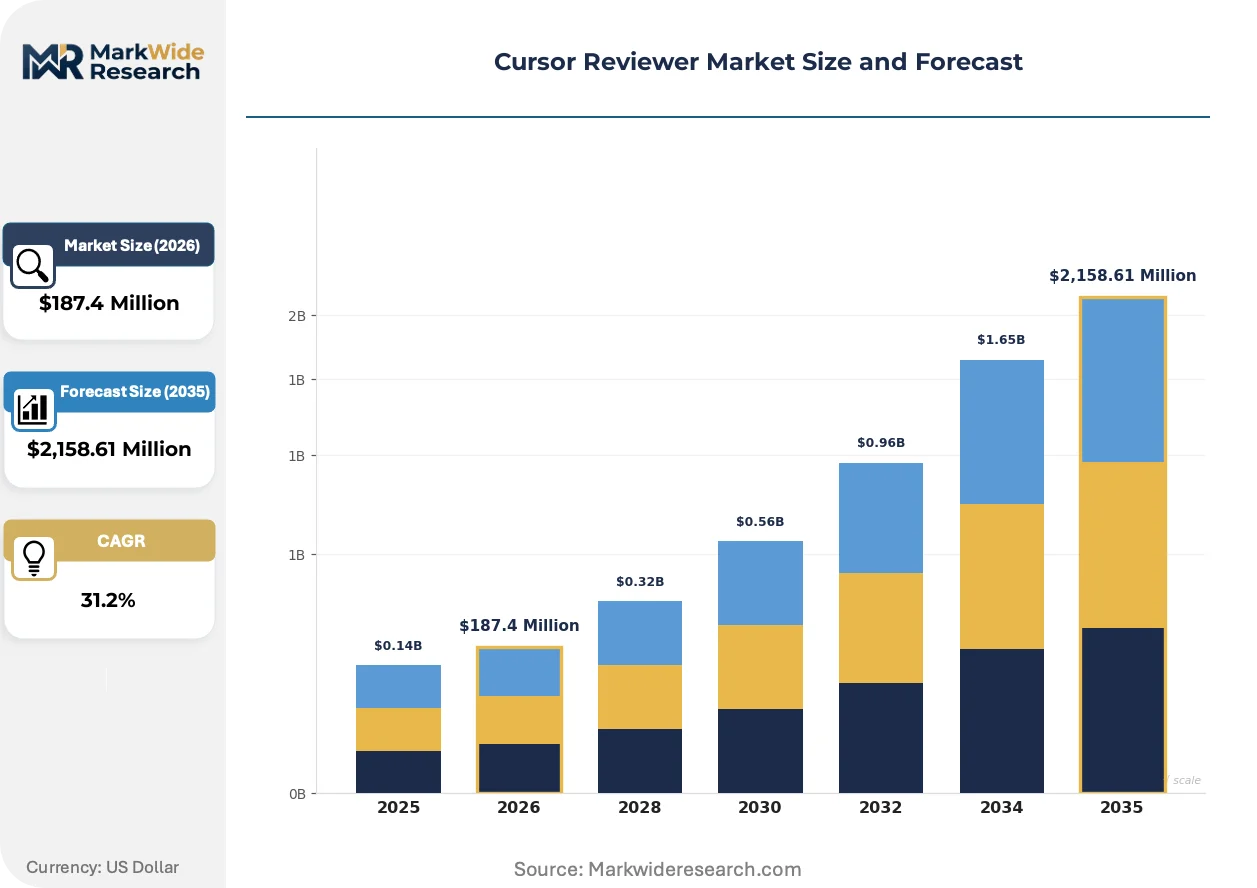
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,158.61 Million |
| CAGR (2026 – 2036) | 31.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Graphic Designers, Software Developers, Content Creators, Digital Marketers Technology: Browser-based, Standalone, Cloud-based, Mobile Applications Deployment: On-premise, Public Cloud, Private Cloud, Hybrid Customer Type: Small Enterprises, Medium Enterprises, Large Corporations, Freelancers |
| Companies Covered | CVISION Technologies, Lottery, Nanxun Information Industry, Cursor, OMR, Violet, EKEMP, BugBot, Jingnan Chuangbo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cursor Reviewer Market Trends and Innovations
Transformer-based attention mechanisms are displacing rule-based heuristics in cursor anomaly detection, while regulatory pressure on algorithmic transparency is forcing architectural bets between performance and auditability.
Neural attention layers for pointer trajectory prediction are fragmenting the competitive landscape between incumbent optical recognition vendors and deep-learning-native entrants. Software developers in San Francisco and Seattle are adopting these models for predictive latency compensation in real-time collaborative environments. The technology is fragmenting buyer segments: teams prioritizing throughput select GPU-heavy inference stacks, while compliance-focused buyers in Frankfurt and Paris favor lighter, interpretable attention variants.
EU AI Act documentation requirements for automated decision systems are compelling vendors to retrofit explainability modules into existing cursor review pipelines. Industrial consequence includes 18-24 month product roadmap delays as engineering resources shift from feature expansion to audit trail infrastructure. Medical device software teams under FDA jurisdiction are responding fastest, leveraging pre-cleared quality management systems to accelerate compliance documentation.
Subscription fatigue among mid-market software houses is compressing review-tool procurement into bundled IDE platform deals. Independent vendors are losing direct sales traction to Microsoft and JetBrains ecosystem bundling, particularly in Canadian and Australian developer markets. After-sales service unbundling is emerging as a counter-strategy: specialized consultancies in London and Singapore now sell cursor review configuration as a discrete professional service separate from software licensing.
Cursor Reviewer Market Segmentation
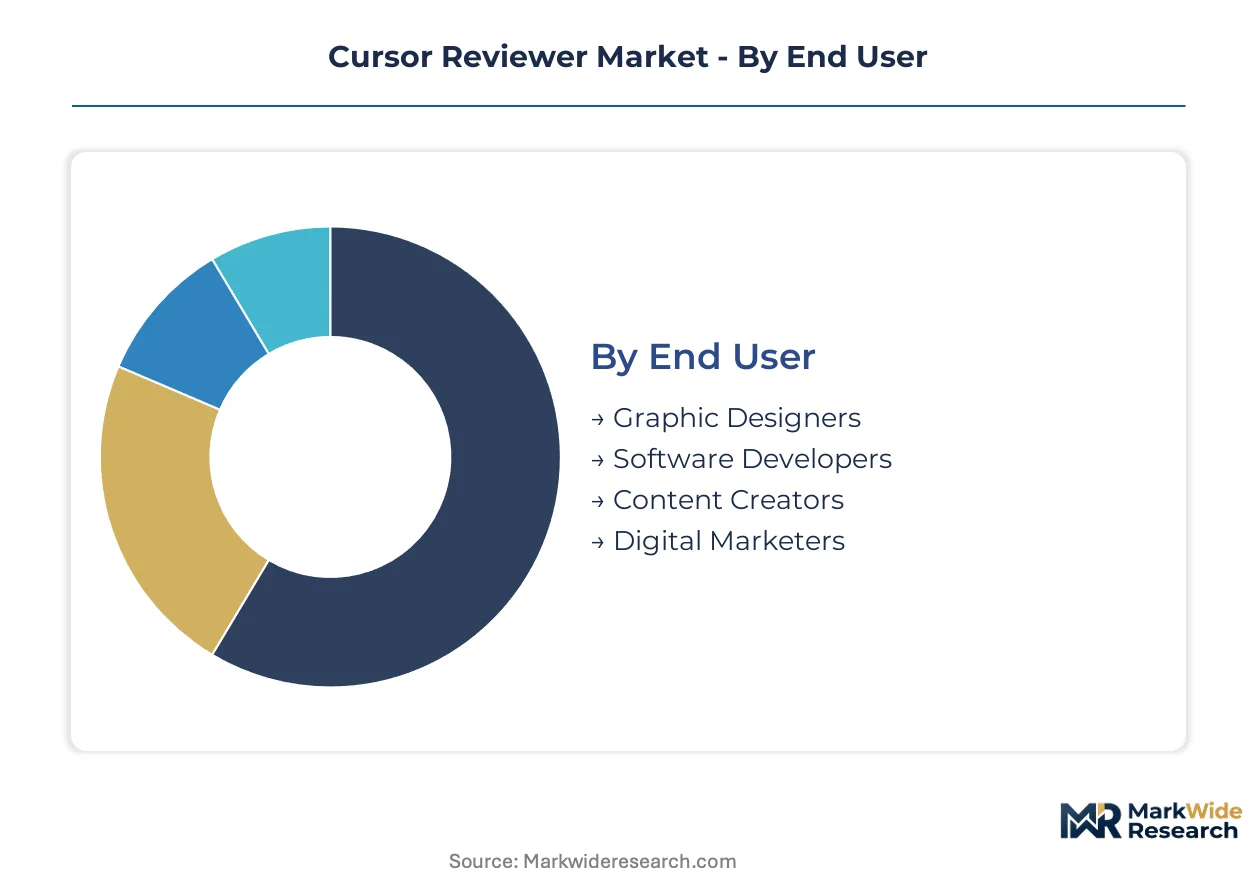
Cursor reviewer procurement patterns diverge sharply across end-user workflows, with IDE-integrated tooling dominating software development pipelines while browser-based solutions capture distributed creative teams. Understanding these segment boundaries reveals where vendor R&D investments concentrate and which deployment architectures command premium pricing.
End User:
Software developers in San Francisco and Seattle drive domestic demand concentration, while graphic designers in London and Amsterdam anchor export-led procurement for accessibility compliance tooling.
- Software Developers:Deep IDE integration requirements shape tooling specifications, with continuous validation pipelines now standard in United States and Indian DevOps environments. San Francisco's developer-tool ecosystem and Seattle's cloud infrastructure clusters anchor enterprise procurement patterns for millisecond-level sampling systems.
- Graphic Designers:Browser-based deployment preference dominates this cohort, driven by zero-install requirements for distributed creative teams across Brazilian and Mexican markets. EU AI Act transparency mandates are accelerating procurement of explainable review algorithms among Frankfurt and Paris design agencies.
- Content Creators:Mobile application interfaces capture growing traction for on-device review workflows.
- Digital Marketers:Cloud-based accessibility auditing tools are gaining adoption for campaign compliance verification.
Software developers command the established base. The steepest expansion runs through graphic designers.
Technology:
Cost-tier stratification separates GPU-heavy inference stacks from lightweight interpretable variants, with compliance-focused buyers favoring auditability over raw throughput.
- Cloud-based:Synchronous multi-user review sessions drive architecture decisions, capturing fastest growth as remote collaboration demands scale across distributed teams. NVIDIA A100/H100 allocation requirements expose vendor margins to foundry capacity constraints and cloud provider pricing power.
- Browser-based:WebAssembly-enabled on-device inference is bypassing cloud latency for Brazilian and Mexican creative teams, merging accessibility with zero-install deployment advantages. Edge-AI convergence is reshaping competitive positioning between browser-native and cloud-native vendors.
- Standalone:Air-gapped security requirements retain margin concentration among Swiss and Saudi defense and financial services buyers.
- Mobile Applications:On-device inference capabilities are emerging for field-based accessibility auditing workflows.
Cloud-based architectures capture the premium tier. Browser-based tooling is climbing the fastest.
Deployment:
Volume concentration favors public cloud among mid-market software houses, while private cloud and hybrid patterns dominate regulated sectors with data residency requirements.
- Public Cloud:Subscription bundling into IDE platform deals is compressing standalone procurement, with Microsoft and JetBrains ecosystem integration capturing Canadian and Australian developer markets. Real-time collaborative review workloads require elastic GPU allocation that public cloud providers uniquely supply.
- Private Cloud:EU AI Act documentation requirements and GDPR algorithmic transparency obligations are compelling German and French enterprises to maintain on-premise audit trail infrastructure. Medical device software teams under FDA jurisdiction leverage pre-cleared quality management systems for accelerated compliance.
- On-premise:Air-gapped installations serve Swiss and Saudi defense buyers with standalone security requirements.
- Hybrid:Split workloads between cloud inference and on-premise data retention are emerging in healthcare IT procurement.
Public cloud commands the established base. Private cloud is gaining share fastest.
Customer Type:
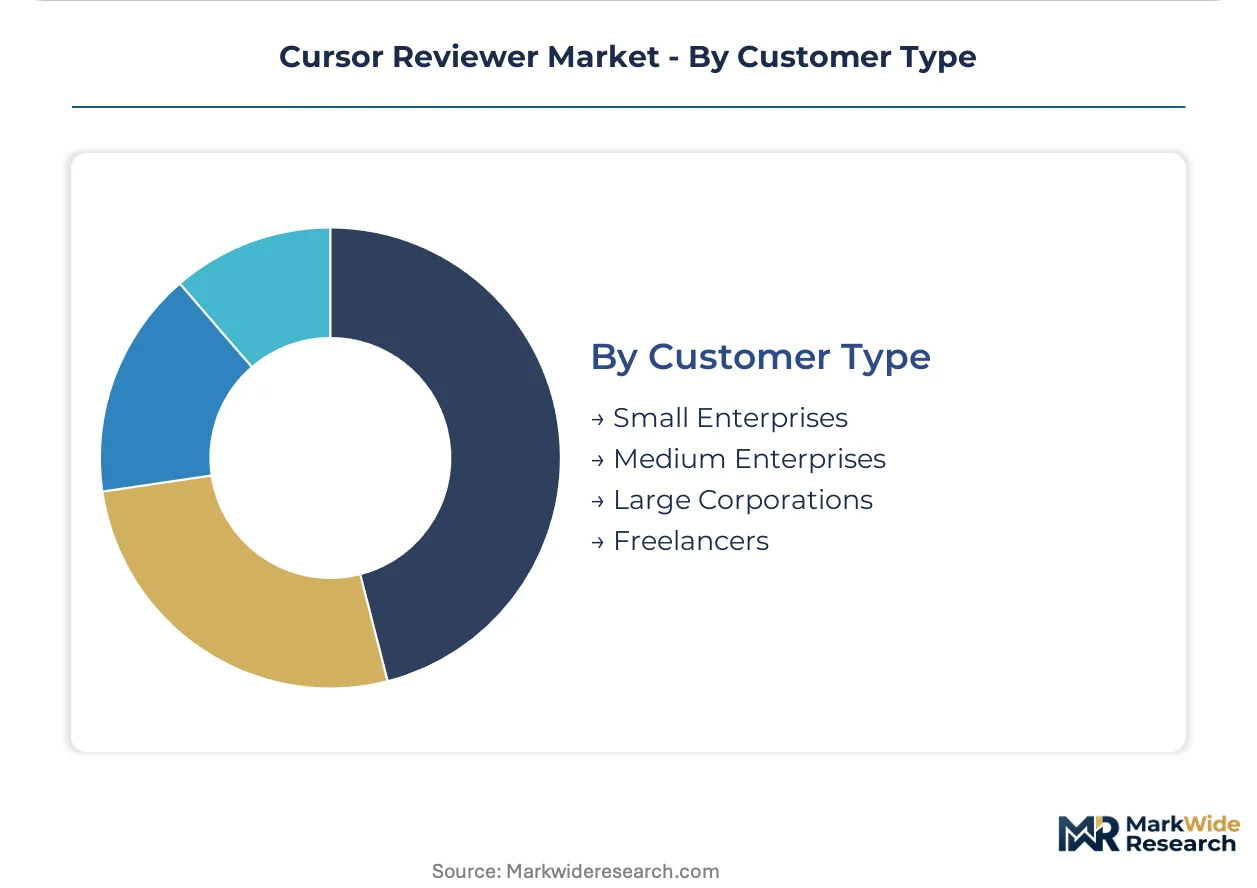
Application maturity separates legacy enterprise migrations from greenfield freelancer adoption, with mid-market software houses experiencing the most acute subscription fatigue pressures.
- Large Corporations:Pre-cleared quality management systems and established vendor relationships create compliance moats, with FDA-regulated medical device software teams replacing legacy review systems fastest. Enterprise procurement in the United States concentrates through San Francisco and Seattle clusters.
- Medium Enterprises:Bundled IDE platform deals are displacing independent vendor relationships, particularly in Canadian and Australian markets where after-sales service unbundling is emerging as a counter-strategy. London and Singapore consultancies now sell cursor review configuration as discrete professional services.
- Small Enterprises:Price-sensitive procurement favors browser-based and mobile application tooling with minimal infrastructure overhead.
- Freelancers:Individual accessibility compliance requirements are driving adoption of lightweight browser-based solutions.
Large corporations command the established base. Medium enterprises are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian public-sector buyers demonstrate the highest price elasticity, while Swiss defense contractors accept 40-60% premiums for air-gapped standalone systems. Demand concentration in San Francisco and Seattle anchors premium procurement, with Frankfurt and Paris design agencies driving explainable algorithm adoption under EU AI Act mandates.
United States
FDA guidance on medical device software cursor tracking accelerates compliance-driven replacement cycles among healthcare IT vendors. FCC sector-specific oversight of telehealth interfaces creates regulatory moats for vendors with pre-cleared quality management systems. Enterprise procurement clusters in San Francisco's developer-tool ecosystem and Seattle's cloud infrastructure hubs dominate millisecond-level sampling system acquisition.
Germany
EU AI Act transparency requirements for automated decision-making systems compel documented logic trails in cursor review tools. BSI and national data protection authorities enforce GDPR algorithmic transparency obligations that favor on-premise audit trail infrastructure. Frankfurt's financial services sector and Munich's industrial software clusters anchor demand for explainable review algorithms with human override capabilities.
India
BIS certification pathways for automated review tools open state-level procurement channels for accessibility compliance in government software tenders. DevOps teams at software houses mandate pre-commit cursor validation, converting optional tooling into infrastructure spend. Bangalore's SaaS ecosystem and Hyderabad's public-sector digitization programs drive fastest-expanding end-user adoption among software developers.
Switzerland
Swissmedic and FINMA oversight of medical device and financial software create stringent air-gapped security requirements for cursor tracking systems. Defense and financial services buyers accept standalone installations that forfeit cloud-native feature velocity. Zurich's private banking IT infrastructure and Geneva's precision manufacturing software clusters sustain margin concentration for hardware-coupled review systems.
Brazil
WebAssembly-enabled browser-based review tools gain traction among distributed creative teams seeking zero-install deployment with on-device inference. ANVISA's emerging digital health regulations create compliance preparation demand for accessibility auditing workflows. São Paulo's advertising technology sector and Rio de Janeiro's media production clusters drive adoption of lightweight, latency-bypassing review solutions.
Cursor Reviewer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the cursor reviewer landscape. GPU-heavy inference stacks command premium positioning among throughput-focused buyers, while lighter interpretable variants capture compliance-driven procurement in regulated sectors. Three archetypes dominate: IDE-integrated platform bundlers, specialized optical recognition heritage vendors, and deep-learning-native entrants. Competitive intensity concentrates on M&A activity targeting millisecond-level algorithmic auditing expertise and strategic partnerships bridging cloud-native feature velocity with air-gapped deployment capabilities.
Within the optical recognition heritage tier, CVISION Technologies represents established enterprise document-review workflows, while Nanxun Information Industry anchors geographic positioning across East Asian public-sector procurement channels. Cursor exemplifies the IDE-integrated archetype dominating software developer segments through deep platform embedding. BugBot occupies a specialist position in automated bug-detection pipelines for agile team environments. These three companies collectively illustrate the competitive fragmentation between heritage optical systems, modern IDE-native platforms, and workflow-specific automation tools.
| Leading Market Players |
|---|
| CVISION Technologies |
| Lottery |
| Nanxun Information Industry |
| Cursor |
| OMR |
| Violet |
| EKEMP |
| BugBot |
| Jingnan Chuangbo |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts for NVIDIA A100/H100 GPU allocation lock in both cloud inference access and predictable unit economics for cursor review vendors serving real-time collaborative workloads. These arrangements expose buyers to foundry pricing power while insulating margins from spot-market volatility in Taiwanese and South Korean optical sensor supply.
Pricing Analysis
After-sales configuration services now generate higher lifetime value than base software licenses as London and Singapore consultancies unbundle implementation from SaaS subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates GPU-heavy inference stacks from lightweight interpretable variants, with certification grade under EU AI Act mandates commanding measurable premiums. Cost compression in browser-based tiers is intensifying because WebAssembly-enabled edge inference reduces cloud dependency. Freelancers and small enterprises in Brazilian markets exhibit highest price sensitivity, while Swiss defense contractors accept substantial premiums for air-gapped standalone installations.
Supply Chain Analysis
Port congestion on transpacific lanes from Taiwanese semiconductor fabrication hubs to US West Coast cloud infrastructure clusters elevates inbound logistics costs for hardware-coupled review systems. Optical sensor component fabrication concentrates in Taiwan and South Korea, while GPU accelerator supply draws from NVIDIA's foundry partnerships. Single-source vulnerability in East Asian sensor supply creates procurement fragility for vendors requiring millisecond-level sampling hardware. Distribution runs through hyperscaler cloud marketplaces for public cloud deployments and specialized systems integrators for air-gapped defense installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cursor reviewer procurement is restructuring around service-attach revenue as configuration consulting and compliance documentation outpace raw software licensing growth. Recurring audit-trail infrastructure subscriptions now expand faster than IDE plugin sales among EU-regulated enterprises.
For Market Incumbents: Shield installed base relationships by deepening backward integration into optical sensor supply chains and accelerating ISO/IEC interoperability certification ahead of pending standardization mandates. Subscription fatigue among mid-market software houses threatens direct sales traction, making channel control through JetBrains and Microsoft ecosystem bundling the critical defensive lever.
For New Entrants and Emerging Players: BIS certification fast-tracks for Indian state-level government tenders open accessible procurement channels without competing against entrenched US and EU vendor relationships. White-space concentration sits with accessibility compliance auditing for CSRD-aligned ESG reporting among listed European enterprises, with browser-based WebAssembly deployment as the differentiated go-to-market angle.
For Investors and Strategic Acquirers: Millisecond-level algorithmic auditing expertise represents the scarcest acquisition target archetype as engineering talent capable of validating sub-frame latency detection commands premium multiples. Long-term viability favors vendors bridging cloud-native feature velocity with modular air-gapped deployment capabilities. The signal to watch is FDA pre-clearance queue depth for medical device software cursor tracking applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Explainable Algorithm Retrofit | EU AI Act documentation requirements force 18-24 month engineering roadmap reallocations toward audit trail infrastructure. |
| GPU Capacity Reservation | NVIDIA A100/H100 allocation agreements lock in inference economics for real-time collaborative review workloads. |
| WebAssembly Edge Deployment | On-device inference bypasses cloud latency for Brazilian and Mexican distributed creative teams. |
| After-Sales Service Unbundling | London and Singapore consultancies now sell cursor review configuration as discrete professional services. |
| Interoperability Certification | ISO and IEC standardization mandates freeze procurement decisions pending data portability clarity. |
Research Methodology
Operator-level perspectives from DevOps leads at US and Indian software houses, compliance officers at German and French enterprises, and procurement managers at Swiss defense contractors anchored the qualitative base for this analysis. Primary interviews with IDE platform engineers, accessibility consultants in Amsterdam and London, and cloud infrastructure architects in Seattle combined with secondary validation from SEC filings of publicly traded developer-tool vendors, EU AI Act implementation guidance documents, and FDA medical device software guidance records. Bottom-up deployment modeling across end-user segments triangulated against top-down market sizing from cloud provider GPU allocation disclosures.
Sensitivity analysis tested forecast robustness across scenarios varying EU AI Act enforcement timelines, NVIDIA foundry capacity expansion, and ISO/IEC standardization adoption curves. Segmentation dimensions modeled include deployment architecture, end-user workflow type, organization scale, geographic regulatory cluster, and integration complexity tier. CAGRs were derived from weighted regression against historical IDE tooling adoption patterns and projected DevOps pipeline embedding rates. Industry-specific forecast inputs encompassed BIS certification pathway velocity for Indian public-sector tenders and FDA pre-clearment queue dynamics for medical device software applications.
Underlying assumptions cover continuous integration pipeline standardization, GPU cloud pricing stability, and EU algorithmic transparency enforcement consistency, with deviation risk concentrated in East Asian optical sensor supply disruptions and pending interoperability mandate delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Programming Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Global Architect Software Market
Software & Services
Communication Software Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Document Capture Software Market
Software & Services
Professional Service Automation Market
Software & Services
Global Custom Software Development Services Market
Software & Services
SRM Software Market
Software & Services
Global Smartphone Operating System (OS) Market
Software & Services
Parametric Design Software Market
Software & Services
Small Business Manufacturing Software Market
Software & Services
Human Capital Management (HCM) Saas Market
Software & Services
Global Data Entry Software Market
Software & Services
Advanced Mobile UX Design Services Market
Software & Services
Global Android Kiosk Software Market