
 Global Data Entry Software Market | 2026-2036
Global Data Entry Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Entry Software Market Foresight
Optical character recognition is consolidating as the dominant input modality, displacing legacy manual keystroke workflows across enterprise environments. Foxtrot RPA leverages robotic process automation to anchor high-volume document processing for financial services clients. ProntoForms competes through mobile-first field data collection, while Typeform differentiates via conversational interfaces that reduce form abandonment rates.
Data entry software encompasses platforms that capture, validate, and route structured information through automated recognition engines, API connectors, and workflow orchestration layers, typically processing fields at throughput rates exceeding human operators by orders of magnitude. Cloud-based deployment leads current adoption curves due to elastic scaling and reduced infrastructure overhead, while intelligent character recognition represents the fastest-expanding solution type as machine learning models improve accuracy on handwritten and degraded source documents. The invoice processing use case commands disproportionate margin pools given the compliance stakes and volume density within accounts payable functions.
The EU AI Act imposes risk-tiered obligations on automated data processing systems, compelling vendors to embed audit trails and human oversight mechanisms. FDA guidelines for electronic records in healthcare settings, alongside India's BIS data localization frameworks, shape product roadmaps and market access conditions across three distinct regulatory spheres. Stakeholders must monitor evolving cross-border data governance regimes to anticipate compliance costs that could alter total cost of ownership calculations.
Market Dynamics
The EU AI Act is compressing vendor timelines for embedding explainability and human oversight into automated data capture systems, forcing architecture redesigns ahead of enforcement deadlines.
Growth Catalysts
- Healthcare digitization:FDA guidelines for electronic records in clinical settings are mandating audit-ready data trails, pulling automated capture tools into hospital IT stacks.
- India's back-office expansion:Enterprises in Mumbai and Bangalore are digitizing legacy paper workflows, creating concentrated demand for intelligent character recognition at scale.
- Cloud elasticity:Elastic scaling capabilities are reducing infrastructure overhead for mid-market buyers, accelerating deployment timelines without capital commitment.
Market Restraints
- Handwritten accuracy ceilings:Intelligent character recognition still exhibits error rates on degraded source documents that exceed human transcription thresholds in legal and medical contexts.
- Cross-border data friction:India's BIS data localization frameworks are fragmenting cloud architectures, compelling vendors to maintain sovereign infrastructure copies.
- API integration debt:Legacy enterprise resource planning systems require custom connector development, extending implementation cycles and professional services dependency.
Strategic Opportunities
- Mobile field deployment:First-line workers in utilities and logistics are adopting smartphone-based capture, opening white space beyond desktop-centric legacy installations.
- Conversational form interfaces:Chat-based data collection is reducing abandonment rates in customer-facing applications, displacing static web forms in financial services onboarding.
- EU compliance services:The AI Act's risk-tiered obligations are creating attach-rate potential for audit-trail modules and human-in-the-loop verification layers.
Industry Challenges
- Machine learning operations talent:Vendors face scarcity of engineers capable of deploying and maintaining production-grade document recognition models at enterprise scale.
- Legacy system interoperability:Mainframe-era databases in financial services resist standard API protocols, forcing brittle screen-scraping fallbacks that break on interface updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Entry Software Market |
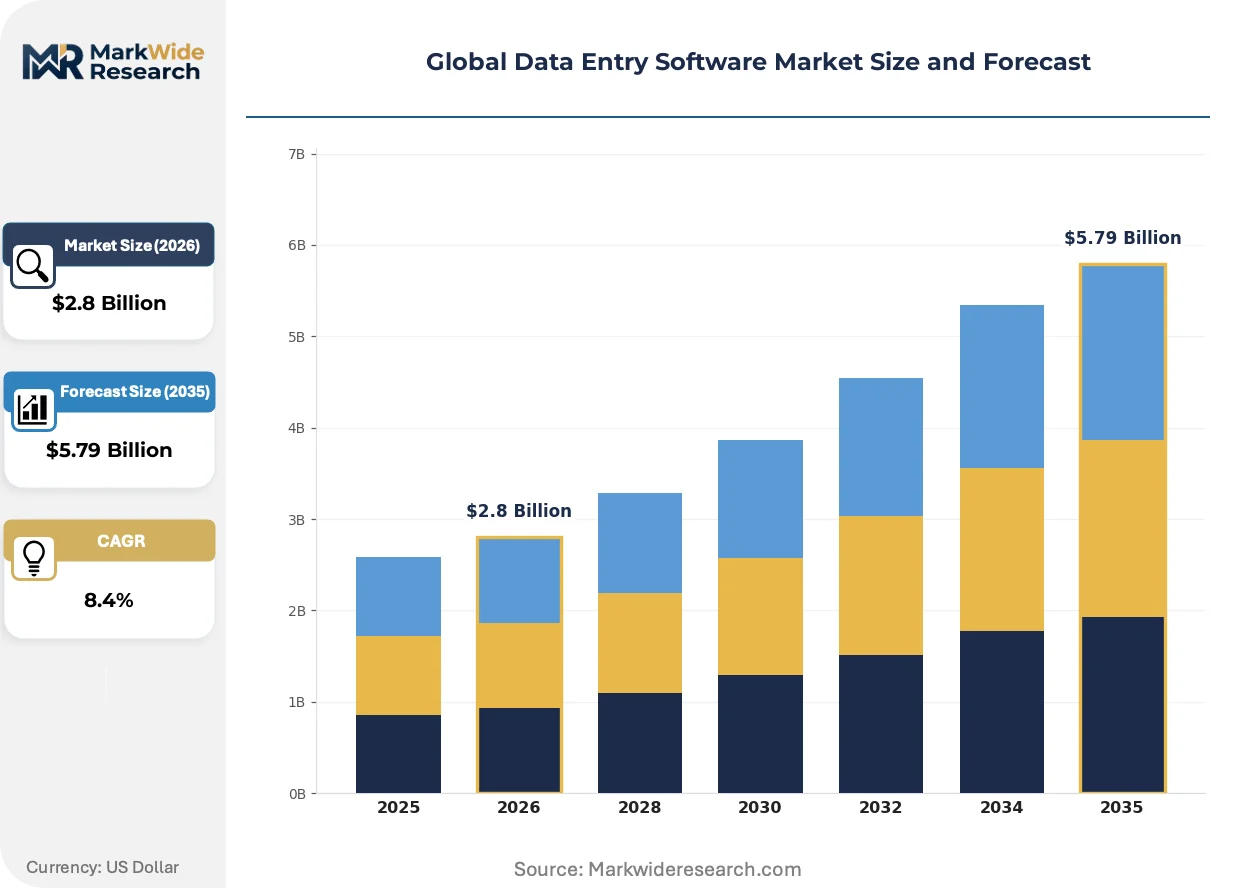
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, SaaS Solution Type: Optical Character Recognition, Intelligent Character Recognition, Automated Forms Processing, Manual Data Entry, Voice Recognition Use Case: Invoice Processing, Customer Data Management, Inventory Tracking, Form Digitization, Survey Data Entry End User: BFSI Firms, Government Agencies, Educational Institutions, Legal Entities, Telecommunications Providers |
| Companies Covered | Foxtrot RPA, ProntoForms, Infinity, Tabidoo, FastField, Zoho Forms, Typeform, Form Tools, Entrypoint i4, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Entry Software Market Shifts & Advancements
Machine learning architectures are compressing accuracy thresholds for degraded document sources, while regulatory pressure is hardening compliance requirements across automated decision systems.
Optical character recognition is consolidating as the dominant input modality across enterprise environments. Financial services operations teams are deploying recognition engines at throughput rates that displace manual keystroke workflows entirely. This consolidation is compressing pricing for basic transcription services while concentrating margin in vertical-specific accuracy tuning.
The EU AI Act imposes risk-tiered obligations on automated data processing systems with enforcement timelines accelerating through 2025. Vendors must embed audit trails and human oversight mechanisms into production architectures or face market access restrictions. Healthcare and financial services segments are responding by pre-emptively procuring compliance-certified platforms ahead of formal deadlines.
Buyer procurement patterns are compressing vendor evaluation cycles as IT departments prioritize rapid deployment over extended pilot phases. Subscription pricing models are displacing perpetual licenses in mid-market accounts, unbundling implementation services from core software fees. This shift is most visible in India, where digitization mandates are forcing accelerated procurement decisions across back-office functions.
Global Data Entry Software Market Segmentation
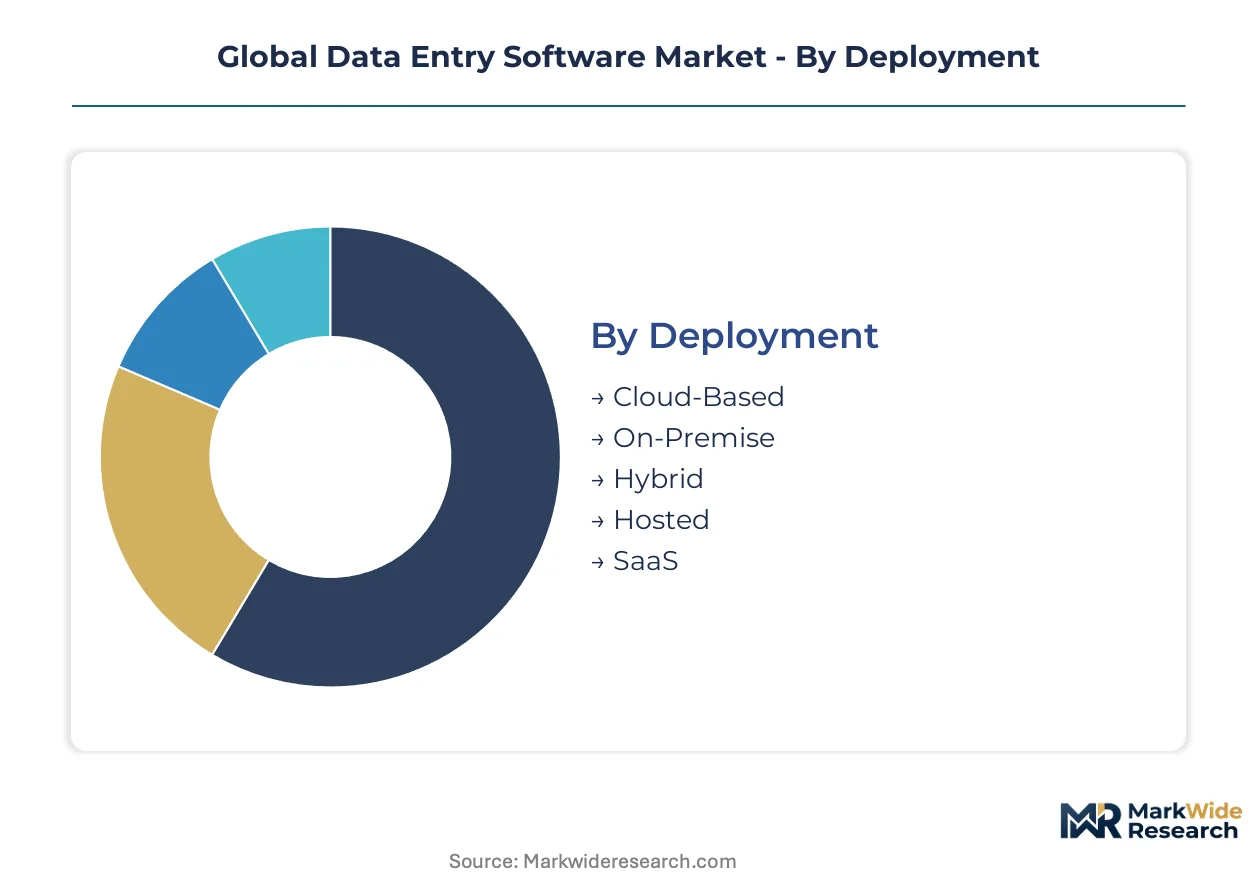
Segmentation in data entry software reveals how deployment flexibility, recognition technology sophistication, and vertical-specific compliance requirements reshape procurement decisions. Buyers trade off customization depth against implementation velocity across each dimension.
Deployment:
Customization-vs-standardization tension runs deepest here — cloud-native configurations sacrifice tailoring for speed while on-premise installations preserve control at infrastructure cost.
- Cloud-Based:Elastic infrastructure scales processing throughput without capital commitment. Demand concentrates among mid-market enterprises in India digitizing back-office operations under compressed timelines.
- On-Premise:Dedicated hardware maintains data sovereignty for regulated workloads. BFSI firms in Frankfurt and Singapore deploy these configurations to satisfy EU AI Act audit trail requirements and local financial authority mandates.
- Hybrid:Split architectures route sensitive processing on-premise while burst workloads hit cloud capacity.
- Hosted:Managed single-tenant deployments reduce internal IT burden without multi-tenancy exposure.
- SaaS:Standardized multi-tenant platforms minimize per-seat pricing through shared infrastructure economics.
Leading the category by volume: Cloud-Based. Expanding most quickly: Hybrid.
Solution Type:
Recognition accuracy thresholds stratify pricing tiers — machine learning-powered engines command premium positioning over rules-based optical systems.
- Optical Character Recognition:Pattern-matching algorithms extract text from scanned documents with deterministic rule sets. Financial services operations in London and New York deploy these engines at throughput rates displacing manual keystroke workflows.
- Intelligent Character Recognition:Neural architectures learn character deformations from training corpora. Healthcare providers in Boston and Mumbai adopt these systems to process degraded handwritten clinical records where error tolerance narrows.
- Automated Forms Processing:Template-driven extraction normalizes structured document layouts into database fields.
- Manual Data Entry:Human-in-the-loop interfaces handle exception routing and quality verification.
- Voice Recognition:Acoustic models transcribe spoken input for hands-free field data capture.
Volume leadership: Optical Character Recognition. Steepest expansion trajectory: Intelligent Character Recognition.
Use Case:
Compliance stakes and transaction density determine margin capture — invoice processing carries regulatory weight that survey entry lacks.
- Invoice Processing:Three-way matching algorithms validate purchase orders against receipts and payment authorizations. Accounts payable functions in German automotive supply chains embed these tools to satisfy tax authority documentation requirements.
- Customer Data Management:Identity verification pipelines standardize onboarding information across CRM systems. Telecommunications providers in Brazil and Saudi Arabia deploy these capabilities to meet national identity registry mandates.
- Inventory Tracking:Barcode and RFID integration maintains real-time stock position accuracy.
- Form Digitization:Paper-to-digital conversion streamlines legacy document backlogs.
- Survey Data Entry:Structured response capture supports market research and census operations.
Invoice Processing commands the largest revenue pool. Customer Data Management gains share fastest.
End User:
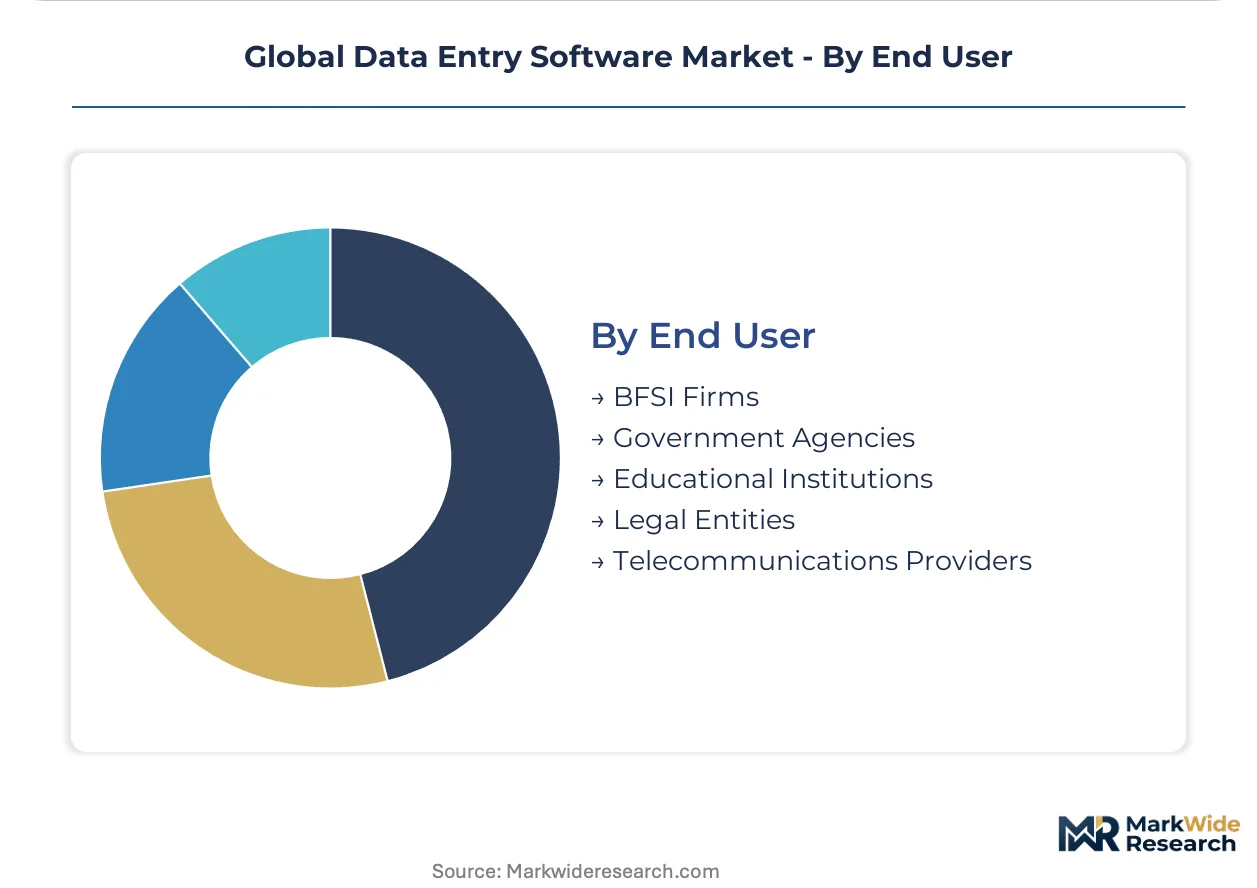
Procurement sophistication varies — BFSI buyers negotiate enterprise terms while government agencies prioritize certification compliance over price.
- BFSI Firms:Trading floors and retail banking operations process high-velocity transaction streams. JPMorgan Chase and HSBC procurement teams specify sub-second latency requirements for real-time data capture in foreign exchange operations.
- Government Agencies:Citizen service portals and tax administration systems demand audit-grade documentation. India's UIDAI and Brazil's Receita Federal mandate localized data residency for biometric and fiscal records.
- Educational Institutions:Student information systems and research data management drive adoption.
- Legal Entities:Discovery and contract review workflows require privileged information handling.
- Telecommunications Providers:Subscriber provisioning and billing integration create recurring processing volumes.
BFSI Firms dominate current spend. Government Agencies show the fastest procurement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the most intense procurement activity as enterprises digitize back-office operations under compressed timelines. Germany and the United States anchor compliance-heavy deployments driven by regulatory mandates. Japan and Brazil round out the five-country view with distinct sectoral drivers.
United States
Healthcare providers in Boston and New York are expanding automated capture tools to satisfy FDA electronic records guidelines. The FDA mandates audit-ready data trails for clinical settings, pulling recognition engines into hospital IT stacks. Financial services operations in Manhattan deploy sub-second latency capture systems for foreign exchange transaction streams.
Germany
Automotive supply chains in Stuttgart and Wolfsburg embed invoice processing tools to satisfy tax authority documentation requirements. The EU AI Act imposes risk-tiered obligations on automated data processing systems, compelling architecture redesigns ahead of enforcement deadlines. BFSI firms in Frankfurt maintain on-premise deployments to satisfy local financial authority mandates.
India
Enterprises in Mumbai and Bangalore are digitizing legacy paper workflows, creating concentrated demand for intelligent character recognition at scale. BIS data localization frameworks fragment cloud architectures, compelling vendors to maintain sovereign infrastructure copies. Back-office operations in Hyderabad and Pune drive subscription pricing adoption over perpetual licenses.
Japan
Manufacturing operations in Osaka and Nagoya deploy mobile field capture for utilities and logistics first-line workers. METI industrial digitization programs accelerate smartphone-based data collection beyond desktop-centric legacy installations. Healthcare providers in Tokyo adopt neural recognition architectures to process degraded handwritten clinical records.
Brazil
Telecommunications providers in São Paulo deploy customer data management pipelines to meet national identity registry mandates. ANVISA regulatory frameworks shape product roadmaps for pharmaceutical data capture systems. Financial services operations in Rio de Janeiro process high-velocity transaction streams through automated recognition engines.
Global Data Entry Software Market Competitive Landscape
Portfolio diversification dominates the current landscape as vendors unbundle implementation services from core software fees. The vendor base stratifies across three tiers: cloud-native specialists, mobile-first field capture providers, and conversational interface platforms. Two strategic archetypes occupy distinct positions — robotic process automation anchors and form-builder SaaS platforms. M&A activity and geographic expansion represent the dominant competitive moves as players acquire regional compliance expertise and establish sovereign infrastructure copies.
Within the RPA anchor tier, Foxtrot RPA exemplifies high-volume document processing positioning for financial services clients. Among mobile-first specialists, ProntoForms and FastField occupy positions serving field data collection requirements in utilities and logistics. Typeform sits within the conversational interface archetype, representing chat-based data collection approaches that reduce form abandonment rates in customer-facing applications.
| Leading Market Players |
|---|
| Foxtrot RPA |
| ProntoForms |
| Infinity |
| Tabidoo |
| FastField |
| Zoho Forms |
| Typeform |
| Form Tools |
| Entrypoint i4 |
| Others |
Supply & Pricing Matrix
EU AI Act compliance mandates gate both qualified supply and premium-tier pricing access, forcing vendors to embed audit trails and human oversight mechanisms before commanding subscription premiums. Cloud-native providers in India and the United States absorb infrastructure costs to maintain elasticity, while on-premise specialists in Germany and Singapore capture margin through sovereignty guarantees.
Pricing Analysis
Volume-vs-margin splits sharply across deployment models. SaaS multi-tenant platforms anchor the economy tier through shared infrastructure economics, while hybrid configurations with sovereign cloud components command standard-tier premiums. On-premise installations with EU AI Act certification support premium positioning among Frankfurt BFSI firms. Price differentiation rests on compliance certification depth and vertical-specific accuracy tuning. Pricing pressure stems from OCR commoditization in basic transcription services. Mid-market enterprises in India exhibit highest price sensitivity; German automotive supply chains show lowest sensitivity due to tax authority documentation stakes.
Supply Chain Analysis
Certification and qualification gating concentrates supply among vendors with FDA, EU AI Act, and BIS framework attestations. Cloud infrastructure draws from hyperscaler regions in the United States, Ireland, and Singapore, with sovereign copies maintained in India per BIS localization mandates. Neural recognition model training feeds from annotated document corpora sourced through healthcare and financial services partnerships. Single-source vulnerability runs through NVIDIA GPU supply for ICR model training workloads. Distribution runs through direct enterprise sales teams and systems integrators with vertical specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race into compliance-certified infrastructure layers, with players pursuing sovereign cloud deployments to satisfy data localization mandates.
For Market Incumbents: To counter margin compression in basic OCR services, deepen in-house production of ICR training pipelines and neural model architectures. Acquire regional compliance expertise in India and Brazil to pre-empt BIS and ANVISA framework evolution. Lock channel control through systems integrator partnerships with hospital IT and automotive supply chain specialists.
For New Entrants and Emerging Players: The premium-economy price-point gap in mobile field capture creates white-space entry around utilities and logistics first-line workers. Target smartphone-native deployment in Japan's METI digitization programs and Brazil's telecommunications sector. Pursue conversational interface differentiation to displace static web forms in financial services onboarding workflows.
For Investors and Strategic Acquirers: EU AI Act enforcement timeline acceleration is the leading indicator that compliance-certified platform valuations will detach from commodity OCR providers. Favor acquisition targets with sovereign infrastructure copies in India and hybrid deployment capabilities across Frankfurt and Singapore. Watch for FDA 21 CFR Part 11 audit trail certification as the inflection signal for healthcare segment premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API connector libraries reduce ERP implementation cycles for JPMorgan Chase procurement specifications. |
| Geographic Expansion | Sovereign cloud deployments in Mumbai and Bangalore satisfy BIS data localization frameworks. |
| Acquisition of Specialist Firm | Mobile field capture capabilities extend reach into Osaka utilities and Nagoya logistics operations. |
| Strategic Partnership | Systems integrator alliances accelerate hospital IT stack penetration in Boston and New York. |
| Product Launch | Human-in-the-loop verification modules attach to EU AI Act risk-tiered obligations. |
Research Methodology
Multi-period observation of deployment model adoption curves and regulatory enforcement timelines anchored the trend analysis, supplemented by interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across financial services, healthcare, and telecommunications verticals. Secondary validation drew from SEC filings, hyperscaler capex disclosures, FDA 21 CFR Part 11 guidance documents, and EU AI Act implementation texts. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Segment-weighting approaches distributed value across cloud, on-premise, hybrid, hosted, and SaaS deployment configurations, further stratified by OCR, ICR, automated forms processing, manual data entry, and voice recognition solution types. CAGRs were derived from elasticity-adjusted adoption curves and compliance-driven procurement acceleration patterns. Forecast inputs incorporated BFSI latency requirements, healthcare audit trail mandates, and India's back-office digitization velocity.
Inputs from regulatory filing databases and enterprise procurement systems were available through the study window; gaps in real-time vendor pricing disclosure introduce uncertainty bands around segment-level value estimates. Forecasts reflect assumptions regarding EU AI Act enforcement consistency and BIS framework stability. A model refresh is warranted upon material change in FDA electronic records guidance or India's data localization enforcement posture.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Voip Software Market
Software & Services
Ad Creation Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Global ERP Software Market
Software & Services
Global Blue Prism Technology Services Market
Software & Services
Global Integration Software Market
Software & Services
Global Inspection Management Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Content Marketing Software Market
Software & Services
Global Online OCR Software Market
Software & Services
HR Saas Market
Software & Services
Global Gamification Software Market
Software & Services
Embedded Software Market
Software & Services
Global Mobile Application Market
Software & Services
Pure Play Software Testing Market
Software & Services
Cemetery Software Market