
 Landscaping Engineering Software Market | 2026-2036
Landscaping Engineering Software Market Size, Share, and Industry Trends Forecast 2026-2036
Landscaping Engineering Software Market Insights
North American software development capacity is realigning around cloud-native architectures for outdoor infrastructure design. Autodesk Civil 3D leverages deep integration with civil engineering workflows to sustain dominance in complex grading and drainage projects. Vectorworks Landmark competes through specialized BIM tools tailored to landscape architects, while DynaSCAPE Software anchors its position in the mid-market residential design segment through purpose-built planting and hardscape libraries.
Landscaping engineering software encompasses digital tools that integrate terrain modeling, irrigation hydraulics, plant material databases, and construction documentation into unified design environments. These platforms process topographic survey data, soil composition parameters, and climatic variables to generate buildable plans that satisfy municipal permitting requirements. Design Tools and Estimation Software command the largest current revenue pools, as landscape contractors prioritize visualization capabilities alongside automated material takeoffs to compress bid cycles. Cloud-Based deployment is expanding fastest among municipal and multi-office landscape architecture firms seeking real-time collaboration across distributed project teams.
EPA stormwater regulations and municipal green infrastructure codes in the United States shape product roadmaps by mandating permeable surface calculations and retention volume verification within design deliverables. ISO 19650 BIM standards and the EU Green Deal's urban nature restoration targets are pressing European developers to specify software with embedded carbon accounting and biodiversity metric reporting. Stakeholders must evaluate whether their current platforms can absorb emerging regulatory modules without fragmentating project workflows across incompatible toolchains.
Market Dynamics
Cloud-native deployment architectures are forcing incumbent vendors to re-platform legacy desktop applications while municipal procurement offices mandate SaaS compliance for multi-vendor bidding access.
Growth Catalysts
- EPA stormwater regulations:Municipal green infrastructure mandates in the United States require permeable surface calculations and retention volume verification, embedding hydraulic modeling tools into standard design workflows.
- Sun Belt metropolitan development:Intense construction activity across Phoenix, Austin, and Atlanta intersects with water conservation requirements, concentrating demand for irrigation-integrated design platforms.
- BIM standardization:ISO 19650 compliance requirements in public infrastructure procurement are pushing landscape architecture firms toward unified data environments that span concept through construction documentation.
Market Restraints
- Specialized talent scarcity:The intersection of civil engineering hydraulics, botanical science, and computational design creates recruitment bottlenecks for firms scaling digital operations.
- Legacy data migration costs:Decades of project archives in proprietary formats impose switching friction that anchors mid-market contractors to incumbent vendors despite feature gaps.
- Hardware-software coupling:Precision GPS survey equipment and drone photogrammetry systems require vendor-specific file formats, fragmenting toolchain interoperability.
Strategic Opportunities
- Carbon accounting modules:The EU Green Deal's urban nature restoration targets create openings for embedded biodiversity metric reporting and embodied carbon calculators in European deployments.
- Residential contractor SaaS:Purpose-built estimation and visualization tools for single-family landscape installers remain underpenetrated relative to commercial and municipal segments.
- AR field verification:Convergence of tablet-based design files with augmented reality overlay is compressing change-order cycles by enabling real-time as-built comparison during construction.
Industry Challenges
- Cross-disciplinary workflow integration:Landscape architects, civil engineers, and irrigation contractors operate in siloed software environments, forcing manual file translation and version-control failures.
- Municipal certification timelines:Permitting authorities in water-stressed jurisdictions require hydraulic performance verification that exceeds standard software output formats, necessitating custom engineering overlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Landscaping Engineering Software Market |
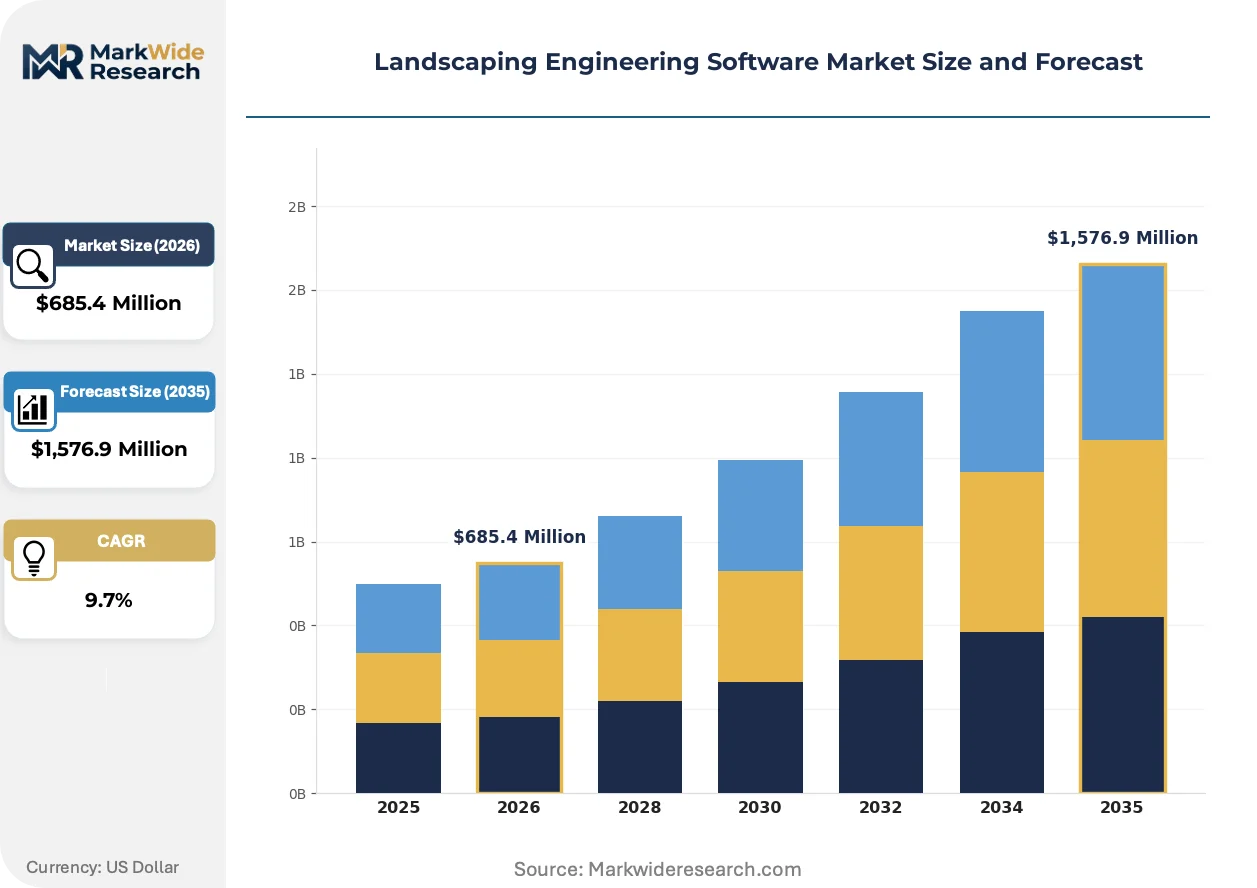
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,576.9 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Design Tools, Project Management, Simulation Software, Estimation Software End User: Landscapers, Architects, Civil Engineers, Municipalities Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Application: Residential Landscaping, Commercial Landscaping, Urban Planning, Golf Course Design |
| Companies Covered | Jobber, Service Autopilot, DynaSCAPE Software, Aspire, Vectorworks Landmark, Autodesk Civil 3D, Realtime Landscaping Architect, Land F/X, Arborgold, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Landscaping Engineering Software Market Trends and Innovations
Generative design algorithms and real-time collaboration protocols are compressing project timelines while embedding compliance verification into iterative design loops rather than post-hoc documentation.
Parametric planting design engines are modularizing how landscape architects configure biome-appropriate species palettes. Mid-size firms in the United States are adopting these tools fastest as they bid municipal restoration projects requiring native plant compliance. The technology is modularizing what were previously bespoke horticultural consulting engagements into self-service configuration workflows.
REACH chemical restriction frameworks in Europe are reshaping material specification databases within design software. Embedded substance-of-concern flags now trigger automatic substitution suggestions when hardscape products violate evolving toxicity thresholds. German and Dutch landscape architecture practices report the highest adoption rates as their procurement policies anticipate stricter F-Gas Regulation extensions to outdoor equipment.
Subscription pricing is displacing perpetual licensing across municipal and multi-office firms. Annual SaaS commitments now dominate RFP requirements for public sector landscape design contracts, with procurement officers prioritizing real-time collaboration features over offline capability. This shift is most visible in United States Sun Belt cities where distributed project teams span satellite offices and remote field staff.
Landscaping Engineering Software Market Segmentation
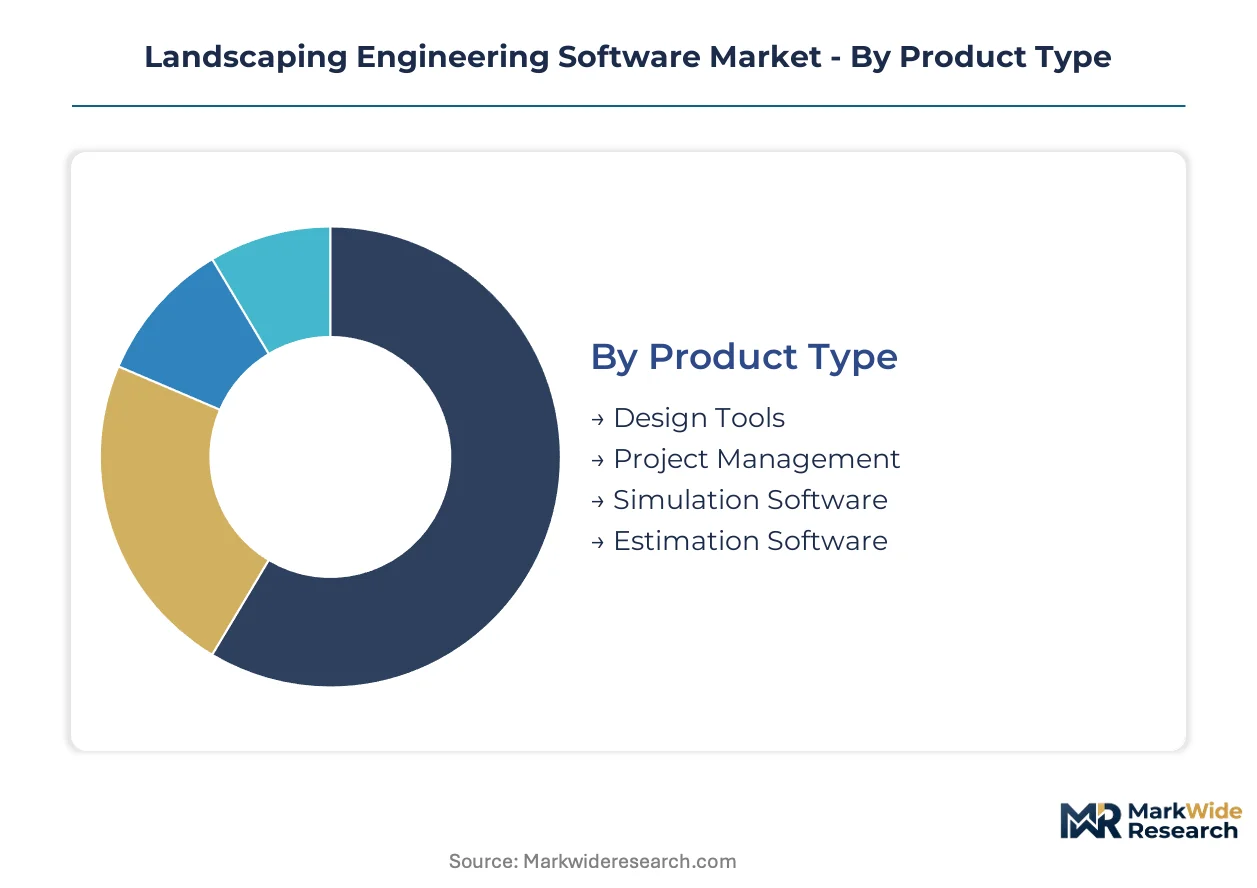
Segmentation in landscaping engineering software reveals how capital intensity, regulatory exposure, and workflow complexity concentrate purchasing power across distinct user archetypes. Vendors must align product architecture with the specific compliance burdens and collaboration requirements of each segment.
Product Type:
Capital intensity varies sharply across product categories, with simulation and estimation platforms demanding the heaviest upfront development investment in hydraulic modeling engines and material database maintenance.
- Design Tools:Terrain modeling, planting configuration, and hardscape layout capabilities form the core visualization layer. Demand concentrates among commercial landscape architects in Phoenix, Austin, and Atlanta where municipal green infrastructure codes require permeable surface calculations embedded directly into design deliverables.
- Estimation Software:Automated material takeoff engines integrate with supplier pricing feeds to compress bid cycles. Residential contractors across Sun Belt metropolitan areas prioritize these tools to compete for water-conservation-focused installations where irrigation component costs dominate project economics.
- Project Management:Scheduling and resource allocation modules track crew deployment across multiple job sites.
- Simulation Software:Hydraulic performance modeling validates stormwater retention volumes against EPA regulations.
Most installed capacity flows through Design Tools. Expansion is steepest in Estimation Software.
End User:
Customer sophistication determines pricing tolerance and feature requirements, with civil engineers and municipalities demanding the most extensive compliance documentation capabilities.
- Civil Engineers:Grading, drainage, and utility coordination workflows require deep integration with civil engineering platforms. Firms in water-stressed jurisdictions across the United States anchor demand for hydraulic verification tools that exceed standard software output formats.
- Municipalities:Procurement offices mandate SaaS compliance for multi-vendor bidding access and prioritize real-time collaboration features. Sun Belt cities with distributed project teams span satellite offices and remote field staff, driving cloud-native requirements into RFP specifications.
- Landscapers:Residential and commercial installation contractors prioritize visualization and estimation speed over compliance depth.
- Architects:Landscape architecture practices require BIM-compliant data environments spanning concept through construction documentation.
Civil Engineers command the highest per-seat pricing. Municipalities are expanding most quickly as procurement digitization accelerates.
Deployment:
IT infrastructure requirements and data sovereignty concerns shape deployment preferences, with hybrid architectures capturing firms navigating legacy system transitions.
- Cloud-Based:Real-time collaboration protocols enable distributed project teams to synchronize design iterations across locations. Municipal and multi-office landscape architecture firms in the United States adopt these platforms fastest as procurement officers prioritize SaaS compliance for public sector contracts.
- On-Premise:Perpetual licensing persists among mid-market contractors with decades of project archives in proprietary formats that impose switching friction.
- Hybrid:Combines local processing for compute-intensive terrain modeling with cloud storage for document management.
- Mobile:Tablet-based field verification with augmented reality overlay compresses change-order cycles during construction.
Cloud-Based deployment hosts the majority of new installations. Mobile is gaining share fastest among residential contractors.
Application:
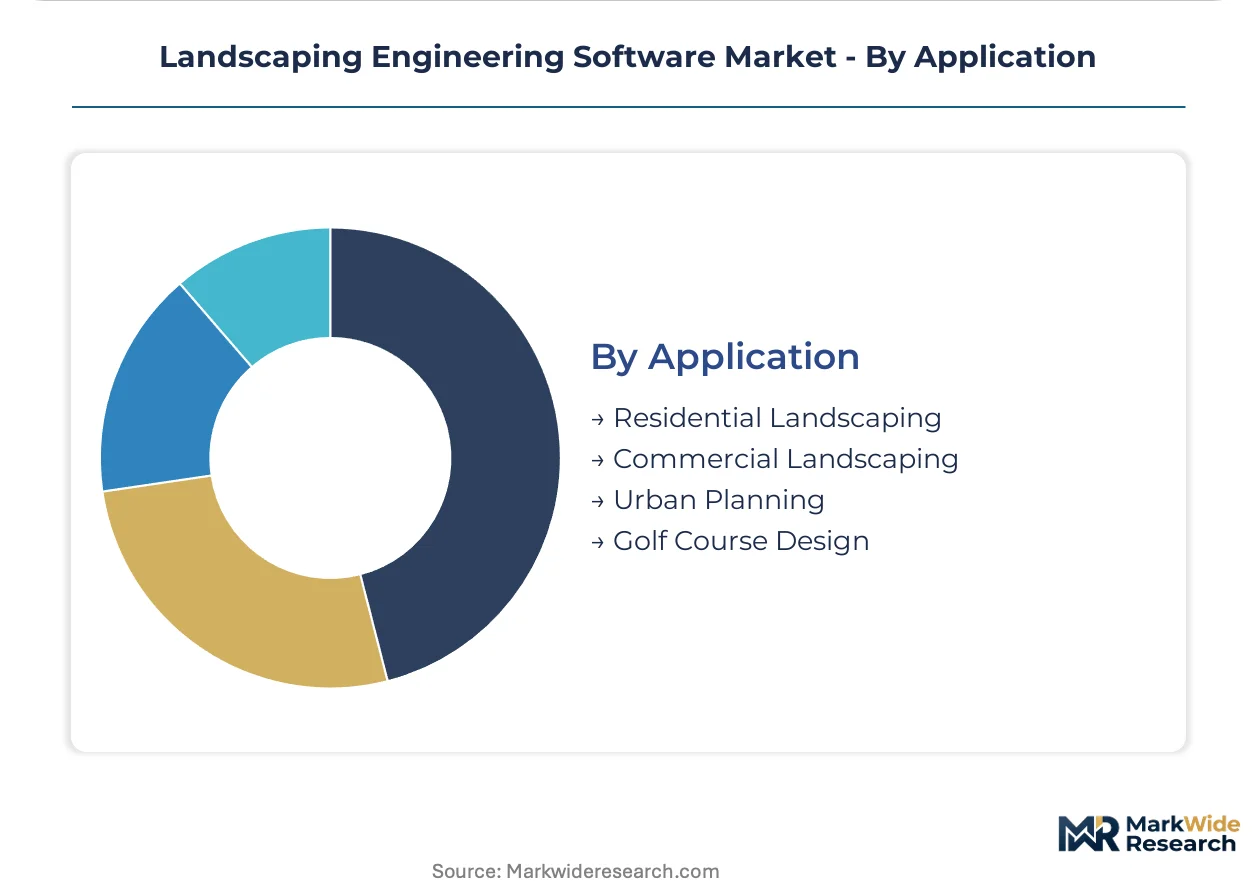
Project scale and regulatory exposure create distinct software requirements, with urban planning and golf course design representing opposite poles of complexity and standardization.
- Commercial Landscaping:Large-scale installations require multi-discipline coordination across landscape architects, civil engineers, and irrigation contractors. EPA stormwater regulations and municipal green infrastructure mandates in the United States embed hydraulic modeling into standard workflows for this segment.
- Urban Planning:Public infrastructure procurement requires ISO 19650 BIM compliance and embedded carbon accounting capabilities. EU Green Deal urban nature restoration targets press European developers toward biodiversity metric reporting.
- Residential Landscaping:Single-family landscape installers prioritize purpose-built estimation and visualization tools.
- Golf Course Design:Specialized irrigation hydraulics and terrain sculpting requirements demand precision GPS survey integration.
Commercial Landscaping absorbs the largest software investment. Urban Planning is climbing the fastest as green infrastructure mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between jurisdictions are redirecting software development investment toward markets with streamlined regulatory pathways for cloud-native infrastructure tools. EPA mandates in the United States impose stricter hydraulic verification requirements than EU counterparts, concentrating premium platform development in American engineering corridors.
United States
Sun Belt metropolitan construction drives concentrated demand for irrigation-integrated design platforms across Phoenix, Austin, and Atlanta. EPA stormwater regulations embed permeable surface calculations into standard municipal procurement specifications. Cloud-native deployment dominates RFP requirements in water-stressed jurisdictions where distributed project teams span satellite offices and remote field staff.
Germany
REACH chemical restriction frameworks reshape material specification databases within landscape design software platforms. German landscape architecture practices lead European adoption of embedded substance-of-concern flags that trigger automatic substitution suggestions. Bavarian engineering clusters concentrate development of BIM-compliant carbon accounting modules anticipating stricter F-Gas Regulation extensions.
United Kingdom
ISO 19650 compliance requirements in public infrastructure procurement push landscape architecture firms toward unified data environments. London-based practices anchor demand for biodiversity metric reporting tools aligned with emerging urban nature restoration standards. Southeast England municipal procurement offices mandate SaaS compliance for multi-vendor bidding access.
Canada
Health Canada and PMRA chemical oversight influences material database configurations in cross-border platform deployments. Ontario engineering firms prioritize hydraulic modeling tools that satisfy both domestic stormwater codes and American EPA equivalency requirements. Toronto and Vancouver metropolitan procurement offices accelerate cloud migration timelines for distributed design teams.
Australia
TGA-aligned environmental standards and water conservation mandates in drought-prone states concentrate demand for irrigation optimization platforms. New South Wales and Victoria municipal procurement specifications increasingly require real-time collaboration features for multi-office landscape architecture firms. Sydney engineering clusters drive adoption of mobile field verification tools with augmented reality overlay capabilities.
Landscaping Engineering Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized compliance modules and vertical workflow integration. The vendor base stratifies across three maturity tiers: legacy desktop incumbents re-platforming toward cloud-native architectures, mid-market specialists with purpose-built planting and hardscape libraries, and venture-backed challengers attacking field verification and augmented reality niches. Dominant competitive moves include strategic partnerships with precision GPS equipment manufacturers and portfolio diversification into carbon accounting and biodiversity reporting modules.
Within the specialized BIM tier, Vectorworks Landmark and DynaSCAPE Software occupy distinct positioning archetypes that exemplify alternative pathways for landscape-specific feature depth. Autodesk Civil 3D anchors the civil engineering integration vector where deep grading and drainage workflow compatibility determines procurement decisions. Among field-focused challengers, Jobber and Service Autopilot represent the residential contractor SaaS archetype pursuing purpose-built estimation and visualization speed over compliance depth.
| Leading Market Players |
|---|
| Jobber |
| Service Autopilot |
| DynaSCAPE Software |
| Aspire |
| Vectorworks Landmark |
| Autodesk Civil 3D |
| Realtime Landscaping Architect |
| Land F/X |
| Arborgold |
| Others |
Pricing and Supply Chain Analysis
Computational design specialists concentrated in Bavarian engineering clusters and Austin technology corridors create labor-cost differentials that widen pricing-tier spreads between premium BIM-compliant platforms and mid-market estimation tools. Municipal procurement offices in water-stressed Sun Belt jurisdictions absorb SaaS subscription premiums for real-time collaboration capabilities, while residential contractors in secondary metropolitan areas gravitate toward purpose-built tools with compressed feature sets.
Pricing Analysis
Distributor margins on perpetual-licensed desktop software range from fifteen to twenty-five percent, whereas direct-to-municipality SaaS contracts eliminate intermediary markups entirely. Three-tier pricing structure across premium, standard, and economy levels separates ISO 19650-certified platforms from BIM-capable mid-market tools and basic estimation software without hydraulic modeling. Cost compression in the economy tier intensifies because residential contractors prioritize bid-cycle speed over compliance depth. Municipal buyers exhibit the lowest price sensitivity due to mandated procurement budgets, while single-family landscape installers face acute margin pressure that drives subscription churn.
Supply Chain Analysis
Dual-sourcing requirements embedded in municipal RFP specifications compel platform vendors to maintain qualified development partnerships across at least two geographic jurisdictions. Software engineering talent concentrates in the United States, Germany, and Canada, with precision GPS hardware integration components sourced from Japanese and Swiss sensor manufacturers. Cloud infrastructure services draw from hyperscaler data centers in Virginia, Frankfurt, and Sydney, creating tariff exposure on cross-border data sovereignty compliance. Distribution runs through direct enterprise sales teams for municipal and civil engineering accounts, with value-added resellers serving fragmented residential contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Landscaping Engineering Software Market functions as a stable compounder where regulatory compliance mandates create recurring revenue stickiness that outpaces cyclical construction volatility. EPA stormwater rules and municipal green infrastructure codes institutionalize platform switching costs across multi-year procurement cycles.
For Market Incumbents: Deepen hydraulic modeling engine capabilities to defend against venture-backed challengers attacking field verification niches with augmented reality overlays. Incumbent vendors should prioritize backward integration into precision GPS survey equipment partnerships to lock in file-format interoperability that anchors mid-market contractors. Certification investment in ISO 19650 BIM modules represents the critical lever for retaining municipal procurement eligibility as European urban nature restoration targets proliferate. For New Entrants and Emerging Players: Single-family residential contractors in Sun Belt secondary markets represent the most penetrable buyer archetype currently underserved by compliance-heavy platforms. New entrants should pursue purpose-built estimation and visualization speed without hydraulic modeling overhead, targeting contractors where irrigation component costs dominate project economics. A mobile-first SaaS go-to-market angle with tablet-based AR field verification compresses change-order cycles and differentiates against legacy desktop incumbents. For Investors and Strategic Acquirers: Private equity firms with vertical software portfolios are the most active acquirer in this space, consolidating mid-market specialists with planted asset libraries into broader outdoor infrastructure platforms. Acquisition targets should display embedded compliance module roadmaps aligned with EPA and EU Green Deal regulatory trajectories. The signal to watch is municipal procurement office SaaS-mandate acceleration in water-stressed jurisdictions, which would shift the outlook materially toward cloud-native architectures and away from perpetual-licensed desktop retention.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Autodesk Civil 3D's grading workflow compatibility anchors civil engineering procurement decisions against specialized landscape tools. |
| Acquisition of Specialist Firm | Mid-market planting library specialists like DynaSCAPE Software provide immediate native species compliance capabilities for municipal restoration bids. |
| Strategic Partnership | Precision GPS equipment manufacturers require vendor-specific file formats that fragment toolchain interoperability without exclusive alliances. |
| Geographic Expansion | Sun Belt metropolitan procurement offices in Phoenix, Austin, and Atlanta mandate SaaS compliance for multi-vendor bidding access. |
| Product Launch | Embedded carbon accounting modules anticipate EU Green Deal urban nature restoration targets pressing European biodiversity metric reporting. |
Research Methodology
Multiple input streams — primary interviews with landscape architecture principals, municipal procurement officers, and civil engineering firm technology directors, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Secondary sources encompassed EPA stormwater regulation filings, ISO 19650 certification databases, municipal RFP documentation from Sun Belt jurisdictions, and hyperscaler SaaS deployment disclosures. Conversations with irrigation contractors and residential installation business owners captured price sensitivity and feature prioritization patterns across buyer archetypes.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling segmentation dimensions including deployment architecture, organization size by employee count, vertical application focus, integration complexity with civil engineering platforms, and regional regulatory adoption patterns. CAGRs were derived from installed base growth trajectories and annual recurring revenue expansion rates. Industry-specific forecast inputs incorporated municipal green infrastructure mandate implementation timelines and cloud-native procurement specification velocity.
Underlying measurement precision varies by segment; cloud-based deployment and commercial landscaping application data carry tighter precision than on-premise legacy retention and golf course design niches. Forecasts reflect assumptions regarding EPA regulatory continuity and EU Green Deal funding allocation trajectories. Deviation in municipal SaaS mandate acceleration or precision GPS equipment vendor consolidation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Family Law Software Market
Software & Services
BFSI Software Market
Software & Services
Global Email Software Market
Software & Services
Global Thermal Analysis Software Market
Software & Services
Denmark Software As a Service (Saas) Market
Software & Services
Poland IT Software and Service Market
Software & Services
Global Neural Network Software Market
Software & Services
Digital Painting Software Market
Software & Services
Global Jewelry Store Management Software Market
Software & Services
Invoice Processing Software Market
Software & Services
Spain Sports Management Software Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
United States IT Services Market
Software & Services
House Cleaning App Market
Software & Services
United States Contract Lifecycle Management Software Market