
 Asia-Pacific Smart Airport Market | 2026-2036
Asia-Pacific Smart Airport Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Smart Airport Market Outlook
Passenger processing is decoupling from legacy manual check-in as biometric self-service adoption accelerates across major hub airports. Siemens AG leverages its building automation heritage to anchor infrastructure management contracts in Singapore and Sydney. Honeywell International Inc. sustains R&D intensity in IoT sensor networks for runway condition monitoring. Thales Group differentiates through biometric system integration for border control checkpoints at expanding Indian terminals.
Smart airports integrate digital infrastructure including biometric identification terminals, automated baggage handling conveyors, IoT-enabled environmental sensors, and AI-driven gate management systems to optimize passenger throughput, aircraft turnaround times, and energy consumption across terminal operations. Biometric systems and IoT sensors capture the fastest-growing investment pools as airports prioritize touchless passenger journeys and predictive maintenance for critical infrastructure. Baggage handling retains mature margin structures where Vanderlande Industries B.V. competes on installed base servicing, while security management applications attract premium pricing from integrated threat-detection platforms.
India's CEA mandates smart grid compatibility for airport power systems, while Australia's infrastructure standards enforce cybersecurity frameworks for passenger data systems; both regulations elevate compliance costs for technology vendors entering these markets. China's GB standards and MIIT directives on IoT device interoperability shape procurement specifications for domestic airport expansions. Stakeholders must weigh certification requirements against localization incentives when selecting partnership structures for multi-country deployment strategies.
Market Dynamics
Biometric passenger processing systems are decoupling terminal operations from legacy manual workflows across major Asia-Pacific hub airports, forcing infrastructure vendors to reconfigure deployment architectures around touchless identity verification and real-time data interoperability.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Local component sourcing requirements accelerate domestic production of smart gate hardware, reducing import dependency for biometric terminal deployments at Delhi and Mumbai airports.
- Biometric self-service adoption:Passenger processing automation is expanding across Australian and Southeast Asian terminals, driven by demand for reduced queue times and contactless journey experiences.
- CEA smart grid mandates:India's Central Electricity Authority requires airport power systems to integrate smart grid compatibility, creating procurement pull for intelligent energy management infrastructure.
Market Restraints
- Cybersecurity compliance costs:Australia's infrastructure standards enforce data protection frameworks for passenger biometric systems, elevating vendor certification expenses and extending deployment timelines.
- Semiconductor supply concentration:IoT sensor and edge computing component sourcing remains concentrated in East Asian foundries, exposing airport operators to input volatility and geopolitical disruption risks.
- Legacy system integration friction:Existing baggage handling and building management infrastructure at mature airports requires costly retrofitting to interface with new digital platforms.
Strategic Opportunities
- Southeast Asian greenfield airports:Vietnam, Indonesia, and Philippines terminal expansions offer first-mover positioning for integrated smart infrastructure without legacy system constraints.
- AI-driven predictive maintenance:Convergence of machine learning algorithms with IoT sensor networks enables shift from scheduled to condition-based infrastructure servicing, reducing downtime costs.
- India's metro airport pipeline:Bangalore and Hyderabad expansion projects create concentrated demand for biometric border control and automated baggage systems through 2035.
Industry Challenges
- Cybersecurity talent scarcity:Airport operators face acute shortages of certified professionals capable of managing zero-trust architectures for passenger data systems across multi-vendor environments.
- Interoperability certification delays:China's GB standards and MIIT directives on IoT device compatibility create extended approval cycles for foreign equipment suppliers seeking domestic airport contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Smart Airport Market |
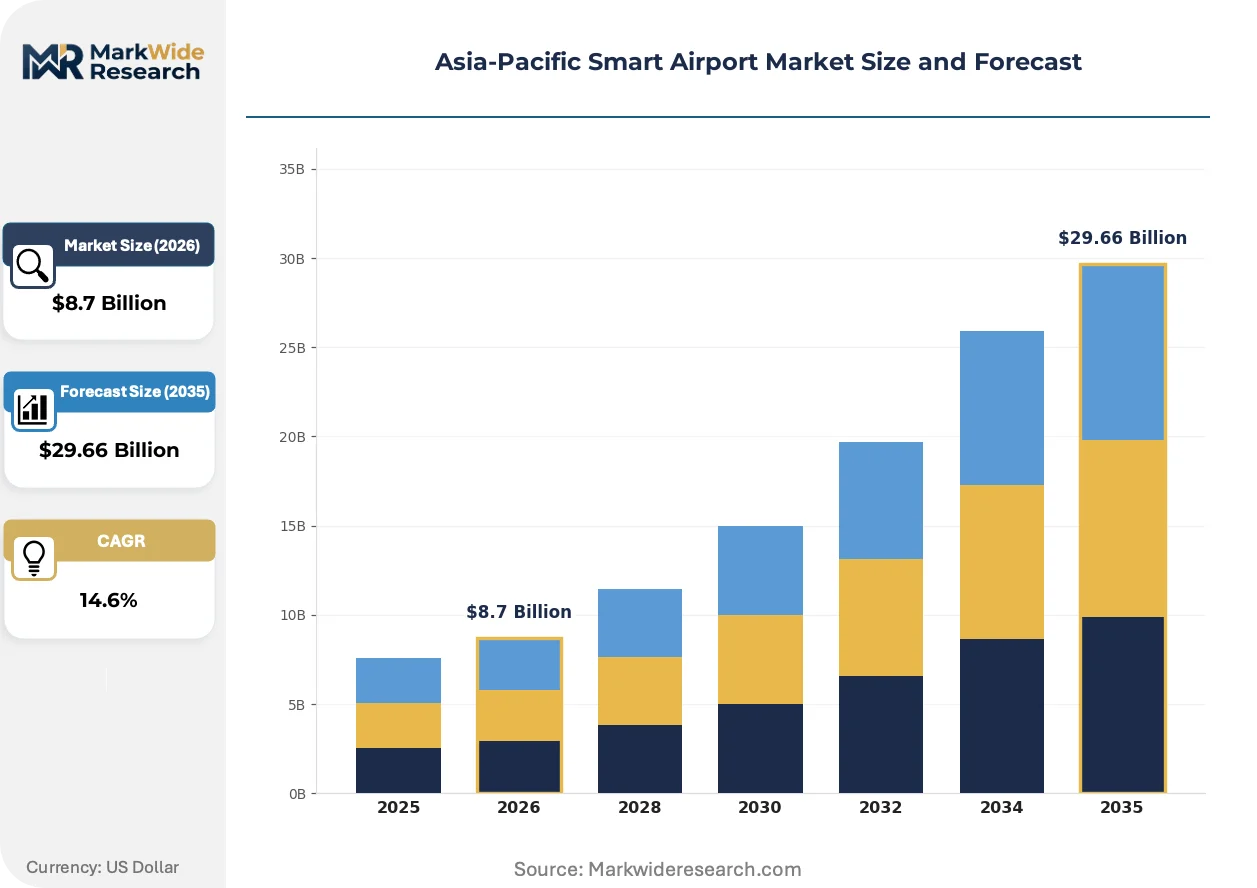
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biometric Systems, Baggage Handling, Smart Gates, IoT Sensors End User: Airlines, Airport Operators, Passengers, Security Agencies Application: Passenger Processing, Ground Handling, Security Management, Infrastructure Management Service Type: Consulting, Integration, Managed Services, Support & Maintenance |
| Companies Covered | SITA, Siemens AG, Honeywell International Inc., Vanderlande Industries B.V., Leidos, Inc., Thales Group, Cisco Systems, Amadeus IT Group, Huawei Technologies Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Smart Airport Market Strategic Shifts
Digital twin architectures are reshaping how airport operators model terminal capacity, enabling real-time simulation of passenger flows and infrastructure stress before physical deployment commitments.
Computer vision-based passenger tracking is converging with biometric identity verification to create continuous authentication corridors from curb to gate. Changi Airport and Sydney Airport are deploying these frictionless journey systems, compressing processing times while eliminating redundant document checks. The technology is converging with existing access control infrastructure, forcing incumbent security vendors to reengineer hardware-software integration layers.
Australia's cybersecurity frameworks for critical infrastructure are mandating sovereign data residency and encryption standards for passenger biometric storage. This regulatory pressure is fragmenting procurement specifications across Asia-Pacific jurisdictions, compelling multinational vendors to develop region-specific product variants. Indian terminals under CEA jurisdiction are responding with domestic cloud partnerships to satisfy data localization requirements.
Airport authorities are consolidating vendor relationships around integrated service contracts spanning design, deployment, and decade-long operational support. This bundling displaces traditional equipment-only procurement at major hubs, favoring firms with multi-disciplinary capabilities across hardware, software, and facilities management. The shift is most pronounced in Singapore and Australian markets where long-term concession structures align operator and vendor incentives.
Asia-Pacific Smart Airport Market Segmentation
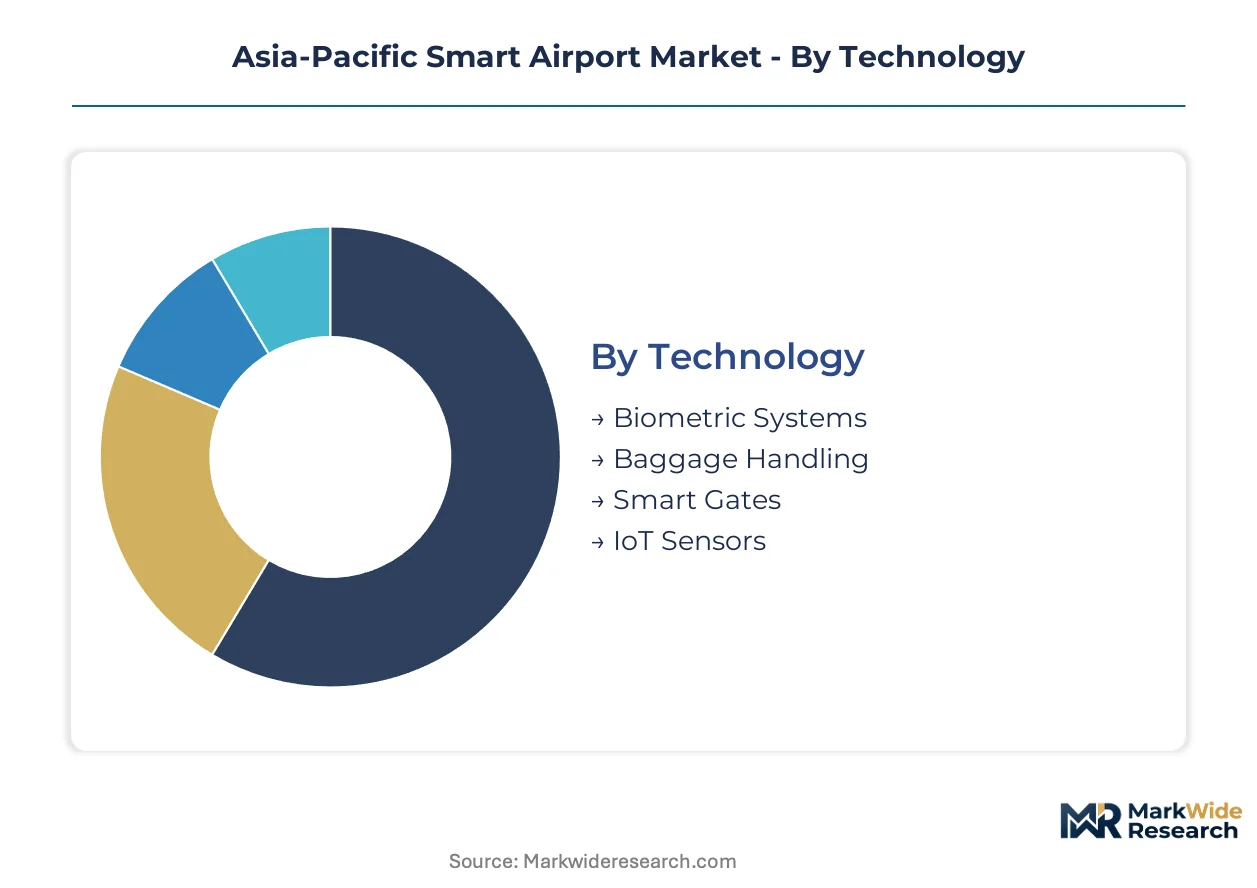
Smart airport procurement patterns diverge sharply across technology maturity, end-user sophistication, and service complexity. Understanding these fault lines clarifies where vendor capabilities must stretch versus where standardized offerings suffice.
Technology:
Hardware-software integration depth determines deployment architecture and vendor selection criteria across the four technology clusters.
- Biometric Systems:Facial recognition terminals and touchless identity verification engines anchor passenger processing modernization. Delhi and Mumbai airports are mandating multi-modal biometric corridors for international terminal expansions, with India's PLI scheme accelerating local component sourcing for fingerprint and iris scanning hardware.
- IoT Sensors:Environmental monitors, runway condition detectors, and energy consumption trackers feed real-time data streams into building management platforms. Australian terminals under critical infrastructure cybersecurity frameworks are specifying sovereign-certified sensor networks with edge computing capabilities for predictive maintenance applications.
- Baggage Handling:Automated conveyor systems and RFID-tracked luggage routing retain mature margin structures where installed base servicing drives recurring revenue. Retrofit demand concentrates at legacy hubs in Japan and South Korea facing capacity constraints without greenfield expansion options.
- Smart Gates:Self-service boarding and immigration checkpoints integrate biometric verification with access control hardware. Southeast Asian greenfield airports in Vietnam and Indonesia are specifying gate architectures without legacy system interface requirements.
Mature deployment sits with Baggage Handling. Newer deployment is concentrated in Biometric Systems.
End User:
Budget authority and procurement timelines fragment across four stakeholder groups with divergent technical specifications and compliance obligations.
- Airport Operators:Terminal owners and concession holders drive integrated infrastructure decisions spanning multiple technology domains. Singapore Changi and Sydney Airport authorities are consolidating vendor relationships around decade-long service contracts bundling design, deployment, and operational support.
- Security Agencies:Border control and aviation security regulators mandate biometric data handling protocols and threat detection system certifications. Australia's infrastructure standards enforce sovereign data residency requirements that fragment procurement specifications across jurisdictions.
- Airlines:Carriers prioritize passenger-facing biometric services and self-service check-in integration with loyalty program databases.
- Passengers:End-user experience feedback indirectly shapes technology adoption through queue time reduction metrics and contactless journey satisfaction scores.
Procurement consolidation centers on Airport Operators. Regulatory compliance complexity concentrates with Security Agencies.
Application:
Operational domain determines system interoperability requirements and integration friction with legacy infrastructure.
- Passenger Processing:Check-in, security screening, and boarding automation systems are decoupling from manual workflows through biometric self-service adoption. Indian metro airport expansions at Bangalore and Hyderabad are specifying continuous authentication corridors from curb to gate.
- Security Management:Integrated threat detection platforms combining video analytics, access control, and perimeter monitoring attract premium pricing from vendors with multi-layered cybersecurity certifications.
- Infrastructure Management:Building automation, energy optimization, and environmental control systems leverage existing industrial IoT platforms from established automation suppliers.
- Ground Handling:Aircraft turnaround coordination, cargo tracking, and apron management systems interface with airline operations centers and ground service provider fleets.
Touchless automation investment clusters in Passenger Processing. Predictive analytics deployment is expanding most quickly in Infrastructure Management.
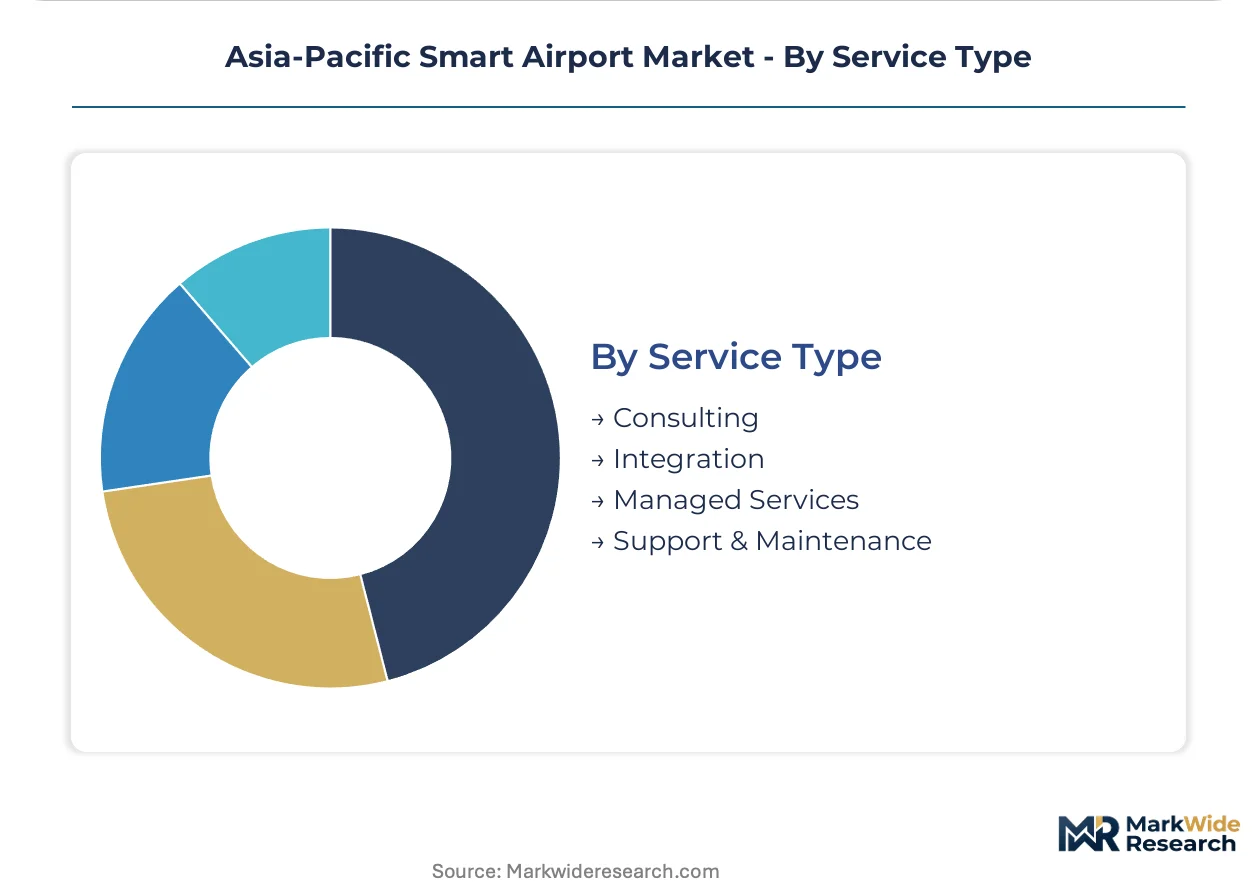
Service Type:
Revenue model selection reflects airport operator maturity and internal technical capability depth.
- Managed Services:Long-term operational outsourcing contracts spanning monitoring, maintenance, and system optimization are displacing equipment-only procurement at major hubs. Singapore and Australian markets favor concession-aligned vendor relationships with performance-based payment structures.
- Integration:Multi-vendor system interoperability and legacy platform interface development command specialist technical premiums where airport operators lack in-house integration capabilities.
- Consulting:Digital transformation strategy, regulatory compliance roadmap, and technology selection advisory services precede capital deployment at greenfield airports and major expansion projects.
- Support & Maintenance:Break-fix servicing and scheduled maintenance contracts retain steady revenue streams from installed base equipment across mature airport infrastructure.
Recurring revenue concentration sits with Support & Maintenance. Margin expansion is steepest in Managed Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates smart airport component manufacturing while India and Southeast Asia absorb the majority of system deployments. This production-consumption divide shapes vendor localization strategies and partnership structures across the region.
India
Metro airport expansions at Delhi, Mumbai, and Bangalore are mandating biometric passenger processing corridors for international terminals. India's PLI scheme for electronics manufacturing accelerates domestic sourcing of smart gate hardware components. Hyderabad's Rajiv Gandhi International Airport is deploying automated baggage handling systems for its upcoming expansion phases.
China
Domestic airport expansions in Chengdu, Xi'an, and Guangzhou are specifying IoT-enabled infrastructure under GB standards and MIIT interoperability directives. The country's dual carbon goals are elevating smart grid compatibility requirements for terminal energy systems. Shanghai Pudong International Airport is integrating AI-driven gate management platforms for its satellite terminal construction.
Australia
Sydney Airport and Melbourne Airport are consolidating vendor relationships around decade-long managed service contracts with performance-based structures. TGA-aligned cybersecurity frameworks enforce sovereign data residency for passenger biometric storage. Brisbane Airport is deploying computer vision-based passenger tracking for its frictionless journey pilot programs.
Singapore
Changi Airport Group is pioneering digital twin architectures for real-time terminal capacity simulation and passenger flow modeling. The Civil Aviation Authority of Singapore mandates integrated threat-detection platforms combining video analytics with access control systems. Terminal 5 development is specifying automated baggage handling without legacy system interface constraints.
Vietnam
Greenfield airport developments at Long Thanh and Van Don are attracting first-mover positioning for integrated smart infrastructure deployments. Vietnam's national aviation masterplan prioritizes touchless passenger processing systems for new terminal constructions. Da Nang International Airport is implementing biometric self-service checkpoints for its expansion project.
Asia-Pacific Smart Airport Market Competitive Environment
Top-tier vendors anchor infrastructure integration contracts, while specialized component suppliers compete on certification speed and localization compliance. The vendor base organizes around three strategic tiers: full-service integrators bundling design through decade-long operational support, technology specialists concentrating on biometric or IoT subsystems, and regional system integrators bridging foreign equipment with local certification requirements. Competitive positioning hinges on M&A activity consolidating multi-disciplinary capabilities and strategic partnerships navigating jurisdiction-specific data residency mandates.
Within the full-service integration tier, Siemens AG and Honeywell International Inc. occupy positions reflecting building automation heritage and IoT sensor network expertise respectively. Thales Group exemplifies the biometric specialization archetype, anchoring border control system integration for expanding Indian terminals. These three vendors represent contrasting approaches to the market's central tension between comprehensive service bundling and targeted technology depth.
| Leading Market Players |
|---|
| SITA |
| Siemens AG |
| Honeywell International Inc. |
| Vanderlande Industries B.V. |
| Leidos, Inc. |
| Thales Group |
| Cisco Systems |
| Amadeus IT Group |
| Huawei Technologies Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
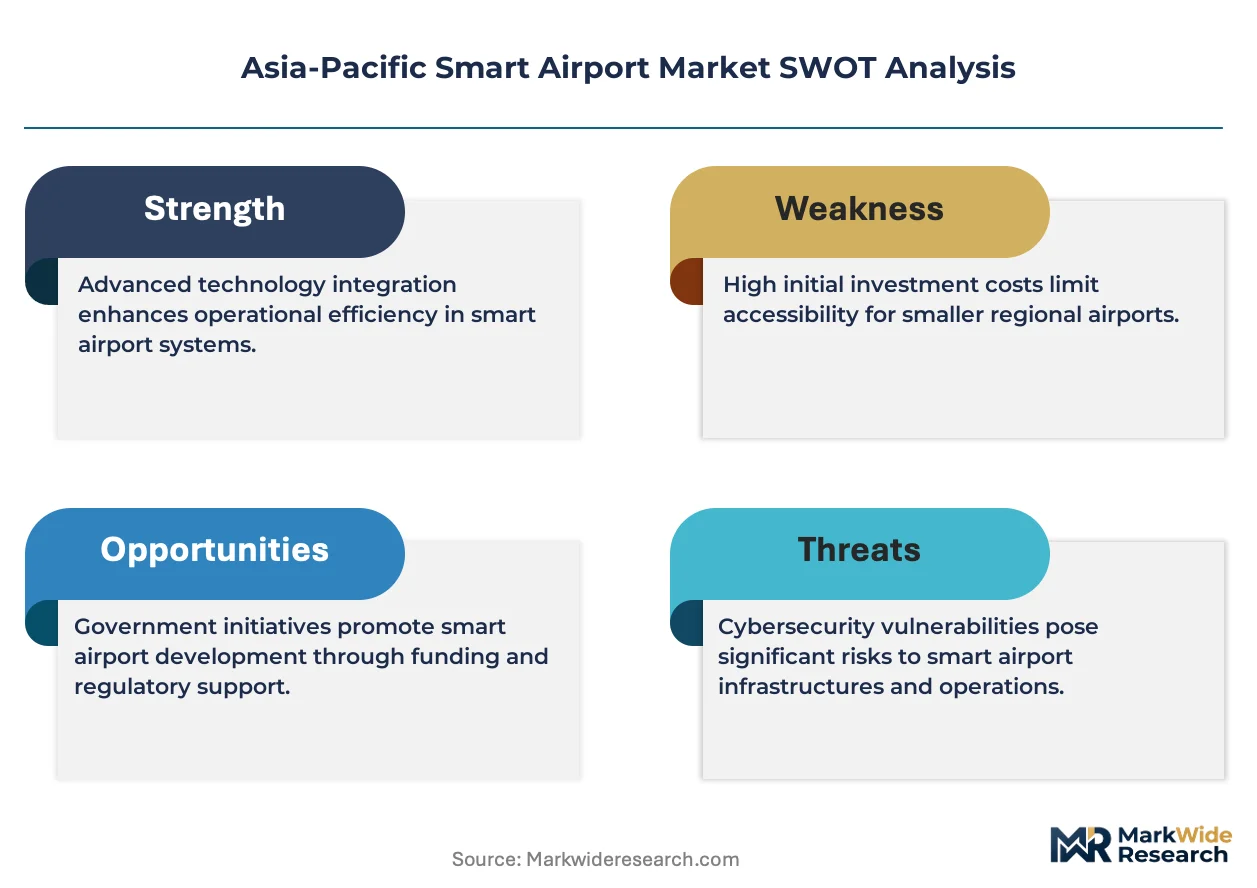
India's PLI scheme mandating local component sourcing for smart gate hardware is forcing foreign biometric terminal vendors to reconfigure procurement architectures around domestic electronics manufacturing clusters, compressing margins on standardized equipment while elevating premiums for certified integration services.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as airport operators facing CEA-mandated smart grid deadlines prioritize rapid deployment over cost optimization. Project-based pricing with milestone payments anchors major infrastructure contracts, while three-tier pricing structure across premium, standard, and economy levels segments biometric system offerings by certification grade and after-sales bundling depth. Cost compression in standard-tier hardware is intensifying because India's domestic manufacturing scale-up reduces import dependency. Regional system integrators exhibit highest price sensitivity due to thin margin structures, whereas full-service integrators with decade-long managed service contracts maintain pricing power through operational risk transfer.
Supply Chain Analysis
Direct-to-airport-operator channels handle hyperscale deployment demand at Delhi, Mumbai, and Singapore Changi, bypassing traditional distribution layers for integrated service contracts. Component manufacturing concentrates in China, South Korea, and Taiwan, with semiconductor foundries and edge computing module production anchoring upstream supply. Biometric sensor arrays, IoT communication chipsets, and automated conveyor mechanical systems draw from these concentrated manufacturing bases. Single-source vulnerability in advanced semiconductor sourcing exposes deployment timelines to geopolitical disruption risks. Distribution runs through certified system integrators who bridge foreign equipment with local CEA, TGA, and MIIT compliance requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors capable of bundling decade-long operational support with hardware deployment, as cybersecurity certification costs and localization mandates force smaller equipment-only suppliers toward exit or acquisition.
For Market Incumbents: Anchor market position through backward integration into domestic smart gate component manufacturing under India's PLI scheme, securing supply continuity while capturing localization incentives. Deepen biometric system integration capabilities to defend against pure-play software entrants targeting the passenger processing automation layer. Prioritize TGA-aligned cybersecurity certification investments to maintain eligibility for Australian infrastructure contracts. For New Entrants and Emerging Players: Launch via strategic partnerships with regional system integrators possessing established CEA and MIIT certification pathways, avoiding direct confrontation with full-service incumbents. Target Vietnam and Indonesia greenfield airport developments where legacy system integration friction is absent and first-mover positioning remains achievable. Concentrate on AI-driven predictive maintenance software layers where hardware-agnostic deployment reduces capital barriers. For Investors and Strategic Acquirers: The window for entry favors regional system integrators with multi-country certification capabilities and established airport operator relationships. Long-term viability hinges on vendor scale sufficient to absorb decade-long managed service contract operational risks. Monitor PLI scheme expansion announcements and TGA cybersecurity framework updates as inflection indicators for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric System Integration Partnership | Combines Thales Group border control expertise with local CEA compliance capabilities at expanding Indian terminals. |
| Domestic Component Manufacturing Scale-Up | Aligns smart gate hardware production with India's PLI scheme incentives for electronics manufacturing localization. |
| Digital Twin Architecture Deployment | Enables Changi Airport Group real-time terminal capacity simulation before physical infrastructure commitments. |
| Managed Service Contract Consolidation | Bundles design, deployment, and decade-long operational support at Sydney Airport and Melbourne Airport. |
| Predictive Maintenance Platform Launch | Converges machine learning algorithms with Honeywell IoT sensor networks for condition-based infrastructure servicing. |
Study Parameters
Multi-period observation of biometric terminal deployment timelines, PLI scheme utilization rates, and managed service contract structures anchored the trend analysis, supplemented by interviews with airport infrastructure directors, cybersecurity compliance officers, biometric system integration specialists, and regional aviation authority regulators. Secondary validation drew from CEA smart grid mandates, TGA critical infrastructure frameworks, MIIT IoT interoperability directives, and airport operator procurement disclosures. Bottom-up project pipeline aggregation triangulated against top-down regional aviation masterplan expenditure allocations.
Segment-weighting across technology clusters, end-user procurement authority tiers, application domains, and service type revenue models informed the analytical framework over the projection horizon. Biometric systems and IoT sensors received differentiated growth assumptions reflecting touchless passenger journey prioritization and predictive maintenance adoption curves. CAGRs derived from installed base expansion rates, replacement cycle compression, and greenfield airport development pipelines across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for computer vision-based continuous authentication corridors would alter the outlook if regulatory data residency requirements shift or passenger acceptance lags. Forecasts reflect assumptions regarding semiconductor supply normalization, CEA mandate enforcement consistency, and TGA cybersecurity framework stability. Practitioners should monitor PLI scheme expansion scope, TGA sovereign data residency clarifications, and MIIT interoperability certification cycle durations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Airport Information Systems Market
Airport Technologies
Helideck Monitoring System Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Airport Baggage Conveyor System Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Global Remote Towers Market
Airport Technologies
Smart Airport Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Airport Smart Lighting Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Airport RFID System Market
Airport Technologies
Advanced Airport Technologies Market