
 Air Compressor Market | 2026-2036
Air Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Air Compressor Market Analysis
Food and beverage processors is rotating toward oil-free compressed air systems as hygiene standards tighten across packaged goods supply chains. Atlas Copco leverages its oil-free compressor portfolio to anchor premium positioning in pharmaceutical and food-grade installations. Kaeser Kompressoren sustains manufacturing scale at its Coburg facility while extending service density across European industrial clusters. ELGi Equipments Limited competes aggressively on cost-optimized rotary screw units for South Asian small and medium enterprises.
An air compressor is a mechanical device that converts power into potential energy stored in pressurized air, typically achieving discharge pressures from 100 psi to over 6,000 psi depending on stage configuration and cooling architecture. The machine draws ambient air through an intake filter, compresses it via positive-displacement or dynamic mechanisms, then delivers conditioned compressed air to power pneumatic tools, automation actuators, and process equipment across industrial settings. Rotary screw compressors dominate installed base value due to continuous-duty reliability and lower lifecycle maintenance profiles in manufacturing and automotive assembly. Centrifugal systems occupy the high-flow, baseload segment where oil and gas processing and large chemical facilities require contamination-free air at volumes exceeding 1,000 cubic feet per minute. Variable speed technology is capturing incremental share as facilities prioritize part-load efficiency to curb electricity consumption, which typically represents over seventy percent of total compressor ownership cost.
The EPA enforces emissions standards for diesel-powered portable compressors used in construction and mining, pushing fleet operators toward electric and dual-fuel alternatives. ISO 8573 air quality classes govern oil and moisture content thresholds, directly specifying filtration and dryer configurations that OEMs must certify for pharmaceutical and electronics cleanroom applications. OSHA mandates guarding and pressure relief protocols that shape stationary compressor enclosure design and operator training requirements in US manufacturing plants. Stakeholders must monitor how carbon border adjustments and embedded emissions accounting reshape total cost of ownership calculations for imported compressor systems against locally manufactured alternatives.
Market Dynamics
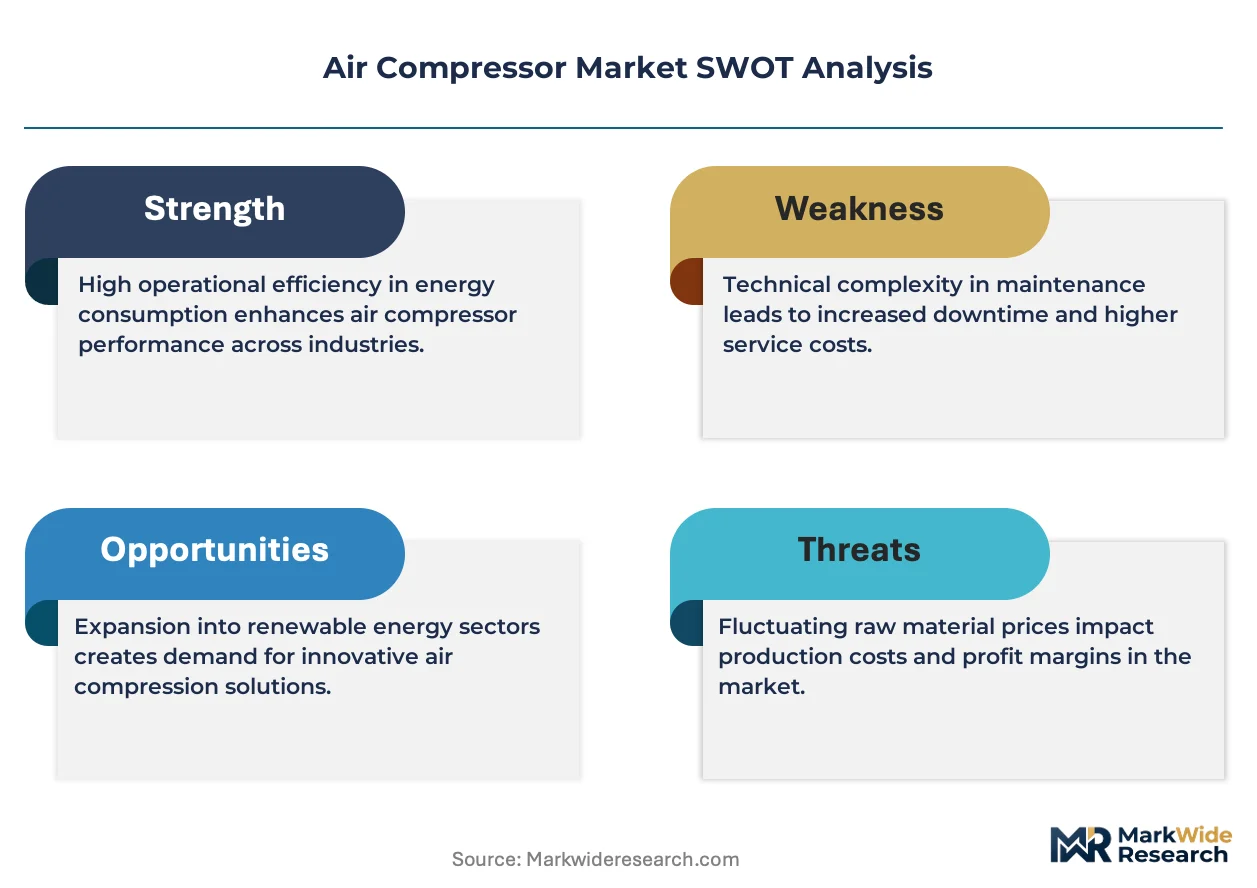
Variable-speed drive technology is compressing payback periods for energy-efficient rotary screw systems while EU Ecodesign Directive mandates force premature replacement of fixed-speed installed base across industrial facilities.
Growth Catalysts
- EU Ecodesign Directive:Mandatory minimum efficiency standards for compressors above 75kW are accelerating fleet turnover toward variable-speed rotary screw units in German and Italian manufacturing plants.
- Electronics cleanroom expansion:Semiconductor fabrication facilities in Taiwan and South Korea require ISO 8573 Class 0 oil-free compressed air, driving premium system installations.
- India PLI scheme:Production-linked incentives for domestic manufacturing are triggering capital expenditure in compressed air infrastructure across Maharashtra and Tamil Nadu industrial corridors.
Market Restraints
- Permanent magnet motor cost volatility:Neodymium and dysprosium price swings from Chinese rare earth processing concentration inflate variable-speed compressor bill-of-materials unpredictably.
- Baseload centrifugal lock-in:Oil and gas processors face switching costs from decades-old turbine-driven installations that resist electric motor retrofit economics.
- Copper and steel input pressure:Pressure vessel and heat exchanger fabrication depends on commodity metals whose cyclical pricing compresses OEM margin buffers.
Strategic Opportunities
- Indonesia industrial corridor development:Batang integrated industrial estate and similar zones lack mature compressed air infrastructure, creating first-mover positioning for system integrators.
- Heat recovery integration:Capturing compressor thermal output for process heating or space conditioning opens energy service contracting models in Nordic district heating networks.
- Remote monitoring convergence:IoT sensor deployment combined with predictive analytics enables unbundled compressor-as-a-service offerings independent of equipment ownership.
Industry Challenges
- Compressed air system auditor scarcity:Qualified technicians capable of leak detection and demand-side optimization assessments remain concentrated in Western European and North American markets.
- Legacy controller integration:Proprietary communication protocols from 1990s-era installations resist retrofit with modern building management and Industry 4.0 platforms.
- ISO 8573 certification timeline:Third-party validation for oil-free compressor claims requires extended testing cycles that delay product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Compressor Market |
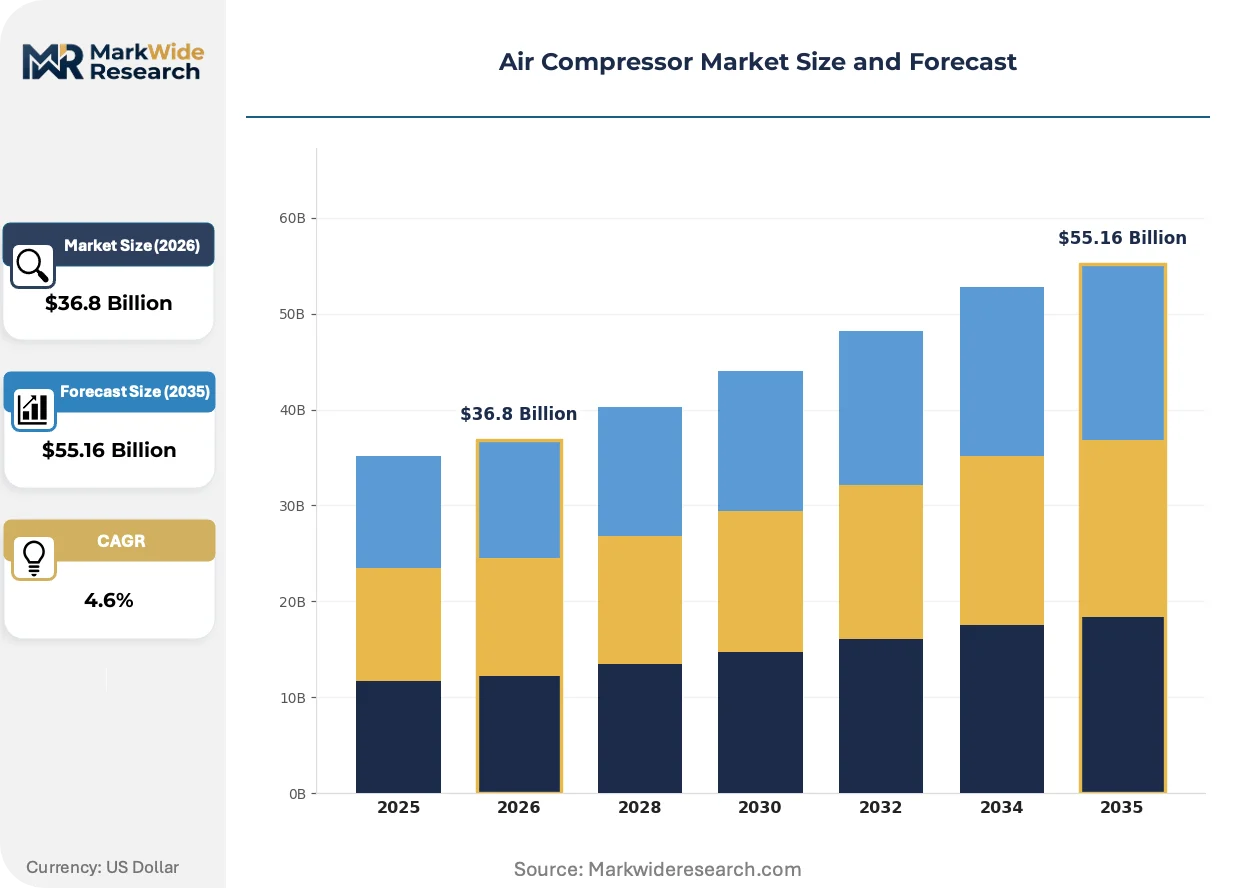
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $55.16 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Rotary Screw, Centrifugal, Scroll End User: Manufacturing, Automotive, Construction, Oil & Gas Deployment Type: Portable, Stationary, Electric, Diesel Technology: Low Pressure, Medium Pressure, High Pressure, Variable Speed |
| Companies Covered | Atlas Copco, Ingersoll Rand, Kaeser Kompressoren, Gardner Denver, Sullair, ELGi Equipments Limited, Hitachi, Mitsubishi Heavy Industries, Bauer Compressors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Compressor Market Emerging Trajectories
Digitalization of compressor performance monitoring is collapsing information asymmetry between operators and OEMs, while thermal management innovations and service model unbundling are restructuring how industrial buyers source compressed air capability.
Magnetic bearing centrifugal compressors eliminate mechanical contact losses and oil contamination risk entirely. Pharmaceutical manufacturers and electronics fabs in Ireland and Singapore are specifying these systems for critical process air. The technology is bifurcating the high-flow segment between oil-free turbocompressors and traditional geared centrifugal designs.
REACH regulation restrictions on fluorinated greenhouse gases are constraining refrigerant selection for compressed air dryers. Desiccant dryer manufacturers face reformulation pressure on activated alumina and molecular sieve regeneration cycles. Food and beverage processors in Denmark and the Netherlands are early adopters of CO2-based drying alternatives to maintain compliance timelines.
Performance-based service contracts are displacing traditional time-and-materials maintenance arrangements. Automotive tier-one suppliers in Bavaria and Baden-Württemberg now specify guaranteed air availability metrics rather than equipment ownership. Compressor fleet operators in these regions are consolidating vendor relationships to capture volume-based risk transfer pricing.
Air Compressor Market Segmentation
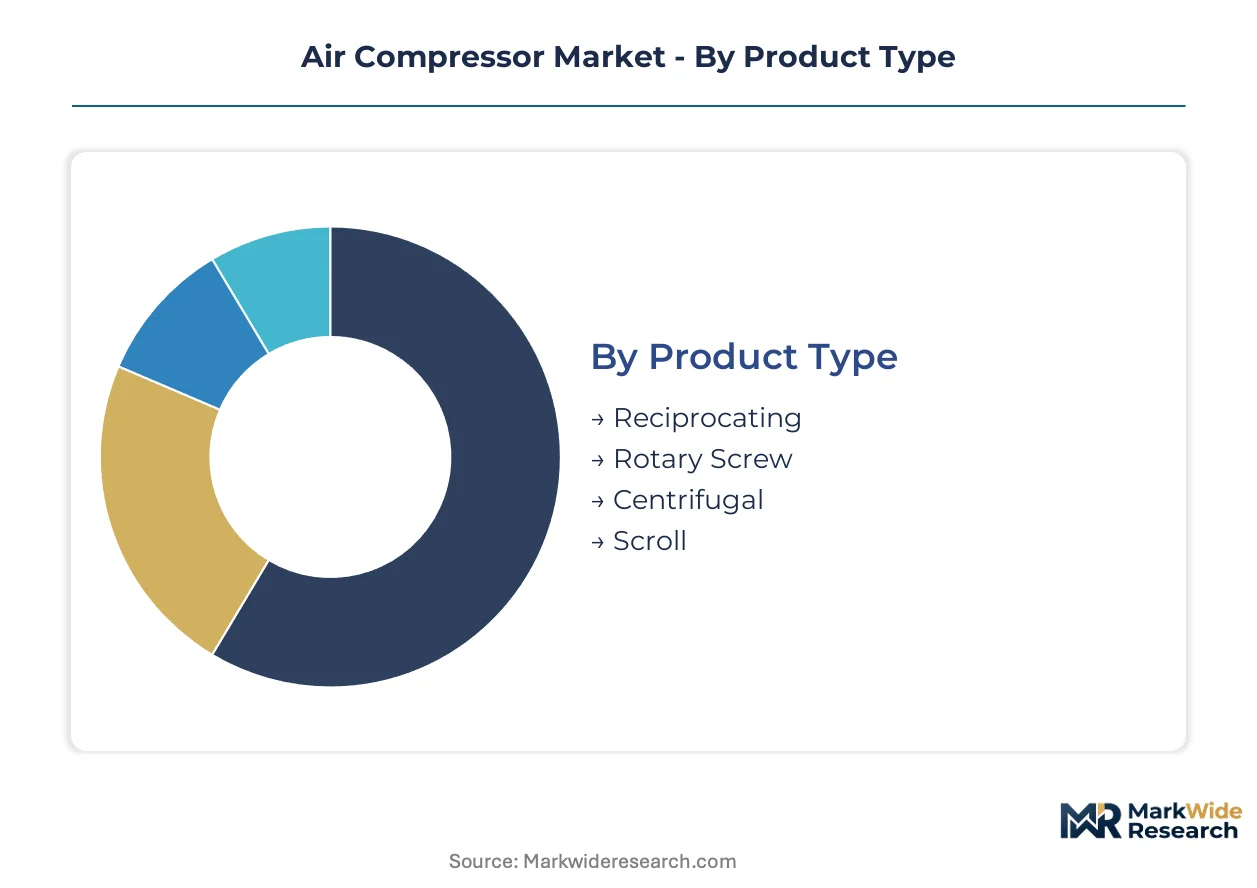
Compressed air infrastructure investment patterns diverge sharply across product architectures and deployment contexts. OEMs configure channel strategies around lifecycle service intensity rather than upfront equipment margins alone.
Product Type:
Rotary screw and centrifugal systems flow through factory-direct and authorized distributor channels with bundled service contracts, while reciprocating units move through industrial supply houses and equipment rental fleets.
- Rotary Screw:Positive-displacement compression via intermeshing helical rotors delivers continuous-duty output with minimal pulsation. Demand clusters in German and Italian automotive assembly plants where EU Ecodesign Directive mandates accelerate fixed-speed replacement. Variable-speed configurations now dominate premium quotations.
- Centrifugal:Dynamic compression using high-speed impellers achieves oil-free air delivery beyond 1,000 CFM for baseload chemical and petrochemical processing. Taiwanese semiconductor fabs specify magnetic bearing variants for ISO 8573 Class 0 compliance. Capital intensity limits this segment to project-based procurement through EPC contractors.
- Reciprocating:Piston-driven intermittent compression serves intermittent-duty workshops and legacy industrial maintenance bays across Maharashtra's SME manufacturing clusters.
- Scroll:Orbiting spiral compression provides quiet, oil-free output for dental clinics, laboratory automation, and food packaging lines in Denmark and the Netherlands.
By volume, reciprocating leads in unit shipments. By growth pace, rotary screw is ahead.
End User:
Cost tier stratification separates mission-critical process air investments from general shop-floor utility applications.
- Manufacturing:Electronics, textiles, and packaged goods production lines require 24/7 compressed air availability with predictive maintenance integration. Tamil Nadu industrial corridor development under India's PLI scheme is expanding rotary screw installations.
- Automotive:Paint shops and assembly automation demand ISO 8573-1 Class 1.2.1 air quality with desiccant drying and activated carbon filtration. Bavarian tier-one suppliers now contract for guaranteed availability rather than equipment ownership.
- Construction:Portable diesel and electric units power pneumatic breaking, drilling, and compaction tools across Indonesian infrastructure projects. EPA emissions enforcement is compressing diesel fleet residual values.
- Oil & Gas:Offshore platforms and downstream refineries maintain decades-old turbine-driven centrifugal installations that resist electric motor retrofit economics due to explosion-proofing requirements.
Manufacturing commands the largest installed base value. Automotive exhibits the steepest expansion trajectory for oil-free system specifications.
Deployment Type:
Customer type and mobility requirements determine whether procurement flows through rental fleets, permanent installation contractors, or integrated facility engineering.
- Stationary:Permanent plant infrastructure with dedicated piping networks dominates capital expenditure in process industries. Heat recovery integration for space conditioning or process heating is gaining traction in Nordic district heating networks.
- Portable:Towable and skid-mounted units serve construction, mining, and emergency utility applications. Fleet operators face OSHA guarding mandates and EPA diesel emissions standards that reshape replacement timing.
- Electric:Grid-connected systems eliminate local emissions and enable variable-speed drive efficiency across manufacturing and automotive end uses.
- Diesel:Off-grid and remote site applications persist in mining and pipeline construction, though dual-fuel and battery-electric alternatives are capturing incremental share.
Stationary systems anchor revenue concentration. Portable electric configurations are climbing the fastest as construction fleet electrification accelerates.
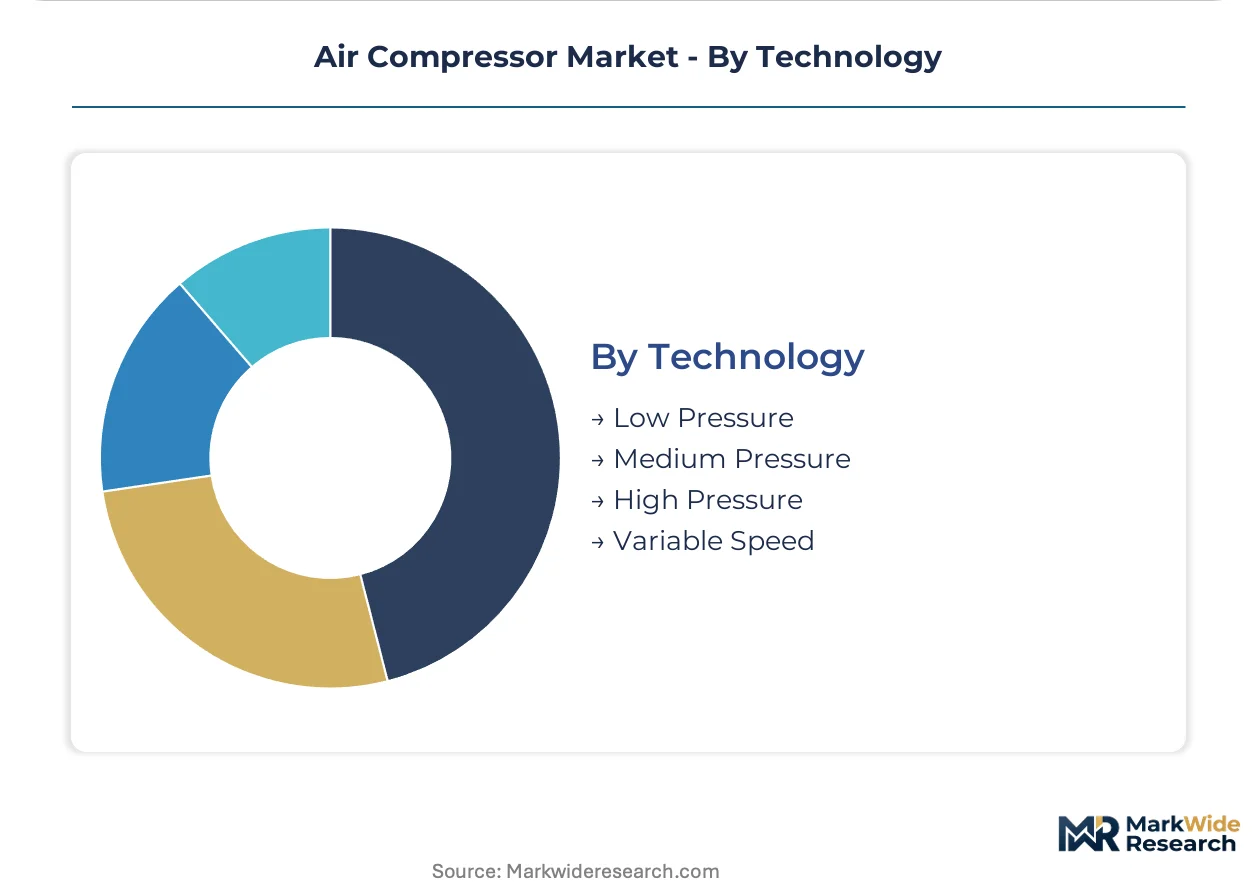
Technology:
Maturity and margin profiles separate established pressure-range categories from emerging efficiency-optimized architectures.
- Variable Speed:Inverter-driven motor control matches output to fluctuating demand, slashing part-load electricity consumption that typically exceeds seventy percent of lifecycle cost. German and Italian facilities above 75kW face EU Ecodesign Directive mandates that effectively require this technology.
- Medium Pressure:100-150 psi discharge serves general industrial automation, pneumatic conveying, and machine tool actuation across Southeast Asian electronics and textile corridors.
- High Pressure:Multi-stage compression to 3,000-6,000 psi supports PET bottle blowing, breathing air systems, and specialized chemical injection processes.
- Low Pressure:Below 100 psi applications include aeration, ventilation, and light pneumatic conveying where energy efficiency matters less than capital minimization.
Medium pressure holds the broadest application footprint. Variable speed is gaining share fastest as electricity cost pressure intensifies across European and North American industrial facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compressor manufacturing clusters in Germany, Italy, and Sweden anchor European supply chains, while final demand concentrates in industrial corridors across India, China, and the United States where factory automation and process air requirements are expanding.
Germany
Automotive assembly plants in Bavaria and Baden-Württemberg drive variable-speed rotary screw demand for paint shops and pneumatic automation. The EU Ecodesign Directive mandates minimum efficiency standards for compressors above 75kW, forcing premature replacement of fixed-speed installed base. Stuttgart's tier-one supplier ecosystem now contracts for guaranteed air availability metrics rather than equipment ownership.
India
Electronics and textile manufacturing expansion across Maharashtra and Tamil Nadu industrial corridors is triggering capital expenditure in compressed air infrastructure. The PLI scheme for domestic manufacturing provides production-linked incentives that accelerate compressed air system procurement. Tamil Nadu's Sriperumbudur electronics cluster is seeing rotary screw installations rise to support smartphone and component assembly lines.
China
Semiconductor fabrication facilities in Shanghai and Hefei require ISO 8573 Class 0 oil-free compressed air for cleanroom process applications. MIIT efficiency standards and dual carbon goals are pushing industrial facilities toward variable-speed electric systems. The Yangtze River Delta's advanced manufacturing belt is specifying magnetic bearing centrifugal compressors for high-flow, contamination-free process air.
United States
Shale processing and petrochemical expansion along the Gulf Coast maintains demand for large centrifugal baseload systems. EPA emissions enforcement for diesel-powered portable compressors is compressing construction fleet residual values and accelerating electric alternatives. Texas's Permian Basin operations face OSHA guarding mandates and pressure relief protocol requirements for stationary compressor enclosures.
Indonesia
Batang integrated industrial estate and similar greenfield zones lack mature compressed air infrastructure, creating first-mover positioning for system integrators. The country's national industrial development authority is prioritizing manufacturing corridor electrification that favors stationary electric compressor installations. Jakarta's construction sector is absorbing portable electric and dual-fuel units as diesel faces regulatory pressure.
Air Compressor Market Vendor Landscape
Concentration sits with diversified industrial conglomerates and specialized compressor manufacturers that have built decades-long service relationships across European and North American industrial clusters. The vendor base separates into three strategic archetypes: full-lifecycle solution providers bundling equipment and long-term service contracts, component-focused specialists optimizing specific compression technologies, and regional cost-optimized fabricators serving price-sensitive emerging markets. Competitive dynamics center on geographic expansion through authorized distributor networks and vertical integration into aftermarket service density.
Among European-based full-lifecycle providers, Atlas Copco and Kaeser Kompressoren exemplify the premium-tier archetype through oil-free portfolio depth and embedded service contracting. ELGi Equipments Limited represents the cost-optimized specialist position, competing on rotary screw unit economics for South Asian small and medium enterprises. These three occupy distinct competitive spaces without direct overlap: Swedish and German incumbents anchor developed-market process air specifications, while the Indian specialist captures volume in capital-constrained manufacturing corridors.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Kaeser Kompressoren |
| Gardner Denver |
| Sullair |
| ELGi Equipments Limited |
| Hitachi |
| Mitsubishi Heavy Industries |
| Bauer Compressors |
| Others |
Supply Flow & Price Mechanics
Long-term service bundling contracts lock in both supply access and price visibility for compressed air infrastructure, with German and Italian automotive OEMs favoring guaranteed-availability agreements that transfer operational risk from balance sheets to OEM service networks. This contractual architecture concentrates pricing power with full-lifecycle providers while exposing cost-optimized fabricators to raw material volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 8573 Class 0 oil-free systems from general industrial grades and basic reciprocating units. Price differentiation hinges on certification grade and after-sales service density, with pharmaceutical and electronics buyers absorbing premiums for contamination-free air while construction fleet operators drive cost compression in portable diesel segments. Pricing pressure stems from rare earth magnet cost volatility in variable-speed configurations, compressing margin buffers for mid-tier rotary screw suppliers. Small and medium enterprises across South Asia exhibit highest price sensitivity, whereas semiconductor fabs in Taiwan and South Korea prioritize specification compliance over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate European and North American OEM assembly, while strategic stockpiling of rare earth magnets and copper cathode concentrates in Chinese and German trading hubs buffers against commodity price spikes. Manufacturing concentration centers on Germany, Italy, and Sweden for precision screw machining and aerofoil casting, with India and China supplying pressure vessel fabrication and electric motor windings. Supply chain risk rests on single-source vulnerability for neodymium and dysprosium from Chinese rare earth processing complexes. Distribution runs through authorized service networks for rotary screw and centrifugal systems, while industrial supply houses and rental fleets handle reciprocating and portable segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified compressed air system auditors capable of leak detection and demand-side optimization remain scarce outside Western Europe and North America, creating a capability bottleneck that constrains efficiency gains across Southeast Asian and Indian industrial corridors.
For Market Incumbents: Secure aftermarket service density in Tamil Nadu and Maharashtra industrial corridors before PLI scheme maturation saturates greenfield installations. Deepen backward integration into permanent magnet motor supply chains to buffer against Chinese rare earth export restrictions. Defend premium positioning by accelerating ISO 8573 Class 0 certification timelines for oil-free portfolios ahead of electronics cleanroom expansion in Southeast Asia. For New Entrants and Emerging Players: Anchor in Indonesia's Batang integrated industrial estate and similar greenfield zones where mature compressed air infrastructure remains absent. Target heat recovery integration services for Nordic district heating networks as unbundled energy service contracting gains traction. Lead with remote monitoring and predictive maintenance platforms to bypass capital-intensive equipment manufacturing barriers. For Investors and Strategic Acquirers: Regional service specialists with dense technician networks in underserved industrial corridors represent the most defensible acquisition archetype. Long-term viability hinges on transition from equipment sales to outcome-based air availability contracts. Monitor carbon border adjustment implementation timelines as the inflection indicator reshaping total cost of ownership calculations for imported versus locally manufactured systems.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Recovery Integration | Captures compressor thermal output for Nordic district heating network energy service contracts. |
| Magnetic Bearing Centrifugal Deployment | Eliminates oil contamination risk for Irish and Singapore pharmaceutical cleanroom specifications. |
| Variable-Speed Retrofit Acceleration | Addresses EU Ecodesign Directive mandates forcing German and Italian fixed-speed replacement cycles. |
| Remote Monitoring Platform Launch | Enables unbundled compressor-as-a-service offerings independent of equipment ownership transfer. |
| Indonesia Industrial Corridor Entry | Captures first-mover positioning in Batang estate before infrastructure maturity consolidates vendor relationships. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade association filings, customs data, and regulatory disclosures from the EPA and EU Ecodesign Directive implementing bodies. Plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads across German, Italian, Indian, and Indonesian manufacturing clusters provided operational perspective on replacement cycles and specification priorities. Bottom-up triangulation of installation data against top-down macroeconomic indicators anchors volume and value estimates.
Segmentation dimensions modeled include product architecture, end-use industry, deployment mobility, and pressure range tier across the projection horizon. CAGRs derive from regression analysis of historical capital expenditure patterns and policy-driven replacement schedules. Forecast inputs incorporate electricity cost trajectories affecting variable-speed adoption economics and semiconductor fabrication capacity expansion timelines governing oil-free system demand.
Decision-makers should treat outputs as directional under assumptions of continued EU Ecodesign Directive enforcement and stable rare earth magnet supply from Chinese processing facilities; material deviation would warrant model refresh. Revision becomes warranted when carbon border adjustment mechanisms cross implementation thresholds or when Indonesian industrial corridor electrification accelerates beyond baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
LNG Compressor Market
Compressors
Bus Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Industrial Air Compressor Market
Compressors
USA Scroll Compressor Market
Compressors
Regenerative Blowers Market
Compressors
Axial Compressor Market
Compressors
Positive-Displacement Hydrogen Compressor Market
Compressors
Oil Free Compressor Market
Compressors
Rental Air Compressors Market
Compressors
Positive Displacement Gas Compressor Market
Compressors
Oil Filled Air Compressor Market
Compressors
Reciprocating Air Compressor Market
Compressors
Europe Compressor Market
Compressors
Rotary Lobe Compressor Market
Compressors
Compressor Wheel Market