
 Inner Bulk Liners Market | 2026-2036
Inner Bulk Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Inner Bulk Liners Market Foresight
Market Context
Southeast Asia is tilting toward expanded woven polypropylene capacity to serve regional chemical export growth. Greif leverages its integrated container and liner supply chain to capture bundled packaging contracts across North American agricultural exporters. Thrace Group anchors its position through vertical control of tape extrusion and weaving operations in Southeastern Europe. Vishakha PolyFab Pvt. Ltd. dominates domestic Indian demand with specialized food-grade liner fabrication for spice and grain handlers.
Technical Definition and Segment Structure
Inner bulk liners are high-barrier containment systems inserted into intermediate bulk containers, road tankers, or ocean freight containers to isolate dry or liquid cargoes from vessel walls, typically constructed from multi-layer polyethylene or polypropylene films ranging from 100 to 250 microns in thickness. Their primary purpose is to eliminate cross-contamination, reduce cleaning costs, and enable single-use hygiene protocols in food, chemical, and pharmaceutical logistics. Flexible liners lead volume due to lower freight cost and storage footprint, while composite liners command margin premiums in pharmaceutical applications where moisture and oxygen transmission rates must meet exacting thresholds. Polyethylene material grades sustain the broadest adoption across food and beverage end uses, though polypropylene is displacing legacy options in chemical transport where elevated temperature resistance proves essential.
Regulatory Frame and Outlook
FDA food-contact substance notifications, EU Regulation 10/2011 on plastic materials, and ISO 22000 food safety management standards collectively define material eligibility and migration testing protocols for liner suppliers seeking multi-jurisdiction market access. Compliance with these frameworks shapes R&D allocation, as manufacturers reformulate additive packages to satisfy divergent regional limits on heavy metals and primary aromatic amines. Stakeholders must monitor evolving extended producer responsibility mandates in the European Union and state-level packaging regulations in the United States, as these will determine whether recyclable or bio-based liner formulations become baseline requirements rather than premium differentiators.
Market Dynamics
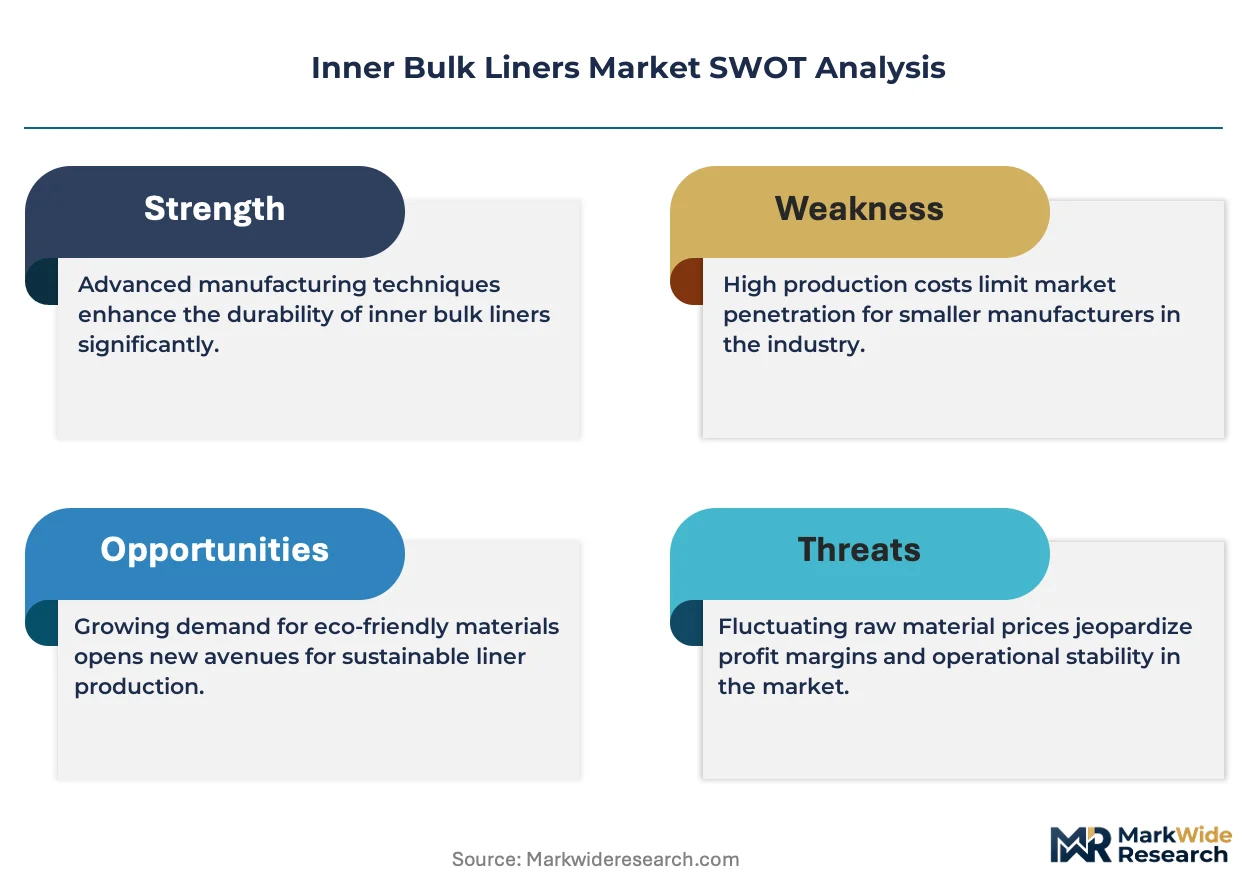
EU migration limits for plastics under Regulation 10/2011 are forcing liner manufacturers to reformulate additive packages and revalidate multi-layer film constructions, compressing R&D timelines and raising compliance costs across the supply base.
Growth Catalysts
- Food-contact compliance mandates:FDA food-contact substance notifications and EU migration testing protocols compel food and beverage processors to specify certified liners, expanding procurement volumes for validated suppliers.
- Chemical export corridors:Southeast Asia's expanding woven polypropylene capacity serves regional chemical export growth, stimulating liner demand for intermediate bulk container protection.
- Pharmaceutical cluster concentration:Germany's chemical and pharmaceutical hubs drive specification-grade liner consumption for moisture-sensitive active pharmaceutical ingredient transport.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer price swings tied to naphtha cracking economics compress liner margins and complicate contract pricing.
- Single-use plastic restrictions:Extended producer responsibility mandates in the European Union threaten liner economics unless recyclable or bio-based formulations achieve cost parity.
- Cleaning technology substitution:Advanced CIP (clean-in-place) systems for road tankers reduce liner necessity in liquid chemical logistics.
Strategic Opportunities
- Bio-based material convergence:Polyhydroxyalkanoate and polylactic acid film technologies are approaching performance thresholds for food-grade liner applications.
- Indian spice and grain handling:Domestic food-grade liner fabrication for spice exporters remains underpenetrated relative to volume potential.
- Digital traceability integration:RFID-enabled liners combined with blockchain verification create premium positioning for pharmaceutical cold chain compliance.
Industry Challenges
- Migration testing bottlenecks:ISO 22000 certification timelines and EU 10/2011 compliance documentation create 12-18 month product launch delays.
- Multi-layer lamination expertise scarcity:Coextrusion die design and barrier layer adhesion chemistry skills concentrate in legacy packaging regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inner Bulk Liners Market |
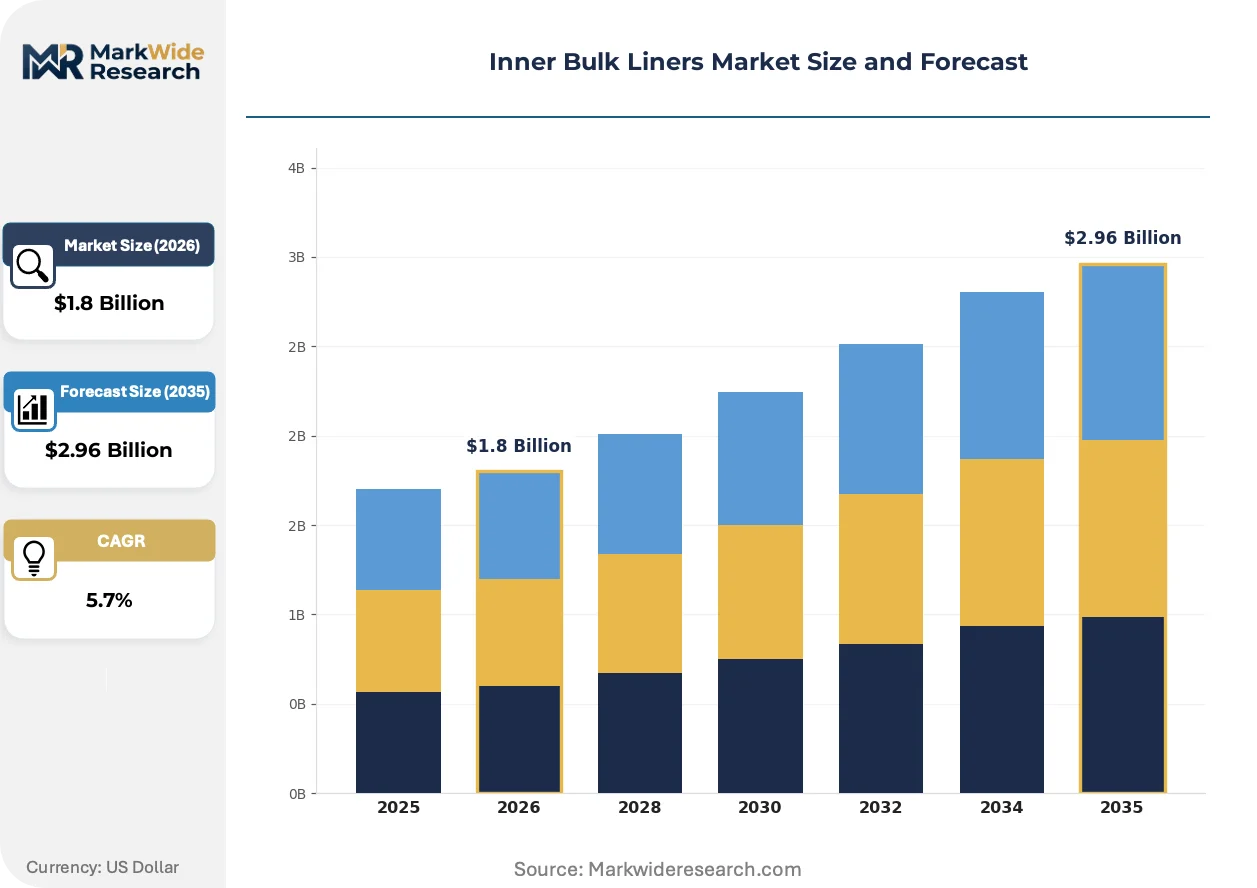
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Liners, Rigid Liners, Composite Liners, Hybrid Liners Material: Polyethylene, Polypropylene, PVC, EVA End Use Industry: Food & Beverage, Chemicals, Pharmaceuticals, Agriculture Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Tufbag, Marsol Group, Bulk-Flow, Thrace Group, Vishakha PolyFab Pvt. Ltd., Greif, Amcor plc, LC Packaging International B.V., Berry Global, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inner Bulk Liners Market Shifts & Advancements
Smart packaging technologies and sustainability mandates are restructuring how liner specifications are written, tested, and enforced across food, chemical, and pharmaceutical supply chains.
RFID inlay integration into polyethylene liner films is digitizing custody documentation for pharmaceutical shipments. Cold chain operators in Germany and the Netherlands are piloting sensor-enabled liners that transmit temperature and humidity data across distribution networks. This capability compresses insurance premiums and reduces spoilage claims for high-value active pharmaceutical ingredients.
REACH substance restrictions and the EU Green Deal's packaging waste targets are accelerating recyclable mono-material liner development. Manufacturers are eliminating ethylene vinyl alcohol barrier layers in favor of metallized polypropylene or bio-based alternatives. Food-grade applications in France and Italy face the steepest reformulation deadlines under national extended producer responsibility schemes.
Consolidated buying desks at multinational agricultural exporters are unbundling liner procurement from container leasing agreements. North American grain handlers now issue separate liner tenders with technical specifications exceeding traditional bundled contracts. This pattern concentrates volume with specialized fabricators capable of custom sizing and rapid turnaround.
Inner Bulk Liners Market Segmentation
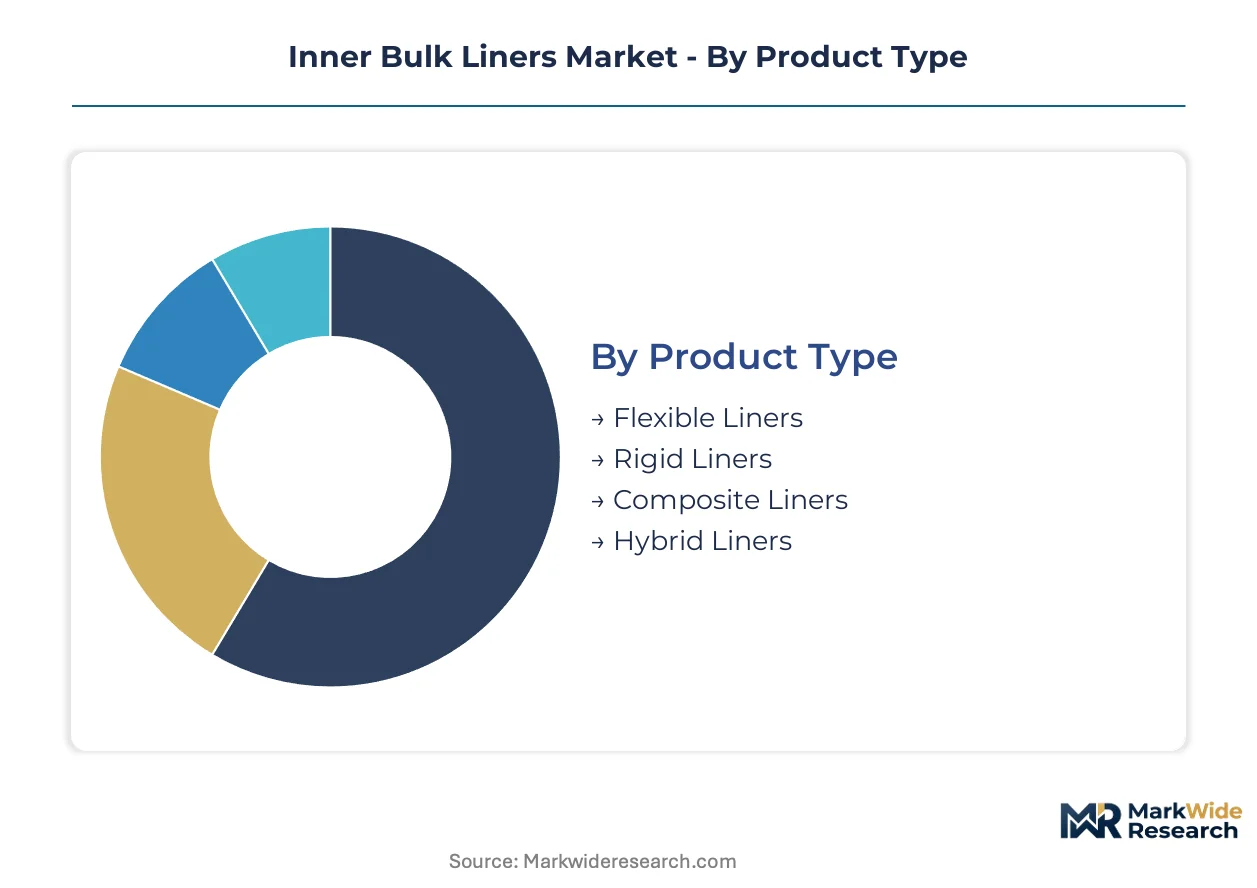
Inner bulk liner specifications diverge sharply across transport modes and cargo sensitivity. Procurement teams weight barrier performance against freight economics when selecting product categories, while material grades must satisfy jurisdiction-specific migration limits.
Product Type:
Flexible configurations dominate road and container freight where space efficiency governs total landed cost.
- Flexible Liners:Multi-layer polyethylene or polypropylene films between 100-250 microns enable folding for empty-backhaul efficiency. Food and beverage processors in Germany specify these for intermediate bulk container shipments of liquid ingredients, balancing contamination control against freight minimization.
- Composite Liners:Aluminum-oxide or metallized barrier layers laminated to polymer substrates achieve oxygen transmission rates below 0.1 cc/m²/day. Pharmaceutical clusters in the Netherlands and Switzerland mandate these for moisture-sensitive active pharmaceutical ingredient transport, accepting premium positioning for cold chain integrity.
- Rigid Liners:Thermoformed polyethylene shells provide structural support for dense chemical powders.
- Hybrid Liners:Combine flexible sidewalls with rigid base panels for irregular cargo shapes.
Established volume favors Flexible Liners; emerging adoption favors Composite Liners.
Material:
Polymer selection traces directly to temperature exposure and regulatory jurisdiction.
- Polyethylene:Linear low-density and metallocene grades sustain broad food-contact adoption under FDA and EFSA frameworks. Migration testing protocols for heavy metals and primary aromatic amines are well-established, compressing supplier qualification timelines for North American and European food processors.
- Polypropylene:Higher melting points (160-170°C) enable chemical transport applications where steam cleaning or elevated temperature exposure occurs. Southeast Asian chemical exporters are displacing legacy polyethylene specifications as regional woven polypropylene capacity expands.
- PVC:Declining share due to plasticizer migration concerns under REACH restrictions.
- EVA:Specialty applications requiring flexibility at low temperatures.
Polyethylene captures current procurement volume; polypropylene climbs the fastest on chemical corridor expansion.
End Use Industry:
Compliance thresholds escalate from agricultural commodities through pharmaceutical actives.
- Food & Beverage:ISO 22000 certification and EU 10/2011 migration limits define baseline eligibility. Spice and grain handlers in India drive domestic fabrication demand, while European dairy and beverage processors specify liners with full additive disclosure documentation.
- Pharmaceuticals:EMA guidelines and national competent authority requirements in Germany, France, and Italy enforce exacting barrier performance documentation. Sensor-enabled liners with RFID traceability are gaining trial adoption for high-value cold chain shipments.
- Chemicals:UN transport regulations and REACH substance restrictions govern material compatibility.
- Agriculture:Cost-sensitive bulk grain and fertilizer applications prioritize freight efficiency over barrier sophistication.
Food and beverage sustains procurement scale; pharmaceuticals show steepest specification escalation.
Distribution Channel:
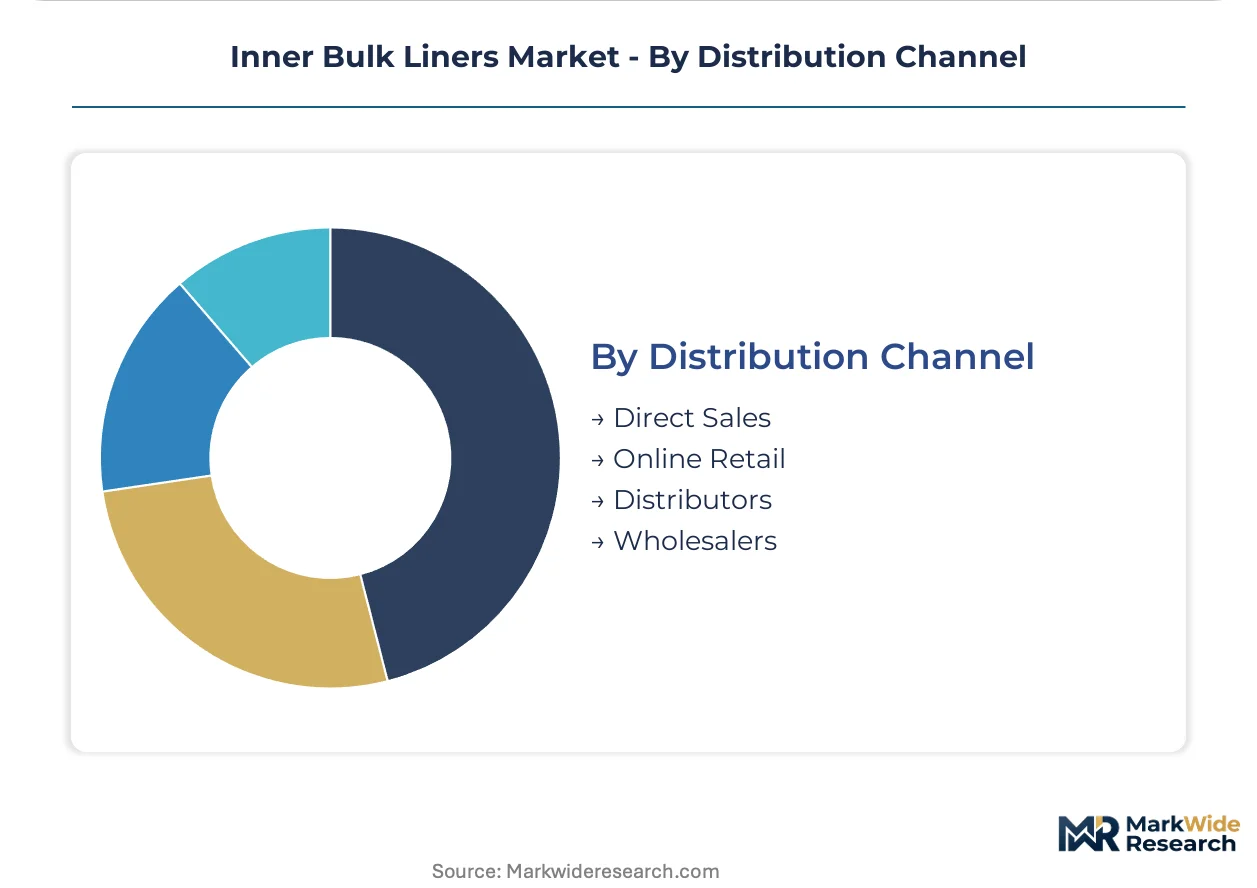
Channel selection reflects buyer scale and technical specification complexity.
- Direct Sales:Multinational agricultural exporters and pharmaceutical manufacturers negotiate multi-year frame contracts with dedicated technical service support. Greif and integrated packaging suppliers leverage captive liner production to capture these bundled arrangements.
- Distributors:Regional fabricators serving mid-size chemical processors and food handlers rely on specialty plastics distributors for geographic coverage without direct sales infrastructure.
- Online Retail:Standardized dimension liners for small-scale agricultural and food processors.
- Wholesalers:Generic specifications for price-sensitive commodity applications.
Direct sales concentrate premium specification volume; distributors expand fastest among mid-tier chemical processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes specification-grade liners for pharmaceutical cold chains, while India deploys commodity-grade fabrication for spice exports. This consumption-mix differential separates premium barrier markets from volume-driven food logistics.
United States
North American agricultural exporters drive tender unbundling, separating liner procurement from container leases. FDA food-contact substance notifications govern material eligibility for dairy and beverage processors. Midwest grain handlers concentrate volume with fabricators offering custom sizing and rapid turnaround.
Germany
Chemical and pharmaceutical clusters in Ludwigshafen and Leverkusen mandate composite liners with oxygen transmission rates below 0.1 cc/m²/day. EMA guidelines enforce exacting barrier documentation for active pharmaceutical ingredient transport. Cold chain operators in the Rhine-Ruhr region pilot RFID-enabled liners with blockchain verification.
India
Domestic spice and grain handlers sustain demand for food-grade liner fabrication with full additive disclosure. FSSAI compliance requirements compress supplier qualification timelines for export-oriented processors. Gujarat and Maharashtra host specialized fabricators serving turmeric and rice export corridors.
Netherlands
Rotterdam's chemical logistics hub stimulates woven polypropylene liner adoption for intermediate bulk container protection. REACH substance restrictions govern material compatibility for hazardous cargo handling. Sensor-enabled liner trials in the Port of Rotterdam transmit temperature data across distribution networks.
China
Dual carbon goals and packaging waste regulations accelerate recyclable mono-material liner development. NMPA pharmaceutical guidelines shape barrier specifications for domestic active ingredient transport. Yangtze River Delta chemical processors displace legacy polyethylene specifications with temperature-resistant alternatives.
Inner Bulk Liners Market Competitive Landscape
Capability concentration sits with specialized fabricators mastering coextrusion die design; scale advantage sits with integrated packaging conglomerates controlling captive liner production. The market structures around three tiers: multinational bundlers, regional specialists, and domestic commodity fabricators. Dominant competitive moves include backward integration into tape extrusion and weaving operations, plus geographic expansion through distributor partnerships.
Among integrated packaging suppliers, Greif exemplifies the bundling archetype through combined container and liner offerings. Thrace Group anchors the specialist tier with Southeastern European manufacturing presence. Vishakha PolyFab Pvt. Ltd. occupies the domestic commodity position serving Indian spice export demand.
| Leading Market Players |
|---|
| Tufbag |
| Marsol Group |
| Bulk-Flow |
| Thrace Group |
| Vishakha PolyFab Pvt. Ltd. |
| Greif |
| Amcor plc |
| LC Packaging International B.V. |
| Berry Global, Inc. |
| Others |
Supply & Pricing Matrix
Southeast Asia's woven polypropylene capacity expansion in Vietnam and Thailand directly compresses spot pricing for commodity-grade liners serving regional chemical exporters, while German pharmaceutical clusters sustain premium positioning through specification-grade composite liner contracts.
Pricing Analysis
Long-term offtake agreements dominate procurement for multinational agricultural exporters and pharmaceutical manufacturers, insulating validated suppliers from propylene monomer volatility while spot transactions govern mid-tier chemical processor purchases. Three-tier pricing structure across premium, standard, and economy levels separates RFID-enabled pharmaceutical liners from food-grade flexible configurations and generic agricultural specifications. Cost compression in standard-grade polyethylene liners is intensifying because Southeast Asian woven polypropylene capacity expansion erodes regional pricing power. Agricultural grain handlers exhibit highest price sensitivity, while pharmaceutical cold chain operators accept substantial premiums for barrier performance documentation.
Supply Chain Analysis
Contract manufacturing concentration rests with Thrace Group's tape extrusion and weaving operations in Southeastern Europe and Vishakha PolyFab's food-grade fabrication clusters in Gujarat and Maharashtra. Raw material draws from Saudi and Qatari polyethylene resin supply, German metallocene catalyst technology, and Chinese metallized film substrates. Single-source vulnerability concentrates in EVOH barrier layer supply from Japanese specialty chemical producers. Distribution runs through integrated packaging bundlers for multinational accounts and specialty plastics distributors for regional chemical processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal packaging waste targets and FDA food-contact notification tightening constitute a dual regulatory inflection accelerating recyclable mono-material liner development and compressing qualification timelines for additive-dependent formulations.
For Market Incumbents: Entrench market position through backward integration into tape extrusion and weaving operations, mirroring Thrace Group's Southeastern European manufacturing model. Captive resin compounding capabilities insulate against propylene monomer volatility while accelerating EU 10/2011 compliance documentation. Certification investment in ISO 22000 and RFID-enabled traceability systems creates switching costs against emerging bio-based material competitors. For New Entrants and Emerging Players: Indian spice export corridors remain underpenetrated relative to volume potential, with domestic fabricators lacking full additive disclosure documentation required by European and North American buyers. Polyhydroxyalkanoate film technology approaches performance thresholds for food-grade applications, enabling sustainability-positioned entry. Direct technical service relationships with Gujarat-based turmeric and rice processors provide beachhead access before scaling to multinational agricultural exporters. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized fabricators mastering coextrusion die design and barrier layer adhesion chemistry over commodity converters. Five-to-ten year viability hinges on migration from multi-layer EVOH constructions to recyclable mono-material or bio-based alternatives. Monitor EU extended producer responsibility mandate implementation timelines as the critical inflection signal determining whether sustainable formulations achieve cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply insulates Greif against propylene volatility in North American agricultural contracts. |
| RFID-Enabled Traceability Launch | Sensor-integrated liners command pharmaceutical cold chain premiums in Germany's Rhine-Ruhr distribution networks. |
| Recyclable Mono-Material Development | Metallized polypropylene alternatives satisfy EU Green Deal targets for French and Italian food-grade applications. |
| Geographic Expansion via Distributor Partnerships | Regional fabricators penetrate mid-tier chemical processors in Netherlands' Rotterdam logistics hub without direct sales infrastructure. |
| Certification Acceleration Program | Compressed ISO 22000 timelines enable Indian spice exporters to qualify for European migration limit compliance. |
Research Methodology
Cross-validation between primary interviews with liner procurement managers at multinational agricultural exporters and secondary analysis of FDA food-contact substance notifications anchors the qualitative findings. Plant managers at German chemical clusters, technical R&D directors at Southeast Asian woven polypropylene facilities, and channel partners serving Indian spice handlers provided operational validation. Secondary sources include EU 10/2011 migration limit documentation, REACH substance restriction updates, SEC filings from integrated packaging suppliers, and customs data tracking regional liner trade flows. Bottom-up demand modeling triangulates against top-down capacity assessments across major production hubs.
Calibration against historical propylene monomer price elasticity and pharmaceutical cold chain spoilage claim data refines volume projections across the analysis window. Segmentation dimensions encompass product type, material grade, end-use industry vertical, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, export corridor expansion rates, and compliance-driven specification upgrades. Industry-specific inputs include EU extended producer responsibility mandate implementation schedules and NMPA pharmaceutical barrier guideline evolution in China.
Practitioners should monitor propylene feedstock volatility, EU migration limit amendments, and bio-based material performance thresholds for early signals requiring forecast revision. Quarterly review of FDA notification approval timelines, REACH substance restriction proposals, and Indian FSSAI enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Child Resistant Bags Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Gusseted Bags Market
Bags and Containers
Lawn and Leaf Bags Market
Bags and Containers
2 Loop FIBC Bags Market
Bags and Containers
Laser Scored Bags Market
Bags and Containers
Type-C Bulk Bags Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Textile Bags Market
Bags and Containers
Cross Corner Industrial Bags Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Padding Bags Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Lunch Boxes and Lunch Bags Market