
 2 Loop FIBC Bags Market | 2026-2036
2 Loop FIBC Bags Market Size, Share, and Industry Trends Forecast 2026-2036
2 Loop FIBC Bags Market Outlook
Industrial packaging distribution is tilting toward direct manufacturer-to-processor contracts, bypassing traditional wholesale layers. Greif Inc. leverages its North American manufacturing footprint to control bulk container supply chains. Mondi Group anchors European demand through integrated kraft paper and woven polypropylene operations. Conitex Sonoco specializes in multiwall and FIBC combinations for chemical sector clients.
Two-loop FIBC bags are large woven polypropylene containers with dual lifting straps sewn to the bag body, typically rated for 500 kg to 2,000 kg loads and constructed from coated or uncoated woven fabric with optional liner insertion. These bags serve primary industrial purposes in bulk powder and granular material handling across food processing, chemical manufacturing, and pharmaceutical ingredient transport. Standard bags occupy the volume base due to commodity chemical and construction mineral demand, while conductive bags command premium positioning in flammable powder applications where electrostatic discharge protection determines procurement. Liner bags segment growth tracks pharmaceutical and food-grade containment requirements where moisture and contamination barriers override cost sensitivity.
FDA food-contact regulations and EU REACH chemical compliance frameworks govern material composition and migration limits for FIBC bags serving regulated industries. ISO 21898 testing standards define cyclic top lift, drop, and tear resistance protocols that determine product qualification for international bulk shipment. Stakeholders must monitor evolving extended producer responsibility schemes and recycled content mandates that will reshape raw material sourcing decisions and compliance cost structures across manufacturing footprints.
Market Dynamics
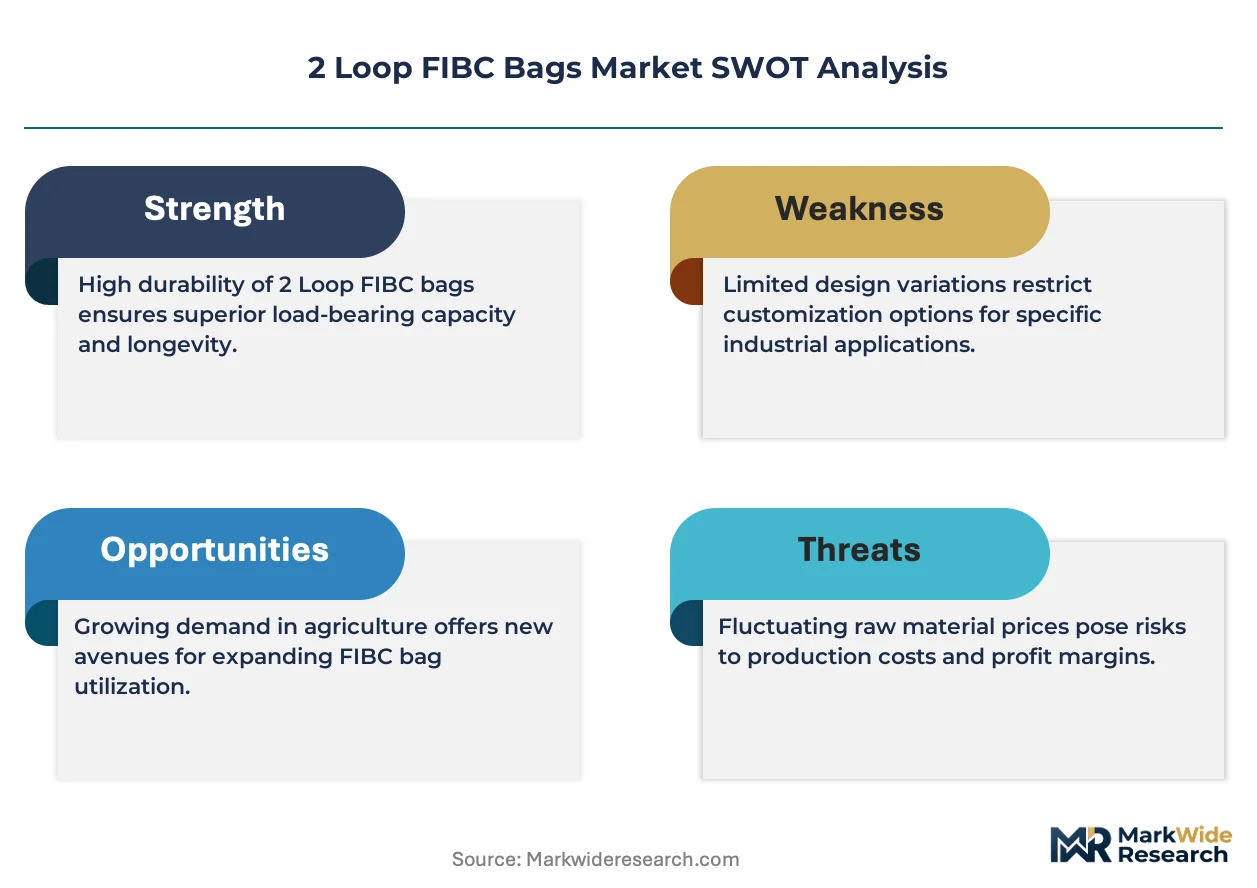
EU Packaging and Packaging Waste Regulation mandates are compressing polypropylene sourcing flexibility for woven bulk container manufacturers, forcing rapid recyclability certification investments across European production footprints.
Growth Catalysts
- REACH chemical compliance frameworks:Stringent EU migration limits for pharmaceutical ingredient transport are disqualifying uncertified competitors and consolidating procurement around qualified woven polypropylene suppliers with documented traceability systems.
- Brazilian agricultural commodity exporters:Soybean and coffee processors in Mato Grosso and São Paulo states are expanding bulk packaging procurement volumes for ocean freight containerization, creating dedicated demand corridors for two-loop FIBC configurations.
- Conductive fabric technology:Electrostatic discharge protection requirements in flammable powder handling are expanding the addressable market beyond standard commodity bags into premium-rated conductive variants with sewn-in grounding tabs.
Market Restraints
- Polypropylene resin price volatility:Propylene feedstock fluctuations tied to naphtha cracking economics in Middle Eastern and Asian supply basins compress margin predictability for woven fabric converters.
- Indian supply concentration:Gujarat and Maharashtra chemical processing corridors dominate qualified liner bag production, creating geographic vulnerability for pharmaceutical-grade containment procurement.
- Woven PP substitution by rigid IBCs:Stainless steel and composite intermediate bulk containers are capturing reusable-loop applications in high-frequency chemical transfer operations where bag disposal costs accumulate.
Strategic Opportunities
- Underpenetrated Vietnamese food processing:Mekong Delta rice and aquaculture exporters lack qualified local FIBC suppliers, creating first-mover positioning for ISO 21898-certified manufacturers establishing regional sewing operations.
- EU Green Deal recycled content mandates:Upcoming post-consumer polypropylene incorporation requirements will reward early movers with secured recycled woven fabric supply chains and pre-qualified circularity documentation.
- RFID-embedded inventory tracking:Convergence of woven container manufacturing with passive sensor integration enables pharmaceutical and chemical processors to automate batch traceability and customs documentation workflows.
Industry Challenges
- ISO 21898 cyclic top lift certification timelines:Testing protocol completion stretches 8-14 weeks for new fabric weights, delaying product launches and locking working capital in qualification inventory.
- Multi-jurisdiction compliance stacking:Simultaneous FDA food-contact, EU REACH, and BIS Indian standards certification requires dedicated regulatory affairs staffing that mid-scale manufacturers struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2 Loop FIBC Bags Market |
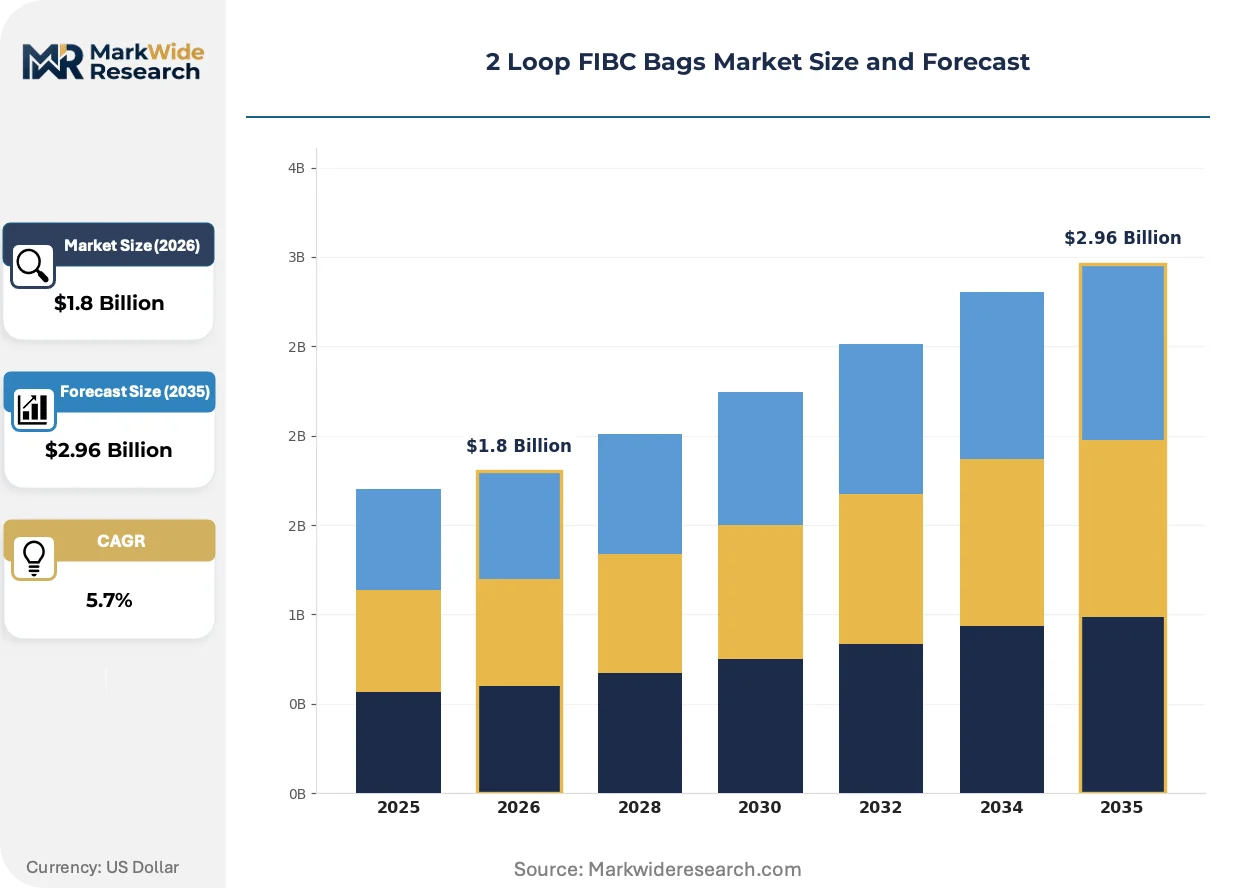
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bags, Conductive Bags, Liner Bags, UV Resistant Bags Application: Food, Chemicals, Pharmaceuticals, Construction Material: Polypropylene, HDPE, LDPE, Woven Fabric Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Berry Global Inc., Greif Inc., Conitex Sonoco, LC Packaging, Rishi FIBC Solutions, Mondi Group, RKW SE, Plastene India, Intertape Polymer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2 Loop FIBC Bags Market Strategic Shifts
Woven polypropylene bulk packaging is undergoing material and process transformation driven by circularity mandates and automation integration demands across chemical and pharmaceutical supply chains.
Ultrasonic sewing technology is collapsing the cost gap between traditional needle-stitched and thermally bonded lifting strap attachments. Pharmaceutical ingredient processors in Basel and Frankfurt are specifying ultrasonic seams for liner bag orders to eliminate fiber contamination risks from needle puncture holes. This process shift is collapsing the premium pricing previously commanded by specialized clean-room sewing facilities.
EU Green Deal packaging circularity requirements are mandating post-consumer recycled content thresholds in transport packaging by 2030. Woven polypropylene converters in Belgium and the Netherlands are piloting chemically recycled propylene feedstocks to meet color consistency and tensile strength specifications. Chemical sector buyers are responding with dual-source contracts that split volume between virgin and certified recycled-content bags during qualification phases.
Direct manufacturer-to-processor contracting is displacing layered wholesale distribution for standardized bag specifications. Chemical manufacturers in Ludwigshafen and Antwerp are consolidating annual FIBC procurement into single-source framework agreements with sewing operations, bypassing regional distributors. This channel compression is most advanced in German and Dutch chemical corridors where procurement teams have established internal technical specifications teams.
2 Loop FIBC Bags Market Segmentation
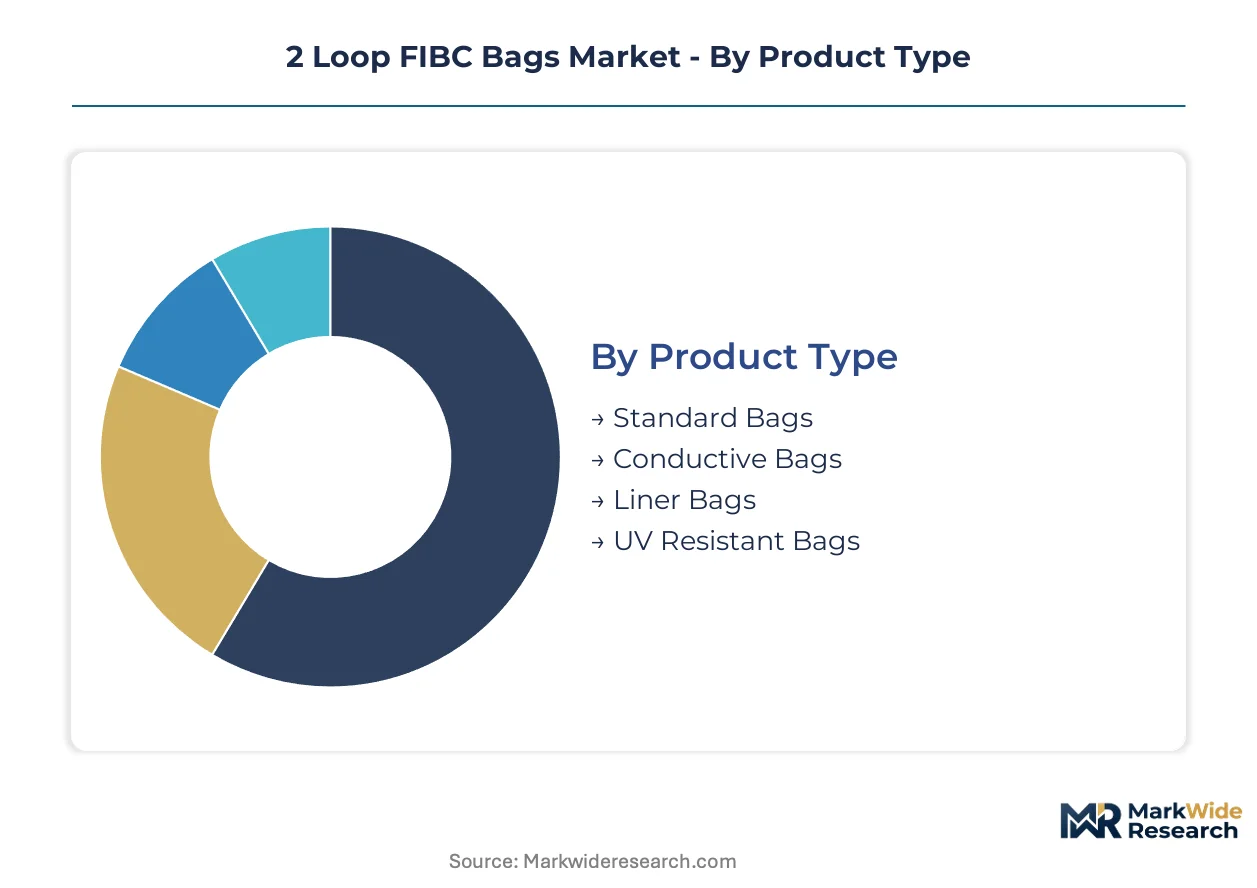
Two-loop FIBC bags segment across four distinct dimensions that shape procurement patterns and margin structures. Product type determines compliance burden and certification investment. Application verticals dictate performance specifications and replacement frequency. Material selection governs recyclability credentials under tightening EU mandates. Distribution channel choice reflects customer scale and technical specification complexity.
Product Type:
After-sales-service intensity varies sharply across product types, with conductive and liner bags demanding technical support for grounding verification and liner integrity testing that standard bags rarely require.
- Standard Bags:These uncoated or coated woven polypropylene containers serve commodity chemical and construction mineral handling where cost minimization dominates procurement. Demand concentrates in Brazilian soybean export corridors around Mato Grosso, where volume procurement for ocean freight containerization prioritizes unit economics over specialized features.
- Conductive Bags:Electrostatic discharge protection variants incorporate carbon-thread woven fabric with sewn-in grounding tabs for flammable powder applications. Pharmaceutical ingredient processors in Basel and Frankfurt specify these for solvent-based active pharmaceutical ingredient transport where spark ignition risks override cost sensitivity.
- Liner Bags:Moisture barrier configurations with inserted polyethylene liners serve food-grade and hygroscopic chemical containment. India's Gujarat pharmaceutical corridor dominates qualified production.
- UV Resistant Bags:Stabilized polypropylene fabric with hindered amine light absorbers extends outdoor storage durability for agricultural commodity stockpiling.
By volume, standard bags lead. By growth pace, liner bags are expanding most quickly.
Application:
Application segmentation tracks regulatory exposure intensity, with pharmaceutical and food verticals carrying FDA and EU REACH compliance burdens that construction and commodity chemical applications largely avoid.
- Food:FDA food-contact compliance mandates migration-tested polypropylene resin and documented chain-of-custody for grain, sugar, and dairy powder transport. Mekong Delta rice exporters in Vietnam drive unmet demand for ISO 21898-certified local supply.
- Chemicals:REACH-registered substances require woven containers with traceable fabric batch records and chemical resistance certification. Ludwigshafen and Antwerp chemical manufacturers consolidate procurement into direct manufacturer contracts.
- Pharmaceuticals:EMA-compliant containment demands ultrasonic-sewn liner bags eliminating needle puncture contamination risks. Basel processors specify clean-room assembly protocols.
- Construction:Mineral and cement handling tolerates lower specification tiers where cyclic top lift testing suffices without pharmaceutical-grade documentation.
Construction absorbs the highest unit volumes. Pharmaceutical applications command the steepest expansion trajectory.
Material:
Material cost tiers separate virgin polypropylene from recycled-content alternatives, with EU Green Deal mandates forcing rapid qualification of chemically recycled feedstocks to maintain tensile strength and color consistency.
- Polypropylene:Virgin and recycled-content woven polypropylene dominates fabric construction, with Belgian and Dutch converters piloting post-consumer chemically recycled propylene to meet 2030 circularity thresholds.
- HDPE:High-density polyethylene liners provide moisture barriers for hygroscopic chemical and pharmaceutical applications where polypropylene woven shells require supplemental protection.
- LDPE:Low-density polyethylene offers flexibility for liner insertion in food-grade configurations where conformability to bag corners matters.
- Woven Fabric:Multi-filament and tape-extruded weave patterns determine tear propagation resistance and cyclic fatigue performance under ISO 21898 testing protocols.
Polypropylene woven fabric anchors volume. Recycled-content variants are gaining share fastest.
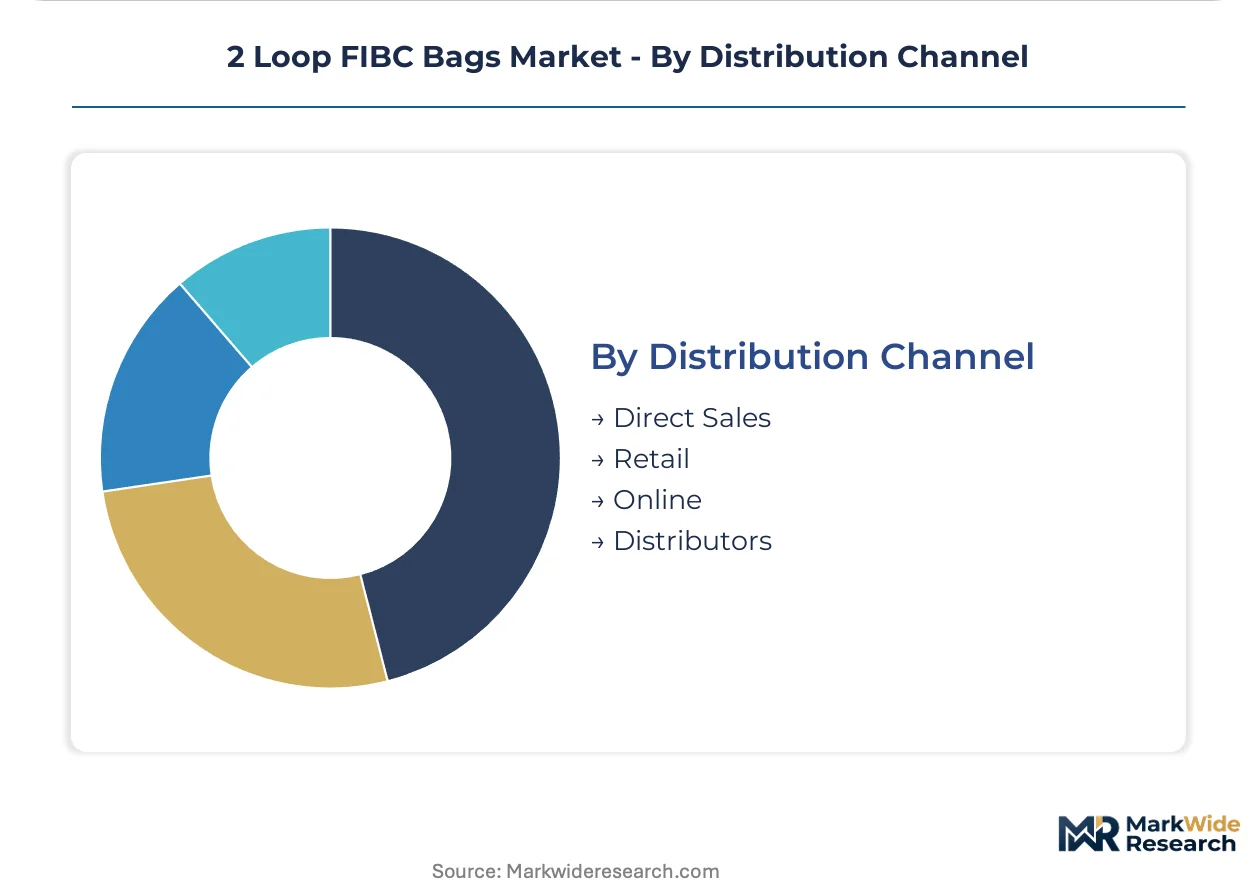
Distribution Channel:
Customer scale and technical complexity determine channel selection, with large chemical processors bypassing intermediaries while smaller agricultural buyers retain distributor relationships for inventory pooling.
- Direct Sales:Framework agreements between sewing operations and chemical manufacturers in German and Dutch corridors eliminate wholesale margins for standardized specifications with predictable annual volumes.
- Retail:Agricultural supply cooperatives and construction material yards stock standard bags for walk-up procurement by small-scale Brazilian coffee processors and regional contractors.
- Online:Digital procurement platforms serve mid-scale buyers seeking price transparency for commodity specifications where technical consultation requirements remain minimal.
- Distributors:Regional wholesalers maintain buffer inventory for pharmaceutical and food processors requiring rapid liner bag replacement without manufacturer lead times.
Direct sales capture the largest revenue pool. Online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH compliance mandates from ECHA are compressing sourcing flexibility for polypropylene-based bulk containers across European manufacturing footprints, while agricultural commodity exporters in Brazil and Southeast Asia drive procurement expansion outside regulatory-heavy zones.
Germany
Ludwigshafen and Antwerp chemical manufacturers consolidate annual FIBC procurement into direct manufacturer framework agreements, eliminating wholesale margins for standardized specifications. The EU Packaging and Packaging Waste Regulation forces rapid recyclability certification investments across German production sites. BASF's home corridor in Ludwigshafen anchors demand for REACH-registered substance containment with traceable fabric batch records.
India
Gujarat and Maharashtra chemical processing corridors dominate qualified liner bag production for pharmaceutical-grade containment, creating geographic concentration for EMA-compliant supply. BIS standards certification overlaps with FDA food-contact requirements for export-oriented processors. Ahmedabad and Mumbai clusters face working capital lock-up from ISO 21898 cyclic top lift testing timelines stretching 8-14 weeks.
Brazil
Soybean and coffee processors in Mato Grosso and São Paulo states expand bulk packaging procurement volumes for ocean freight containerization. ANVISA pharmaceutical regulations apply to limited domestic ingredient transport, leaving most demand driven by agricultural commodity export logistics. Santos port corridor operations prioritize unit economics over specialized bag features for commodity chemical handling.
Vietnam
Mekong Delta rice and aquaculture exporters lack qualified local FIBC suppliers, creating first-mover positioning gaps for ISO 21898-certified manufacturers. The country's national food safety regulator enforces migration limits for grain and seafood powder transport. Ho Chi Minh City logistics hubs currently import bulk containers from Thai and Chinese sewing operations, inflating landed costs.
United States
FDA food-contact regulations govern polypropylene resin composition for dairy and grain powder transport across Midwest agricultural processing belts. EPA industrial waste rules intersect with bag disposal cost accumulation in high-frequency chemical transfer operations. Texas and Louisiana petrochemical corridors source conductive bags for flammable powder handling where OSHA electrostatic discharge protocols apply.
2 Loop FIBC Bags Market Competitive Environment
Vertically integrated packaging conglomerates and specialized woven fabric converters split the market between scale-driven standard bag production and premium-tier certified containment. Consolidation pressure concentrates around REACH-registered suppliers with documented traceability systems, while mid-scale manufacturers struggle to retain dedicated regulatory affairs staffing for multi-jurisdiction compliance stacking. Two dominant competitive moves define current positioning: backward integration into polypropylene resin sourcing to compress feedstock volatility exposure, and geographic expansion into underpenetrated Vietnamese and Indonesian food processing corridors to capture first-mover certification advantages.
Among North American industrial packaging groups, Greif Inc. exemplifies the scale-driven archetype with captive manufacturing footprint control over bulk container supply chains. Mondi Group anchors European positioning through integrated kraft paper and woven polypropylene operations spanning multiple substrate technologies. Conitex Sonoco occupies a specialist position in multiwall and FIBC combination formats for chemical sector clients requiring hybrid containment solutions.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Greif Inc. |
| Conitex Sonoco |
| LC Packaging |
| Rishi FIBC Solutions |
| Mondi Group |
| RKW SE |
| Plastene India |
| Intertape Polymer Group |
| Others |
Value Chain & Pricing Dynamics
Middle Eastern and Asian naphtha cracking economics concentrate propylene feedstock pricing power upstream, compressing margin predictability for woven polypropylene converters downstream and forcing tiered pricing stratification across standard, conductive, and liner bag categories.
Pricing Analysis
European REACH-certified liner bags command 40-60% premiums over Brazilian commodity soybean export specifications, with price differentiation anchored in ISO 21898 certification tier and ultrasonic sewing protocol compliance. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service intensity, with conductive bags requiring grounding verification support. Pricing pressure stems from polypropylene resin volatility, with chemical sector buyers in Ludwigshafen and Antwerp consolidating procurement into direct contracts that eliminate distributor margins. Agricultural commodity exporters in Mato Grosso exhibit highest price sensitivity, while Basel pharmaceutical processors prioritize contamination risk mitigation over unit economics.
Supply Chain Analysis
Propylene feedstock draws from Middle Eastern petrochemical corridors and Asian naphtha cracking complexes, with woven fabric conversion concentrating in India, Belgium, and the Netherlands. Virgin and chemically recycled polypropylene pellets, multi-filament weaving looms, and conductive carbon-thread formulations constitute critical input dependencies. Single-source vulnerability pervades Gujarat and Maharashtra pharmaceutical-grade liner bag production, where ISO 21898 testing timelines lock working capital for 8-14 weeks. Distribution runs through direct manufacturer-to-processor framework agreements for large chemical accounts, with regional distributors maintaining buffer inventory for smaller agricultural and construction buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal circularity mandates fragment procurement patterns across recycled-content qualification tiers, creating specialist niches for certified converters with secured post-consumer polypropylene supply chains.
For Market Incumbents: Entrench positioning through backward integration into chemically recycled propylene feedstock sourcing and captive ultrasonic sewing capacity in Basel-Frankfurt pharmaceutical corridors. Rigid IBC substitution in high-frequency chemical transfer operations threatens reusable-loop bag volumes, demanding defensive certification investments in EMA-compliant clean-room assembly protocols. Geographic consolidation of European production footprints under unified recyclability documentation will compress mid-scale competitor margins. For New Entrants and Emerging Players: Mekong Delta rice and aquaculture exporters in Vietnam represent the most penetrable entry point, with ISO 21898-certified regional sewing operations enabling first-mover capture of unmet food-grade demand. Indonesian palm kernel and rubber powder processors offer secondary white-space targeting. Go-to-market execution should leverage digital procurement platform partnerships to bypass entrenched Thai and Chinese import channels serving Ho Chi Minh City logistics hubs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European woven fabric converters struggling to staff dedicated regulatory affairs teams for multi-jurisdiction compliance stacking. Long-term viability hinges on circularity credential pre-qualification ahead of 2030 EU recycled content mandates. Watch for BASF and Ludwigshafen chemical corridor procurement teams consolidating annual FIBC volumes into single-source frameworks as inflection signal for channel compression acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Supply Chain Securement | Belgian and Dutch converters piloting chemically recycled propylene gain pre-qualified circularity documentation for EU Green Deal compliance. |
| Ultrasonic Sewing Capacity Expansion | Pharmaceutical processors in Basel specify thermally bonded seams to eliminate needle puncture contamination risks in liner bags. |
| Direct Manufacturer Framework Agreements | Ludwigshafen and Antwerp chemical buyers bypass wholesale margins through annual volume consolidation with sewing operations. |
| RFID-Embedded Inventory Tracking Integration | Passive sensor convergence enables pharmaceutical batch traceability and automated customs documentation workflows. |
| Vietnamese Regional Sewing Operations Establishment | Mekong Delta rice exporters lack qualified local FIBC suppliers, inflating landed costs from Thai and Chinese imports. |
Study Parameters
A standing panel of plant managers at woven polypropylene converters, procurement leads at BASF and Antwerp chemical manufacturers, distribution channel partners in Brazilian agricultural cooperatives, and technical R&D directors provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation against customs and trade data, European Chemical Industry Council reports, SEC 10-K filings from packaging conglomerates, and ISO 21898 certification registry records. Bottom-up demand modeling from end-use verticals triangulated against top-down supply-side capacity assessments.
Scenario-bracketing anchored volume and value outputs across the projection horizon, with segmentation modeling spanning product type tier, application vertical regulatory exposure, material recyclability credential, and distribution channel complexity. CAGRs derived from fitted growth curves incorporating propylene feedstock price elasticity, REACH compliance cost pass-through rates, and agricultural commodity export volume correlations. Forecast inputs included EU Packaging and Packaging Waste Regulation implementation pace and Vietnamese food safety regulator enforcement intensity.
Practitioners should monitor polypropylene resin volatility spikes and EU Green Deal recycled content threshold announcements for early signals requiring forecast revision. Cross-checking against European Chemical Industry Council capacity utilization surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Compression Baggers Market
Bags and Containers
Insulated Delivery Bag Market
Bags and Containers
Breather Bags Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Plastic Bags and Sacks Market
Bags and Containers
Bag Clips Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Leno Bags Market
Bags and Containers
Frosted Bag Market
Bags and Containers
Bulk Bag Divider Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Craft Bags Market
Bags and Containers
Loose-Fill Peanuts Market