
 Textile Bags Market | 2026-2036
Textile Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Bags Market Analytics
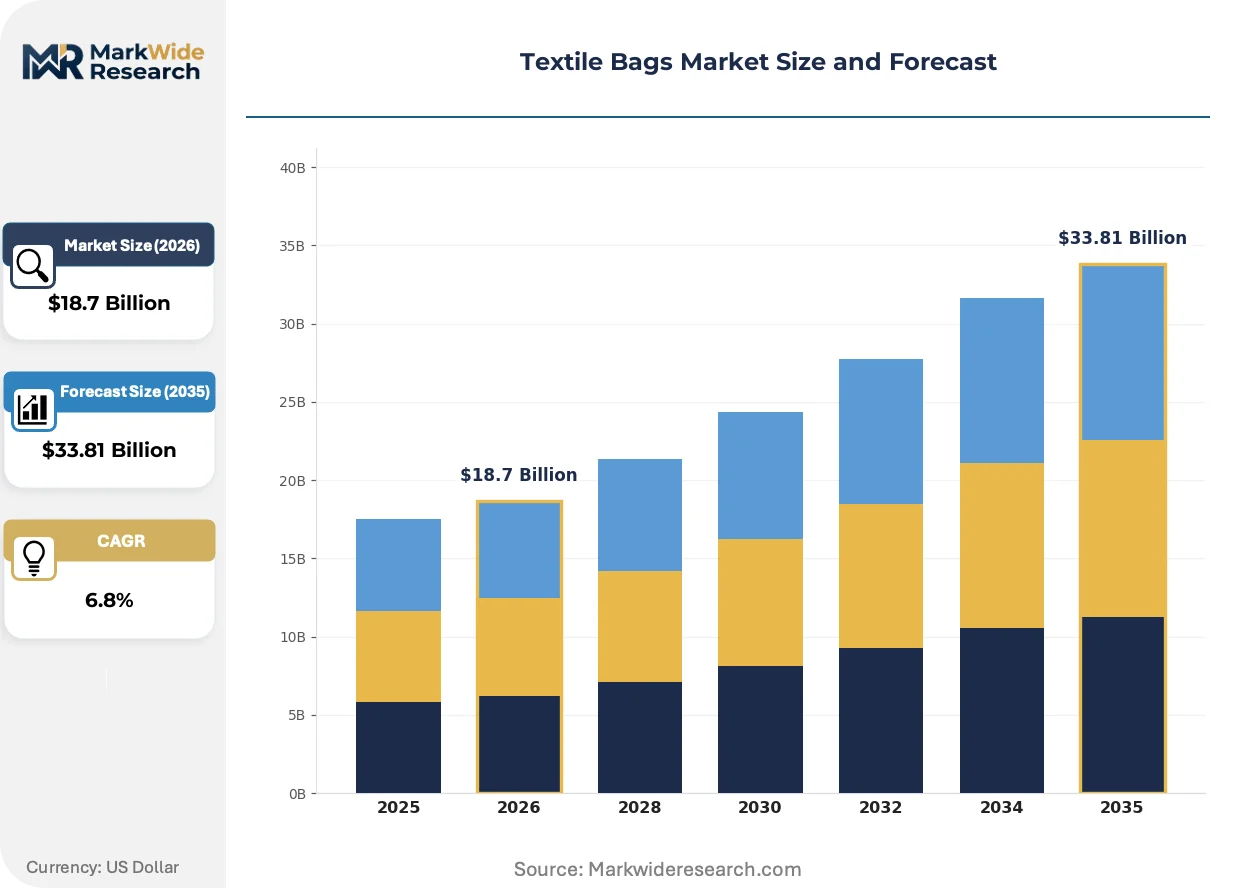
Subscription-based corporate branding programs is broadening how textile bags generate recurring revenue beyond one-time wholesale transactions. Hubco Inc. leverages vertical integration across woven polypropylene operations to control cost structures in industrial packaging. JohnPac, LLC sustains manufacturing scale through automated sewing lines serving bulk agricultural buyers. BIDBI LTD. differentiates via ethical certification programs that anchor premium positioning in European retail channels.
Textile bags are stitched or woven containers manufactured from natural fibers such as cotton and jute or synthetic filaments like polyester, typically rated for load capacities between five and twenty-five kilograms depending on construction density and seam reinforcement. These products serve retail branding, agricultural commodity handling, and consumer goods transport across commercial and institutional supply chains. Canvas and cotton materials dominate unit volume in fashion and grocery applications where breathability and printability command preference. Jute segments attract sustainability-driven procurement from European retailers seeking biodegradable alternatives under packaging waste directives. Polyester occupies the promotional and travel segments where water resistance and colorfastness justify synthetic content despite circularity concerns.
The EU Green Deal and REACH frameworks restrict chemical treatments in imported textile bags while mandating recycled content disclosures for products sold within member states. India's BIS certification requirements and PLI scheme incentives for jute processing are redirecting export capacity toward standardized sustainable supply chains. Stakeholders must monitor how diverging national labeling rules for biodegradability reshape sourcing decisions and factory audit protocols across origin markets.
Market Dynamics
EU Green Deal packaging waste directives are forcing retail procurement departments to requalify entire supplier bases around biodegradable fiber specifications and recycled content verification systems.
Growth Catalysts
- REACH chemical disclosure mandates:European retailers now require full material traceability, creating competitive advantage for certified South Asian exporters with BIS-compliant jute processing capabilities.
- Agricultural commodity handling:Grain cooperatives in the US Midwest are converting from polypropylene to woven cotton bulk bags for domestic transport, responding to food-contact safety preferences from downstream processors.
- Closed-loop recycling infrastructure:Mechanical shredding and fiber reclamation systems are lowering input costs for polyester bag manufacturers serving promotional merchandise distributors.
Market Restraints
- Jute fiber price volatility:Monsoon-dependent harvests in Bangladesh and West Bengal create raw material cost instability that compresses margin predictability for sustainable bag specialists.
- Polyester feedstock concentration:Purified terephthalic acid supply chains cluster around Chinese petrochemical complexes, exposing non-integrated converters to geopolitical freight disruptions.
- Biodegradability testing fragmentation:Divergent national composting standards between France's NF T 51-800 and Germany's DIN CERTCO create certification duplication costs for exporters serving multiple EU markets.
Strategic Opportunities
- India's PLI scheme for jute processing:Export-oriented manufacturers can capture incentive-backed capacity expansion in West Bengal's standardized fiber preparation facilities.
- Subscription-based corporate branding programs:Quarterly replenishment contracts for uniformed employee tote distributions replace transactional wholesale purchasing among Fortune 500 campus services teams.
- RFID-embedded inventory tracking:Combining woven construction with near-field communication tags enables closed-loop rental bag systems for grocery chains trialing reuse deposit schemes.
Industry Challenges
- Automated sewing line calibration:Precision tension control for natural fiber variability requires skilled technicians that bag factories in Vietnam and Indonesia struggle to retain.
- Multi-jurisdiction audit fatigue:Simultaneous compliance with EU Green Deal, India's BIS certification, and US FDA food-contact regulations stretches quality assurance departmental bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Bags Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Bags, Eco-Friendly Bags, Promotional Bags, Tote Bags Material: Canvas, Cotton, Jute, Polyester Application: Retail, Grocery, Travel, Fashion Distribution Channel: Online, Retail Stores, Supermarkets, Wholesale |
| Companies Covered | Hubco Inc., JohnPac, LLC, BIDBI LTD., Extrapack OOD, Xiamen Novelbag Co. Ltd., Blivus Bags Private Limited, Double R Bags, United Bags, Inc., Zest Tex International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Bags Market Evolving Landscape
Digital printing and automated cutting systems are compressing minimum order quantities while expanding design customization, enabling batch-size flexibility that reconfigures procurement relationships between converters and retail buyers.
Digital sublimation printing on polyester substrates is consolidating promotional bag production around regional print-service hubs. Corporate merchandise buyers now source finished decorated products within two-week turnaround windows. This geographic compression of decoration capacity is eliminating ocean-freight economics for low-margin commodity blanks.
EU Green Deal packaging waste directives mandate recycled content disclosures and restrict per- and polyfluoroalkyl substance treatments in imported textile bags. REACH enforcement through ECHA is blocking non-compliant shipments at Rotterdam and Hamburg. European retail chains are responding by pre-qualifying South Asian suppliers with third-party biodegradable certification.
Subscription replenishment contracts are displacing annual blanket purchase orders among corporate uniform and merchandise procurement teams. Facilities management departments at US technology campuses now contract for quarterly tote bag refresh programs. This purchasing pattern shift concentrates volume with vertically integrated converters capable of design-to-delivery cycle compression.
Textile Bags Market Segmentation
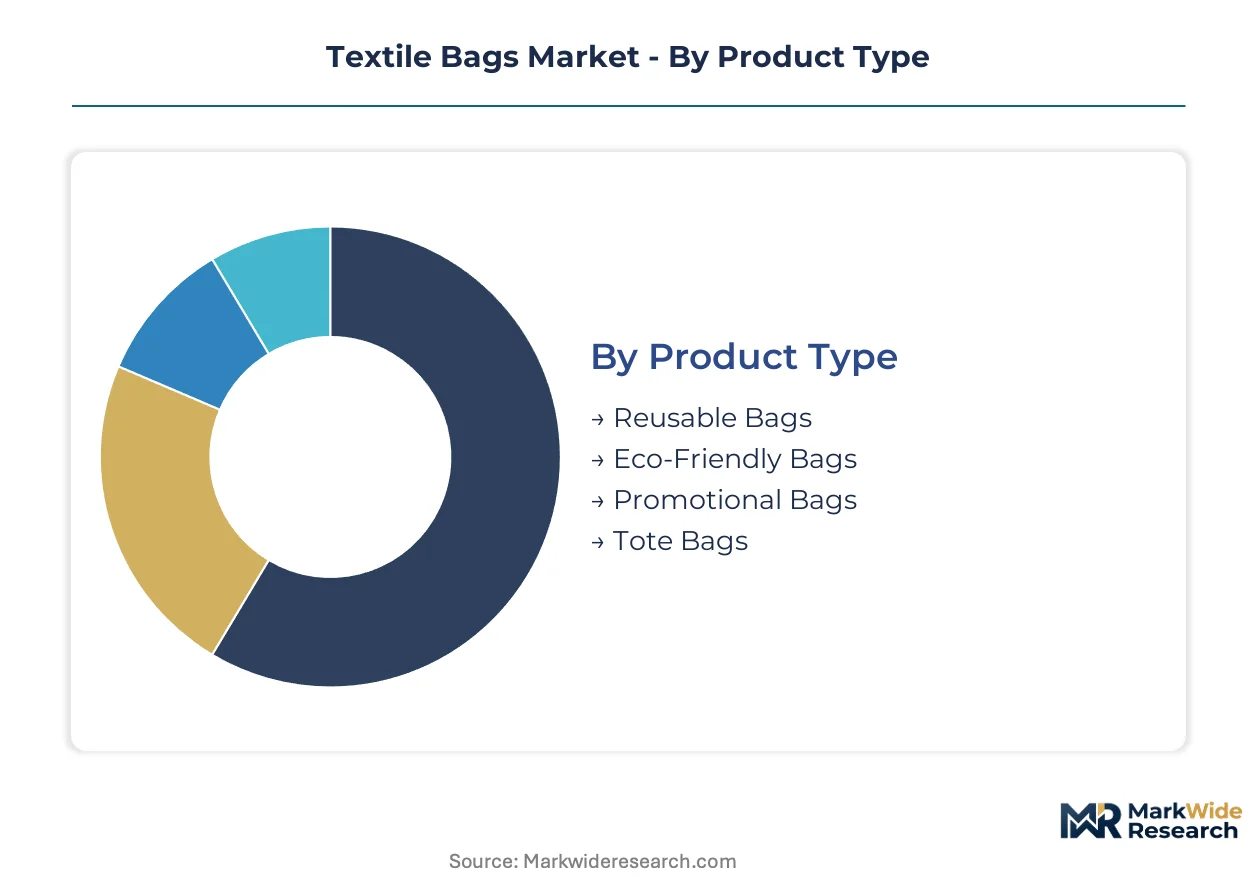
Textile bag procurement varies sharply by use case, with retail branding programs demanding print fidelity while agricultural buyers prioritize load ratings and seam durability. Material selection drives compliance pathways, as EU Green Deal mandates and India's BIS certification create divergent qualification requirements across export corridors.
Product Type:
Buyer differentiation centers on replenishment frequency and customization depth, with subscription corporate programs favoring standardized formats while event marketers chase short-run flexibility.
- Reusable Bags:Woven or non-woven constructions rated for 50+ use cycles dominate grocery chain deposit schemes and corporate campus services. EU retailers pre-qualify South Asian suppliers with biodegradable certification for these programs.
- Eco-Friendly Bags:Jute and organic cotton compositions carry third-party sustainability credentials that command premium positioning in European retail channels. India's PLI scheme incentives are expanding standardized fiber preparation capacity for this segment.
- Promotional Bags:Polyester substrates with digital sublimation decoration serve two-week turnaround requirements from corporate merchandise buyers.
- Tote Bags:Canvas and cotton variants anchor fashion and grocery applications where breathability and printability drive selection.
Volume sits with Reusable Bags; growth tilts toward Eco-Friendly Bags.
Material:
Cost tier stratification separates premium natural fibers from commodity synthetics, with certification grade and circularity credentials widening price spreads.
- Canvas:Heavy-duty cotton duck fabric rated for 15-25 kilogram loads serves agricultural commodity handling and fashion applications. US Midwest grain cooperatives are converting from polypropylene to woven cotton bulk bags for domestic transport.
- Cotton:Lightweight, breathable constructions dominate unit volume in grocery and fashion segments where printability and tactile appeal command preference.
- Jute:Biodegradable bast fiber from Bangladesh and West Bengal harvests attracts sustainability-driven procurement under EU packaging waste directives.
- Polyester:Water-resistant, colorfast filaments occupy promotional and travel segments despite circularity concerns; mechanical shredding infrastructure is lowering input costs for closed-loop recycling.
Supply concentrates in Cotton for unit volume; Jute posts the steepest expansion trajectory.
Application:
Volume scale separates mass retail from niche fashion, while regulatory exposure varies by end-use contact requirements.
- Retail:Branded carrier programs at European chains are replacing single-use plastics under EU Green Deal directives, with BIS-certified Indian exporters capturing share.
- Grocery:Breathable constructions for produce handling face food-contact safety scrutiny from downstream processors.
- Travel:Water-resistant polyester duffels and totes prioritize durability over biodegradability.
- Fashion:Premium canvas and cotton designs emphasize aesthetic customization and tactile quality.
Retail commands current volume; Fashion shows the fastest share gain.
Distribution Channel:
Customer type splits between institutional procurement teams and individual consumers, with contract structure and order frequency driving channel economics.
- Online:Direct-to-customer platforms enable batch-size flexibility and design customization through digital printing integration.
- Retail Stores:Branded carrier programs at point-of-sale locations convert foot traffic into reusable bag adoption.
- Supermarkets:Deposit-based reuse schemes and private-label tote programs anchor grocery chain sustainability commitments.
- Wholesale:Bulk agricultural buyers and promotional distributors source through automated sewing line operators with scale economics.
Wholesale holds volume dominance; Online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in South Asia while consumption concentrates in European retail channels, creating a trade-flow dependency that shapes regulatory compliance investments across export corridors.
India
Jute processing facilities in West Bengal supply biodegradable grocery totes to European supermarket chains under BIS certification protocols. The PLI scheme for jute processing incentivizes standardized fiber preparation capacity expansion. Kolkata-based exporters are pre-qualifying for EU Green Deal packaging waste directives through third-party biodegradable certification.
Germany
Retail procurement departments at major chains are requalifying supplier bases around REACH chemical disclosure mandates and DIN CERTCO composting standards. ECHA enforcement at Hamburg and Rotterdam ports blocks non-compliant textile bag shipments. The Ruhr industrial region hosts mechanical shredding operations that lower input costs for closed-loop polyester recycling.
United States
Midwest grain cooperatives are converting from polypropylene to woven cotton bulk bags for domestic agricultural commodity transport. FDA food-contact safety preferences from downstream processors drive material substitution. Automated sewing line operators in the Southeast serve bulk agricultural buyers with scale economics.
China
Purified terephthalic acid supply chains cluster around coastal petrochemical complexes, exposing polyester bag converters to freight disruption risks. Digital sublimation printing hubs in Guangdong province compress promotional bag turnaround times to two-week windows. SAMR oversight of recycled content labeling creates compliance friction for export-oriented manufacturers.
Bangladesh
Monsoon-dependent jute harvests in the Ganges Delta create raw material price volatility that compresses margin predictability for sustainable bag specialists. DGFT export facilitation programs support fiber preparation standardization. Dhaka-based converters are capturing share in EU retail channels through biodegradable certification alignment.
Textile Bags Market Competitive Landscape
Capital-heavy producers with captive weaving and sewing operations compete with asset-light designers that outsource manufacturing to contracted facilities. The vendor base separates into three tiers: vertically integrated specialists controlling fiber preparation through finished goods, regional converters with automated sewing scale, and design-forward brands relying on third-party decoration. Consolidation pressure favors players with backward integration into raw material sourcing and in-house certification compliance capabilities. Geographic expansion through distribution partnerships and portfolio diversification into subscription replenishment contracts represent the dominant competitive moves.
Among North American fabricators, Hubco Inc. and JohnPac, LLC exemplify the vertically integrated archetype with control over woven polypropylene operations and automated sewing lines respectively. BIDBI LTD. occupies a position within the premium-tier ethical certification segment, anchoring sustainable positioning in European retail channels. These three entities represent contrasting strategic postures: manufacturing scale, agricultural supply chain integration, and sustainability-driven brand differentiation.
| Leading Market Players |
|---|
| Hubco Inc. |
| JohnPac, LLC |
| BIDBI LTD. |
| Extrapack OOD |
| Xiamen Novelbag Co. Ltd. |
| Blivus Bags Private Limited |
| Double R Bags |
| United Bags, Inc. |
| Zest Tex International |
| Others |
Value Network & Pricing Analysis
Jute fiber procurement costs in Bangladesh and West Bengal cascade through three distinct pricing tiers, with monsoon-dependent harvest volatility compressing margins at the sustainable bag specialist tier while automated sewing scale in Vietnam protects standard-grade positioning.
Pricing Analysis
Cost-down pressure on biodegradable tiers accelerates because EU Green Deal compliance investments and third-party certification duplication across France's NF T 51-800 and Germany's DIN CERTCO inflate qualification overhead. Three-tier pricing structure across premium ethical certification, standard BIS-compliant, and economy polyester promotional levels separates buyers by sustainability mandate intensity. Certification grade and volume scale drive price differentiation, with Fortune 500 subscription contracts commanding schedule stability unavailable to transactional wholesale purchasers. Agricultural commodity handlers in the US Midwest exhibit highest price sensitivity due to polypropylene substitution economics, while European retail chains absorb premium positioning for biodegradable alternatives.
Supply Chain Analysis
Direct-to-retail channels handle European supermarket chain demand through Kolkata and Dhaka export corridors, with BIS-certified West Bengal facilities pre-qualified under REACH chemical disclosure mandates. Raw cotton and jute bast fiber draw from Bangladesh, India, and China's Xinjiang region, while purified terephthalic acid for polyester feedstock clusters around Chinese coastal petrochemical complexes. Single-source vulnerability in PTA supply exposes non-integrated converters to geopolitical freight disruptions. Distribution runs through automated sewing line operators in Vietnam and Indonesia serving bulk agricultural buyers, with digital sublimation hubs in Guangdong province compressing promotional bag turnaround windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
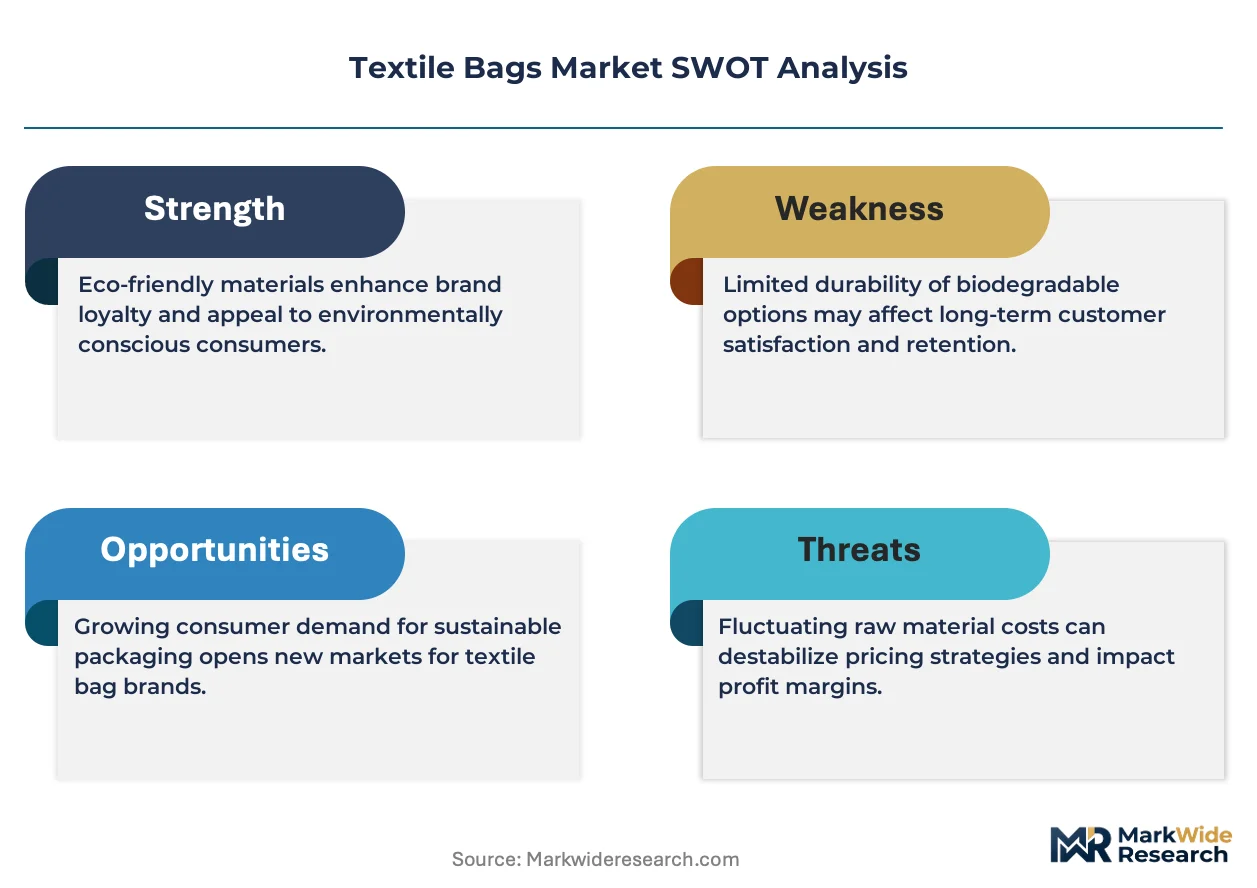
Standardized fiber preparation capacity in India's PLI scheme zones is the binding constraint propping sustainable tier pricing, as European retailer requalification timelines outpace qualified supplier expansion.
For Market Incumbents: Deepen backward integration into jute fiber preparation through West Bengal facility acquisitions, insulating margin structures from monsoon-driven raw material volatility. Secure multi-jurisdiction audit protocols simultaneously against EU Green Deal, India's BIS certification, and US FDA food-contact regulations to defend against emerging South Asian competitors with narrower compliance bandwidth. Prioritize automated sewing line calibration capabilities that natural fiber variability demands, as technician retention deficits in Vietnam and Indonesia create operational risk for scale-dependent rivals. For New Entrants and Emerging Players: Mid-tier agricultural cooperatives in the US Southeast represent an underserved buyer archetype seeking food-contact safe woven cotton alternatives to polypropylene bulk handling. Capture share through FDA-compliant fiber preparation investments and regional automated sewing partnerships, bypassing entrenched Midwest supply relationships. Position around quarterly replenishment contract structures that displace annual blanket purchase orders among facilities management departments at technology campuses. For Investors and Strategic Acquirers: Subscription contract penetration exceeding twenty-five percent of corporate merchandise procurement is the leading indicator that recurring revenue models have achieved structural viability in this market. Target vertically integrated specialists with captive weaving, in-house certification compliance, and established South Asian export corridor relationships for acquisition. Monitor RFID-embedded inventory tracking adoption rates among grocery chains trialing reuse deposit schemes as the inflection signal for closed-loop rental system scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Preparation | Captive jute processing in West Bengal insulates margins from monsoon-driven raw material cost spikes. |
| Multi-Jurisdiction Certification Investment | Simultaneous EU Green Deal, BIS, and FDA compliance creates defensive moats against audit-stretched competitors. |
| Subscription Replenishment Contract Conversion | Quarterly corporate campus refresh programs replace transactional wholesale purchasing with predictable recurring revenue. |
| RFID-Embedded Product Development | Near-field communication tags enable grocery chain reuse deposit schemes and closed-loop rental tracking. |
| Automated Sewing Line Scale Expansion | Precision tension control capabilities address natural fiber variability that manual operations in Vietnam struggle to retain. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with jute processing facility managers, European retail procurement directors, agricultural cooperative grain handlers, and automated sewing line operators. ECHA enforcement databases, India's BIS certification registries, and US FDA food-contact substance notifications provided compliance pathway validation. Bottom-up fiber preparation capacity assessments and top-down retail chain procurement spend estimates were triangulated against export corridor shipment manifests.
Data-stream reconciliation across material segmentation, application use cases, and distribution channel economics shaped the analytical framework over the projection horizon. Modeled dimensions included product type, material composition, end-use application, and regional regulatory cluster. CAGRs were derived from shipment volume trajectories and value-per-unit trends across certified sustainable and commodity polyester tiers. Jute fiber harvest variability coefficients and REACH enforcement blocking rates at Rotterdam and Hamburg served as industry-specific forecast sensitivity inputs.
Revisions become necessary when EU Green Deal packaging waste directive amendments, India's PLI scheme incentive adjustments, or Bangladesh monsoon failure patterns materialize outside base-case assumptions. Forecasts reflect documented assumptions regarding fiber preparation standardization timelines and retailer requalification velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bag & Bag Aerosol Can Market
Bags and Containers
Wicketless Bags Market
Bags and Containers
Global Bag Filling Machines Market
Bags and Containers
Quad Seal Bag Market
Bags and Containers
Pasted Valve Bags Market
Bags and Containers
Big Bag Discharge Station Market
Bags and Containers
Inner Bulk Liners Market
Bags and Containers
Wicketed Bags Market
Bags and Containers
Heat Sealing Bags Market
Bags and Containers
On the Go Packaging Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Loop Handle Bags Market
Bags and Containers
Self-Sealing Bags Market
Bags and Containers
FIBC Market
Bags and Containers
Vacuum Shrink Bags Market
Bags and Containers
Twin Seal Bags Market