
 Side Gusset/Quad Seal Bag Market | 2026-2036
Side Gusset/Quad Seal Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Side Gusset/Quad Seal Bag Market Outlook
Digital printing integration with flexographic workflows is narrowing the minimum order quantities for customized side gusset and quad seal bag production. Glenroy leverages in-house extrusion capabilities to control laminate quality across pharmaceutical and food-grade specifications. Amcor sustains global supply chain scale across multiple continents, while Mondi Group specializes in fiber-based barrier solutions that compete with conventional plastic laminates.
Side gusset and quad seal bags are multi-panel flexible packaging constructions formed from flat web stock, sealed along four edges with gusseted side panels that expand to accommodate bulk contents; quad seal variants add corner seals for enhanced cube efficiency and shelf stability, typically manufactured from oriented polypropylene, polyethylene terephthalate, or aluminum oxide-coated films via continuous form-fill-seal processes. The food packaging end user segment dominates volume consumption, driven by coffee, snack, and dry goods applications where oxygen transmission rates below 0.1 cc/m²/day preserve flavor integrity. Biodegradable plastics represent the fastest-expanding material category, though plastic laminates still anchor margin pools due to established barrier performance and lower unit costs at commercial scale.
FDA food contact substance regulations govern laminate compositions for US-bound products, while the EU F-Gas Regulation and REACH framework restrict certain fluorinated barrier chemistries in European supply chains. EFSA migration limit standards further shape material selection for food-contact layers across EU member states. Stakeholders must monitor evolving extended producer responsibility schemes and substrate recyclability certifications, as these criteria increasingly determine retailer acceptance and market access across major economies.
Market Dynamics
Material recovery mandates under the EU Packaging and Packaging Waste Regulation are forcing laminate suppliers to redesign multi-layer constructions while maintaining oxygen barrier performance below 0.1 cc/m²/day for coffee and snack applications.
Growth Catalysts
- High-barrier film demand from German confectionery:Chocolate and premium snack producers in Germany specify aluminum oxide-coated PET constructions for 18-month shelf-life requirements, pulling volume toward centralized European converters.
- REACH-compliant fluorinated barrier phase-out:ECHA restrictions on perfluorinated compounds are accelerating migration to silicon oxide and bio-based barrier coatings for EU-bound food packaging.
- Digital print-to-order workflows:Flexographic hybrid presses with inline color management are compressing minimum order quantities from 50,000 units toward 5,000-unit customized runs for regional coffee roasters.
Market Restraints
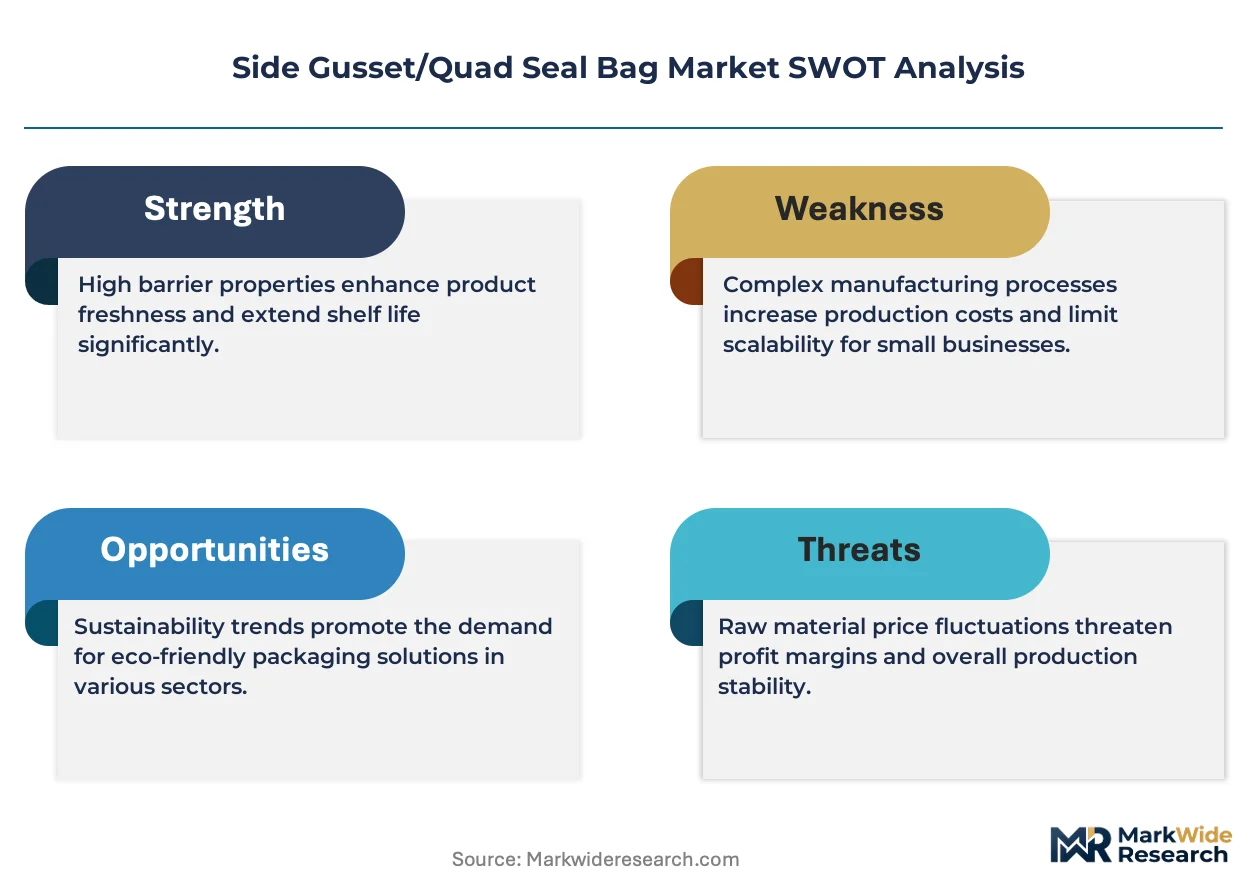
- Aluminum price volatility:Foil-dependent high-barrier laminates face margin compression when London Metal Exchange aluminum contracts swing beyond 15% quarterly bands, forcing converters to absorb or pass through costs.
- Oriented polypropylene supply concentration:Three Southeast Asian resin producers control 60% of biaxially oriented PP feedstock for gusseted bag webs, creating single-source vulnerability for mid-tier converters.
- Biodegradable oxygen barrier gap:PLA and PHA films currently transmit 10-50x more oxygen than conventional EVOH laminates, limiting their deployment in coffee and nut applications beyond short-turnover retail channels.
Strategic Opportunities
- Indian specialty coffee retail expansion:Third-wave roasters in Bangalore and Mumbai are importing European-specification quad seal formats for 250g and 1kg premium single-origin retail, creating demand for localized high-barrier converting capacity.
- Fiber-based barrier convergence:Mondi's paper-based barrier solutions paired with heat-sealable bio-coatings are opening shelf-stable dry goods applications previously locked to plastic laminates.
- Extended producer responsibility premiums:Retailers in France and Germany now pay 8-12% packaging fee premiums for mono-material or certified-recyclable side gusset constructions, rewarding upstream design investment.
Industry Challenges
- Multi-layer delamination during mechanical recycling:Conventional PET/PE/foil laminates fragment in existing European sorting infrastructure, requiring costly solvent-based separation investments that most municipal systems lack.
- Migration testing timeline compression:EFSA food-contact notifications for novel bio-based adhesives now require 18-24 month evaluation cycles, delaying product launches for converters serving pan-EU brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Side Gusset/Quad Seal Bag Market |
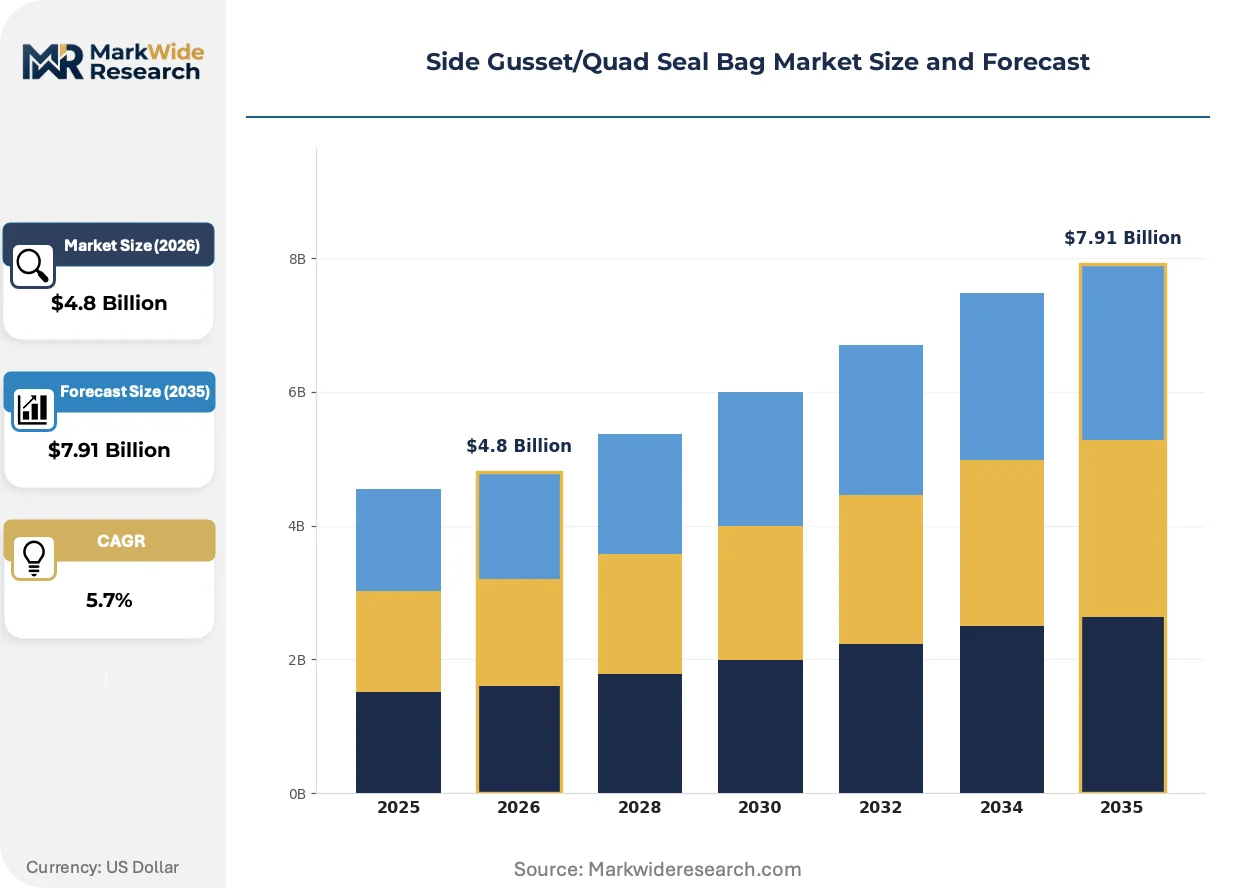
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Side Gusset Bags, Quad Seal Bags, Flat Bags, Stand-Up Pouches Material: Plastic, Paper, Biodegradable Plastics, Aluminum Foil End User: Food Packaging, Pet Food, Pharmaceutical, Personal Care Closure Type: Zip Lock, Heat Seal, Adhesive Seal, Tear Notch |
| Companies Covered | Glenroy, Swiss Pack, Amcor, Foster Packaging Pty Ltd, Tyler Packaging Limited, Mondi Group, Coveris, Diamond Flexible Packaging, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Side Gusset/Quad Seal Bag Market Strategic Shifts
Active barrier technologies and substrate redesign are compressing traditional trade-offs between shelf-life performance and end-of-life recyclability, forcing converters to requalify entire laminate stacks.
Water-based high-barrier coatings incorporating graphene oxide platelets are collapsing the oxygen transmission rate gap between conventional metallized films and emerging mono-material solutions. Specialty coffee roasters in Portland and Copenhagen are piloting these coatings for 12-month shelf-life claims. The technology is collapsing the premium pricing power of aluminum foil laminates in sub-500g retail formats.
The EU F-Gas Regulation's phase-down schedule for hydrofluorocarbon blowing agents is redirecting investment toward physical vapor deposition barrier systems. German and Italian film extruders are retrofitting vacuum coating lines to deposit silicon oxide layers at thicknesses below 50 nanometers. Coffee packaging lines in Hamburg and Milan are most affected, with technical teams revalidating heat-seal windows for the new substrate surface energies.
Brand owners are consolidating supplier panels from twelve to three approved converters per region, demanding audited carbon footprint data and recyclability certifications as table stakes for RFP participation. This concentration is displacing spot-market purchasing for seasonal promotional SKUs. The shift is most visible in Nordic markets, where ICA and Coop retail chains now require ISO 14001 certification and third-party recyclability validation for all flexible packaging suppliers.
Side Gusset/Quad Seal Bag Market Segmentation
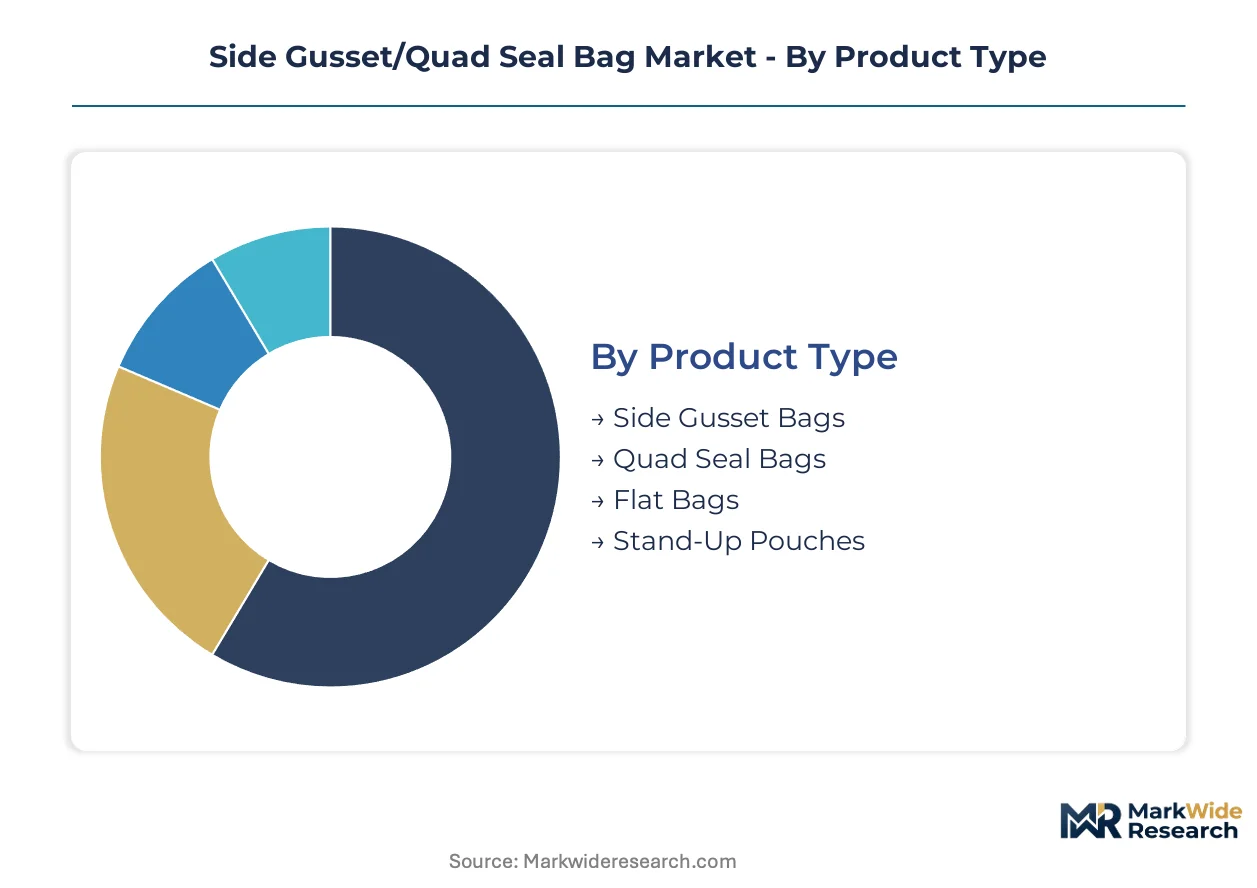
Segmentation in side gusset and quad seal bag markets reveals how barrier specifications, shelf-life requirements, and retail channel formats drive purchasing patterns across converters and brand owners. Understanding these divisions exposes where margin pools concentrate and where material innovation is displacing conventional constructions.
Product Type:
End-use applications span premium retail presentation through bulk industrial handling, with each format optimizing for cube efficiency, shelf stability, or production throughput.
- Side Gusset Bags:Two-panel constructions with expandable side folds accommodate volume expansion for coffee and dry goods. German confectionery producers specify these for 500g-1kg chocolate SKUs requiring 18-month oxygen barriers below 0.1 cc/m²/day.
- Quad Seal Bags:Four-corner sealing delivers superior stackability and vertical shelf presence. Pet food brands in North America are accelerating purchases for premium dry kibble presentation in 2.5kg and 5kg formats.
- Flat Bags:Simple two-seam constructions prioritize production speed over expansion capacity. Snack manufacturers deploy these for single-serve portions where barrier demands are moderate.
- Stand-Up Pouches:Bottom gusseting enables vertical display without secondary packaging. Specialty coffee roasters in Portland and Copenhagen pilot these for retail differentiation.
Established volume favors Side Gusset Bags; emerging adoption favors Quad Seal Bags.
Material:
Substrate selection balances oxygen transmission performance against end-of-life recovery pathways under tightening EPR schemes.
- Plastic:Multi-layer PET/PE/EVOH laminates dominate commercial scale with proven barrier below 0.1 cc/m²/day. REACH-compliant reformulations are accelerating as ECHA restricts fluorinated chemistries.
- Paper:Fiber-based barrier solutions from Mondi and competitors compete for dry goods applications previously locked to plastic. Heat-sealable bio-coatings are opening shelf-stable categories.
- Biodegradable Plastics:PLA and PHA films transmit 10-50x more oxygen than conventional laminates, limiting deployment to short-turnover retail channels.
- Aluminum Foil:Metallized and foil laminates anchor high-barrier segments but face margin compression from London Metal Exchange volatility beyond 15% quarterly bands.
Plastic laminates anchor current margin pools; biodegradable substrates face the steepest technical barriers to mainstream adoption.
End User:
Customer verticals impose distinct migration limits, sterilization requirements, and shelf-life specifications that filter converter qualification.
- Food Packaging:Coffee, snack, and dry goods applications drive volume consumption. FDA food contact substance regulations govern US-bound laminate compositions.
- Pet Food:Premium dry kibble brands specify quad seal formats for retail differentiation. Glenroy and comparable converters maintain pharmaceutical-grade extrusion controls for this segment.
- Pharmaceutical:Blister-compatible barrier films require validated sterility assurance. EFSA migration limit standards shape material selection for EU-bound medical packaging.
- Personal Care:Cosmetic and hygiene applications prioritize aesthetic surface printability over extended shelf-life performance.
Food Packaging concentrates procurement volume; Pet Food represents the fastest-expanding specification tier.
Closure Type:
Resealability features differentiate retail-facing formats from single-use industrial packaging.
- Zip Lock:Interlocking plastic tracks enable repeated opening for multi-serve contents. Coffee roasters specify these for 250g-1kg retail formats.
- Heat Seal:Thermal fusion delivers hermetic integrity for shelf-stable goods. Form-fill-seal lines in Hamburg and Milan are revalidating seal windows for silicon oxide-coated substrates.
- Adhesive Seal:Pressure-sensitive tapes suit promotional and seasonal SKUs with shorter distribution cycles.
- Tear Notch:Mechanical perforations provide controlled opening without reseal functionality. Single-serve snack portions favor this lowest-cost option.
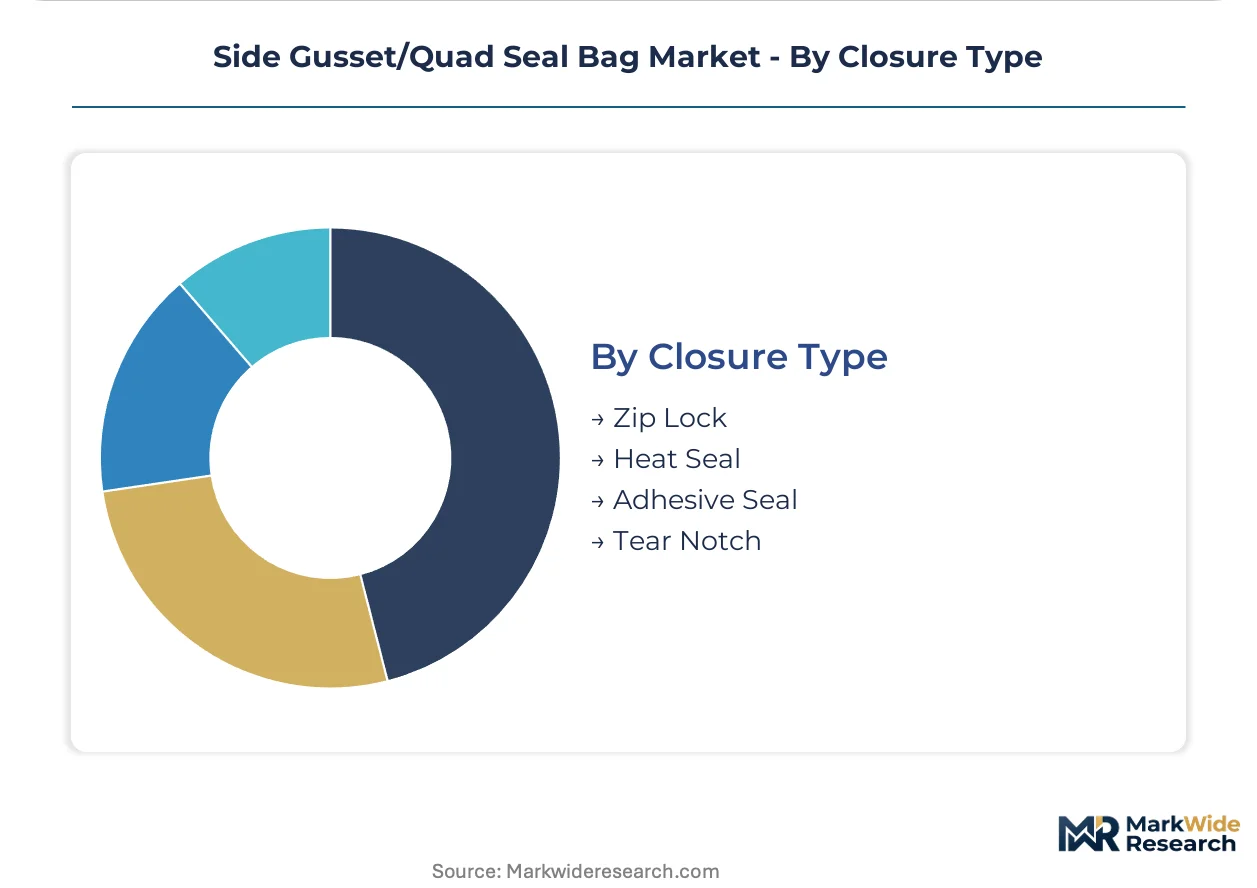
Heat Seal dominates industrial throughput; Zip Lock commands retail premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters export high-barrier side gusset laminates to Nordic retail chains, while Southeast Asian resin producers supply oriented polypropylene feedstock to mid-tier bag manufacturers across India and China.
Germany
Confectionery and coffee roasters in Hamburg and Berlin drive specification demand for aluminum oxide-coated PET with sub-0.1 cc/m²/day oxygen transmission. The EU Packaging and Packaging Waste Regulation tightens material recovery targets, forcing laminate redesign. Bavarian film extruders retrofit vacuum coating lines for silicon oxide barrier deposition below 50 nanometers.
United States
Pet food brands accelerate quad seal purchases for premium dry kibble presentation in 2.5kg and 5kg formats. FDA food contact substance regulations govern laminate compositions for domestic and export-bound production. Portland specialty coffee roasters pilot graphene oxide water-based barrier coatings for 12-month shelf-life claims.
India
Third-wave coffee roasters in Bangalore and Mumbai import European-specification quad seal formats for 250g and 1kg premium single-origin retail. The country's national food safety regulator enforces migration limits for food-contact packaging materials. Localized high-barrier converting capacity remains underdeveloped, creating import dependency for oxygen-barrier specifications.
China
Snack manufacturers deploy flat bag constructions for single-serve portions with moderate barrier demands. The Ministry of Ecology and Environment advances dual carbon goals that pressure converters toward mono-material designs. Yangtze River Delta film producers dominate biaxially oriented PP web supply for regional gusseted bag converters.
France
Retailers pay 8-12% packaging fee premiums for mono-material or certified-recyclable side gusset constructions under extended producer responsibility schemes. EFSA migration limit standards shape adhesive and coating selection for pan-EU brand owners. Paris-based converters consolidate supplier panels and demand audited carbon footprint data for RFP participation.
Side Gusset/Quad Seal Bag Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply relationships. The vendor base clusters around three archetypes: integrated film extruders with in-house barrier coating, regional converters with digital print-to-order capabilities, and multinational laminate suppliers with pharmaceutical-grade quality systems. Competitive moves center on M&A for geographic coverage and capacity expansion for high-barrier silicon oxide deposition lines.
Within the integrated extruder tier, Glenroy and Amcor exemplify scale-driven positions. Glenroy represents North American captive supply capabilities for pharmaceutical and food-grade specifications. Amcor anchors multinational supply chain scale across multiple continents. Mondi Group occupies a fiber-based barrier specialization that competes with conventional plastic laminates.
| Leading Market Players |
|---|
| Glenroy |
| Swiss Pack |
| Amcor |
| Foster Packaging Pty Ltd |
| Tyler Packaging Limited |
| Mondi Group |
| Coveris |
| Diamond Flexible Packaging |
| ProAmpac |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta film extrusion clusters anchor global oriented polypropylene feedstock supply, translating resin availability volatility directly into converter margin compression across mid-tier bag manufacturers in India and Southeast Asia.
Pricing Analysis
Current-generation silicon oxide barrier coatings command premium positioning over prior-generation aluminum foil laminates, while next-generation graphene oxide platelet technologies compress the pricing gap further. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade specifications from food-grade and industrial-tier constructions. Price differentiation centers on oxygen transmission certification tier and volume scale commitment. Pricing pressure stems from London Metal Exchange aluminum volatility forcing converters to absorb or pass through quarterly cost swings. Small regional roasters exhibit highest price sensitivity; multinational pet food brands show lowest.
Supply Chain Analysis
Contract manufacturing concentration sits with German and Italian vacuum coating specialists retrofitting barrier deposition lines below 50 nanometer thicknesses. Geographic supply concentration clusters in Germany, China, and India for finished bag converting, with Southeast Asian resin producers feeding oriented polypropylene webstock. Raw material dependencies center on biaxially oriented PP resin, EVOH barrier films, and aluminum oxide deposition targets. Single-source vulnerability pervades the three Southeast Asian producers controlling sixty percent of oriented PP feedstock. Distribution runs through brand-owner consolidated supplier panels demanding audited carbon footprint data as RFP table stakes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty coffee consumption cycles drive this market's recovery trajectory, with third-wave retail expansion in Bangalore and Mumbai pulling European-specification quad seal demand through import channels.
For Market Incumbents: Entrench barrier coating capabilities through in-house vacuum deposition retrofitting, defending against silicon oxide specialist entrants from Bavarian and Lombardy extrusion clusters. Prioritize REACH-compliant fluorinated barrier phase-out acceleration to capture EPR premium positioning in French and German retail chains. Certification investment in ISO 14001 and third-party recyclability validation locks out spot-market competitors from Nordic ICA and Coop supplier panels. For New Entrants and Emerging Players: Indian specialty coffee retail underpenetration offers localized high-barrier converting capacity buildout opportunity, importing European quad seal specifications for 250g and 1kg premium single-origin formats. Target biodegradable oxygen barrier gap remediation through PLA/PHA bio-coating partnerships with Bangalore roasters seeking short-turnover retail channel positioning. Go-to-market leverage rests on digital print-to-order workflows compressing minimum order quantities toward 5,000-unit customized runs. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational laminate suppliers divesting non-core flexible packaging divisions amid brand-owner supplier panel consolidation from twelve to three approved converters per region. Five-to-ten year viability frames around extended producer responsibility scheme maturation and substrate recyclability certification standardization. Signal to watch: EFSA migration testing timeline compression for novel bio-based adhesives indicating regulatory pathway clarity for acquisition target qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Coating Line Retrofit | German extruders deposit silicon oxide below 50 nanometers for coffee packaging heat-seal revalidation. |
| Digital Print-to-Order Workflow | Flexographic hybrid presses compress minimum order quantities toward 5,000-unit regional roaster runs. |
| Extended Producer Responsibility Certification | Mono-material constructions capture 8-12% packaging fee premiums from French and German retailers. |
| REACH-Compliant Barrier Migration | ECHA fluorinated compound restrictions accelerate silicon oxide and bio-based coating adoption. |
| Supplier Panel Consolidation Defense | Audited carbon footprint data and ISO 14001 certification secure RFP participation in Nordic retail chains. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with packaging converters, brand-owner procurement directors, and film extrusion plant managers; and secondary validation through customs trade records, SEC filings of publicly traded laminate suppliers, and EFSA food-contact notification databases. Bottom-up volume triangulation across product type, material substrate, and end-use segment dimensions intersected with top-down macroeconomic framing. Primary stakeholder roles included technical directors at German confectionery converters, coffee roaster packaging specification leads in Portland and Copenhagen, and EPC contractors for vacuum coating line installations.
Forecast inputs considered segment-level volume trajectories across side gusset, quad seal, flat bag, and stand-up pouch formats, material migration patterns from plastic laminates toward fiber-based and biodegradable alternatives, and closure type adoption curves. Modeling spanned the projection horizon with CAGRs derived from segment-specific growth drivers including pet food premiumization, specialty coffee retail expansion, and EPR scheme implementation. Industry-specific inputs incorporated EVOH barrier film supply constraints, aluminum oxide coating capacity buildout timelines, and digital printing technology penetration curves.
Practitioners should monitor aluminum price volatility beyond fifteen percent quarterly bands, EFSA bio-based adhesive migration testing backlogs, and brand-owner supplier panel consolidation velocity for early signals of forecast revision necessity. Quarterly review of London Metal Exchange aluminum contract movements, ECHA restriction implementation timelines, and Nordic retailer certification requirement updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Ventilated Bulk Bags Market
Bags and Containers
Clay Desiccant Bag Market
Bags and Containers
Quad Seal Bag Market
Bags and Containers
Wicketed Bags Market
Bags and Containers
Child Resistant Bags Market
Bags and Containers
Type-C Bulk Bags Market
Bags and Containers
Garbage Bag Market
Bags and Containers
Liner Bags Market
Bags and Containers
Lay Flat Bags Market
Bags and Containers
Bulk Bag Divider Market
Bags and Containers
Conical Top Bulk Bag Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Archive Boxes Market
Bags and Containers
Isothermal Bags and Containers Market
Bags and Containers
Bag-In-Bottle Market