
 Shopping Bag Market | 2026-2036
Shopping Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Shopping Bag Market Intelligence
Modular sizing across small, medium, and large configurations is pivoting how retailers manage inventory and consumer choice. Novolex leverages its North American manufacturing footprint to sustain consistent supply for grocery chains. Mondi Group anchors European demand through specialized kraft paper solutions. Smurfit Kappa competes on integrated fiber sourcing and converting capabilities.
Shopping bags are fabricated from plastic films, kraft paper, woven cotton, or jute fibers, typically featuring handles, gussets, and load-bearing seams designed to transport consumer goods from point of sale. Production involves extrusion, papermaking, weaving, or stitching, with performance calibrated to specified weight capacity and reuse cycles. Paper and cotton segments capture premium positioning as retailers phase out conventional plastics. Reusable and biodegradable styles are expanding fastest, though plastic retains volume dominance in emerging markets where cost thresholds govern procurement.
The EU's Single-Use Plastics Directive and REACH chemical standards constrain material inputs and mandate recyclability disclosures across European supply chains. The US EPA and state-level bag bans in California and New York shape regional product specifications and distribution eligibility. China's SAMR enforces national standards for plastic product labeling and thickness minimums. Stakeholders must monitor evolving extended producer responsibility frameworks and material certification requirements to align sourcing with compliance timelines.
Market Dynamics
The EU's Single-Use Plastics Directive is compressing virgin plastic bag volumes while redirecting procurement toward certified compostable and recycled-content alternatives across European retail supply chains.
Growth Catalysts
- E-commerce fulfillment surge:Online retailers in China and the United States are specifying heavier-gauge shipping-compatible bags with reinforced handles and tamper-evident closures for last-mile durability.
- REACH chemical standards:European converters are reformulating inks and adhesives to eliminate restricted substances, opening certified supply contracts with supermarkets seeking compliance documentation.
- Closed-loop fiber recovery:German and French paper mills are integrating post-consumer kraft pulp into bag-grade stocks, securing renewable feedstock commitments from grocery chains.
Market Restraints
- Polypropylene price volatility:Woven bag manufacturers in India face margin compression when propylene feedstock costs spike, forcing spot purchasing or inventory write-downs.
- Chinese supply concentration:Over half of global non-woven bag capacity clusters in Zhejiang and Guangdong provinces, exposing buyers to single-region logistics disruptions.
- Mechanical recycling limitations:Multi-layer laminated structures with polyethylene barriers cannot be processed through conventional municipal streams, limiting circular claims.
Strategic Opportunities
- Extended producer responsibility frameworks:France's Citeo system and Italy's CONAI scheme create funded collection infrastructure that rewards participating bag producers with lower compliance fees.
- Blockchain traceability integration:Combining RFID tagging with distributed ledger verification allows premium fashion retailers to document recycled-content provenance for consumer-facing claims.
- Reusable bag-as-a-service models:Dutch supermarket chains are piloting deposit-return systems for durable polypropylene totes, shifting unit economics from single-sale to recurring rental revenue.
Industry Challenges
- Composting certification timelines:TUV Austria's OK Compost HOME and BPI industrial certification processes require 6-12 month validation cycles that delay product launches.
- Legacy heat-sealing equipment incompatibility:Converters running vintage ultrasonic welding lines cannot process new bio-based films with lower melt temperatures without capital retooling.
- Color consistency in recycled kraft:Post-consumer fiber batches vary in shade and strength, forcing bag printers to accept wider tolerances or segregate premium virgin-grade lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shopping Bag Market |
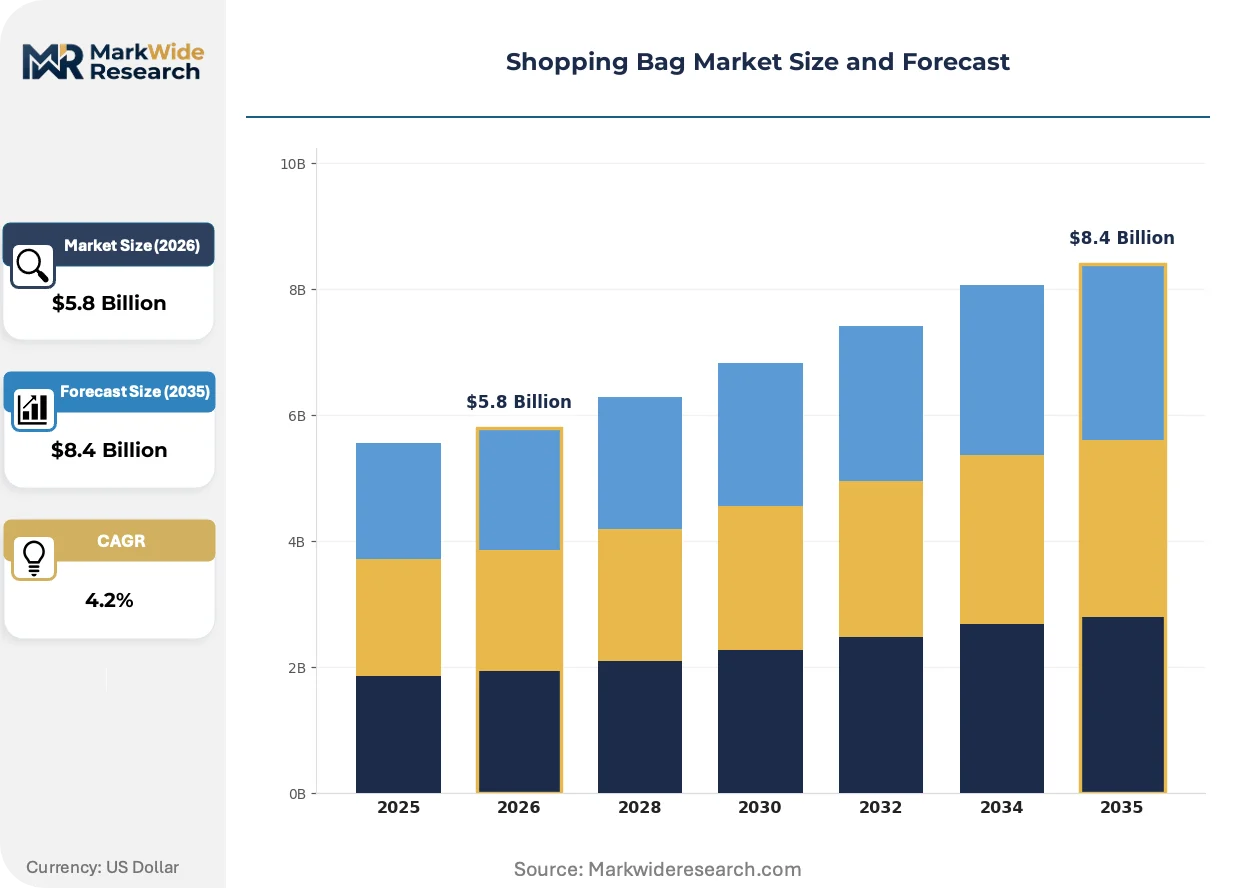
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Cotton, Jute Style: Reusable, Biodegradable, Drawstring, Tote End User: Retail Stores, Supermarkets, E-commerce, Events Size: Small, Medium, Large, Extra Large |
| Companies Covered | Advance Polybag, Bagcraft Packaging, Novolex, Smurfit Kappa Group, International Paper, Inteplast Group, Superbag Corporation, Mondi Group, Duro Bag, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shopping Bag Market Strategic Shifts & Innovations
Material science breakthroughs and compliance automation are compressing development cycles while fragmenting procurement specifications across retail tiers.
Algae-based biopolymer films are electrifying sustainable packaging roadmaps. The material delivers marine-biodegradable performance without industrial composting infrastructure. Premium cosmetics brands in South Korea and California are specifying algae-blend carry bags for flagship store openings. This substrate is compressing the addressable market for conventional oxo-degradable additives that fail to meet emerging marine toxicity standards.
California's SB 54 and New York's extended producer responsibility legislation are mandating recycled-content minimums and source reduction targets. Bag distributors must now submit annual reporting on polymer origin and end-of-life pathways to state environmental agencies. Mid-market retailers without dedicated compliance staff are outsourcing documentation to specialized third-party auditors, creating a new service layer in the supply chain.
Direct-to-consumer brands are unbundling packaging from logistics, specifying distinct bag formats for in-store pickup versus home delivery. Urban fulfillment centers in London and Tokyo are requesting collapsible, space-efficient designs that minimize storage footprint. This bifurcation is forcing converters to maintain dual SKU portfolios with incompatible dimensional specifications, complicating production scheduling and inventory positioning.
Shopping Bag Market Segmentation
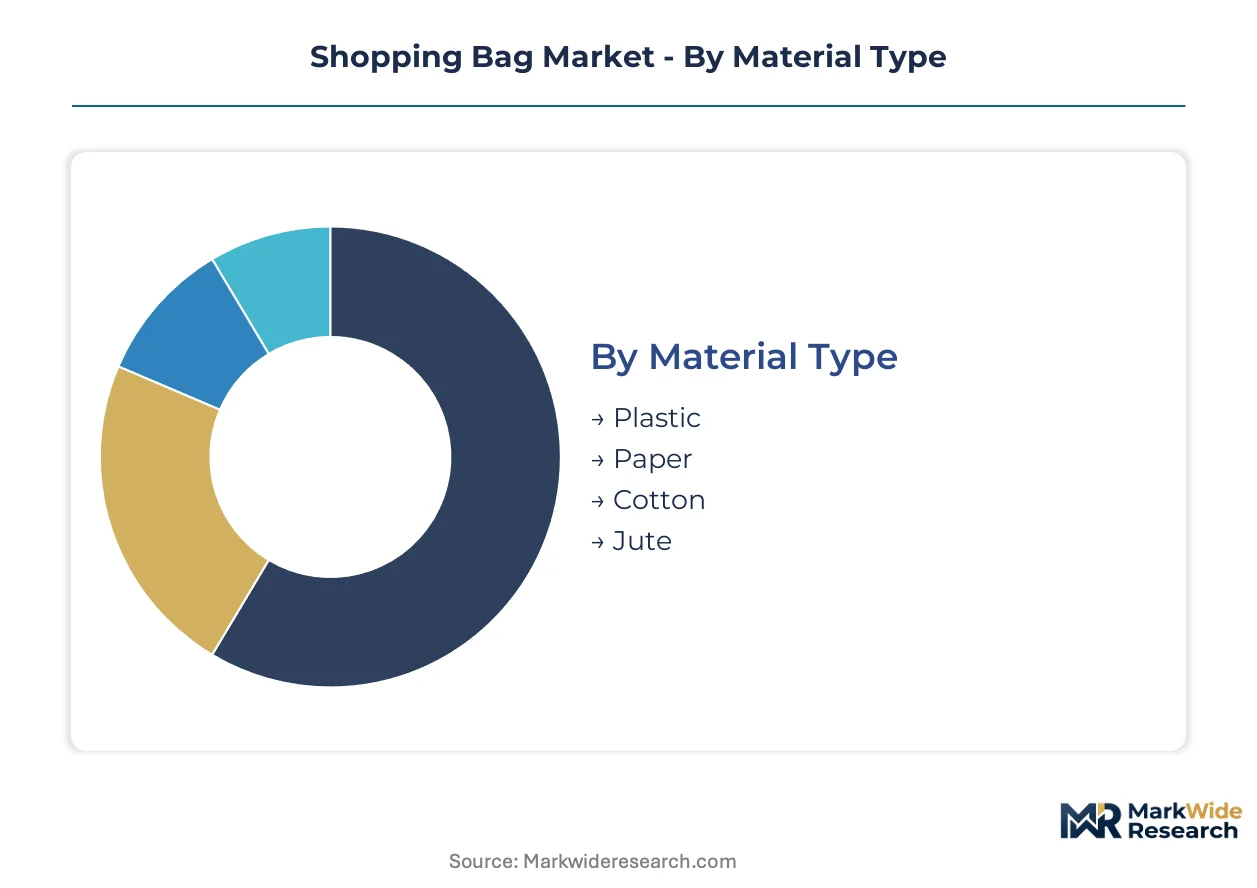
Material composition and end-use specifications fragment procurement requirements across retail tiers. Understanding how bag specifications align with fulfillment channels enables converters to prioritize capacity investments and certification pathways.
Material Type:
Plastic dominates standalone single-use applications while fiber-based alternatives embed into reusable and premium positioning strategies.
- Plastic:Polyethylene and polypropylene films deliver moisture resistance and heat-seal compatibility for high-volume grocery and fast-fashion retail. China's SAMR enforces thickness minimums that eliminate ultra-light gauges, compressing volumes toward heavier multi-use specifications in domestic supermarkets.
- Paper:Kraft pulp constructions with twisted paper handles serve boutique retail and foodservice segments seeking compostable end-of-life pathways. German paper mills are integrating post-consumer fiber into bag-grade stocks, securing renewable feedstock contracts with supermarket chains under the EU Green Deal circularity mandates.
- Cotton:Woven natural fiber bags carry premium positioning for fashion and cosmetics retail with extended reuse cycles.
- Jute:Coarse vegetable fiber constructions target agricultural and wine retail segments valuing rustic aesthetic and biodegradability.
Plastic leads volumes today; paper is gaining share fastest.
Style:
Functional design determines reuse potential and compliance eligibility across regulatory jurisdictions.
- Reusable:Durable polypropylene totes with reinforced stitching support 100+ use cycles, anchoring supermarket loyalty programs and corporate gifting. Dutch chains are piloting deposit-return systems that shift unit economics from single-sale to recurring rental revenue.
- Biodegradable:Certified compostable films and kraft constructions meet France's Citeo extended producer responsibility requirements and Italy's CONAI packaging fees. TUV Austria's OK Compost HOME validation requires 6-12 month certification cycles that delay product launches.
- Drawstring:Flexible closure systems with corded openings serve gift retail and promotional merchandise.
- Tote:Open-top rectangular constructions with parallel handles dominate grocery and book retail.
Reusable totes anchor supermarket procurement; biodegradable styles are expanding most quickly under European regulatory pressure.
End User:
Channel-specific durability and branding requirements drive specification divergence.
- Retail Stores:Boutique fashion and cosmetics flagships specify custom-printed paper and cotton constructions with foil stamping and ribbon handles.
- Supermarkets:High-volume grocery chains balance cost thresholds with reusability mandates, sourcing laminated kraft or woven polypropylene in standardized sizes.
- E-commerce:Online fulfillment demands heavier-gauge shipping-compatible bags with reinforced handles and tamper-evident closures for last-mile durability in China and the United States.
- Events:Trade shows and conferences specify lightweight non-woven totes for attendee distribution with sponsor branding.
Supermarkets drive procurement scale; e-commerce channels are climbing the fastest as fulfillment volumes surge.
Size:
Dimensional standardization enables inventory pooling while custom sizing supports category-specific merchandise.
- Small:Compact constructions for jewelry, cosmetics, and confectionery retail with limited load-bearing requirements.
- Medium:Standard grocery and apparel dimensions that balance material cost with functional capacity.
- Large:Expanded gusseted designs for bulk retail and home goods with reinforced bottom boards.
- Extra Large:Oversized specifications for bedding, seasonal merchandise, and wholesale club formats.
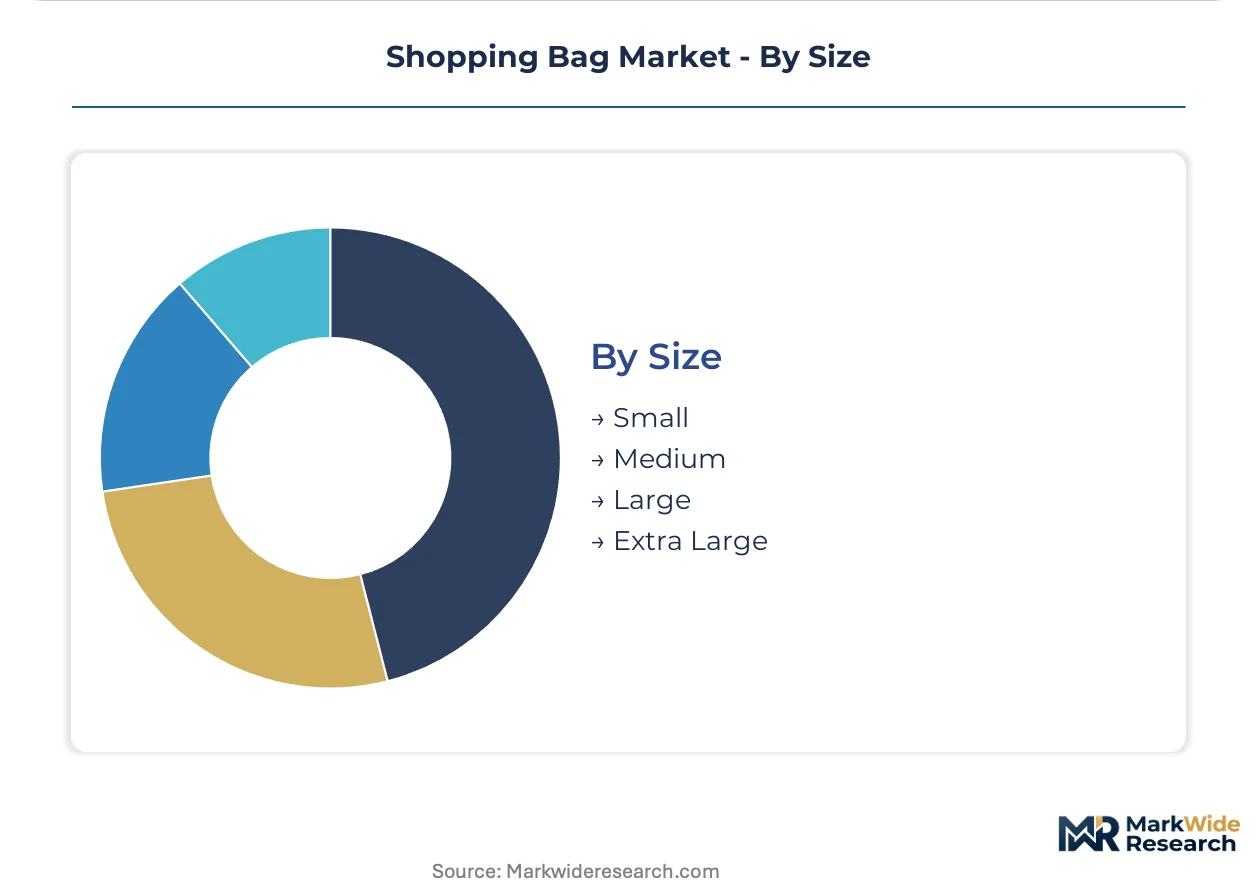
Medium sizes dominate procurement volumes; extra large formats are gaining share fastest in wholesale club expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mass production of shopping bags scaled first in the United States during the mid-20th century polyethylene expansion, then migrated toward Asian manufacturing clusters as conversion costs compressed. Today procurement patterns diverge sharply across regulatory jurisdictions, with material specifications and reuse mandates driving regional sourcing strategies.
United States
E-commerce fulfillment networks in California and New York are specifying heavier-gauge shipping bags with tamper-evident closures. The EPA and state-level bans in California and New York constrain thin-film distribution while mandating recycled-content disclosures. Manufacturing concentrates in the Midwest and Southeast, where converters supply grocery chains with laminated kraft and woven polypropylene.
China
Domestic retail expansion and cross-border e-commerce are absorbing rising volumes of non-woven and reinforced plastic bags. SAMR enforces thickness minimums and labeling standards that eliminate ultra-light gauges. Production clusters in Zhejiang and Guangdong provinces supply both domestic supermarkets and export channels to Southeast Asia and Europe.
Germany
Supermarket chains under the EU Green Deal are contracting paper mills for post-consumer kraft pulp integration into bag-grade stocks. ECHA's REACH standards restrict chemical inputs in inks and adhesives. The Rhine-Ruhr and Bavarian industrial corridors host converting operations serving French and Benelux retail markets.
France
Citeo's extended producer responsibility system funds collection infrastructure that rewards participating bag producers with lower compliance fees. OK Compost HOME certification requirements are compressing conventional plastic volumes toward certified compostable alternatives. Converters in the Île-de-France and Auvergne-Rhône-Alpes regions supply boutique retail and supermarket chains.
India
Woven polypropylene demand from organized retail and quick-commerce platforms is expanding despite feedstock price volatility. The central government's plastic waste management rules mandate thickness standards and extended producer responsibility registration. Manufacturing concentrates in Gujarat and Maharashtra, where converters serve domestic grocery chains and Middle East export markets.
Shopping Bag Market Key Industry Players
The competitive structure tilts toward integrated fiber and film converters with captive raw material access. Market participation fragments across three tiers: multinational packaging conglomerates with continental manufacturing footprints, regional specialists in kraft paper or woven polypropylene, and commodity converters serving price-sensitive emerging markets. Dominant competitive moves include backward integration into pulp and resin sourcing and strategic partnerships with retail chains for exclusive supply contracts.
Among North American packaging conglomerates, Novolex and International Paper occupy positions anchored by manufacturing scale and grocery chain relationships. European fiber specialists Smurfit Kappa and Mondi Group exemplify the integrated kraft paper archetype, leveraging captive pulp sourcing and converting capabilities to serve supermarket and boutique retail segments under EU circularity mandates.
| Leading Market Players |
|---|
| Advance Polybag |
| Bagcraft Packaging |
| Novolex |
| Smurfit Kappa Group |
| International Paper |
| Inteplast Group |
| Superbag Corporation |
| Mondi Group |
| Duro Bag |
| Others |
Cost & Logistics Intelligence
Extrusion technicians and papermaking specialists concentrated in Zhejiang province and the American Midwest compress labor-cost differentials into pricing-tier spreads, with European converters absorbing REACH compliance premiums that Asian exporters avoid.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified compostable kraft bags with TUV Austria validation from virgin-grade polypropylene totes and commodity polyethylene carry bags. Price differentiation hinges on certification grade and volume scale, with supermarket chains commanding 40-60% discounts over boutique fashion orders. Pricing pressure stems from propylene feedstock volatility squeezing woven bag margins in India. Quick-commerce platforms exhibit highest price sensitivity; luxury cosmetics brands show least.
Supply Chain Analysis
OK Compost HOME and BPI certification gating restricts supplier pools to converters with 6-12 month validation capabilities, compressing viable sourcing options. Manufacturing concentrates in China, India, and Germany, with Zhejiang province hosting over half of global non-woven capacity. Raw material dependencies include kraft pulp, polyethylene resin, and polypropylene feedstock. Single-region logistics exposure in Guangdong province creates structural vulnerability. Distribution runs through retail procurement consortia and e-commerce fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shopping bag procurement functions as a geographic-arbitrage play, with EU regulatory compliance costs running 15-25% above Asian manufacturing bases while California's SB 54 mandates create premium pricing windows for certified alternatives.
For Market Incumbents: Deploy backward integration into captive pulp and resin sourcing to defend margins against propylene price volatility and Chinese supply concentration. Secure exclusive supply contracts with supermarket chains under France's Citeo extended producer responsibility framework. Invest in TUV Austria certification pipelines to preempt competitor access to compostable segments. For New Entrants and Emerging Players: The 30-40% price-point gap between premium certified compostable bags and economy-grade polyethylene creates entry space for mid-tier recycled-content specialists. Target Indian quick-commerce platforms and Southeast Asian e-commerce fulfillment centers where durability specifications outpace regulatory compliance requirements. Lead with algae-based biopolymer formulations to bypass incumbent heat-sealing equipment limitations. For Investors and Strategic Acquirers: Valuations sit cheapest among Indian woven polypropylene converters facing feedstock margin compression but holding quick-commerce growth exposure. Five-to-ten-year viability favors integrated fiber specialists with captive kraft pulp access under EU Green Deal circularity mandates. Monitor blockchain traceability adoption rates among premium fashion retailers as inflection signal for recycled-content premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp and Resin Sourcing | Captive feedstock supply insulates Novolex and Mondi Group from propylene volatility and pulp price spikes. |
| Compostable Certification Pipeline Investment | TUV Austria and BPI validation unlocks Citeo fee reductions and French supermarket procurement eligibility. |
| Blockchain Traceability Integration | RFID-distributed ledger systems enable premium fashion brands to document recycled-content provenance for consumer claims. |
| Reusable Bag-as-a-Service Pilot | Dutch deposit-return systems shift unit economics from single-sale to recurring rental revenue for polypropylene totes. |
| Algae-Based Biopolymer Scale-Up | Marine-biodegradable films displace oxo-degradable additives in South Korean and California cosmetics retail channels. |
Research Approach
Direct dialogue with procurement directors at supermarket chains, technical directors at paper mills and extrusion facilities, sustainability officers at fashion retailers, and logistics managers at e-commerce fulfillment centers grounded qualitative findings. Secondary validation drew from EU Single-Use Plastics Directive implementation reports, SAMR labeling standard filings, REACH chemical restriction updates, and customs trade data for kraft pulp and polypropylene resin flows. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Segment-level outputs across material type, style, end user, and size dimensions calibrated to regulatory phase-in timelines and channel-specific durability requirements throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporating e-commerce fulfillment growth, extended producer responsibility fee structures, and material substitution elasticities. Industry-specific inputs included composting infrastructure deployment rates and heat-sealing equipment retooling cycles.
Caveats apply where EU Green Deal circularity mandate acceleration, Chinese dual carbon policy tightening, or propylene feedstock supply disruptions could materially shift the outlook. A model refresh is warranted upon material change in algae-based biopolymer cost-competitiveness thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Tamper Evident Bag Sealers Market
Bags and Containers
Freezing Bags Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Shrink Bags Market
Bags and Containers
Bag-In-Tube Market
Bags and Containers
Household and Cleaning Container Market
Bags and Containers
Laminated Woven PP Bags Market
Bags and Containers
Conical Top Bulk Bag Market
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
Baggage Packaging Service Market
Bags and Containers
Cross Corner Industrial Bags Market
Bags and Containers
Anti-Corrosion Bags Market
Bags and Containers
Wooden Boxes Market
Bags and Containers
Circular Industrial Bags Market
Bags and Containers
2 Loop FIBC Bags Market
Bags and Containers
Woven Bags Market