
 Blood Lancet Market | 2026-2036
Blood Lancet Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Lancet Market Outlook
The capital-intensity divergence between automated manufacturing platforms and manual assembly operations is rotating competitive advantage toward firms with scale economies. Becton, Dickinson and Company leverages its integrated device portfolio to control hospital procurement channels across North America. HTL-Strefa S.A. specializes in precision-molded lancet tips that anchor its position in European diabetes care supply chains. Owen Mumford Ltd differentiates through ergonomic design platforms that extend its reach into home-use segments.
A blood lancet is a sterile, single-use puncture device typically constructed from surgical-grade stainless steel or ABS plastic housings, designed to penetrate skin at controlled depths between 0.8 mm and 2.2 mm to extract capillary blood samples for diagnostic testing. Safety lancets dominate hospital procurement due to needlestick prevention mandates, while manual lancets retain volume leadership in emerging markets where cost sensitivity shapes purchasing. Electronic lancets represent the fastest-expanding technology segment, driven by pain-minimization features that command premium positioning in home care and pediatric applications.
The FDA enforces sharps injury prevention standards under the Needlestick Safety and Prevention Act, compelling manufacturers to engineer retractable or shielded mechanisms into safety lancet designs. ISO 11607-1 sterilization validation requirements govern global barrier packaging, while the EU MDR recertification timeline is compressing market access windows for non-European suppliers. Stakeholders must monitor evolving reimbursement codes for home glucose monitoring systems, as payer coverage decisions directly determine lancet replacement frequency and brand loyalty patterns.
Market Dynamics
Home care glucose monitoring is displacing clinical blood draws as the dominant sampling context, forcing manufacturers to redesign lancet mechanics for untrained users rather than healthcare professionals. This demand rotation compresses product development cycles while elevating pain-minimization engineering to a primary competitive variable.
Growth Catalysts
- FDA Sharps Safety Updates:The Needlestick Safety and Prevention Act mandates retractable or shielded mechanisms in safety lancets, compelling hospital procurement upgrades across acute care networks.
- Self-Monitoring Regimes:Diabetes patients in the United States are adopting continuous glucose monitoring companion devices that require frequent capillary calibration, sustaining replacement lancet consumption.
- ABS Precision Molding:Advanced polymer housings enable controlled-depth penetration mechanisms that reduce tissue trauma and expand pediatric eligibility.
Market Restraints
- Surgical-Steel Input Volatility:Nickel and chromium price swings in commodity metals markets compress margin stability for stainless-steel needle producers.
- EU MDR Recertification Compression:The European Medical Device Regulation timeline is narrowing market access windows for non-European suppliers without notified body relationships.
- Capillary Microsampling Displacement:Volumetric absorptive microsampling devices are substituting traditional lancet-plus-test-strip workflows in research and some clinical settings.
Strategic Opportunities
- Pediatric Pain-Minimization:Electronic lancets with vibration-dampening mechanisms are penetrating family medicine practices where needle anxiety drives brand switching.
- Indian Home Care Expansion:The country's PLI scheme for medical devices is attracting contract manufacturers to serve price-sensitive diabetes populations with localized production.
- Reimbursement Code Alignment:CMS coverage decisions for integrated glucose monitoring systems create bundled procurement opportunities for lancet-device combinations.
Industry Challenges
- ISO 11607-1 Sterilization Validation:Barrier packaging compliance for ethylene oxide residuals demands extended laboratory timelines that delay product launches.
- Biocompatibility Testing Backlogs:Cytotoxicity and sensitization studies for new polymer formulations are queuing at contracted laboratories beyond 18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Lancet Market |
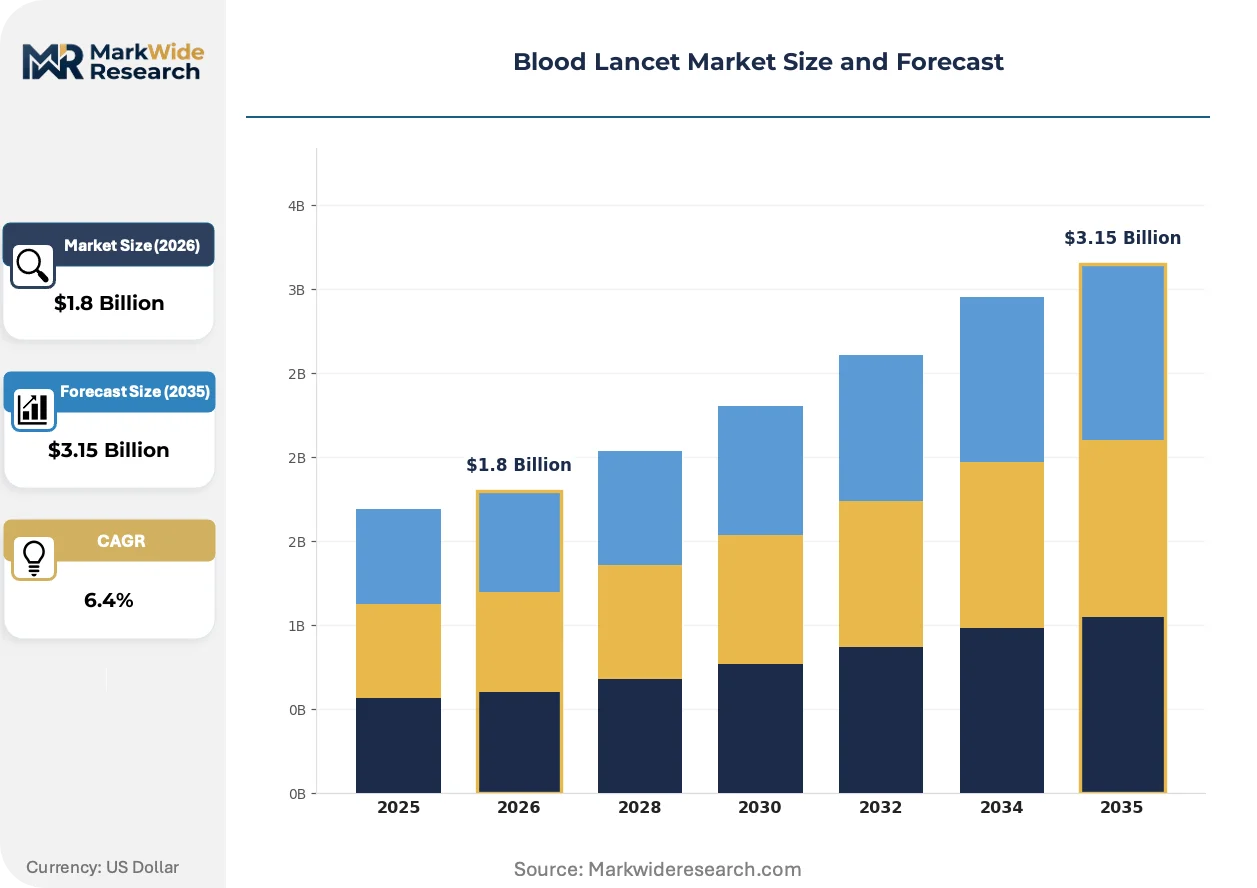
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Lancets, Basic Lancets, Multi-Depth Lancets, Adjustable Lancets End User: Hospitals, Diagnostics Centers, Home Care, Clinics Technology: Automatic Lancets, Manual Lancets, Electronic Lancets, Disposable Lancets Application: Diabetes Management, Blood Sample Collection, Point-of-Care Testing, Clinical Research |
| Companies Covered | Terumo Corporation, Owen Mumford Ltd, Becton, Dickinson and Company, Nipro Medical Corporation, SARSTEDT AG & Co. KG, F. Hoffmann-La Roche Ltd, B. Braun Melsungen AG, HTL-Strefa S.A., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Lancet Market Strategic Shifts
Needle retraction engineering and electronic actuation mechanisms are converging to redefine the user experience boundary between professional and home-use devices. Manufacturers are racing to embed sensor feedback loops that adjust penetration depth based on skin resistance measurements.
Silicon MEMS pressure sensors are miniaturizing within lancet housings to enable real-time force feedback during skin penetration. Home-use segments in Germany and Japan are adopting these mechanisms at three times the rate of hospital procurement channels. The technology is miniaturizing device footprints while collapsing the performance gap between manual and electronic lancet categories.
EU MDR Annex I general safety and performance requirements are mandating clinical evidence packages for legacy lancet designs previously cleared under the Medical Devices Directive. Manufacturers with substantial equivalent predicates are rebuilding technical documentation from raw biocompatibility data. Safety lancets with integrated sharps protection are absorbing disproportionate compliance resources, delaying portfolio refreshes by 12-18 months.
Hospital group purchasing organizations are consolidating supplier rosters around full-line diabetes device vendors rather than standalone lancet specialists. Integrated procurement contracts covering meters, strips, and lancets are displacing category-specific bidding in United States health systems. This concentration is most visible in the southeastern states where regional GPOs have merged purchasing authority across 340B-eligible networks.
Blood Lancet Market Segmentation
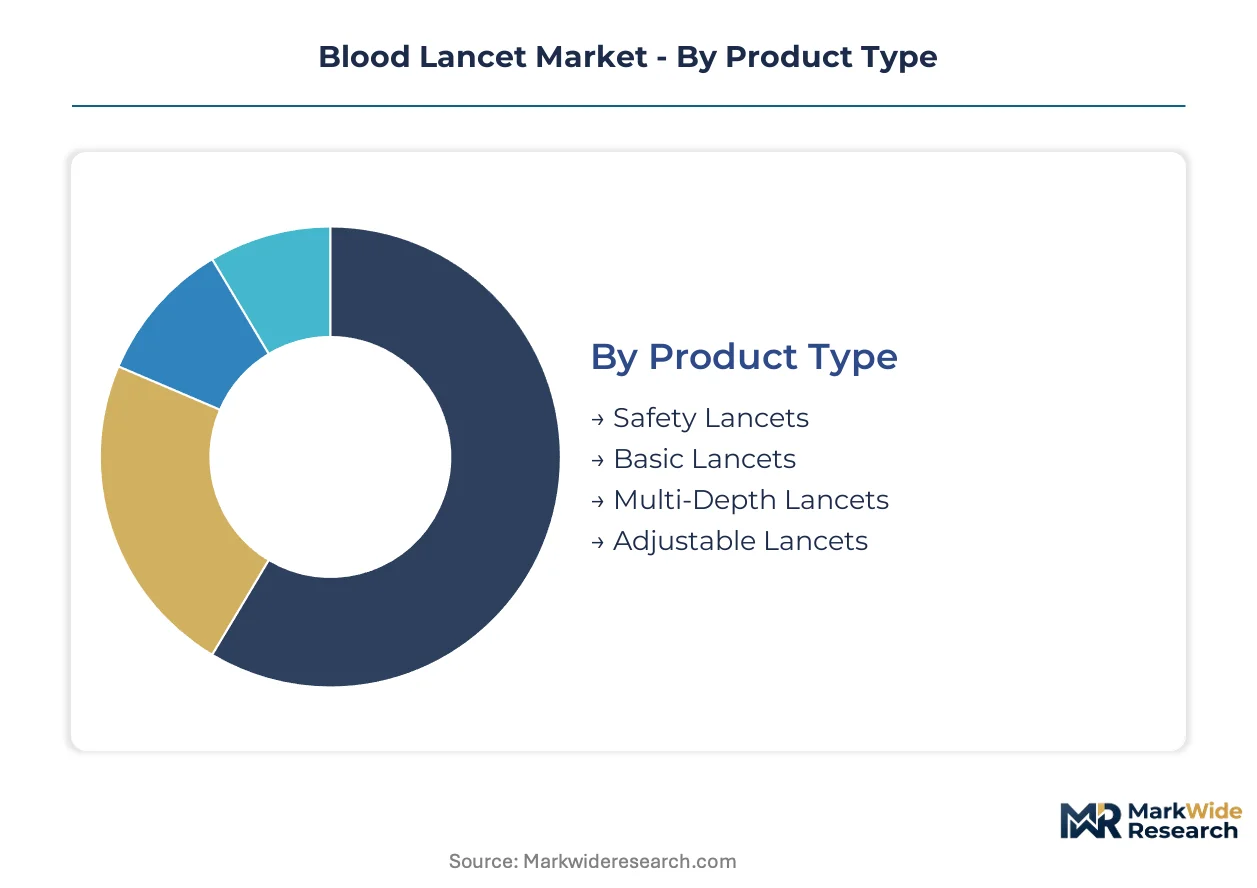
Segmentation in blood lancets reveals divergent profit pools across safety mandates, patient self-management trends, and technology substitution curves. Manufacturers must align R&D portfolios with the segments where regulatory pressure and user experience expectations are tightening fastest.
Product Type:
Substitution pressure from microsampling technologies and integrated glucose sensors is compressing demand for basic mechanical designs while amplifying value capture in safety-engineered formats.
- Safety Lancets:Spring-loaded retraction mechanisms with integrated sharps shields satisfy FDA Needlestick Safety and Prevention Act mandates in United States hospital networks. Procurement concentrates in integrated delivery networks where GPO contracts bundle diabetes device portfolios.
- Basic Lancets:Simple plastic-molded housings with fixed-depth steel blades dominate emerging market volumes where cost-per-test drives purchasing decisions. India's PLI scheme for medical devices is attracting contract manufacturers to serve price-sensitive diabetes populations with localized production.
- Multi-Depth Lancets:Dial-adjustable penetration settings accommodate varying skin thickness across pediatric, adult, and geriatric patients.
- Adjustable Lancets:Precision-threaded depth control mechanisms target home care users seeking personalized comfort settings.
Basic Lancets anchors the volume base while Safety Lancets gains share at the steepest rate.
End User:
Cost tier stratification separates acute care procurement with bundled contracting from fragmented retail-channel purchasing in home settings.
- Hospitals:Centralized purchasing through GPOs favors full-line diabetes device vendors with safety-engineered portfolios. The United States southeastern states exhibit the most concentrated procurement authority across 340B-eligible networks.
- Home Care:Direct-to-patient channels require ergonomic designs for untrained users with pain-minimization engineering as the primary competitive variable. Germany and Japan are adopting MEMS pressure-sensor feedback mechanisms at three times the rate of hospital channels.
- Diagnostics Centers:High-throughput capillary sampling operations prioritize speed and sterility assurance in workflow design.
- Clinics:Mixed professional-patient interaction models demand versatility across trained staff use and patient self-application.
Hospitals command the highest per-unit pricing while Home Care expands most quickly as self-monitoring regimes displace clinical blood draws.
Technology:
Application context determines whether speed, precision, or cost minimization dominates technology selection.
- Electronic Lancets:Vibration-dampening actuation with programmable depth settings penetrates family medicine practices where needle anxiety drives brand switching. Silicon MEMS pressure sensors are miniaturizing within housings to enable real-time force feedback during skin penetration.
- Manual Lancets:Spring-actuated or pressure-triggered mechanisms retain cost leadership in price-sensitive markets with minimal regulatory burden.
- Automatic Lancets:One-touch triggering systems with concealed blades address sharps safety compliance without full electronic complexity.
- Disposable Lancets:Single-use sterile designs with pre-attached capillary collection tubes serve point-of-care testing workflows.
Manual Lancets retains installed-base dominance while Electronic Lancets climbs the fastest on pediatric pain-minimization positioning.
Application:
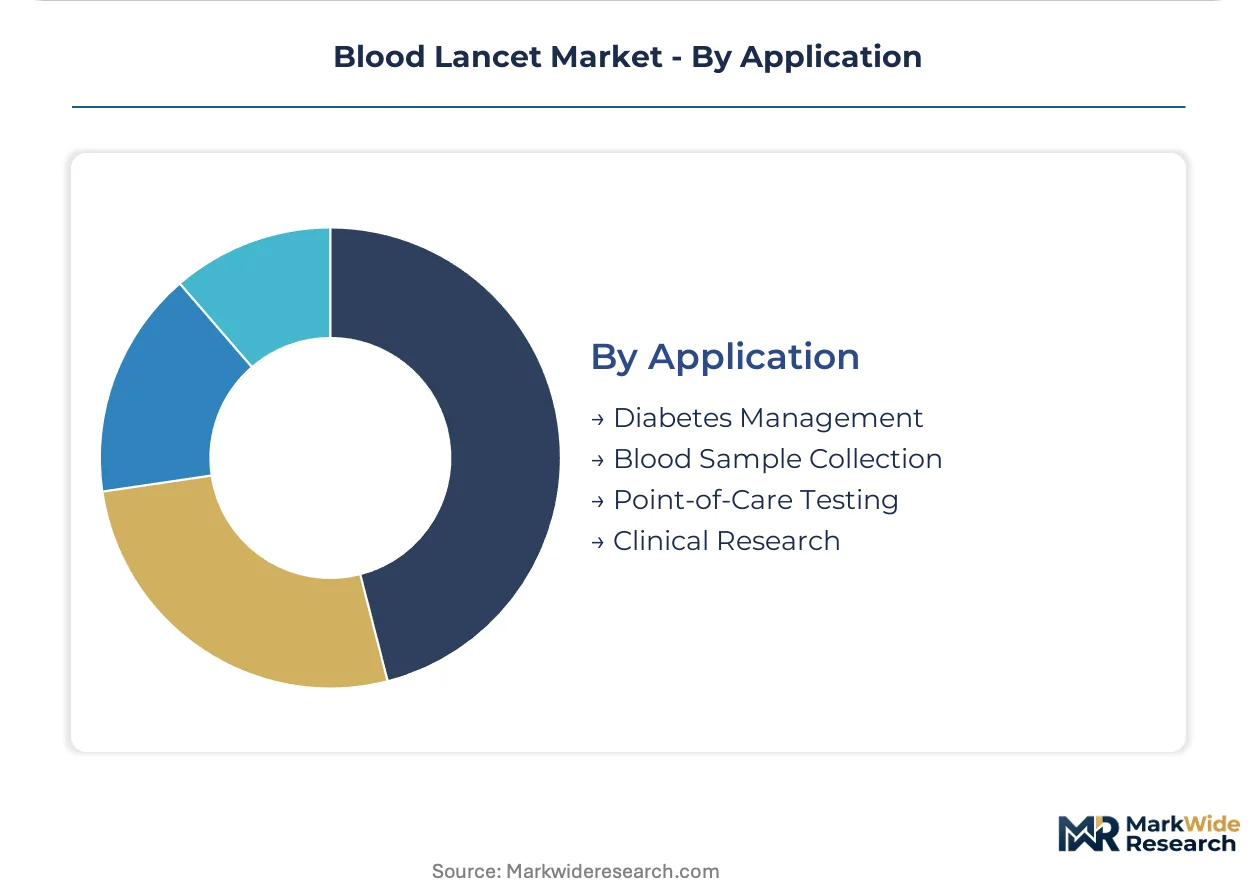
Volume concentration in diabetes management creates scale economies that subsidize specialized clinical research and point-of-care formats.
- Diabetes Management:Continuous glucose monitoring companion devices require frequent capillary calibration, sustaining replacement lancet consumption in United States patient populations. Reimbursement codes for integrated glucose monitoring systems directly determine lancet replacement frequency and brand loyalty patterns.
- Blood Sample Collection:General diagnostic workflows demand sterility assurance and minimal tissue trauma for valid hematology results.
- Point-of-Care Testing:Rapid diagnostic protocols in non-laboratory settings prioritize speed and operator safety.
- Clinical Research:Volumetric absorptive microsampling devices are substituting traditional lancet-plus-test-strip workflows in research settings.
Diabetes Management absorbs the majority of production volume while Clinical Research faces the steepest displacement threat from alternative sampling technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in blood lancet devices, exporting safety-engineered formats to European hospital networks while importing basic mechanical variants from Asian contract manufacturers. Germany and Japan generate consistent outbound shipments of electronic lancet technologies. India's PLI scheme is redirecting regional supply chains toward domestic production for price-sensitive diabetes populations.
United States
Hospital group purchasing organizations in the southeastern states have consolidated procurement authority across 340B-eligible networks, bundling diabetes device portfolios under single-vendor contracts. The FDA enforces sharps injury prevention standards under the Needlestick Safety and Prevention Act, compelling retractable mechanism adoption. Greater Boston hosts concentrated R&D operations for MEMS pressure-sensor integration into next-generation home-use formats.
Germany
Family medicine practices across Bavaria and North Rhine-Westphalia are adopting electronic lancets with vibration-dampening mechanisms at three times the rate of hospital channels. The EU MDR recertification timeline is compressing market access for legacy device designs. The Eindhoven-Randstadt corridor serves as a precision-molding hub supplying polymer housings to diabetes device assemblers throughout the region.
Japan
Aging demographics in the Kanto and Kansai regions are expanding home glucose monitoring penetration among geriatric populations with limited clinical access. METI standards for medical device software validation govern sensor-feedback algorithm deployment. Osaka-based manufacturers are miniaturizing silicon MEMS pressure sensors for real-time force feedback mechanisms.
India
Maharashtra and Gujarat are attracting contract manufacturers under the PLI scheme for medical devices to serve domestic diabetes populations exceeding 77 million diagnosed cases. CDSCO licensing requirements for sterile single-use devices are tightening import substitution incentives. The Delhi-NCR corridor is emerging as a distribution nexus for basic lancet formats targeting tier-2 and tier-3 cities.
China
Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces are scaling ABS precision-molding capacity for export-oriented lancet housing production. NMPA registration pathways for Class II medical devices are harmonizing with international standards to accelerate overseas market entry. Shenzhen-based electronics assemblers are integrating actuation mechanisms for premium electronic lancet exports to European home care segments.
Blood Lancet Market Competitive Environment
Concentration sits with diversified medical device conglomerates that leverage integrated diabetes portfolios to control hospital procurement channels. The vendor base stratifies across three tiers: full-line suppliers bundling meters, strips, and lancets; precision-molding specialists capturing European safety-lancet demand; and ergonomic-design focused players penetrating home-use segments. Competitive maneuvering centers on GPO contract consolidation and MEMS sensor technology licensing rather than standalone product rivalry.
Within the diversified conglomerate tier, Becton, Dickinson and Company and Abbott Laboratories exemplify scale-driven positioning through integrated device portfolios. HTL-Strefa S.A. occupies a specialist position in precision-molded lancet tip manufacturing. Owen Mumford Ltd represents the ergonomic-design archetype with differentiated home-use segment focus. These three entities collectively illustrate the strategic segmentation governing procurement influence across acute care and self-monitoring contexts.
| Leading Market Players |
|---|
| Terumo Corporation |
| Owen Mumford Ltd |
| Becton, Dickinson and Company |
| Nipro Medical Corporation |
| SARSTEDT AG & Co. KG |
| F. Hoffmann-La Roche Ltd |
| B. Braun Melsungen AG |
| HTL-Strefa S.A. |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Polymer housing substitution for surgical-grade stainless steel is rotating procurement economics toward ABS precision-molding clusters in China and India while compressing margin structures for legacy metal-needle producers in Europe and North America. This material transition simultaneously redistributes supply geography toward Asian contract manufacturers and intensifies price competition in basic lancet tiers.
Pricing Analysis
Hospital group purchasing organizations anchor a three-tier pricing structure across premium, standard, and economy levels, with safety-engineered electronic formats commanding substantial premiums over basic manual variants. Price differentiation rests on FDA certification tier and MEMS sensor integration depth, with reimbursement code alignment determining effective net pricing to end patients. Pricing pressure stems from India's PLI scheme attracting localized production for price-sensitive diabetes populations. Home care segments exhibit highest price sensitivity due to direct out-of-pocket exposure, while integrated delivery networks in the United States southeastern states demonstrate lowest sensitivity through bundled procurement contracts.
Supply Chain Analysis
Just-in-time inventory preferences dominate hospital procurement channels, while strategic stockpiling characterizes GPO-managed diabetes device portfolios across 340B-eligible networks. Supply concentrates in China's Yangtze River Delta for ABS precision-molding, Germany's Eindhoven-Randstadt corridor for polymer housings, and India's Maharashtra-Gujarat corridor for contract assembly. Raw material dependencies include nickel and chromium for surgical-steel needles, medical-grade ABS resin, and silicon MEMS wafers. Single-source vulnerability in MEMS sensor fabrication creates concentrated risk for electronic lancet manufacturers. Distribution runs through regional GPO consolidation in the United States, specialized diabetes device distributors in Germany, and tiered wholesale networks penetrating India's tier-2 and tier-3 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous glucose monitoring platform economics are redefining lancet market boundaries, with interoperability between companion calibration devices and integrated glucose systems determining replacement consumption rates and brand stickiness.
For Market Incumbents: Consolidate procurement influence by deepening GPO contract penetration across southeastern United States health systems before EU MDR recertification windows compress supplier rosters. Acquire MEMS sensor technology capabilities or license force-feedback algorithms from Osaka-based semiconductor specialists to defend electronic lancet positioning against emerging Asian contract manufacturers.
For New Entrants and Emerging Players: Pediatric pain-minimization service layers present underexploited white space where incumbent ergonomic designs under-serve family medicine practices in Germany and Japan. Target India's home care expansion through PLI-linked contract manufacturing partnerships with localized ABS molding capacity. Pursue direct-to-patient digital channels bypassing fragmented retail pharmacy distribution.
For Investors and Strategic Acquirers: EU MDR recertification reshapes the acquisition landscape by stranding legacy device designs without notified body relationships, creating distressed opportunities for technical documentation assets. Long-term viability centers on MEMS integration depth and GPO contract tenure rather than standalone manufacturing scale. Monitor CMS reimbursement code revisions for integrated glucose monitoring systems as the critical inflection signal determining lancet replacement frequency economics.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for MEMS-Integrated Electronic Lancets | Accelerates hospital procurement upgrades under Needlestick Safety and Prevention Act mandates. |
| CE Marking Pathway Alignment with EU MDR Annex I | Preserves European market access for safety-engineered portfolio refreshes. |
| Hospital System Partnership for Bundled Diabetes Device Contracts | Secures multi-year GPO procurement slots across integrated delivery networks. |
| Software Companion Development for Sensor Feedback Algorithms | Enables real-time penetration depth adjustment based on skin resistance measurements. |
| Reimbursement Strategy for Home Glucose Monitoring Integration | Determines patient out-of-pocket exposure and brand loyalty patterns in United States home care segments. |
Study Parameters
A standing panel of hospital purchasing committee members, GPO contracts managers, biomedical engineers, and diabetes care clinicians provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body guidance documents, and hospital procurement contract disclosures. Bottom-up demand modeling triangulated against top-down epidemiological projections for diagnosed diabetes prevalence.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for lancet device categories, SEC filings from diversified medical device conglomerates, and GPO contract award announcements. Segmentation dimensions spanned product type, end user, technology, application, and regional regulatory cluster across the projection horizon. CAGRs were derived from fitted growth curves incorporating MEMS technology adoption rates, reimbursement code revision timelines, and PLI scheme capacity buildouts.
Underlying assumptions cover EU MDR recertification completion rates, nickel and chromium price stability, and CMS coverage continuity for integrated glucose monitoring systems, with deviation risk concentrated in notified body backlog duration and commodity metals volatility. Revision becomes warranted when MEMS sensor cost curves cross thresholds enabling mass-market electronic lancet penetration or when reimbursement bundling decisions alter replacement frequency economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Argentina Aesthetic Devices Market
Medical Devices
UAE Respiratory Devices Market
Medical Devices
Implantable Neurostimulation Device EMI and Safety Test Systems Market
Medical Devices
Indonesia Devices Market
Medical Devices
Artificial Pancreas Market
Medical Devices
Global Breast Implants Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Cryoballoon Ablation System Market
Medical Devices
Global Microdermabrasion Devices Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
Artificial Disc Market
Medical Devices
Capnography Devices Market
Medical Devices
Global Deep Brain Stimulation Devices Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Medical Device Complaint Management Market