
 Infrastructure As a Service Market | 2026-2036
Infrastructure As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Infrastructure As a Service Market Intelligence
On-premises capital expenditure is narrowing as enterprises shift consumption models toward operationalized cloud spending. Amazon Web Services leverages its hyperscale data center footprint across multiple continents to sustain pricing power in compute-intensive workloads. Microsoft Azure anchors enterprise trust through deep integration with existing productivity software stacks. Google Cloud Platform differentiates on artificial intelligence and analytics-optimized infrastructure offerings.
Infrastructure as a Service denotes the provision of virtualized computing resources—servers, storage, networking, and data center space—delivered over the internet through subscription or pay-per-use arrangements, typically measured in compute hours, gigabytes stored, or bandwidth consumed. The model eliminates capital-intensive hardware ownership while enabling elastic scaling of CPU, memory, and I/O resources to match real-time application demand. Public cloud deployment leads aggregate revenue due to economies of scale in multi-tenant architectures, though hybrid cloud configurations capture the fastest growth as regulated industries demand workload portability between on-premises and off-premises environments. Compute services command the largest share of service model revenue, while storage and backup segments attract margin expansion from data retention compliance requirements.
ISO 27001 certification and SOC 2 Type II attestation shape vendor qualification criteria across healthcare and BFSI procurement teams. The EU AI Act and GDPR impose data localization and algorithmic transparency obligations that filter available supplier pools for European deployments. India's MeitY guidelines and BIS cloud standards create parallel compliance pathways for public sector contracts. Stakeholders must weigh sovereign infrastructure requirements against the interoperability limitations of region-locked deployments.
Market Dynamics
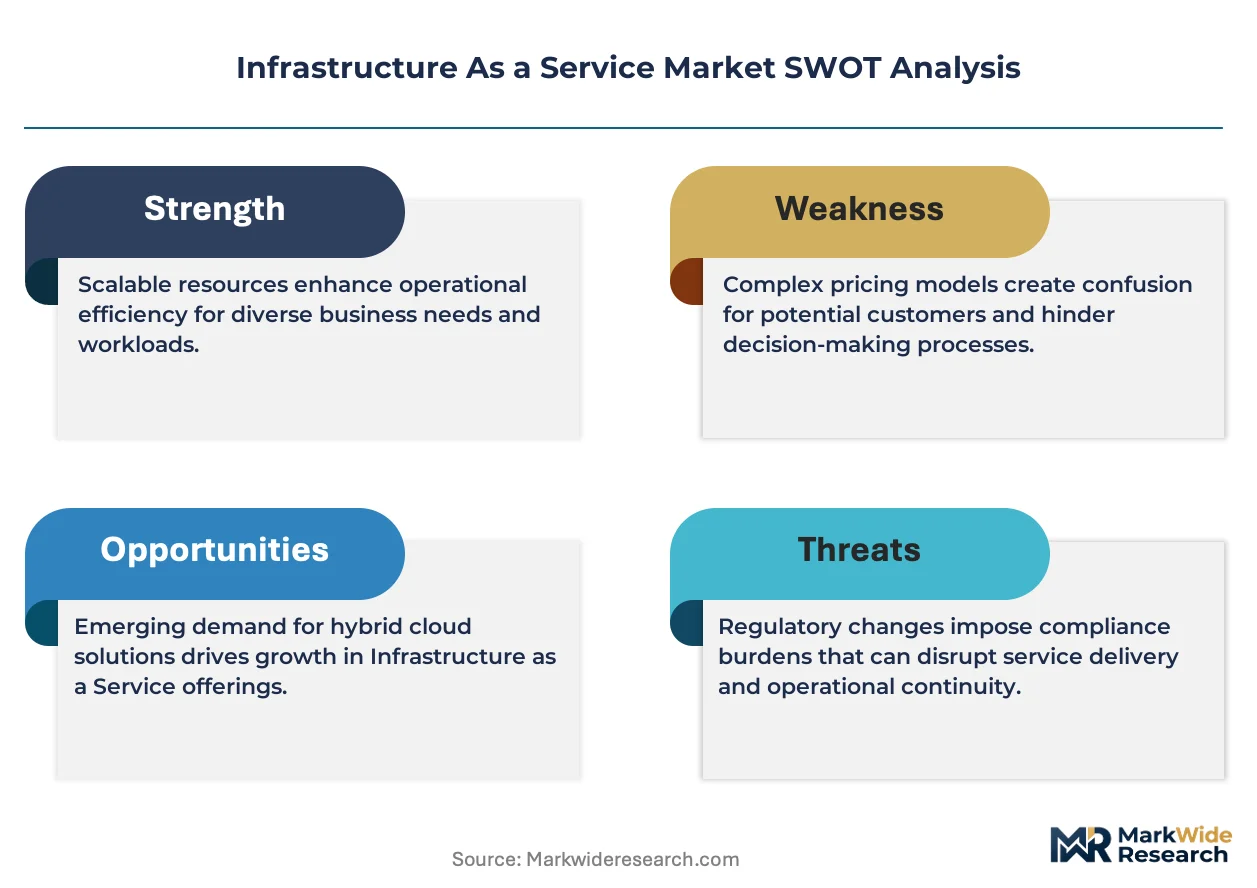
Data sovereignty mandates under the EU AI Act and India's MeitY guidelines are fragmenting procurement patterns, forcing vendors to deploy region-locked infrastructure while maintaining interoperability with hyperscale platforms.
Growth Catalysts
- Hybrid cloud architectures:Financial services firms demand workload portability between on-premises and off-premises environments to satisfy risk management frameworks. This configuration captures the fastest expansion trajectory across regulated industries.
- GDPR data localization:European enterprises must retain personal data within jurisdictional boundaries, creating dedicated procurement pools for sovereign cloud capacity in Germany, France, and the Netherlands.
- GPU-intensive workloads:Generative AI training and inference operations require specialized compute instances that command premium pricing and extend contract durations.
Market Restraints
- Energy input volatility:Data center power consumption ties operational margins to regional electricity grid pricing, particularly affecting facilities in Germany and Singapore where carbon transition levies apply.
- Hyperscale supplier concentration:Three vendors control the majority of global compute capacity, creating single-source risk for enterprises without multi-cloud orchestration capabilities.
- Cross-border data transfer friction:Schrems II rulings invalidate EU-US Privacy Shield mechanisms, complicating transatlantic workload distribution for multinational corporations.
Strategic Opportunities
- Brazilian sovereign cloud buildout:Local data center operators capture public sector contracts as ANVISA and the central bank mandate domestic infrastructure for health and financial data processing.
- Edge-to-cloud convergence:5G network slicing enables distributed computing architectures that reduce latency for manufacturing automation and autonomous vehicle telemetry.
- Green cloud procurement mandates:CSRD disclosure requirements and EU Green Deal taxonomy criteria reward providers with verified renewable energy matching and carbon-negative cooling systems.
Industry Challenges
- Multi-cloud orchestration expertise:Enterprise IT teams lack proficiency in Kubernetes federation and cross-platform identity management, slowing migration timelines and increasing professional services dependency.
- SOC 2 Type II attestation cycles:Healthcare and BFSI procurement teams require twelve-month audit windows that delay vendor onboarding and compress implementation schedules.
- Legacy mainframe integration:Core banking and insurance policy administration systems resist containerization, forcing costly middleware layers that erode cloud cost advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrastructure As a Service Market |
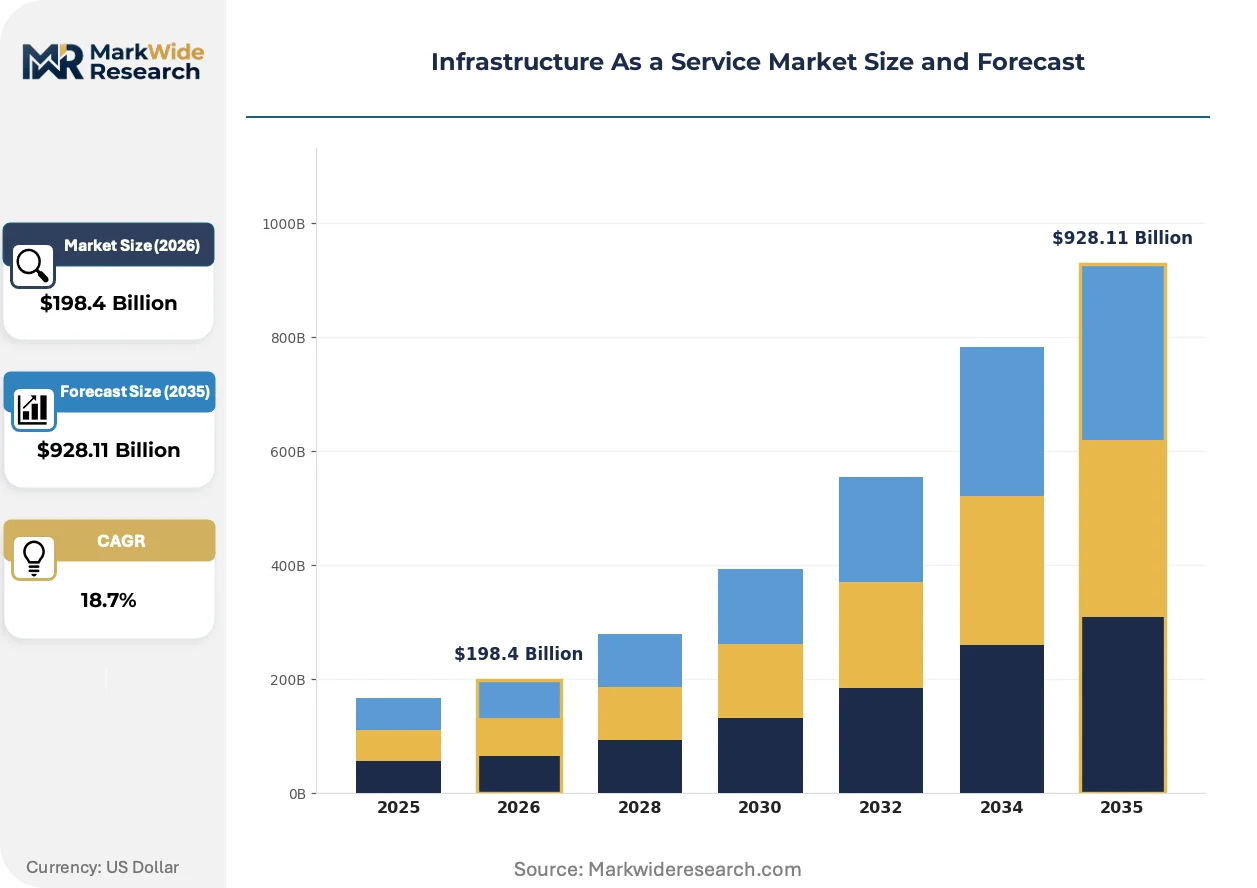
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $928.11 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Model: Compute, Storage, Networking, Backup End User: SMEs, Large Enterprises, Government, Startups Industry Vertical: Healthcare, BFSI, Retail, Education |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud Platform, IBM Cloud, Oracle Cloud Infrastructure, Alibaba Cloud, Dell Technologies, Cisco Systems, Fujitsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrastructure As a Service Market Strategic Shifts & Innovations
Workload deployment patterns are fragmenting across specialized infrastructure tiers as regulatory complexity and performance requirements outstrip the capabilities of uniform public cloud offerings.
Arm-based processor architectures are migrating from mobile and embedded applications into data center compute instances. Hyperscale operators now deploy Graviton and Cobalt chips for web serving and containerized microservices, cutting per-watt operational expenditure by one-third against x86 equivalents. This silicon transition is migrating from niche adoption into mainstream procurement specifications for sustainability-conscious enterprises.
India's BIS cloud standards and MeitY empanelment requirements create parallel compliance pathways distinct from ISO 27001 and SOC 2 frameworks. Public sector contracts mandate domestic data residency and encryption key localization, disqualifying providers without Indian data center presence. State governments in Maharashtra and Karnataka now require empanelment for any infrastructure serving education and municipal service delivery.
Consumption-based billing models displace reserved instance commitments as buyers prioritize flexibility over rate discounts. FinOps tooling adoption spreads through mid-market enterprises seeking visibility into departmental cloud spend allocation. This behavioral shift concentrates in technology and professional services verticals where project-based funding cycles resist long-term capacity planning.
Infrastructure As a Service Market Segmentation
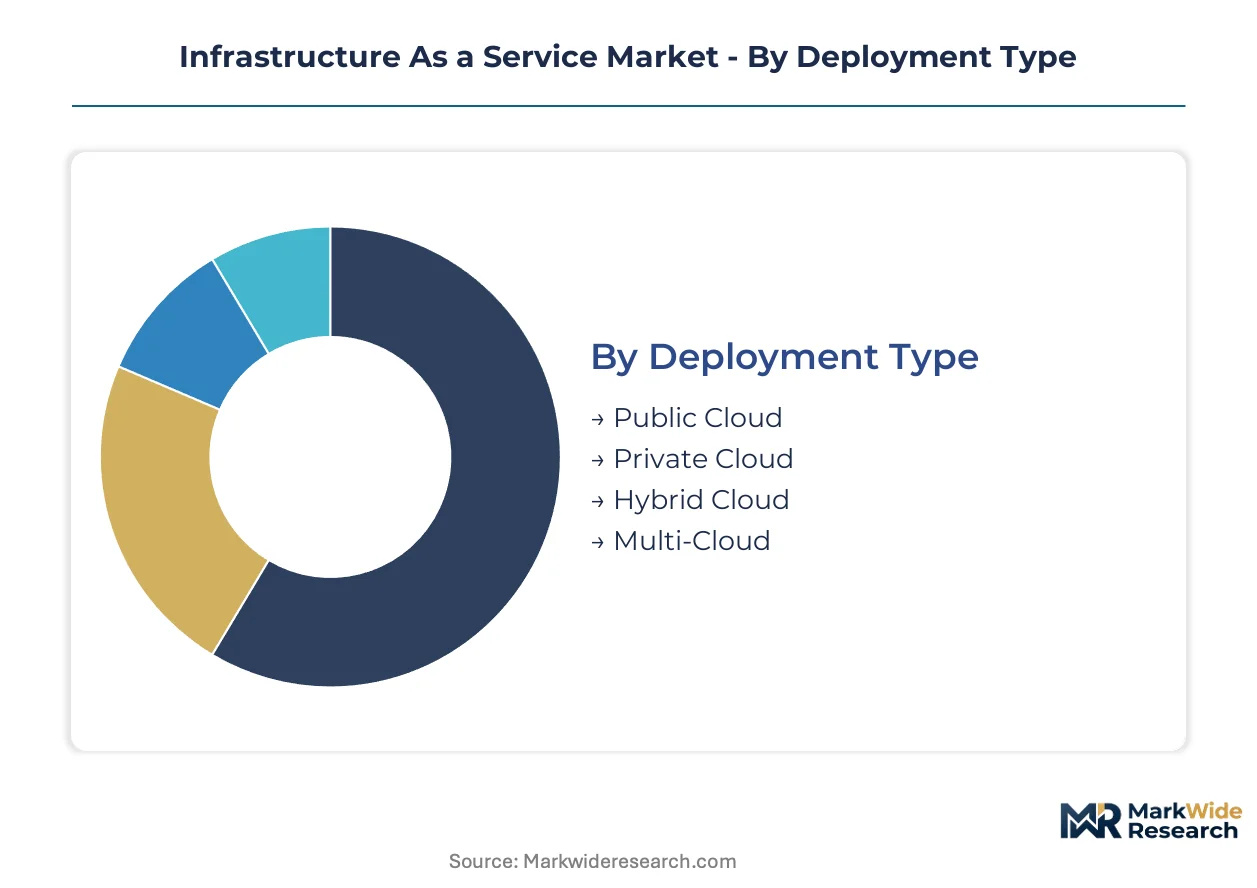
Infrastructure as a Service procurement patterns diverge sharply across deployment configurations and consumption models. Enterprise buyers weight data sovereignty mandates against elasticity requirements when selecting infrastructure tiers. Vendor qualification criteria and contract structures vary materially by segment, reshaping competitive positioning across the supplier base.
Deployment Type:
Contract renewal cycles range from month-to-month consumption in public cloud to five-year capital leases in private deployments, creating distinct revenue recognition patterns across the category.
- Public Cloud:Multi-tenant architectures deliver virtualized compute, storage, and networking through shared infrastructure pools. Financial services firms in Singapore and retail conglomerates in Germany concentrate procurement here for burst capacity and development environments, though GDPR data localization constraints limit workload types.
- Hybrid Cloud:Orchestrated workload portability between on-premises and off-premises environments satisfies risk management frameworks in regulated industries. India's MeitY empanelment requirements and Brazil's ANVISA mandates accelerate sovereign-hybrid configurations that retain sensitive data domestically while tapping hyperscale platforms for non-critical workloads.
- Private Cloud:Single-tenant infrastructure dedicates physical resources to individual organizations, typically deployed in captive data centers or exclusive colocation facilities.
- Multi-Cloud:Distributed architectures span two or more hyperscale providers to mitigate concentration risk and optimize workload placement by capability.
Public Cloud anchors the volume base while Hybrid Cloud gains share at the steepest rate.
Service Model:
Margin structures compress from compute commoditization while data retention compliance requirements expand storage pricing power.
- Compute:Virtual CPU and memory instances scale elastically to match real-time application demand, measured in core-hours or normalized compute units. GPU-intensive configurations for generative AI training command premium pricing and extend contract durations in India's technology corridors and Germany's industrial automation clusters.
- Storage:Object, block, and file services retain persistent data with tiered durability guarantees. Healthcare systems in the United States under HIPAA and European pharmaceutical manufacturers under GDPR drive demand for immutable backup and long-term archival with jurisdictional lock-in.
- Networking:Software-defined connectivity, load balancing, and content delivery optimize traffic flows across distributed infrastructure.
- Backup:Point-in-time recovery and disaster replication services protect against data loss and ransomware incidents.
Compute services generate the highest absolute revenue while Storage delivers the most resilient margin expansion.
End User:
Procurement sophistication varies from self-service credit card activation among Startups to eighteen-month RFP cycles in Government.
- Large Enterprises:Centralized IT governance mandates multi-year enterprise agreements with committed spend thresholds and custom security attestations. Manufacturing conglomerates in Japan and telecommunications operators in South Korea anchor this segment with complex multi-region deployments requiring dedicated customer success teams.
- Government:Public sector contracts impose domestic data residency, encryption key localization, and certified personnel clearance requirements. India's state governments in Maharashtra and Karnataka now mandate MeitY empanelment for education and municipal service delivery, disqualifying providers without local data center presence.
- SMEs:Mid-market organizations consume standardized services through self-service portals with limited customization.
- Startups:Venture-backed technology firms prioritize consumption flexibility over rate discounts, often migrating across providers.
Large Enterprises contribute the majority of contracted revenue while Government expands most quickly under sovereign cloud mandates.
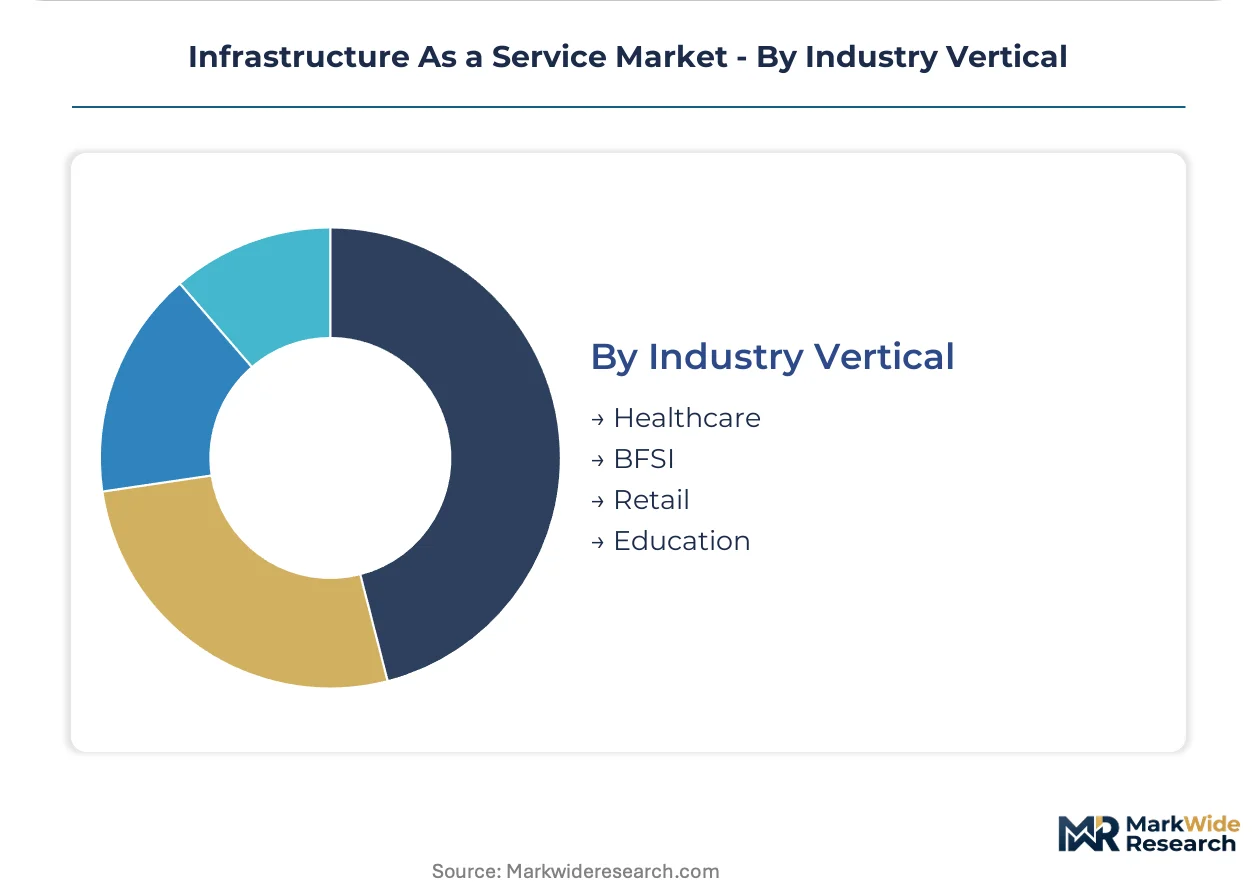
Industry Vertical:
Compliance burden intensity separates procurement specifications, with healthcare and financial services imposing the most stringent vendor qualification criteria.
- BFSI:Banking, insurance, and capital markets operations demand SOC 2 Type II attestation, ISO 27001 certification, and region-locked infrastructure for core transaction processing. European institutions under the EU AI Act and Brazilian banks under central bank mandates fragment supplier pools toward domestic or sovereign-qualified providers.
- Healthcare:Patient data protection under HIPAA in the United States and equivalent national frameworks elsewhere requires encrypted transmission, access logging, and business associate agreements. Academic medical centers and pharmaceutical manufacturers concentrate procurement in jurisdictions with established clinical trial infrastructure.
- Retail:Seasonal demand volatility drives elasticity requirements for e-commerce platforms and supply chain systems.
- Education:Public universities and K-12 systems prioritize cost containment over advanced capabilities, often aggregating demand through state-level contracts.
BFSI commands the highest per-customer contract values while Healthcare demonstrates the most resilient growth under data protection mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement markets. German enterprises accept premium rates for certified sovereign capacity, while Indian mid-market buyers prioritize consumption flexibility over committed discounts. This elasticity divergence fragments vendor pricing power geographically.
Germany
Industrial automation clusters in Bavaria and Baden-Württemberg drive GPU-intensive workload demand for manufacturing AI. The EU AI Act and GDPR impose strict data localization requirements, filtering supplier pools toward domestic-qualified providers. Frankfurt's data center corridor anchors sovereign cloud buildout as banks and automotive OEMs consolidate regional infrastructure procurement.
United States
Financial services firms in New York and technology enterprises in Seattle demand hybrid portability between on-premises and cloud environments. HIPAA governs healthcare data handling, while SEC disclosure rules shape BFSI vendor qualification. Northern Virginia's hyperscale cluster sustains the world's densest compute concentration, though Schrems II friction complicates transatlantic workload distribution.
India
Technology corridors in Karnataka and Maharashtra generate surge demand for generative AI training infrastructure. MeitY empanelment and BIS cloud standards create parallel compliance pathways distinct from ISO frameworks. State governments now mandate domestic data residency for education and municipal service delivery, accelerating local data center construction.
Brazil
Public sector digitization and central bank mandates drive sovereign cloud procurement in São Paulo and Rio de Janeiro. ANVISA requirements for health data processing and central bank infrastructure rules disqualify providers without domestic presence. Local operators capture public sector contracts as federal agencies consolidate cloud spending under national security frameworks.
Japan
Manufacturing conglomerates in the Chubu region and telecommunications operators in Tokyo anchor multi-region enterprise agreements. METI guidelines shape industrial data governance, while financial regulators impose operational resilience requirements on core banking systems. Osaka's emerging data center cluster targets disaster recovery demand from Tokyo-based enterprises.
Infrastructure As a Service Market Key Industry Players
Capability concentration sits with hyperscale operators; scale advantage sits with vertically integrated technology conglomerates. The market structure consolidates around three dominant compute providers while fragmenting across specialized sovereign and edge infrastructure tiers. Strategic archetypes include hyperscale platform operators, legacy enterprise technology vendors pivoting to service models, and regional sovereign cloud specialists. Competitive moves center on multi-cloud orchestration partnerships and carbon-negative infrastructure certification to satisfy CSRD procurement mandates.
Among hyperscale platform operators, Amazon Web Services, Microsoft Azure, and Google Cloud Platform occupy positions defined by compute scale and ecosystem integration depth. These entities exemplify the capability-concentrated tier where pricing power in GPU-intensive workloads remains most pronounced. Legacy technology conglomerates such as IBM Cloud and Oracle Cloud Infrastructure represent alternative positioning anchored in enterprise software stack entrenchment and regulated industry relationships. Regional specialists including Alibaba Cloud sit within geographically constrained opportunity sets defined by domestic data sovereignty requirements.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud Platform |
| IBM Cloud |
| Oracle Cloud Infrastructure |
| Alibaba Cloud |
| Dell Technologies |
| Cisco Systems |
| Fujitsu |
| Others |
Cost & Logistics Intelligence
Transatlantic subsea cable corridors linking Virginia Beach to Bilbao and Mumbai to Singapore shape cost dynamics across Infrastructure as a Service provisioning, concentrating supply in hyperscale landing zones while forcing price differentiation between latency-optimized and archival storage tiers. Energy transmission costs from regional grids to Frankfurt and São Paulo facilities further fragment pricing power across sovereign-compliant and standard deployments.
Pricing Analysis
Extended service contracts and reserved capacity commitments drive lifetime value more than base compute rates, with hyperscale operators bundling FinOps tooling and dedicated support into enterprise agreements. Three-tier pricing structure across premium sovereign, standard compliant, and economy multi-tenant levels separates buyers by data residency requirements and audit complexity. Cost compression in standard compute is intensifying because Arm-based processor adoption cuts per-watt operational expenditure. Government procurement teams demonstrate lowest price sensitivity, accepting premium rates for MeitY empanelment and EU AI Act compliance, while venture-backed startups prioritize consumption flexibility over committed discounts.
Supply Chain Analysis
Foundry concentration at TSMC, Samsung, and Intel sustains silicon supply for Graviton, Cobalt, and custom AI training chips deployed in hyperscale data centers. Server assembly draws from China, Taiwan, and Mexico, with cooling systems and power distribution units resting on copper and rare earth supply from Chile and Indonesia. Single-source vulnerability concentrates in advanced node semiconductor manufacturing, where geopolitical export controls threaten GPU instance availability. Distribution runs through direct enterprise sales teams for large contracts and self-service portals for mid-market consumption, with systems integrators bridging multi-cloud orchestration gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Infrastructure as a Service represents high-growth disruption as generative AI training workloads and EU AI Act data localization mandates simultaneously expand demand and fragment supplier qualification criteria.
For Market Incumbents: Insulate core enterprise relationships through dedicated sovereign cloud zones in Germany, India, and Brazil that preempt regulatory disqualification. Deepen backward integration into renewable energy matching and carbon-negative cooling to satisfy CSRD procurement mandates and defend margin position against specialized regional competitors.
For New Entrants and Emerging Players: Build out edge-to-cloud convergence offerings targeting manufacturing automation clusters in Japan's Chubu region and autonomous vehicle telemetry networks in Germany's automotive corridors. Capture white-space in sovereign-hybrid configurations for Brazilian public sector contracts where ANVISA and central bank mandates disqualify hyperscale providers without domestic presence.
For Investors and Strategic Acquirers: Regional sovereign cloud specialists with established MeitY empanelment or EU AI Act qualification pathways offer consolidation targets as compliance fragmentation accelerates. Long-term viability hinges on multi-cloud orchestration software capabilities that abstract workload portability across hyperscale and domestic infrastructure tiers. Monitor GPU availability constraints and export control expansion as inflection indicators for compute pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Zone Deployment | MeitY empanelment and EU AI Act compliance secure public sector contract eligibility in India and Germany. |
| Arm-Based Processor Transition | Graviton and Cobalt adoption cuts per-watt operational expenditure by one-third against x86 equivalents. |
| FinOps Platform Integration | Consumption visibility tools capture mid-market enterprises resisting long-term capacity commitments. |
| Multi-Cloud Orchestration Partnership | Kubernetes federation capabilities address enterprise IT proficiency gaps slowing migration timelines. |
| Carbon-Negative Certification Program | Verified renewable energy matching satisfies CSRD disclosure requirements and EU Green Deal taxonomy criteria. |
Research Approach
A standing panel of cloud procurement officers at financial services firms, MeitY empanelment auditors, data center operations directors, and FinOps tooling vendors provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from SEC hyperscaler capex disclosures, EU regulatory filings under GDPR and the EU AI Act, and BIS cloud standard documentation. Bottom-up segment sizing and top-down macroeconomic triangulation anchored market estimates across deployment types, service models, and regional adoption patterns.
Scenario-bracketing framed demand projections across the analysis window, modeling adoption curves for generative AI training workloads and sovereign cloud buildout timelines. Segmentation dimensions included deployment configuration, service model tier, end-user organization scale, and industry vertical compliance intensity. CAGRs derived from elasticity modeling of compute-hour consumption, storage gigabyte growth, and networking bandwidth expansion, with GPU instance pricing and carbon transition levy impacts incorporated as industry-specific forecast inputs.
Stress conditions across energy price volatility, semiconductor export control expansion, and data sovereignty mandate enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hyperscale capacity expansion, sovereign infrastructure construction timelines, and regulatory interpretation stability. Quarterly review of GPU supply constraints, MeitY empanelment list updates, and EU AI Act implementation guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Edge Server Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Computer Servers Market
Data Center and Networking
Data Center Networks Market
Data Center and Networking
APAC Data Center Networking Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Cluster Computing Market
Data Center and Networking
Global Data Management Platform Market
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Brazil Optical Transceiver Market
Data Center and Networking
Voice Over Internet Protocol (Voip) Market
Data Center and Networking
Austria Data Center Networking Market
Data Center and Networking
South Korea Data Center Server Market
Data Center and Networking
Global Network Configuration and Change Management Market