
 Greece E-Commerce Market | 2026-2036
Greece E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Greece E-Commerce Market Foresight
EU Digital Services Act enforcement is consolidating the cost-of-entry calculus for marketplace operators entering Greece. Skroutz S.A. leverages its domestic search-to-purchase ecosystem to sustain repeat transaction rates among Greek consumers. Public.gr anchors its position through vertical control over electronics distribution and in-house fulfillment networks. Kotsovolos competes by integrating physical appliance showrooms with digital order orchestration.
Greece E-Commerce denotes the digital exchange of goods and services conducted through web-based platforms and mobile applications, typically requiring secure payment gateways, inventory management systems, and last-mile logistics coordination to complete transactions. Electronics and clothing dominate product category transaction volumes, though groceries represent the fastest-growing segment as supermarket chains deploy dedicated delivery apps. Direct-to-consumer channels capture premium margin pools by eliminating intermediary fees, while marketplace platforms aggregate fragmented merchant supply across Greek regions. Cash on delivery retains structural importance in rural areas where card penetration lags, though credit card and digital wallet adoption accelerates in Athens and Thessaloniki urban corridors.
BIS certification requirements for imported electronics, EFTA-aligned consumer protection standards, and Greece's national data protection authority enforcement shape product safety disclosures and cross-border seller registration protocols. The Greek Ministry of Development and Investment monitors unfair commercial practices through periodic marketplace audits. Stakeholders must track how EU-wide platform liability rules reshape merchant onboarding costs and whether domestic fulfillment infrastructure expansion keeps pace with rising consumer delivery speed expectations.
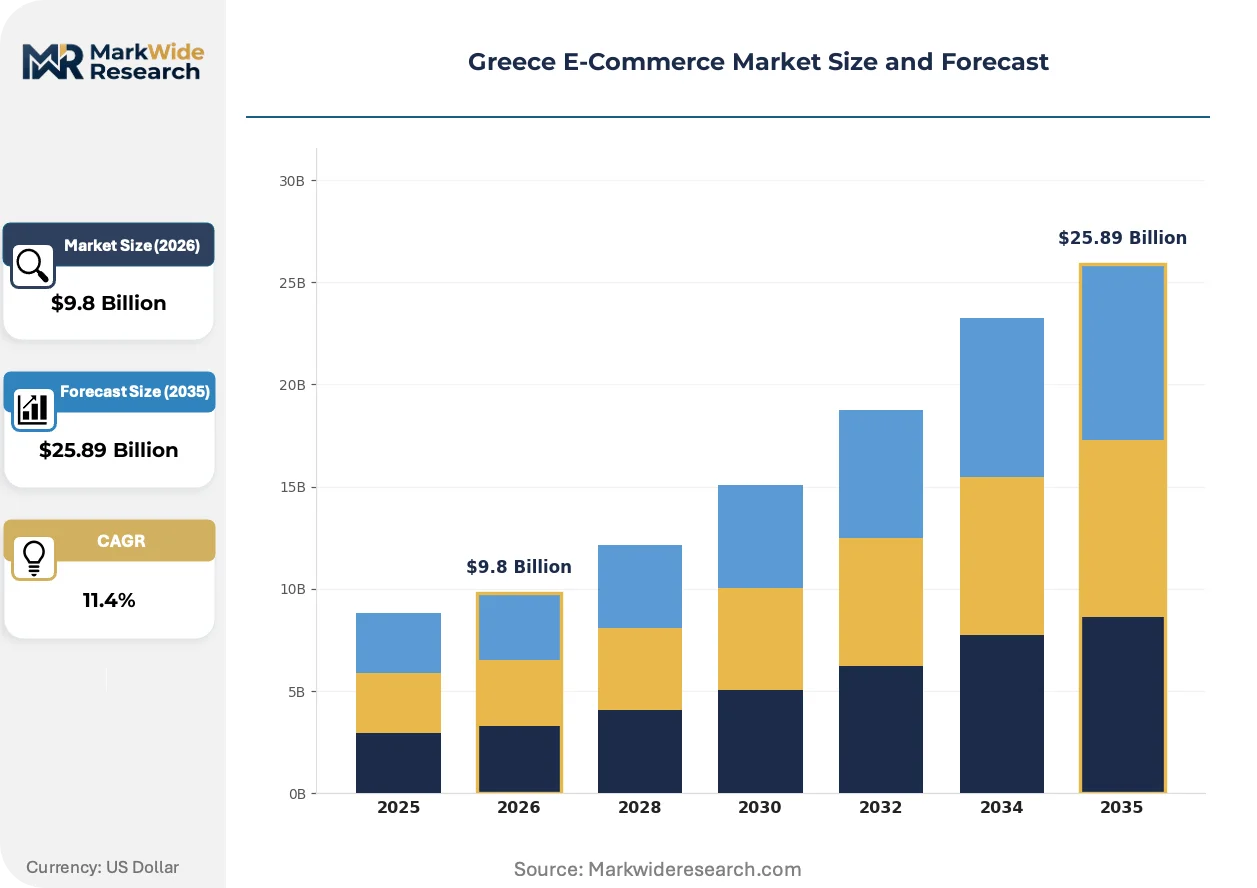
Market Dynamics
The EU Digital Services Act is consolidating compliance burdens for marketplace operators entering Greece, forcing recalculation of entry costs against the country's concentrated demand base in Greater Athens and Thessaloniki.
Growth Catalysts
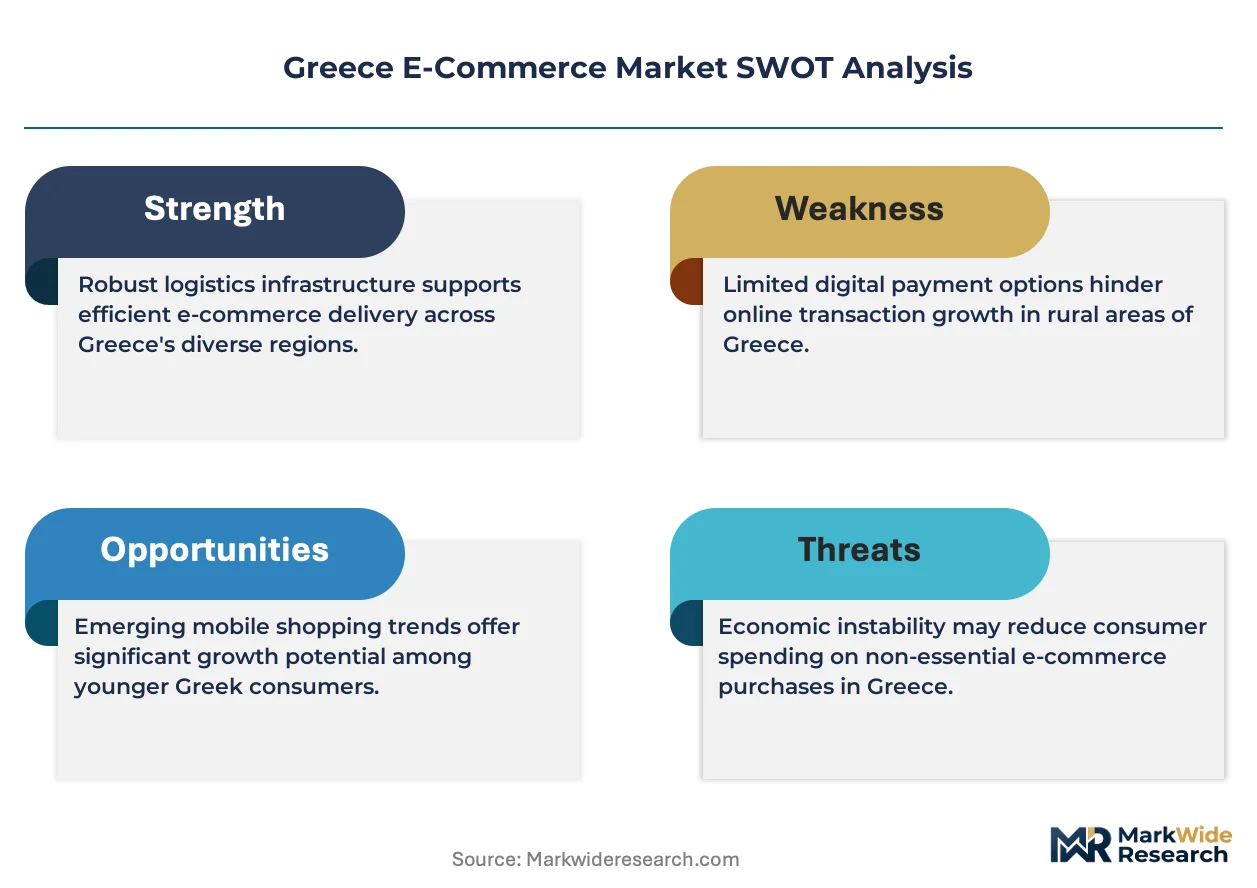
- Supermarket Delivery App Deployment:Greek supermarket chains are accelerating dedicated mobile application rollouts, capturing grocery purchases that previously required physical store visits.
- REACH-aligned Product Safety Standards:EFTA-aligned consumer protection frameworks are streamlining cross-border seller registration, reducing friction for merchants accessing Greek consumers.
- Same-Day Infrastructure Density:Logistics providers are concentrating fulfillment capacity in Athens, compressing delivery windows and elevating repeat purchase rates among urban households.
Market Restraints
- Rural Card Penetration Lag:Cash on delivery retains structural importance outside Athens and Thessaloniki, elevating working capital requirements and fraud exposure for merchants.
- Platform Liability Cost Escalation:EU-wide merchant onboarding rules are inflating verification and monitoring expenditures for marketplace operators targeting Greek consumers.
- Electronics Import Certification Burden:BIS certification requirements for imported electronics extend product launch timelines and complicate inventory planning for cross-border sellers.
Strategic Opportunities
- Thessaloniki Corridor Expansion:Northern Greece's second-largest urban center remains underserved relative to Athens, presenting first-mover advantages for fulfillment network investment.
- Direct-to-Consumer Channel Capture:Premium margin pools are accessible through elimination of intermediary fees, particularly in health and beauty segments where Greek consumers demonstrate channel-switching willingness.
- GDPR-Compliant Data Monetization:Greece's national data protection authority enforcement creates compliant frameworks for first-party data utilization in personalization and inventory forecasting.
Industry Challenges
- Last-Mile Talent Scarcity:Driver recruitment and retention difficulties in rural Peloponnese and island regions constrain delivery network expansion beyond core urban zones.
- Legacy Warehouse Management Integration:Greek retailers with established physical footprints face complex system reconciliation when connecting in-store inventory to digital order orchestration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greece E-Commerce Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Clothing, Groceries, Health & Beauty Sales Channel: Direct-to-Consumer, Marketplace, Subscription, B2B Payment Method: Credit Card, PayPal, Bank Transfer, Cash on Delivery Customer Segment: Millennials, Families, Seniors, Professionals |
| Companies Covered | Skroutz S.A., Public.gr, Kotsovolos, Plaisio Computers S.A., e-shop.gr, RetailWorld S.A., Amazon.com Inc., eBay, COSMOTE e-value S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greece E-Commerce Market Shifts & Advancements
Digital payment infrastructure and regulatory compliance technology are actively restructuring how Greek e-commerce operators manage transaction flow and merchant verification. Three developments merit particular attention.
Unified commerce platforms are unifying inventory visibility across physical showrooms and digital storefronts, enabling retailers to fulfill online orders from store stock. Appliance and electronics merchants in Athens are adopting these systems most aggressively. This convergence is compressing the competitive gap between pure-play digital entrants and established physical retailers.
GDPR enforcement by Greece's national data protection authority is elevating consent management and data retention protocols. Marketplace operators must now implement granular tracking disclosures and deletion workflows. Health and beauty segments face the steepest compliance adjustments due to sensitive consumer data handling requirements.
Greek consumers are compressing purchase decision cycles through mobile-first search-to-transaction behavior. Skroutz S.A.'s domestic search ecosystem has conditioned buyers to expect immediate price comparison and stock availability verification. Younger demographics in Athens demonstrate the shortest path from discovery to checkout, pressuring merchants to optimize mobile conversion funnels.
Greece E-Commerce Market Segmentation
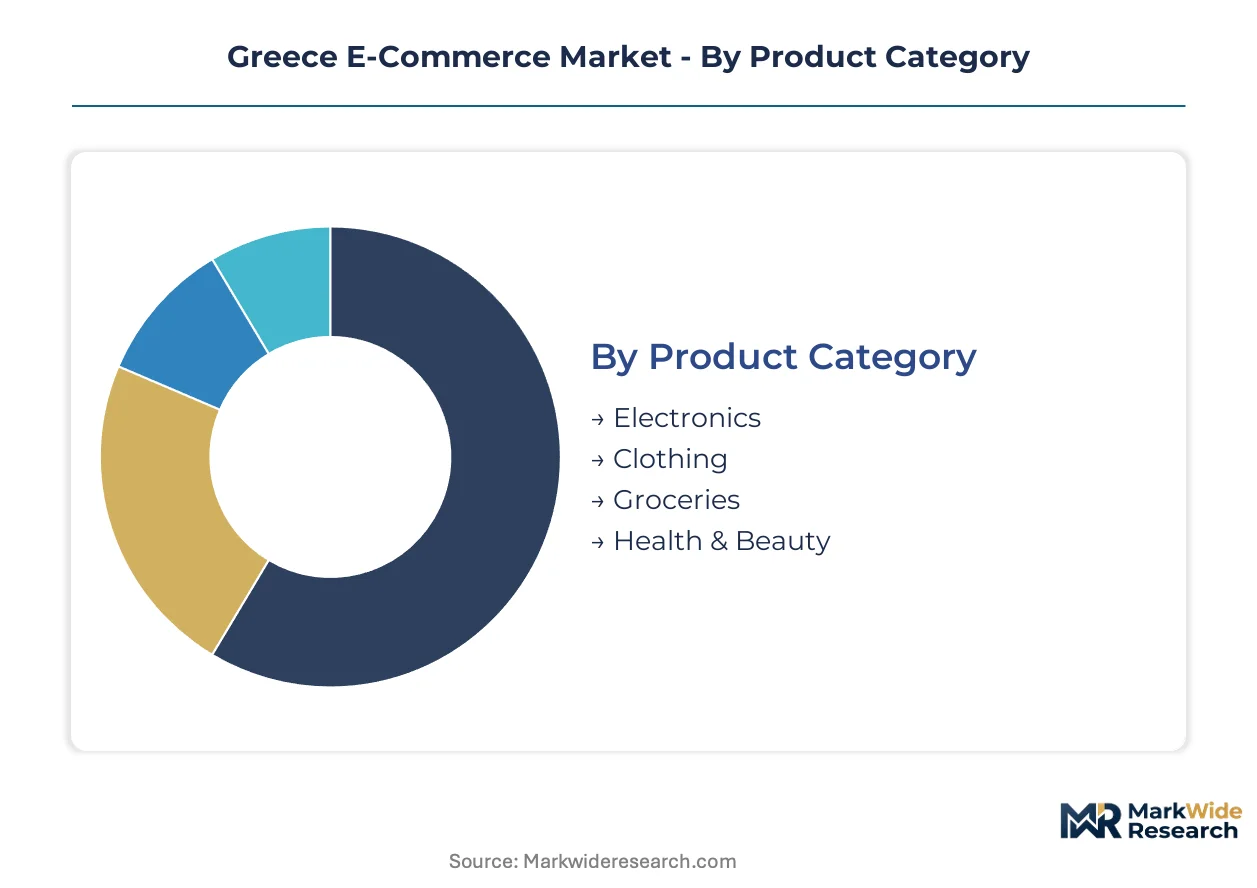
Greek e-commerce segmentation reveals how channel preferences and payment behaviors fragment across demographic and geographic lines. Understanding these divisions matters for inventory positioning, logistics investment, and compliance resource allocation in a market where Athens concentrates demand while rural areas retain distinct transaction patterns.
Product Category:
Upgrade cycles and replacement frequencies vary sharply across product types, with durable goods commanding longer purchase intervals than consumable categories.
- Electronics:Smartphones, laptops, and home appliances dominate transaction values through planned replacement purchases. Demand concentrates in Greater Athens and Thessaloniki where same-day fulfillment infrastructure supports impulse-driven upgrades. The EU Digital Services Act compliance costs weigh heaviest here due to cross-border seller density and import certification requirements.
- Clothing:Apparel purchases exhibit the shortest decision cycles among major categories, driven by seasonal refresh patterns and mobile-first discovery behavior. Volume clusters in Athens urban corridors where return logistics networks enable flexible sizing experimentation. Fast fashion penetration accelerates among younger demographics.
- Groceries:Supermarket chains deploy dedicated applications to capture weekly basket purchases previously requiring physical store visits.
- Health & Beauty:Greek consumers demonstrate notable channel-switching willingness as pharmacy chains and direct-to-consumer brands compete for skincare and wellness spending.
Volume placements concentrate in Electronics; the faster expansion belongs to Groceries.
Sales Channel:
Margin capture potential diverges based on intermediary elimination and customer relationship depth.
- Direct-to-Consumer:Brand-owned storefronts eliminate platform fees and capture first-party data for personalization. Health and beauty merchants exploit this channel most aggressively in Athens and Thessaloniki where logistics density supports reliable fulfillment promises.
- Marketplace:Aggregator platforms consolidate fragmented merchant supply across Greek regions, reducing customer acquisition costs for smaller sellers. Public.gr and Skroutz S.A. anchor this channel through search-to-purchase ecosystem integration.
- Subscription:Recurring revenue models gain traction in consumable categories requiring predictable replenishment cycles.
- B2B:Procurement digitization accelerates among Greek SMEs seeking supply chain efficiency improvements.
Revenue concentration sits with Marketplace platforms; Direct-to-Consumer channels are climbing the fastest as margin pressure intensifies.
Payment Method:
Working capital requirements and fraud exposure fluctuate based on settlement timing and geographic penetration patterns.
- Credit Card:Urban Athens and Thessaloniki corridors drive adoption where banking infrastructure and consumer trust align. Merchants prefer this method for immediate settlement and lower chargeback rates.
- Cash on Delivery:Structural importance persists in rural Peloponnese and island regions where card penetration lags and digital wallet trust remains underdeveloped.
- PayPal:Cross-border transactions favor this method for buyer protection guarantees and currency conversion simplicity.
- Bank Transfer:B2B purchases and high-value transactions default to this method for audit trail requirements.
Transaction volume clusters around Credit Card in urban zones; Cash on Delivery retains defensive importance in peripheral geographies.
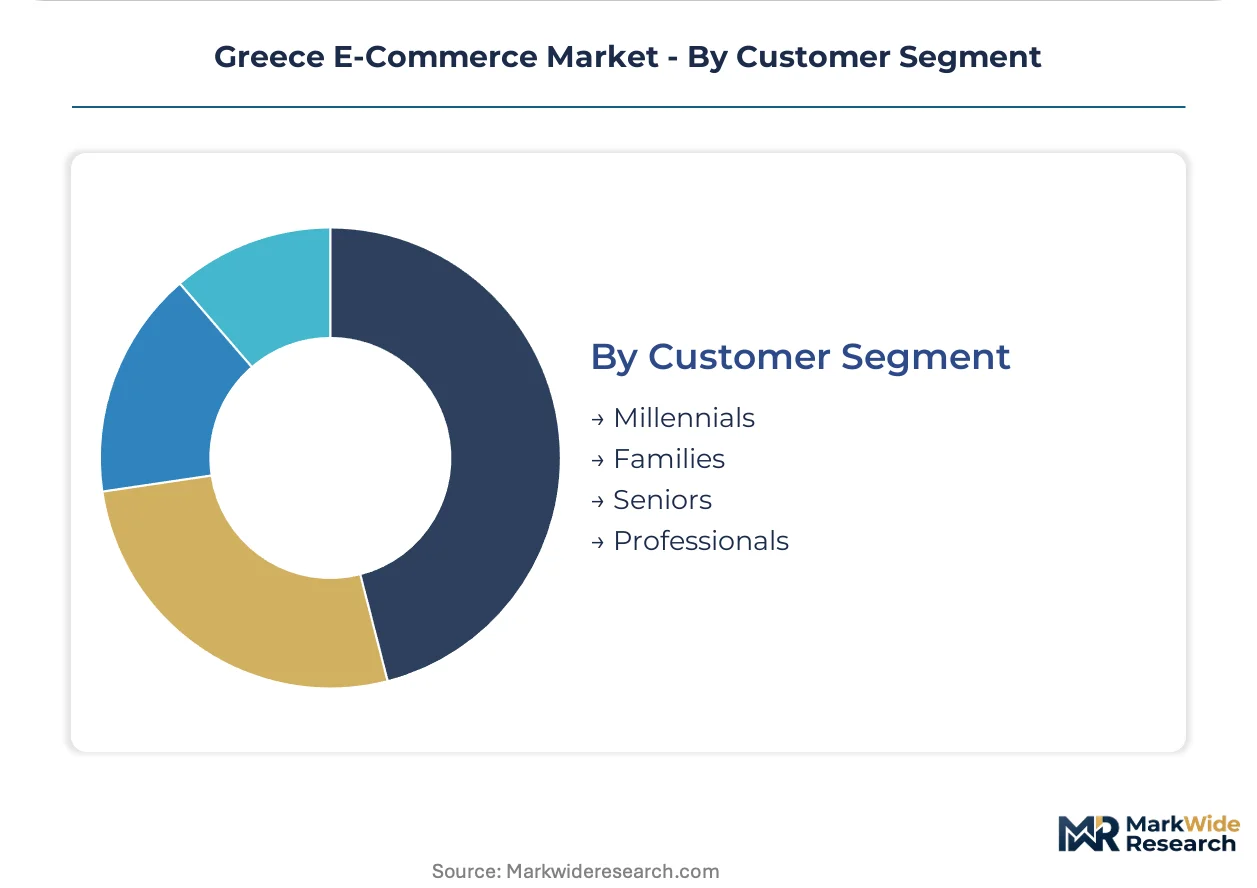
Customer Segment:
Digital sophistication and delivery speed expectations segment sharply across age and household composition lines.
- Millennials:Mobile-native behavior compresses discovery-to-purchase cycles through price comparison platforms. This cohort demonstrates highest subscription service adoption and social commerce responsiveness.
- Families:Bulk grocery purchasing and planned electronics replacement dominate spending patterns. Delivery reliability matters more than speed for household inventory management.
- Seniors:Customer service dependency and payment security concerns elevate support costs. Cash on delivery preference persists strongest here.
- Professionals:Time-constrained purchasing favors same-day delivery premiums and streamlined return processes in Athens commercial districts.
Spend concentration aligns with Millennials; Professionals are gaining share fastest as remote work normalization expands digital purchasing windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Attica Special Economic Zone incentives concentrate fulfillment infrastructure investment around Athens, accelerating same-day delivery network density while Thessaloniki corridor expansion lags in logistics capacity.
Greater Athens
Urban households drive credit card and digital wallet adoption through mobile-first purchasing behavior. The EU Digital Services Act compliance requirements reshape merchant onboarding costs for marketplace operators targeting Attica consumers. Piraeus port logistics clusters anchor cross-border inventory staging for electronics imports.
Thessaloniki Urban Corridor
Northern Greece's second metropolitan center exhibits underserved fulfillment infrastructure relative to consumer demand density. Greece's national data protection authority enforcement elevates consent management costs for health and beauty segments operating in Macedonia-Thrace retail zones. Thermi industrial parks attract cold-chain logistics investment for grocery delivery expansion.
Peloponnese Peninsula
Rural card penetration lag sustains cash on delivery structural importance across Corinth and Patras secondary cities. EFTA-aligned consumer protection frameworks streamline cross-border seller registration for agricultural equipment merchants. Kalamata logistics hubs struggle with driver recruitment scarcity constraining last-mile network reach.
Crete and Aegean Islands
Island geography fragments delivery network economics through ferry-dependent supply chains and seasonal demand volatility. Tourism-driven consumer spending concentrates in Heraklion and Chania during summer months. Piraeus shipping connections determine inventory replenishment cycles for electronics and apparel merchants.
Central Greece and Thessaly
Volos and Larissa manufacturing bases generate B2B procurement digitization demand among SME industrial suppliers. REACH-aligned product safety standards reduce friction for cross-border chemical and agricultural input sellers. Lamia distribution centers serve as inland consolidation points connecting northern and southern consumption corridors.
Greece E-Commerce Market Competitive Landscape
Athens-based operators anchor the domestic tier; international marketplace subsidiaries hold cross-border volume. The vendor structure concentrates around three domestic platforms controlling search-to-purchase ecosystems, with global entrants capturing premium electronics and cross-border niche segments. Strategic archetypes include domestic search aggregators, vertical electronics distributors, and omnichannel appliance retailers. Competitive moves center on fulfillment network densification and unified commerce platform deployment connecting physical showroom inventory to digital order orchestration.
Within the domestic platform tier, Skroutz S.A. and Public.gr exemplify search-to-purchase ecosystem integration, while Kotsovolos occupies a position bridging physical appliance showrooms with digital order fulfillment. Amazon.com Inc. and eBay represent cross-border marketplace archetypes competing on import electronics selection and buyer protection guarantees. These five entities collectively illustrate how Greek e-commerce competition stratifies between domestically rooted infrastructure players and international volume aggregators.
| Leading Market Players |
|---|
| Skroutz S.A. |
| Public.gr |
| Kotsovolos |
| Plaisio Computers S.A. |
| e-shop.gr |
| RetailWorld S.A. |
| Amazon.com Inc. |
| eBay |
| COSMOTE e-value S.A. |
| Others |
Supply & Pricing Matrix
Vertical integration into in-house fulfillment networks anchors supply positioning for domestic marketplace operators while compressing margin pools available to cross-border sellers. This integration choice concentrates pricing power with Athens-based platforms that control last-mile density, forcing international entrants to absorb higher logistics costs or cede urban market share.
Pricing Analysis
Premium pricing for same-day delivery windows separates Athens corridor merchants from standard-tier competitors serving next-day or longer lead times. Three-tier pricing structure across premium, standard, and economy delivery tiers reflects fulfillment infrastructure investment levels, with health and beauty segments commanding the widest spreads due to perishable handling requirements. Pricing pressure stems from EU Digital Services Act compliance cost inflation, particularly for marketplace operators onboarding cross-border electronics merchants. Small domestic retailers exhibit highest price sensitivity, while time-constrained professionals in Athens commercial districts accept delivery premiums.
Supply Chain Analysis
Workforce availability constraints in Bulgarian and Romanian logistics hubs limit fulfillment capacity expansion for Greek market coverage. Electronics inventory draws from Chinese manufacturing clusters and German distribution centers, while apparel sourcing concentrates in Turkish and Italian production zones. Single-source vulnerability runs through Piraeus port chokepoints for containerized Asian imports. Distribution runs through Attica-based fulfillment centers with radiating spoke networks to Thessaloniki, Patras, and island ferry terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greek e-commerce is consolidating around platform operators with captive fulfillment infrastructure, as EU compliance cost escalation forces smaller cross-border merchants toward aggregator dependence or exit.
For Market Incumbents: Deploy unified commerce platforms connecting physical showroom inventory to digital order orchestration, closing the competitive gap with pure-play entrants. Kotsovolos and Public.gr should deepen cold-chain logistics investment in Thermi industrial parks ahead of grocery delivery acceleration. Defensive positioning requires pre-emptive certification alignment with REACH product safety standards before EFTA enforcement tightens. For New Entrants and Emerging Players: Enter via Thessaloniki corridor fulfillment gaps, where demand density exceeds logistics infrastructure investment. Health and beauty direct-to-consumer channels present the most penetrable white space, given Greek consumer willingness to switch from pharmacy retail. A mobile-first search optimization go-to-market angle captures Skroutz S.A.-conditioned purchase behavior among Athens millennials. For Investors and Strategic Acquirers: Exit pathways concentrate in domestic platform acquisitions by regional European marketplace operators seeking Attica logistics density. Five-to-ten year viability favors vertically integrated players with captive warehousing rather than asset-light marketplace models. The signal to watch is Piraeus port capacity expansion timelines, which determine inventory cost structures for electronics import-dependent sellers.| Strategic Initiative | Industry Significance |
|---|---|
| Same-Day Fulfillment Network Densification | Athens-based platforms capture repeat purchase premiums through compressed delivery windows. |
| Unified Commerce Platform Deployment | Electronics retailers reconcile in-store inventory with digital order orchestration systems. |
| GDPR-Compliant Data Infrastructure | Health and beauty merchants navigate Greece's national data protection authority enforcement. |
| Thessaloniki Logistics Hub Investment | Northern Greece corridor expansion addresses underserved demand density relative to Athens. |
| Direct-to-Consumer Channel Launch | Brand-owned storefronts eliminate platform fees and capture first-party personalization data. |
Research Methodology
Document review covered EU regulatory filings, Greek Ministry of Development audit reports, and logistics operator capacity disclosures, complemented by interviews with e-commerce platform executives, third-party fulfillment providers, and supermarket chain digital directors. Secondary validation drew from Attica Special Economic Zone investment announcements, Piraeus port throughput statistics, and EU Digital Services Act implementation guidance. Bottom-up merchant onboarding cost modeling and top-down Attica demand aggregation were triangulated against cross-referenced estimates.
Market sizing outputs reflect segmentation across product category, sales channel, payment method, and customer demographic dimensions over the projection horizon. CAGRs were derived from logistics infrastructure investment trajectories and supermarket application deployment timelines. Modeled inputs included same-day delivery penetration curves, cash-on-delivery geographic decay patterns, and EU compliance cost pass-through assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Piraeus port congestion scenarios or accelerated EU platform liability enforcement. Forecasts reflect documented assumptions regarding Athens demand concentration stability and Thessaloniki infrastructure investment pacing. A small set of triggers—ferry schedule disruptions, BIS certification timeline shifts, and rural card penetration acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Finland E-Commerce Market
E-Commerce Solutions
Business to Business E Commerce Market
E-Commerce Solutions
Nigeria E-Commerce Market
E-Commerce Solutions
Czech Republic E-Commerce Market
E-Commerce Solutions
Brazil E-Commerce Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market
E-Commerce Solutions
North America FMCG B2B E-Commerce Market
E-Commerce Solutions
South Korea Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Japan Cross Border E Commerce Market
E-Commerce Solutions
Hungary E-Commerce Market
E-Commerce Solutions
North America E-Commerce Watch Market
E-Commerce Solutions
North America E-Commerce Market
E-Commerce Solutions
Global Digital Commerce Market
E-Commerce Solutions
Egypt E-Commerce Market
E-Commerce Solutions
Courier Express and Parcel (CEP) Market
E-Commerce Solutions
Mobile Commerce Market