
 Global Service Procurement Market | 2026-2036
Global Service Procurement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Service Procurement Market Foresight
Subscription-based access to procurement orchestration tools is repositioning how enterprises acquire external professional capabilities. SAP SE leverages its embedded S/4HANA procurement modules to anchor large manufacturing clients in integrated source-to-pay workflows. Oracle Corporation competes through autonomous procurement cloud features that automate supplier qualification and contract compliance. GEP differentiates via its direct materials and services procurement convergence platform, occupying a niche among Fortune 500 indirect spend programs.
Service procurement encompasses the structured sourcing, contracting, and lifecycle management of external professional capabilities delivered through statement-of-work engagements, purchase orders, or vendor-managed arrangements, typically governed by service-level agreements specifying deliverables, timelines, and performance metrics. The practice enables organizations to access specialized expertise without permanent workforce expansion, with procurement technology platforms automating requisition routing, vendor scoring, and invoice reconciliation against milestone completion. IT services and consulting segments lead current platform adoption as enterprises digitize legacy operations and seek systems integrator flexibility. Managed services engagement models are recording the fastest expansion as buyers shift from transactional project purchasing to continuous outcome accountability. Facility management and logistics procurement remain comparatively mature, with margin pools compressing toward vendor consolidation and bundled asset-plus-service contracts.
FDA 21 CFR Part 11 electronic records requirements shape validation protocols for procurement platforms serving pharmaceutical and medical device supply chains. ESG disclosure mandates under EU CSRD and SEC climate rules are forcing procurement organizations to embed supplier emissions tracking into service vendor selection criteria. ISO 20400 sustainable procurement guidance provides a voluntary framework that large enterprises increasingly reference in RFP scoring. Stakeholders must decide whether to build carbon accounting into service procurement workflows now or retrofit compliance architectures as mandatory scope 3 reporting tightens.
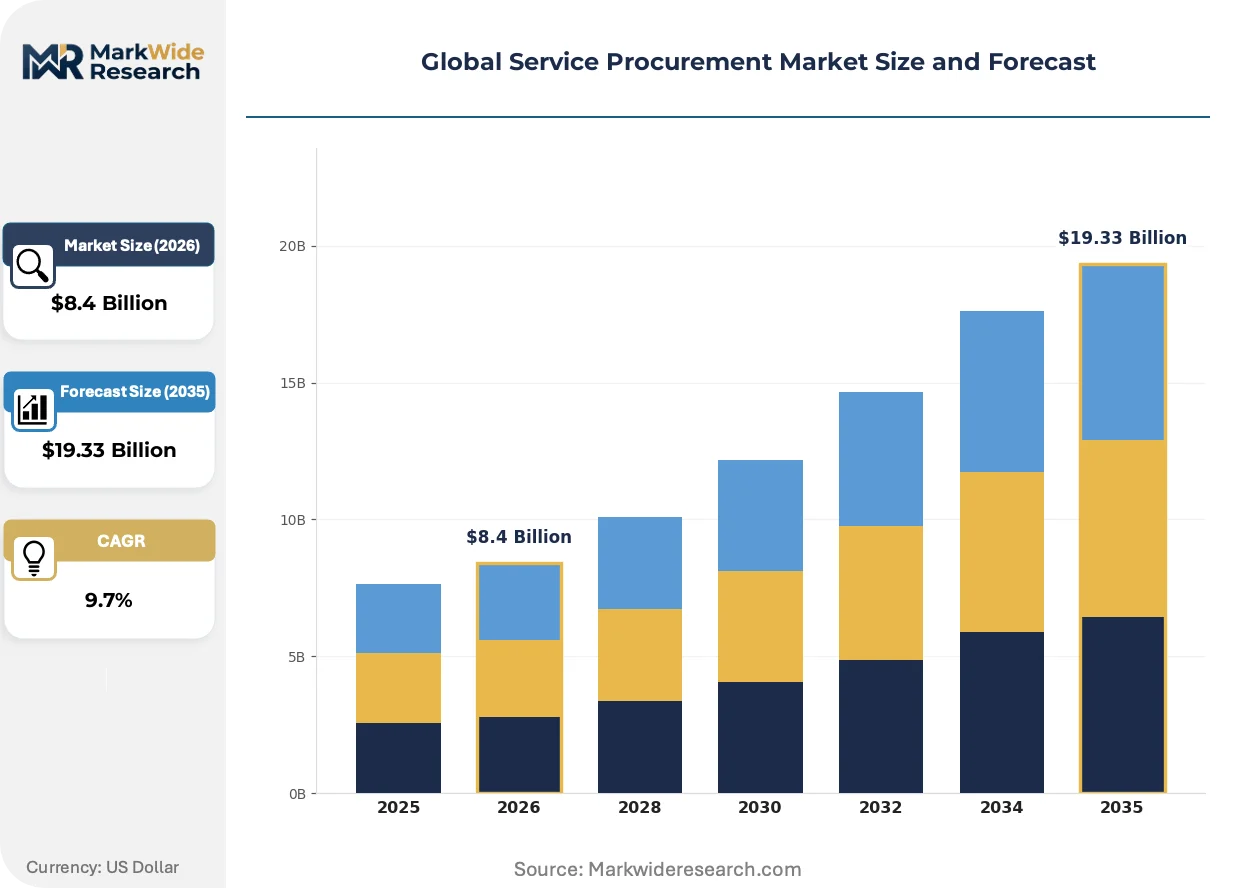
Market Dynamics
Enterprise migration toward continuous outcome accountability is compressing transactional project purchasing models across IT services and consulting engagements, with procurement platforms racing to embed milestone-based payment automation and vendor performance scoring.
Growth Catalysts
- EU CSRD disclosure mandates:Large enterprises must now track supplier emissions in service vendor selection, forcing procurement organizations to integrate carbon accounting workflows into source-to-pay platforms.
- Basel III capital requirements:Financial institutions face heightened liquidity and risk-weighting rules that accelerate adoption of managed services procurement to convert fixed workforce costs into variable operational expenditures.
- IT services digitization:Enterprise legacy modernization programs generate sustained demand for systems integrator flexibility through statement-of-work engagements rather than permanent headcount expansion.
Market Restraints
- Platform integration complexity:Legacy ERP architectures in manufacturing and energy sectors resist seamless API connectivity with cloud-native procurement orchestration tools, extending implementation timelines.
- Supplier data fragmentation:Vendor qualification records, performance histories, and compliance certifications remain siloed across disparate systems, degrading automated scoring accuracy.
- Specialized talent scarcity:Procurement technology teams lack sufficient expertise in machine learning model governance and supplier risk analytics, constraining feature deployment velocity.
Strategic Opportunities
- India's professional services export expansion:IT consulting and business process outsourcing clusters in Bangalore and Hyderabad present underpenetrated addressable market for procurement platform localization.
- ISO 20400 sustainable procurement framework:Voluntary guidance adoption among Fortune 500 indirect spend programs creates competitive differentiation for platforms embedding ESG scoring into RFP workflows.
- AI-driven contract analytics convergence:Natural language processing engines extracting obligation clauses from statement-of-work documents are unifying with procurement orchestration layers, enabling automated compliance monitoring.
Industry Challenges
- FDA 21 CFR Part 11 validation protocols:Pharmaceutical and medical device supply chains require electronic records integrity standards that procurement platforms must satisfy through extensive documentation and audit trails.
- Scope 3 emissions measurement skill gaps:Procurement organizations struggle to source analysts capable of calculating service vendor carbon footprints across distributed professional engagements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Service Procurement Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Marketing, IT Services, Facility Management, Logistics, Financial Advisory Client Type: Enterprises, Government Agencies, Nonprofits, Small & Medium Businesses, Startups Engagement Model: Project-Based, Retainer, Outcome-Based, Managed Services, Time & Materials Distribution Channel: Direct Sales, Online Marketplaces, Channel Partners, Vendor Platforms, Third-Party Brokers |
| Companies Covered | Accenture, IBM, GEP, Genpact, Infosys, SAP SE, Coupa Software, Oracle Corporation, WNS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Service Procurement Market Shifts & Advancements
Intelligent automation layers are compressing the requisition-to-payment cycle while embedding compliance and sustainability checkpoints directly into workflow orchestration, eliminating retrospective audit and reconciliation overhead.
Procurement orchestration platforms is unifying source-to-pay workflows with embedded supplier risk analytics and contract lifecycle management. Large manufacturing enterprises operating SAP S/4HANA environments are adopting these converged stacks fastest, consolidating previously siloed indirect spend programs under single data models. The structural consequence is compressing vendor management headcount requirements while accelerating qualification cycle times.
SEC climate disclosure rules finalized under the prior administration are forcing US-listed enterprises to capture service vendor emissions data in procurement workflows. Industrial consequence includes mandatory supplier questionnaires and third-party verification requirements that procurement platforms must now automate. Technology and healthcare verticals with complex professional services supply chains are responding by embedding carbon scoring into vendor onboarding sequences.
Managed services engagement models are displacing transactional project purchasing across IT consulting and facilities management categories. Large enterprises in United States federal contracting and German automotive manufacturing are shifting vendor accountability toward continuous outcome measurement rather than deliverable acceptance. This behavioral pivot is most visible in GSA schedule professional services sourcing and Bundeswehr IT infrastructure outsourcing programs.
Global Service Procurement Market Segmentation
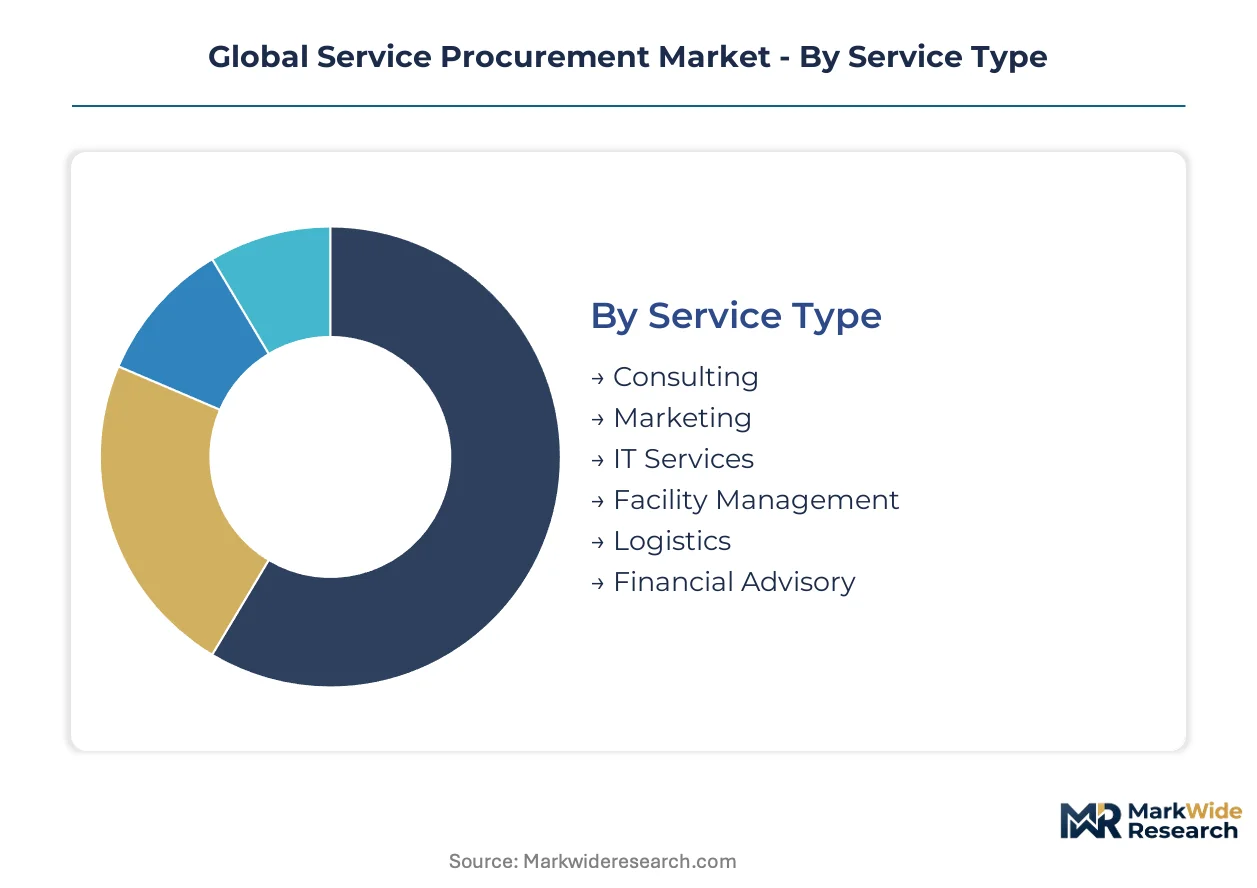
Service procurement segmentation reveals how buyer sophistication and contract complexity vary across professional capabilities. Procurement platforms must configure distinct workflow engines for each dimension to capture pricing transparency and performance accountability.
Service Type:
Replacement cycles for external professional capabilities accelerate as enterprises refresh digital infrastructure and restructure operating models.
- IT Services:Systems integration, cloud migration, and cybersecurity engagements dominate platform transaction volumes. Demand concentrates among German automotive manufacturers and US federal contractors modernizing legacy infrastructure under compressed timelines.
- Consulting:Strategy and operations advisory delivered through statement-of-work structures with milestone-based payment terms. Financial institutions in the United States leverage these engagements to navigate Basel III workforce flexibility requirements.
- Marketing:Creative and media buying services procured through agency-of-record and project-based arrangements.
- Facility Management:Integrated asset-plus-service contracts consolidating maintenance, cleaning, and energy management under single vendors.
- Logistics:Third-party transportation and warehousing services with performance metrics tied to delivery reliability.
- Financial Advisory:M&A due diligence, restructuring, and valuation services subject to SEC conflict-of-interest protocols.
IT Services sits at the top of the volume ranking, with Consulting climbing the fastest.
Client Type:
Procurement sophistication and contract scale diverge sharply across organizational maturity tiers.
- Enterprises:Fortune 500 and large multinational organizations operating centralized procurement functions with embedded ESG scoring. These buyers in the United States and Germany drive adoption of converged source-to-pay platforms with supplier risk analytics.
- Government Agencies:Federal, state, and municipal entities bound by competitive bidding mandates and socio-economic contracting quotas. US agencies utilize GSA schedules for professional services sourcing with stringent compliance documentation.
- Small & Medium Businesses:Mid-market organizations prioritizing cost efficiency over procurement technology investment.
- Nonprofits:Mission-driven organizations with donor-imposed spending constraints and grant compliance requirements.
- Startups:Venture-backed companies favoring flexible, short-term engagements without long-term vendor lock-in.
Enterprises command the largest addressable spend base, while Government Agencies are expanding procurement platform mandates most aggressively.
Engagement Model:
Contract structures determine how risk, accountability, and payment timing allocate between buyer and vendor.
- Managed Services:Continuous outcome accountability with vendors assuming operational risk for defined service levels. Large enterprises in US federal contracting and German manufacturing are displacing transactional purchasing with these arrangements.
- Outcome-Based:Payment contingent upon measurable business results rather than effort expended. Healthcare systems and pharmaceutical supply chains under FDA 21 CFR Part 11 requirements favor this structure for validation-critical engagements.
- Project-Based:Fixed-scope deliverables with defined acceptance criteria and milestone payments.
- Retainer:Recurring fees for on-call advisory access without guaranteed utilization.
- Time & Materials:Hourly or daily rates with limited outcome guarantees, declining in strategic procurement programs.
Managed Services generates the highest contract values, with Outcome-Based structures gaining share fastest in regulated industries.
Distribution Channel:
Channel selection shapes pricing transparency, vendor discovery breadth, and contract negotiation leverage.
- Vendor Platforms:Cloud-native procurement orchestration tools embedding supplier qualification, contract lifecycle management, and invoice reconciliation. SAP SE and Oracle Corporation anchor large manufacturing clients in these integrated environments.
- Online Marketplaces:Digital exchanges matching buyers with pre-qualified service providers across geographies. Demand concentrates among technology and healthcare verticals seeking rapid vendor activation.
- Direct Sales:Relationship-driven procurement through established vendor account teams.
- Channel Partners:Systems integrators and consultancies reselling specialized capabilities.
- Third-Party Brokers:Intermediaries aggregating demand and negotiating volume discounts.
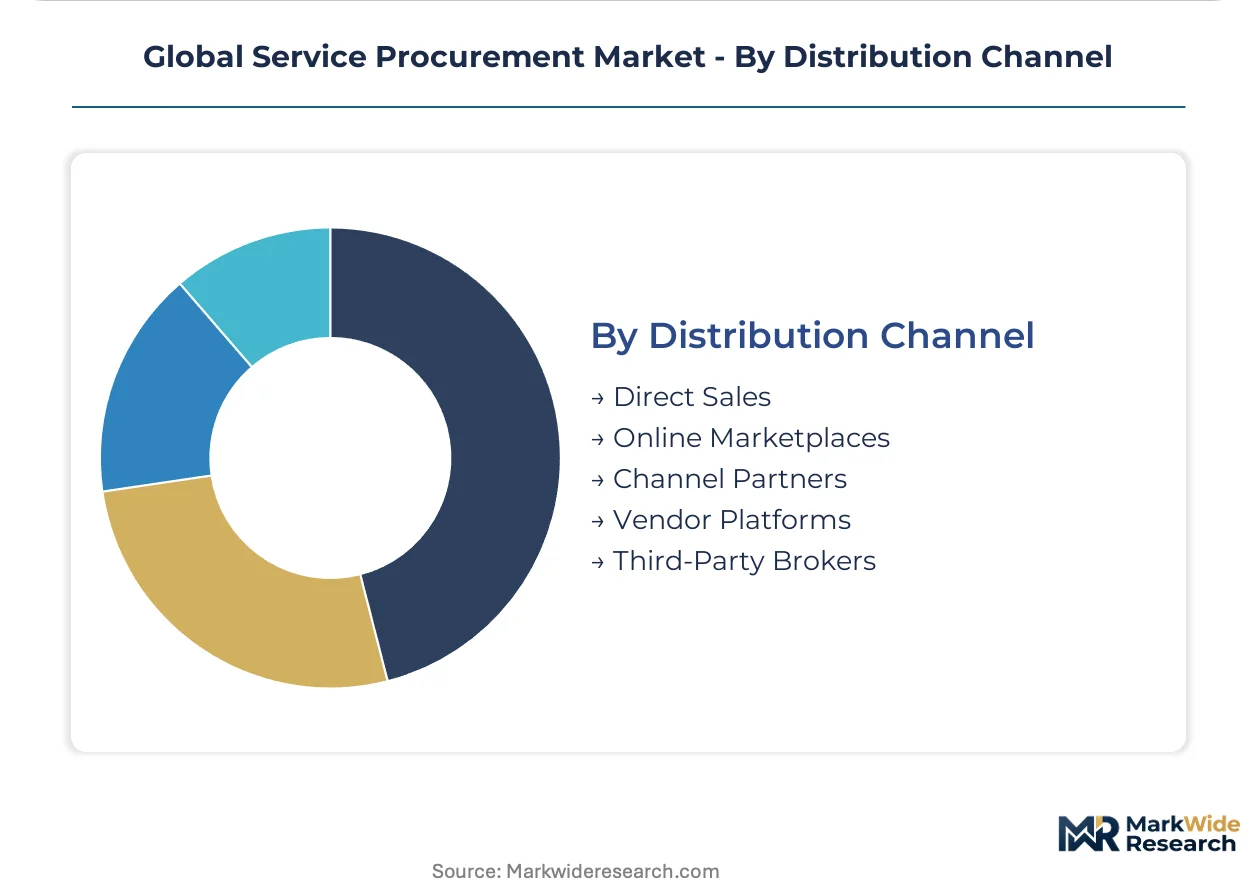
Vendor Platforms capture the greatest technology investment, with Online Marketplaces expanding most quickly among mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting service procurement platform investment toward jurisdictions with clearer compliance roadmaps and lower cost-of-implementation gaps. Enterprises migrate procurement orchestration capabilities to markets where ESG disclosure mandates and capital requirements create immediate technology upgrade imperatives.
United States
Federal contractors expanding professional services sourcing through GSA schedules drive platform adoption among government-facing enterprises. SEC climate disclosure rules finalized under prior administration force US-listed companies to capture service vendor emissions data in procurement workflows. Technology and healthcare verticals in California and Massachusetts respond by embedding carbon scoring into vendor onboarding sequences.
Germany
Automotive manufacturers operating under compressed digitization timelines generate concentrated demand for systems integrator flexibility through statement-of-work engagements. EU CSRD disclosure mandates require large enterprises to track supplier emissions in service vendor selection, forcing procurement organizations to integrate carbon accounting workflows. Industrial procurement clusters in Bavaria and Baden-Württemberg consolidate indirect spend programs under converged source-to-pay platforms.
India
IT consulting and business process outsourcing clusters in Bangalore and Hyderabad present underpenetrated addressable market for procurement platform localization. RBI guidelines on outsourcing risk management shape validation protocols for financial institutions procuring external professional capabilities. Export-oriented services hubs in Telangana and Karnataka accelerate adoption of milestone-based payment automation for systems integrator engagements.
United Kingdom
Financial institutions navigating post-Brexit regulatory restructuring convert fixed workforce costs into variable operational expenditures through managed services procurement. FCA operational resilience requirements mandate third-party risk management frameworks that procurement platforms must satisfy through extensive documentation capabilities. London-based professional services buyers shift vendor accountability toward continuous outcome measurement rather than deliverable acceptance.
China
State-owned enterprises modernizing legacy infrastructure under compressed timelines generate sustained demand for external professional capabilities delivered through vendor-managed arrangements. MIIT data security regulations shape supplier qualification protocols for procurement platforms serving domestic technology supply chains. Yangtze River Delta manufacturing clusters adopt integrated source-to-pay workflows to consolidate previously siloed indirect spend programs.
Global Service Procurement Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise software vendors anchoring large manufacturing clients while pure-play procurement platforms capture mid-market flexibility requirements. The vendor ecosystem organizes around three strategic archetypes: ERP-embedded procurement modules, cloud-native orchestration specialists, and business process outsourcing hybrids. Consolidation pressure intensifies as buyers demand converged stacks unifying supplier risk analytics with contract lifecycle management. Competitive positioning hinges on API connectivity depth and vertical-specific compliance template libraries.
Within the ERP-embedded tier, SAP SE and Oracle Corporation exemplify platform strategies that anchor large manufacturing clients in integrated source-to-pay workflows. GEP occupies a distinct position among Fortune 500 indirect spend programs through its direct materials and services procurement convergence capabilities. These three entities represent how procurement technology vendors differentiate through either embedded enterprise system relationships or specialized spend category convergence.
| Leading Market Players |
|---|
| Accenture |
| IBM |
| GEP |
| Genpact |
| Infosys |
| SAP SE |
| Coupa Software |
| Oracle Corporation |
| WNS |
| Others |
Supply & Pricing Matrix
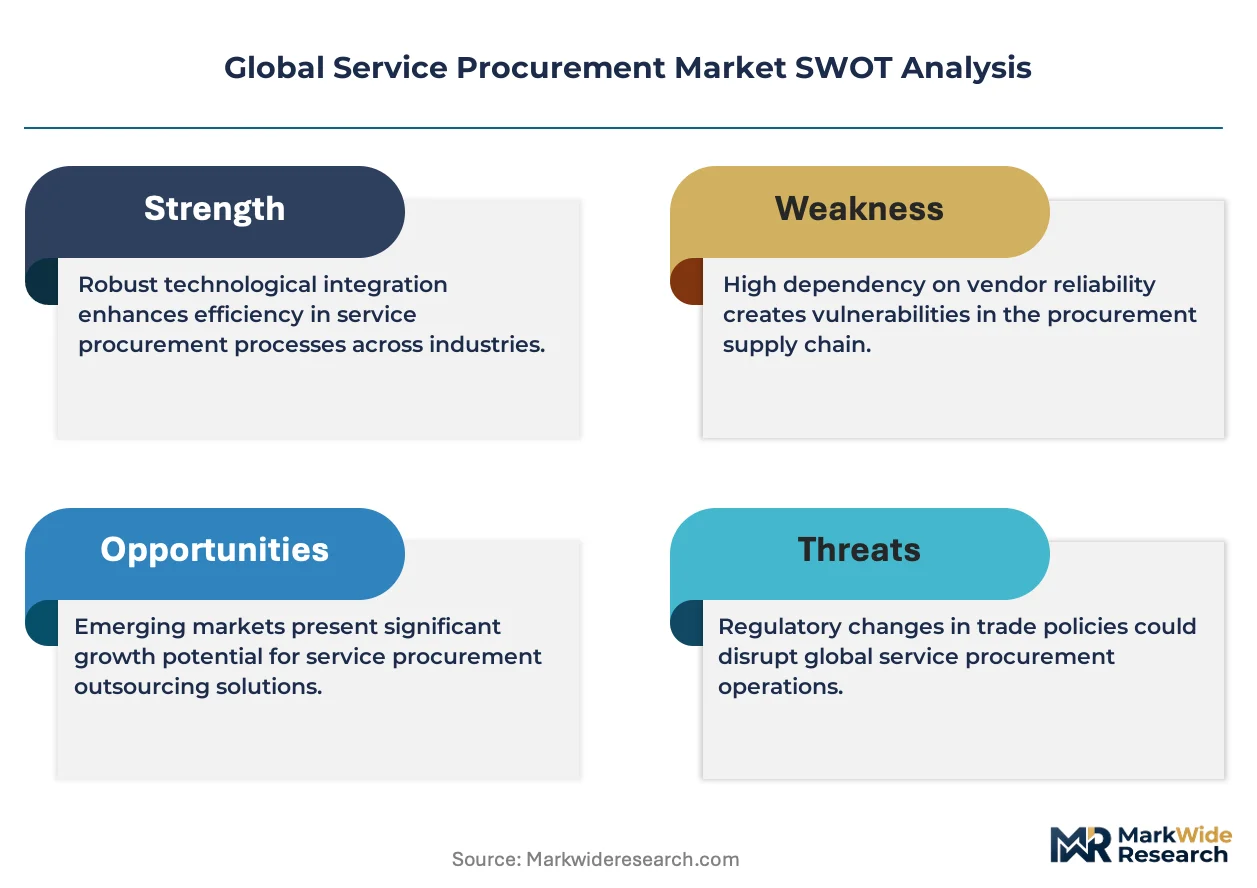
EU CSRD disclosure mandates gate qualified supply and premium-tier pricing access by requiring carbon-accounting capabilities in procurement platforms, forcing vendors to absorb compliance costs or forfeit enterprise contracts to certified competitors.
Pricing Analysis
Capacity additions in India are reshaping price floors for procurement orchestration tools as Bangalore and Hyderabad service hubs expand delivery bandwidth. SaaS-tiered subscription models dominate, with price differentiation resting on vertical-specific compliance template depth and API connectivity sophistication. Pricing pressure stems from cloud-native entrants undercutting ERP-embedded incumbents on implementation timelines. Small and medium businesses exhibit highest price sensitivity, while Fortune 500 enterprises prioritize outcome accountability over license cost.
Supply Chain Analysis
Single-source vulnerability sits with United States-based hyperscaler infrastructure providers hosting procurement platform workloads. Software development talent concentrates in India, Germany, and the United States, with platform engineering expertise drawing from Bangalore, Munich, and Silicon Valley clusters. Supply chain risk centers on regulatory restriction as FDA 21 CFR Part 11 validation requirements and EU CSRD carbon-accounting protocols fragment vendor qualification standards. Distribution runs through direct enterprise sales teams anchored by SAP SE and Oracle Corporation account relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate between Germany's regulatory-compressed implementation timelines and India's cost-advantaged platform localization capacity.
For Market Incumbents: Deepen vertical integration into supplier risk analytics by acquiring niche ESG scoring specialists before EU CSRD enforcement tightens. Anchor large manufacturing clients in S/4HANA procurement modules through embedded carbon-accounting workflows that cloud-native competitors cannot replicate without ERP partnerships. For New Entrants and Emerging Players: Online marketplaces targeting mid-market technology and healthcare verticals offer the most penetrable entry vector. Localize milestone-based payment automation for Indian IT consulting clusters in Telangana and Karnataka, where export-oriented services hubs lack indigenous procurement platform alternatives. For Investors and Strategic Acquirers: Roll-up economics work for procurement orchestration specialists because fragmented vendor management headcount requirements across Fortune 500 indirect spend programs create consolidation value. Target platforms with ISO 20400 sustainable procurement framework certification and FDA 21 CFR Part 11 validation capabilities. Watch SEC climate disclosure rule enforcement intensity as the inflection signal for carbon-scoring feature demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies SAP S/4HANA procurement modules with autonomous supplier qualification workflows for German automotive manufacturers. |
| Acquisition of Specialist Firm | Captures ESG scoring capabilities required by EU CSRD mandates affecting large enterprise vendor selection criteria. |
| Geographic Expansion | Localizes procurement orchestration tools for Indian IT consulting clusters in Bangalore and Hyderabad export hubs. |
| Strategic Partnership | Aligns procurement platforms with GSA schedule compliance requirements for United States federal contractor professional services sourcing. |
| Product Launch | Introduces milestone-based payment automation embedding FDA 21 CFR Part 11 validation protocols for pharmaceutical supply chains. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with procurement technology executives, enterprise IT procurement officers, platform integration specialists, and vendor risk analysts with secondary validation against SEC filings, EU regulatory disclosure databases, GSA schedule contracting records, and ISO certification registries. Bottom-up platform adoption estimates and top-down enterprise spend analysis were triangulated to anchor market sizing.
Comparable-period anchoring linked the projection horizon to historical procurement platform deployment cycles across the modeling period. Segmentation dimensions modeled include service type, client tier, engagement model structure, and distribution channel complexity. CAGRs were derived from trend extrapolation adjusted for regulatory mandate enforcement schedules and cloud migration velocity in financial services verticals.
The model assumes a particular technology adoption path; alternative pathways for AI-driven contract analytics convergence would alter the outlook. Forecasts reflect assumptions about Basel III capital requirement enforcement continuity and EU CSRD disclosure mandate adherence timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
US Managed Print Services Market
Business Process Outsourcing (BPO)
Global Insurance Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Telecom Outsourcing Market
Business Process Outsourcing (BPO)
Front Office BPO Services Market
Business Process Outsourcing (BPO)
Global Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Data Entry Service Market
Business Process Outsourcing (BPO)
Legal Process Outsourcing (LPO) Market
Business Process Outsourcing (BPO)
Global IT Outsourcing Services Market
Business Process Outsourcing (BPO)
Public Cloud Business Process Services Market
Business Process Outsourcing (BPO)
North America Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Cloud Bpo Market
Business Process Outsourcing (BPO)
Customer Relationship Management (CRM) Outsourcing Market
Business Process Outsourcing (BPO)
Middle East and Africa Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Indonesia Business Process Outsourcing Services Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Technical Support Outsourcing Market