
 South Korea Data Center Server Market | 2026-2036
South Korea Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Data Center Server Market Insights
AI-optimized server architectures is rewriting procurement patterns across Korean data center operators. Samsung SDS leverages its semiconductor supply chain to anchor captive server production for enterprise workloads. Naver Cloud competes through domestic language-model training clusters positioned near Seoul. SK Telecom differentiates by integrating telecom edge infrastructure with low-latency server nodes for 5G services.
South Korea data center servers are enterprise-grade compute systems built on x86 and ARM architectures with power densities exceeding 30 kW per rack for AI training workloads, designed to host virtualization, storage, and networking functions for cloud and on-premises environments. Rack servers dominate volume shipments for hyperscale deployments, while hyper-converged infrastructure captures premium pricing from mid-market enterprises consolidating storage and compute. Blade servers retain share in financial services data centers where space constraints and thermal management priorities shape procurement.
MFDS cybersecurity frameworks for medical data hosting, KISA cloud security certification requirements, and Ministry of Environment carbon intensity standards for new data center construction collectively elevate compliance costs and technical specifications for server procurement. Kepco electricity pricing reforms and renewable energy quotas are reshaping total cost of ownership calculations for facility operators. Stakeholders must weigh domestic supply chain localization incentives against the capital efficiency of imported GPU server platforms.
Market Dynamics
Kepco electricity pricing reforms and renewable energy quotas are compressing total cost of ownership calculations for Korean data center operators, forcing server procurement decisions toward power-optimized architectures and captive renewable generation.
Growth Catalysts
- MFDS cybersecurity frameworks:Medical data hosting mandates from the Ministry of Food and Drug Safety are accelerating enterprise-grade server deployments in healthcare cloud infrastructure.
- Hyperscale expansion:Cloud service providers are building AI training clusters in Gyeonggi Province, pulling rack densities above 30 kW per rack.
- Carbon neutrality roadmap:The Korean government's digital infrastructure decarbonization targets are retrofitting existing facilities with liquid-cooled server architectures.
Market Restraints
- GPU supply concentration:AI training server builds depend on concentrated advanced semiconductor foundry capacity outside Korean borders, creating procurement bottlenecks.
- Kepco tariff volatility:Industrial electricity rate restructuring is inflating facility operating costs faster than server efficiency gains can offset.
- Land scarcity in Seoul metropolitan cluster:Pangyo Techno Valley corridor saturation is constraining greenfield data center expansion for hyperscale deployments.
Strategic Opportunities
- Busan-Ulsan corridor:Secondary metropolitan zones outside Seoul offer lower land costs and submarine cable landing proximity for export-oriented cloud infrastructure.
- KISA cloud security certification:Compliance premiums for certified server deployments create pricing power for domestic integrators meeting government procurement standards.
- 5G edge convergence:Telecom infrastructure densification is hybridizing central cloud and distributed server nodes for ultra-low latency workloads.
Industry Challenges
- Liquid cooling integration:Retrofitting legacy air-cooled facilities with direct-to-chip cooling requires structural reconfiguration and extended deployment timelines.
- AI infrastructure talent scarcity:Shortages of thermal engineers and GPU cluster architects are delaying hyperscale project commissioning in Gyeonggi Province.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Data Center Server Market |
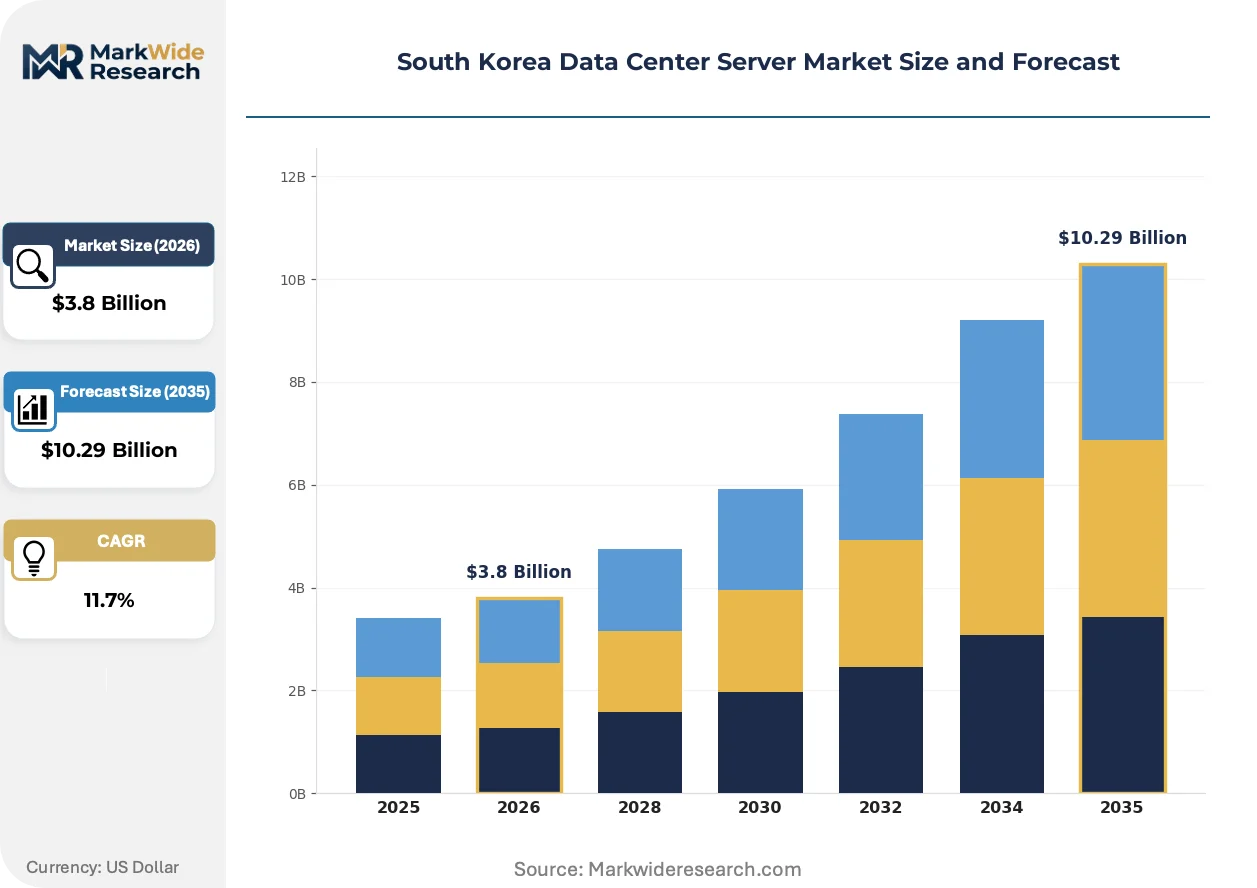
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Hyper-Converged Infrastructure Deployment Model: On-Premises, Colocation, Cloud, Hybrid End User: Telecommunication, BFSI, IT & Telecom, Government Service Type: Managed Services, Professional Services, Integration Services, Maintenance Services |
| Companies Covered | KT Corporation, Amazon Web Services, Naver (Naver Cloud), Google Cloud, Microsoft Azure, Samsung SDS, SK Telecom, Equinix, LG Uplus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Data Center Server Market Trends and Innovations
Server architecture decisions in Korean data centers are increasingly governed by thermal design power constraints rather than raw compute benchmarks, with procurement committees weighting energy efficiency certifications above legacy performance metrics.
Direct liquid cooling is hybridizing traditional air-cooled rack designs with cold plate and immersion variants for AI training workloads above 100 kW per rack. Domestic operators in Pangyo Techno Valley are piloting single-phase immersion for language model training clusters. This thermal architecture is compressing facility power usage effectiveness ratios toward government-mandated thresholds.
KISA cloud security certification requirements are mandating hardware-rooted trust modules and encrypted memory for government cloud procurement. Server vendors must pre-integrate trusted platform modules and secure boot architectures at manufacturing stage. Financial services data centers in Seoul are adopting these specifications ahead of formal deadlines to secure early-mover accreditation.
Enterprise buyers are consolidating server procurement through domestic systems integrators rather than direct OEM relationships, unbundling hardware purchase from managed services contracts. Mid-market manufacturers in Gyeonggi Province are capturing this channel shift through localized maintenance networks. This pattern is most visible in healthcare and public sector verticals where MFDS compliance documentation requirements favor integrated vendor accountability.
South Korea Data Center Server Market Segmentation
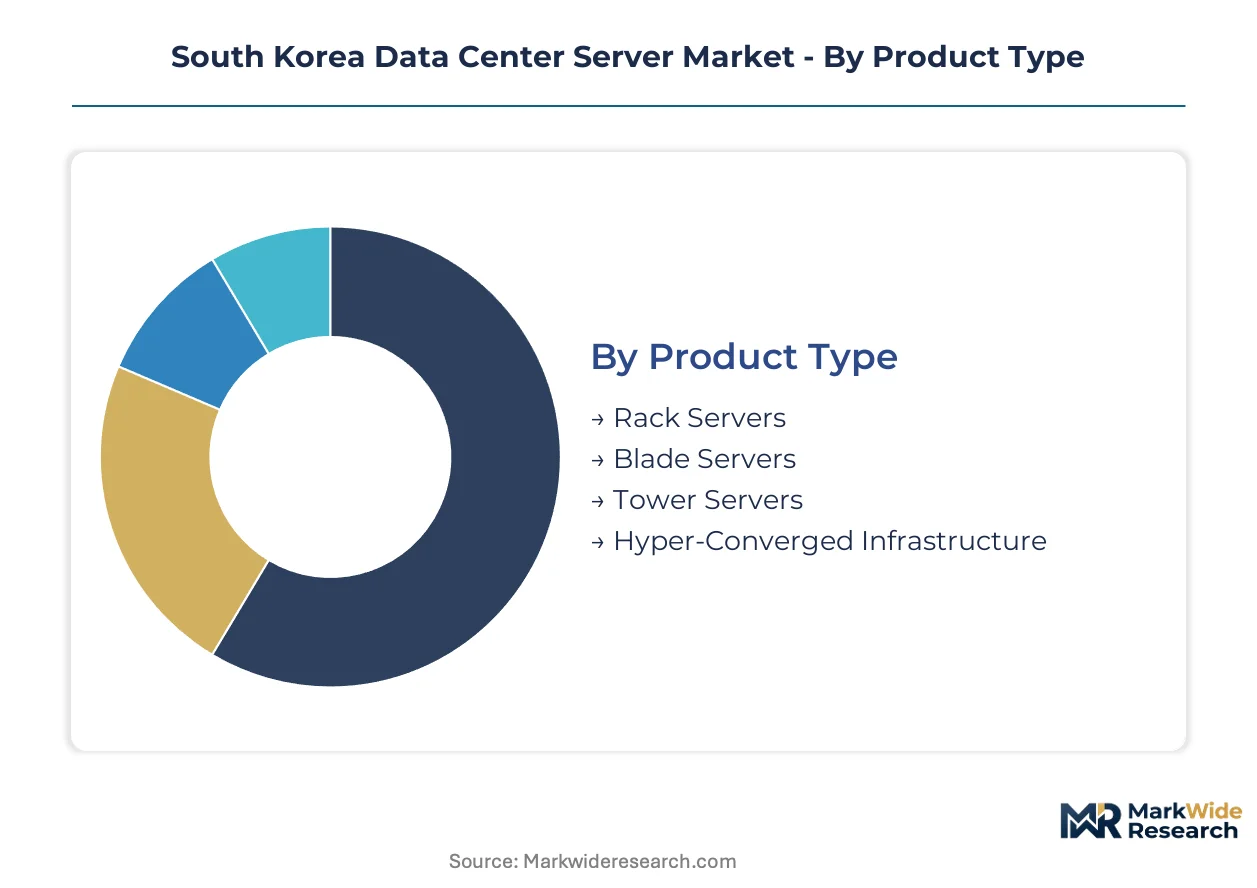
Server procurement patterns in South Korea diverge sharply across product architectures and deployment models, with hyperscale operators in Gyeonggi Province driving rapid refresh cycles while enterprise on-premises installations extend replacement timelines. Understanding these velocity differentials shapes inventory planning and margin capture strategies for domestic integrators.
Product Type:
Rack servers turn over fastest in hyperscale facilities where AI training clusters demand annual density upgrades, while tower servers persist longest in branch office deployments with minimal virtualization pressure.
- Rack Servers:Standardized 19-inch form factors support densities exceeding 30 kW per rack for AI workloads. Hyperscale facilities in Pangyo Techno Valley are pulling volume shipments for language model training clusters where thermal constraints dominate procurement specifications.
- Hyper-Converged Infrastructure:Integrated compute-storage-networking nodes command premium pricing from mid-market enterprises consolidating legacy silos. Healthcare providers under MFDS compliance mandates are adopting these systems to streamline medical data hosting documentation.
- Blade Servers:High-density chassis designs retain share in Seoul financial services data centers where floor space constraints and redundant cooling architectures shape vendor selection.
- Tower Servers:Standalone pedestal configurations serve small regional enterprises outside the metropolitan cluster with minimal virtualization requirements and extended depreciation schedules.
Rack servers dominate installed base. Hyper-converged infrastructure is where expansion concentrates.
Deployment Model:
Cloud deployments concentrate capital expenditure with hyperscale operators while hybrid architectures spread spending across internal infrastructure and external capacity.
- Cloud:Public cloud capacity absorbs the majority of AI training server demand through Gyeonggi Province hyperscale builds. Naver Cloud and domestic CSPs are expanding language model clusters with direct liquid cooling integration to meet government PUE mandates.
- Hybrid:Mixed on-premises and off-premises configurations capture enterprise demand for sensitive workload containment with burst capacity flexibility. Financial institutions in Seoul are adopting these architectures to satisfy KISA certification requirements while retaining core transaction processing internally.
- Colocation:Third-party facility leasing allows mid-market enterprises to access high-density power and cooling without facility construction. Busan-Ulsan corridor operators are targeting export-oriented firms with submarine cable proximity advantages.
- On-Premises:Captive data center ownership persists in defense and classified government applications where data sovereignty requirements preclude external hosting.
Cloud deployments absorb the majority of new server procurement. Hybrid architectures are climbing the fastest as enterprises balance compliance control with capital efficiency.
End User:
Telecommunication operators drive edge server deployment velocity while government procurement cycles extend through multi-year budget appropriations.
- Telecommunication:SK Telecom and domestic carriers are densifying 5G infrastructure with low-latency server nodes at cell tower aggregation points. Edge computing convergence with central cloud architectures is reshaping server form factor requirements.
- BFSI:Banking and insurance data centers in Seoul prioritize blade server deployments for core transaction processing with redundant power and cooling specifications. Early adoption of KISA-mandated hardware security modules is accelerating refresh timelines ahead of formal deadlines.
- IT & Telecom:Technology service providers span the full deployment spectrum from hyperscale cloud builds to enterprise managed services. Samsung SDS captive production serves internal workloads and external client infrastructure simultaneously.
- Government:Public sector procurement follows multi-year budget cycles with extended vendor qualification processes. KISA cloud security certification requirements are filtering supplier eligibility to domestic integrators with established compliance documentation.
Telecommunication verticals lead edge infrastructure expansion. Government procurement is where certification premiums concentrate.
Service Type:
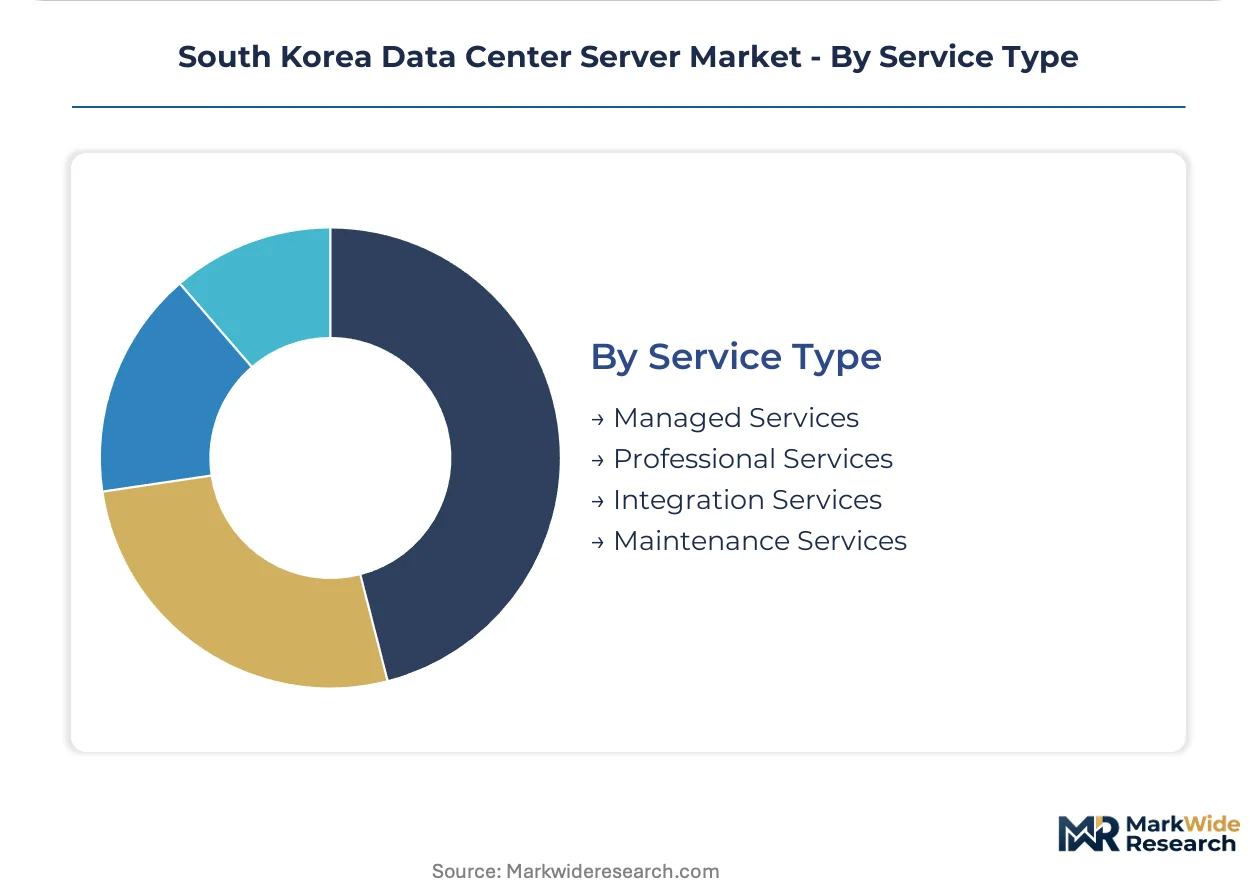
Managed services contracts extend customer relationships across server lifecycles while professional services revenue concentrates at initial deployment.
- Managed Services:Ongoing operational outsourcing captures recurring revenue from enterprises lacking internal AI infrastructure expertise. Healthcare providers under MFDS frameworks are outsourcing medical data hosting to certified domestic operators.
- Integration Services:System deployment and workload migration command project-based fees during facility commissioning. Gyeonggi Province hyperscale builds are pulling thermal engineering and GPU cluster architecture specialists.
- Professional Services:Consulting and design engagements precede major procurement decisions. Mid-market manufacturers are bundling these services with hardware sales to differentiate against direct OEM channels.
- Maintenance Services:Post-warranty support and spare parts logistics extend hardware economic life. Regional service networks in secondary metropolitan zones are capturing business from Seoul-saturated primary markets.
Managed services dominate recurring revenue. Integration services are where talent scarcity creates pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
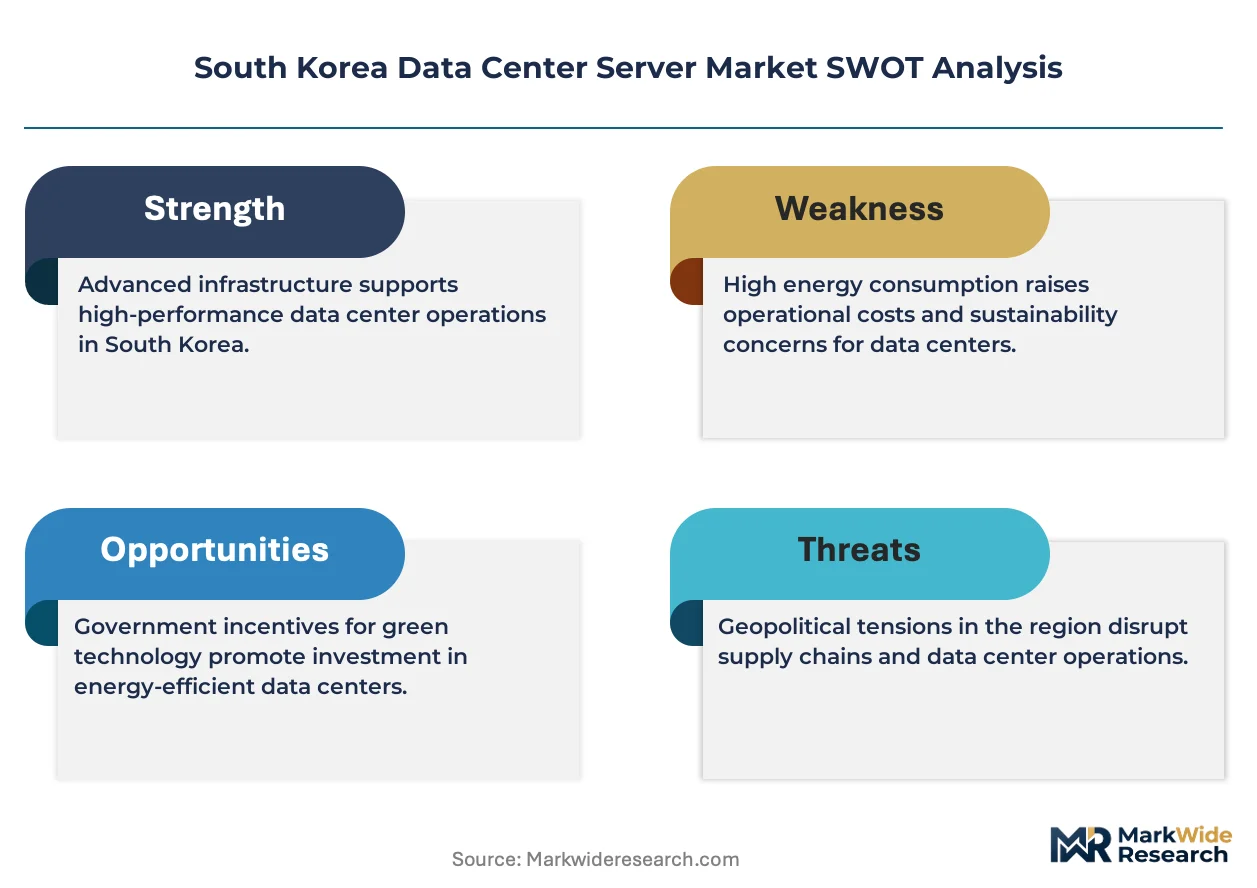
South Korea's data center server market operates as a net importer of advanced GPU accelerators and high-density server components, with domestic production concentrated in captive supply chains for enterprise workloads while hyperscale AI training clusters rely on foreign semiconductor foundry capacity.
Seoul Capital Area
Gyeonggi Province hosts the densest concentration of hyperscale facilities, with cloud service providers expanding AI training clusters requiring liquid-cooled architectures above 30 kW per rack. MFDS cybersecurity frameworks for medical data hosting are accelerating enterprise-grade server deployments in Pangyo Techno Valley. The corridor faces land scarcity constraints that are compressing greenfield expansion timelines and elevating facility construction costs.
Busan-Ulsan Corridor
Secondary metropolitan zones outside Seoul offer lower land acquisition costs and submarine cable landing proximity for export-oriented cloud infrastructure. Kepco electricity pricing reforms are less severe in this region, improving total cost of ownership calculations for facility operators. Regional colocation providers are targeting maritime logistics firms and gaming content exporters with latency-optimized server nodes.
Daegu-Gyeongbuk
Industrial automation and smart manufacturing clusters are pulling edge server deployments for factory-floor data processing. The central government's carbon neutrality roadmap for digital infrastructure is mandating renewable energy quotas that reshape procurement specifications for new construction. Local integrators are capturing mid-market enterprise demand through bundled hardware and managed services contracts.
Daejeon-Sejong
Government research institutions and public sector data centers concentrate in this administrative hub, with multi-year budget appropriations extending procurement cycles. KISA cloud security certification requirements are filtering supplier eligibility to domestic integrators with established compliance documentation. Defense and classified applications retain captive on-premises server ownership due to data sovereignty mandates.
Gwangju-Honam
Regional enterprise demand concentrates in agricultural technology and food processing automation requiring localized data processing. Kepco tariff volatility affects smaller operators disproportionately, forcing procurement decisions toward power-optimized server architectures. Mid-market manufacturers are establishing service networks to capture maintenance revenue from Seoul-saturated primary markets.
South Korea Data Center Server Market Competitive Landscape
On the supply side, the industry is bifurcated between hyperscale cloud service providers with captive infrastructure investments and domestic systems integrators serving regulated enterprise verticals. The vendor base stratifies across three tiers: global cloud platforms with local region deployments, Korean conglomerate-affiliated IT service providers with captive server production, and specialized colocation operators with geographic differentiation strategies. Competitive moves center on liquid cooling technology partnerships for AI density compliance and domestic supply chain localization incentives versus imported GPU platform capital efficiency.
Among Korea-based service providers, Samsung SDS anchors the captive production archetype through semiconductor supply chain integration, while KT Corporation and SK Telecom occupy positions bridging telecom edge infrastructure with central cloud capacity. Naver Cloud exemplifies the domestic language model specialization vector, competing through training cluster proximity to Seoul metropolitan demand. These three entities represent distinct responses to KISA certification requirements and MFDS compliance frameworks that elevate barriers for foreign platform competitors in regulated verticals.
| Leading Market Players |
|---|
| KT Corporation |
| Amazon Web Services |
| Naver (Naver Cloud) |
| Google Cloud |
| Microsoft Azure |
| Samsung SDS |
| SK Telecom |
| Equinix |
| LG Uplus |
| Others |
Pricing and Supply Chain Analysis
Gyeonggi Province hyperscale buildouts concentrate procurement volume for AI-optimized server platforms, compressing pricing power for domestic integrators unable to match direct OEM relationships with cloud service providers. Kepco electricity tariff restructuring feeds back into total cost of ownership calculations, elevating power-optimized architectures above raw compute benchmarks in procurement committees.
Pricing Analysis
Current-generation GPU server platforms command substantial premiums over prior-generation CPU-centric designs, while next-generation liquid-cooled architectures are pre-pricing at certification-tier levels. Three-tier pricing structure across KISA-certified, enterprise-grade, and standard configurations separates government procurement from healthcare and mid-market verticals. Cost compression in the standard tier is intensifying because hyperscale operators are consolidating direct OEM relationships. Mid-market enterprises exhibit highest price sensitivity, while MFDS-compliant healthcare deployments show lowest sensitivity due to bundled compliance documentation requirements.
Supply Chain Analysis
Export control regimes on advanced semiconductor manufacturing equipment constrain GPU accelerator flows from Taiwan and USA into Korean hyperscale facilities. Domestic supply chains draw from captive Samsung foundry capacity for memory components and enterprise-grade processors, but AI training clusters rest on NVIDIA and AMD silicon sourced through concentrated distribution channels. Single-source vulnerability in advanced packaging capacity creates procurement bottlenecks for 30 kW-plus rack densities. Distribution runs through domestic systems integrators with KISA certification credentials, unbundling hardware from managed services contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment through KISA certification and MFDS compliance documentation creates switching costs that foreign platform competitors struggle to replicate.
For Market Incumbents: Harden market position by deepening captive semiconductor supply chain integration for enterprise-grade server production, insulating against GPU supply concentration risks. Expand liquid cooling technology partnerships in Pangyo Techno Valley to anchor AI training cluster deployments. Secure channel control through localized maintenance networks in Busan-Ulsan corridor secondary markets. For New Entrants and Emerging Players: Geographic underpenetration in Daegu-Gyeongbuk industrial automation clusters offers white-space targets for edge server deployments with bundled managed services. KISA certification investment unlocks government procurement verticals where compliance documentation barriers filter foreign competition. Target mid-market healthcare providers under MFDS frameworks with integrated hardware and outsourcing contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic systems integrators with established KISA certification pathways and regional service networks. Long-term viability hinges on liquid cooling deployment capabilities and AI infrastructure talent acquisition. Thermal engineering capability scarcity in Gyeonggi Province represents the signal to watch as inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Technology Partnership | Direct-to-chip and immersion architectures satisfy government PUE mandates for AI training clusters. |
| KISA Cloud Security Certification Investment | Hardware-rooted trust modules unlock government and healthcare procurement verticals with compliance premiums. |
| Captive Semiconductor Supply Chain Expansion | Backward integration into memory and processor production reduces dependency on foreign foundry capacity. |
| Regional Service Network Buildout | Busan-Ulsan corridor maintenance capabilities capture mid-market enterprises fleeing Seoul land scarcity. |
| AI Infrastructure Talent Acquisition | Thermal engineering and GPU cluster architecture specialists accelerate hyperscale project commissioning timelines. |
Research Methodology
A spread of perspectives from data center facility operators, server procurement officers at hyperscale cloud providers, thermal engineering specialists, KISA certification auditors, and MFDS compliance consultants converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against hyperscaler capex disclosures, KISA certification registries, Kepco tariff filings, and MFDS regulatory guidance documents. Bottom-up server shipment estimates triangulated against top-down facility construction permits across the analysis window.
Demand-supply balance modeling anchored volume projections, with segmentation across product architecture, deployment model, end-user vertical, and service type. CAGRs were derived from fitted growth curves calibrated to facility commissioning timelines and technology refresh cycles. Industry-specific forecast inputs included Kepco electricity pricing reform schedules, renewable energy quota implementation trajectories, and GPU supply availability through restricted technology channels.
Practitioners should monitor export control regime adjustments, Kepco tariff restructuring announcements, and KISA certification requirement updates for early signals of forecast deviation. Forecasts reflect assumptions about hyperscale expansion timelines, liquid cooling adoption curves, and domestic talent pipeline development. Material shifts in semiconductor supply chain access or government carbon neutrality enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Brazil Data Center Networking Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
Singapore Data Center Networking Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
Global Network Configuration and Change Management Market
Data Center and Networking
Application Delivery Network (ADN) Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Cache Server Market
Data Center and Networking
North America Data Center Networking Market
Data Center and Networking
United States Data Center Networking Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Nosql Market
Data Center and Networking
Germany Data Center Networking Market
Data Center and Networking
Enterprise Server Market