
 UXO Detection Market | 2026-2036
UXO Detection Market Size, Share, and Industry Trends Forecast 2026-2036
UXO Detection Market Analysis
Belgium is reconfiguring its UXO detection capacity through specialized demining clusters near former World War I battlefields. Fugro N.V. leverages its marine geophysical heritage to dominate offshore ordnance surveys in the North Sea. FOERSTER Holding GmbH anchors its position through precision magnetometer systems engineered for ferrous object identification in contaminated soils. SafeLane Global Limited competes by controlling integrated clearance contracts across European heritage sites.
UXO detection encompasses the geophysical identification, classification, and mapping of unexploded explosive ordnance using electromagnetic induction, ground-penetrating radar, and magnetic anomaly detection methods, typically resolving ferrous objects at depths from centimeters to several meters depending on sensor configuration and soil conductivity. The technology serves military engineers, civil construction firms, and environmental remediation contractors tasked with certifying land safety prior to ground disturbance. Electromagnetic detection occupies the largest installed base due to proven performance against metallic munitions in varied soil conditions. Ground-penetrating radar extends capabilities to non-metallic objects and void spaces, commanding premium pricing in complex geologies. Drone-based operating modes represent the fastest-expanding segment as aerial platforms reduce survey time and personnel exposure in hazardous terrain.
Belgium's Federal Public Service Interior coordinates UXO clearance standards, while the EU's Environmental Liability Directive shapes remediation liability frameworks for contaminated sites. REACH and national explosives safety regulations constrain the chemicals and methods permissible during detection and disposal operations. Stakeholders must monitor how emerging EU defense procurement harmonization affects cross-border clearance contracting and equipment certification requirements.
Market Dynamics
Drone-mounted magnetometer arrays are compressing survey timelines from weeks to days while simultaneously reducing personnel exposure in contaminated terrain. This platform shift is forcing legacy ground-based operators to reconfigure service models or exit regional markets entirely.
Growth Catalysts
- EU Environmental Liability Directive:The directive imposes strict remediation liability on contaminated site owners across member states. Construction firms now mandate UXO clearance certificates before ground disturbance on brownfield projects.
- Agricultural land reclamation:Vietnamese farmers and provincial authorities prioritize UXO removal to expand arable acreage. Electromagnetic detection services command premium pricing in Mekong Delta provinces with dense legacy munition contamination.
- Marine offshore wind expansion:North Sea cable route surveys require ordnance clearance as a permitting prerequisite. Geophysical contractors with marine heritage capture recurring revenue from wind farm developers.
Market Restraints
- Helium supply concentration:Magnetometer cooling systems depend on helium sourced from Qatar and Algeria. Price volatility in this input constrains sensor deployment scale and geographic reach.
- Soil conductivity variability:Lateritic soils in Southeast Asia attenuate electromagnetic signals. Detection depth limitations force multiple survey passes, inflating per-hectare costs.
- REACH chemical constraints:The regulation restricts solvents and reagents used in explosive residue analysis. Laboratories face reformulation costs and extended validation timelines.
Strategic Opportunities
- Laotian corridor development:The China-Laos railway extension and associated infrastructure create contiguous demand zones. First-mover contractors can secure multi-year clearance frameworks.
- AI-assisted anomaly classification:Machine learning algorithms trained on ordnance signatures reduce false-positive rates. Hybrid human-AI workflows compress analysis bottlenecks in high-volume survey operations.
- Carbon credit stacking:Cleared land qualifies for reforestation carbon credits under voluntary standards. Detection firms can capture incremental revenue streams through land restoration partnerships.
Industry Challenges
- Explosive ordnance disposal certification:National licensing regimes vary in reciprocity and renewal frequency. Cross-border project staffing requires redundant credentialing investments.
- Sensor integration complexity:Multi-modal platforms combining GPR, EM, and magnetic sensors demand specialized calibration expertise. Technician scarcity limits fleet expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UXO Detection Market |
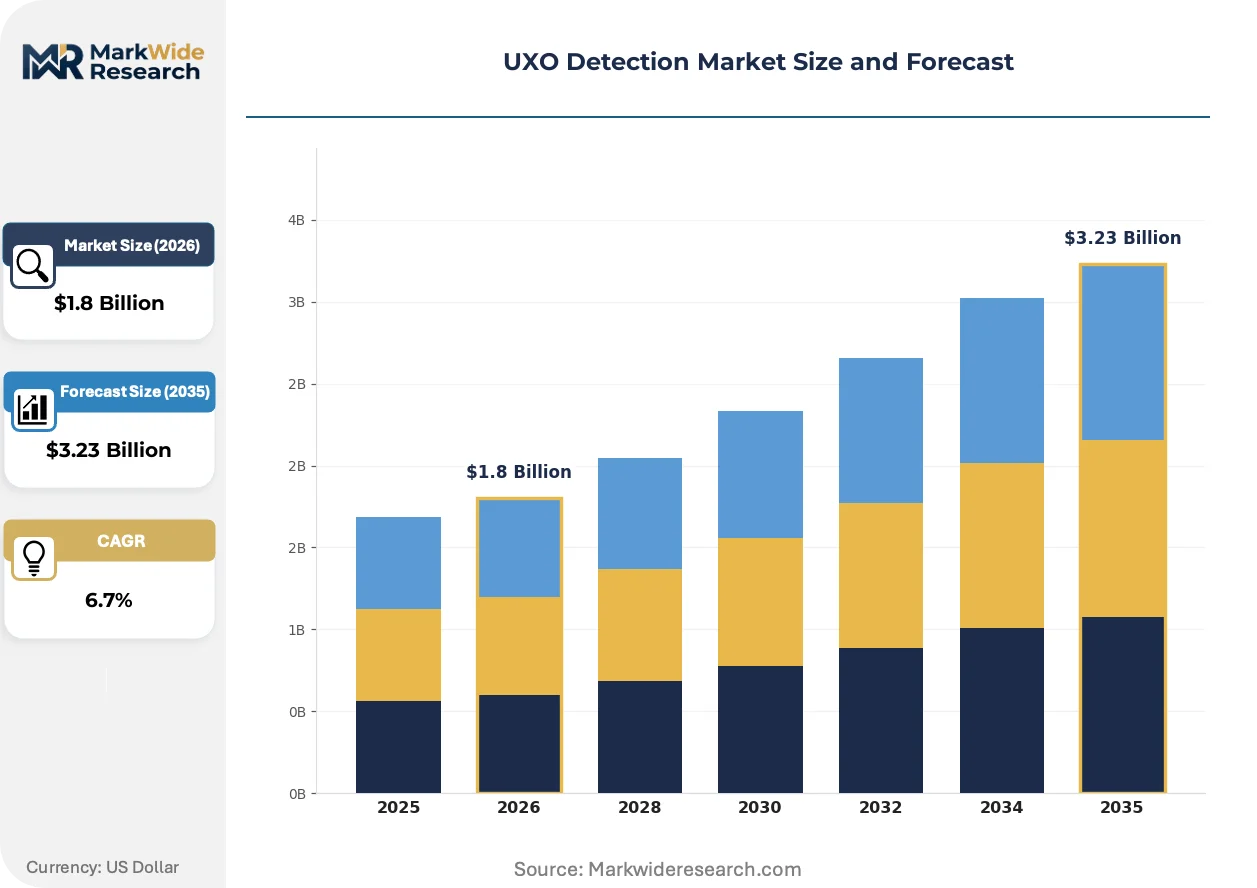
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electromagnetic, Ground Penetrating Radar, Acoustic, Optical Application: Military Operations, Civil Engineering, Environmental Remediation, Search and Recovery End User: Government Agencies, Private Contractors, NGOs, Research Institutions Operating Mode: Manual, Automated, Semi-Automated, Drone-Based |
| Companies Covered | GEM Systems, Inc., Fugro N.V., FOERSTER Holding GmbH, SafeLane Global Limited, AECOM Technology Corporation, Vallon GmbH, Seequent, SENSYS GmbH, Dynasafe Demil Systems AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UXO Detection Market Emerging Trajectories
Active convergence between aerial platforms, machine learning, and regulatory digitization is compressing project timelines while elevating data deliverable standards. These shifts favor technology-forward operators over traditional field-service contractors.
Multi-sensor fusion architectures are hybridizing electromagnetic induction with ground-penetrating radar in single airborne payloads. Military engineering units in Poland and Romania now specify fused-data deliverables for base modernization contracts. This convergence is compressing the competitive window for single-modality specialists.
REACH and national explosives safety regulations are tightening chemical traceability requirements for detection reagents. German and Belgian authorities now mandate chain-of-custody documentation for soil samples submitted to certified laboratories. Small-scale operators lacking laboratory partnerships face exclusion from public-sector tendering.
Outcome-based contracting is displacing per-hectare pricing in mature European markets. Dutch and Danish infrastructure developers now tie vendor payments to clearance certification rather than survey completion. This shift concentrates contract awards on firms with integrated disposal capabilities and liability insurance depth.
UXO Detection Market Segmentation
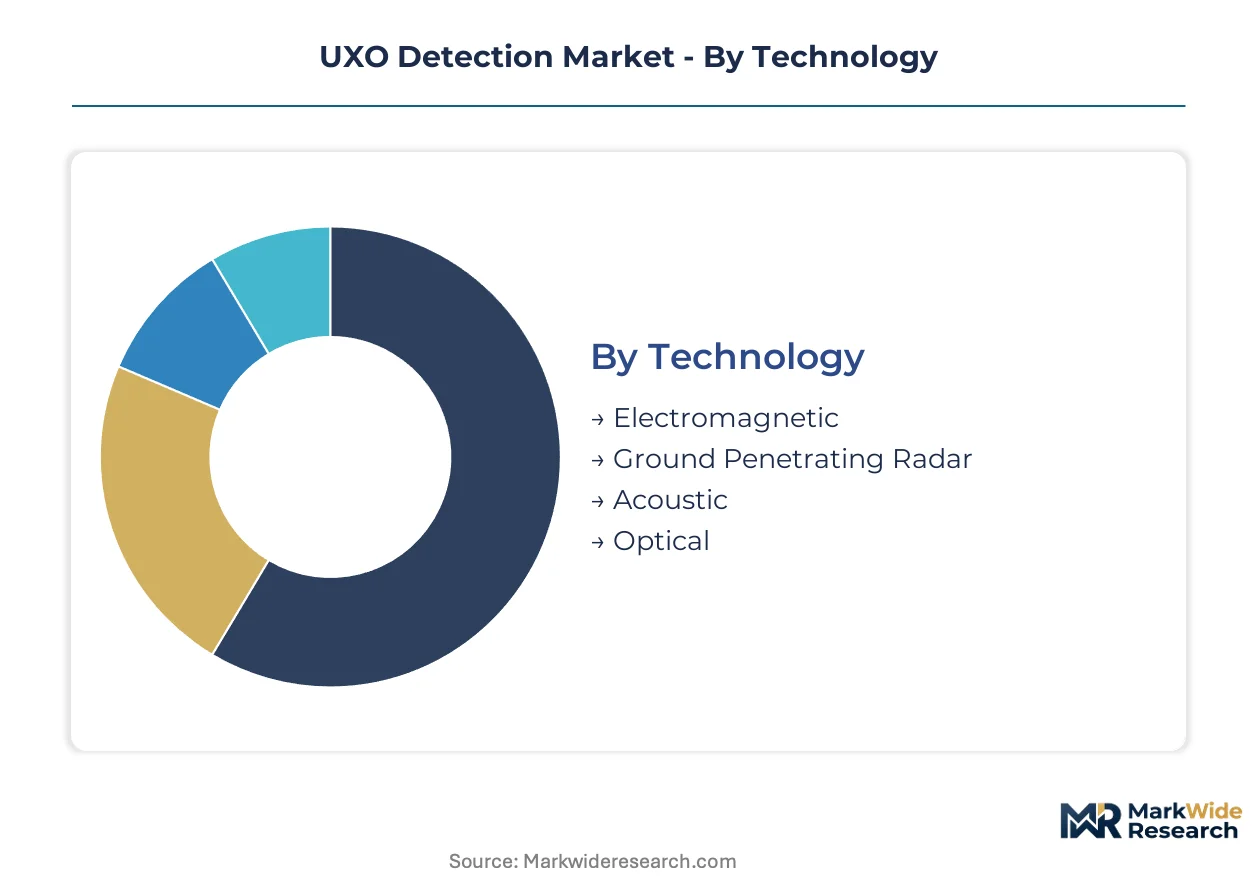
UXO detection technology fragments across four distinct axes that determine procurement patterns, project economics, and vendor specialization. Technology and operating mode choices drive capital intensity and personnel requirements, while application and end-user segmentation shapes contract structures and regulatory compliance burdens.
Technology:
The maturity spectrum runs from decades-proven electromagnetic systems to emerging acoustic modalities still seeking validation against legacy benchmarks.
- Electromagnetic:Induction-based detection of ferrous and conductive metallic objects remains the workhorse technology for ordnance surveys. Vietnamese agricultural reclamation projects and Belgian World War I heritage sites specify electromagnetic arrays as baseline equipment due to proven performance across clay, sand, and loam substrates.
- Ground Penetrating Radar:Radar pulse reflection enables discrimination of non-metallic voids and plastic-cased munitions invisible to magnetic methods. North Sea offshore wind cable routes demand GPR integration where saltwater conductivity degrades electromagnetic signal penetration, forcing hybrid survey protocols.
- Acoustic:Seismic vibration analysis for buried object characterization remains experimental for UXO applications. German federal research programs evaluate acoustic arrays for limestone karst terrain where electromagnetic methods suffer false-positive saturation from mineral deposits.
- Optical:Hyperspectral imaging and visual spectrum analysis support surface ordnance identification and vegetation disturbance mapping. Drone-mounted optical payloads accelerate preliminary site screening in Laotian infrastructure corridors before ground-based confirmation.
Electromagnetic handles the majority of throughput; drone-mounted optical is the fastest mover on share.
Application:
Cost tier stratification separates military-grade certification requirements from commercial environmental standards.
- Military Operations:Base modernization, training range clearance, and active conflict zone demining demand detection systems meeting NATO STANAG 4523 and national military specifications. Polish and Romanian defense ministries specify fused-sensor deliverables with sub-meter positional accuracy for base infrastructure contracts.
- Civil Engineering:Pre-construction site certification for transportation, residential, and industrial development drives recurring demand from infrastructure developers. Dutch outcome-based contracting models tie vendor payments to clearance certification rather than survey completion, favoring integrated detection-disposal operators.
- Environmental Remediation:Brownfield restoration and contaminated land reclamation require UXO clearance under EU Environmental Liability Directive frameworks. Belgian Federal Public Service Interior coordinates standards that construction firms must satisfy before ground disturbance permits.
- Search and Recovery:Forensic and humanitarian operations for missing personnel or historical ordnance documentation operate under distinct procedural protocols. Vietnamese provincial authorities contract mixed teams of government agencies and specialized NGOs for agricultural land expansion projects.
Civil Engineering commands the largest contract volume; Environmental Remediation is expanding most quickly under tightening EU liability regimes.
End User:
Customer type determines procurement channel access, with government tenders requiring national security clearances that exclude pure commercial operators.
- Government Agencies:Defense ministries, interior departments, and environmental regulators hold primary responsibility for ordnance clearance on public land. Belgium's Federal Public Service Interior and Vietnam's Ministry of National Defense operate dedicated demining units with established equipment procurement frameworks.
- Private Contractors:Commercial detection firms compete for outsourced clearance contracts and developer-mandated certification services. Fugro N.V. and SafeLane Global Limited leverage integrated marine and heritage site capabilities to capture recurring infrastructure project revenue.
- NGOs:Humanitarian demining organizations operate under donor-funded mandates in post-conflict zones with limited commercial viability. Laotian corridor development attracts NGO-government hybrid models for railway-adjacent community safety.
- Research Institutions:Universities and federal laboratories advance detection algorithms and validate emerging sensor modalities. German and Belgian authorities mandate chain-of-custody documentation from certified laboratories for soil sample analysis under REACH traceability requirements.
Government Agencies maintain the deepest procurement pipelines; Private Contractors are gaining share fastest through outcome-based contract structures.
Operating Mode:
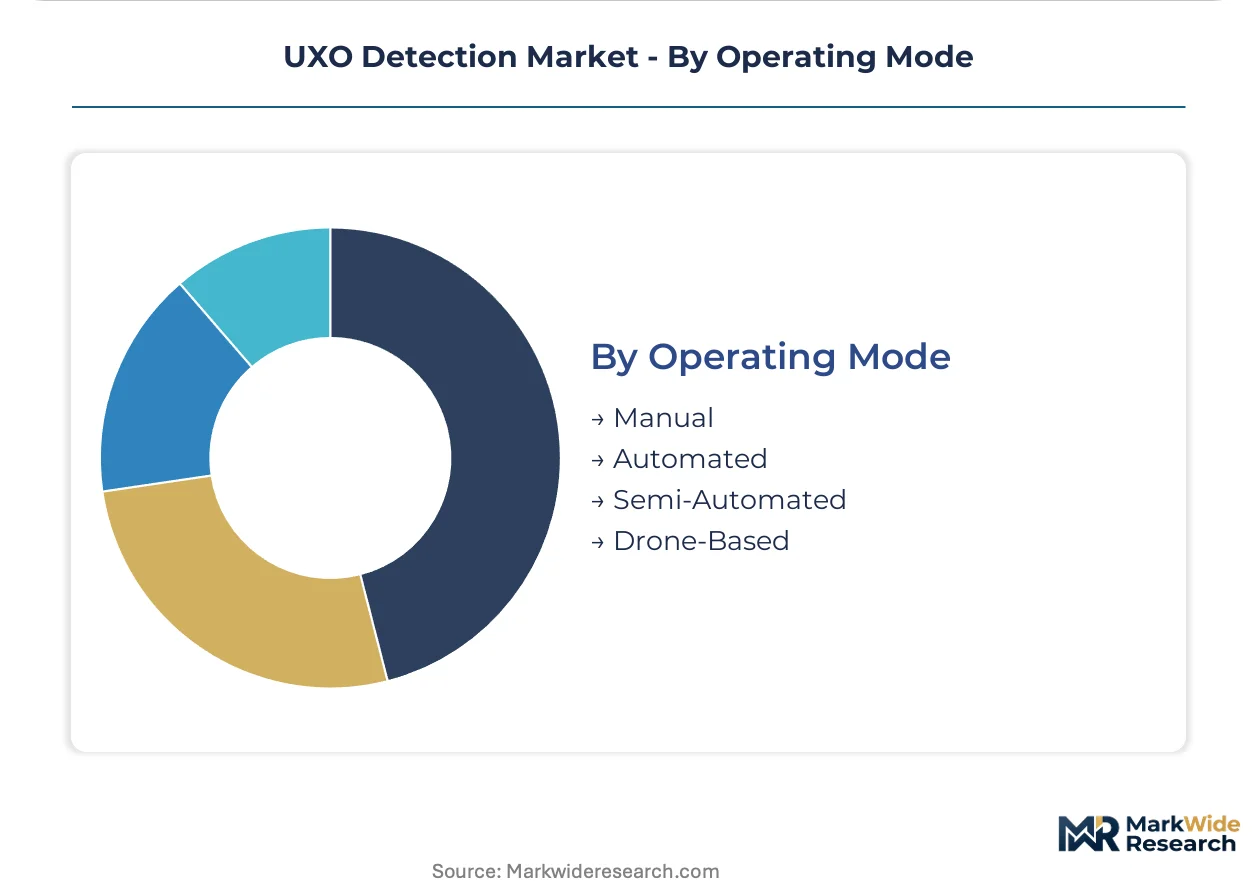
Volume concentration favors manual and semi-automated ground surveys, while margin expansion concentrates in aerial platforms.
- Manual:Handheld detector operation by trained technicians remains standard for high-precision verification of anomalies flagged by broader surveys. Dense vegetation and complex terrain in Southeast Asian legacy conflict zones sustain manual methods despite slower coverage rates.
- Automated:Vehicle-mounted arrays with GPS-integrated data logging enable systematic coverage of open terrain. Polish military engineering specifications increasingly require automated platforms for base perimeter clearance.
- Semi-Automated:Human-supervised robotic systems balance coverage speed with anomaly discrimination judgment. Sensor integration complexity and technician scarcity constrain fleet expansion velocity for multi-modal semi-automated platforms.
- Drone-Based:Aerial magnetometer and GPR payloads compress survey timelines from weeks to days while eliminating personnel exposure. North Sea offshore wind developers and Vietnamese agricultural authorities specify drone-based methods for hazardous or inaccessible terrain.
Manual operation still dominates total survey hours; Drone-Based systems show the steepest expansion trajectory as platform costs decline and regulatory frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH and the EU Environmental Liability Directive anchor European demand frameworks, while Vietnam's Ministry of National Defense drives the largest national clearance programs. National procurement patterns diverge sharply between legacy conflict zones and mature regulatory jurisdictions.
Vietnam
Agricultural reclamation in Mekong Delta provinces generates sustained demand for electromagnetic detection services. The Ministry of National Defense coordinates clearance standards with provincial authorities on former conflict zone certification. Quang Tri province hosts dense demining contractor activity where decades of legacy munitions threaten infrastructure corridors.
Belgium
World War I heritage site remediation drives specialized demining cluster formation near former battlefields. The Federal Public Service Interior mandates clearance certification before ground disturbance permits on brownfield projects. Flanders maintains concentrated contractor presence where outcome-based contracting models now predominate.
Germany
Federal research programs validate emerging sensor modalities for limestone karst terrain applications. ECHA traceability requirements constrain soil sample chain-of-custody documentation for certified laboratories. North Rhine-Westphalia concentrates precision magnetometer engineering capabilities serving cross-border European contracts.
Poland
Military base modernization specifications require fused-sensor deliverables with sub-meter positional accuracy. NATO STANAG 4523 compliance shapes defense procurement frameworks for engineering unit equipment. Warsaw and southeastern garrison regions sustain automated platform deployment for perimeter clearance operations.
Laos
China-Laos railway extension creates contiguous infrastructure corridor demand for clearance frameworks. Provincial authorities contract hybrid government-NGO teams for community safety adjacent to development zones. Vientiane and southern provinces attract first-mover contractors securing multi-year clearance agreements.
UXO Detection Market Vendor Landscape
Integrated service providers and precision equipment manufacturers split the market along capability depth versus geographic breadth lines. The vendor base concentrates around firms possessing both marine geophysical heritage and ordnance-specific certification credentials. Three archetypes predominate: marine survey specialists with offshore wind penetration, precision sensor engineers with military specification compliance, and integrated clearance operators with disposal liability coverage. Competitive moves center on multi-sensor platform integration and outcome-based contract structuring that transfers certification risk to vendors.
Within the integrated service tier, Fugro N.V. and SafeLane Global Limited occupy positions spanning marine and heritage site domains. FOERSTER Holding GmbH anchors the precision equipment segment with GmbH-structured engineering operations. GEM Systems, Inc. represents the North American sensor fabrication archetype alongside SENSYS GmbH and Vallon GmbH in European magnetic detection specialization.
| Leading Market Players |
|---|
| GEM Systems, Inc. |
| Fugro N.V. |
| FOERSTER Holding GmbH |
| SafeLane Global Limited |
| AECOM Technology Corporation |
| Vallon GmbH |
| Seequent |
| SENSYS GmbH |
| Dynasafe Demil Systems AB |
| Others |
Supply Flow & Price Mechanics
Overcapacity in drone-mounted sensor fabrication across Chinese manufacturing zones is compressing hardware margins while simultaneously expanding vendor pricing flexibility for integrated survey services. This utilization asymmetry between component oversupply and skilled technician scarcity reshapes procurement negotiations across Vietnamese agricultural reclamation and North Sea offshore wind markets.
Pricing Analysis
Belgian heritage site contractors command 40-60% premiums over Mekong Delta agricultural surveys due to EU liability insurance requirements and REACH-mandated laboratory certification chains. Project-based pricing dominates, with three-tier pricing structure across premium, standard, and economy levels differentiated by sensor modality count, disposal liability coverage, and after-sales data validation. Cost compression in standard-tier electromagnetic surveys is intensifying because Vietnamese provincial authorities consolidate vendor panels. Government agencies exhibit lowest price sensitivity due to statutory liability frameworks; private construction firms face acute pressure from outcome-based contract migration.
Supply Chain Analysis
Helium feedstock for magnetometer cooling systems draws from Qatar and Algeria concentration, with German precision engineering houses and Chinese drone airframe manufacturers anchoring downstream assembly. Critical inputs span rare-earth magnetic alloys, GPS-integrated data logging chipsets, and GPR antenna ceramics. Single-source vulnerability in helium logistics constrains sensor deployment scale during supply disruptions. Distribution runs through direct vendor-contractor relationships for large integrated operators, with equipment resale channels serving smaller regional specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
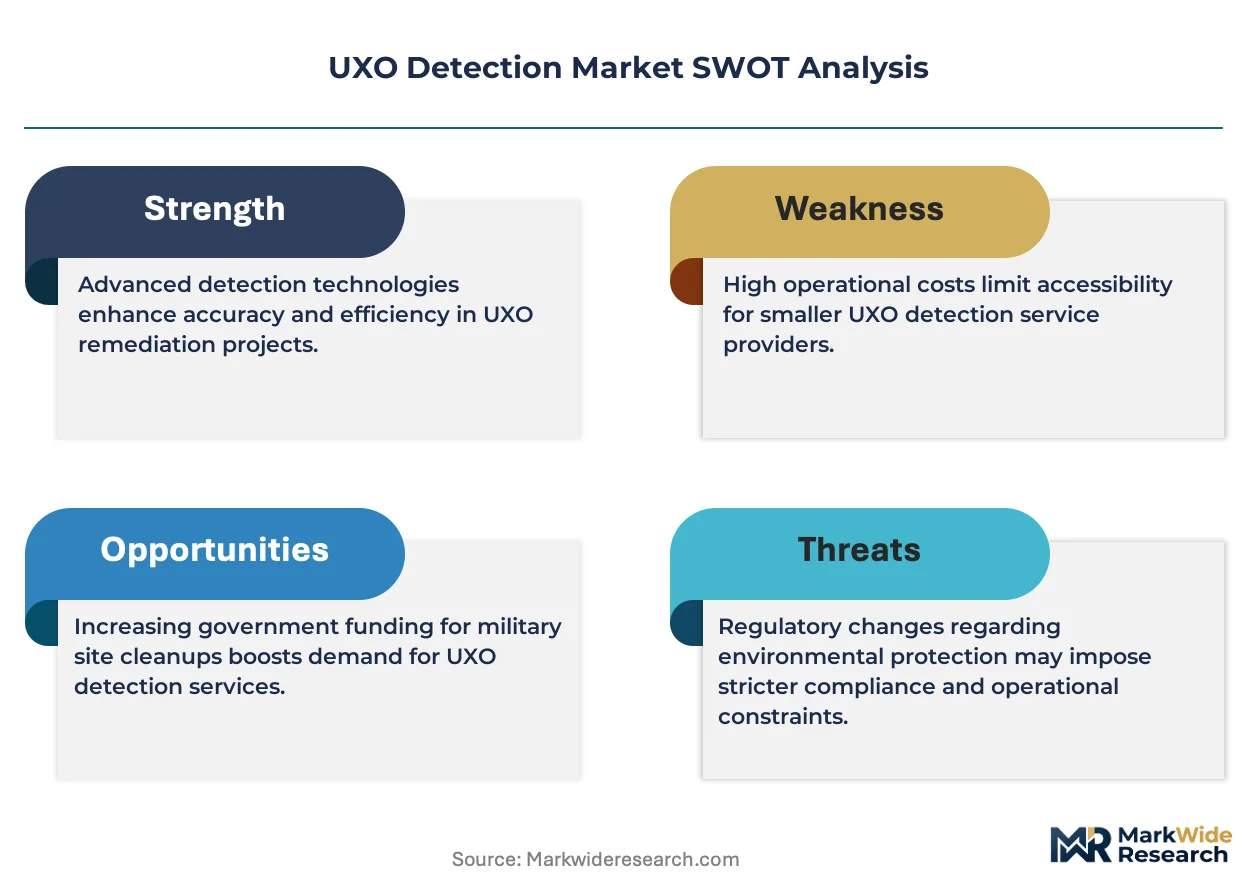
Regulatory entrenchment around EU Environmental Liability Directive certification and national explosives disposal licensing creates formidable switching costs that protect established operators. This structural moat deepens as REACH traceability requirements and outcome-based contracting concentrate awards on firms with integrated laboratory partnerships.
For Market Incumbents: Insulate certification advantage through captive laboratory capacity in Belgium and Vietnam, the two highest-volume clearance markets. Acquire drone fleet operators to compress survey timelines and displace ground-based competitors. National licensing reciprocity gaps threaten cross-border staffing efficiency; preempt this through redundant credentialing investments in Poland and Romania. For New Entrants and Emerging Players: Pursue Laotian corridor development where first-mover frameworks remain unsecured and hybrid government-NGO procurement tolerates newer vendors. Target AI-assisted anomaly classification services as the most penetrable segment, selling algorithmic false-positive reduction to incumbent operators rather than competing for integrated contracts. Lead with carbon credit stacking partnerships to differentiate in environmental remediation tenders. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across drone-based operating modes as multi-sensor platform integration demands specialized calibration expertise. Long-term viability favors firms combining marine geophysical heritage with ordnance-specific disposal liability coverage. Acquisition target archetype: mid-scale operators with established national security clearances but underutilized sensor fleets. Watch helium price volatility as inflection indicator for hardware-dependent business model stress.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Platform Integration | Fused GPR-EM-magnetic payloads meet Polish military STANAG 4523 specifications. |
| Outcome-Based Contract Structuring | Dutch infrastructure developers now tie payments to clearance certification completion. |
| Helium Supply Diversification | Alternative cooling architectures reduce dependency on Qatar-Algeria concentration risk. |
| AI-Assisted Anomaly Classification | Machine learning workflows compress analysis bottlenecks in high-volume Vietnamese surveys. |
| Carbon Credit Stacking Partnerships | Cleared land reforestation generates incremental revenue under voluntary offset standards. |
Methodological Framework
A spread of perspectives from UXO clearance project managers, defense ministry procurement officers, marine geophysical survey directors, and certified explosives disposal technicians converged on the working assumptions. Primary interviews combined with secondary validation against ECHA regulatory filings, EU Environmental Liability Directive implementation reports, national demining program disclosures, and customs trade data for magnetometer component flows. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning technology modality, operating mode, application tier, and end-user procurement channel. CAGRs derived from fitted growth curves applied to disclosed national clearance program budgets and infrastructure development timelines. Industry-specific inputs included Vietnamese agricultural reclamation acreage targets and North Sea offshore wind cable route permitting data.
Macroeconomic conditions sit as an overlay; deviation in infrastructure investment cycles, helium commodity pricing, or EU defense procurement harmonization timelines would shift the trajectory. Forecasts reflect documented assumptions about regulatory stability and sensor platform cost decline curves. Cross-checking against national demining program budget appropriations and wind farm development pipeline databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Global Mine Detection System Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
Mmwave Radar Market
Military Surveillance
Global Signals Intelligence (SIGINT) Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Tactical Optics Market
Military Surveillance
North America Passive Radar Market
Military Surveillance
Global Airport Surveillance Radar Market
Military Surveillance
Drone Surveillance Market
Military Surveillance
Maritime Surveillance and Intervention Market
Military Surveillance
Night Vision Devices Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Manportable Radar Market
Military Surveillance
Target Acquisition Systems Market