
 Military Jammer Market | 2026-2036
Military Jammer Market Size, Share, and Industry Trends Forecast 2026-2036
Military Jammer Market Outlook
Defense procurement offices are collapsing traditional distinctions between electronic attack and electronic protection missions, forcing integrators to design modular architectures that reconfigure across threat spectra. RTX Corporation leverages its GaN foundry investments to sustain dominance in high-power airborne jamming transmitters. L3Harris Technologies anchors naval electronic warfare portfolios with shipborne countermeasure suites that integrate across Aegis combat systems. Northrop Grumman Corporation differentiates through digital radio frequency memory architectures that enable precise threat replication in training and operational environments.
A military jammer is an electronic warfare device that emits radio frequency energy to disrupt, deny, or deceive adversary radar, communications, navigation, or command-and-control systems, typically operating across frequency ranges from VHF through Ku-band with effective radiated power measured in kilowatts. These systems serve primarily to establish electromagnetic spectrum superiority by degrading enemy situational awareness and weapon guidance while protecting friendly force maneuver. Countermeasure jammers and radar jammers capture the largest installed base as legacy platforms undergo mid-life upgrades, yet communication jammers and GPS jammers represent the fastest-expanding categories driven by proliferation of small unmanned aerial systems and satellite navigation denial requirements. Portable and vehicle-mounted deployment modes attract disproportionate investment as maneuver forces prioritize distributed electromagnetic operations over fixed-site infrastructure.
The U.S. Department of Defense Joint Electromagnetic Spectrum Operations framework, NATO's Standardization Agreement 4774, and the EU's Permanent Structured Cooperation on defense capability development collectively shape certification requirements, interoperability mandates, and cross-border procurement eligibility for military jamming systems. FCC Part 15 restrictions on civilian spectrum interference and national export control regimes under the Wassenaar Arrangement further constrain technology transfer and foreign market access for advanced jamming platforms. Stakeholders must monitor how software-defined jamming architectures alter traditional hardware refresh cycles and whether allied defense industrial base consolidation will restrict subsystem supplier diversity.
Market Dynamics
Software-defined radio architectures are collapsing the traditional hardware refresh cycles that once governed military jammer procurement, forcing defense ministries to renegotiate long-term sustainment contracts and accelerating competition among subsystem suppliers.
Growth Catalysts
- Counter-UAS Mandates:NATO's Standardization Agreement 4774 compels member states to field interoperable counter-drone jamming capabilities, creating standardized demand for portable and vehicle-mounted systems across allied forces.
- GaN Power Amplifier Maturation:Gallium nitride semiconductors deliver higher effective radiated power with reduced thermal footprint, enabling next-generation airborne jammers to operate at extended ranges without vacuum tube reliability constraints.
- Contested Electromagnetic Operations:The U.S. Department of Defense Joint Electromagnetic Spectrum Operations framework prioritizes spectrum superiority, driving procurement of multi-band systems capable of simultaneous electronic attack and protection missions.
Market Restraints
- Export Control Friction:The Wassenaar Arrangement restricts technology transfer of advanced digital radio frequency memory architectures, limiting foreign market access for U.S. and European integrators seeking allied sales.
- Specialized Substrate Concentration:High-purity gallium nitride substrates concentrate among a handful of foundry operators, creating supply vulnerability for power amplifier modules critical to high-power transmitters.
- Spectrum Allocation Conflicts:FCC Part 15 civilian interference restrictions constrain test and training operations, compressing development timelines for systems operating across congested VHF through Ku-band ranges.
Strategic Opportunities
- Naval Platform Integration:Shipborne countermeasure suites represent underpenetrated demand as Aegis combat system upgrades create openings for modular electronic warfare architectures that reconfigure across threat spectra.
- Software-Defined Convergence:The merging of artificial intelligence-enabled threat recognition with adaptive jamming waveforms enables real-time spectrum allocation decisions that legacy analog systems cannot execute.
- EU Permanent Structured Cooperation:This defense capability development mechanism pools procurement budgets across member states, creating consolidated tender opportunities for jamming systems meeting collective interoperability mandates.
Industry Challenges
- Radio Frequency Engineering Talent Scarcity:The specialized skill set combining microwave engineering with cryptographic waveform design concentrates among aging defense contractor workforces, constraining program staffing.
- Legacy System Integration Complexity:New software-defined architectures must interface with vacuum tube-era platforms still in operational service, requiring costly middleware development and extended qualification timelines.
- Cross-Domain Certification Burden:Systems must simultaneously satisfy airworthiness, maritime, and ground vehicle safety standards, multiplying test matrix requirements before operational deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Jammer Market |
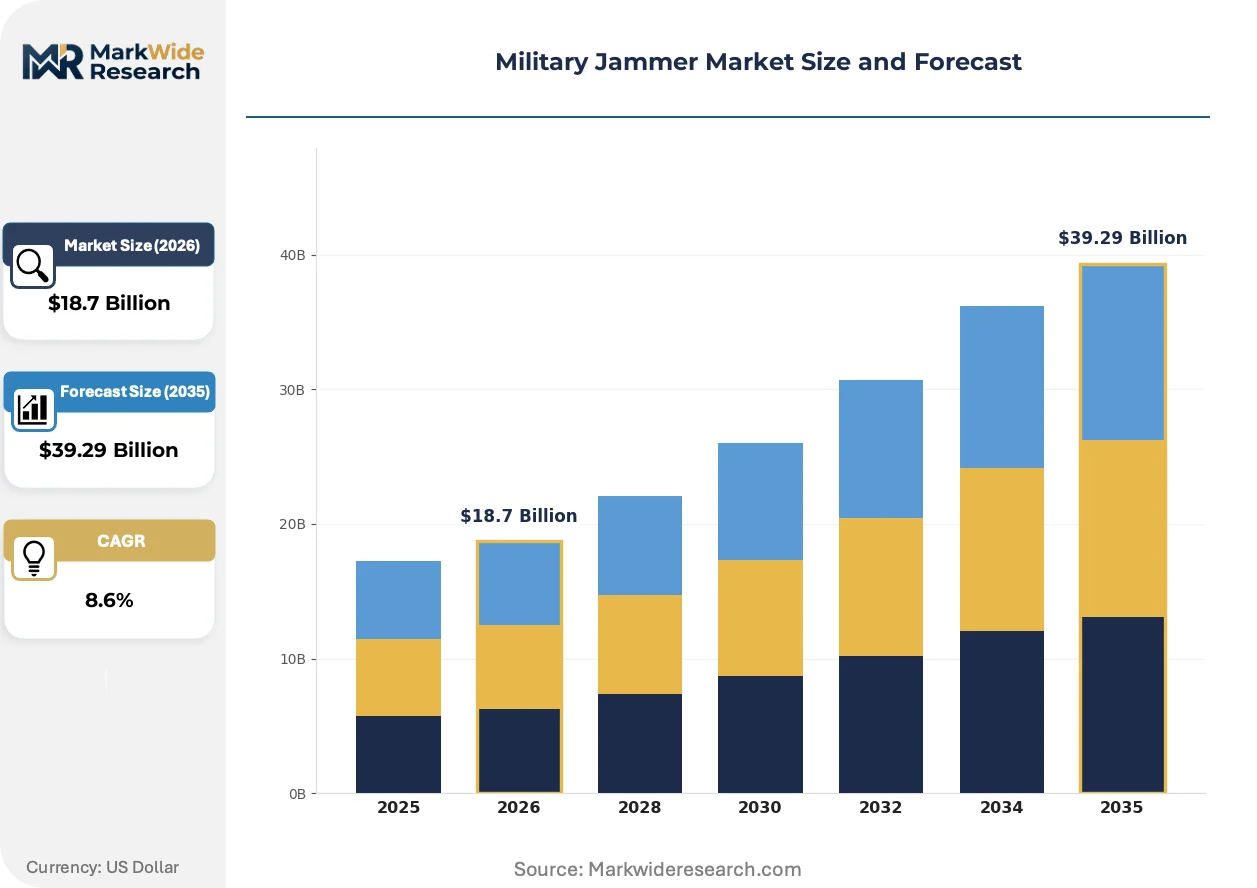
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Countermeasure Jammers, Communication Jammers, Radar Jammers, GPS Jammers Application: Electronic Warfare, Signal Intelligence, Tactical Communication, Counter-IED Technology: Digital, Analog, Hybrid, Frequency Hopping Deployment: Portable, Vehicle-Mounted, Shipborne, Fixed Station |
| Companies Covered | RTX Corporation, Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems, Thales Group, L3Harris Technologies, Elbit Systems, Leonardo S.p.A., Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Jammer Market Strategic Shifts
Cognitive electronic warfare capabilities are redefining operational concepts by enabling autonomous threat response without human-in-the-loop decision cycles, compressing the timeline from detection to effective jamming deployment.
Digital radio frequency memory technology is fragmenting the traditional distinction between training and operational equipment. These architectures capture, store, and precisely replicate adversary radar signatures, allowing military forces to conduct realistic electronic warfare exercises without dedicated threat simulator infrastructure. Defense ministries in Israel and the United Kingdom are prioritizing DRFM-based systems for their dual-use training and combat utility. This convergence is compressing procurement budgets previously split between separate operational and training system lines.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on autonomous jamming systems deployed by member state forces. Manufacturers must now document decision logic for AI-enabled threat prioritization and spectrum allocation functions, extending development timelines for next-generation cognitive electronic warfare platforms. Naval electronic warfare portfolios face particular scrutiny given the safety-critical nature of maritime navigation denial operations.
Defense procurement offices are consolidating previously fragmented electronic attack and electronic protection budgets into unified electromagnetic spectrum operations accounts. This structural change is displacing single-mission system suppliers in favor of integrators offering reconfigurable architectures. The United States exhibits the most pronounced consolidation, with the Department of Defense collapsing separate program executive offices into joint capability directorates that evaluate total spectrum dominance rather than isolated jamming functions.
Military Jammer Market Segmentation
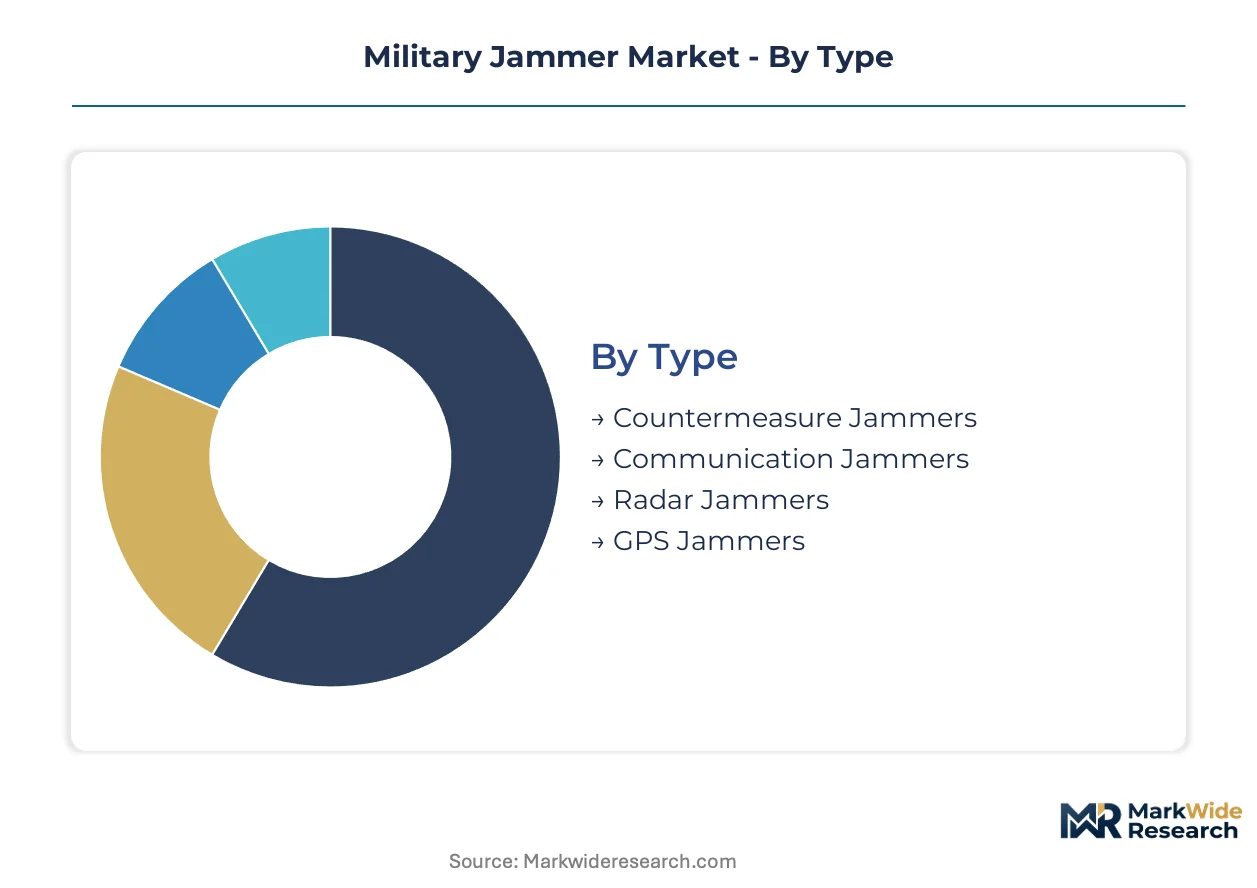
Military jammer procurement patterns diverge sharply across operational domains, with spectrum allocation rules and platform certification requirements determining which configurations defense ministries prioritize. Segment boundaries are blurring as software-defined architectures enable single systems to traverse multiple mission profiles.
Type:
FCC Part 15 restrictions on civilian interference and NATO Standardization Agreement 4774 interoperability mandates create divergent certification pathways for each jammer category, shaping procurement eligibility across allied forces.
- Countermeasure Jammers:These systems emit deceptive RF signals to corrupt adversary radar tracking and missile guidance loops. Demand concentrates in Israel and the United Kingdom for airborne self-protection suites, driven by contested airspace operations requiring rapid threat response cycles.
- Radar Jammers:High-power transmitters operating across X-band and Ku-band frequencies saturate enemy fire control radars with noise or coherent false targets. The United States prioritizes these for penetrating strike aircraft, constrained by Wassenaar Arrangement export controls on advanced digital radio frequency memory architectures.
- Communication Jammers:VHF through UHF systems disrupt tactical voice and data networks. NATO interoperability requirements standardize procurement specifications.
- GPS Jammers:L1/L2 band denial systems counter satellite navigation dependence in precision munitions. Counter-UAS mandates accelerate fielding timelines.
Countermeasure jammers handle the majority of throughput; GPS jammers are the fastest mover on share.
Application:
Cost tier differentiation separates budget-heavy strategic programs from rapidly fielded tactical systems, with electronic warfare absorbing the largest development expenditures while counter-IED procurement favors commercial-off-the-shelf adaptation.
- Electronic Warfare:Spectrum dominance missions integrating electronic attack, protection, and support functions into unified operational frameworks. The U.S. Department of Defense Joint Electromagnetic Spectrum Operations framework consolidates previously fragmented program budgets, favoring integrators with multi-domain capabilities.
- Counter-IED:RF-triggered explosive device neutralization using targeted jamming of command initiation signals. Vehicle-mounted systems dominate procurement in Iraq and Afghanistan legacy theaters, though demand is shifting toward portable configurations for special operations forces.
- Signal Intelligence:Passive collection platforms with embedded jamming capability for reactive countermeasures. Classification constraints limit vendor participation.
- Tactical Communication:Force protection through friendly spectrum management and adversary denial. Network-centric warfare doctrines prioritize interoperability.
Electronic warfare absorbs the dominant share of program funding; counter-IED applications are climbing the fastest as procurement accelerates for asymmetric threat environments.
Technology:
Volume concentration favors digital architectures as gallium nitride power amplifier maturation displaces vacuum tube transmitters, though analog systems persist in lowest-cost tiers and hybrid configurations bridge legacy-modernization gaps.
- Digital:Software-defined radio platforms enabling waveform reconfiguration without hardware modification. The EU AI Act imposes algorithmic transparency requirements on autonomous threat recognition functions, extending development timelines for cognitive electronic warfare systems deployed by member state forces.
- Analog:Fixed-function circuitry with deterministic response characteristics and minimal latency. Aging defense contractor workforces maintain these systems through specialized microwave engineering expertise concentrated in the United States and Israel.
- Hybrid:Digital control layers managing analog RF front-ends, balancing flexibility with power efficiency. Mid-life upgrade programs favor this architecture.
- Frequency Hopping:Rapid spectrum switching to evade detection and maintain effectiveness against adaptive receivers. Anti-jam communication denial requires sophisticated synchronization.
Digital platforms command the dominant procurement volume; frequency hopping systems are expanding most quickly as adversary waveform agility intensifies.
Deployment:
Customer type segmentation separates strategic force investments in fixed infrastructure from maneuver unit priorities for distributed electromagnetic operations, with vehicle-mounted systems capturing the procurement sweet spot between capability and mobility.
- Vehicle-Mounted:Integrated platforms on tactical trucks and armored vehicles providing mobile spectrum dominance for brigade combat teams. The United Kingdom and NATO allies prioritize these for collective defense scenarios, with Aegis combat system integration creating naval crossover demand.
- Portable:Manpack and handheld configurations for dismounted special operations and counter-UAS point defense. Israel fields the most extensive inventories, driven by dense urban operational requirements and rapid deployment mandates against small unmanned aerial system threats.
- Shipborne:Naval electronic warfare suites with sector coverage and integration into combat management systems. L3Harris Technologies anchors this segment with Aegis-compatible countermeasure architectures.
- Fixed Station:Permanent installations for border monitoring and strategic communications denial. High power output compensates for immobility constraints.
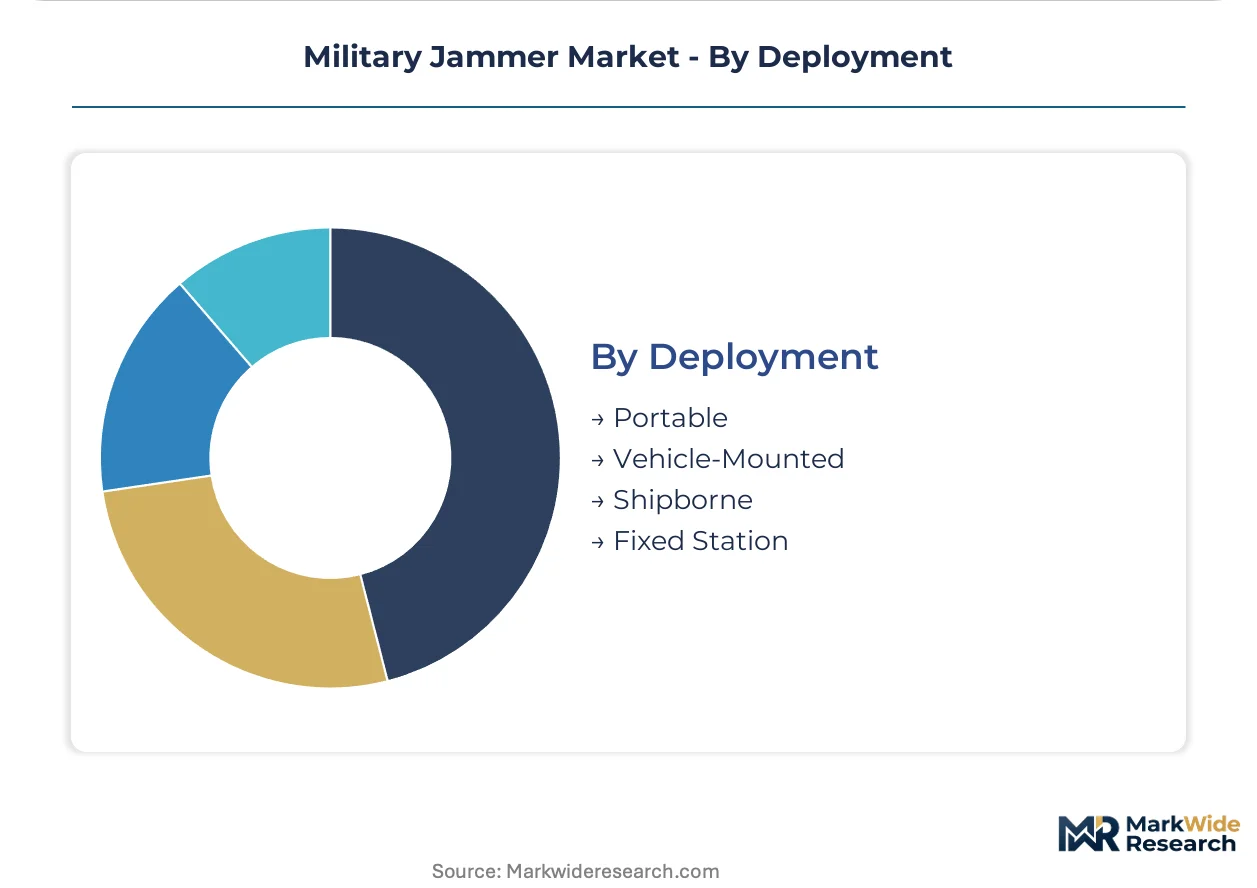
Vehicle-mounted systems carry the majority of procurement value; portable configurations are gaining share fastest as distributed operations concepts displace centralized electronic warfare nodes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices in the United States, Israel, and the United Kingdom concentrate the largest share of military jammer acquisition budgets, driven by contested electromagnetic operations and counter-drone mandates. Each market exhibits distinct regulatory frameworks and industrial cluster specializations that shape supplier access and technology deployment timelines.
United States
The U.S. Department of Defense Joint Electromagnetic Spectrum Operations framework consolidates previously fragmented electronic attack and protection budgets into unified capability directorates. FCC Part 15 restrictions on civilian spectrum interference constrain test operations across congested VHF through Ku-band ranges. Defense contractors cluster around Washington D.C.-Maryland-Virginia corridor and Greater Boston, where RTX Corporation leverages GaN foundry investments for high-power airborne transmitters.
Israel
Israel fields the most extensive inventories of portable jamming configurations, driven by dense urban operational requirements and rapid deployment mandates against small unmanned aerial system threats. The Israeli Ministry of Defense prioritizes dual-use training and combat utility through digital radio frequency memory architectures. Industrial concentration centers on Haifa and Tel Aviv metropolitan areas, where specialized microwave engineering expertise supports countermeasure jammer development.
United Kingdom
The UK Ministry of Defence accelerates procurement of vehicle-mounted systems for collective defense scenarios under NATO Standardization Agreement 4774 interoperability mandates. The EU AI Act imposes algorithmic transparency requirements on autonomous threat recognition functions, extending development timelines for cognitive electronic warfare platforms. Defense electronics activity concentrates around Bristol and the South West, with supply chain linkages to Scottish aerospace clusters.
Germany
Germany pools procurement budgets through the EU Permanent Structured Cooperation mechanism, creating consolidated tender opportunities for jamming systems meeting collective interoperability mandates. The country's national defense regulator emphasizes cross-domain certification compliance across airworthiness, maritime, and ground vehicle safety standards. Industrial capability centers on Bavaria and Baden-Württemberg, where subsystem suppliers support NATO platform integration programs.
France
France prioritizes naval electronic warfare portfolios through shipborne countermeasure suites integrated with combat management systems. The Wassenaar Arrangement restricts technology transfer of advanced digital architectures, limiting foreign market access for French integrators seeking allied sales. Defense industrial concentration spans Île-de-France and Provence-Alpes-Côte d'Azur, with Thales Group anchoring maritime electronic warfare development.
Military Jammer Market Competitive Environment
Player mix skews toward diversified defense conglomerates with captive electronic warfare divisions, supplemented by specialized subsystem suppliers concentrated in RF engineering niches. Tier-one integrators dominate high-power airborne and naval platforms through long-term sustainment contracts, while mid-tier specialists capture portable and vehicle-mounted segments via rapid procurement channels. Two strategic archetypes define competitive positioning: full-spectrum integrators offering reconfigurable multi-mission architectures, and component-focused suppliers delivering gallium nitride power amplifier modules. Dominant competitive moves include defense industrial base consolidation through prime-subcontractor restructuring, and backward integration into semiconductor foundry capacity to secure substrate supply.
Within the full-spectrum integrator tier, RTX Corporation, Northrop Grumman Corporation, and L3Harris Technologies occupy positions exemplifying divergent platform specializations. RTX represents the airborne transmitter archetype through GaN foundry investments. Northrop Grumman sits within the digital architecture segment, exemplifying precise threat replication capabilities. L3Harris anchors naval electronic warfare portfolios, representing shipborne countermeasure integration with Aegis combat systems. These three conglomerates collectively illustrate how defense procurement consolidation favors suppliers offering unified electromagnetic spectrum operations rather than isolated jamming functions.
| Leading Market Players |
|---|
| RTX Corporation |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| Thales Group |
| L3Harris Technologies |
| Elbit Systems |
| Leonardo S.p.A. |
| Saab AB |
| Others |
Value Chain & Pricing Dynamics
Twenty-four-month qualification timelines for GaN substrate qualification compress supplier switching options and amplify pricing power for foundry operators serving high-power transmitter programs. Defense procurement offices absorb these lead-time premiums through multi-year sustainment contracts that lock in volume commitments before substrate availability tightens.
Pricing Analysis
Current-generation software-defined architectures command substantial premiums over vacuum tube legacy systems and early analog solid-state replacements, while next-generation cognitive electronic warfare platforms with embedded AI threat recognition extend price bands further upward. Three-tier pricing structure across premium, standard, and economy levels separates NATO-certified multi-band systems from single-mission configurations and commercial-off-the-shelf counter-UAS adaptations. Cost compression in portable and vehicle-mounted tiers intensifies as Israeli and British defense ministries accelerate fielding timelines against small unmanned aerial system threats. Commercial-off-the-shelf counter-UAS segments exhibit highest price sensitivity, whereas airborne self-protection suites for penetrating strike aircraft demonstrate lowest sensitivity due to mission-critical performance requirements and Wassenaar Arrangement-constrained supplier pools.
Supply Chain Analysis
Inbound logistics costs for high-purity GaN substrates from Japan and the United States face elevated exposure to transpacific container availability constraints and customs processing delays at Los Angeles-Long Beach and Yokohama ports. Taiwan, Japan, and the United States concentrate gallium nitride foundry capacity critical to next-generation power amplifier modules. Supply chains draw from specialized microwave engineering talent pools in Israel and the United Kingdom, alongside rare earth element dependencies for magnetics and thermal management substrates. Single-source vulnerability concentrates in six-inch GaN-on-SiC wafer supply from two dominant foundry operators. Distribution runs through prime contractor integration channels with direct defense ministry contracting, supplemented by subsystem vendor relationships with tier-one electronic warfare integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement consolidation is fragmenting supplier opportunities across specialized subsystem niches, as software-defined architectures enable mid-tier specialists to capture vehicle-mounted and portable segments previously dominated by full-spectrum integrators.
For Market Incumbents: Secure captive gallium nitride foundry capacity or long-term substrate offtake agreements to isolate power amplifier supply from single-source concentration risk. Invest in NATO Standardization Agreement 4774 certification pathways to maintain eligibility across pooled EU Permanent Structured Cooperation tenders. Threat substitution from Chinese counter-UAS exports and margin pressure from software-defined radio commoditization demand defensive consolidation moves. For New Entrants and Emerging Players: Aftermarket sustainment and legacy system middleware development represent under-served service layers where aging defense contractor workforces constrain incumbent responsiveness. Portable configurations for special operations forces offer the most penetrable deployment segment, given Israeli and British rapid procurement channels and lower certification burden relative to airborne platforms. Pursue subcontractor relationships with tier-one naval integrators seeking Aegis combat system compatibility expertise as a go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified defense conglomerates spinning non-core electronic warfare divisions amid portfolio rationalization pressures. Five-to-ten-year viability hinges on software-defined architecture transition completion and cognitive electronic warfare capability maturation. Acquisition candidates with DRFM architecture expertise and existing NATO certification represent priority archetypes. Monitor EU AI Act implementation timelines as an inflection indicator for algorithmic transparency compliance costs that could reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Backward Integration | Captive substrate supply insulates RTX Corporation and L3Harris Technologies from six-inch wafer bottlenecks. |
| DRFM Architecture Licensing | Northrop Grumman Corporation's threat replication IP extends training and combat utility across allied forces. |
| Naval Platform Integration Partnership | Thales Group's combat management system linkages anchor maritime electronic warfare procurement in France and NATO. |
| Counter-UAS Rapid Fielding Program | Israeli Ministry of Defense portable configuration mandates accelerate procurement cycles for specialized suppliers. |
| EU PESCO Consolidated Tender Participation | German pooling mechanisms create volume opportunities for systems meeting collective interoperability mandates. |
Study Parameters
Initial hypotheses were tested against primary input from electronic warfare program executives, GaN foundry operations directors, defense ministry procurement officers, and subsystem engineering leads, then refined through secondary validation against NATO Standardization Agreement documentation, Wassenaar Arrangement control lists, U.S. Department of Defense budget justification materials, and EU Permanent Structured Cooperation capability development reports. Bottom-up triangulation across platform-level procurement data and top-down validation against national defense expenditure patterns ensured cross-verification of volume and value estimates.
Variance decomposition across the projection horizon isolates contribution from type, application, technology, and deployment segment dynamics, with additional modeling of regulatory framework impacts from FCC Part 15 restrictions and EU AI Act algorithmic transparency requirements. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion, incorporating GaN power amplifier maturation curves, counter-UAS mandate implementation timelines, and software-defined radio adoption patterns as industry-specific forecast inputs.
Underlying assumptions cover sustained NATO interoperability investment, continued GaN substrate supply concentration, and stable Wassenaar Arrangement control list enforcement, with deviation risk concentrated in export control relaxation, foundry capacity expansion, or electromagnetic spectrum operations doctrine shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Air-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Global Radar Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Surveillance Radar System Market
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Missile Seeker Detector Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Manportable Radar Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
Maritime Situational Awareness Systems Market
Military Surveillance
Military Radar Market