
 Global Actinic Keratosis Treatment Market | 2026-2036
Global Actinic Keratosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Actinic Keratosis Treatment Market Foresight
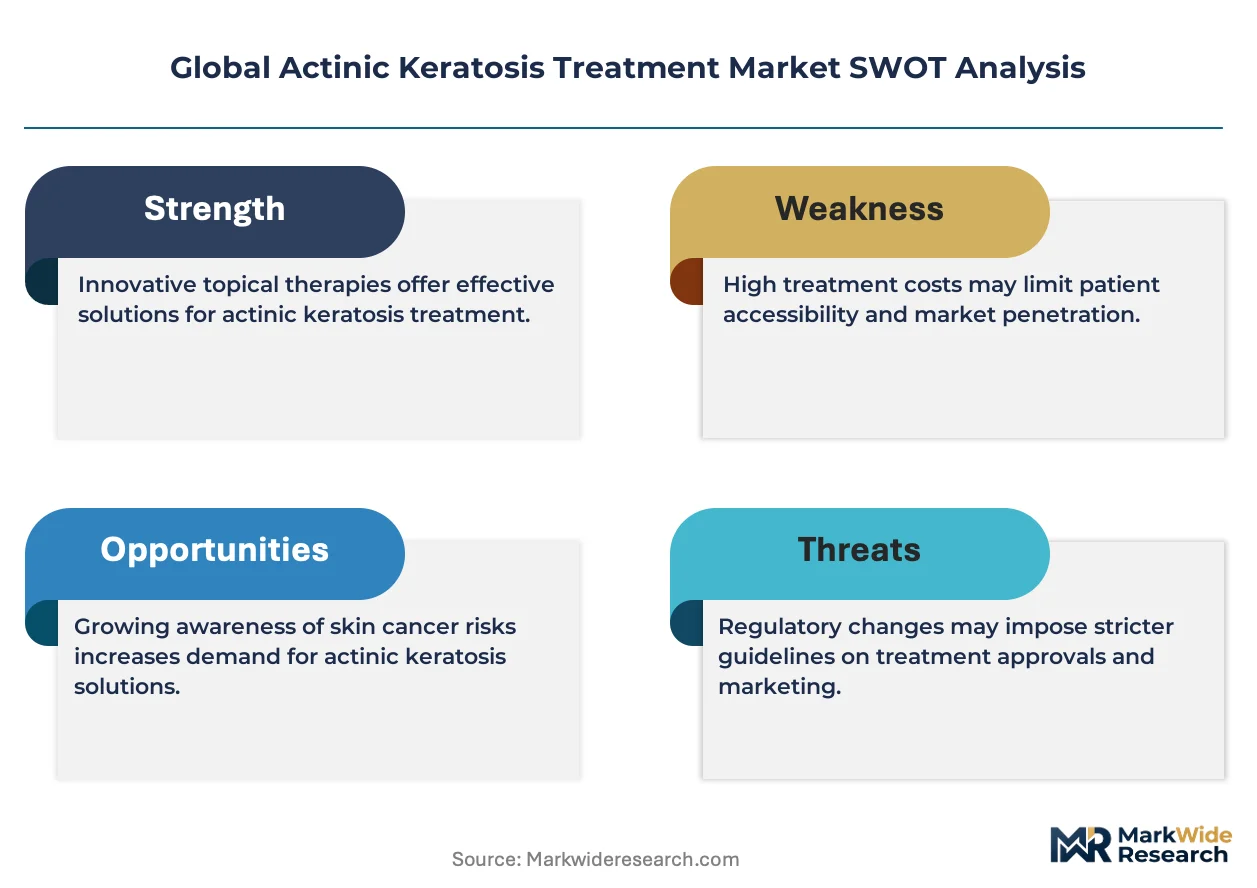
Asset-light licensing and royalty-based partnering is reshaping competitive economics in actinic keratosis therapeutics. Sun Pharmaceutical Industries Ltd leverages its vertically integrated manufacturing footprint to dominate generic imiquimod supply. Biofrontera AG specializes in photodynamic therapy devices and photosensitizer combinations that anchor its position in clinic-based procedures. Galderma S.A. competes through dermatology-focused commercial infrastructure that extends across European and North American prescription channels.
Actinic keratosis treatment encompasses medical interventions targeting ultraviolet-induced premalignant epidermal lesions, typically involving cryogenic destruction, photosensitizer activation at 630 nm wavelength, or immune response modulation through toll-like receptor agonists. The primary purpose is field-directed eradication of subclinical lesions to prevent progression to invasive squamous cell carcinoma. Topical creams and immunomodulators occupy the largest revenue pool due to at-home administration and repeat prescription cycles, while photodynamic therapy commands premium pricing in cosmetic surgery centers where patients prioritize rapid clearance and superior aesthetic outcomes. Destructive approaches including cryotherapy remain mature segments with stable procedural volumes in outpatient settings.
FDA clearance requirements for combination device-drug photodynamic systems and EMA's MDR classification for dermatological lasers shape product development timelines and market access conditions. REACH compliance for photosensitizer manufacturing and EPA oversight of methyl aminolevulinate synthesis impose formulation and environmental handling standards that filter smaller competitors. Stakeholders must monitor reimbursement decisions by CMS and Germany's G-BA, as coverage determinations for field-directed therapies will dictate whether pharmacological approaches capture share from established destructive modalities.
Market Dynamics
Photodynamic therapy systems are compressing treatment protocols from multiple clinic visits to single-session field-directed eradication, fundamentally restructuring how dermatology practices allocate capital and patient throughput.
Growth Catalysts
- FDA accelerated approval pathways:Compressed development timelines for topical field-directed therapies are pulling pharmacological alternatives into earlier treatment lines.
- Dermatology clinic patient volumes:Rising screening rates and aging populations in the United States are expanding the addressable lesion population seeking procedural intervention.
- Medicare reimbursement stability:Sustained coverage determinations for cryotherapy and photodynamic procedures preserve procedure economics in outpatient settings.
Market Restraints
- Methyl aminolevulinate synthesis costs:EPA environmental handling requirements for photosensitizer manufacturing impose fixed cost burdens that filter smaller formulation competitors.
- Device-drug combination complexity:FDA clearance requirements for integrated photodynamic systems extend development timelines beyond standalone pharmaceutical pathways.
- Generic imiquimod supply concentration:Vertically integrated manufacturers dominate toll-like receptor agonist supply, constraining pricing flexibility for branded alternatives.
Strategic Opportunities
- At-home topical administration:Immune response modulators and field-directed creams present expansion potential in patient-managed care models outside clinic settings.
- Cosmetic surgery center channel:Premium aesthetic outcomes from photodynamic therapy command superior pricing in elective procedure environments.
- EMA MDR classification alignment:Harmonized dermatological laser standards across European markets streamline multi-country product registration for device manufacturers.
Industry Challenges
- Photosensitizer handling certification:REACH compliance and environmental safety protocols require specialized training that constrains clinic staff scalability.
- Reimbursement fragmentation:Divergent coverage determinations between CMS and Germany's G-BA complicate market access strategy for field-directed pharmacological therapies.
- Legacy cryotherapy infrastructure:Established destructive modality equipment represents sunk capital that slows adoption of alternative treatment platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Actinic Keratosis Treatment Market |
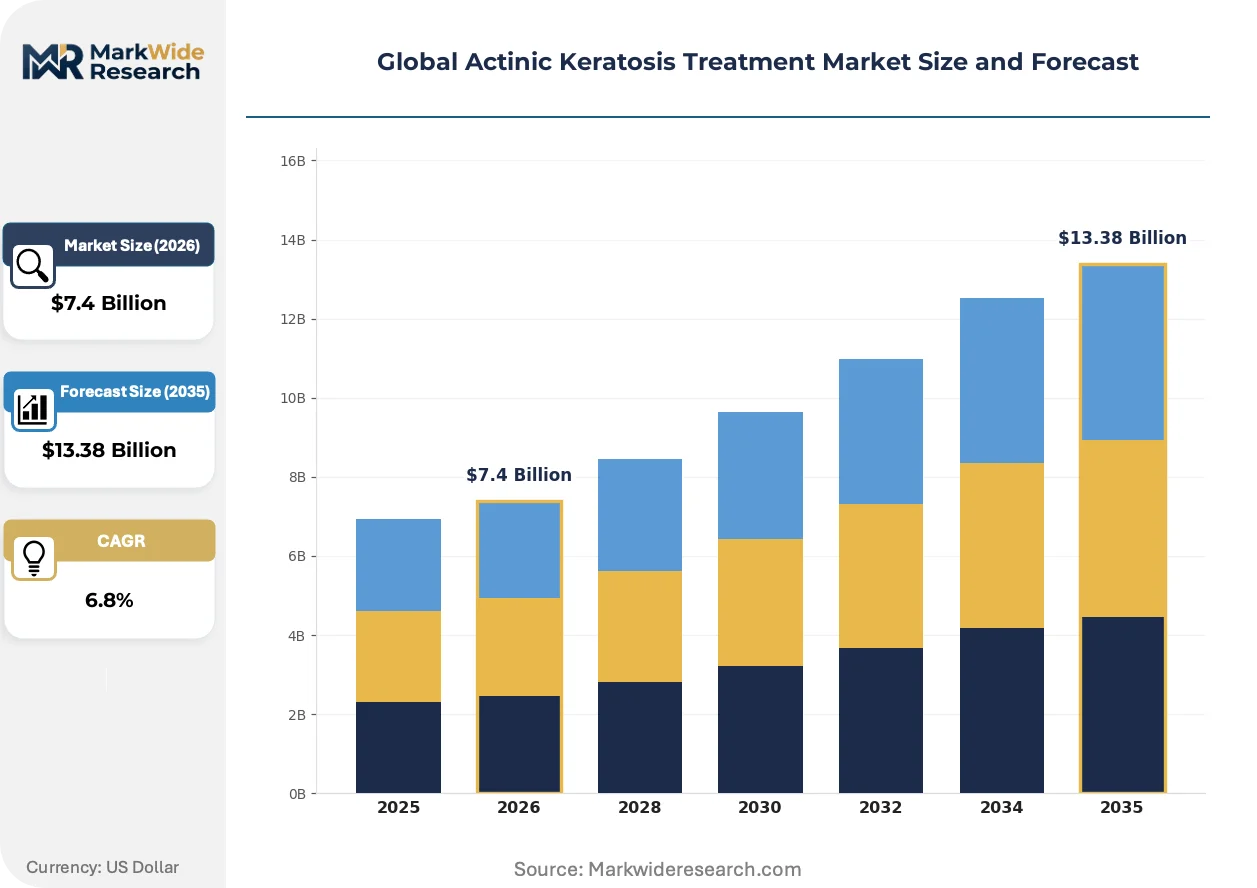
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryotherapy, Topical Creams, Photodynamic Therapy, Chemical Peels, Laser Therapy, Immunomodulators Application Area: Face, Scalp, Hands, Neck, Arms, Shoulders End User: Dermatology Clinics, Outpatient Centers, Cosmetic Surgery Centers, Hospitals Treatment Approach: Destructive, Pharmacological, Phototherapeutic, Immunotherapy |
| Companies Covered | Sun Pharmaceutical Industries Ltd, Biofrontera AG, Bausch Health Companies Inc., LEO Pharma A/S, Almirall S.A., Galderma S.A., Novartis AG, 3M Company, Hill Dermaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Actinic Keratosis Treatment Market Shifts & Advancements
Device-drug convergence is collapsing the traditional separation between pharmaceutical and procedural actinic keratosis management, creating new competitive arenas where manufacturing and clinical expertise must integrate.
Photodynamic therapy is migrating from multi-visit protocols toward single-session field-directed treatment. Dermatology practices in the United States are adopting 630 nm wavelength activation systems at accelerated replacement cycles. This compression is enabling same-day lesion eradication that challenges the repeat-prescription economics of topical immunomodulators.
REACH compliance frameworks are tightening environmental handling standards for photosensitizer manufacturing across European supply chains. ECHA oversight of methyl aminolevulinate synthesis is forcing reformulation investments and captive production capabilities. German and French manufacturing clusters are responding with closed-loop synthesis systems that internalize waste management.
Patient preference for rapid clearance and superior cosmetic outcomes is rotating demand toward clinic-based procedural interventions. Cosmetic surgery centers are displacing traditional dermatology offices as the premium channel for photodynamic therapy. This shift concentrates in United States metropolitan markets where elective procedure pricing tolerates device-drug combination premiums.
Global Actinic Keratosis Treatment Market Segmentation
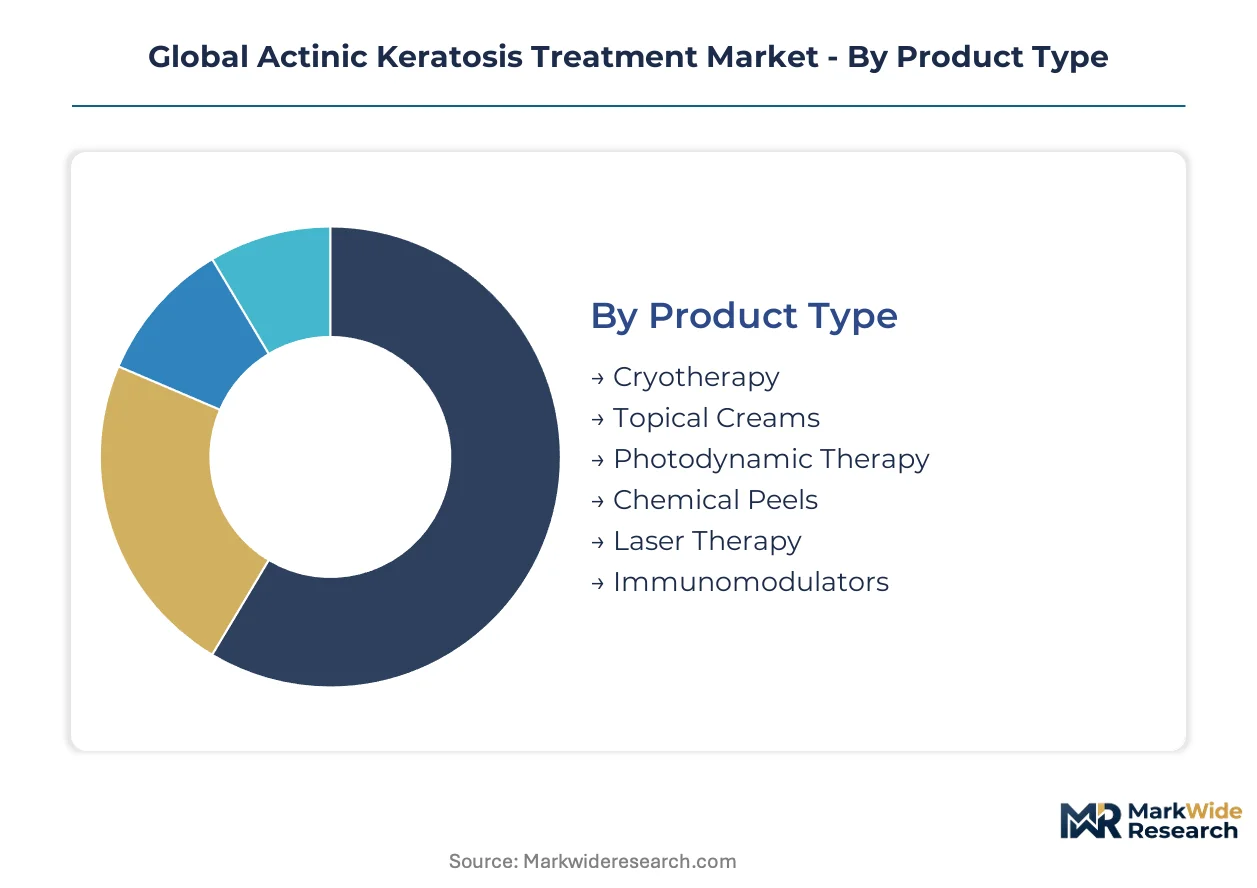
Actinic keratosis treatment modalities differ sharply in reimbursement economics, patient throughput, and capital intensity. Segmentation reveals how capital allocation and channel strategy diverge across destructive, pharmacological, and phototherapeutic approaches.
Product Type:
Cost tier stratification separates high-capital device systems from consumable pharmaceutical formats with recurring revenue profiles.
- Cryotherapy:Liquid nitrogen-based lesion destruction requires minimal equipment investment and delivers immediate procedural revenue. Demand concentrates in Medicare-reimbursed outpatient settings across the United States where rapid lesion turnover sustains volume economics.
- Photodynamic Therapy:630 nm wavelength activation systems paired with methyl aminolevulinate photosensitizers command premium pricing in cosmetic surgery centers. Patient preference for single-session field-directed clearance and superior aesthetic outcomes drives adoption in metropolitan United States markets.
- Topical Creams:Patient-administered field-directed formulations with repeat prescription cycles.
- Chemical Peels:Acid-based keratolysis for superficial lesion eradication in clinic settings.
- Laser Therapy:Ablative and non-ablative wavelength systems for targeted lesion destruction.
- Immunomodulators:Toll-like receptor agonist creams requiring extended application protocols.
Cryotherapy commands the established base. The steepest expansion runs through photodynamic therapy.
Application Area:
Anatomical location determines treatment modality selection based on cosmetic sensitivity, lesion density, and patient tolerance for procedural downtime.
- Face:High-visibility lesions drive demand for aesthetic-preserving interventions. Photodynamic therapy captures disproportionate share in United States cosmetic surgery centers where patients prioritize rapid healing and minimal scarring.
- Scalp:Hair-bearing tissue complicates destructive approaches and favors field-directed pharmacological treatment. Medicare reimbursement patterns in the United States sustain cryotherapy volume despite cosmetic limitations.
- Hands:Chronic sun exposure creates dense lesion fields requiring repeated intervention.
- Neck:Thin epidermis limits aggressive destructive modality selection.
- Arms:Extensive surface area favors field-directed topical administration.
- Shoulders:Lower cosmetic priority permits cost-optimized destructive approaches.
Facial applications concentrate premium pricing power. Scalp lesions are climbing the fastest as screening protocols expand.
End User:
Customer type segmentation maps capital intensity, reimbursement access, and patient volume throughput across delivery settings.
- Dermatology Clinics:Purpose-built facilities with integrated photodynamic therapy systems and trained staff for photosensitizer handling. Rising patient volumes from aging populations and expanded screening in the United States compress appointment availability and accelerate capital replacement cycles.
- Cosmetic Surgery Centers:Elective procedure environments with pricing tolerance for device-drug combination premiums. Concentrated in United States metropolitan markets where aesthetic outcome prioritization sustains margins above traditional reimbursement rates.
- Outpatient Centers:General procedural facilities with cryotherapy infrastructure and stable Medicare economics.
- Hospitals:Inpatient and emergency settings for complex or extensive lesion presentations.
Outpatient centers anchor procedural volume. Dermatology clinics are gaining share fastest as field-directed therapy adoption accelerates.
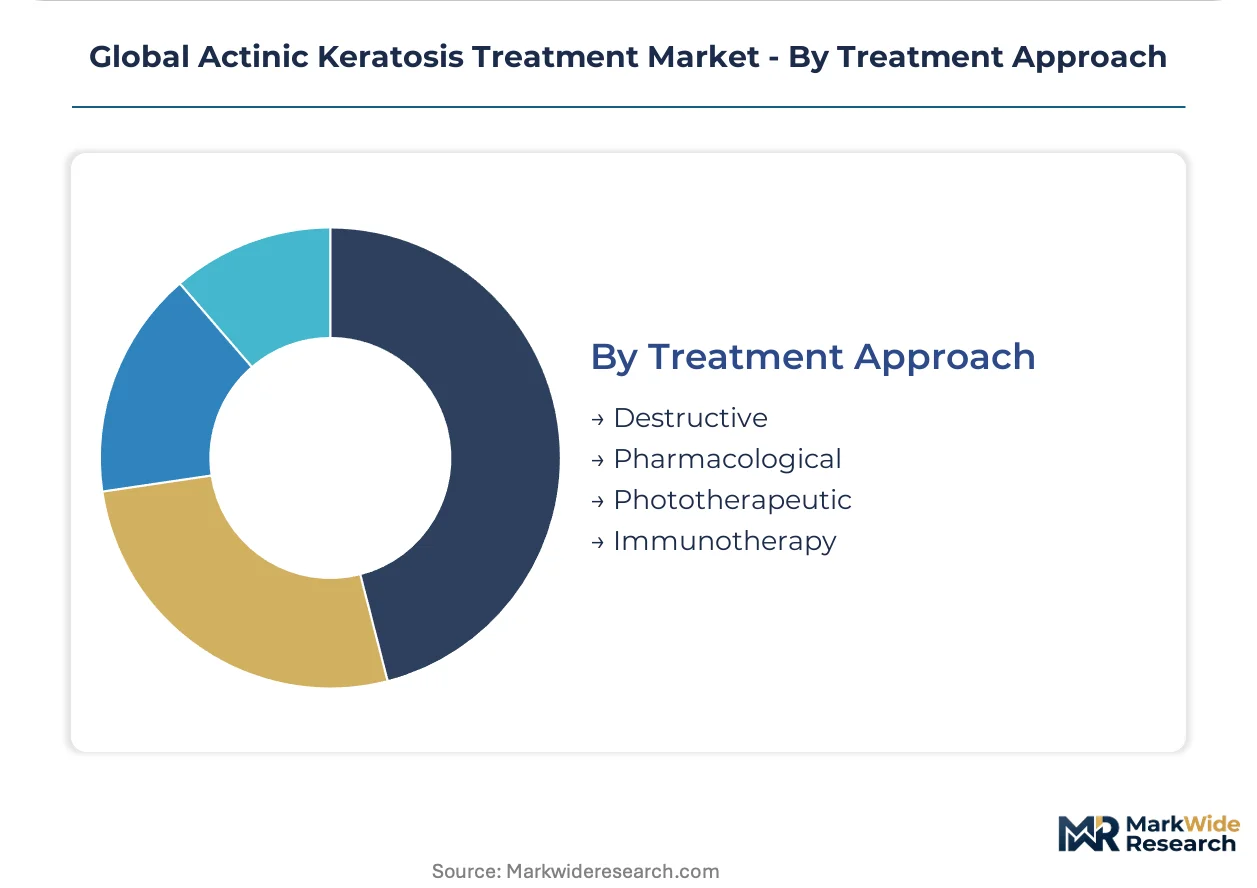
Treatment Approach:
Technical mechanism determines development timeline, regulatory pathway, and competitive entry barriers for market participants.
- Destructive:Physical eradication through cryogenic, thermal, or mechanical means with established FDA clearance pathways and immediate reimbursement codes. Mature segment with stable procedural economics in United States outpatient settings.
- Phototherapeutic:Light-activated photosensitizer systems requiring combination device-drug FDA clearance. Extended development timelines filter competition and sustain premium positioning in cosmetic channels.
- Pharmacological:Topical field-directed therapies with accelerated FDA approval pathways compressing time-to-market for new molecular entities.
- Immunotherapy:Toll-like receptor modulation through patient-applied creams with at-home administration economics.
Destructive approaches hold the volume base. Phototherapeutic modalities show the steepest trajectory as single-session protocols displace multi-visit alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic surgery centers in the United States concentrate premium demand for photodynamic therapy, while Medicare-sustained dermatology clinics anchor procedural volume. European manufacturing clusters supply photosensitizer active ingredients under REACH environmental protocols. Asian markets remain underpenetrated for device-drug combination therapies.
United States
Medicare reimbursement stability for cryotherapy and photodynamic procedures preserves outpatient economics across dermatology clinics. FDA accelerated approval pathways compress development timelines for topical field-directed therapies. Metropolitan cosmetic surgery centers in Los Angeles and Miami command premium pricing for single-session photodynamic protocols.
Germany
EMA MDR classification for dermatological lasers streamlines multi-country registration for device manufacturers. G-BA reimbursement determinations for field-directed therapies influence pharmacological adoption rates versus destructive modalities. Manufacturing clusters in Baden-Württemberg deploy closed-loop methyl aminolevulinate synthesis systems under ECHA oversight.
France
ANSM regulatory frameworks govern photosensitizer handling certification requirements for clinic staff. Patient preference for aesthetic outcomes drives photodynamic therapy adoption in Parisian cosmetic surgery centers. Lyon-based chemical manufacturing infrastructure supports European photosensitizer supply chains.
United Kingdom
NICE technology appraisals shape National Health Service coverage for actinic keratosis interventions. London dermatology practices integrate photodynamic systems at accelerated capital replacement cycles. Manchester and Birmingham outpatient centers sustain cryotherapy volume through stable procedural reimbursement.
Japan
PMDA regulatory pathways for combination device-drug systems extend market entry timelines versus standalone pharmaceuticals. METI industrial policy supports domestic dermatological laser manufacturing capabilities. Tokyo and Osaka metropolitan clinics concentrate demand for premium aesthetic-preserving interventions.
Global Actinic Keratosis Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent access points. Vertically integrated pharmaceutical manufacturers dominate generic supply, while device-drug combination specialists anchor clinic-based procedural channels. Three archetypes structure competition: integrated manufacturers with captive supply chains, photodynamic therapy system specialists, and dermatology-focused commercial infrastructure operators. Strategic moves concentrate on licensing partnerships and manufacturing footprint consolidation.
Among the integrated manufacturers, Sun Pharmaceutical Industries Ltd occupies a position exemplifying vertical control over generic imiquimod supply. Biofrontera AG and Galderma S.A. represent contrasting archetypes within the procedural and prescription channels respectively. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries Ltd |
| Biofrontera AG |
| Bausch Health Companies Inc. |
| LEO Pharma A/S |
| Almirall S.A. |
| Galderma S.A. |
| Novartis AG |
| 3M Company |
| Hill Dermaceuticals Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in methyl aminolevulinate synthesis across European manufacturing clusters is compressing supplier margins while elevating pricing power for integrated photosensitizer producers. This utilization squeeze propagates through device-drug combination systems, where captive supply chains command premium positioning against toll-manufactured alternatives.
Pricing Analysis
Certification level (FDA 510(k)-cleared versus CE-marked-only) creates the primary spread between photodynamic therapy system tiers. Three-tier pricing structure across premium, standard, and economy levels separates integrated device-drug bundles from standalone pharmaceutical consumables. Pricing pressure stems from generic imiquimod oversupply concentrated in Indian manufacturing. Dermatology clinics exhibit highest price sensitivity; cosmetic surgery centers tolerate device-drug combination premiums.
Supply Chain Analysis
Contract manufacturing concentration for photosensitizer active ingredients rests with Baden-Württemberg chemical clusters and Lyon-based pharmaceutical intermediates specialists. Geographic supply concentration centers on Germany, France, and India for synthesis and formulation stages. Raw material dependencies include porphyrin precursors, 5-aminolevulinic acid, and specialized 630 nm wavelength laser diodes. Single-source vulnerability in methyl aminolevulinate API production constrains supply security. Distribution runs through dermatology-focused medical device distributors and hospital GPO channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from at-home topical immunomodulators that erode clinic-based procedural economics. Defense requires hardening reimbursement-dependent revenue streams against pharmacological displacement.
For Market Incumbents: Harden photodynamic therapy positioning through backward integration into photosensitizer manufacturing and accelerated FDA submission for single-session field-directed protocols. Channel control in United States dermatology clinics represents the critical defensive lever against generic topical erosion. For New Entrants and Emerging Players: At-home field-directed cream formulations for Medicare-insured scalp lesions represent the most penetrable entry point outside cosmetic surgery center saturation. Licensing partnerships with established dermatology commercial infrastructure enable rapid channel access without capital-intensive field force buildout. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among device-drug combination specialists with captive photosensitizer supply and cosmetic surgery center channel penetration. Five-to-ten-year viability hinges on reimbursement durability for procedural interventions. The signal to watch is CMS coverage determination shifts for field-directed pharmacological alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses development timelines for topical field-directed therapies against cryotherapy standards. |
| Manufacturing Scale-Up | Closed-loop methyl aminolevulinate synthesis systems under ECHA oversight reduce environmental compliance burden. |
| Reimbursement Strategy | Medicare coverage determination advocacy preserves outpatient procedural economics against pharmacological substitution. |
| Strategic Partnership | Licensing agreements with dermatology-focused commercial infrastructure accelerate market access without field force investment. |
| Product Launch | Single-session photodynamic protocols challenge repeat-prescription economics of topical immunomodulators in cosmetic channels. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling and top-down market sizing triangulated on segment-level estimates.
Demand-supply balance across treatment modalities anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include treatment approach, end-user channel, anatomical application area, and regional regulatory cluster. CAGRs derived from procedure volume trajectories, pricing elasticity assumptions, and reimbursement stability projections. Forecast inputs incorporated dermatology clinic patient throughput data and photosensitizer manufacturing capacity utilization signals.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, REACH compliance cost inflation, or FDA review timeline variability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway outcomes and channel mix evolution. Quarterly review of CMS coverage determinations and EMA MDR implementation timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Congenital Neutropenia Treatment Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Central Nervous System (CNS) Biomarkers Market
Specialty Medicine
Global Cancer Therapy Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
China Precision Medicine Market
Specialty Medicine
Peptide-Based Metabolic Disorders Therapeutics Market
Specialty Medicine
Cutaneous Fibrosis Treatment Market
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market
Specialty Medicine
Palmoplantar Pustulosis Market
Specialty Medicine
Splenomegaly Therapeutics Market
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
Mitochondrial Disorders Treatment Market