
 Global Cancer Biological Therapy Market | 2026-2036
Global Cancer Biological Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cancer Biological Therapy Market Foresight
The gap between monoclonal antibody engineering and cell-based manufacturing is narrowing as platform technologies standardize production workflows. Bristol-Myers Squibb leverages its integrated discovery-to-commercial infrastructure across immuno-oncology portfolios. Novartis anchors its position through CAR-T manufacturing scale and global logistics networks. Roche differentiates via companion diagnostic alignment with targeted biological agents.
Cancer biological therapy encompasses protein-based, cell-based, and nucleic acid therapeutics that modulate immune recognition or interrupt oncogenic signaling pathways, typically manufactured through recombinant DNA technology in mammalian cell culture systems with purity thresholds exceeding 95 percent. Monoclonal antibodies dominate current revenue pools due to established infusion infrastructure and broad tumor-type approvals. Immunomodulators represent the fastest-expanding category as checkpoint inhibitors extend into earlier treatment lines and combination protocols. Nanoparticle carriers command premium positioning where tumor penetration and reduced systemic toxicity justify formulation complexity.
The FDA accelerates biological therapy access through breakthrough therapy and regenerative medicine advanced therapy designations, while the EMA enforces centralized marketing authorization with post-authorization safety monitoring under the MDR framework. China's NMPA aligns growing domestic biological therapy demand with streamlined priority review pathways for innovative oncology products. Stakeholders must monitor how regulator convergence on real-world evidence requirements reshapes post-market commitment burdens and competitive differentiation.
Market Dynamics
The FDA's breakthrough therapy designation compresses clinical timelines while simultaneously intensifying manufacturing capacity constraints for mammalian cell culture systems. This regulatory acceleration creates a structural bottleneck where approval velocity outpaces bioreactor availability.
Growth Catalysts
- Immuno-oncology protocol expansion:Academic medical centers in the United States, China, and Germany now position biological therapies as first-line interventions rather than salvage treatments, expanding addressable patient pools across solid tumor indications.
- EMA centralized authorization harmonization:The MDR framework streamlines post-authorization safety monitoring across EU member states, reducing redundant compliance costs for multi-market launches.
- Platform technology standardization:Single-use bioreactor systems and continuous manufacturing workflows collapse batch-to-batch variability, enabling faster tech transfer between discovery and commercial production.
Market Restraints
- Mammalian cell culture input concentration:Chinese hamster ovary cell line supply and recombinant protein media formulation depend on a concentrated supplier base in Switzerland and Germany, creating vulnerability to geopolitical disruption.
- Cold chain infrastructure gaps:CAR-T cell therapies require cryogenic logistics networks that remain underdeveloped in India, Brazil, and Southeast Asian markets, limiting geographic reach.
- Reimbursement compression:Germany's AMNOG early benefit assessment and the United Kingdom's NICE technology appraisals impose mandatory price discounts for therapies without demonstrated mortality superiority.
Strategic Opportunities
- Subcutaneous formulation penetration:Biologics with self-administration potential bypass infusion center capacity constraints, opening homecare channels in Japan and South Korea where aging populations strain hospital infrastructure.
- Biosimilar substitution frameworks:The IRA's Medicare price negotiation provisions create policy tailwinds for interchangeable biological products in the United States, rewarding manufacturing scale and analytical parity investments.
- Companion diagnostic convergence:CDx-enabled patient stratification aligns reimbursement with biomarker-defined responder populations, reducing commercial risk in heterogeneous tumor types.
Industry Challenges
- Cell therapy manufacturing workforce scarcity:GMP-grade aseptic processing and vector production require specialized technicians whose training pipelines lag facility construction timelines by 24-36 months.
- Multi-product facility contamination risk:Campaign changeover protocols for antibody-drug conjugates and live cell products demand validated cleaning verification that extends downtime between batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cancer Biological Therapy Market |
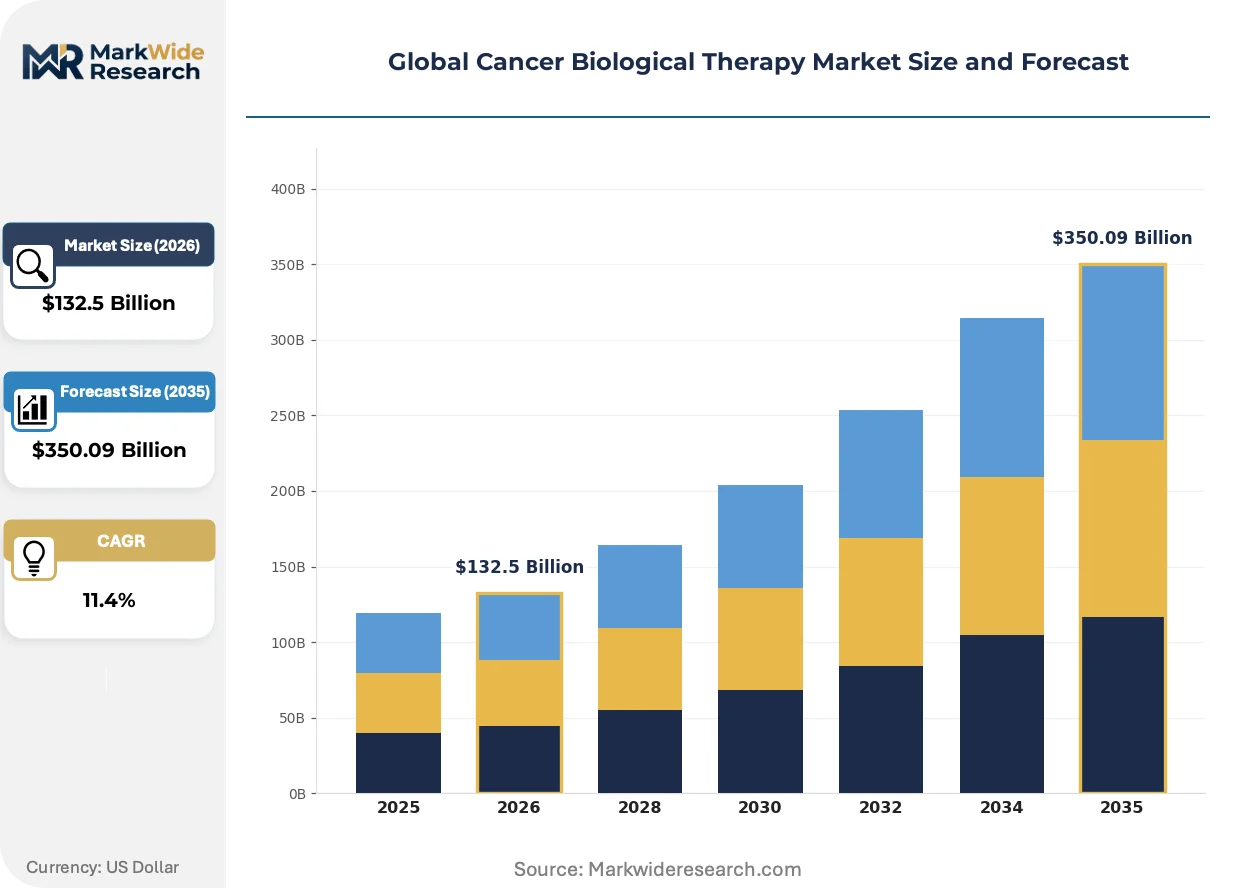
| Market Size in 2026 | $132.5 Billion |
| Market Size in 2035 | $350.09 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Monoclonal Antibodies, Interferons, Cancer Vaccines, Immunomodulators, Oncolytic Virus, Hematopoietic Growth Factors Therapy Indication: Breast Carcinoma, Lung Neoplasms, Colorectal Adenocarcinoma, Prostate Malignancies, Melanoma, Gastric Tumors End User Setting: Specialized Clinics, Research Institutes, Outpatient Treatment Centers, Rehabilitation Facilities, Diagnostic Laboratories, Community Health Centers Delivery Technology: Intravenous Infusion, Subcutaneous Injection, Oral Formulations, Nanoparticle Carriers, Liposomal Delivery, Biodegradable Implants |
| Companies Covered | Bristol-Myers Squibb, Novartis, Amgen, Pfizer, AstraZeneca, Gilead Sciences, Roche, BioNTech, Merck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cancer Biological Therapy Market Shifts & Advancements
Biological therapy development is converging on modalities that bypass historical manufacturing constraints through synthetic biology and automated production systems. Three developments dominate competitive positioning.
Non-viral gene delivery platforms are collapsing the cost structure of cell engineering by replacing lentiviral vectors with electroporation-based transposon systems. Contract development organizations in Singapore and the Netherlands now integrate these tools into standardized workflows, compressing IND-to-clinic timelines from 18 months to under 9 months for autologous programs.
China's NMPA priority review pathway for innovative oncology products now aligns with FDA breakthrough criteria, enabling simultaneous submission strategies that accelerate market entry. Domestic manufacturers leverage this regulatory convergence to file first-in-class biologics globally rather than sequentially, forcing multinational incumbents to defend position through lifecycle management rather than launch timing.
Hospital procurement consortia in Germany and France now aggregate demand across multiple academic centers, shifting purchasing power from individual institutions to regional buying groups. This concentration pressures list prices while rewarding suppliers with integrated real-world data collection capabilities that support HTA submissions, favoring companies with established pharmacovigilance infrastructure over emerging entrants.
Global Cancer Biological Therapy Market Segmentation
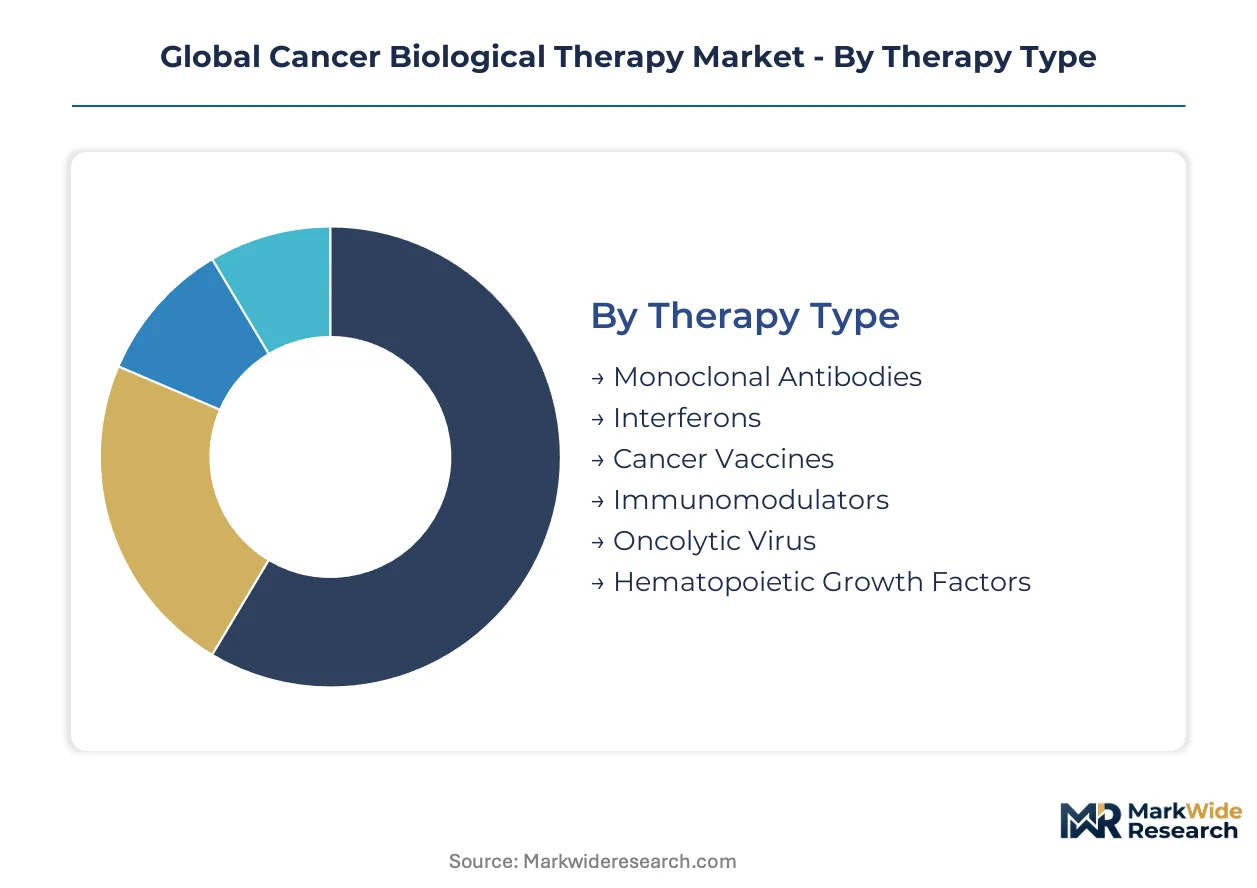
Biological therapy segmentation reveals how manufacturing complexity, clinical infrastructure requirements, and reimbursement pathways fragment commercial opportunity across distinct technical and delivery categories. Understanding these divisions illuminates where capital deployment yields differential returns.
Therapy Type:
Mature modalities with established infusion infrastructure coexist alongside emerging platforms requiring novel supply chains and workforce competencies.
- Monoclonal Antibodies:Engineered immunoglobulins targeting specific tumor antigens, manufactured through recombinant DNA technology in Chinese hamster ovary cell lines with purity thresholds exceeding 95 percent. Demand concentrates in the United States and Germany where infusion center networks and favorable reimbursement support high-volume administration of trastuzumab and rituximab analogs.
- Immunomodulators:Checkpoint inhibitors and cytokine modulators that amplify anti-tumor immune responses through PD-1/PD-L1 or CTLA-4 pathway blockade. Academic medical centers in China and the United States now deploy these as first-line interventions in melanoma and non-small cell lung carcinoma, compressing timelines for salvage chemotherapy.
- Interferons:Recombinant cytokine proteins with established manufacturing protocols but narrowing clinical utility as targeted alternatives displace them in renal cell carcinoma and melanoma protocols.
- Cancer Vaccines:Autologous or allogeneic cellular preparations designed to prime tumor-specific T-cell responses, constrained by individualized production workflows and limited durable response data in solid tumors.
- Oncolytic Virus:Genetically modified viral vectors that selectively replicate in and lyse malignant cells, requiring specialized biosafety containment and cold chain logistics that limit geographic reach.
- Hematopoietic Growth Factors:Colony-stimulating factors supporting neutrophil recovery following myelosuppressive chemotherapy, with demand tied to oncology protocol volume in outpatient infusion centers.
Monoclonal antibodies handle the majority of throughput; immunomodulators are gaining share fastest as checkpoint inhibitors expand into earlier treatment lines.
Therapy Indication:
Segmentation by tumor type tracks epidemiological burden, biomarker prevalence, and the maturity of companion diagnostic infrastructure across major solid malignancies.
- Breast Carcinoma:HER2-targeted biological therapies anchor adjuvant and metastatic protocols, with demand concentrated in tertiary hospitals with integrated pathology and infusion services.
- Lung Neoplasms:Non-small cell histologies drive biological therapy adoption where PD-L1 expression testing stratifies checkpoint inhibitor eligibility; small cell variants remain chemotherapy-dependent.
- Colorectal Adenocarcinoma:Anti-EGFR antibodies serve RAS wild-type populations, with molecular diagnostic capabilities determining addressable patient pools in the United States and Germany.
- Prostate Malignancies:Sipuleucel-T and radioligand therapies occupy niche positions where hormonal resistance emerges, constrained by specialized manufacturing and nuclear medicine infrastructure.
- Melanoma:BRAF/MEK inhibitor combinations and anti-PD-1 antibodies transformed survival curves, establishing this indication as the proving ground for immuno-oncology combination strategies.
- Gastric Tumors:HER2 testing and PD-L1 scoring now standard in academic centers, though biological therapy penetration lags breast and lung counterparts due to geographic variation in molecular diagnostic access.
Breast carcinoma commands the largest patient volume; lung neoplasms show the steepest expansion trajectory as screening programs enlarge early-stage detection pools.
End User Setting:
Site-of-care distribution reflects reimbursement differentials, capital equipment requirements, and the concentration of specialized clinical expertise.
- Specialized Clinics:Dedicated oncology infusion centers with pharmacy compounding capabilities and emergency response infrastructure for hypersensitivity reactions.
- Research Institutes:Academic medical centers with integrated phase I/II trial units, GMP-adjacent manufacturing facilities, and correlative science laboratories.
- Outpatient Treatment Centers:Community-based infusion suites capturing stable patients on maintenance biological therapy, optimizing against hospital outpatient department reimbursement.
- Rehabilitation Facilities:Post-acute settings managing biological therapy complications including immune-related adverse events requiring corticosteroid taper protocols.
- Diagnostic Laboratories:Reference sites with CLIA-certified companion diagnostic testing, NGS profiling, and minimal residual disease monitoring.
- Community Health Centers:Federally qualified sites expanding access in underserved geographies, constrained by 340B pricing complexity and limited cold chain capacity.
Specialized clinics process the majority of biological therapy encounters; outpatient treatment centers are expanding most quickly as payers drive site-of-care migration.
Delivery Technology:
Route of administration determines manufacturing formulation complexity, patient convenience trade-offs, and competitive differentiation through lifecycle management.
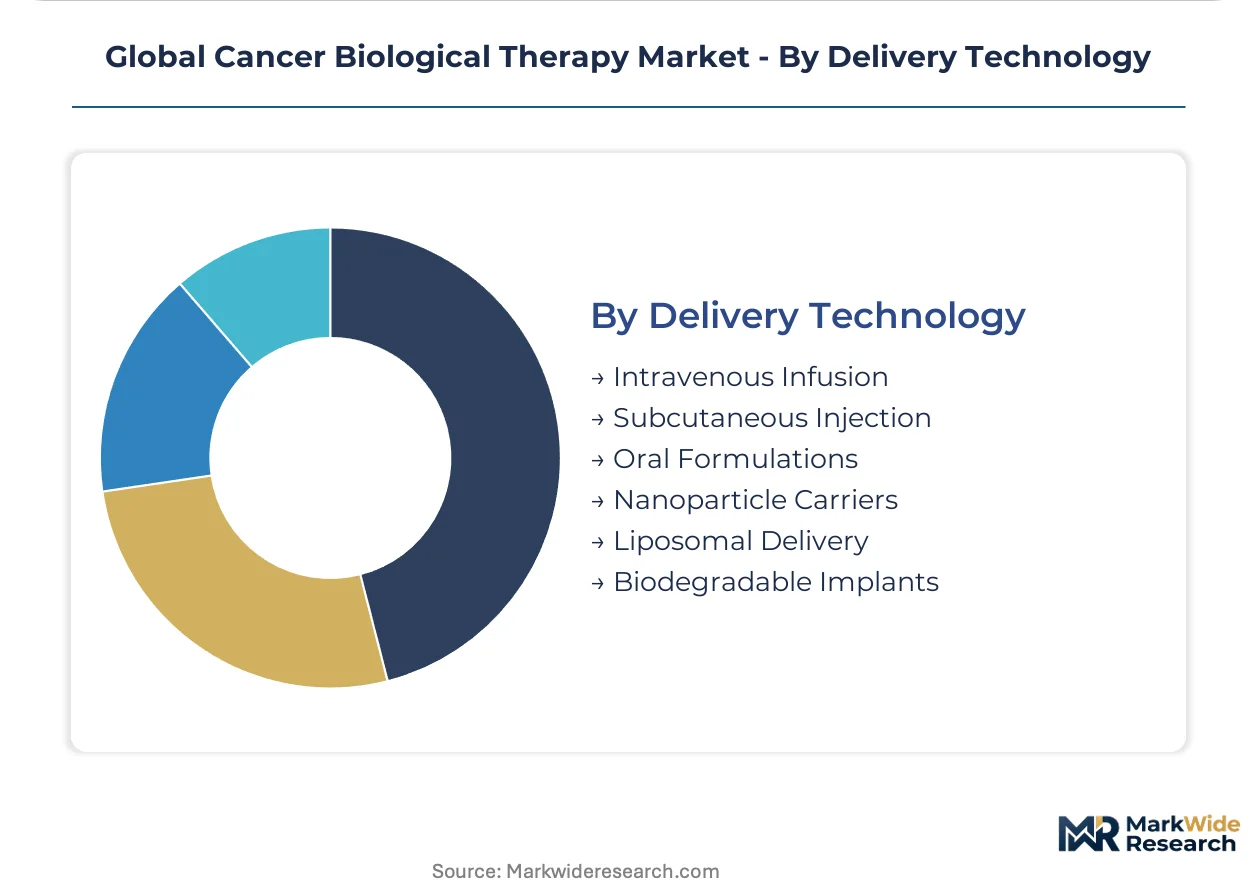
- Intravenous Infusion:Standard delivery for monoclonal antibodies and checkpoint inhibitors, requiring infusion center capacity that creates bottlenecks in high-volume markets.
- Subcutaneous Injection:Self-administration formulations bypassing facility constraints, with trastuzumab and rituximab hyaluronidase combinations gaining preference in the United States and Japan.
- Oral Formulations:Small molecule kinase inhibitors within broader biological therapy protocols, though distinct from protein-based modalities in manufacturing and distribution.
- Nanoparticle Carriers:Albumin-bound paclitaxel and emerging mRNA lipid nanoparticles enabling tumor penetration and reduced systemic toxicity.
- Liposomal Delivery:Encapsulated cytotoxics with altered pharmacokinetic profiles, extending utility of established agents through formulation innovation.
- Biodegradable Implants:Depot formulations under investigation for localized cytokine delivery, requiring surgical placement and retrieval protocols.
Intravenous infusion remains the dominant delivery mode; subcutaneous injection is climbing the fastest as manufacturers pursue differentiation through patient convenience and reduced healthcare utilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology departments at academic medical centers in the United States, China, and Germany anchor biological therapy procurement. Reimbursement frameworks and manufacturing infrastructure determine adoption velocity across concentrated demand clusters.
United States
The FDA's breakthrough therapy designation accelerates approval timelines for novel biologics, compressing development cycles. Medicare's coverage expansion under the IRA creates policy tailwinds for innovative oncology products. The Boston-Cambridge corridor concentrates CAR-T manufacturing and vector production facilities serving national distribution networks.
China
Domestic manufacturers leverage NMPA priority review pathways to file first-in-class biologics simultaneously with FDA submissions. The country's dual carbon goals pressure energy-intensive mammalian cell culture operations toward efficiency upgrades. Shanghai and Suzhou biotech clusters host integrated discovery-to-commercial infrastructure rivaling Western counterparts.
Germany
EMA centralized authorization under the MDR framework streamlines multi-market launches while AMNOG early benefit assessments impose mandatory price discounts. Hospital procurement consortia aggregate demand across academic centers, shifting purchasing power to regional buying groups. The Rhine-Main region anchors monoclonal antibody production with established CHO cell line supply chains.
Japan
PMDA accelerated review pathways align with aging population demand for subcutaneous self-administration formulations. METI industrial policy supports domestic biologics manufacturing to reduce import dependency. The Kanto region's tertiary hospitals integrate companion diagnostic testing with biological therapy protocols.
Switzerland
Swissmedic maintains stringent GMP enforcement while facilitating early access programs for breakthrough therapies. The country's concentrated supplier base for recombinant protein media and CHO cell lines creates strategic leverage over global production networks. Basel and Zurich host integrated pharmaceutical manufacturing and logistics hubs serving European markets.
Global Cancer Biological Therapy Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented therapeutic categories. The vendor base organizes into three tiers: integrated pharmaceutical conglomerates with discovery-to-commercial infrastructure, mid-scale biologics specialists with platform manufacturing capabilities, and emerging cell therapy developers with novel modality pipelines. Consolidation pressure intensifies as manufacturing scale requirements and regulatory compliance costs favor entities with established pharmacovigilance systems. Strategic moves center on M&A for manufacturing capacity and technology licensing for non-viral gene delivery platforms.
Within the integrated pharmaceutical tier, Bristol-Myers Squibb and Novartis occupy positions exemplifying end-to-end control over immuno-oncology portfolios. Roche anchors the companion diagnostic convergence archetype through alignment between targeted biological agents and biomarker testing infrastructure. These entities represent distinct competitive models: platform standardization versus diagnostic-therapy integration.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Novartis |
| Amgen |
| Pfizer |
| AstraZeneca |
| Gilead Sciences |
| Roche |
| BioNTech |
| Merck |
| Others |
Supply & Pricing Matrix
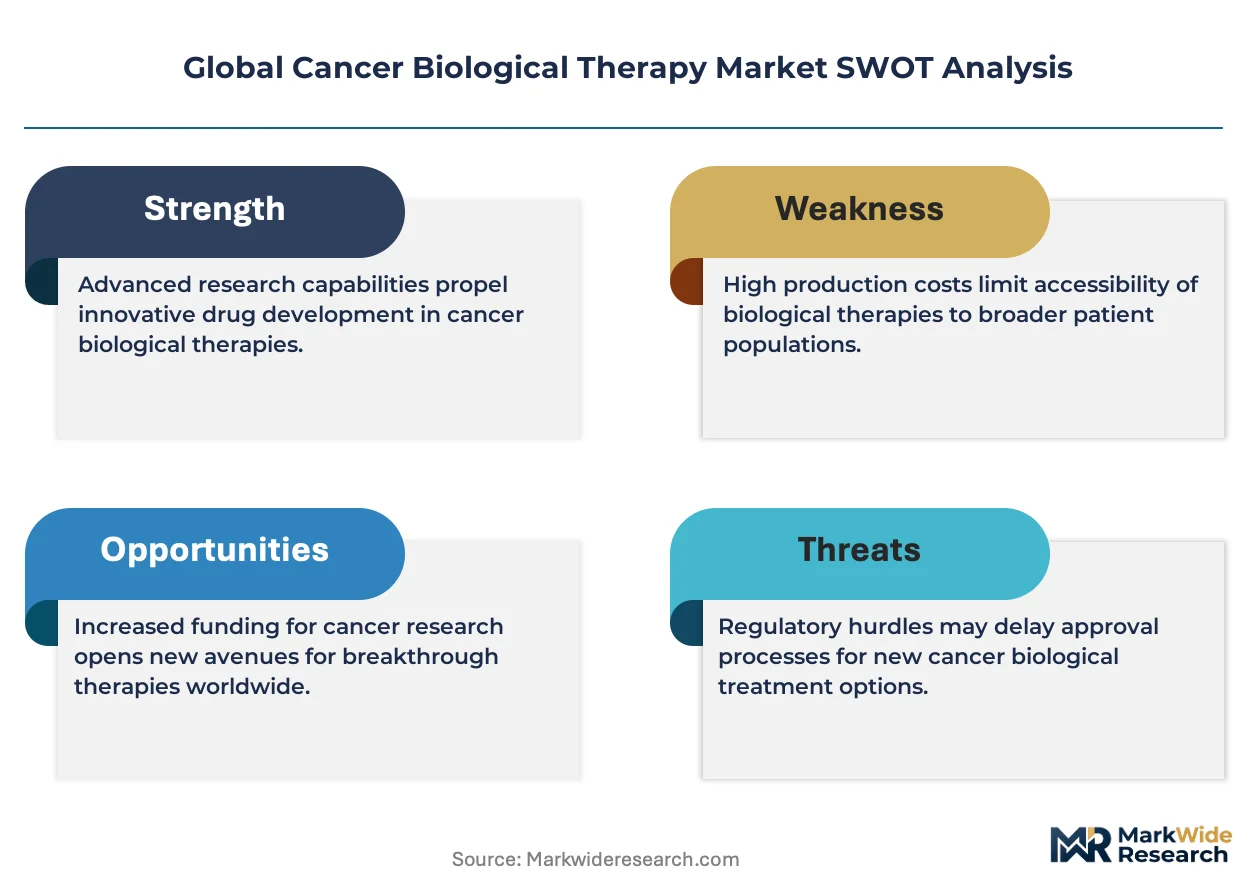
Single-source dependency on Chinese hamster ovary cell lines from Switzerland and Germany determines both the premium-to-standard pricing spread and the geographic clustering of bioreactor capacity. Contract manufacturers with validated CHO master cell banks command 40-60 percent price premiums over emerging entrants lacking equivalent lineage documentation.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate biological therapy procurement, tying list prices to recombinant protein media and fetal bovine serum commodity benchmarks. Price differentiation rests on GMP certification tier and cold chain assurance level, with FDA-validated facilities extracting premiums over EMA-equivalent counterparts. Cost compression in the biosimilar tier intensifies as the IRA's Medicare price negotiation provisions force originator discounting. Hospital procurement consortia in Germany exhibit highest price sensitivity; academic medical centers in the United States show lowest sensitivity where outcomes-based contracts insulate list prices.
Supply Chain Analysis
Export control regimes restricting gene synthesis equipment and viral vector production technology limit flows from the United States and Switzerland to Chinese manufacturing partners. Supply concentrates in Germany, Switzerland, and the United States for CHO cell lines, recombinant protein media, and GMP-grade aseptic processing equipment. Raw material dependencies include fetal bovine serum from Australia and New Zealand, single-use bioreactor bags from Ireland and Singapore, and chromatography resins from Sweden and Japan. Single-source vulnerability in CHO master cell bank supply creates structural risk. Distribution runs through specialized cold chain logistics providers with cryogenic capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological therapy markets fragment across modality complexity tiers, with the shift toward cell-based manufacturing creating specialist niches that generalist pharmaceutical conglomerates cannot efficiently serve.
For Market Incumbents: Harden manufacturing moats through captive CHO cell line development and bioreactor capacity expansion in the Boston-Cambridge corridor. Acquire non-viral gene delivery platform specialists to defend against electroporation-based transposon systems displacing lentiviral vectors. Lock in hospital procurement consortia through integrated real-world data collection capabilities that support HTA submissions.
For New Entrants and Emerging Players: Pursue subcutaneous formulation development for established monoclonal antibodies, where hyaluronidase combinations bypass infusion center bottlenecks in Japan and South Korea. Target CAR-T manufacturing partnerships with Singaporean contract development organizations to compress IND-to-clinic timelines. Lead with biosimilar interchangeability designation as the go-to-market angle under IRA Medicare price negotiation tailwinds.
For Investors and Strategic Acquirers: The market sits at a manufacturing-capacity-constrained phase that favors platform-technology specialists over asset-heavy integrated conglomerates. Five-to-ten year viability hinges on non-viral delivery modality maturation and automated cell therapy production scale. Acquisition target archetype: mid-scale biologics specialists with validated single-use bioreactor workflows and Singapore or Netherlands regulatory filing experience. Watch NMPA-FDA submission timing convergence as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Non-Viral Gene Delivery Platform Licensing | Electroporation-based transposon systems collapse lentiviral vector costs and compress autologous program timelines. |
| Companion Diagnostic Convergence | CDx-enabled patient stratification aligns reimbursement with biomarker-defined responder populations in heterogeneous tumors. |
| Subcutaneous Formulation Development | Self-administration biologics bypass infusion center constraints and open homecare channels in aging populations. |
| CHO Cell Line Backward Integration | Captive master cell bank development insulates against single-source supply vulnerability from Swiss and German suppliers. |
| Real-World Evidence Infrastructure | Integrated pharmacovigilance systems satisfy hospital procurement consortia requirements for HTA submission support. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up modeling of therapy-type volumes triangulated with top-down expenditure estimates from payer and provider financial disclosures.
Scenario-bracketing anchored projections across treatment line positioning, administration route adoption curves, and regional regulatory cluster divergence. Segmentation dimensions modeled include therapy modality, tumor indication, end-user setting, and delivery technology. CAGRs derived from epidemiological burden trajectories, protocol penetration assumptions, and pricing elasticity estimates. Forecast inputs incorporate biomarker prevalence shifts and reimbursement pathway evolution.
Macroeconomic conditions sit as an overlay; deviation in biotech capital availability and exchange rate volatility would shift the trajectory. Forecasts reflect documented assumptions on regulatory approval velocity and manufacturing scale-up success rates. Material shifts in FDA breakthrough therapy designation criteria or NMPA priority review pathway alignment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Alopecia Market
Specialty Medicine
Aarskog Syndrome Treatment Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Reactive Arthritis Treatment Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Dupuytrens Disease Market
Specialty Medicine
Nephroblastoma Therapeutics Market
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Pleurisy Market
Specialty Medicine
Global Liver Cancer Treatment Market
Specialty Medicine
United States Sports Medicine Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Fatty Liver Treatment Market
Specialty Medicine
Latin America Liver Cancer Treatment Market