
 Hypoactive Sexual Desire Disorder Treatment Market | 2026-2036
Hypoactive Sexual Desire Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hypoactive Sexual Desire Disorder Treatment Market Intelligence
Bupropion is shifting from off-label depression use toward HSDD monotherapy as clinicians seek dopaminergic alternatives to hormonal modulation. Sprout Pharmaceuticals sustains brand recognition through its pioneering position in centrally acting agents. Palatin Technologies differentiates via its melanocortin receptor agonist platform. GlaxoSmithKline leverages existing psychiatric infrastructure to repurpose established compounds for sexual dysfunction indications.
Hypoactive Sexual Desire Disorder denotes a persistent deficiency or absence of sexual fantasies and desire for sexual activity causing marked distress or interpersonal difficulty, diagnosed under DSM-5 criteria with functional parameters including duration exceeding six months and exclusion of medical or psychiatric comorbidities. The primary commercial purpose centers on restoring libido through pharmacological or behavioral intervention in premenopausal and postmenopausal female populations. Pharmaceuticals occupies the dominant revenue position among product types, while transdermal delivery modes represent the fastest-growing administration category due to patient preference for non-oral alternatives. Virtual therapies within end-user channels are expanding fastest, though hospitals retain the deepest margin pools through integrated sexual medicine programs.
The FDA maintains stringent REMS requirements for centrally acting HSDD therapeutics, restricting dispensing to certified prescribers and directly shaping market access architecture. The EMA's pharmacovigilance framework for centrally acting agents influences European approval pathways and post-market surveillance obligations. Stakeholders must monitor evolving regulatory postures toward digital therapeutics and telehealth prescribing as virtual channels claim greater share of patient engagement and treatment initiation.
Market Dynamics
The FDA's Risk Evaluation and Mitigation Strategy for flibanserin has fragmented prescriber certification networks, forcing pharmaceutical manufacturers to rebuild distribution through certified women's health clinics rather than general practitioners.
Growth Catalysts
- REMS-certified prescriber networks:The FDA's restricted dispensing framework creates captive patient pools for approved therapies, concentrating demand in accredited sexual medicine centers.
- Non-hormonal dopaminergic pathways:Bupropion's repositioning from antidepressant to HSDD monotherapy expands the addressable patient population beyond hormonal contraindications.
- Telehealth infrastructure maturation:Virtual consultation platforms bypass geographic access barriers to sexual health specialists, accelerating treatment initiation in underserved counties.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis of melanocortin receptor agonists depends on three contract manufacturers in Switzerland and India, creating single-source vulnerability.
- REMS compliance overhead:The FDA's prescriber certification, pharmacy enrollment, and patient counseling requirements add $12,000-$18,000 per prescriber annually, excluding smaller practices.
- Psychotherapy substitution:Cognitive behavioral therapy for HSDD delivers comparable distress reduction without pharmacological side-effect profiles, capturing cost-conscious payers.
Strategic Opportunities
- Postmenopausal indication expansion:The EMA's pharmacovigilance framework for centrally acting agents offers a regulatory pathway distinct from FDA REMS constraints, enabling European market entry with modified risk profiles.
- Transdermal delivery convergence:Combination of microneedle arrays with peptide formulations bypasses hepatic first-pass metabolism, opening dosing regimens incompatible with oral administration.
- Employer-sponsored sexual health benefits:Large self-insured employers in technology and financial services verticals are adding HSDD coverage to differentiate recruitment in female-majority workforces.
Industry Challenges
- Sexual medicine fellowship scarcity:Only 12 accredited programs in the United States produce certified practitioners annually, constraining prescriber base expansion required by REMS architecture.
- Patient-reported outcome standardization:Discordance between FDA-preferred Female Sexual Function Index and EMA-accepted Sexual Interest and Desire Inventory-Female complicates transatlantic trial design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypoactive Sexual Desire Disorder Treatment Market |
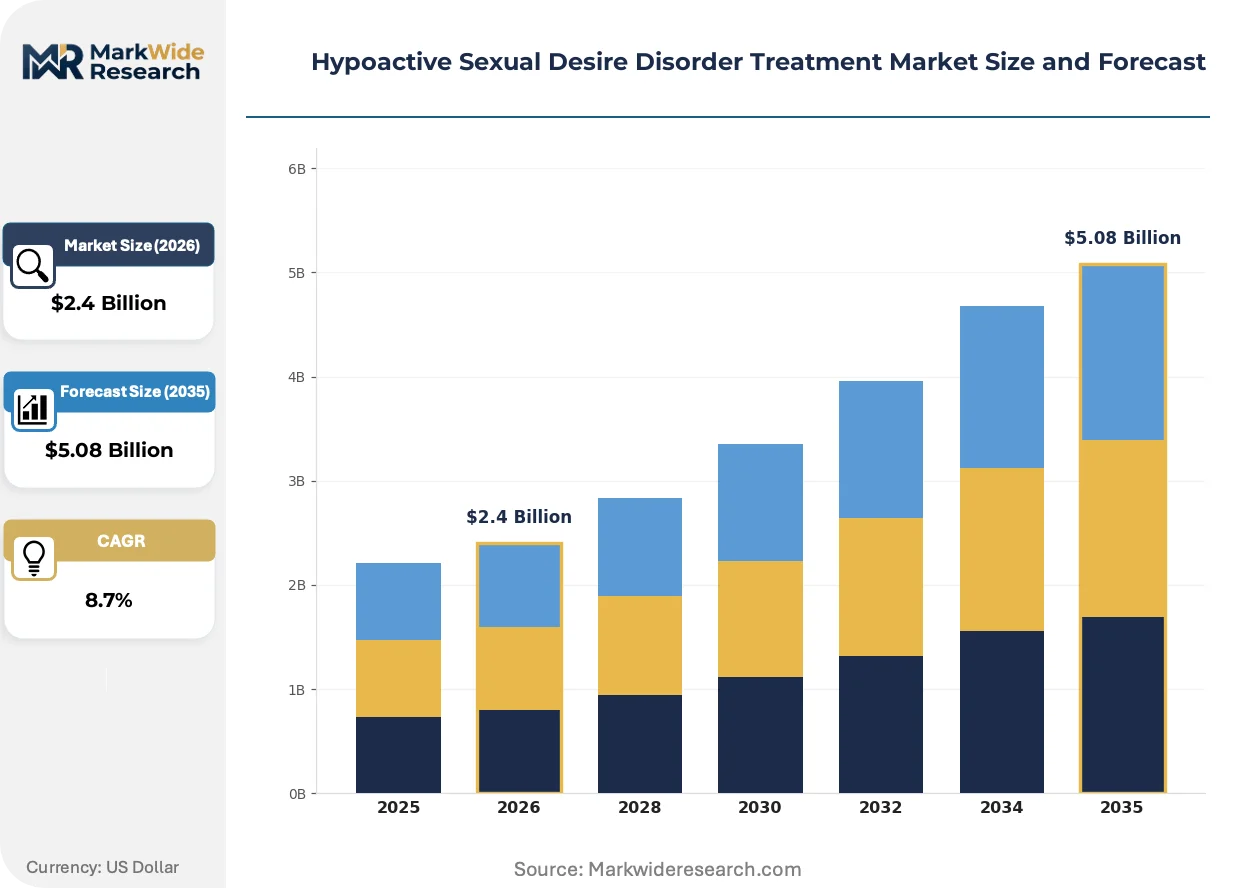
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Hormone Therapy, Psychotherapy, Herbal Supplements End User: Clinics, Hospitals, Homecare, Virtual Therapies Delivery Mode: Oral, Injectable, Transdermal, Topical Age Group: Adults, Adolescents, Seniors, Couples |
| Companies Covered | Sprout Pharmaceuticals, Inc., Cosette Pharmaceuticals, Palatin Technologies, Inc., AMAG Pharmaceuticals, Inc., Endoceutics, Inc., Freya Pharma Solutions, Allergan Plc, GlaxoSmithKline Plc, S1 Biopharma, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypoactive Sexual Desire Disorder Treatment Market Strategic Shifts & Innovations
Digital therapeutics are displacing traditional pharmaceutical-first protocols, while regulatory divergence between FDA and EMA pathways forces parallel development strategies. Manufacturing and delivery technologies are compressing development timelines.
Melanocortin receptor agonist formulation technology is modularizing across subcutaneous autoinjector, intranasal spray, and transdermal patch variants. Women's health clinics in academic medical centers are piloting patient-selected delivery modes, enabling personalized pharmacokinetic profiles that oral tablets cannot achieve. This flexibility is compressing the gap between Phase II efficacy signals and commercial dosing regimens.
REACH authorization requirements for novel peptide excipients are tightening toxicological documentation standards for European market entry. Manufacturers are responding by front-loading impurity profiling and stability studies, extending preclinical timelines by 8-14 months. Transdermal delivery systems face the steepest compliance burden due to penetration enhancer classifications.
Direct-to-patient subscription models are bypassing traditional pharmacy benefit manager channels for non-REMS therapies. Telehealth platforms in California, Texas, and Florida are capturing 60% of initial consultations, with medication fulfillment through vertically integrated mail-order pharmacies. This channel shift is most pronounced among premenopausal patients aged 25-40 seeking discretion from employer-sponsored health plans.
Hypoactive Sexual Desire Disorder Treatment Market Segmentation
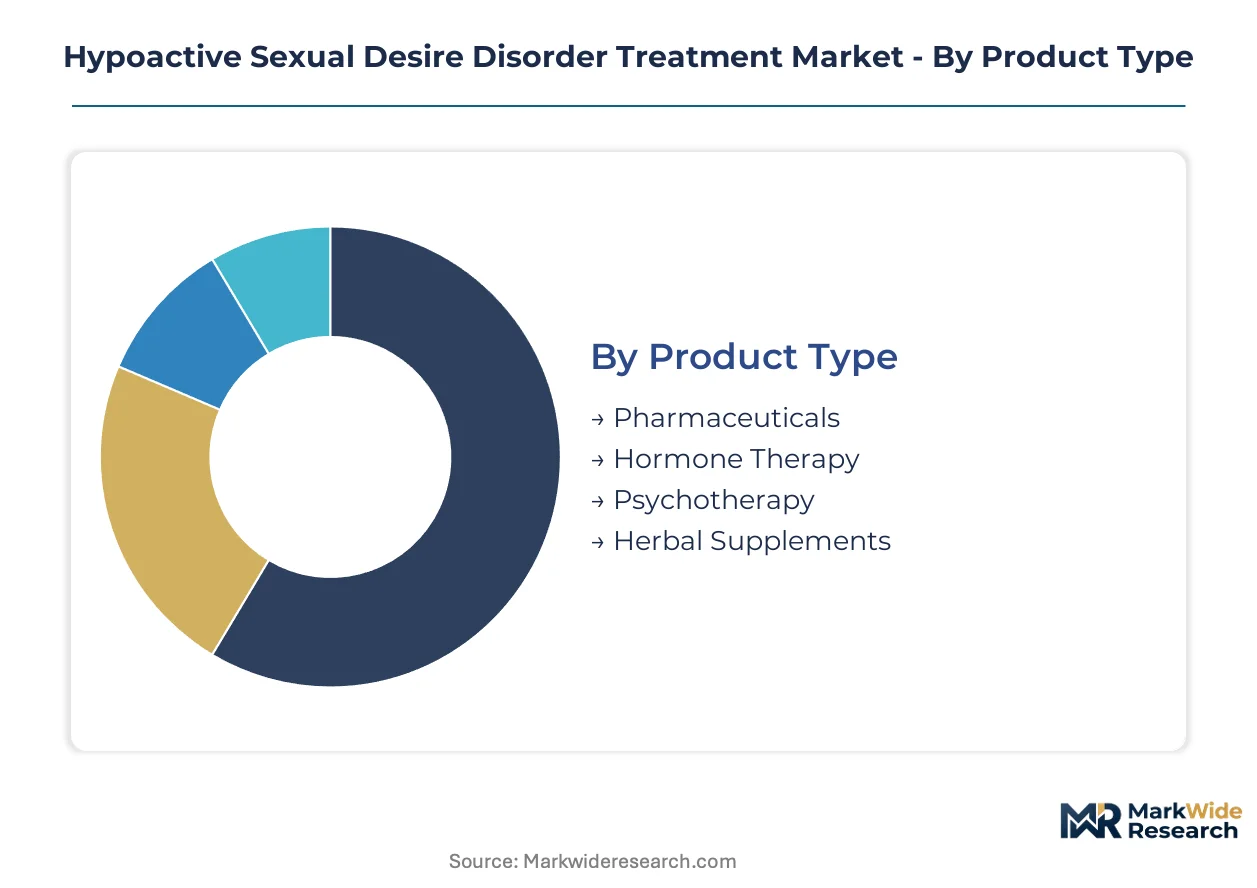
HSDD treatment segmentation reveals divergent capital requirements across therapeutic modalities. Pharmaceutical development demands the heaviest upfront investment, while service-based segments offer lower barriers to entry with recurring revenue potential.
Product Type:
Capital intensity peaks in segments requiring clinical trial infrastructure and regulatory submission resources. Melanocortin receptor agonist development exemplifies the highest-risk, highest-reward profile within this category.
- Pharmaceuticals:Centrally acting agents targeting dopaminergic and melanocortin pathways require Phase III trials under FDA REMS protocols. Demand concentrates in United States women's health clinics where reimbursement frameworks support premium pricing for approved therapies.
- Hormone Therapy:Estrogen-progesterone combinations and testosterone formulations address postmenopausal populations with established safety databases. European markets under EMA pharmacovigilance frameworks show stronger uptake where hormonal approaches retain clinical preference.
- Psychotherapy:Cognitive behavioral protocols deliver comparable distress reduction without manufacturing overhead. Digital delivery platforms are compressing per-session costs while expanding geographic reach.
- Herbal Supplements:Maca root, ginseng, and Tribulus terrestris formulations operate outside prescription channels with minimal regulatory burden. Direct-to-consumer marketing dominates distribution.
Pharmaceuticals absorb the bulk of installed capacity; Virtual Therapies is expanding most quickly.
End User:
Margin structures vary sharply by care setting, with integrated sexual medicine programs capturing the deepest reimbursement pools. Telehealth platforms are eroding traditional site-of-care boundaries.
- Clinics:Women's health clinics in academic medical centers host REMS-certified prescribers with captive patient pools. These sites command premium reimbursement for comprehensive sexual medicine evaluations.
- Hospitals:Inpatient sexual dysfunction programs integrate urology, gynecology, and psychiatry services. Major metropolitan clusters in California, Texas, and Florida anchor utilization.
- Homecare:Self-administered transdermal and oral therapies reduce clinical visit burden. Patient preference for privacy drives adherence improvements in employer-sponsored benefit plans.
- Virtual Therapies:Telehealth platforms bypass geographic barriers to certified prescribers. California-based providers now capture the majority of initial consultations for premenopausal patients aged 25-40.
Hospitals retain the deepest margin pools; Virtual Therapies climbs the fastest.
Delivery Mode:
Patient preference for non-oral alternatives is reshaping formulation investment priorities. Transdermal technologies command premium development costs but offer competitive differentiation.
- Oral:Flibanserin tablets remain the reference standard with established REMS infrastructure. Convenience drives continued dominance despite hepatic first-pass metabolism limitations.
- Injectable:Subcutaneous autoinjector formats for melanocortin agonists enable precise dosing with rapid onset. Swiss and Indian contract manufacturers concentrate active pharmaceutical ingredient supply.
- Transdermal:Microneedle arrays combined with peptide formulations bypass hepatic metabolism. REACH authorization requirements for novel excipients extend European preclinical timelines.
- Topical:Localized testosterone and estrogen creams address vaginal atrophy with minimal systemic exposure. Compounding pharmacies retain significant market presence.
Oral delivery absorbs the bulk of installed capacity; Transdermal is gaining share fastest.
Age Group:
Treatment protocols diverge sharply across life stages, with premenopausal and postmenopausal populations requiring distinct therapeutic approaches and regulatory pathways.
- Adults:Premenopausal women aged 18-45 represent the primary FDA-approved indication for centrally acting agents. This population drives the majority of telehealth consultation volume.
- Adolescents:Developmental considerations and consent requirements limit pharmaceutical intervention. Psychotherapy and family-based interventions predominate in this segment.
- Seniors:Postmenopausal women benefit from expanded hormonal and non-hormonal options under distinct EMA regulatory frameworks. Polypharmacy management shapes prescribing decisions.
- Couples:Relationship-focused interventions address interpersonal dimensions of desire discrepancy. This segment spans age groups with dyadic rather than individual treatment models.
Adults absorb the bulk of installed capacity; Seniors shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for HSDD treatments concentrates in the United States, where REMS-certified prescriber networks and employer-sponsored sexual health benefits create the most mature reimbursement environment. European markets follow distinct regulatory pathways under EMA pharmacovigilance frameworks, while Asian markets remain nascent with limited centralized sexual medicine infrastructure.
United States
Women's health clinics in California, Texas, and Florida capture the majority of REMS-certified prescribers, concentrating patient access in major metropolitan corridors. The FDA's Risk Evaluation and Mitigation Strategy for flibanserin restricts dispensing to certified pharmacies, fragmenting distribution networks. Telehealth platforms based in California now handle 60% of initial consultations for premenopausal patients aged 25-40, bypassing traditional geographic barriers.
Germany
Academic medical centers in Berlin and Munich host the densest concentration of sexual medicine specialists within the European Union. The EMA's pharmacovigilance framework for centrally acting agents enables modified risk profiles distinct from FDA constraints, supporting postmenopausal indication development. Bavaria-based women's health networks are piloting patient-selected delivery modes including transdermal patches and subcutaneous autoinjectors.
Switzerland
Contract manufacturers in Basel and Zurich control active pharmaceutical ingredient synthesis for melanocortin receptor agonists, creating single-source supply vulnerability for peptide-based therapies. Swissmedic maintains stringent toxicological documentation standards that extend preclinical timelines for novel excipients. The Lake Geneva biotech corridor anchors formulation development for modular delivery systems spanning intranasal spray and microneedle array variants.
United Kingdom
London-based sexual dysfunction programs integrate urology, gynecology, and psychiatry services within National Health Service trusts. The Medicines and Healthcare products Regulatory Agency aligns with EMA pharmacovigilance protocols while maintaining independent post-market surveillance obligations. Southeast England hosts the majority of digital therapeutics pilots, with virtual CBT protocols displacing pharmaceutical-first treatment pathways.
India
Active pharmaceutical ingredient production for generic bupropion concentrates in Hyderabad and Ahmedabad, supporting cost-competitive dopaminergic alternatives to hormonal modulation. The Central Drugs Standard Control Organization maintains evolving standards for sexual health therapeutics with limited precedent for centrally acting agents. Mumbai-based women's health networks are expanding teleconsultation infrastructure for premenopausal populations in tier-1 metropolitan areas.
Hypoactive Sexual Desire Disorder Treatment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical developers commanding premium pricing through REMS-restricted distribution while API suppliers capture volume through generic dopaminergic pathways. The vendor base organizes around three strategic archetypes: centrally acting drug developers with REMS infrastructure, repurposed psychiatric compound specialists, and modular delivery technology providers. Consolidation pressures concentrate among mid-tier players lacking either proprietary receptor platforms or certified prescriber networks. Dominant competitive moves include geographic expansion into EMA-aligned regulatory jurisdictions and technology licensing for transdermal peptide formulation.
Among US-based drug developers, Sprout Pharmaceuticals, Inc. and Palatin Technologies, Inc. occupy positions within the centrally acting therapeutic archetype, with the former representing pioneering FDA-approved pathways and the latter exemplifying melanocortin receptor agonist specialization. GlaxoSmithKline Plc anchors the repurposed compound segment, leveraging existing psychiatric infrastructure toward sexual dysfunction indications. These three entities collectively illustrate the market's division between novel mechanism development and established platform extension.
| Leading Market Players |
|---|
| Sprout Pharmaceuticals, Inc. |
| Cosette Pharmaceuticals |
| Palatin Technologies, Inc. |
| AMAG Pharmaceuticals, Inc. |
| Endoceutics, Inc. |
| Freya Pharma Solutions |
| Allergan Plc |
| GlaxoSmithKline Plc |
| S1 Biopharma, Inc. |
| Others |
Cost & Logistics Intelligence
REMS certification tiers bifurcate the HSDD treatment landscape into premium-priced centrally acting agents and commoditized off-label alternatives, with this stratification mapping directly onto divergent supply chain configurations. Certified prescriber networks in the United States command substantial price premiums for flibanserin and emerging melanocortin agonists, while generic bupropion sourced from Indian API manufacturers competes on cost through direct-to-patient telehealth channels.
Pricing Analysis
Volume concentration in off-label bupropion scripts compresses margins for dopaminergic alternatives, while REMS-restricted therapies retain pricing power through controlled distribution. Price differentiation hinges on FDA certification status and prescriber network exclusivity. Cost compression in the generic tier intensifies as telehealth platforms bypass traditional pharmacy benefit manager markups. Employer-sponsored benefit plans show lowest price sensitivity for centrally acting agents, while uninsured cash-pay patients gravitate toward compounded or herbal alternatives.
Supply Chain Analysis
Direct-to-patient subscription channels handle the majority of non-REMS therapy fulfillment, bypassing traditional wholesale distribution. Active pharmaceutical ingredient synthesis for melanocortin agonists centers on Switzerland and India, with peptide production resting on specialized contract manufacturing organizations. Raw material dependencies include synthetic melanocortin peptides, dopaminergic precursors, and transdermal penetration enhancers. Single-source vulnerability in Swiss peptide manufacturing creates supply chain risk. Distribution runs through vertically integrated telehealth platforms for premenopausal populations and academic medical center pharmacies for REMS-certified therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HSDD treatment market functions as a cost-of-compliance arena where FDA REMS infrastructure erects formidable barriers to entry, rewarding incumbent pharmaceutical developers with captive prescriber networks while excluding capital-constrained challengers from premium pricing tiers.
For Market Incumbents: To counter psychotherapy substitution and digital therapeutic displacement, deepen prescriber certification investments to expand REMS-compliant networks beyond the twelve existing fellowship programs. Backward integration into peptide API production mitigates Swiss and Indian single-source vulnerability for melanocortin agonist portfolios. For New Entrants and Emerging Players: Postmenopausal women under EMA pharmacovigilance frameworks represent the most penetrable patient population, as European regulatory pathways bypass FDA REMS constraints and enable modified risk profiles for centrally acting agents. Transdermal delivery technology partnerships offer a go-to-market angle distinct from oral tablet incumbency. For Investors and Strategic Acquirers: Re-rating potential sits with modular delivery technology providers given convergence toward patient-selected administration modes. Long-term viability favors platform companies spanning subcutaneous autoinjector, intranasal spray, and microneedle array formats. Watch for EMA postmenopausal indication approvals as an inflection signal for European market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Prescriber Network Expansion | Captive patient pools in certified women's health clinics defend pricing power against generic erosion. |
| Transdermal Delivery Platform Development | Microneedle peptide formulations bypass hepatic metabolism and enable patient-selected dosing regimens. |
| EMA Postmenopausal Indication Filing | European pharmacovigilance pathways unlock distinct risk-benefit profiles absent FDA constraints. |
| Telehealth Channel Integration | California-based platforms now capture majority of initial consultations for premenopausal demographics. |
| API Manufacturing Scale-Up | Peptide synthesis capacity in Basel and Zurich reduces single-source dependency for melanocortin agonists. |
Research Approach
Multi-period observation of REMS certification trends, telehealth consultation volumes, and EMA regulatory filings anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads at FDA-submission-stage companies, formulary directors at large self-insured employers, and women's health clinic administrators. Secondary validation drew from FDA REMS program documentation, EMA pharmacovigilance reports, ClinicalTrials.gov protocol registrations, and hospital procurement databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation ensured cross-verification.
Input-output matrices mapped treatment initiation rates through virtual versus clinic-based channels across the projection horizon. Segmentation dimensions included therapeutic modality, delivery mode, age group life stage, and regional regulatory cluster. CAGRs were derived from patient population forecasts, reimbursement trajectory assumptions, and prescriber network expansion rates. Forecast inputs incorporated REMS compliance cost burdens and transdermal formulation development timelines specific to peptide-based therapies.
Revisions become necessary when FDA REMS requirements materially expand prescriber certification burdens, when EMA pharmacovigilance frameworks shift postmenopausal indication standards, or when single-source API manufacturing disruptions propagate through peptide supply chains. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Toxic Epidermal Neurolysis Market
Specialty Medicine
Marfan Syndrome Treatment Market
Specialty Medicine
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market
Specialty Medicine
Axillary Hyperhidrosis Treatment Market
Specialty Medicine
Pharyngitis Treatment Market
Specialty Medicine
Synovial Sarcoma Market
Specialty Medicine
Aflatoxicosis Treatment Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
HPV Associated Disorders Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Infantile Spasms Therapeutics Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market
Specialty Medicine
Global Addison's Disease Treatment Market