
 Atrophic Vaginitis Treatment Market | 2026-2036
Atrophic Vaginitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Atrophic Vaginitis Treatment Market Outlook
EMA labeling requirements for vaginal estrogen products is hardening compliance costs for new entrants across European markets. Pfizer Inc. leverages its established manufacturing infrastructure to sustain supply continuity for topical estrogen formulations. Bayer HealthCare Pharmaceuticals Inc. competes through specialized intravaginal delivery systems that occupy premium positioning in gynecology practices.
Atrophic vaginitis treatment encompasses pharmaceutical and non-pharmaceutical interventions designed to restore vaginal epithelial integrity, maintain pH balance between 3.8 and 4.5, and alleviate symptoms of genitourinary syndrome of menopause. Estrogen Therapies dominate current prescription volumes due to established clinical efficacy, while Non-Hormonal Therapies are gaining fastest traction among patients with hormone-sensitive conditions. Intravaginal delivery modes command superior margin pools compared to oral and transdermal alternatives, reflecting formulation complexity and targeted tissue absorption advantages.
FDA oversight of hormone replacement therapies, EMA pharmacovigilance frameworks for vaginal products, and WHO menopause care guidelines collectively shape product development priorities and market access pathways. These regulatory bodies enforce bioequivalence standards, post-market surveillance obligations, and patient counseling requirements that influence prescribing behavior. Stakeholders must monitor evolving reimbursement policies for non-hormonal alternatives and anticipate how real-world evidence mandates will reshape competitive differentiation between established and emerging therapeutic categories.
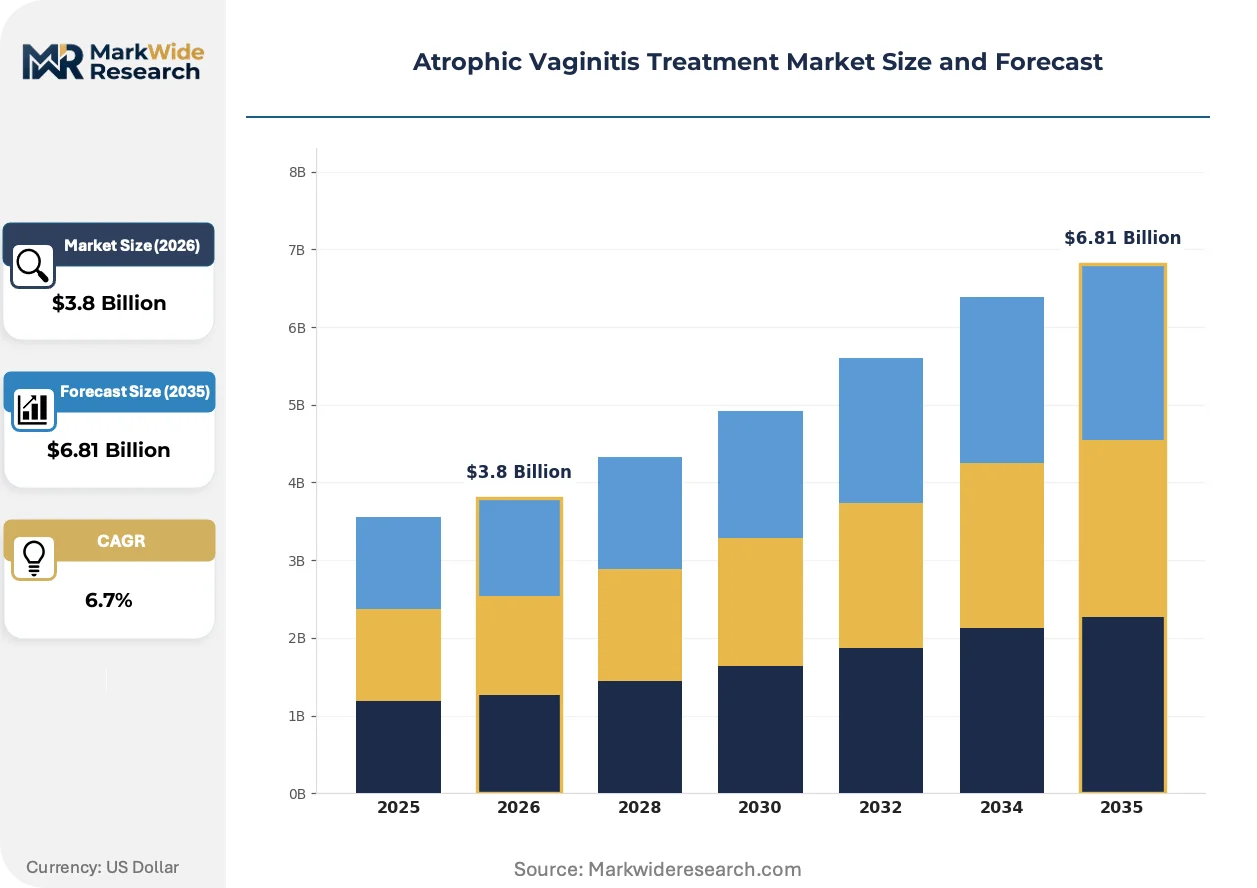
Market Dynamics
FDA's updated labeling guidance for vaginal estrogen products is compressing prescription protocols and forcing manufacturers to restructure patient counseling frameworks, reshaping competitive differentiation between hormonal and non-hormonal therapeutic categories.
Growth Catalysts
- Aging Demographics:United States census data shows expanding post-menopausal populations driving clinical visits to gynecology practices for genitourinary syndrome management.
- EMA Pharmacovigilance Frameworks:Stricter post-market surveillance obligations for vaginal products are elevating quality standards and filtering substandard competitors from European markets.
- Intravaginal Delivery Innovation:Specialized localized hormone delivery systems are capturing premium positioning through superior tissue absorption and reduced systemic exposure profiles.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of estradiol and estriol precursors concentrates among specialized chemical manufacturers in India and China, creating supply vulnerability.
- Regulatory Friction:WHO menopause care guidelines diverge from national formularies in several markets, complicating multi-country product registration strategies.
- Substitution Threat:Over-the-counter vaginal moisturizers and lubricants present lower-cost alternatives for patients with mild symptoms, limiting prescription conversion rates.
Strategic Opportunities
- Underpenetrated Rural Markets:United States telehealth platforms are extending menopause specialist access to underserved regions lacking dedicated gynecology clinics.
- Technology Convergence:Combination of pH-monitoring biosensors with hormone-releasing intravaginal rings enables real-time therapeutic adjustment and personalized dosing protocols.
- Reimbursement Tailwinds:Medicare Part D formulary expansions for non-hormonal alternatives are reducing out-of-pocket burdens and expanding addressable patient populations.
Industry Challenges
- Specialized Formulation Expertise:Lipid-based drug delivery science and mucoadhesive polymer chemistry require scarce talent pools, constraining R&D pipeline velocity.
- Bioequivalence Study Complexity:FDA mandates for pharmacokinetic bridging studies between reference listed drugs and generic alternatives extend development timelines and inflate clinical trial costs.
- Legacy System Integration:Electronic health record interoperability gaps between gynecology practices and pharmacy benefit managers fragment prescription fulfillment tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atrophic Vaginitis Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Estrogen Therapies, Non-Hormonal Therapies, Vaginal Moisturizers, Lubricants Delivery Mode: Topical, Oral, Transdermal, Intravaginal End User: Hospitals, Clinics, Home Care, Pharmacies Treatment Duration: Short-Term, Long-Term, Intermittent, Continuous |
| Companies Covered | Pfizer Inc., AbbVie Inc., Bayer HealthCare Pharmaceuticals Inc., Duchesnay, Shionogi, TherapeuticsMD, AMAG Pharmaceuticals, Mithra Pharmaceuticals, Endoceutics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atrophic Vaginitis Treatment Market Strategic Shifts
Non-hormonal therapeutic modalities are gaining structural momentum as patient preference shifts and regulatory scrutiny of systemic hormone exposure intensify across developed markets.
Hyaluronic acid-based vaginal moisturizers are expanding into prescription-adjacent positioning through clinical efficacy claims and gynecologist endorsement programs. United States gynecology practices increasingly recommend these formulations as first-line maintenance therapy between estrogen treatment courses. This expansion is compressing traditional over-the-counter category boundaries and forcing incumbent manufacturers to develop professional-channel distribution capabilities.
REACH authorization requirements for endocrine-disrupting chemical assessments are hardening raw material qualification standards for European vaginal product manufacturers. Suppliers must now submit extended safety data sets for excipients previously considered pharmacologically inert. Small and mid-sized formulation houses face compliance cost pressures that favor larger competitors with dedicated regulatory affairs infrastructure.
Patient-driven information seeking through digital health platforms is disrupting traditional physician-centric education models for menopause symptom management. Women aged 50-65 increasingly arrive at gynecology appointments with pre-formed treatment preferences based on peer community experiences and direct-to-consumer pharmaceutical advertising. United States markets exhibit the most pronounced behavioral shift, with online symptom trackers and telehealth triage services redirecting clinical visit patterns toward specialized menopause clinics.
Atrophic Vaginitis Treatment Market Segmentation
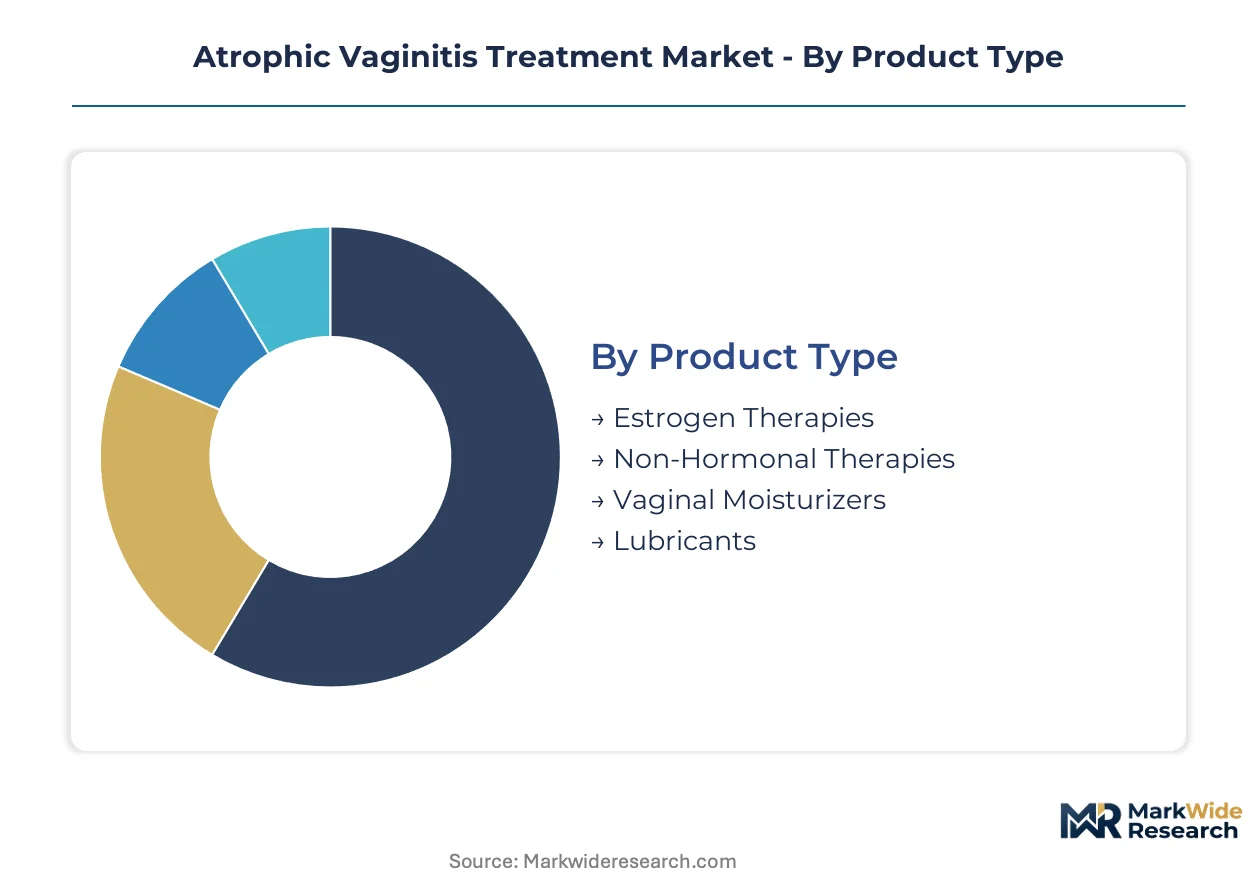
Atrophic vaginitis treatment segmentation reveals distinct capital requirements and margin profiles across therapeutic modalities. Product type and delivery mode configurations determine manufacturing infrastructure investments, while end-user channel strategies dictate commercialization complexity.
Product Type:
Estrogen Therapies command the highest upfront capital commitment due to API synthesis facilities, sterile manufacturing suites, and regulatory compliance infrastructure. Non-Hormonal Therapies require lower barrier-to-entry investments but face compressed margins from commodity competition.
- Estrogen Therapies:Estradiol and estriol formulations restore vaginal epithelial thickness through nuclear receptor activation. United States gynecology clinics prescribe these as first-line intervention for moderate-to-severe genitourinary syndrome, though FDA labeling revisions have tightened counseling protocols and extended prescriber liability.
- Non-Hormonal Therapies:Ospemifene and prasterone alternatives target estrogen-receptor modulation without systemic hormone exposure. Demand concentrates among breast cancer survivors and patients with thromboembolic risk profiles who cannot tolerate traditional hormone replacement.
- Vaginal Moisturizers:Hyaluronic acid and polycarbophil-based formulations maintain epithelial hydration through osmotic water retention.
- Lubricants:Water-based and silicone-based products provide symptomatic relief during intercourse without therapeutic tissue remodeling claims.
Most installed capacity flows through Estrogen Therapies. Expansion is steepest in Non-Hormonal Therapies.
Delivery Mode:
Intravaginal systems generate superior margin pools but require specialized formulation expertise in mucoadhesive polymer chemistry and controlled-release engineering. Oral and transdermal alternatives leverage existing tablet and patch manufacturing platforms with lower incremental investment.
- Intravaginal:Rings, tablets, creams, and gels achieve localized tissue concentrations with minimal systemic absorption. United States specialty pharmacies report highest fulfillment volumes for estradiol-releasing ring systems due to patient adherence advantages and reduced dosing frequency.
- Topical:Vaginal creams and gels require compounding capabilities or sterile fill-finish lines depending on prescription status.
- Oral:Systemic estrogen tablets face declining preference due to venous thromboembolism risk warnings in FDA labeling.
- Transdermal:Patches deliver estradiol through skin absorption but show limited adoption for vaginal-specific symptom relief.
Revenue concentrates in Intravaginal formats. Oral modalities are losing share fastest to localized alternatives.
End User:
Hospital and clinic channels demand field-based medical liaison teams and formulary negotiation infrastructure. Home care and pharmacy direct-to-patient models require digital marketing capabilities and telehealth integration investments.
- Clinics:Gynecology and menopause specialty practices drive prescription initiation through diagnostic workup and treatment counseling. United States telehealth platforms now extend specialist access to rural counties lacking physical clinic presence.
- Hospitals:Inpatient and surgical settings prescribe pre-operative vaginal estrogen for post-menopausal patients requiring pelvic procedures.
- Home Care:Self-administered regimens rely on patient education materials and adherence monitoring technologies.
- Pharmacies:Retail and specialty pharmacy networks manage prior authorization workflows and insurance coverage verification.
Prescription volume originates predominantly in Clinics. Home Care channels are expanding most quickly through direct-to-patient subscription models.
Treatment Duration:
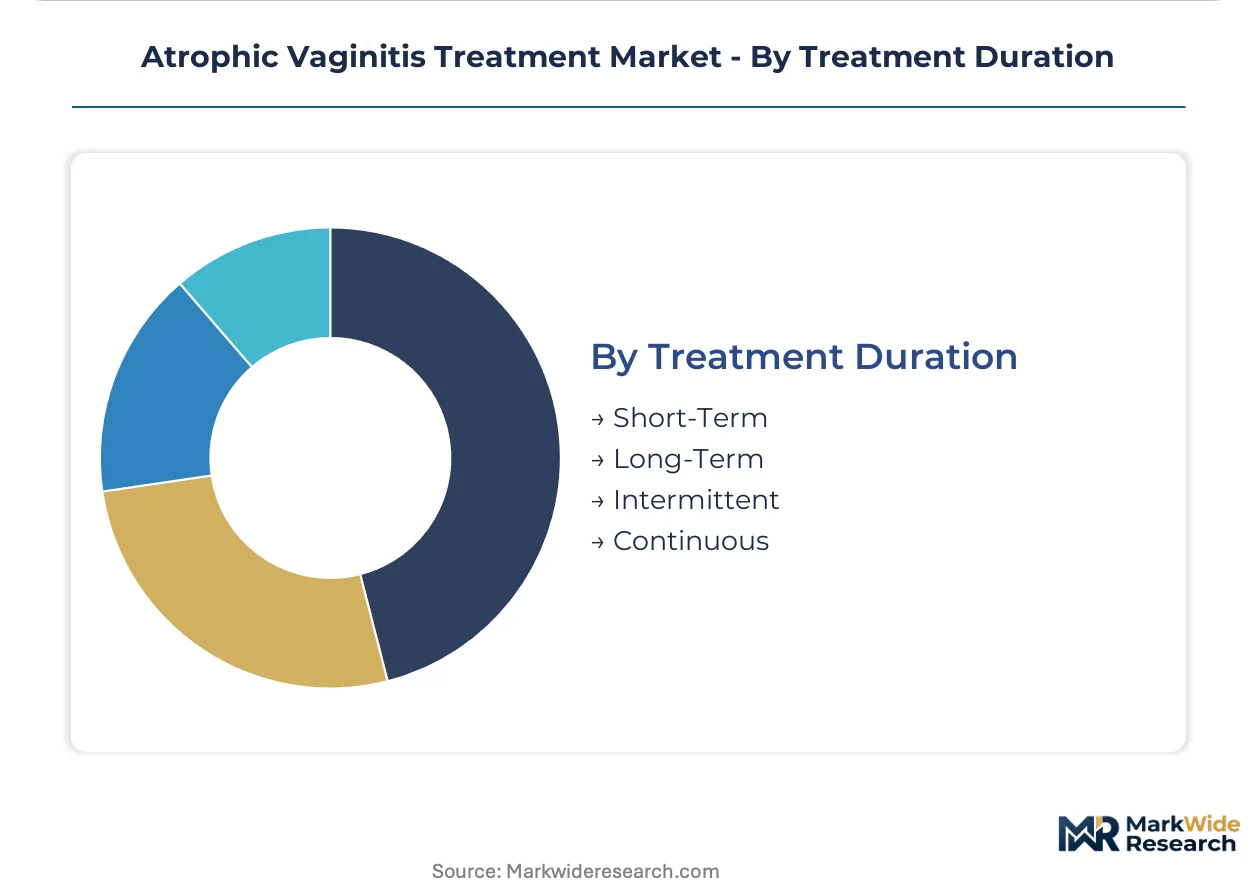
Continuous long-term regimens generate predictable recurring revenue but require patient retention programs and safety monitoring infrastructure. Intermittent and short-term protocols face higher churn and re-acquisition costs.
- Long-Term:Maintenance estrogen therapy continues indefinitely for post-menopausal patients without contraindications. United States Medicare Part D formularies increasingly cover these regimens with tiered copay structures.
- Continuous:Uninterrupted daily or weekly dosing maintains steady tissue estrogenization.
- Intermittent:Cyclic treatment pauses attempt to minimize cumulative hormone exposure.
- Short-Term:Limited-duration courses address acute symptom flares or peri-menopausal transition periods.
Patient-years accumulate fastest in Long-Term segments. Intermittent protocols are gaining traction among risk-averse patient populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized gynecology workforce clusters in the United States, Germany, and Japan anchor regional treatment capacity. Regulatory divergence between FDA, EMA, and PMDA frameworks shapes product registration strategies and market access timelines.
United States
Post-menopausal population expansion and telehealth platform proliferation drive clinical visit volumes. FDA labeling revisions for vaginal estrogen products tighten prescriber counseling obligations and reshape pharmacy fulfillment protocols. Gynecology practice clusters in Boston and New York Metro concentrate menopause specialist density and hormone therapy prescription initiation.
Germany
Aging demographics and statutory health insurance coverage for hormone therapies sustain prescription volumes. EMA pharmacovigilance frameworks enforce extended post-market surveillance for vaginal estrogen products. Pharmaceutical manufacturing infrastructure in North Rhine-Westphalia supports API synthesis and sterile formulation capacity for European distribution.
Japan
Declining birth rates and lengthening female life expectancy expand the addressable patient base for genitourinary syndrome management. PMDA guidelines for hormone replacement therapies mandate rigorous clinical endpoint documentation for new product approvals. Tokyo and Osaka metropolitan areas concentrate specialized gynecology clinics and menopause research centers.
United Kingdom
NHS menopause service expansion and hormone therapy shortage response protocols elevate treatment access priorities. MHRA alignment with EMA regulatory standards streamlines product authorization pathways. London and Southeast England clusters host tertiary gynecology referral centers and clinical trial sites.
India
Rising menopause awareness in urban centers and expanding private healthcare infrastructure drive diagnostic and treatment demand. CDSCO oversight of hormone formulations requires bioequivalence documentation for imported reference products. Maharashtra and Gujarat pharmaceutical manufacturing zones supply estradiol precursors and generic formulation capacity.
Atrophic Vaginitis Treatment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the atrophic vaginitis treatment landscape. Market structure tilts toward consolidation among established pharmaceutical manufacturers with existing gynecology therapeutic portfolios. Three archetypes dominate: vertically integrated API-to-formulation operators, specialized women's health pure-plays, and diversified Big Pharma divisions leveraging cross-therapeutic sales infrastructure. Competitive moves concentrate on strategic licensing arrangements for novel delivery technologies and geographic expansion through distribution partnerships in underpenetrated markets.
Within the diversified pharmaceutical tier, Pfizer Inc. and Bayer HealthCare Pharmaceuticals Inc. occupy positions reflecting established manufacturing infrastructure and multi-therapeutic sales force deployment. TherapeuticsMD exemplifies the specialized pure-play archetype with concentrated women's health portfolio positioning. Duchesnay represents the regional specialist model with focused European market presence. These three companies anchor distinct strategic approaches: scale-driven supply continuity, targeted therapeutic specialization, and geography-concentrated market development.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AbbVie Inc. |
| Bayer HealthCare Pharmaceuticals Inc. |
| Duchesnay |
| Shionogi |
| TherapeuticsMD |
| AMAG Pharmaceuticals |
| Mithra Pharmaceuticals |
| Endoceutics Inc. |
| Others |
Value Chain & Pricing Dynamics
Specialty gynecology practices and menopause clinic networks concentrate prescription volume and negotiate formulary placement, anchoring a pricing model that stratifies across premium intravaginal delivery systems, standard topical formulations, and economy-tier generic alternatives. This buyer concentration enables manufacturers to extract tiered margins while exposing commodity-grade suppliers to cost compression from pharmacy benefit manager rebate structures.
Pricing Analysis
Service bundling separates diagnostic counseling from product acquisition, with premium intravaginal ring systems commanding higher price points through prescriber education programs and adherence monitoring wraparounds. Price differentiation rests on FDA approval tier and localized delivery sophistication, with branded estradiol formulations holding margin advantage over compounded alternatives. Cost compression in the standard topical tier is intensifying because Medicare Part D formulary expansions for non-hormonal substitutes redirect volume toward lower-reimbursement categories. Hospital procurement committees exhibit highest price sensitivity due to bundled payment constraints, while cash-pay direct-to-patient subscription models show lowest elasticity.
Supply Chain Analysis
REACH authorization and FDA bioequivalence certification gate raw material qualification, filtering European and United States market participation toward established manufacturers with dedicated regulatory infrastructure. API synthesis concentrates in India and China, with sterile fill-finish capacity clustering in Germany and the United States. Estradiol and estriol precursor supply draws from specialized chemical manufacturers in Maharashtra and Gujarat pharmaceutical zones. Single-source vulnerability in estradiol precursor synthesis exposes formulation houses to import restriction risk. Distribution runs through specialty pharmacy networks and gynecology practice direct-purchase programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in this market stems from technology convergence between pH-monitoring biosensors and hormone-releasing intravaginal rings, enabling premium-tier subscription pricing for personalized dosing protocols.
For Market Incumbents: To counter substitution threat from over-the-counter vaginal moisturizers, Pfizer and Bayer should deepen prescriber education investments in genitourinary syndrome diagnostic protocols while securing backward integration into estradiol precursor supply through captive manufacturing agreements with Indian API specialists. For New Entrants and Emerging Players: Enter via United States telehealth platforms extending menopause specialist access to rural counties lacking physical gynecology clinic presence, targeting non-hormonal therapeutic modalities for breast cancer survivor populations. White-space concentration in technology-enabled personalized dosing systems offers the most penetrable entry angle. For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates with existing women's health portfolios are the most active acquirer in this space, seeking specialized intravaginal delivery technology platforms. Five-to-ten-year viability hinges on regulatory navigation capabilities and reimbursement strategy execution. Acquisition targets should demonstrate FDA submission readiness for novel localized hormone delivery systems. The signal to watch is Medicare Part D formulary expansion velocity for non-hormonal alternatives as volume-shift indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA 505(b)(2) submissions for intravaginal ring formulations accelerate market entry timelines. |
| Manufacturing Scale-Up | Sterile polymer extrusion capacity expansion in North Rhine-Westphalia supports European supply continuity. |
| Licensing Agreement | Mucoadhesive polymer chemistry patents from academic medical centers unlock formulation differentiation. |
| Reimbursement Strategy | Medicare Part D tier placement negotiations determine patient out-of-pocket cost exposure. |
| Pipeline Diversification | Ospemifene and prasterone development programs capture hormone-sensitive patient segments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with drug development executives, regulatory affairs leads, formulary directors at pharmacy benefit managers, and gynecology practice administrators with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare Part D formulary databases. Bottom-up prescription volume modeling and top-down therapeutic category sizing were triangulated to anchor market estimates.
Comparable historical periods anchored the projection horizon, with analytical frameworks segmenting by therapeutic modality, delivery mode, end-user channel, and regional regulatory cluster. CAGRs were derived from patient population expansion rates, prescription conversion assumptions, and reimbursement trajectory modeling. Forecast inputs incorporated FDA labeling revision impacts, EMA pharmacovigilance enforcement trends, and telehealth platform penetration curves.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-world evidence for non-hormonal therapeutic efficacy introduce uncertainty bands around prescription conversion assumptions. Forecasts reflect documented assumptions regarding aging demographic trajectories and reimbursement policy evolution. A model refresh is warranted upon material change in FDA vaginal estrogen labeling guidance or Medicare Part D formulary tier structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Soft Tissue Sarcoma Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Global Appendiceal Cancer Treatment Market
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
Polymyalgia Rheumatica Treatment Market
Specialty Medicine
Fibroadenoma Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Borderline Personality Disorder Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Necrotizing Fasciitis Treatment Market