
 Disinfection Equipment Market | 2026-2036
Disinfection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Disinfection Equipment Market Analysis
Skilled ultraviolet system engineering talent is bifurcating the competitive landscape, separating vendors that can design wavelength-optimized UV-C reactors from commodity assemblers. Xylem leverages its water infrastructure integration capabilities to bundle disinfection with pumping and analytics platforms. Trojan Technologies sustains technology leadership through proprietary medium-pressure lamp architectures that reduce energy intensity in municipal applications. Atlantium Technologies specializes in fiber-optic UV delivery systems that penetrate complex fluid geometries where conventional lamps fail.
Disinfection equipment encompasses engineered systems that inactivate or eliminate pathogenic microorganisms through physical, chemical, or thermal means, typically operating at UV-C wavelengths of 200–280 nanometers, hydrogen peroxide concentrations of 30–35% vapor phase, or ozone generation rates measured in grams per hour. These systems serve critical functions in water treatment loops, healthcare sterilization chains, and food safety protocols where microbial load reduction must achieve 4-log to 6-log elimination standards. Ultraviolet product types dominate installed base value due to lower operating chemistry costs and minimal byproduct formation, while vaporized hydrogen peroxide segments command premium pricing in pharmaceutical cleanroom and isolation chamber applications where residue-free validation is mandatory. Chemical disinfectant categories face margin compression from regulatory pressure on quaternary ammonium compound discharge limits, though they retain volume strength in hospitality and residential channels where capital barriers exclude UV or ozone capital expenditure.
The U.S. EPA regulates drinking water disinfection byproduct thresholds under the Stage 2 Disinfectants and Disinfection Byproducts Rule, compelling utilities to evaluate UV as an alternative to chlorine-based approaches. The EU F-Gas Regulation restricts certain fluorinated greenhouse gases used in thermal disinfection cooling systems, redirecting investment toward electrostatic spraying and fogging technologies with lower global warming potential footprints. China's NMPA and GB standards enforce sterility assurance levels for medical equipment reprocessing, creating compliance-driven replacement demand for automated washer-disinfector systems. Stakeholders must monitor how fragmented national certification requirements for UV dose validation reshape cross-border equipment procurement and service contract structures.
Market Dynamics
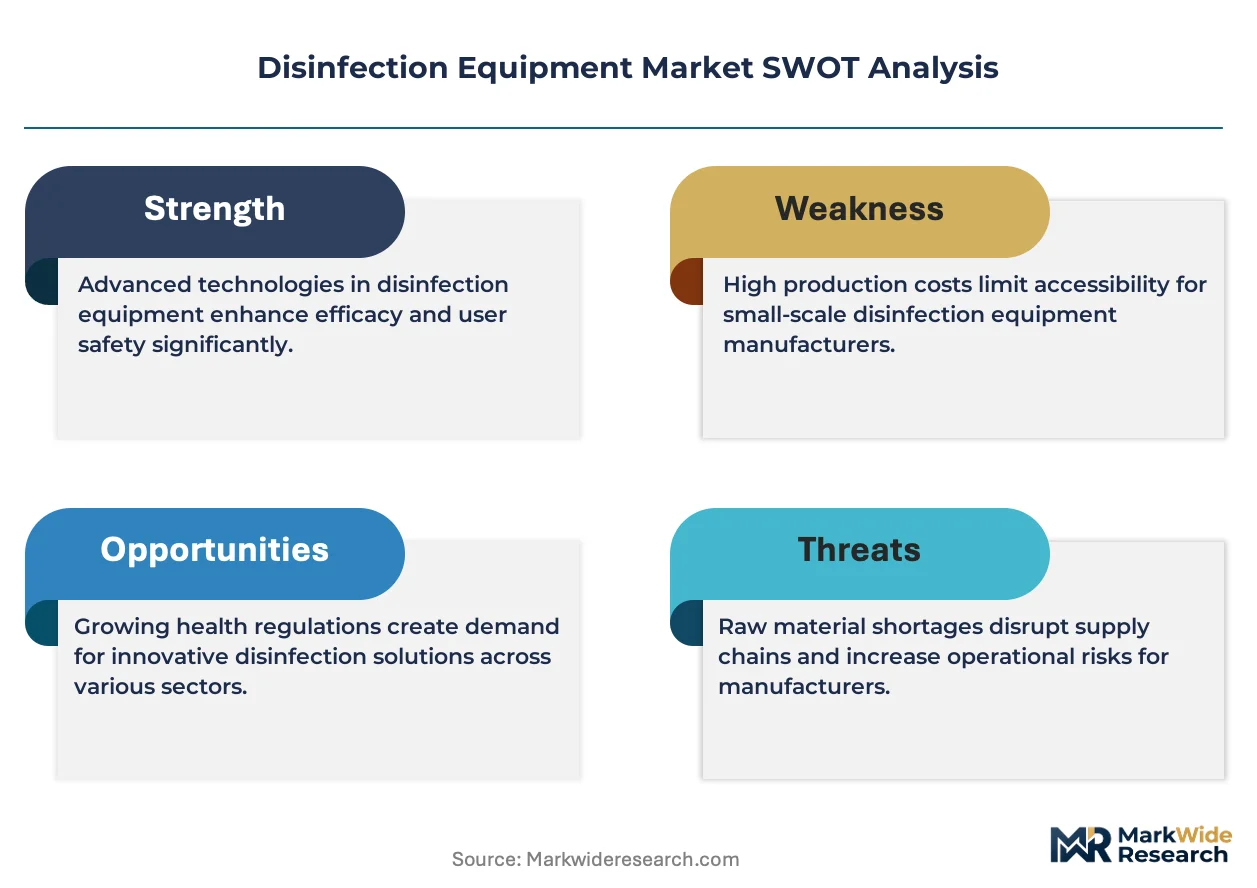
Post-pandemic institutional hygiene mandates are forcing healthcare and municipal water operators to replace legacy chlorine-based systems with UV-C and advanced oxidation technologies, compressing replacement cycles from 15-year intervals to 7-10 year refresh schedules.
Growth Catalysts
- EPA Stage 2 Disinfectants and Disinfection Byproducts Rule:US drinking water utilities face tightening trihalomethane and haloacetic acid limits, accelerating UV reactor installations as chlorine alternatives.
- Hospital infrastructure reinvestment:German healthcare facilities are deploying vaporized hydrogen peroxide systems in surgical suites and isolation chambers to meet enhanced sterility assurance protocols.
- UV-C LED wavelength optimization:Solid-state emitter advances at 265-275 nanometers are reducing mercury lamp dependency in point-of-use water treatment devices.
Market Restraints
- Mercury supply concentration:Medium-pressure UV lamp production depends on limited mercury refining capacity concentrated in China and Kyrgyzstan, exposing OEMs to raw material volatility.
- EU F-Gas Regulation thermal system restrictions:Fluorinated greenhouse gas phase-downs are forcing thermal disinfection equipment redesigns, extending R&D timelines and certification costs.
- Quaternary ammonium compound discharge limits:Wastewater treatment plants in Germany and France are rejecting chemical disinfectant effluents, compressing margins in hospitality and institutional cleaning segments.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO sterility requirements for active pharmaceutical ingredient production are creating demand for automated washer-disinfector and isolator systems in Hyderabad and Ahmedabad clusters.
- Electrostatic fogging convergence with IoT dosing:Precision application systems combining charged droplet physics with real-time concentration monitoring are penetrating food processing and cold chain logistics.
- China NMPA medical device reprocessing mandates:Provincial hospital consolidation under GB standards is forcing replacement of manual disinfection workflows with validated automated systems.
Industry Challenges
- UV dose validation engineering scarcity:Third-party biodosimetry testing capacity bottlenecks are extending equipment commissioning timelines for municipal water utilities.
- Legacy SCADA integration complexity:Water treatment plants running 1990s-era control architectures face retrofit costs exceeding 40% of new UV system capital expenditure.
- Cross-border certification fragmentation:Divergent national protocols for ozone generator electrical safety and UV lamp electromagnetic compliance are fragmenting supplier service contract structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disinfection Equipment Market |
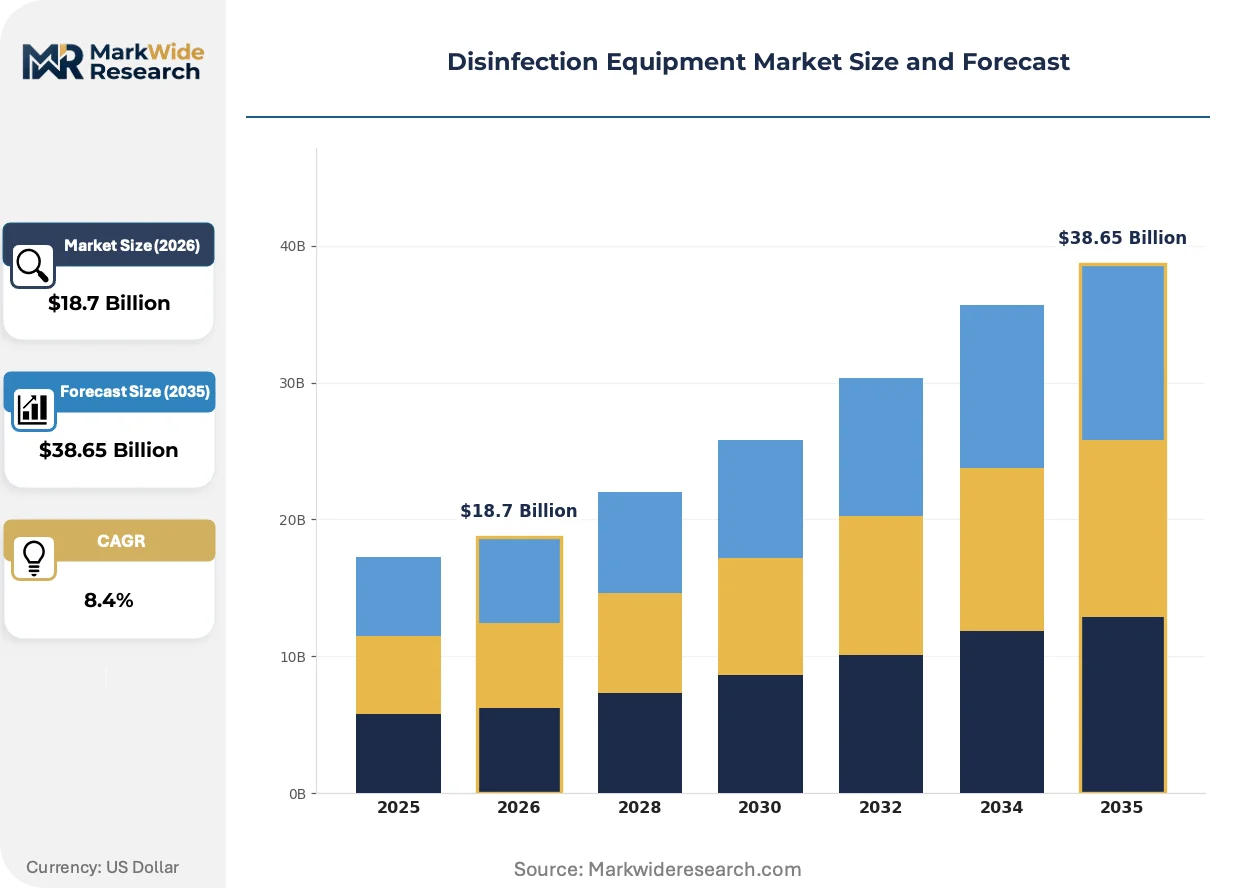
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultraviolet, Vaporized Hydrogen Peroxide, Ozone Generators, Chemical Disinfectants End User: Healthcare Facilities, Food Processing, Hospitality, Residential Users Application: Surface Disinfection, Air Purification, Water Treatment, Medical Equipment Sterilization Technology: Electrostatic Spraying, Fogging, UV-C Technology, Thermal Disinfection |
| Companies Covered | Xylem, Trojan Technologies, Halma, Atlantic Ultraviolet Corporation, Industrie De Nora, Advanced UV, American Ultraviolet, Atlantium Technologies, Hönle AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disinfection Equipment Market Emerging Trajectories
Equipment intelligence and wavelength-specific engineering are displacing commodity hardware configurations, while regulatory chemistry restrictions and service model unbundling reshape how buyers evaluate total cost of ownership across treatment modalities.
UV-C LED emitter technology is decomposing the installed base of low-pressure mercury amalgam lamps in residential and light commercial point-of-use applications. German and Japanese plumbing fixture manufacturers are embedding 275-nanometer diode arrays directly into faucet and showerhead assemblies. This solid-state transition is compressing aftermarket lamp replacement revenue streams while enabling form factors impossible with glass-tube architectures.
The EU Drinking Water Directive's revised microbial parametric values are compelling municipal utilities to validate 4-log virus inactivation through UV dose monitoring rather than proxy chlorine residual testing. French and Dutch water authorities now require continuous UV intensity sensors with automated flow modulation. Medium-pressure polychromatic systems are gaining share in combined sewer overflow applications where single-wavelength LED systems lack the spectral breadth for photoreactivation suppression.
Hospital sterilization departments are unbundling equipment capital expenditure from validation and maintenance services, treating disinfection systems as operational rather than capital budget line items. UK and Australian healthcare procurement frameworks now favor 10-year service contracts with guaranteed uptime and biological indicator pass rates. This shift is compressing upfront equipment margins while extending vendor cash conversion cycles and demanding field service network density that smaller OEMs cannot sustain.
Disinfection Equipment Market Segmentation
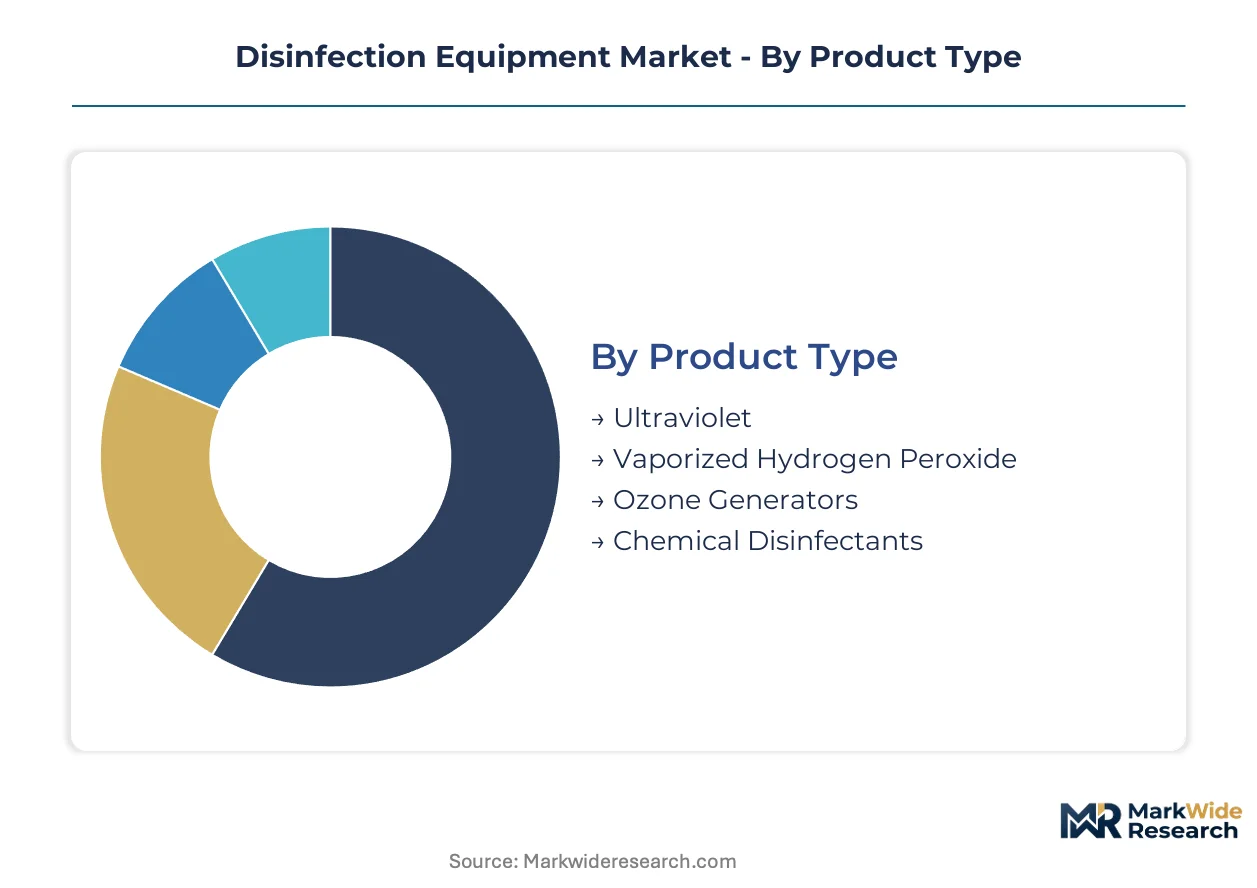
Disinfection equipment purchasing decisions pivot on pathogen elimination standards, capital constraints, and operational chemistry costs. Buyers segment choices across physical modalities, institutional settings, and compliance validation requirements rather than treating disinfection as a commodity category.
Product Type:
Substitution pressure intensifies where solid-state emitters threaten mercury-dependent architectures and chemical methods face effluent discharge restrictions.
- Ultraviolet:Systems operating at 200–280 nanometer wavelengths dominate municipal water treatment and healthcare surface protocols. German hospital networks and Dutch water utilities are replacing legacy chlorine trains with medium-pressure polychromatic reactors to meet EU Drinking Water Directive microbial parametric values.
- Vaporized Hydrogen Peroxide:Concentrations of 30–35% in vapor phase achieve residue-free sterilization for pharmaceutical isolators and surgical suites. Demand concentrates in German healthcare infrastructure reinvestment programs where sterility assurance levels must validate 6-log elimination.
- Ozone Generators:Production rates measured in grams per hour serve combined sewer overflow and food processing wash water applications.
- Chemical Disinfectants:Quaternary ammonium compound formulations face margin compression from French and German wastewater discharge limits.
Ultraviolet retains volume leadership; vaporized hydrogen peroxide holds the steepest expansion curve.
End User:
Capital budget scale and regulatory scrutiny intensity separate institutional procurement from consumer acquisition patterns.
- Healthcare Facilities:Hospitals and surgical centers deploy automated washer-disinfectors, UV-C tower robots, and vaporized hydrogen peroxide chambers. UK and Australian procurement frameworks now mandate 10-year service contracts with guaranteed biological indicator pass rates, compressing upfront equipment margins.
- Food Processing:Cold chain logistics and packaging lines integrate electrostatic fogging with real-time concentration monitoring to manage listeria and salmonella protocols.
- Hospitality:Hotels and commercial kitchens rely on chemical disinfectant programs where capital barriers exclude UV or ozone expenditure.
- Residential Users:Point-of-use UV-C LED faucet attachments and countertop ozone generators serve kitchen and shower applications.
Healthcare facilities command the highest validation standards; residential channels are climbing fastest as solid-state costs decline.
Application:
Log reduction requirements and exposure geometry complexity determine technology selection across treatment targets.
- Surface Disinfection:UV-C tower systems and electrostatic sprayers address horizontal and vertical plane coverage in patient rooms and food preparation areas.
- Air Purification:Upper-room UVGI and bipolar ionization systems target airborne pathogen loads in densely occupied spaces.
- Water Treatment:UV reactor validation for 4-log virus inactivation now supersedes proxy chlorine residual testing under French and Dutch authority mandates.
- Medical Equipment Sterilization:Automated washer-disinfector workflows with thermal and chemical phases replace manual reprocessing in China NMPA-compliant provincial hospitals.
Water treatment carries the heaviest regulatory burden; medical equipment sterilization is expanding most quickly through compliance-driven replacement cycles.
Technology:
Energy intensity and global warming potential metrics are redirecting R&D investment away from thermal and fluorinated gas approaches.
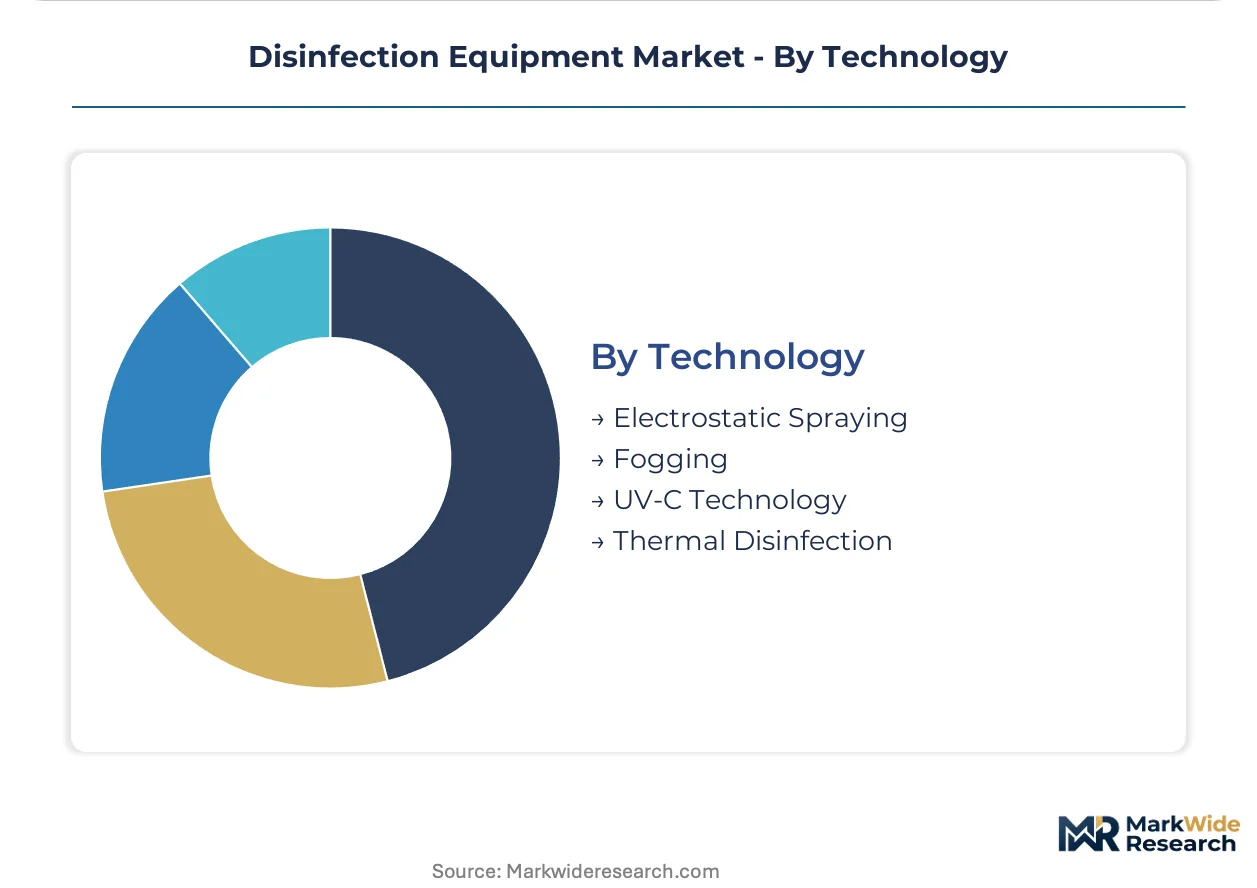
- Electrostatic Spraying:Charged droplet physics combined with IoT dosing monitors enables precision application in food processing and cold chain logistics.
- Fogging:Hydrogen peroxide and peracetic acid mist systems achieve whole-room decontamination in pharmaceutical cleanrooms.
- UV-C Technology:Medium-pressure polychromatic lamps and 265–275 nanometer LED arrays compete for wavelength-optimized reactor designs.
- Thermal Disinfection:Steam and dry heat systems face EU F-Gas Regulation redesign costs from fluorinated greenhouse gas phase-downs.
UV-C technology anchors installed base value; electrostatic spraying is gaining share fastest through convergence with precision agriculture and logistics automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys vaporized hydrogen peroxide systems for pharmaceutical sterility validation, while India concentrates UV reactor demand in municipal water infrastructure. China drives automated medical equipment sterilization through hospital consolidation mandates.
United States
EPA Stage 2 Disinfectants and Disinfection Byproducts Rule enforcement compels drinking water utilities to replace chlorine trains with UV-C reactors. Trihalomethane and haloacetic acid limits tighten annually. Municipal procurement concentrates in California and Texas water districts where combined sewer overflow drives medium-pressure polychromatic installations.
Germany
Hospital infrastructure reinvestment programs accelerate vaporized hydrogen peroxide deployment in surgical suites and isolation chambers. EU F-Gas Regulation restricts fluorinated greenhouse gases in thermal disinfection cooling systems. Industrial sterilization upgrades cluster in Baden-Württemberg pharmaceutical manufacturing corridors.
China
NMPA medical device reprocessing mandates force provincial hospital consolidation to replace manual disinfection workflows. GB standards enforce sterility assurance levels for equipment reuse. Automated washer-disinfector demand concentrates in Yangtze River Delta medical device manufacturing hubs.
India
CDSCO sterility requirements for active pharmaceutical ingredient production drive demand for isolator and automated washer-disinfector systems. Centralized procurement under national health missions expands UV water treatment in rural districts. Hyderabad and Ahmedabad pharmaceutical clusters anchor equipment deployment.
France
Revised EU Drinking Water Directive microbial parametric values mandate continuous UV intensity sensors with automated flow modulation. ANSM enforces hospital sterility protocols that favor validated automated systems over chemical alternatives. Water authority procurement concentrates in Paris and Lyon metropolitan utilities.
Disinfection Equipment Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in disinfection equipment supply. Water infrastructure conglomerates bundle UV reactors with pumping and analytics platforms, while wavelength-engineering specialists command premium positioning in municipal and pharmaceutical applications. Three archetypes dominate: integrated water technology platforms, UV-C wavelength optimization houses, and vaporized hydrogen peroxide validation specialists. Competitive moves concentrate on strategic partnerships for IoT dosing integration and geographic expansion into pharmaceutical manufacturing corridors.
Within the wavelength-engineering tier, Atlantium Technologies and Trojan Technologies exemplify specialized reactor architectures, while Xylem anchors the integrated platform category. Atlantium Technologies occupies a position among fiber-optic UV delivery specialists. Trojan Technologies represents medium-pressure lamp optimization for energy-intensive municipal applications. Xylem exemplifies the bundled infrastructure model combining disinfection with pumping and analytics. Halma sits within the safety-critical instrumentation cluster that supplies validation monitoring for regulated environments.
| Leading Market Players |
|---|
| Xylem |
| Trojan Technologies |
| Halma |
| Atlantic Ultraviolet Corporation |
| Industrie De Nora |
| Advanced UV |
| American Ultraviolet |
| Atlantium Technologies |
| Hönle AG |
| Others |
Supply Flow & Price Mechanics
Mercury lamp fabrication scale economies in China and Kyrgyzstan concentrate medium-pressure UV reactor production among three dominant OEMs, compressing price floors for commodity systems while wavelength-engineering specialists defend premium positioning through proprietary fiber-optic and polychromatic architectures.
Pricing Analysis
Long-term service contracts with guaranteed uptime clauses now dominate healthcare procurement, displacing capital-expenditure models in UK and Australian hospital systems. Price differentiation separates validated 6-log sterility assurance systems from commodity UV towers lacking biodosimetry certification. Cost compression in chemical disinfectant tiers is intensifying because French and German wastewater discharge limits reject quaternary ammonium effluents. Residential point-of-use buyers exhibit highest price sensitivity, while pharmaceutical isolator operators accept 40-60% premiums for residue-free vaporized hydrogen peroxide validation.
Supply Chain Analysis
China and Kyrgyzstan anchor mercury refining and lamp glasswork for medium-pressure UV systems, while Germany and Japan concentrate solid-state LED emitter fabrication. Raw material flows draw from rare earth phosphor deposits in Myanmar, quartz tubing from Heraeus German operations, and aluminum heat sinks from Vietnamese extrusion plants. Single-source vulnerability concentrates in mercury cell production, where two refineries supply 70% of global lamp demand. Distribution runs through water infrastructure integrators bundling disinfection with pumping and analytics platforms, plus direct OEM relationships for pharmaceutical validation systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as hospital procurement frameworks mandate 10-year service contracts with IoT-integrated dosing validation, shifting vendor value capture from equipment margins to recurring uptime guarantees.
For Market Incumbents: Secure wavelength-engineering talent pools in Germany and the Netherlands to defend against UV-C LED substitution threatening mercury lamp revenue streams. Deepen backward integration into fiber-optic quartz supply through captive sourcing agreements with Heraeus or Schott AG, insulating against rare earth phosphor volatility. Fortify field service network density in Yangtze River Delta hospital clusters to meet China NMPA compliance-driven replacement demand. For New Entrants and Emerging Players: Anchor in Indian pharmaceutical manufacturing corridors around Hyderabad and Ahmedabad, where CDSCO sterility requirements for active pharmaceutical ingredient production outpace established vendor service capacity. Target electrostatic fogging convergence with cold chain logistics automation, exploiting precision agriculture adjacencies where incumbent disinfection OEMs lack software competency. Pursue white-label partnerships with German plumbing fixture manufacturers embedding 275-nanometer diode arrays into residential faucet assemblies. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors wavelength-optimization specialists with proprietary reactor geometries over commodity lamp assemblers, as UV-C LED transition devalues mercury-dependent installed bases. Long-term viability across the projection horizon rests on service contract annuity streams rather than equipment shipment volumes. Monitor China provincial hospital consolidation velocity under GB standards as the decisive inflection signal for automated washer-disinfector demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IoT-Integrated Dosing Platform Development | Enables real-time concentration monitoring for electrostatic fogging in food processing cold chains. |
| Backward Integration into Quartz Fiber Supply | Secures captive sourcing for Atlantium-style fiber-optic UV delivery architectures. |
| Hospital System Partnership Expansion | Locks in 10-year service contracts with guaranteed biological indicator pass rates under UK procurement frameworks. |
| CE Marking Pathway for UV-C LED Systems | Validates 265-275 nanometer emitter compliance under EU Drinking Water Directive microbial parametric values. |
| Geographic Manufacturing Footprint in India | Positions local assembly capacity for CDSCO-compliant pharmaceutical isolator demand in Hyderabad clusters. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA enforcement actions, EU F-Gas Regulation implementation reports, and China NMPA medical device reprocessing guidance. Interviews with municipal water utility planning officers, hospital biomedical engineers, pharmaceutical manufacturing quality directors, and UV reactor OEM product managers inform demand-side validation. Secondary sources include FDA 510(k) clearances for automated washer-disinfectors, CDSCO sterility guidance documents, and customs data on mercury lamp imports. Bottom-up equipment shipment estimates triangulate against top-down healthcare capital expenditure surveys and water infrastructure investment databases.
Segmentation dimensions modeled span physical modality (ultraviolet, vaporized hydrogen peroxide, ozone, chemical), end-use institution (healthcare, food processing, hospitality, residential), application target (surface, air, water, medical equipment), and technology architecture (electrostatic, fogging, UV-C LED, thermal). CAGRs derive from log-linear trend fitting across historical replacement cycle data and regulatory compliance-driven acceleration scenarios. Industry-specific inputs incorporate UV dose validation engineering scarcity premiums and EU F-Gas Regulation thermal system redesign cost pass-through estimates.
Material uncertainties — mercury supply disruption, UV-C LED cost-parity acceleration, and fragmented national certification protocol divergence — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory enforcement intensity and hospital procurement framework stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Global Biofilms Treatment Market
Infection Control
Global Disinfection Robots Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
UV Sterilizer Pouch Market
Infection Control
Catheter-Related Bloodstream Infections (Crbsis) Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Sterilization Equipment and Disinfectant Market
Infection Control
Virus Filtration Market
Infection Control
Healthcare Protective Masks Market
Infection Control
Global Infection Prevention Devices Market
Infection Control
Australia Hand Sanitizer Market
Infection Control
Global Pseudomonas Aeruginosa Infection Treatment Market
Infection Control
Antimicrobial Wipes Market
Infection Control
Sterilization Monitoring Market
Infection Control
Germicidal UV Lamp Market
Infection Control
Infection Control Supplies Market