
 Global Skin Antiseptic Products Market | 2026-2036
Global Skin Antiseptic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Skin Antiseptic Products Market Foresight
Chlorhexidine gluconate is restructuring cost-performance trade-offs across surgical prep portfolios as hospitals seek lower-residue alternatives to iodophors. Ecolab Inc. leverages its institutional hygiene infrastructure to dominate North American hospital contracts. Johnson & Johnson anchors consumer-facing antiseptic segments through retail pharmacy channels. 3M Company specializes in film-forming delivery systems that extend skin adhesion during lengthy procedures.
Skin antiseptic products are topical antimicrobial formulations, typically containing chlorhexidine, iodine complexes, or alcohol concentrations between 60% and 90%, designed to reduce microbial flora on intact skin prior to invasive procedures. Alcohol-based solutions achieve rapid bactericidal action within 30 seconds, while chlorhexidine provides persistent residual activity lasting up to 48 hours. Hospitals represent the most mature end-user segment with established group purchasing contracts, though ambulatory surgical centers are expanding fastest as outpatient procedure volumes rise. Preoperative preparation commands the largest application share due to mandatory surgical site infection bundles, while wound care applications are gaining traction in home healthcare settings.
FDA premarket notification requirements and EMA Medical Device Regulation classification shape formulation standards and clinical evidence thresholds for market access. The EPA regulates antimicrobial claims for non-medical skin antiseptics, creating a dual-track compliance environment in the United States. Stakeholders must monitor evolving EU Green Deal chemical restrictions and state-level hospital sustainability mandates that could favor biodegradable excipient systems over conventional formulations.
Market Dynamics
Hospital procurement departments are consolidating antiseptic purchasing under stricter surgical site infection bundles, forcing suppliers to restructure pricing around volume guarantees and clinical outcome metrics rather than per-unit transactions.
Growth Catalysts
- FDA Preoperative Preparation Standards:Updated guidance on skin antisepsis prior to surgery mandates alcohol-based formulations in most inpatient settings, expanding hospital formulary placement for compliant suppliers.
- Ambulatory Surgical Centers:Outpatient procedure volumes are accelerating demand for rapid-drying, single-use applicators designed for high-throughput environments with limited sterilization infrastructure.
- Chlorhexidine Residual Activity:Persistent antimicrobial protection lasting 48 hours reduces surgical site infection rates, driving protocol adoption across tertiary care networks in Germany, Japan, and the United States.
Market Restraints
- Isopropyl Alcohol Supply Concentration:Bulk pharmaceutical-grade alcohol production clusters in Texas and Louisiana, exposing formulators to hurricane-related supply disruptions and price volatility.
- EMA Medical Device Regulation Compliance:Reclassification of skin antiseptics as Class IIa devices demands expanded clinical evidence packages, extending time-to-market by 18-24 months for new entrants.
- Film-Forming Technology Patent Density:3M's extensive intellectual property portfolio in acrylic adhesive systems limits competitive development of comparable persistent barrier products.
Strategic Opportunities
- Home Healthcare Wound Care:Post-acute settings lack standardized antiseptic protocols, creating white space for consumer-adapted chlorhexidine formats with simplified application instructions.
- EU Green Deal Chemical Restrictions:Biodegradable excipient mandates favor suppliers developing plant-derived surfactants to replace petroleum-based formulation components.
- Prefilled Applicator Convergence:Integration of sterile packaging with single-use foam or swab systems eliminates cross-contamination risks in emergency departments and field medicine.
Industry Challenges
- Clinical Evidence Generation:Large-scale randomized controlled trials comparing antiseptic efficacy against surgical site infection require multi-year hospital partnerships and substantial investigator funding.
- Legacy Formulary Inertia:Povidone-iodine retains entrenched position in many surgical departments due to decades of protocol familiarity and lower per-unit procurement cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Skin Antiseptic Products Market |
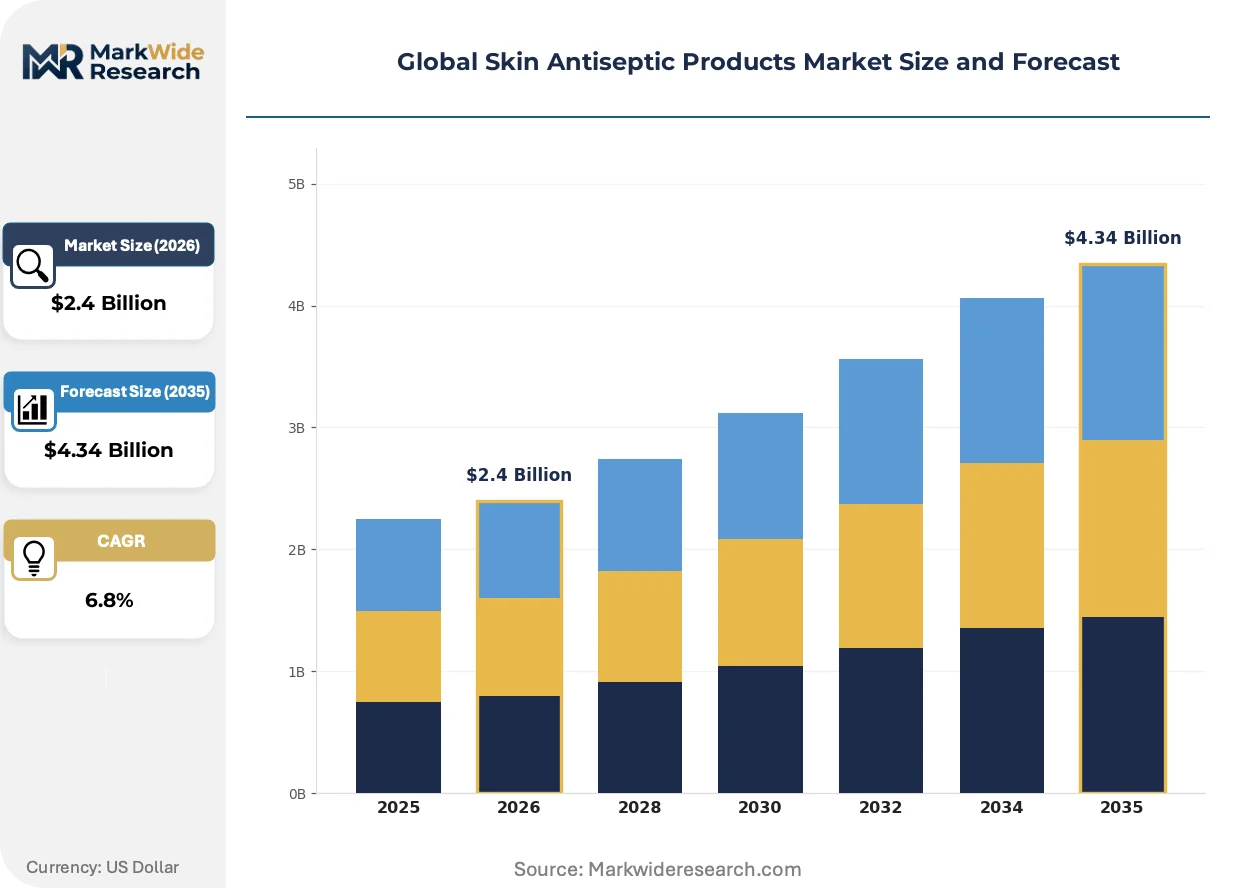
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorhexidine, Iodophors, Alcohol-Based, Parachlorometaxylenol, Hydrogen Peroxide, Others Application: Preoperative Preparation, Catheter Insertion, Wound Care, Injection Site Cleaning, Dermatology Procedures, Infection Control End User: Hospitals, Ambulatory Surgical Centers, Clinics, Diagnostic Laboratories, Home Healthcare, Long-Term Care Facilities Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales, Medical Distributors, E-Commerce Platforms |
| Companies Covered | Becton, Dickinson and Company, Ecolab Inc., Johnson & Johnson, 3M Company, B. Braun Melsungen AG, Solventum, Cardinal Health, Inc., SCHÜLKE & Mayr GmbH, Sage Products LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Skin Antiseptic Products Market Shifts & Advancements
Formulation chemistry and delivery mechanisms are diverging as hospitals prioritize residue reduction and application consistency over raw antimicrobial potency alone.
Film-forming chlorhexidine-alcohol combinations are overtaking traditional aqueous preparations in lengthy orthopedic and cardiac procedures. Major academic medical centers in the United States and Germany have adopted these systems for operations exceeding four hours. The technology is overtaking conventional prep pads by eliminating the need for reapplication and reducing surgical delays.
REACH authorization requirements for residual isopropyl alcohol in wastewater streams are compelling European manufacturers to reformulate with lower-volatility excipients. Ecolab has re-engineered production lines at its Belgian facility to capture solvent emissions. German hospital purchasing cooperatives now require environmental impact disclosures alongside clinical efficacy data.
Group purchasing organizations are consolidating antiseptic contracts into multi-year, sole-source agreements that bundle skin preparation with surface disinfection and instrument sterilization. Independent ambulatory surgical centers in Florida and Texas are losing negotiating leverage as regional GPOs absorb smaller facilities. This concentration is most visible in the southeastern United States, where three purchasing networks control over sixty percent of hospital antiseptic volume.
Global Skin Antiseptic Products Market Segmentation
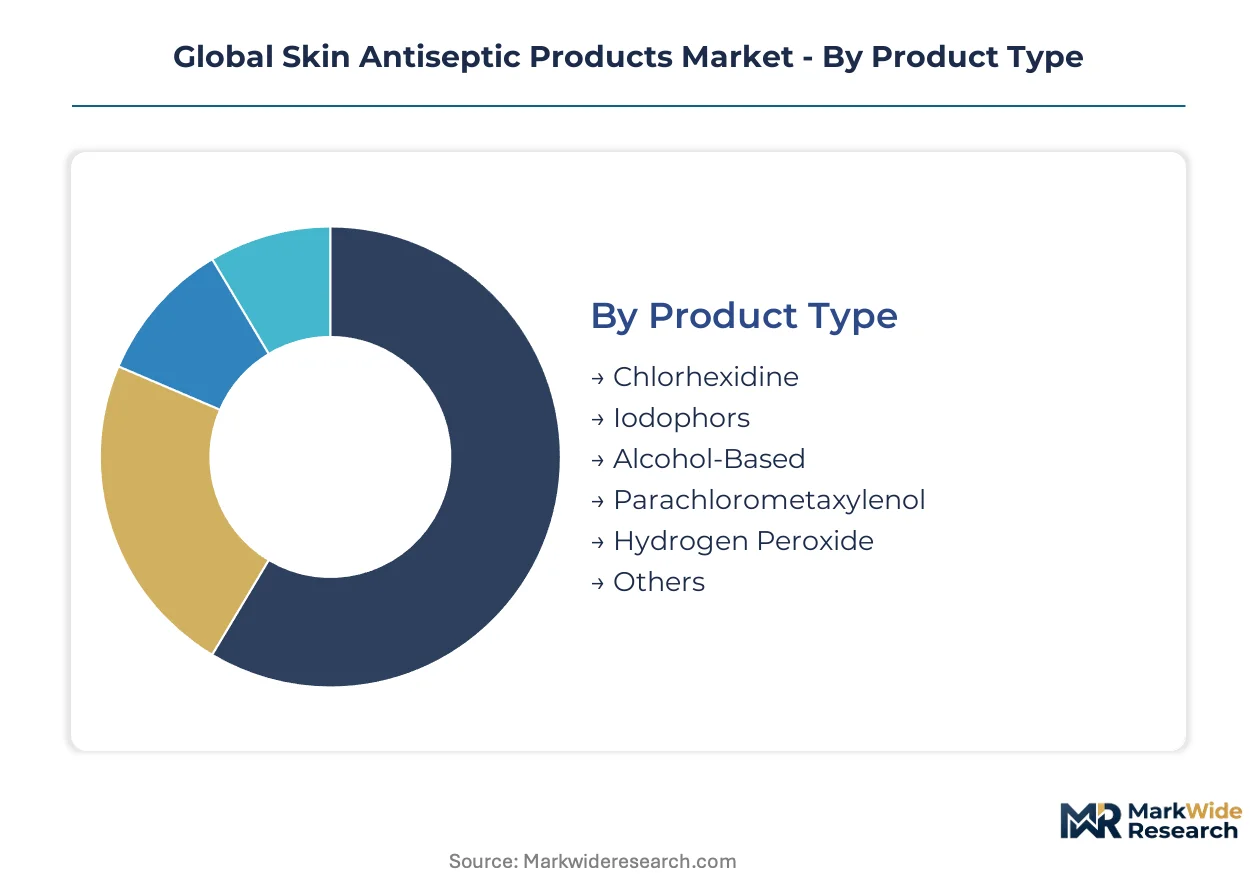
Antiseptic formulation chemistry and delivery mechanisms diverge sharply across clinical settings, with residue profiles, drying times, and persistence requirements dictating procurement decisions. Understanding these segment boundaries clarifies why chlorhexidine-alcohol combinations command premium positioning in lengthy surgeries while simpler alcohol swabs dominate high-throughput outpatient environments.
Product Type:
Active ingredient selection hinges on procedure duration, skin integrity, and mandatory dwell-time protocols established by surgical site infection bundles.
- Chlorhexidine:Chlorhexidine gluconate formulations deliver residual antimicrobial activity persisting 48 hours post-application, making them indispensable for cardiac and orthopedic procedures in Germany and the United States where extended operations demand sustained protection. Tertiary care networks in Japan have standardized chlorhexidine-alcohol combinations as preoperative preparation defaults.
- Alcohol-Based:Isopropyl and ethyl alcohol solutions between 60% and 90% concentration achieve rapid bactericidal action within 30 seconds, suiting emergency departments and ambulatory settings where speed outweighs persistence. Supply concentration in Texas and Louisiana exposes formulators to hurricane-related disruptions.
- Iodophors:Povidone-iodine complexes retain entrenched formulary positions in surgical departments valuing decades of protocol familiarity and lower per-unit procurement cost.
- Parachlorometaxylenol:PCMX formulations serve niche applications requiring reduced skin irritation compared to harsher antiseptic chemistries.
- Hydrogen Peroxide:Oxidative antiseptic action targets anaerobic wound environments with limited penetration into intact skin.
- Others:Emerging botanical and silver-based alternatives address sustainability mandates and chemical sensitivity populations.
Chlorhexidine leads on scale; alcohol-based solutions lead on momentum in high-throughput environments.
Application:
Clinical use cases stratify by invasiveness level, with mandatory bundles driving standardization in surgical settings while home applications remain protocol-fragmented.
- Preoperative Preparation:Mandatory surgical site infection bundles in the United States and Germany mandate standardized skin antisepsis prior to incision, creating the largest revenue concentration across the category. Film-forming chlorhexidine-alcohol combinations are displacing traditional aqueous preparations in operations exceeding four hours.
- Catheter Insertion:Central line-associated bloodstream infection prevention protocols require antiseptic application at insertion sites, with chlorhexidine-impregnated dressings gaining traction in intensive care units.
- Wound Care:Post-acute and home healthcare settings lack standardized antiseptic protocols, creating white space for consumer-adapted formats with simplified application instructions.
- Injection Site Cleaning:Routine immunization and medication administration drives volume consumption of single-use alcohol swabs in clinics and outpatient departments.
- Dermatology Procedures:Cosmetic and therapeutic skin interventions require antiseptics compatible with sensitive facial skin and subsequent cosmetic application.
- Infection Control:General prophylactic applications span pre-procedural patient bathing and decolonization protocols in outbreak management.
Preoperative preparation anchors revenue concentration; wound care applications expand most quickly as home healthcare volumes rise.
End User:
Procurement sophistication varies dramatically, with consolidated purchasing power in hospital systems contrasting fragmented decision-making in smaller facilities.
- Hospitals:Established group purchasing contracts and surgical site infection bundles concentrate antiseptic volume in tertiary care networks across the United States, Germany, and Japan. Consolidated procurement under multi-year agreements forces suppliers to restructure pricing around volume guarantees.
- Ambulatory Surgical Centers:Outpatient procedure acceleration drives demand for rapid-drying, single-use applicators designed for limited sterilization infrastructure and high patient throughput.
- Clinics:Primary care and specialty clinics balance cost sensitivity with infection control requirements through retail pharmacy purchasing channels.
- Diagnostic Laboratories:Blood draw and specimen collection sites prioritize speed and patient comfort in antiseptic selection.
- Home Healthcare:Post-acute settings lack clinical oversight, creating adherence challenges and opportunities for simplified delivery formats.
- Long-Term Care Facilities:Elderly populations with fragile skin require gentler formulations balancing antimicrobial efficacy against irritation risk.
Hospitals dominate procurement volume; ambulatory surgical centers gain share fastest as procedure migration accelerates.
Distribution Channel:
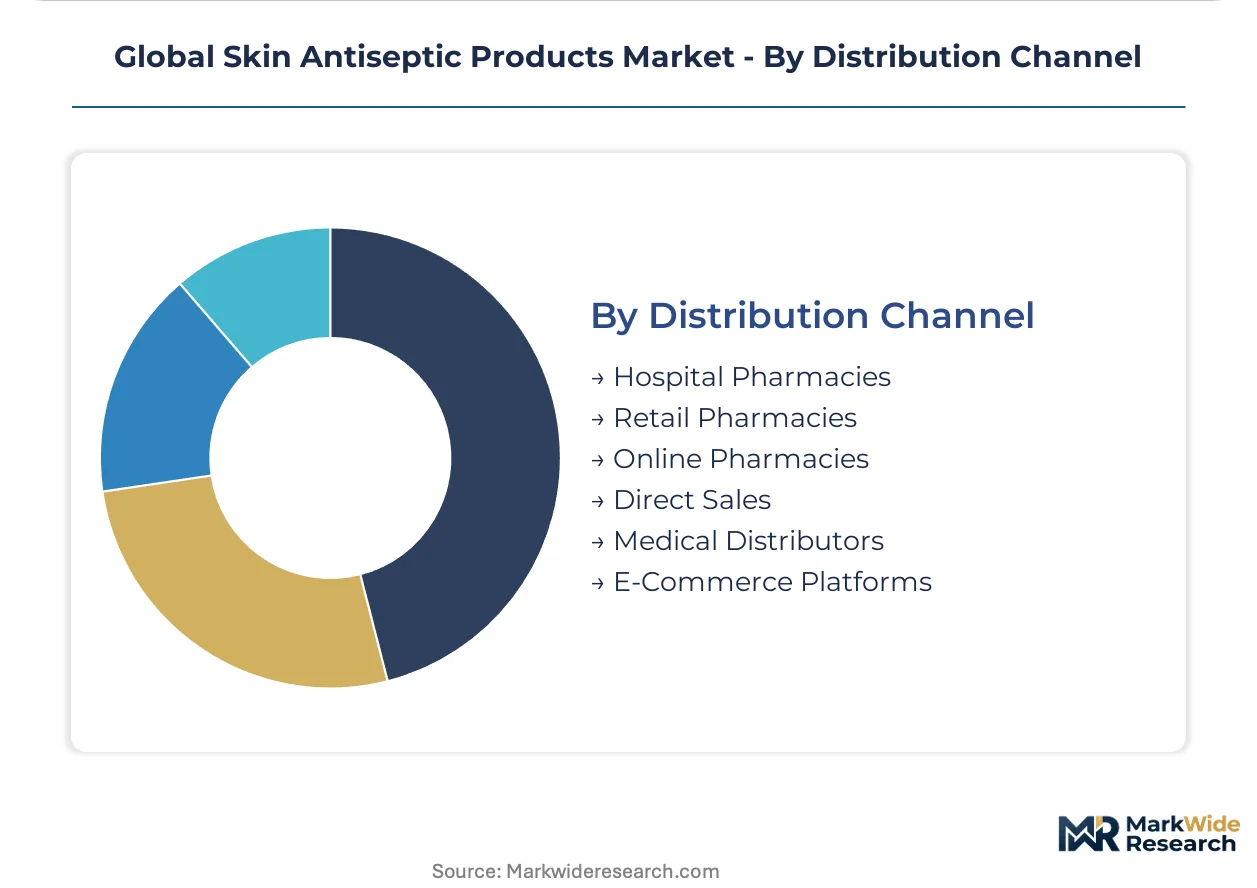
Channel selection reflects end-user scale and regulatory complexity, with direct relationships dominating institutional sales while retail and digital channels serve fragmented demand.
- Hospital Pharmacies:Captive distribution within integrated delivery networks ensures formulary compliance and just-in-time inventory management for surgical schedules.
- Retail Pharmacies:Consumer-facing antiseptic segments reach patients through pharmacy chains and independent drugstores.
- Online Pharmacies:Digital prescription fulfillment expands access for home healthcare patients and chronic wound management.
- Direct Sales:Manufacturer field forces maintain relationships with large hospital systems and group purchasing organizations.
- Medical Distributors:Regional distributors serve ambulatory surgical centers and smaller clinics lacking direct manufacturer access.
- E-Commerce Platforms:General merchandise marketplaces address consumer self-care demand with limited clinical guidance.
Hospital pharmacies concentrate institutional volume; e-commerce platforms climb the fastest as direct-to-consumer channels mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas-Louisiana chemical corridor concentrates pharmaceutical-grade isopropyl alcohol production, exposing formulators to hurricane-season supply disruptions. Hospital procurement networks in Germany and Japan drive chlorhexidine protocol standardization. Regulatory divergence between FDA premarket requirements and EMA Medical Device Regulation creates compliance complexity for multinational suppliers.
United States
Tertiary care networks in Texas, California, and New York have standardized chlorhexidine-alcohol combinations for cardiac and orthopedic procedures exceeding four hours. FDA updated guidance on preoperative skin antisepsis mandates alcohol-based formulations in most inpatient settings. The Houston chemical cluster produces the majority of domestic pharmaceutical-grade alcohol, creating geographic vulnerability to Gulf Coast weather events.
Germany
Baden-Württemberg and Bavaria host the densest concentration of university hospitals adopting film-forming antiseptic systems. EMA Medical Device Regulation reclassification demands expanded clinical evidence packages for new market entrants. Ecolab's Belgian production facility captures solvent emissions to meet REACH authorization requirements for residual alcohol in wastewater streams.
Japan
Tokyo and Osaka metropolitan areas have standardized chlorhexidine-alcohol combinations as preoperative preparation defaults across tertiary care networks. PMDA alignment with international surgical site infection protocols accelerates formulary updates. The Kansai region's medical device manufacturing base supplies applicator systems to domestic and export markets.
United Kingdom
London and the Southeast concentrate National Health Service procurement decisions for surgical site infection bundles. MHRA post-Brexit regulatory autonomy creates parallel compliance tracks with EU MDR requirements. The Cambridge-Oxford healthcare innovation corridor pilots novel delivery mechanisms for outpatient antiseptic applications.
India
Maharashtra and Karnataka states expand domestic chlorhexidine production capacity for hospital and export markets. CDSCO tightening of medical device quality standards elevates evidence requirements for imported antiseptic formulations. The Hyderabad pharmaceutical cluster develops cost-optimized alcohol-based solutions for ambulatory surgical centers across South Asia.
Global Skin Antiseptic Products Market Competitive Landscape
Global majors compete with regional champions across institutional contracting and formulation technology. The market structures around three tiers: integrated hygiene conglomerates with GPO relationships, medical device specialists with delivery system expertise, and regional chemical formulators serving price-sensitive segments. Consolidation pressure intensifies as hospital procurement departments demand volume guarantees tied to clinical outcome metrics. Dominant competitive moves include backward integration into active ingredient supply and technology licensing for film-forming delivery systems.
Among diversified healthcare conglomerates, Becton, Dickinson and Company and Johnson & Johnson exemplify the institutional-contracting archetype through established hospital supply relationships. Ecolab Inc. occupies a distinct position leveraging industrial hygiene infrastructure into North American healthcare networks. 3M Company represents the technology-specialist tier with intellectual property concentration in adhesive delivery systems. SCHÜLKE & Mayr GmbH anchors European chemical formulator capabilities. B. Braun Melsungen AG sits within the integrated medical device supply tier with German manufacturing heritage.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Ecolab Inc. |
| Johnson & Johnson |
| 3M Company |
| B. Braun Melsungen AG |
| Solventum |
| Cardinal Health, Inc. |
| SCHÜLKE & Mayr GmbH |
| Sage Products LLC |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade isopropyl alcohol spot prices cascade through skin antiseptic supply chains into three distinct procurement tiers, with hospital group purchasing organizations extracting volume discounts that independent ambulatory centers cannot match. Chlorhexidine gluconate active pharmaceutical ingredient costs concentrate pricing power among backward-integrated formulators with captive supply agreements.
Pricing Analysis
Input-cost pass-through from isopropyl alcohol volatility feeds into contract-based long-term offtake pricing that separates GPO-anchored hospitals from price-sensitive independent clinics. Price differentiation hinges on FDA 510(k) clearance tier and volume scale, with premium film-forming formulations commanding spreads over commodity alcohol swabs. Cost compression in standard aqueous chlorhexidine is intensifying because of generic API competition from Indian manufacturers. Independent ambulatory surgical centers in Texas and Florida exhibit highest price sensitivity, while integrated delivery networks in Germany and the United States prioritize outcome guarantees over per-unit cost.
Supply Chain Analysis
Ocean freight rate volatility from Asia-Pacific to North Atlantic ports disrupts just-in-time inventory for European hospital networks dependent on Asian applicator manufacturing. Active ingredient production clusters in the United States, India, and Germany, with chlorhexidine gluconate synthesis anchored in Hyderabad and Frankfurt chemical parks. Supply chain risk centers on single-source vulnerability for pharmaceutical-grade alcohol from the Texas-Louisiana corridor exposed to hurricane-season shutdowns. Distribution runs through medical distributors serving regional hospital systems, with direct sales forces maintaining GPO relationships at top-tier accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The skin antiseptic market functions as a stable compounder, with mandatory surgical site infection bundles across tertiary care networks generating recurring procurement volumes resistant to economic cyclicality.
For Market Incumbents: Lock in multi-year GPO contracts with clinical outcome guarantees that embed film-forming technology as the standard-of-care for procedures exceeding four hours. Deepen backward integration into chlorhexidine gluconate API production to offset margin pressure from Indian generic suppliers. Prioritize REACH-compliant excipient reformulation to preempt EU Green Deal chemical restrictions.
For New Entrants and Emerging Players: Capture home healthcare wound care segments where standardized protocols remain absent and consumer-adapted formats face limited incumbent competition. Target ambulatory surgical centers in the southeastern United States losing leverage to regional purchasing consolidation. Pursue private-label partnerships with medical distributors seeking differentiated applicator systems.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional chemical formulators possessing EU MDR technical documentation capabilities and untapped GPO relationships. Long-term viability rests on exposure to outpatient procedure migration and home healthcare expansion rather than inpatient surgical volume. Watch for FDA guidance updates on preoperative preparation standards as inflection indicators for formulation chemistry shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Supply | Captive chlorhexidine gluconate production insulates margin from Indian generic price erosion. |
| Film-Forming Technology Licensing | Acrylic adhesive system partnerships circumvent 3M patent density in persistent barrier products. |
| REACH-Compliant Excipient Reformulation | Plant-derived surfactant substitution secures German hospital purchasing cooperative approval. |
| Prefilled Applicator Convergence | Sterile packaging integration eliminates cross-contamination risks in emergency departments. |
| Home Healthcare Format Development | Simplified application instructions address protocol fragmentation in post-acute settings. |
Research Methodology
Direct dialogue with hospital procurement managers, GPO contracts directors, biomedical engineers, and regulatory affairs specialists at Ecolab, 3M, and SCHÜLKE combined with secondary validation against FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and SEC 10-K disclosures. Bottom-up volume estimates triangulated with top-down market sizing across formulation chemistry, delivery mechanism, and end-user segments.
Segment-level revenue projections across the analysis window model chlorhexidine, alcohol-based, iodophor, and emerging botanical formulations against procedure volume growth in preoperative preparation, catheter insertion, wound care, and injection site cleaning applications. CAGRs derive from regression analysis of historical procurement data, surgical site infection bundle adoption curves, and ambulatory surgical center expansion rates.
EMA MDR reclassification delays, hurricane-related isopropyl alcohol supply disruptions, and EU Green Deal chemical restriction scope expansion are the dominant revision risks to modeled outcomes. A model refresh is warranted upon material change in FDA preoperative preparation guidance or GPO contract consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Blood Stream Infection Testing Market
Infection Control
Sterilization Technologies Market
Infection Control
Yeast Infection Market
Infection Control
South Africa Antibacterial Soap Market
Infection Control
Botulism Market
Infection Control
Sterilization Monitoring Market
Infection Control
Middle East and Africa Hand Sanitizer Market
Infection Control
Sterilization Market
Infection Control
Salivary Gland Infection Treatment Market
Infection Control
Salivary Gland Infection Market
Infection Control
Global Hospital Acquired Infection Control Market
Infection Control
Veterinary Disinfectant for Pets and Farms Market
Infection Control
Global Dental Infection Control Products Market
Infection Control
Global Prophylactic Human Vaccine Market
Infection Control
Disinfection Equipment Market
Infection Control
UV Disinfection Equipment Market