
 Healthcare Protective Masks Market | 2026-2036
Healthcare Protective Masks Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Protective Masks Market Foresight
Hospital procurement departments is redrawing demand patterns across the Healthcare Protective Masks landscape as institutional buyers prioritize N95 stockpiles over disposable surgical alternatives. 3M leverages its NIOSH-certified manufacturing infrastructure to sustain dominance in North American respirator supply. Kimberly-Clark Corporation anchors its position through vertical integration into meltblown polypropylene filtration media. Honeywell International Inc. competes via dual-channel distribution serving both federal stockpile contracts and commercial healthcare purchasers.
Healthcare protective masks are tight-fitting or loose-fitting barrier devices constructed from multi-layer nonwoven polypropylene, cellulose, or textile composites designed to filter airborne particles, droplets, and biological aerosols at specified efficiencies measured by bacterial filtration efficiency or submicron particulate filtration standards. Their primary purpose is to protect healthcare workers and patients from cross-contamination during medical procedures, patient care, and exposure to infectious respiratory pathogens. N95 Respirators command premium positioning due to NIOSH certification complexity and higher raw material costs, while Surgical Masks represent the volume baseline sustained by standardized operating room consumption. The Infection Control application segment leads value generation as hospitals enforce universal masking protocols, whereas Homecare emerges as a growth corridor driven by post-acute patient monitoring and immunocompromised household protection.
FDA governs 510(k) clearances and emergency use authorizations for medical-grade masks in the United States, while NIOSH certifies respirator filtration performance under 42 CFR Part 84, creating a dual-compliance threshold that constrains market entry for uncertified manufacturers. OSHA workplace exposure limits and Joint Commission accreditation standards further institutionalize mask-wearing as a non-negotiable operational requirement across acute care facilities. Stakeholders must monitor evolving ASTM F2100 revision cycles and potential harmonization with EN 14683 European standards, as cross-regulatory alignment would reshape competitive access for domestic versus imported suppliers.
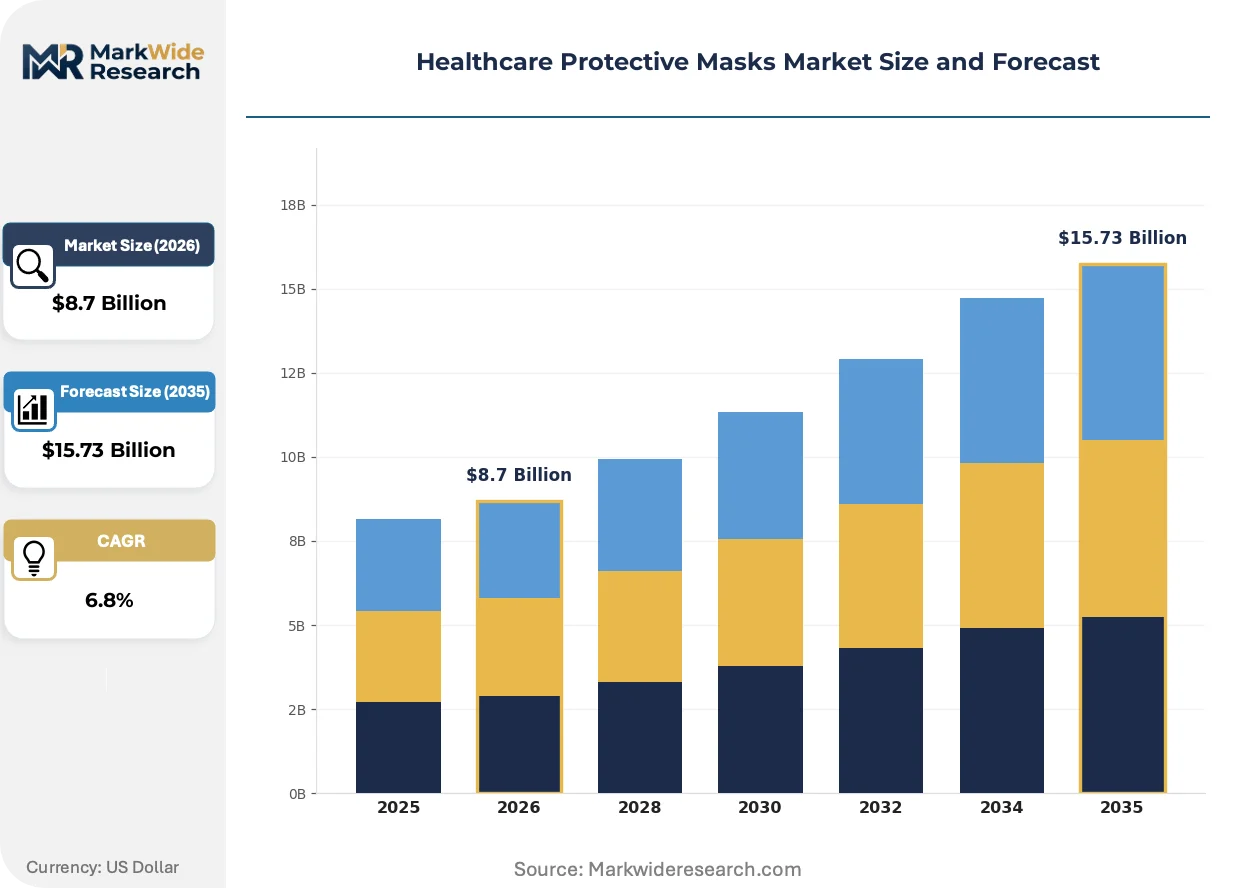
Market Dynamics
Federal pandemic preparedness programs are reshaping procurement priorities as hospital systems rebuild N95 respirator stockpiles above pre-2020 levels, compressing demand timelines and favoring domestic-certified suppliers over import-reliant alternatives.
Growth Catalysts
- NIOSH Certification Mandates:United States federal stockpile programs require NIOSH-approved respirators, creating a compliance-driven demand floor that filters out uncertified competitors and sustains premium pricing for validated manufacturers.
- Homecare Patient Monitoring:Post-acute care expansion drives sustained consumption of surgical-grade masks by immunocompromised patients managing recovery outside institutional settings.
- Meltblown Polypropylene Filtration Media:Advances in electrostatic charging of nonwoven polypropylene layers enable higher bacterial filtration efficiency at reduced material weights, lowering per-unit production costs for compliant manufacturers.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene resin prices fluctuate with crude oil benchmarks, compressing gross margins for mask producers unable to pass through raw material cost swings to contracted hospital purchasers.
- Single-Source Geography Concentration:Domestic meltblown media production concentrates in Gulf Coast petrochemical corridors, exposing supply chains to hurricane disruption and regional utility price spikes.
- ASTM F2100 Revision Uncertainty:Pending updates to American Society for Testing and Materials filtration standards create compliance timeline risk, forcing manufacturers to hedge certification investments across multiple specification scenarios.
Strategic Opportunities
- Rural Health Clinic Underpenetration:Federally qualified health centers in Appalachian and Southwestern regions operate below recommended respiratory protection inventory levels, representing addressable volume for distributors with cold-chain logistics capability.
- Reusable Elastomeric Respirator Adoption:OSHA workplace exposure limit enforcement is accelerating hospital evaluation of half-face elastomeric alternatives to disposable N95s, opening maintenance-service revenue streams.
- Domestic Manufacturing Reshoring Incentives:United States Department of Health and Human Services grants for onshore personal protective equipment production reduce landed cost disadvantages versus Asian imports for qualified applicants.
Industry Challenges
- NIOSH Approval Timeline Compression:Respirator certification queues at the National Personal Protective Technology Laboratory extend to 12-18 months, delaying product launch windows and trapping R&D capital in regulatory limbo.
- Filtration Media Technical Talent Scarcity:Electret charging process engineers with nonwoven polymer expertise command premium compensation, constraining capacity expansion at mid-tier manufacturers without captive training pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Protective Masks Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Masks, N95 Respirators, Cloth Masks, Full-Face Masks End User: Hospitals, Clinics, Laboratories, Homecare Material: Polypropylene, Cotton, Polyester, Latex Application: Infection Control, Dust Protection, Chemical Exposure, General Use |
| Companies Covered | 3M, Honeywell International Inc., Kimberly-Clark Corporation, DuPont, Ansell Ltd., Cardinal Health, Medline Industries Inc., Uvex Group, O&M Halyard Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Protective Masks Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are converging to redefine performance benchmarks and procurement specifications across healthcare respiratory protection.
Electrospun nanofiber filtration media is decomposing the traditional meltblown polypropylene dominance in high-efficiency respirator construction. Academic medical centers in the Northeastern United States are piloting nanofiber-layered N95 alternatives that maintain submicron capture at lower breathing resistance. This technology is decomposing the historical trade-off between filtration efficiency and wearer comfort that has constrained extended-use compliance.
ASTM International is advancing F2100 revision cycles to incorporate synthetic blood penetration resistance and differential pressure testing protocols that more closely mirror EN 14683 European standards. Medical device manufacturers face dual-certification cost burdens as they prepare submissions for both FDA 510(k) clearance and potential future mutual recognition agreements. Surgical mask suppliers serving export markets are most affected, retooling quality management systems to satisfy divergent documentation requirements.
Hospital value analysis committees are consolidating supplier rosters from 12-15 mask vendors to 3-4 strategic partners, compressing switching flexibility in exchange for volume-based pricing guarantees. Group purchasing organizations are intermediating these consolidations, capturing administrative fees while standardizing SKU portfolios across member health systems. This concentration is most visible in the Southeastern United States, where multi-hospital systems are unifying respiratory protection specifications across 20+ affiliated facilities.
Healthcare Protective Masks Market Segmentation
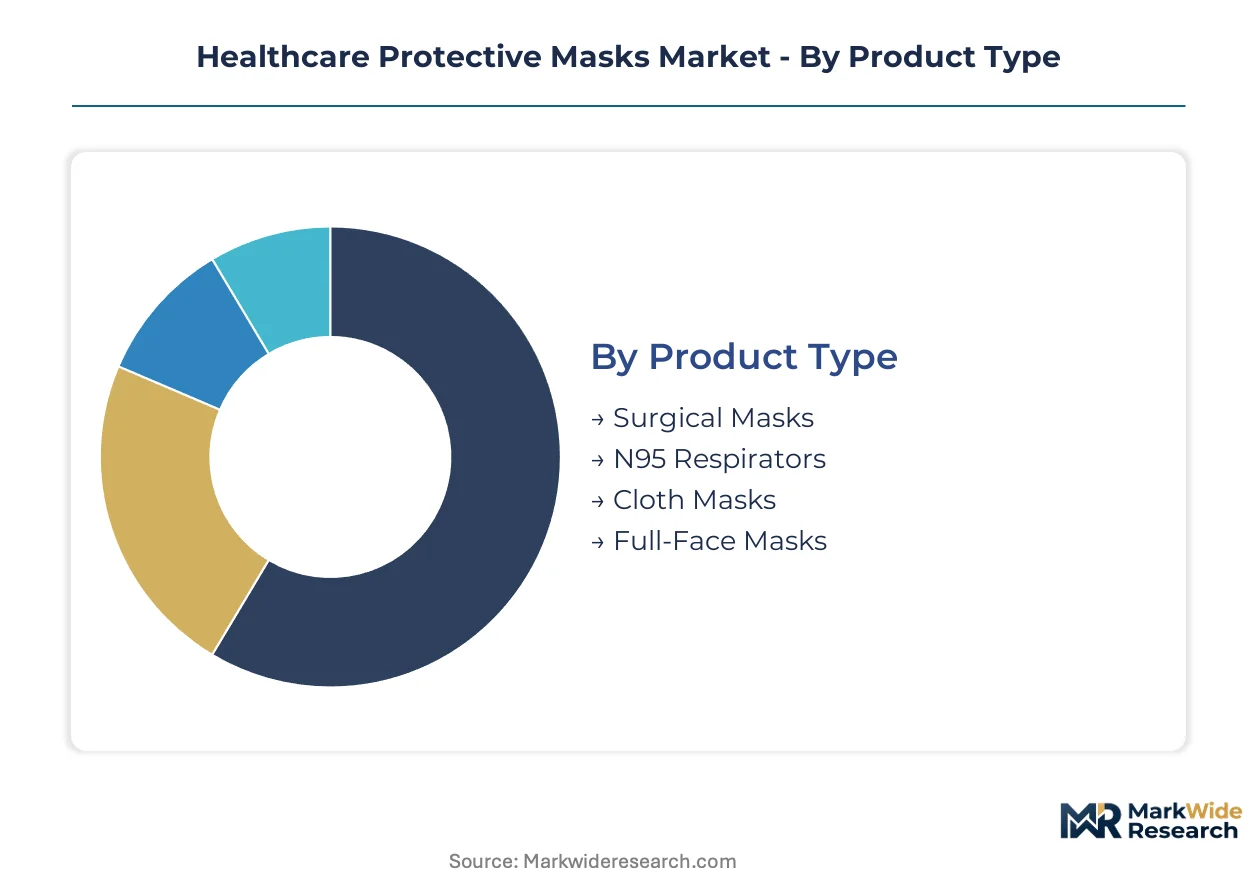
Segmentation in healthcare protective masks determines procurement channel access, certification burden, and margin structure. Hospital buyers route N95 respirators through federal stockpile contracts while surgical masks flow via group purchasing organizations. Material composition dictates regulatory pathway complexity and production geography.
Product Type:
Channel mix varies sharply by product type: N95 respirators concentrate in federal emergency stockpile channels and hospital direct contracts, while surgical masks and cloth alternatives distribute through medical supply distributors and retail pharmacy networks.
- N95 Respirators:Tight-fitting respiratory protection devices constructed from electrostatically charged meltblown polypropylene layers meeting NIOSH 42 CFR Part 84 filtration standards. Demand concentrates in United States acute care facilities rebuilding pandemic stockpiles above pre-2020 levels, with federal procurement mandates filtering out uncertified suppliers and sustaining premium positioning for validated domestic manufacturers.
- Surgical Masks:Loose-fitting barrier devices composed of three-ply nonwoven polypropylene with bacterial filtration efficiency ratings under ASTM F2100. Volume flows through standardized operating room consumption protocols, with group purchasing organizations consolidating supplier rosters from 12-15 vendors to 3-4 strategic partners across Southeastern United States multi-hospital systems.
- Cloth Masks:Reusable textile barriers typically constructed from cotton or cotton-blend fabrics without standardized filtration certification. Consumer and light medical demand channels.
- Full-Face Masks:Elastomeric respirator systems with replaceable cartridge filtration for high-exposure medical procedures. Specialized hospital safety equipment procurement.
N95 Respirators dominate installed base value. Surgical Masks represent where volume expansion concentrates.
End User:
Cost tier segmentation separates institutional buyers with contracted pricing from direct-pay channels. Hospital systems leverage volume guarantees for preferential N95 allocation, while homecare patients absorb retail markup on surgical-grade protection.
- Hospitals:Acute care institutions with Joint Commission accreditation requirements mandating respiratory protection programs. Federal pandemic preparedness funding channels through these facilities, with value analysis committees consolidating vendor relationships in exchange for volume-based pricing guarantees.
- Homecare:Post-acute patients and immunocompromised households managing recovery outside institutional settings. Demand climbs fastest in this segment as extended-care protocols shift monitoring burden to residential environments, with cold-chain logistics capability determining distributor access to rural and underserved geographies.
- Clinics:Outpatient and ambulatory surgical centers with intermediate procurement scale. Federally qualified health centers in Appalachian and Southwestern United States regions operate below recommended inventory levels.
- Laboratories:Clinical and research facilities requiring biosafety-level appropriate respiratory protection. Specialized certification requirements.
Hospitals anchor contracted revenue. Homecare is climbing the fastest.
Material:
Supply concentration and petrochemical feedstock exposure differentiate material segments. Polypropylene producers with captive meltblown capacity capture margin upstream, while natural fiber alternatives bypass resin price volatility.
- Polypropylene:Dominant synthetic polymer for medical-grade filtration media, processed via meltblown extrusion and electrostatic charging to achieve submicron particle capture. Production concentrates in Gulf Coast petrochemical corridors, exposing supply chains to hurricane disruption and regional utility price spikes.
- Cotton:Natural cellulose fiber for reusable cloth mask construction, primarily serving consumer and non-medical channels with lower barrier protection specifications.
- Polyester:Synthetic alternative for durable mask shells and blended filtration layers. Limited medical certification penetration.
- Latex:Elastomer component for respirator face seals and headbands. Niche specialty applications with allergy sensitivity constraints.
Polypropylene dominates technical specifications. Cotton offers feedstock diversification.
Application:
Regulatory stringency and reimbursement eligibility create application tiering. Infection control commands mandatory compliance investment, while general use segments compete on price with minimal certification burden.
- Infection Control:Medical-grade respiratory protection for patient care and surgical procedures, governed by FDA 510(k) clearance and universal masking protocol enforcement. Value generation concentrates here as hospitals institutionalize barrier protection as non-negotiable operational requirement.
- Dust Protection:Industrial and environmental particulate filtration with lower biological aerosol specifications. Adjacent market overlap.
- Chemical Exposure:Specialized respirator configurations for hazardous material handling. Narrow institutional safety channel.
- General Use:Non-medical consumer and community masking with minimal regulatory oversight. Price-sensitive commodity competition.
Infection Control dominates compliance-driven procurement. General Use absorbs surplus capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico exports polypropylene nonwoven media to United States hospital supply chains, while Southeast Asian fabricators redirect surgical mask capacity toward European Union markets facing EN 14683 compliance deadlines.
United States
Federal stockpile mandates and NIOSH certification requirements concentrate procurement around domestic-certified respirator manufacturers. The Department of Health and Human Services channels pandemic preparedness grants toward onshore meltblown production. Gulf Coast petrochemical corridors near Houston host integrated polypropylene-to-media operations vulnerable to hurricane season disruption.
Germany
Industrial safety distributors expand hospital-grade respirator portfolios as occupational exposure limits tighten across manufacturing sectors. BSI Group and TÜV Rheinland validate filtration performance under harmonizing EN 149 and EN 14683 protocols. Bavarian textile engineering clusters around Augsburg prototype electrospun nanofiber alternatives to conventional meltblown construction.
China
Export-oriented fabricators face margin compression from NMPA registration requirements and United States FDA import alerts on uncertified suppliers. Yangtze River Delta producers pivot toward domestic hospital consumption as provincial health commissions mandate surgical mask stockpiles. Zhejiang nonwoven clusters near Shaoxing consolidate capacity around electrostatic charging equipment upgrades.
India
Central government PLI scheme incentives attract meltblown media investments previously concentrated in East Asian supply chains. CDSCO medical device registration timelines delay market entry for new respirator entrants against established surgical mask suppliers. Gujarat chemical processing corridors near Vadodara integrate polypropylene resin production with downstream filtration media fabrication.
Brazil
ANVISA medical device quality system requirements filter import competition as hospital procurement centralizes under national health system tenders. São Paulo state industrial parks house regional converting operations dependent on imported polypropylene feedstock. Southeast Asian mask exporters face freight cost disadvantages versus Andean suppliers serving Mercosur trade corridors.
Healthcare Protective Masks Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and federal contract access. Three to five NIOSH-validated manufacturers capture disproportionate value in United States acute care procurement, while mid-tier surgical mask suppliers compete on volume through group purchasing organization channels. Strategic archetypes separate integrated resin-to-media producers, dedicated respirator specialists, and diversified medical supply conglomerates. Dominant competitive moves include backward integration into meltblown polypropylene production and geographic expansion through distributor acquisition.
Within the integrated materials tier, 3M and DuPont anchor positions through captive control over electrostatic charging technology and polymer science expertise. Honeywell International Inc. occupies a distinctive position bridging federal stockpile contracting and commercial healthcare distribution. Kimberly-Clark Corporation exemplifies vertical scope from pulp and nonwoven base materials through finished device sterilization packaging.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| Kimberly-Clark Corporation |
| DuPont |
| Ansell Ltd. |
| Cardinal Health |
| Medline Industries Inc. |
| Uvex Group |
| O&M Halyard Inc. |
| Others |
Supply & Pricing Matrix
Twelve-to-eighteen-month NIOSH approval queues compress supplier pricing power for uncertified entrants while amplifying premium capture among validated domestic manufacturers with federal stockpile access.
Pricing Analysis
Electrospun nanofiber-layered respirators command 40-60% premiums over conventional meltblown N95s in Northeastern academic medical center pilots, while surgical-grade meltblown masks price at commodity floors through group purchasing organization consolidation. Price differentiation hinges on NIOSH certification tier and captive meltblown capacity, with Gulf Coast-integrated producers least exposed to polypropylene resin volatility. Pricing pressure intensifies in surgical mask tiers as Asian imports absorb margin compression from FDA import alert enforcement. Homecare patients demonstrate highest price sensitivity, while hospital value analysis committees prioritize supply security over per-unit cost.
Supply Chain Analysis
Sixty-day safety stock mandates at major health systems signal inventory normalization after pandemic depletion cycles, though domestic meltblown media production remains concentrated in Texas and Louisiana petrochemical corridors. Supply draws from United States, China, and Germany for electrostatic charging equipment and polymer resin feedstock. Single-source geography concentration in Gulf Coast operations exposes chains to hurricane season disruption. Distribution runs through federal stockpile contracts for N95 respirators and group purchasing organizations for surgical masks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable elastomeric respirator substitution threatens disposable N95 volume as OSHA workplace exposure limit enforcement accelerates hospital evaluation of half-face alternatives with maintenance-service revenue potential.
For Market Incumbents: Compound NIOSH certification infrastructure advantages by accelerating electrospun nanofiber R&D partnerships with Bavarian textile engineering clusters, while securing backward integration into meltblown polypropylene through Department of Health and Human Services reshoring grants to defend against Asian import price erosion in surgical mask tiers. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for surgical mask variants with ASTM F2100 pre-submission feedback offer lowest regulatory barrier to hospital procurement access, with federally qualified health centers in Appalachian and Southwestern regions presenting addressable white space for distributors with cold-chain logistics capability. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across electrospun nanofiber filtration media as equipment costs decline and process yields improve, signaling mid-tier manufacturers with captive electret charging expertise as viable acquisition targets; watch NIOSH approval timeline compression as inflection indicator for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| NIOSH Certification Fast-Track | Accelerates market entry for domestic respirator manufacturers competing for federal stockpile contracts. |
| Meltblown Media Backward Integration | Captures margin upstream from polypropylene resin through finished filtration layer production in Gulf Coast corridors. |
| Electrospun Nanofiber Partnership | Positions manufacturers for next-generation N95 alternatives with lower breathing resistance and extended-use compliance. |
| Rural Health Clinic Distribution | Unlocks volume in federally qualified health centers operating below recommended respiratory protection inventory levels. |
| Reusable Elastomeric Service Model | Opens recurring maintenance revenue streams as OSHA enforcement shifts hospital procurement toward half-face alternatives. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, NIOSH certified product lists, and hospital procurement contract disclosures, with bottom-up and top-down triangulation across interviews with hospital value analysis committee members, group purchasing organization contracts managers, biomedical engineers, meltblown media plant managers, and federal stockpile procurement officers.
Segmentation dimensions modeled include product type, end user, material composition, and application across the projection horizon, with CAGRs derived from trend extrapolation of N95 stockpile rebuild rates, surgical mask operating room consumption protocols, and homecare patient monitoring expansion. Forecast inputs incorporate polypropylene resin price elasticity, NIOSH approval queue duration, and ASTM F2100 revision timeline uncertainty.
Underlying assumptions cover sustained federal pandemic preparedness funding, stable NIOSH certification standards, and petrochemical feedstock accessibility, with deviation risk concentrated in regulatory harmonization with EN 14683 European standards and hurricane disruption to Gulf Coast meltblown production. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Antimicrobial Hospital Curtains Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
Alcohol Wipes Market
Infection Control
Multi-Surface Disinfection Booster Systems with Low QAC Load Market
Infection Control
Salivary Gland Infection Treatment Market
Infection Control
Denture Disinfectants Market
Infection Control
Yeast Infection Market
Infection Control
Global High Level Disinfection Services Market
Infection Control
Global Viral Inactivation Market
Infection Control
Antiseptic Bathing Market
Infection Control
Hand Hygiene Market
Infection Control
Pertussis Infection Testing Market
Infection Control
Medical Disinfectant Wipes Market
Infection Control
Europe Ultrasound Probe Disinfection Market
Infection Control
Global Biofilms Treatment Market
Infection Control
Antimicrobial Suture Market