
 Global Dental Support Organizations Market | 2026-2036
Global Dental Support Organizations Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Support Organizations Market Foresight
DSO formation in the United States is expanding faster than in any other single country, driven by retiring baby-boomer dentists and capital availability from private equity sponsors. Heartland Dental leverages its Midwest operational density to sustain below-market supply costs across hundreds of affiliated practices. Aspen Dental competes through aggressive consumer marketing and retail-style clinic formats in underserved exurban corridors. Pacific Dental Services anchors its model on proprietary technology stacks and same-day dentistry workflows that reduce specialist referral leakage.
Dental Support Organizations are administrative and clinical service platforms that affiliate with licensed dentists to deliver non-clinical functions including revenue cycle management, credentialing, procurement, and IT infrastructure, while preserving clinical autonomy under state dental practice acts. Practice management and revenue cycle management services generate the most predictable recurring revenue streams, whereas AI-enabled platforms and telehealth integration represent the fastest-growing technology adoption segments as labor costs rise and patient convenience expectations intensify. Cloud-based solutions dominate new DSO deployments due to lower capital requirements and faster rollout across multi-location networks.
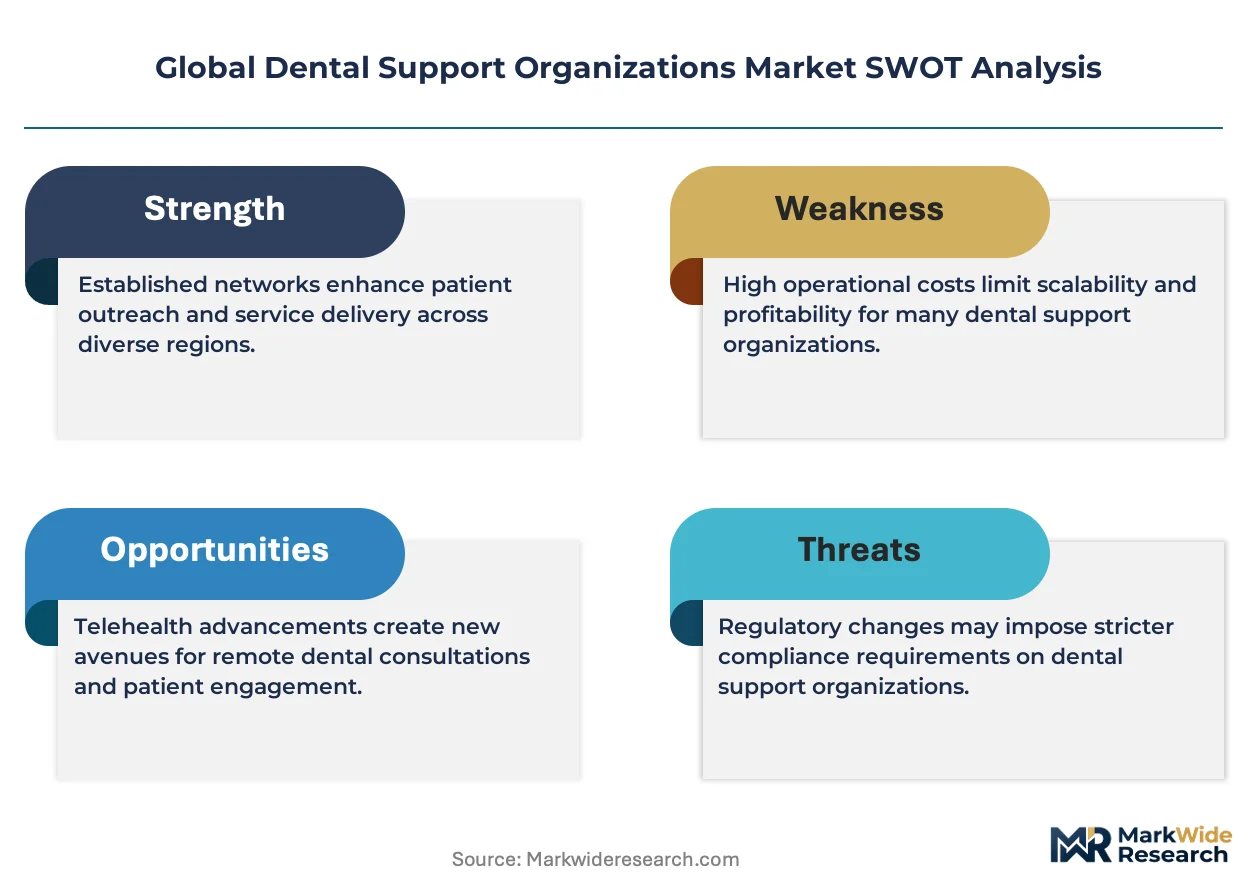
FDA oversight of medical device software and HIPAA privacy requirements shape how DSOs architect patient data systems and vendor selection across affiliated practices. State dental boards in the United States enforce corporate practice of medicine prohibitions that limit ownership structures and determine which services DSOs may legally provide to affiliated dentists. Stakeholders must monitor evolving state-level regulatory interpretations and federal antitrust scrutiny of large DSO rollups that could reshape permissible affiliation structures.
Market Dynamics
Cloud-native practice management infrastructure is compressing the operational gap between independent dental practices and multi-location DSO networks, enabling smaller platforms to achieve procurement and clinical coordination scale previously reserved for the largest affiliates.
Growth Catalysts
- HIPAA-compliant data interoperability frameworks:Unified patient record systems reduce administrative duplication across affiliated practices in the United States, lowering per-clinic overhead thresholds for DSO affiliation.
- AI-enabled radiographic analysis tools:Diagnostic automation reduces specialist referral leakage and captures incremental revenue within DSO networks rather than external specialist practices.
- Private equity capital formation:Sponsors deploy rollup capital into fragmented dental practice ownership, accelerating DSO formation velocity beyond organic growth rates.
Market Restraints
- Corporate practice of medicine prohibitions:State dental boards in the United States restrict ownership structures and service boundaries, creating legal fragmentation that complicates national DSO expansion.
- Cloud infrastructure vendor concentration:Reliance on dominant hyperscale providers creates single-point-of-failure risk for patient data systems across multi-location networks.
- Clinical labor supply constraints:Dental hygienist and assistant shortages in key metropolitan markets limit same-day capacity expansion regardless of administrative scale.
Strategic Opportunities
- Telehealth-integrated urgent dental triage:After-hours virtual consultation platforms capture emergency demand that currently leaks to hospital emergency departments.
- India's emerging DSO formation wave:Regulatory liberalization of healthcare service aggregation creates first-mover advantage for platform operators in underpenetrated metropolitan corridors.
- EU MDR-aligned device software certification:DSOs that pre-validate AI diagnostic tools against European medical device standards unlock faster deployment across multi-country affiliate networks.
Industry Challenges
- Legacy practice management system migration:Data extraction and workflow reconfiguration from on-premise servers to cloud architectures creates operational disruption during affiliation onboarding.
- Cross-state credentialing complexity:Dentist licensure reciprocity gaps between jurisdictions delay multi-state affiliate network expansion despite centralized administrative capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Support Organizations Market |
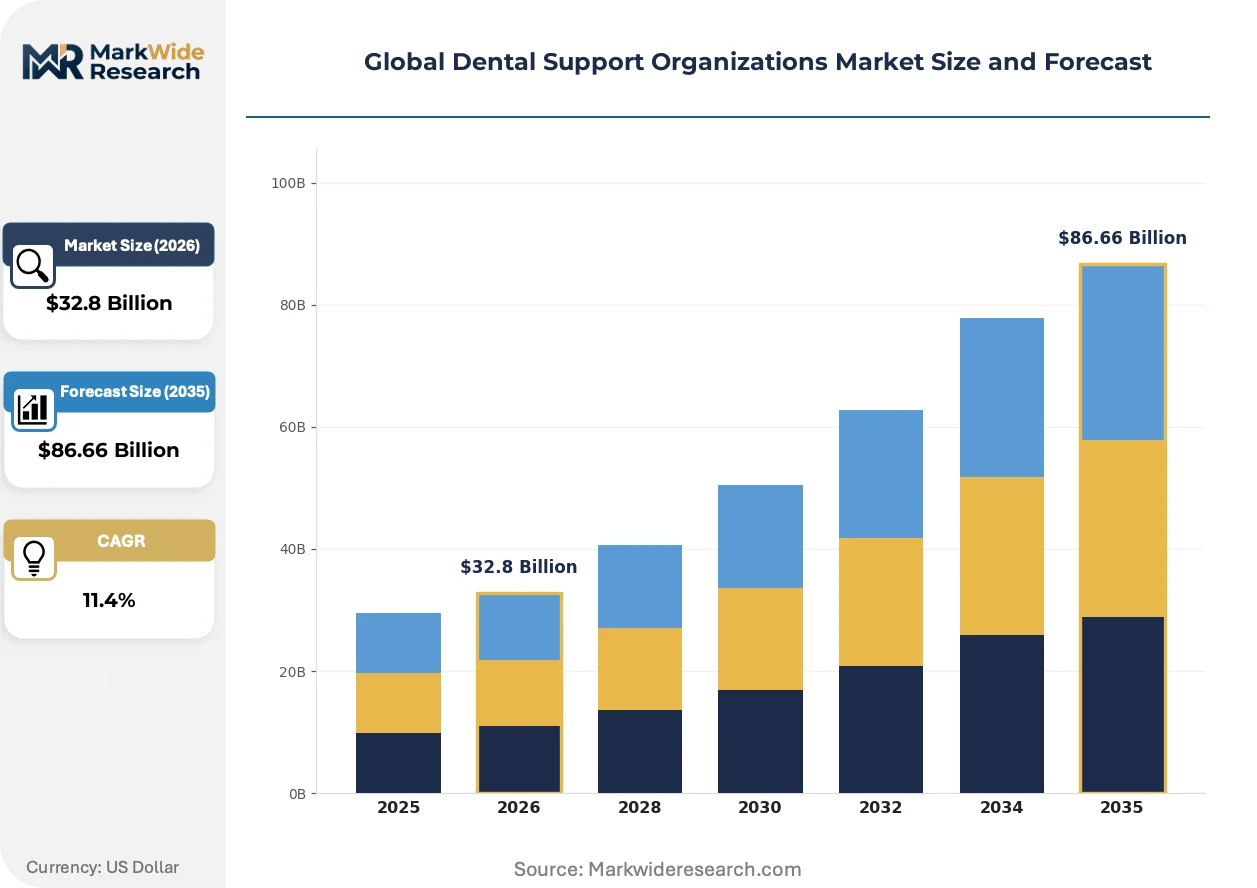
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $86.66 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Practice Management, Marketing Support, Credentialing, Supply Chain Management, Revenue Cycle Management, IT Support Ownership Model: Private Equity, Family-Owned, Partnership, Venture Capital, Individual Practitioner Customer Type: Startups, Established Clinics, Multi-location Practices, Specialty Clinics, Solo Practitioners Technology Adoption: Cloud-Based Solutions, On-Premise Systems, AI-Enabled Platforms, Mobile Applications, Telehealth Integration |
| Companies Covered | Heartland Dental, Aspen Dental, Pacific Dental Services, Dental Care Alliance, Smile Brands Inc, Colosseum Dental Group, 42North Dental, MB2 Dental, GSD Dental Clinics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Support Organizations Market Shifts & Advancements
Technology convergence between diagnostic imaging, patient engagement platforms, and supply chain automation is redefining the operational boundary between clinical and administrative functions within dental service organizations.
AI-powered radiographic interpretation software is absorbing routine diagnostic screening tasks previously performed by general dentists, allowing chairside time to shift toward higher-margin restorative procedures. Mid-market DSOs in the United States and Germany are deploying these tools fastest, driven by labor cost pressure and same-day dentistry throughput targets. The technology is absorbing diagnostic labor hours while compressing specialist referral intervals from weeks to hours.
EU AI Act risk classification requirements are forcing DSOs operating in European markets to rearchitect algorithmic decision-support systems around transparency and human-in-the-loop mandates. High-risk diagnostic applications now require conformity assessment procedures that extend vendor qualification timelines. German and French DSO affiliates face the steepest compliance burden given their early adoption of AI-enabled treatment planning tools.
Subscription-based preventive care memberships are displacing fee-for-service billing for routine hygiene and maintenance visits among younger patient cohorts. DSOs in suburban United States markets pilot these models to improve cash flow predictability and reduce insurance dependency. The shift is most visible in exurban corridors where traditional dental benefit penetration lags metropolitan benchmarks.
Global Dental Support Organizations Market Segmentation
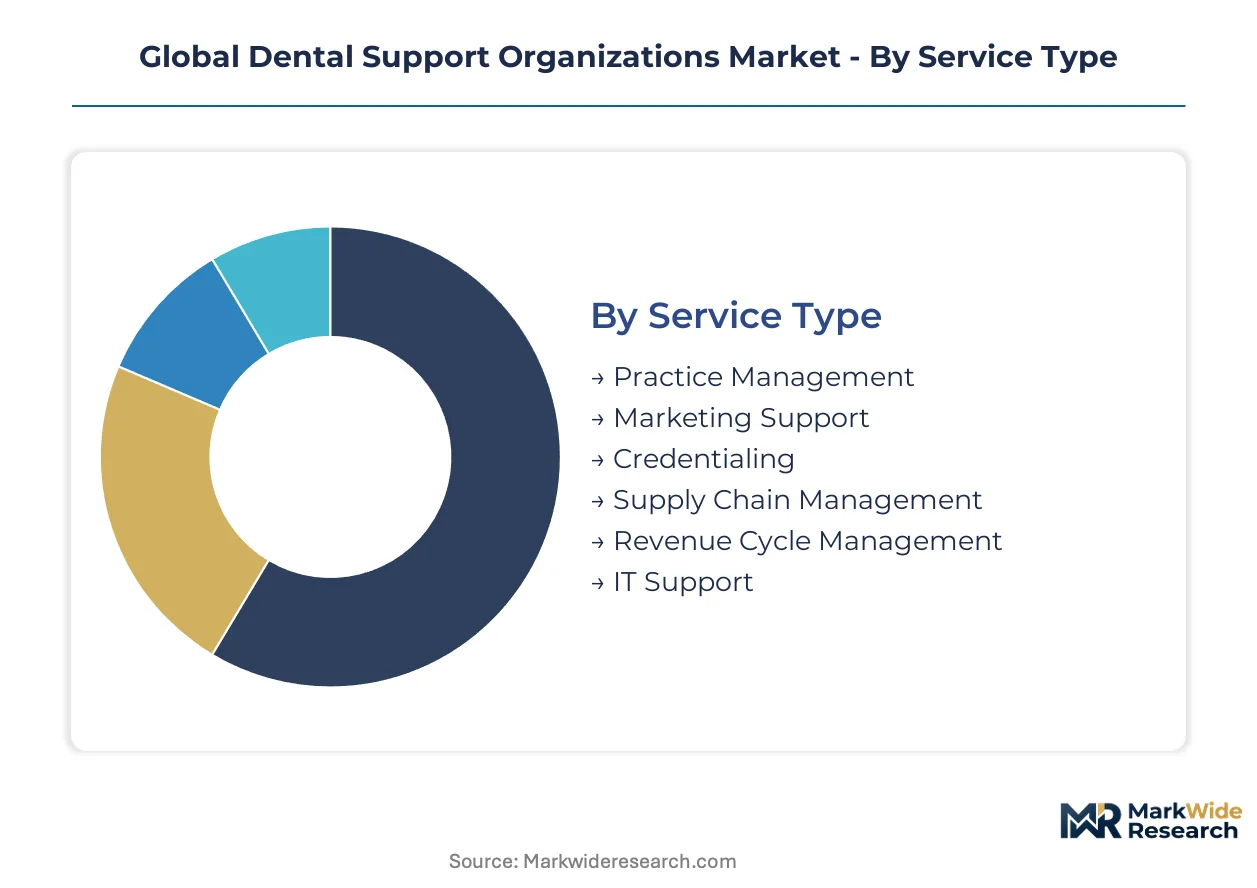
DSO service portfolios fragment across administrative depth, capital backing, and technology maturity. Each segmentation axis reveals distinct margin profiles and competitive moats that determine platform scalability across regulated healthcare markets.
Service Type:
Capital intensity varies sharply across service lines, with technology infrastructure demanding the heaviest upfront deployment while administrative functions scale more linearly.
- Practice Management:Centralized scheduling, patient communication, and clinical workflow orchestration platforms. Multi-location practices in the United States concentrate demand here as they seek to replicate Heartland Dental's operational density without proprietary buildouts.
- Revenue Cycle Management:Claims processing, denial management, and patient billing optimization services. Established clinics across Germany and France prioritize this segment as insurance reimbursement complexity intensifies under EU regulatory harmonization pressures.
- Marketing Support:Patient acquisition campaigns and brand positioning for affiliated practices.
- Credentialing:Provider enrollment and payer contract maintenance across multi-state networks.
- Supply Chain Management:Procurement aggregation and inventory optimization for dental consumables.
- IT Support:Helpdesk services and infrastructure maintenance for hybrid cloud environments.
Practice management absorbs the bulk of installed capacity; revenue cycle management is expanding most quickly as labor costs and reimbursement friction intensify.
Ownership Model:
Funding source dictates growth velocity and risk tolerance, with institutional capital enabling rollup strategies that family capital cannot replicate.
- Private Equity:Sponsor-backed platforms deploy acquisition capital into fragmented practice ownership, prioritizing EBITDA expansion through administrative centralization. US markets dominate this segment given mature dental practice brokerage infrastructure and HIPAA-compliant data frameworks.
- Venture Capital:Technology-first DSOs scaling cloud-native platforms and AI diagnostic tools before affiliate network density. India's metropolitan corridors attract this capital as regulatory liberalization accelerates.
- Family-Owned:Multi-generational platforms with conservative leverage profiles and regional concentration.
- Partnership:Dentist-owned administrative cooperatives sharing overhead without external equity.
- Individual Practitioner:Solo dentists affiliating for non-clinical support while retaining full clinical autonomy.
Private equity structures command the deepest affiliate networks; venture capital backing is gaining share fastest among technology-anchored entrants.
Customer Type:
Practice maturity determines service bundle complexity, with scale thresholds dictating which administrative functions merit externalization.
- Multi-location Practices:Regional dental groups with 3-15 offices seeking procurement scale and brand unification. These customers cluster in US exurban corridors and Indian tier-2 cities where same-day dentistry workflows reduce specialist leakage.
- Established Clinics:Mature single-location practices with stable patient bases optimizing for overhead reduction.
- Startups:De novo practices requiring turnkey operational infrastructure.
- Specialty Clinics:Orthodontic, endodontic, and oral surgery practices with distinct credentialing and supply chain requirements.
- Solo Practitioners:Individual dentists seeking selective administrative relief without full affiliation.
Multi-location practices anchor current revenue concentration; established clinics are converting to DSO affiliation at the steepest rate as retirement transitions accelerate.
Technology Adoption:
Architecture choices lock in cost trajectories and regulatory exposure for the affiliation lifecycle.
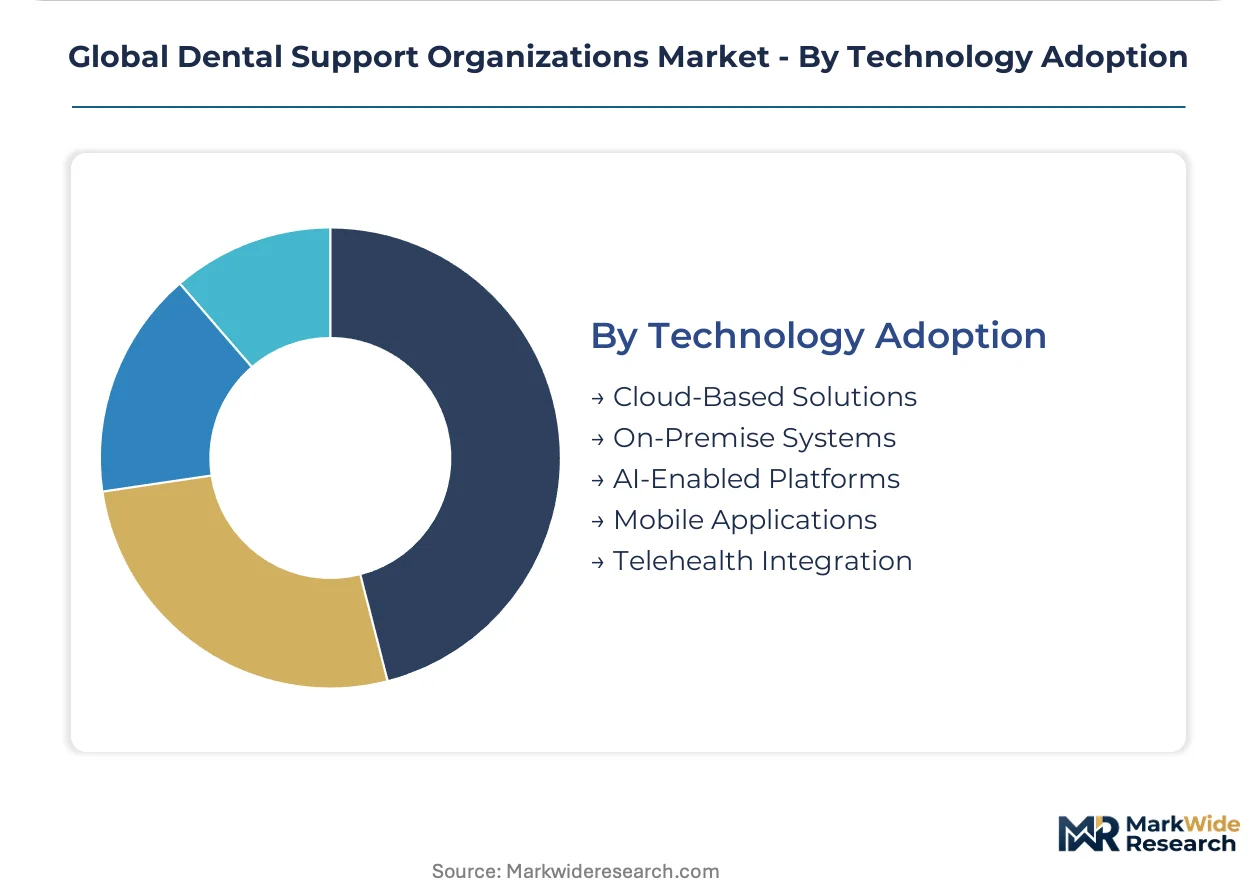
- Cloud-Based Solutions:Subscription-hosted practice management with lower capital requirements and faster multi-location rollout. New DSO deployments in the United States and Germany favor this model as EU AI Act transparency mandates reshape vendor qualification timelines.
- AI-Enabled Platforms:Algorithmic radiographic interpretation and treatment planning tools. Mid-market US DSOs and German affiliates deploy these fastest to compress diagnostic labor hours and capture specialist revenue internally.
- On-Premise Systems:Legacy server-based infrastructure requiring dedicated IT maintenance.
- Mobile Applications:Patient-facing scheduling and communication tools.
- Telehealth Integration:Virtual consultation platforms for urgent triage and post-operative follow-up.
Cloud-based solutions dominate new deployment commitments; AI-enabled platforms are climbing the fastest as labor cost pressure and same-day throughput targets intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private equity capital formation in the United States anchors geographic demand concentration, while regulatory liberalization in India and EU AI Act compliance burdens in Germany reshape expansion trajectories across developed and emerging markets.
United States
Retiring baby-boomer dentists and mature dental practice brokerage infrastructure drive affiliation velocity. HIPAA privacy requirements shape patient data system architecture and vendor selection across multi-state networks. Texas and Florida metropolitan corridors concentrate DSO rollup activity as sponsors deploy acquisition capital into fragmented ownership.
Germany
EU AI Act risk classification requirements force algorithmic decision-support rearchitecture around transparency mandates. CE marking and MDR-aligned device software certification extend vendor qualification timelines for diagnostic platforms. Bavaria and North Rhine-Westphalia host the steepest compliance burden given early adoption of AI-enabled treatment planning tools.
India
Regulatory liberalization of healthcare service aggregation creates first-mover opportunity in underpenetrated metropolitan corridors. CDSCO oversight of medical device software and BIS standards influence platform deployment decisions. Maharashtra and Karnataka tier-2 cities attract venture capital backing for technology-first DSO formation.
United Kingdom
NHS reimbursement complexity and private dental benefit penetration gaps create hybrid service model demand. GDPR data portability requirements complicate cloud-native practice management rollout across affiliate networks. London and Southeast England concentrate multi-location practice consolidation as owners seek procurement scale.
France
ANSM and CNIL oversight of health data systems shapes DSO technology vendor selection and patient consent frameworks. EU MDR compliance timelines delay AI diagnostic tool deployment relative to German affiliates. Île-de-France and Auvergne-Rhône-Alpes anchor administrative platform demand as regional dental groups pursue brand unification.
Global Dental Support Organizations Market Competitive Landscape
Global majors compete with regional champions across administrative depth and technology maturity, producing a tiered structure where scale-driven platforms, technology-anchored entrants, and family-owned cooperatives occupy distinct competitive positions. Consolidation concentrates among private equity-backed rollups in the United States, while fragmentation persists in European markets where national regulatory variation complicates cross-border expansion. Strategic archetypes include sponsor-backed acquisition platforms, cloud-native technology-first DSOs, and dentist-owned administrative cooperatives. Dominant competitive moves center on multi-practice rollup execution and proprietary technology stack development to reduce specialist referral leakage.
Within the sponsor-backed tier, Heartland Dental and Aspen Dental exemplify scale-driven consolidation models, while Pacific Dental Services occupies a position emphasizing proprietary technology infrastructure and same-day dentistry workflows. These three US-based platforms represent contrasting archetypes: operational density leverage, consumer marketing intensity, and clinical workflow automation respectively.
| Leading Market Players |
|---|
| Heartland Dental |
| Aspen Dental |
| Pacific Dental Services |
| Dental Care Alliance |
| Smile Brands Inc |
| Colosseum Dental Group |
| 42North Dental |
| MB2 Dental |
| GSD Dental Clinics |
| Others |
Supply & Pricing Matrix
Certification-tier divergence between HIPAA-compliant cloud platforms and legacy on-premise systems manifests in both subscription pricing and vendor qualification timelines across DSO networks. Premium tiers bundle AI diagnostic modules and same-day dentistry workflows, while economy offerings strip out interoperability features to hit price points for solo practitioner affiliates.
Pricing Analysis
Warranty and service bundling separates full-platform DSO affiliations from à-la-carte administrative modules. Three-tier pricing structure across premium, standard, and economy levels reflects compliance depth, with HIPAA and EU AI Act certification tiers commanding 40-60% premiums over uncertified alternatives. Cost compression in economy tiers intensifies as venture-backed entrants undercut legacy providers. Solo practitioners exhibit highest price sensitivity, while multi-location practices prioritize total cost of ownership over per-seat licensing.
Supply Chain Analysis
Direct-to-DSO channels handle hyperscale buyer demand for cloud infrastructure, bypassing traditional dental distribution intermediaries. Manufacturing concentrates in the United States, Germany, and India for practice management software, with AI diagnostic modules sourcing GPU compute from Taiwan and South Korea. Supply chains draw from dental consumables manufacturers in Mexico, China, and Germany, plus hyperscale cloud providers in the United States and Ireland. Single-source vulnerability in cloud infrastructure creates concentration risk for patient data systems. Distribution runs through vendor-direct enterprise sales teams and dental-specific value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where regulatory compliance burdens and technology investment thresholds force sub-scale operators toward acquisition or exit.
For Market Incumbents: Cement market position through proprietary AI diagnostic stack development and same-day dentistry workflow capture. Defensive moats deepen around HIPAA-compliant data interoperability that smaller competitors cannot replicate. Threat vectors include venture-backed cloud-native entrants and EU AI Act compliance cost escalation. Capacity addition in Texas and Florida metropolitan corridors reinforces geographic density advantages. For New Entrants and Emerging Players: Telehealth-integrated urgent dental triage platforms offer the lowest competitive density entry vector. White-space concentrates in Indian tier-2 cities and US exurban corridors where traditional DSO penetration lags. Go-to-market leverage rests on subscription-based preventive care membership models that displace fee-for-service billing for routine hygiene. For Investors and Strategic Acquirers: Re-rating potential sits with technology-anchored mid-market DSOs given AI diagnostic adoption acceleration and same-day dentistry throughput expansion. Long-term viability favors platforms with cloud-native architecture and multi-state credentialing infrastructure already deployed. Acquisition target archetype: regional dental groups with 3-15 offices lacking proprietary technology stacks. Monitor CDSCO regulatory liberalization pace in India as inflection signal for emerging market platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| AI Diagnostic Platform Integration | Captures specialist revenue internally through algorithmic radiographic interpretation reducing referral leakage. |
| Same-Day Dentistry Workflow Deployment | Compresses treatment intervals from weeks to hours using proprietary scheduling and chairside coordination systems. |
| Multi-State Credentialing Infrastructure | Enables rapid affiliate network expansion across jurisdictions with reciprocity gaps that delay competitors. |
| Subscription-Based Preventive Care Membership | Reduces insurance dependency and improves cash flow predictability among younger patient cohorts in exurban markets. |
| EU AI Act Compliance Pre-Validation | Unlocks faster AI diagnostic tool deployment across German and French affiliate networks ahead of MDR-aligned certification timelines. |
Research Methodology
Document review covered DSO affiliation agreements, HIPAA compliance frameworks, and EU AI Act implementation guidance, complemented by interviews with dental practice owners, private equity sponsors, cloud infrastructure vendors, and state dental board regulators. Secondary validation drew from FDA medical device software filings, CMS Medicare reimbursement data, and dental practice brokerage transaction records. Bottom-up affiliate network modeling triangulated against top-down private equity capital formation estimates.
Market size outputs reflect segment-level reconciliation across service type, ownership model, and technology adoption dimensions over the projection horizon. CAGRs derived from affiliate velocity modeling, technology penetration curves, and regulatory liberalization scenario weighting. Forecast inputs incorporated dental hygienist labor supply constraints, cloud infrastructure vendor concentration risk, and state-level corporate practice of medicine enforcement variance.
The model holds under stable regulatory interpretation of corporate practice prohibitions and continued private equity capital availability; deviation in antitrust scrutiny intensity or HIPAA enforcement escalation would shift affiliation velocity assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Services
Dental Service Organization Market
Dental Services
Dental Fluoride Treatment Market
Dental Services
Microdontia Treatment Market
Dental Services
Periodontal Dental Service Market
Dental Services
US Dental Chains Market
Dental Services
Dental Services Market
Dental Services
Chronic Gingivostomatitis Treatment Market
Dental Services
Orthodontic Services Market
Dental Services
Dental Market
Dental Services
United States Dental Services Market
Dental Services
EMEA Dental Service Organization Market
Dental Services
Teledentistry Market