
 Australia Healthcare Surface Disinfectant Wipes Market | 2026-2036
Australia Healthcare Surface Disinfectant Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Healthcare Surface Disinfectant Wipes Market Outlook
Australian nonwoven substrate producers is broadening output capacity for medical-grade wipe substrates, responding to sustained hospital procurement cycles. TIDDOX leverages its domestic manufacturing footprint to supply private-label and branded disinfectant wipes across acute-care channels. Whiteley sustains competitive positioning through specialized quaternary ammonium formulations tailored to Australian healthcare settings. GAMA Healthcare anchors its presence via extensive distribution into NHS-equivalent procurement frameworks and private hospital groups.
Australia healthcare surface disinfectant wipes are nonwoven substrates impregnated with antimicrobial chemistries, typically containing alcohol concentrations between 60-80% or quaternary ammonium compounds at 0.5-1.5% active levels, engineered for single-use decontamination of medical equipment and environmental surfaces. Their primary purpose is breaking chain-of-infection pathways in clinical settings where hand hygiene alone proves insufficient. Alcohol wipes occupy the largest volume share among product types due to immediate kill kinetics and compatibility with most device surfaces. Long-term care facilities represent the fastest-expanding end-user channel as Australia's aged-care sector intensifies environmental cleaning protocols following regulatory scrutiny. Soft packs are gaining packaging preference over rigid canisters in mobile clinical units where weight and disposal volume constrain operational logistics.
The Therapeutic Goods Administration governs disinfectant wipe claims through its medical device and disinfectant frameworks, while Standards Australia maintains AS/NZS 4187 for reprocessing reusable medical equipment, creating overlapping compliance obligations for surface disinfection products. Healthcare facilities must additionally navigate state-based health department infection control guidelines that mandate specific wipe chemistries for outbreak containment scenarios. Stakeholders should monitor TGA's ongoing alignment with European Medical Device Regulation technical documentation requirements, as divergence or convergence will reshape product registration timelines and competitive entry barriers.
Market Dynamics
The Therapeutic Goods Administration's tightening validation requirements for sporicidal claims is compressing product registration timelines and forcing substrate-chemistry integration decisions earlier in development cycles.
Growth Catalysts
- AS/NZS 4187 Compliance Mandates:Reprocessing standards for reusable medical equipment now explicitly reference surface disinfection protocols, embedding wipe procurement into capital equipment budgets across New South Wales and Victoria hospital networks.
- Aged-Care Regulatory Scrutiny:Royal Commission findings have triggered mandatory environmental cleaning frequency increases in residential aged-care facilities, opening a new volume channel distinct from acute-care procurement cycles.
- Substrate Engineering Advances:Domestic nonwoven producers are commercializing medical-grade cellulose-polyester laminates with controlled liquid release profiles, reducing alcohol evaporation during extended cleaning procedures.
Market Restraints
- Isopropyl Alcohol Price Volatility:Feedstock costs for 70% alcohol formulations fluctuate with crude-derived propylene markets, compressing margin buffers for contract manufacturers serving public hospital tenders.
- Single-Source Substrate Dependency:Australian nonwoven capacity concentrates among three domestic producers, creating supply concentration risk when hospital procurement cycles synchronize post-budget announcements.
- Quaternary Ammonium Efficacy Limitations:TGA-registered QAC formulations demonstrate reduced activity against non-enveloped viruses, restricting their deployment in outbreak containment scenarios specified by state health department guidelines.
Strategic Opportunities
- Western Australia Hospital Expansion:Mining-boom infrastructure investment is delivering new tertiary facilities in Perth and regional hubs where infection control protocols are being specified greenfield rather than retrofitted.
- Soft-Pack Channel Innovation:Mobile clinical units in Queensland's remote health services are abandoning rigid canisters for flexible packaging that reduces disposal volume and transport weight in fixed-wing aircraft resupply.
- TGA-EU MDR Alignment:Convergence between Australian and European medical device technical documentation requirements would enable dual-registration strategies, compressing time-to-market for imported formulations.
Industry Challenges
- Microbiological Validation Talent Scarcity:TGA's sporicidal claim requirements demand in-house EN 13704 testing capability, but qualified laboratory personnel concentrate in Sydney and Melbourne, constraining regional manufacturer expansion.
- Legacy Equipment Compatibility Certification:Disinfectant wipe chemistries must demonstrate material compatibility with ultrasound probes, endoscopes, and monitoring equipment across multiple OEM specifications, extending product development timelines.
- Waste Stream Integration Complexity:Single-use wipe disposal must align with state-based clinical waste segregation protocols that vary between New South Wales, Victoria, and Queensland, complicating national distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Healthcare Surface Disinfectant Wipes Market |
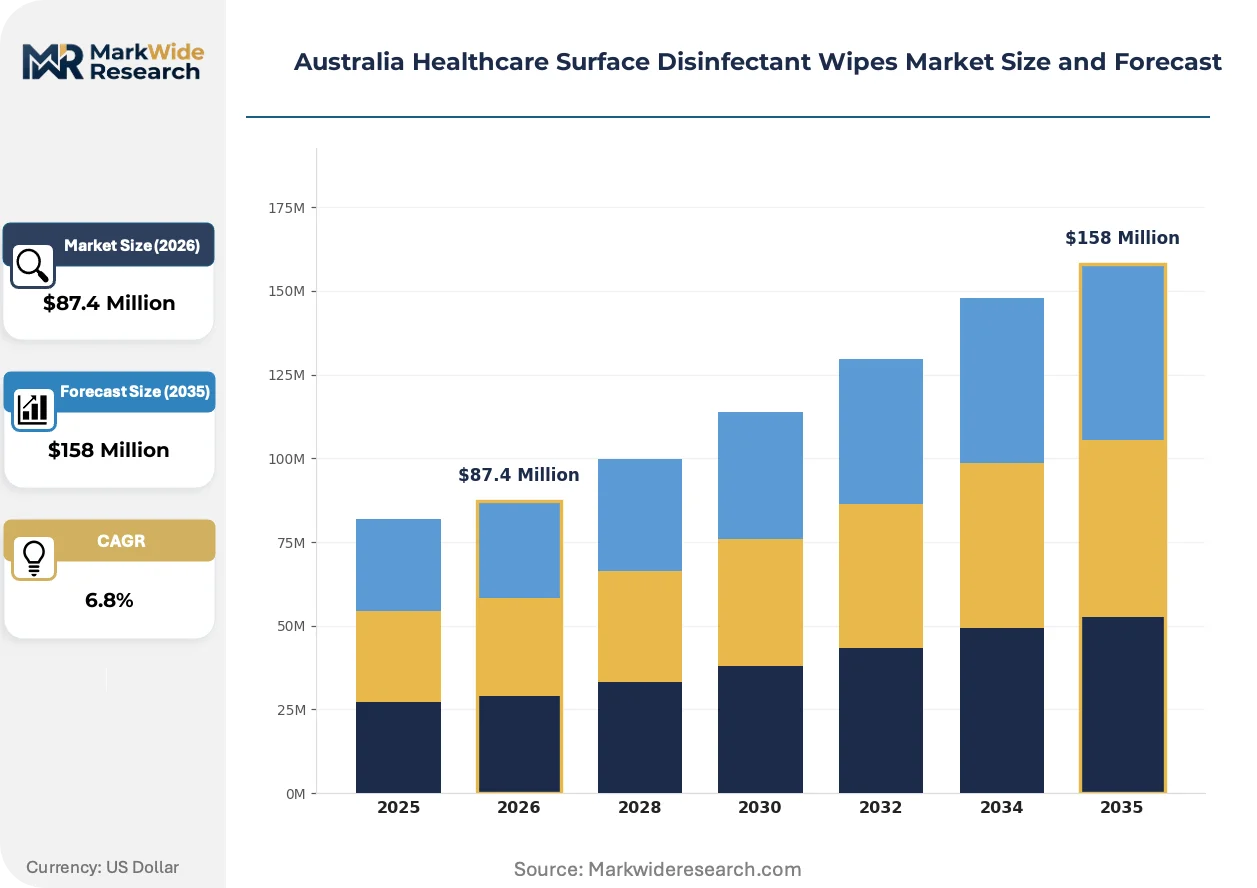
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bleach Wipes, Alcohol Wipes, Biodegradable Wipes, Multi-Surface Wipes End User: Hospitals, Clinics, Long-Term Care Facilities, Home Care Packaging Type: Canisters, Soft Packs, Individually Wrapped, Bucket Packs Formulation: Alcohol-Based, Non-Alcohol Based, Quaternary Ammonium Compounds, Hydrogen Peroxide |
| Companies Covered | TIDDOX, Whiteley, WOW Wipes, Superior Healthcare Australia, Clifford Hallam Healthcare, Reynard Health, McFarlane Medical, Team Medical Supplies, GAMA Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Healthcare Surface Disinfectant Wipes Market Strategic Shifts
Substrate-chemistry integration is displacing off-the-shelf formulation approaches as hospitals demand validated systems rather than commodity components. Manufacturers are responding with co-developed wipe-dispensing systems.
Biodegradable cellulose substrates are expanding into alcohol-impregnated formats previously dominated by synthetic nonwovens. Queensland's rural health services are piloting these materials in remote clinics where waste incineration costs exceed metropolitan levels. The technology is expanding into premium positioning as sustainability metrics enter public hospital tender evaluation frameworks.
TGA's alignment trajectory with European Medical Device Regulation technical documentation is forcing early-stage design-dossier preparation. Manufacturers must now compile clinical evidence packages during formulation development rather than post-production. Private hospital groups with dual Australian-European procurement systems are experiencing accelerated registration timelines as dossier modules achieve mutual recognition.
Hospital buying consortia are consolidating surface disinfection procurement into bundled infection control contracts. Queensland Health's state-wide tender now combines wipes, hand rubs, and automated dispensers under single-supplier frameworks. This pattern is most visible in metropolitan networks where standardization reduces nursing staff training burden across rotating shift patterns.
Australia Healthcare Surface Disinfectant Wipes Market Segmentation
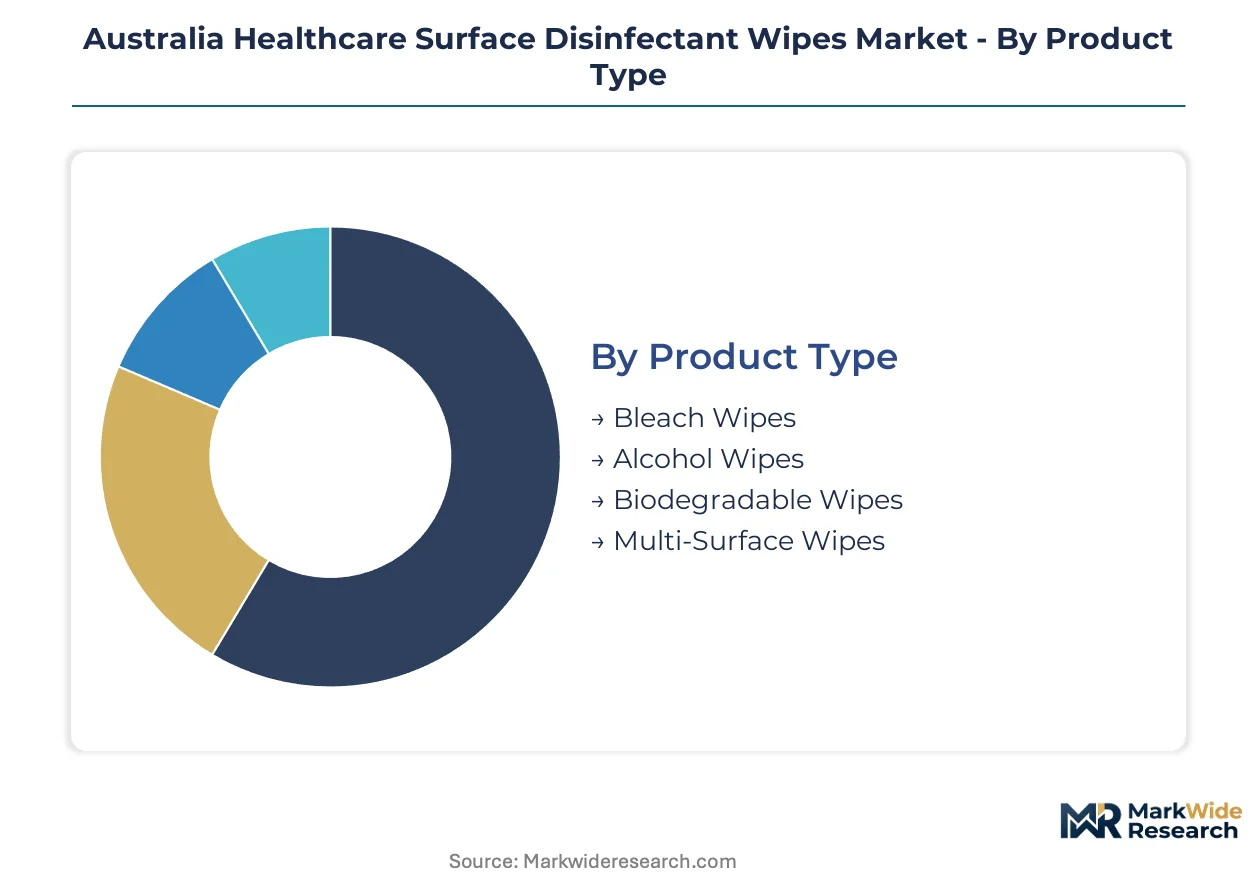
Disinfectant wipe procurement patterns in Australia diverge sharply between acute-care networks with capital equipment budgets and aged-care facilities operating under fixed per-bed cost structures. Substrate-chemistry integration decisions now precede tender participation, forcing manufacturers to align product architectures with specific channel requirements before registration.
Product Type:
Substrate engineering capabilities concentrate among three domestic nonwoven producers, shaping which chemistries achieve viable commercial scale.
- Alcohol Wipes:Nonwoven substrates impregnated with 60-80% isopropyl or ethyl alcohol formulations deliver immediate kill kinetics against enveloped viruses and most bacteria. New South Wales and Victoria hospital networks embed these into high-touch surface protocols where dwell time constraints prevent slower-acting alternatives. Procurement cycles for alcohol wipes synchronize with state budget announcements, creating demand spikes that strain domestic alcohol blending capacity.
- Bleach Wipes:Sodium hypochlorite-impregnated substrates at 0.5-1.0% available chlorine provide sporicidal activity required for Clostridioides difficile containment scenarios. TGA's tightening validation requirements for sporicidal claims favor established manufacturers with in-house EN 13704 testing capability, compressing competitive entry.
- Biodegradable Wipes:Cellulose-based substrates with controlled biodegradation profiles serve Queensland rural health services where waste incineration costs exceed metropolitan levels.
- Multi-Surface Wipes:Quaternary ammonium compound formulations balanced for material compatibility across ultrasound probes, monitors, and furniture surfaces.
Alcohol wipes absorb the bulk of installed capacity; biodegradable wipes are expanding most quickly.
End User:
Channel-specific regulatory pressures reshape volume distribution across customer types.
- Hospitals:Tertiary facilities in New South Wales and Victoria drive specification-grade procurement through infection control committees with non-discretionary budgets. AS/NZS 4187 compliance mandates now embed surface disinfection protocols into capital equipment reprocessing contracts, locking wipe procurement into multi-year frameworks.
- Long-Term Care Facilities:Royal Commission findings triggered mandatory environmental cleaning frequency increases in residential aged care, opening a volume channel with distinct procurement cycles from acute care. Facilities operate under per-bed funding models that prioritize cost-per-wipe metrics over validated kill claims.
- Clinics:General practice and specialist day-procedure centers with limited storage space favor compact packaging formats.
- Home Care:Individual consumers purchasing through pharmacy and medical supply channels.
Hospitals command specification authority; long-term care facilities are climbing the fastest.
Packaging Type:
Operational constraints in mobile and remote settings drive format innovation faster than metropolitan procurement.
- Soft Packs:Flexible laminated film packaging reduces transport weight and disposal volume for Queensland's remote health services using fixed-wing aircraft resupply. The format gains traction in mobile clinical units where rigid canisters create space and waste handling constraints.
- Canisters:Rigid plastic dispensers with resealable lids dominate hospital central supply storage for their stackability and moisture retention.
- Individually Wrapped:Single-unit sterile packaging for procedure-specific applications.
- Bucket Packs:High-capacity refill formats for environmental services carts in large facilities.
Canisters retain the largest volume share; soft packs are gaining share fastest.
Formulation:
Chemistry selection tracks TGA registration pathways and state health department outbreak protocols.
- Alcohol-Based:60-80% ethanol or isopropanol formulations dominate device surface applications for their rapid evaporation and broad material compatibility. TGA's medical device framework governs claims, with registration timelines compressing as dossier modules achieve alignment with European MDR technical documentation.
- Quaternary Ammonium Compounds:QAC formulations at 0.5-1.5% active levels provide residual activity on environmental surfaces but demonstrate reduced efficacy against non-enveloped viruses. State health department guidelines restrict their deployment in outbreak containment scenarios, limiting addressable market scope.
- Non-Alcohol Based:Alternative active systems for alcohol-sensitive equipment surfaces.
- Hydrogen Peroxide:Accelerated hydrogen peroxide chemistries for sporicidal applications with improved material compatibility versus bleach.
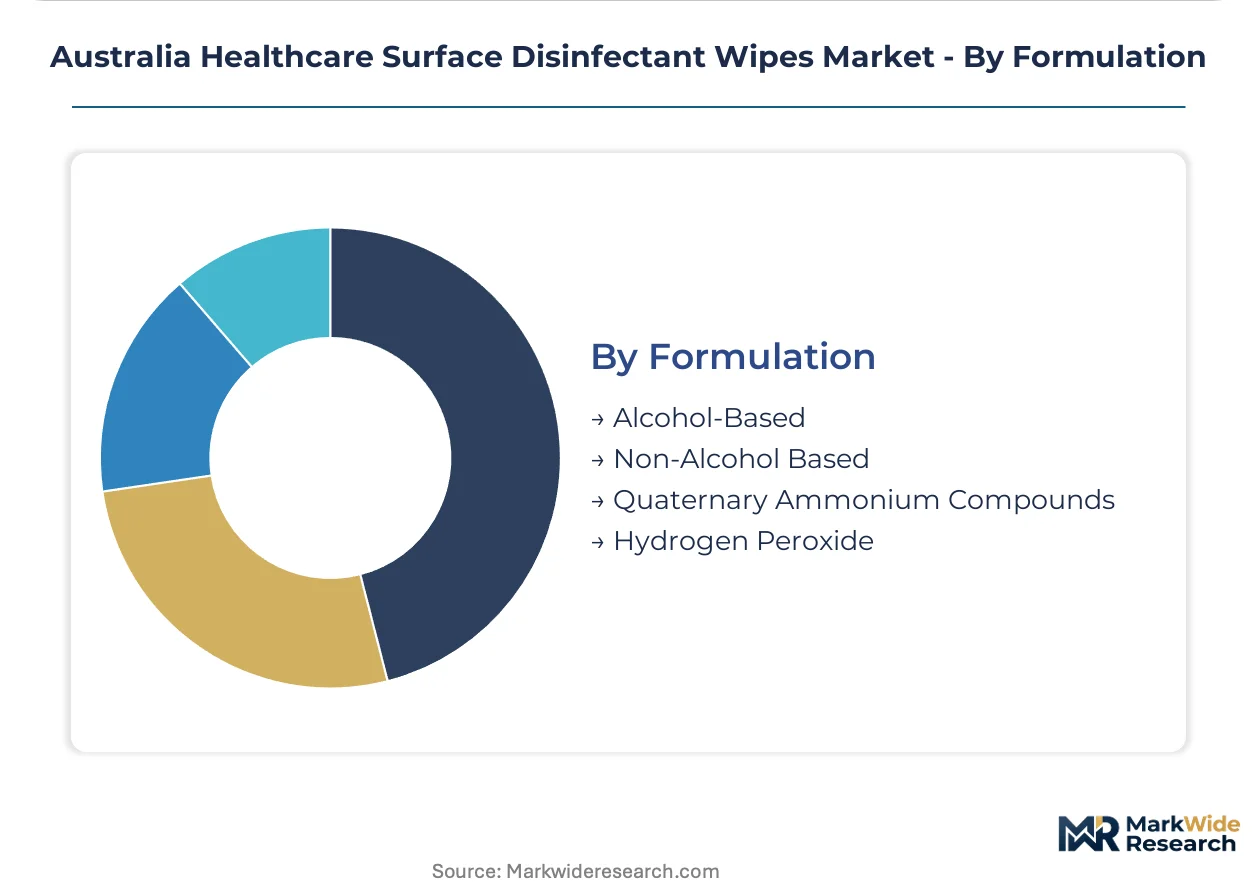
Alcohol-based formulations anchor procurement volume; hydrogen peroxide systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Isopropyl alcohol feedstock flows through Port Botany and Geelong refineries anchor disinfectant wipe production capacity in southeastern Australia. Hospital procurement networks in New South Wales and Victoria concentrate demand volume. Western Australia's mining-funded infrastructure expansion is creating new specification opportunities.
New South Wales
Sydney's tertiary hospital networks drive specification-grade procurement through infection control committees with embedded AS/NZS 4187 compliance mandates. The Therapeutic Goods Administration's medical device framework governs wipe registration timelines for products entering NSW Health's state-wide tender system. Domestic nonwoven producers in the Sydney basin are expanding cellulose-polyester laminate capacity to meet synchronized post-budget demand spikes.
Victoria
Melbourne's hospital procurement consortia bundle surface disinfection into multi-year infection control contracts with non-discretionary budget allocations. State health department outbreak protocols specify alcohol-based formulations for high-touch surface decontamination in metropolitan facilities. The city's concentrated laboratory services sector supports EN 13704 sporicidal validation testing for TGA-registered products.
Queensland
Remote health services using fixed-wing aircraft resupply are abandoning rigid canisters for soft-pack formats that reduce transport weight and disposal volume. State-based clinical waste segregation protocols mandate specific disposal pathways that complicate national distribution strategies. Brisbane-based distributors are piloting biodegradable cellulose substrates in rural clinics where waste incineration costs exceed metropolitan levels.
Western Australia
Mining-boom infrastructure investment is delivering new tertiary facilities in Perth where infection control protocols are being specified greenfield rather than retrofitted. The state's health department procurement framework lacks the consolidated buying power of eastern seaboard consortia. Regional hubs in the Pilbara and Goldfields are importing specification-grade products through Perth distribution channels.
South Australia
Adelaide's hospital networks participate in national buying consortia but operate smaller procurement volumes than Sydney or Melbourne counterparts. The state's aged-care sector is intensifying environmental cleaning protocols following federal regulatory scrutiny of residential facilities. Local distributors serve as intermediaries for eastern states manufacturers seeking western market access.
Australia Healthcare Surface Disinfectant Wipes Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biodegradable substrate specialization and remote-service packaging innovation. Three domestic nonwoven manufacturers anchor upstream supply concentration, creating dependency relationships with downstream wipe assemblers. Market structure fragments between hospital-specification specialists and aged-care cost-optimizers. Dominant competitive moves include substrate-chemistry co-development partnerships and state-level tender consortium participation.
Among Australian-based manufacturers, TIDDOX leverages its domestic production footprint to supply branded and private-label formats across acute-care channels. Whiteley occupies a position exemplifying specialized formulation development, with quaternary ammonium systems tailored to local healthcare settings. GAMA Healthcare anchors the imported-formulation segment through distribution into procurement frameworks serving private hospital groups. These three represent distinct archetypes: domestic integrated production, chemistry specialization, and international scale with local distribution adaptation.
| Leading Market Players |
|---|
| TIDDOX |
| Whiteley |
| WOW Wipes |
| Superior Healthcare Australia |
| Clifford Hallam Healthcare |
| Reynard Health |
| McFarlane Medical |
| Team Medical Supplies |
| GAMA Healthcare |
| Others |
Value Chain & Pricing Dynamics
Biodegradable substrate mandates from Queensland's waste reduction frameworks gate premium-tier pricing access for manufacturers lacking certified cellulose supply chains, while simultaneously compressing margin buffers for standard-tier producers dependent on synthetic nonwoven inputs. TGA's evolving sporicidal validation requirements further stratify supply qualification, embedding chemistry-substrate integration costs into tiered pricing architectures across New South Wales and Victoria hospital networks.
Pricing Analysis
Service-bundling separates validated sporicidal claims with EN 13704 testing documentation from unbundled commodity formulations lacking outbreak-containment certification. Three-tier pricing structure across premium, standard, and economy levels reflects TGA registration tier, state health department guideline alignment, and volume scale commitments. Price differentiation hinges on substrate-chemistry integration depth, with premium tiers commanding position through demonstrated material compatibility across ultrasound probe OEM specifications. Margins are tightening due to isopropyl alcohol feedstock volatility linked to crude-derived propylene markets. Long-term care facilities exhibit highest price sensitivity under per-bed funding constraints, while tertiary hospital infection control committees prioritize validated kill claims over cost-per-wipe metrics.
Supply Chain Analysis
Regional distribution centers in Sydney and Melbourne operate hub-and-spoke patterns feeding Queensland remote health services and Western Australia mining-boom infrastructure sites. Domestic nonwoven production concentrates in Australia's southeastern manufacturing corridor, with cellulose-polyester laminate capacity expanding in the Sydney basin. Raw material dependencies span isopropyl alcohol from Port Botany and Geelong refineries, medical-grade cellulose pulp from New Zealand and Southeast Asian suppliers, and quaternary ammonium compound active ingredients from Chinese and Indian chemical manufacturers. Single-source substrate vulnerability creates supply concentration risk when hospital procurement cycles synchronize post-budget announcements. Distribution runs through state health department tender consortia and private hospital group purchasing organizations with divergent specification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around substrate-chemistry integration capabilities, with TGA's tightening sporicidal validation requirements forcing smaller contract manufacturers toward exit or acquisition. Royal Commission-driven aged-care procurement expansion offers volume refuge for cost-optimized players lacking hospital-specification credentials.
For Market Incumbents: Hedge against quaternary ammonium compound efficacy limitations by accelerating hydrogen peroxide formulation development and securing biodegradable substrate supply agreements ahead of Queensland's waste reduction enforcement timeline. Acquire EN 13704 testing capability in Melbourne or Sydney to compress product registration timelines as TGA aligns with European Medical Device Regulation technical documentation requirements. Defensive capacity addition in Perth addresses Western Australia's greenfield hospital infrastructure without eastern seaboard procurement consortia competition. For New Entrants and Emerging Players: The price-point gap between premium sporicidal formulations and economy-tier aged-care products creates entry space for mid-market players offering validated alcohol-based wipes with soft-pack packaging innovation. Queensland's remote health services represent the most penetrable geography, with fixed-wing aircraft resupply logistics favoring lightweight flexible formats over established canister suppliers. Go-to-market execution should target state-based clinical waste segregation protocol compliance as a differentiated positioning lever against national distributors struggling with interstate regulatory variation. For Investors and Strategic Acquirers: TGA's publication of aligned European Medical Device Regulation technical documentation requirements is the leading indicator that dual-registration capability will separate viable acquisition targets from stranded asset risks. Five-to-ten-year viability favors domestic integrated manufacturers with captive nonwoven supply and in-house microbiological validation infrastructure. Acquisition targets should demonstrate established presence in either New South Wales-Victoria hospital networks or Queensland aged-care distribution channels. Monitor state health department guideline updates specifying wipe chemistry for outbreak containment scenarios as the signal for portfolio rebalancing toward sporicidal-capable assets.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Dual-Registration Capability Investment | Compresses time-to-market for European-imported formulations entering Australian hospital procurement frameworks. |
| Soft-Pack Manufacturing Line Expansion | Captures Queensland remote health services demand where fixed-wing aircraft resupply constrains rigid canister logistics. |
| Biodegradable Substrate Supply Agreement | Secures premium-tier positioning as sustainability metrics enter public hospital tender evaluation frameworks. |
| EN 13704 Testing Laboratory Acquisition | Addresses microbiological validation talent scarcity constraining regional manufacturer expansion beyond Sydney and Melbourne. |
| Western Australia Distribution Partnership | Establishes presence in Perth's greenfield tertiary facilities before eastern seaboard consortia consolidate procurement. |
Study Parameters
Document review covered TGA disinfectant registration databases, AS/NZS 4187 reprocessing standards documentation, state health department infection control guidelines, and hospital procurement tender records, complemented by interviews with infection control committee members, biomedical equipment engineers, GPO contracts managers, and nonwoven substrate manufacturing executives. Secondary validation drew from Standards Australia technical publications, Therapeutic Goods Administration medical device framework updates, and Royal Commission into Aged Care Quality and Safety evidentiary submissions. Bottom-up demand modeling triangulated against top-down healthcare expenditure forecasts across the analysis window.
Segmentation outputs reflect product type, end user channel, packaging format, and formulation chemistry dimensions modeled across metropolitan hospital networks, regional aged-care facilities, and remote health services. CAGRs were derived from regression analysis against historical procurement cycle synchronization patterns and regulatory enforcement timeline assumptions. Forecast inputs incorporated substrate engineering advancement trajectories, isopropyl alcohol feedstock price volatility bands, and TGA-EU MDR alignment probability scenarios.
Inputs from state health department procurement officers and private hospital group purchasing managers were available through the study window; gaps in real-time aged-care facility inventory data introduce uncertainty bands around long-term care channel volume projections. Forecasts reflect documented assumption sets regarding regulatory alignment timelines and infrastructure investment completion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Disinfection Cupboard Market
Infection Control
Ear Infection Treatment Market
Infection Control
Veterinary Disinfectant for Pets and Farms Market
Infection Control
Blood Stream Infection Testing Market
Infection Control
Disinfection Equipment Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Global Pseudomonas Aeruginosa Infection Treatment Market
Infection Control
Infection Prevention Market
Infection Control
Hygiene Stations Market
Infection Control
Pertussis Infection Testing Market
Infection Control
Antimicrobial Wipes Market
Infection Control
Global High Level Disinfection Services Market
Infection Control
Preventable Vaccines Market
Infection Control
Global Prophylactic Human Vaccine Market
Infection Control
Antiseptic Bathing Market
Infection Control
Hand Hygiene Products Market