
 Yeast Infection Market | 2026-2036
Yeast Infection Market Size, Share, and Industry Trends Forecast 2026-2036
Yeast Infection Market Outlook
Aftermarket service revenue from patient adherence programs is rewriting how chronic candidiasis management generates lifetime value. Pfizer Inc. leverages its hospital formulary relationships to sustain prescription volumes for systemic antifungals. Bayer AG anchors its consumer health division with over-the-counter topical azoles that dominate pharmacy shelf space. Mycovia Pharmaceuticals differentiates through novel polyene-sparing mechanisms that compete against legacy fluconazole generics.
Yeast infection refers to mucocutaneous overgrowth of Candida species—primarily Candida albicans—treated with azole antifungals, polyenes, or echinocandins targeting ergosterol biosynthesis or cell membrane integrity. These therapies resolve vulvovaginal, oropharyngeal, and invasive candidiasis in immunocompromised and diabetic patient populations. Oral antifungals command the largest revenue pool due to systemic bioavailability and reimbursement coverage, while probiotics represent the fastest-expanding segment as patients seek microbiome-restoring adjuncts to reduce recurrence. Combination therapies concentrate margin pools where clinicians prescribe sequential topical-oral regimens for refractory infections.
FDA antimicrobial resistance guidance and EMA pharmacovigilance requirements shape clinical trial endpoints and label claims for new antifungal entrants. WHO essential medicines listings influence national procurement tenders and access pathways in low-income settings. Stakeholders must monitor evolving resistance surveillance data and regulatory pathways for non-azole mechanisms to prioritize development portfolios.
Market Dynamics
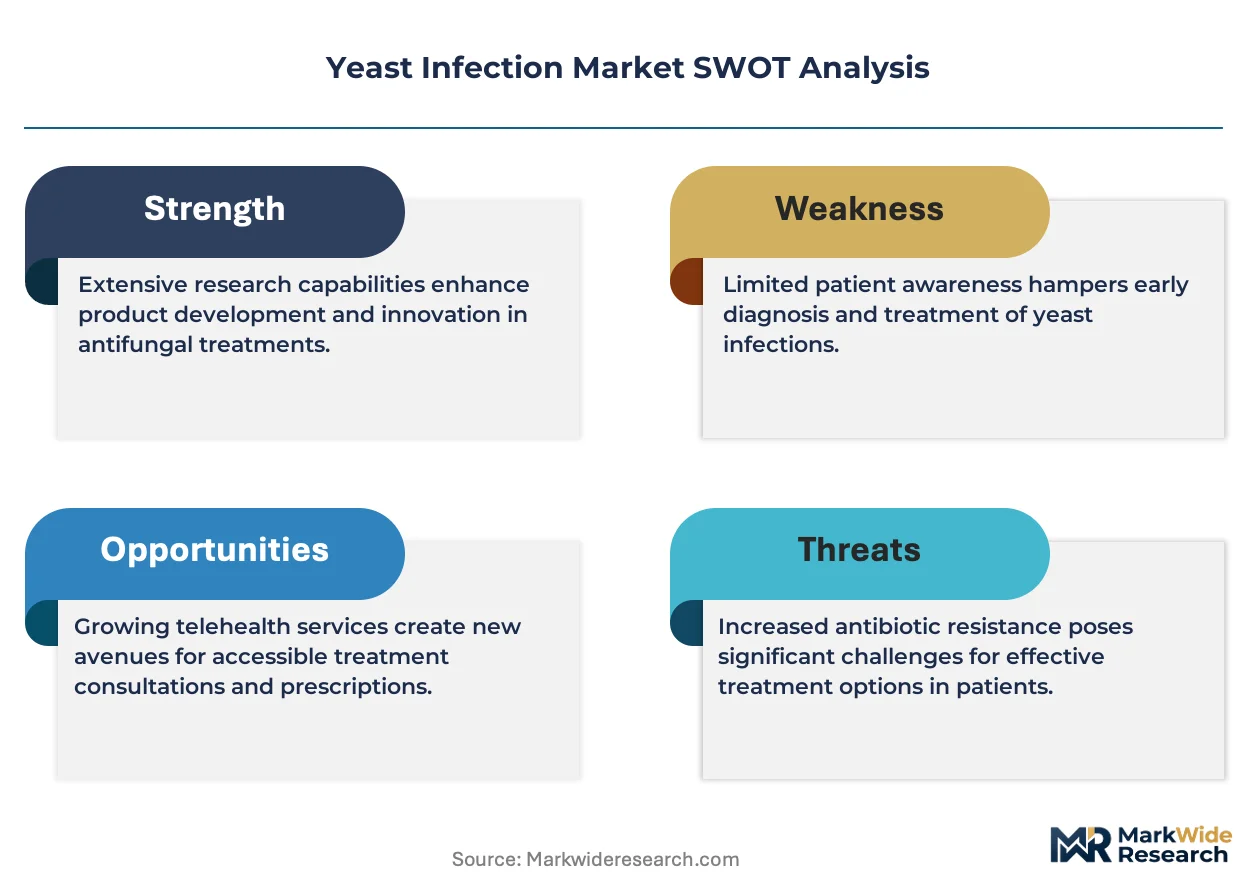
Antimicrobial resistance surveillance is compressing development timelines for novel antifungal mechanisms while tightening formulary access for legacy azole therapies in hospital procurement channels.
Growth Catalysts
- FDA Antimicrobial Resistance Guidance:Accelerated review pathways for non-azole mechanisms incentivize investment in polyene-sparing and echinocandin-class candidates targeting refractory Candida strains.
- Diabetes Prevalence Clusters:Immunocompromised patient populations in the United States and Japan generate sustained demand for systemic antifungal prophylaxis and recurrent infection management protocols.
- Microbiome Restoration Adjuncts:Probiotic co-prescription protocols in German outpatient settings are expanding addressable patient touchpoints beyond standalone pharmaceutical interventions.
Market Restraints
- Generic Fluconazole Saturation:Patent-expired azole formulations dominate pharmacy reimbursement tiers, compressing price realizations for novel therapeutic entrants in outpatient channels.
- Active Pharmaceutical Ingredient Concentration:Polyene and echinocandin API production concentrates in Indian and Chinese contract manufacturing organizations, exposing supply continuity to geopolitical trade friction.
- EMA Pharmacovigilance Requirements:Extended safety surveillance mandates for systemic antifungals extend post-approval cost burdens and delay label expansion for new indications.
Strategic Opportunities
- Combination Therapy Protocols:Sequential topical-oral regimens for refractory vulvovaginal candidiasis capture margin pools in United States specialty gynecology practices seeking recurrence reduction.
- Patient Adherence Platforms:Digital therapeutics and remote monitoring integrations create aftermarket revenue streams in chronic candidiasis management beyond initial prescription fulfillment.
- WHO Essential Medicines Alignment:National procurement tenders in low-income settings favor manufacturers achieving prequalification status for systemic antifungal access pathways.
Industry Challenges
- Antifungal Stewardship Expertise Gap:Hospital pharmacy and infectious disease departments face shortages of specialized clinicians trained in resistance-pattern interpretation and formulary optimization.
- Clinical Trial Endpoint Standardization:Divergent FDA and EMA requirements for mycological versus clinical cure endpoints complicate global development program design and regulatory submission strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yeast Infection Market |
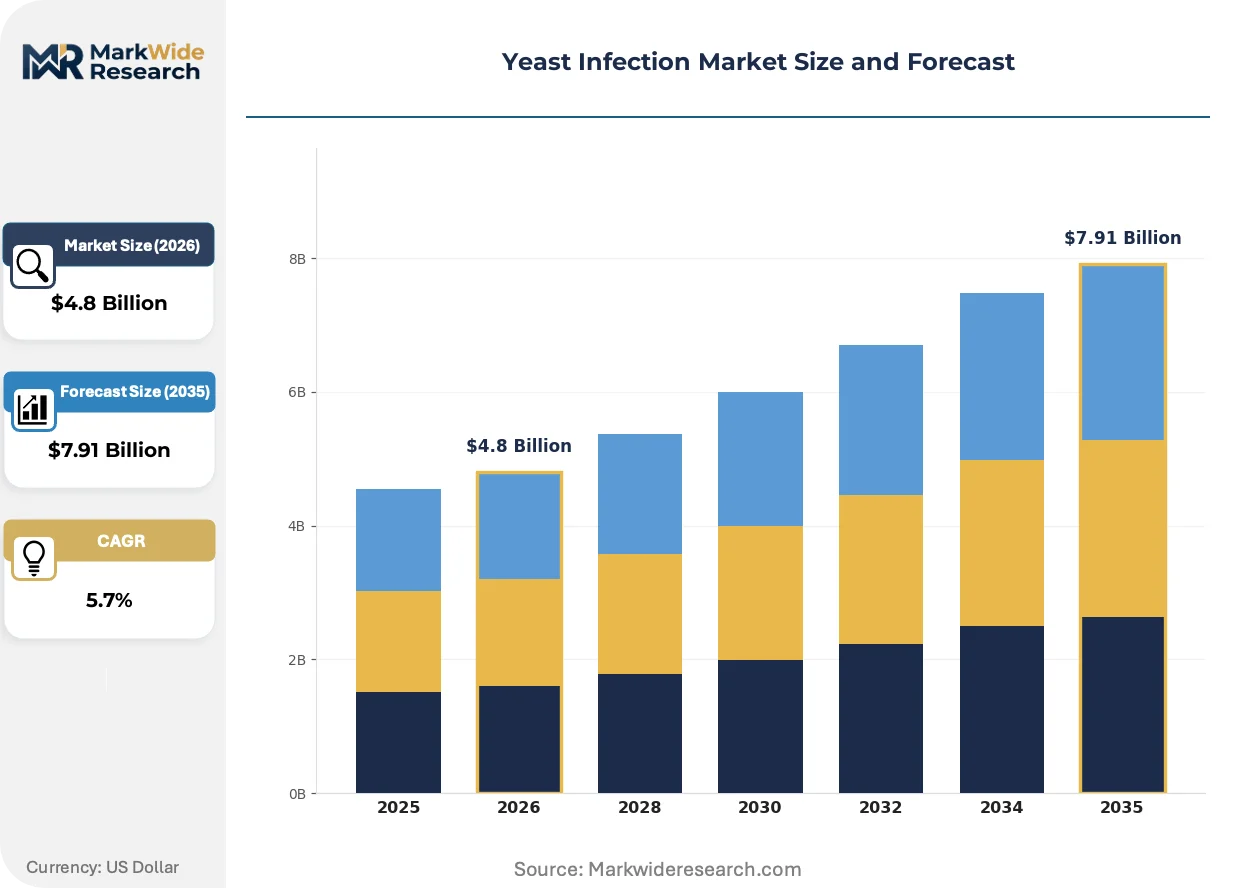
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Antifungals, Topical Antifungals, Probiotics, Combination Therapies End User: Hospitals, Clinics, Pharmacies, Homecare Treatment Type: Over-the-Counter, Prescription, Natural Remedies, Alternative Therapies Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Scynexis Inc., Pfizer Inc., Bayer AG, Merck & Co. Inc., Astellas Pharma Inc., Novartis AG, Johnson & Johnson, Mycovia Pharmaceuticals, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yeast Infection Market Strategic Shifts
Novel mechanisms are displacing legacy azole dependence as resistance surveillance reshapes prescriber behavior and procurement criteria across acute and chronic care settings.
Polyene-sparing small molecules targeting ergosterol biosynthesis through non-azole pathways are hybridizing treatment protocols in immunocompromised patient management. Oncology and transplant centers in the United States are piloting these agents for prophylaxis against breakthrough candidemia. This hybridization is compressing the addressable market for fluconazole generics in high-acuity hospital segments while opening premium pricing tiers for mechanism-differentiated entrants.
REACH antimicrobial resistance reporting requirements and EU MDR device classification updates are tightening documentation standards for diagnostic-assisted antifungal prescribing in European hospital networks. Manufacturers must now integrate resistance surveillance data into product labeling and post-market surveillance protocols. German and French hospital consortia are responding by consolidating procurement around suppliers with integrated diagnostic-therapeutic platforms.
Direct-to-patient adherence programs are displacing traditional pharmacy-centric refill models for chronic recurrent candidiasis management. Telehealth platforms in the United States and Japan are bundling prescription fulfillment with microbiome testing and personalized probiotic recommendations. This channel shift is most visible in employer-sponsored health plans seeking to reduce specialist referral costs for high-recurrence patient cohorts.
Yeast Infection Market Segmentation
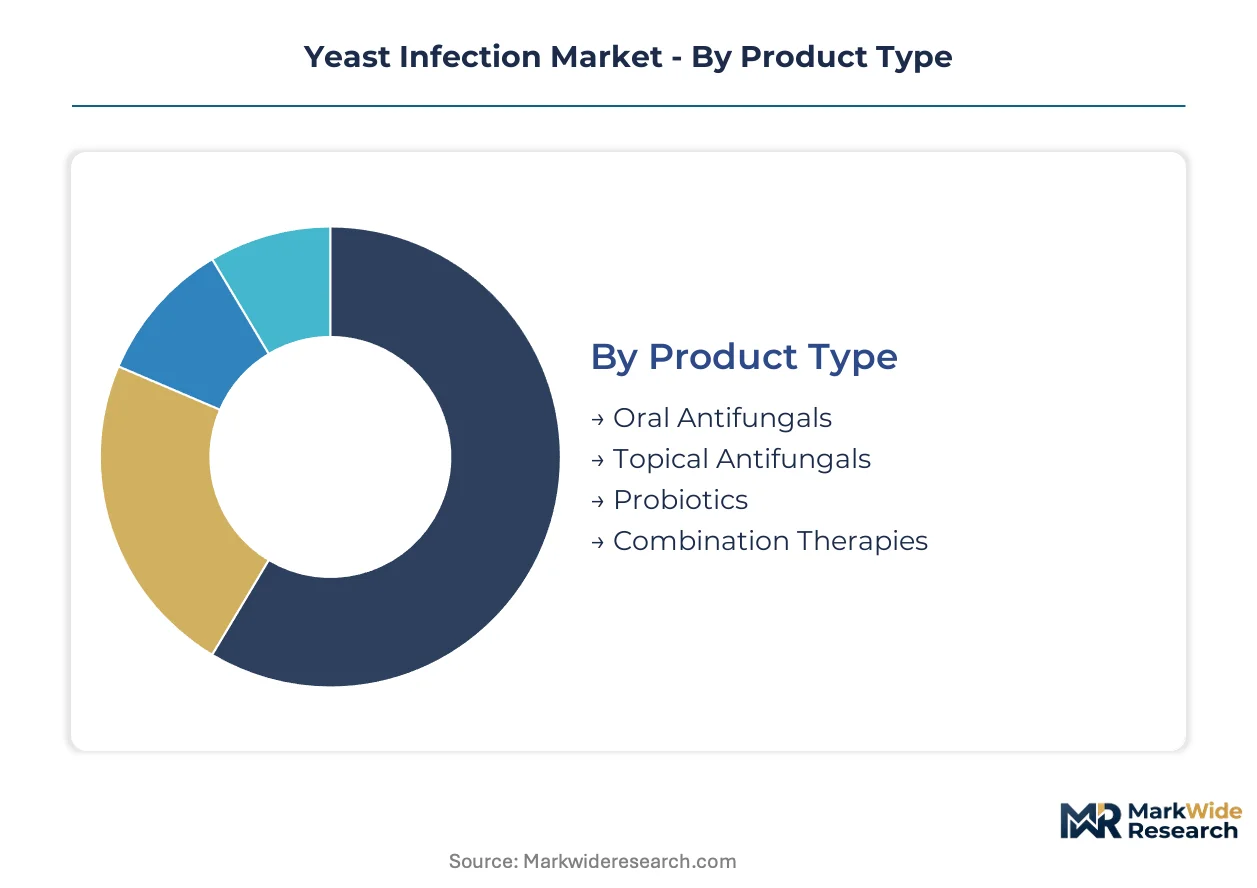
Segmentation in the yeast infection market reveals divergent margin structures across acute versus chronic treatment pathways. Product formulation and channel access determine reimbursement tiers and prescriber behavior in ways that reshape competitive positioning across immunocompetent and immunocompromised patient populations.
Product Type:
Mature oral formulations anchor revenue pools while emerging microbiome-directed segments reshape long-term market architecture.
- Oral Antifungals:Systemic azole and echinocandin formulations deliver bioavailability for invasive candidiasis and recurrent vulvovaginal infections. Hospital formulary placement in the United States and Japan sustains prescription volumes amid tightening antimicrobial stewardship protocols.
- Topical Antifungals:Creams, suppositories, and ointments target localized mucocutaneous infections with lower systemic exposure. German pharmacy networks favor these for initial uncomplicated presentations to preserve oral agent reserves.
- Probiotics:Lactobacillus-dominated formulations restore vaginal microbiome equilibrium as adjunctive recurrence prevention.
- Combination Therapies:Sequential topical-oral regimens address refractory infections in specialty gynecology practices.
Oral antifungals retain volume leadership; probiotics hold the steepest expansion curve.
End User:
Cost tier stratification separates acute intervention sites from chronic management venues across the care continuum.
- Hospitals:Acute care settings manage invasive candidiasis, candidemia, and breakthrough infections in oncology and transplant units. FDA antimicrobial resistance guidance drives formulary consolidation around mechanism-differentiated agents in high-acuity segments.
- Clinics:Outpatient facilities handle recurrent vulvovaginal and oropharyngeal presentations with diagnostic-assisted prescribing. Japanese metabolic disease centers integrate these touchpoints for diabetic patient monitoring.
- Pharmacies:Community and hospital pharmacy counters dispense both prescription and OTC formulations.
- Homecare:Self-administered chronic suppression protocols extend treatment duration for immunocompromised cohorts.
Hospitals command premium pricing tiers; homecare segments are climbing the fastest as remote monitoring platforms mature.
Treatment Type:
Regulatory classification boundaries determine channel access and prescriber autonomy across patient risk stratification.
- Over-the-Counter:Topical azole creams and suppositories enable self-directed treatment of uncomplicated vulvovaginal candidiasis. Bayer AG's pharmacy shelf presence in Germany and the United States dominates this segment through brand recognition and distribution density.
- Prescription:Systemic antifungals require clinician oversight for invasive infections, pregnancy, or refractory presentations. EMA pharmacovigilance requirements extend post-approval surveillance burdens for these agents.
- Natural Remedies:Boric acid and tea tree oil preparations occupy regulatory gray zones in multiple jurisdictions.
- Alternative Therapies:Homeopathic and traditional medicine approaches compete outside formal reimbursement pathways.
Prescription therapies retain volume leadership; OTC segments are gaining share fastest through direct-to-patient platform expansion.
Distribution Channel:
Supply concentration patterns favor integrated platforms over fragmented wholesale networks in post-pandemic procurement.
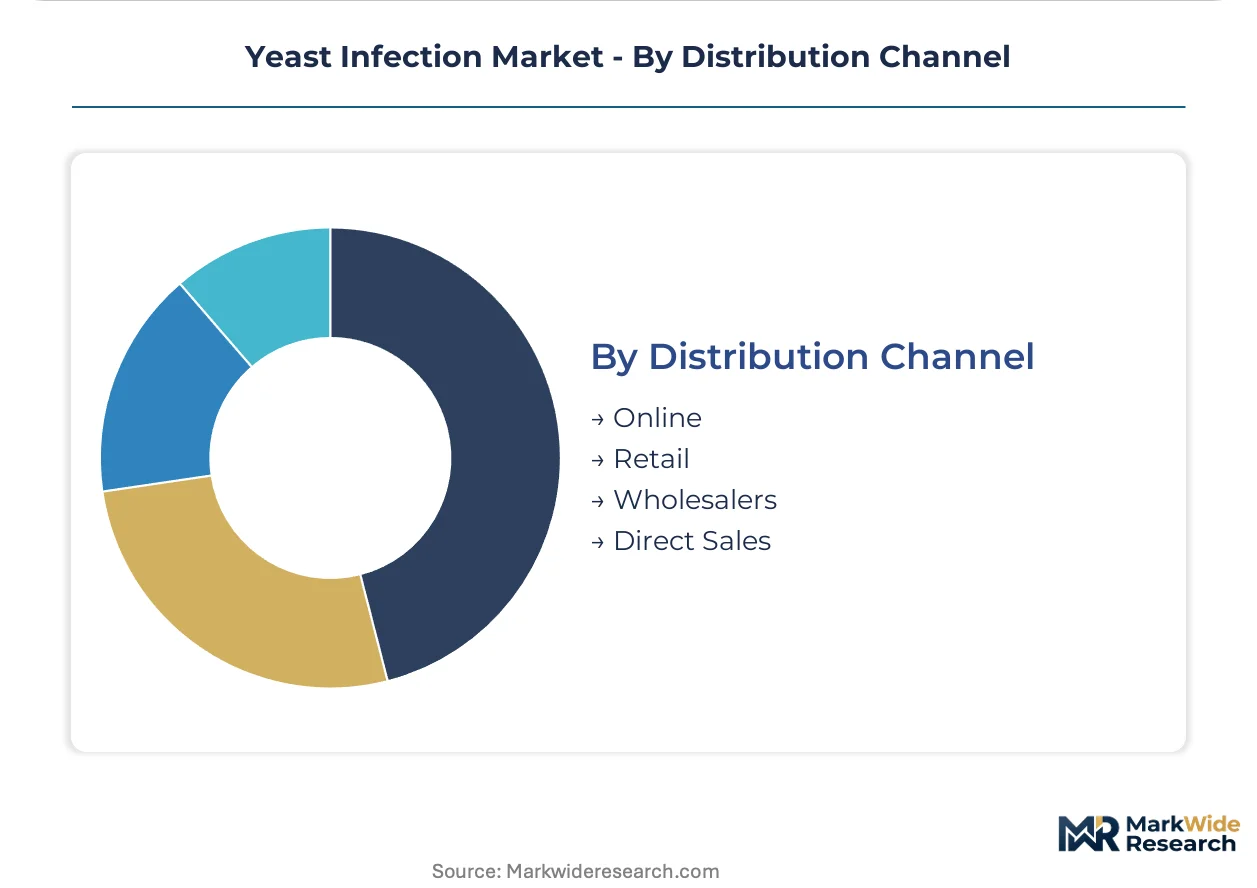
- Online:Telehealth-integrated prescription fulfillment and subscription probiotics reshape patient acquisition economics. United States employer-sponsored plans are consolidating chronic candidiasis management through these channels to reduce specialist referral costs.
- Retail:Pharmacy chains and independent drugstores maintain OTC dominance through physical accessibility and pharmacist counseling.
- Wholesalers:Hospital and clinic procurement relies on regional distributors for formulary-managed systemic antifungals.
- Direct Sales:Manufacturer-to-provider arrangements secure volume commitments for novel mechanism candidates.
Retail channels retain volume leadership; online platforms are expanding most quickly through adherence program bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across markets. United States purchasers absorb premium pricing for mechanism-differentiated agents, while Indian and Chinese procurement channels prioritize cost-minimized fluconazole generics.
United States
Oncology and transplant centers in Boston and Houston drive demand for systemic antifungal prophylaxis. FDA antimicrobial resistance guidance accelerates formulary reviews for non-azole candidates. The Research Triangle Park cluster in North Carolina anchors clinical trial operations for novel echinocandin development programs.
Germany
Metabolic disease centers in Munich and Berlin generate recurrent candidiasis caseloads among diabetic populations. EMA pharmacovigilance requirements extend post-approval surveillance timelines for systemic agents. The Rhine-Ruhr pharmaceutical corridor concentrates manufacturing capacity for polyene API production.
Japan
Aging immunocompromised cohorts in Tokyo and Osaka sustain prescription volumes for azole-sparing therapies. PMDA streamlined review pathways for antifungal resistance countermeasures incentivize local development partnerships. The Kansai biotech cluster hosts active licensing negotiations for microbiome-directed adjuncts.
India
Generic fluconazole manufacturing in Hyderabad and Ahmedabad supplies cost-sensitive outpatient channels across South Asia. CDSCO tightened API quality standards reshape contract manufacturer qualification criteria. The Pune formulation hub is expanding capacity for topical azole exports to African procurement tenders.
China
Hospital procurement consolidation in Shanghai and Beijing favors domestic echinocandin producers over imported legacy brands. NMPA innovation-track approvals for antifungal resistance solutions accelerate local candidate timelines. The Yangtze River Delta cluster integrates diagnostic platform development with therapeutic prescribing protocols.
Yeast Infection Market Competitive Environment
Capability concentration sits with specialized developers of resistance-countering mechanisms; scale advantage sits with diversified pharmaceutical conglomerates with hospital formulary relationships. The market structures around three tiers: multinational innovators with regulatory navigation expertise, mid-cap specialists with novel mechanism platforms, and generic manufacturers with API cost leadership. Consolidation pressures favor partnership arrangements over outright acquisition. Portfolio expansion into microbiome-directed adjacencies represents the dominant competitive vector.
Among mechanism-differentiated developers, Mycovia Pharmaceuticals and Scynexis Inc. exemplify the specialist archetype with polyene-sparing and novel azole-alternative platforms. Pfizer Inc. occupies a position as the scale-driven incumbent leveraging institutional procurement relationships. Bayer AG anchors the consumer health tier with pharmacy-channel distribution density for topical formulations.
| Leading Market Players |
|---|
| Scynexis Inc. |
| Pfizer Inc. |
| Bayer AG |
| Merck & Co. Inc. |
| Astellas Pharma Inc. |
| Novartis AG |
| Johnson & Johnson |
| Mycovia Pharmaceuticals |
| GlaxoSmithKline plc |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Indian and Chinese contract manufacturing organizations for polyene and echinocandin active pharmaceutical ingredients compresses margin buffers at both ends of the value chain. This concentration geometry forces pricing tier spreads that separate hospital formulary premiums from pharmacy generic commoditization while exposing procurement continuity to geopolitical friction.
Pricing Analysis
Aftermarket service revenue from patient adherence programs and digital therapeutic bundling now drives lifetime value capture beyond initial prescription fulfillment. Three-tier pricing structure across premium mechanism-differentiated agents, standard oral azoles, and economy generic fluconazole separates hospital procurement tiers from outpatient pharmacy reimbursement. Pricing pressure stems from patent-expired azole saturation in United States and German pharmacy channels, compressing realizations for novel entrants. Price-sensitive buyers cluster in Indian and Chinese outpatient markets where procurement tenders prioritize cost-minimized generics, while least-sensitive purchasers occupy United States oncology and transplant centers seeking resistance-countering protocols.
Supply Chain Analysis
Tariff exposure between United States and Chinese pharmaceutical inputs dominates supply chain risk calculus for echinocandin and polyene API sourcing. Active pharmaceutical ingredient production concentrates in Hyderabad and Ahmedabad clusters in India, with secondary concentration in Yangtze River Delta chemical corridors in China. Raw material dependencies span ergosterol pathway precursors, fermentation feedstocks, and specialized chromatography resins for purification. Single-source vulnerability intensifies as FDA and EMA quality standards disqualify marginal producers, consolidating viable supply around qualified contract manufacturing organizations. Distribution runs through hospital procurement consortia in developed markets and fragmented wholesale networks in cost-sensitive regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as antimicrobial resistance surveillance compresses development timelines and accelerates formulary turnover for mechanism-differentiated agents. The cyclical driver is patent cliff dynamics for legacy azole franchises creating replacement demand windows.
For Market Incumbents: Entrench hospital formulary relationships through integrated diagnostic-therapeutic platform offerings that bundle resistance surveillance with mechanism-differentiated prescribing protocols. Deepen vertical integration into polyene and echinocandin API production through captive supply arrangements in Indian chemical corridors or qualified contract manufacturing partnerships, insulating against tariff exposure and quality standard escalation. Prioritize certification investment for WHO prequalification status to secure national procurement tenders in low-income access pathways. For New Entrants and Emerging Players: Build out microbiome-directed adjacencies in German outpatient settings where probiotic co-prescription protocols expand addressable patient touchpoints beyond standalone pharmaceutical interventions. Target United States employer-sponsored health plans seeking to reduce specialist referral costs through telehealth-integrated chronic candidiasis management platforms. Pursue direct-to-patient adherence program licensing as the primary go-to-market angle, bypassing saturated pharmacy channel gatekeeping. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap specialists with novel mechanism platforms over diversified conglomerates with legacy azole exposure. Long-term viability over the next decade hinges on resistance-countering R&D productivity and regulatory navigation expertise rather than scale economies in generic manufacturing. Acquisition target archetype: developers of polyene-sparing small molecules with progressed clinical pipelines and existing hospital pilot relationships. Signal to watch: FDA breakthrough therapy designations for non-azole antifungal candidates as inflection indicator for formulary prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Novel polyene-sparing mechanisms require accelerated mycological cure endpoints to satisfy FDA antimicrobial resistance guidance. |
| Regulatory Approval Pathway | EMA pharmacovigilance compliance for systemic antifungals extends post-approval surveillance but secures label expansion rights. |
| Licensing Agreement | Japanese PMDA streamlined review partnerships enable faster market entry for resistance-countering candidates in aging immunocompromised cohorts. |
| Manufacturing Scale-Up | Qualified contract manufacturing organization capacity in Indian API clusters determines supply continuity for echinocandin production. |
| Pipeline Diversification | Microbiome restoration adjuncts in German outpatient protocols represent fastest-expanding segment with recurrence prevention economics. |
Study Parameters
Desk research of FDA antimicrobial resistance guidance documents, EMA pharmacovigilance requirements, WHO essential medicines listings, and hospital formulary databases preceded structured interviews with infectious disease clinicians, hospital pharmacy directors, regulatory affairs specialists, and payer access managers. Primary fieldwork combined with secondary validation from ClinicalTrials.gov entries, SEC pharmaceutical filings, and national procurement tender records enabled bottom-up prescription volume modeling and top-down market sizing triangulation.
Assumptions held fixed across the modeling period include current FDA and EMA regulatory frameworks, existing reimbursement tier structures in United States and German markets, and antimicrobial resistance surveillance protocols. Variables stress-tested include generic fluconazole pricing erosion rates, API supply disruption scenarios, and probiotic adjunct adoption curves in outpatient settings. Segmentation dimensions spanned product formulation, end-user facility type, treatment regulatory classification, and distribution channel. CAGRs were derived from prescription volume trajectories, pricing realization trends, and patient adherence program penetration curves across immunocompetent and immunocompromised population strata.
Stress conditions across API supply concentration, regulatory approval timeline variability, and generic substitution intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding resistance surveillance evolution and formulary consolidation dynamics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Disinfection Cupboard Market
Infection Control
Germicidal UV Lamp Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
Botulism Market
Infection Control
Ultraviolet Germicidal Irradiation Market
Infection Control
Dental Infection Treatment Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Infection Control Surveillance Solutions Market
Infection Control
Sterility Indicators Market
Infection Control
Catheter-Related Bloodstream Infections (Crbsis) Market
Infection Control
Asia-Pacific Hand Sanitizer Market
Infection Control
Global Pseudomonas Aeruginosa Infection Treatment Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Hospital Acquired Infections Therapeutic Market
Infection Control
South Africa Antibacterial Soap Market