
 Infection Control Supplies Market | 2026-2036
Infection Control Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Infection Control Supplies Market Analysis
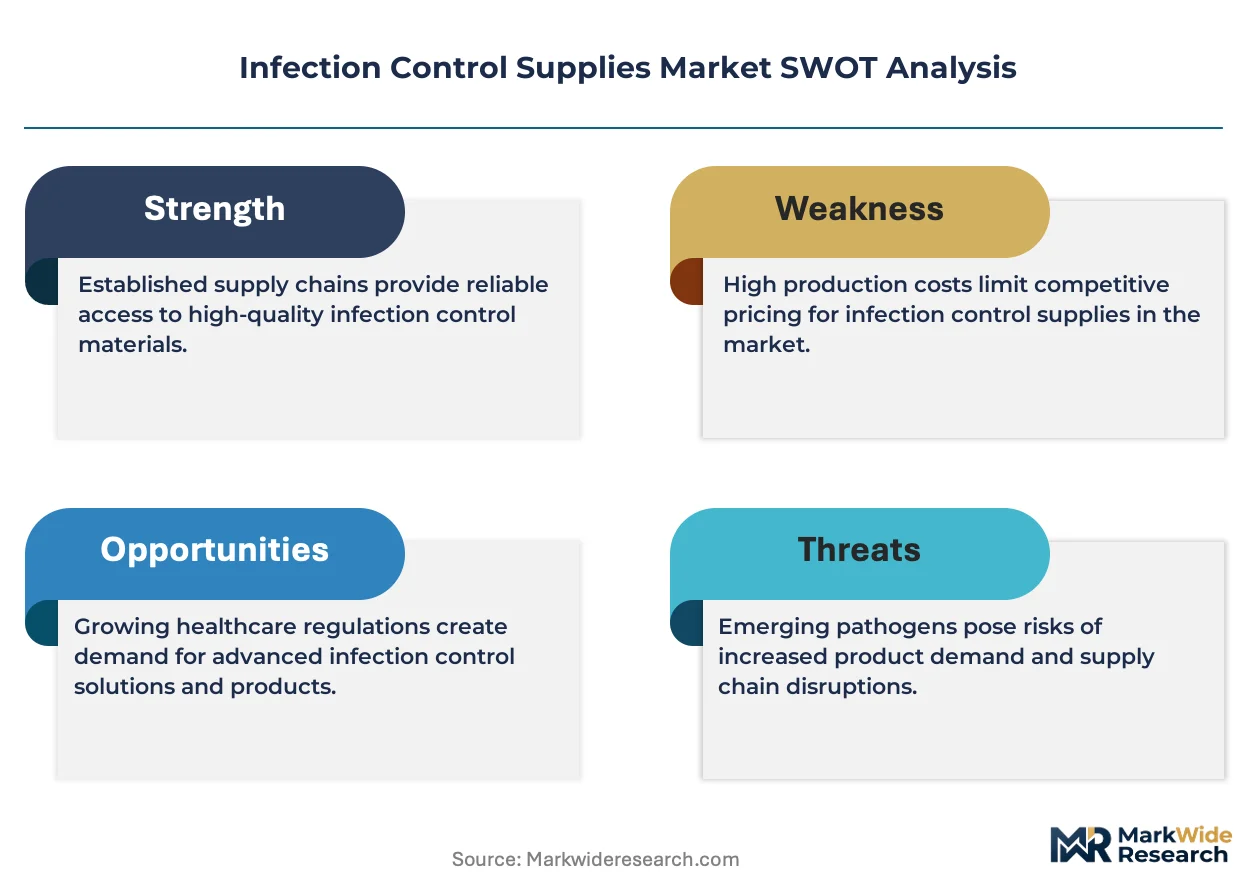
Equipment leasing and managed service contracts are reshaping competitive access in sterilization and disinfection infrastructure. 3M leverages its materials science portfolio to sustain premium positioning across multiple product lines. STERIS anchors its market presence through integrated sterilization systems and service agreements with acute care networks. Cardinal Health competes on distribution density, controlling hospital supply chain touchpoints that competitors struggle to replicate.
Infection control supplies encompass chemical formulations, barrier devices, and mechanical systems engineered to eliminate or suppress pathogenic microorganisms on surfaces, skin, instruments, and airborne particles. Disinfectants typically achieve EPA-registered kill claims against specified organism classes within regulated contact times, while personal protective equipment must meet ASTM or EN standards for fluid resistance and filtration efficiency. Personal protective equipment commands the largest revenue pool due to high turnover rates and mandatory replacement protocols, though sterilization equipment generates superior margins through consumable attachment sales and service contracts. Healthcare facilities represent the dominant application channel, with laboratories representing the fastest-growing segment as diagnostic testing volumes expand and biosafety level requirements tighten across research and clinical settings.
FDA sterilization validation requirements and EPA disinfectant registration protocols create compliance barriers that favor established manufacturers with dedicated regulatory affairs infrastructure. OSHA bloodborne pathogen standards and Joint Commission accreditation criteria directly shape hospital purchasing specifications for personal protective equipment and surface disinfectants. Stakeholders must monitor evolving EPA sustainability mandates for quaternary ammonium compounds and emerging state-level restrictions on ethylene oxide sterilization methods.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around full-service sterilization contracts, compressing the competitive window for standalone disinfectant and PPE suppliers. This structural pull toward integrated infection prevention programs is reshaping how manufacturers structure pricing, service, and regulatory support.
Growth Catalysts
- EPA sustainability mandates:Accelerating phase-outs of legacy quaternary ammonium compounds in the US are forcing facility managers to validate next-generation formulations, creating replacement demand cycles for surface disinfectants.
- Outpatient surgical center expansion:Germany's ambulatory surgery volume growth is concentrating capital equipment purchases for low-temperature sterilization systems in settings previously served by hospital central sterile supply departments.
- Biosafety level upgrades:Diagnostic laboratories across multiple geographies are retrofitting containment infrastructure to BSL-3 specifications, expanding demand for HEPA filtration systems and chemical decontamination protocols.
Market Restraints
- Ethylene oxide supply concentration:US EPA and state-level restrictions on EtO sterilization facilities in Illinois and Georgia are creating regional sterilization capacity bottlenecks for medical device manufacturers.
- Raw material input volatility:Polypropylene and melt-blown nonwoven supply for N95 respirators remains exposed to petrochemical price swings and Asian supplier concentration.
- Reusable device validation costs:FDA's updated sterilization guidance requires manufacturers to generate new lethality data for low-temperature hydrogen peroxide processes, extending time-to-market for reprocessed instruments.
Strategic Opportunities
- India's hospital infrastructure buildout:Government health insurance expansion and medical tourism investments are creating greenfield demand for central sterile supply departments in tier-2 and tier-3 cities.
- UV-C LED convergence with IoT monitoring:Surface disinfection systems integrating semiconductor-based UV sources with real-time dosage verification are penetrating long-term care facilities seeking automated compliance documentation.
- EU MDR clinical data requirements:Stricter post-market surveillance obligations for reusable surgical instruments are incentivizing healthcare networks to outsource sterilization validation to third-party service providers.
Industry Challenges
- Sterilization process engineering talent scarcity:Validation of novel low-temperature modalities requires specialized microbiology and thermal engineering expertise that exceeds current workforce supply in contract sterilization organizations.
- Legacy steam sterilizer integration friction:Healthcare facilities with 20-plus-year-old autoclave infrastructure face capital constraints and physical space limitations when retrofitting for hydrogen peroxide vapor or ozone-based alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infection Control Supplies Market |
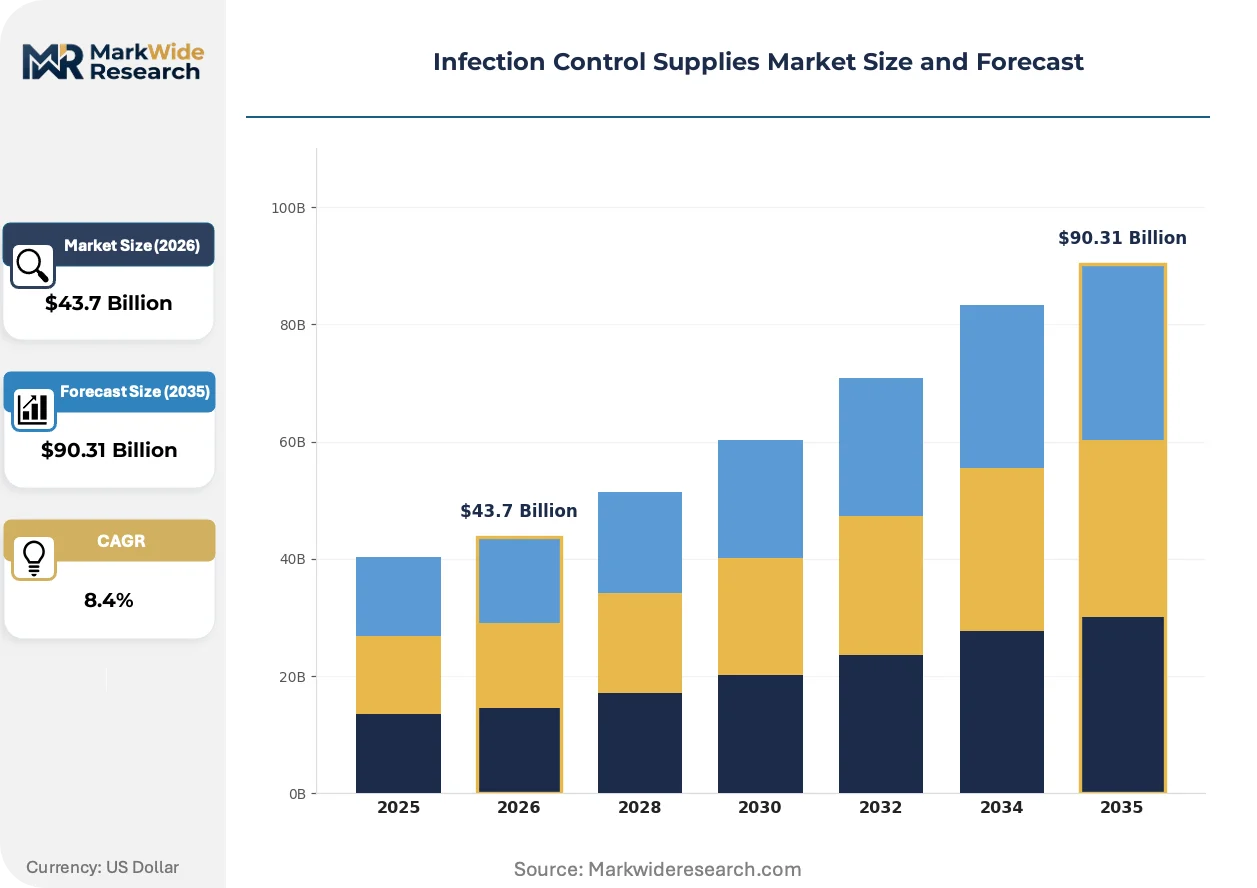
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $90.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disinfectants, Antiseptics, Personal Protective Equipment, Sterilization Equipment Application: Healthcare Facilities, Laboratories, Pharmaceuticals, Food Processing End User: Hospitals, Clinics, Research Institutions, Long-term Care Facilities Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | 3M, STERIS, Ecolab, Getinge, Cardinal Health, Fortive, Sotera Health, Reckitt, Kimberly-Clark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infection Control Supplies Market Emerging Trajectories
Active innovation in infection control is concentrating on materials science breakthroughs that reduce environmental persistence while maintaining kill efficacy, alongside digital integration that automates compliance documentation. These developments are compressing the traditional separation between chemical formulation suppliers and equipment manufacturers.
Hydrogen peroxide vapor systems are migrating from hospital central sterile supply departments into pharmaceutical manufacturing cleanrooms and biotechnology production suites. Contract manufacturers serving cell and gene therapy production are adopting these systems to avoid ethylene oxide residuals on temperature-sensitive biologics. This technology migration from healthcare into life sciences production is creating new equipment specification requirements and service contract structures.
REACH restrictions on per- and polyfluoroalkyl substances are forcing European disinfectant formulators to eliminate PFAS-based surfactants from surface cleaning products by 2026. Industrial consequence includes accelerated R&D spending on bio-based alternatives and reformulation of legacy hospital-grade disinfectants. German and French healthcare procurement consortia are most affected, with several hospital networks now requiring PFAS-free certifications in tender specifications.
Consolidated procurement through regional hospital group purchasing organizations is displacing individual facility purchasing autonomy across North American acute care networks. Supply chain managers at these GPOs are unbundling PPE, disinfectant, and sterilization equipment into separate category contracts to optimize supplier specialization. This pattern is most visible in the southeastern United States, where Catholic health system alliances and for-profit hospital chains are centralizing infection control spend decisions at corporate headquarters.
Infection Control Supplies Market Segmentation
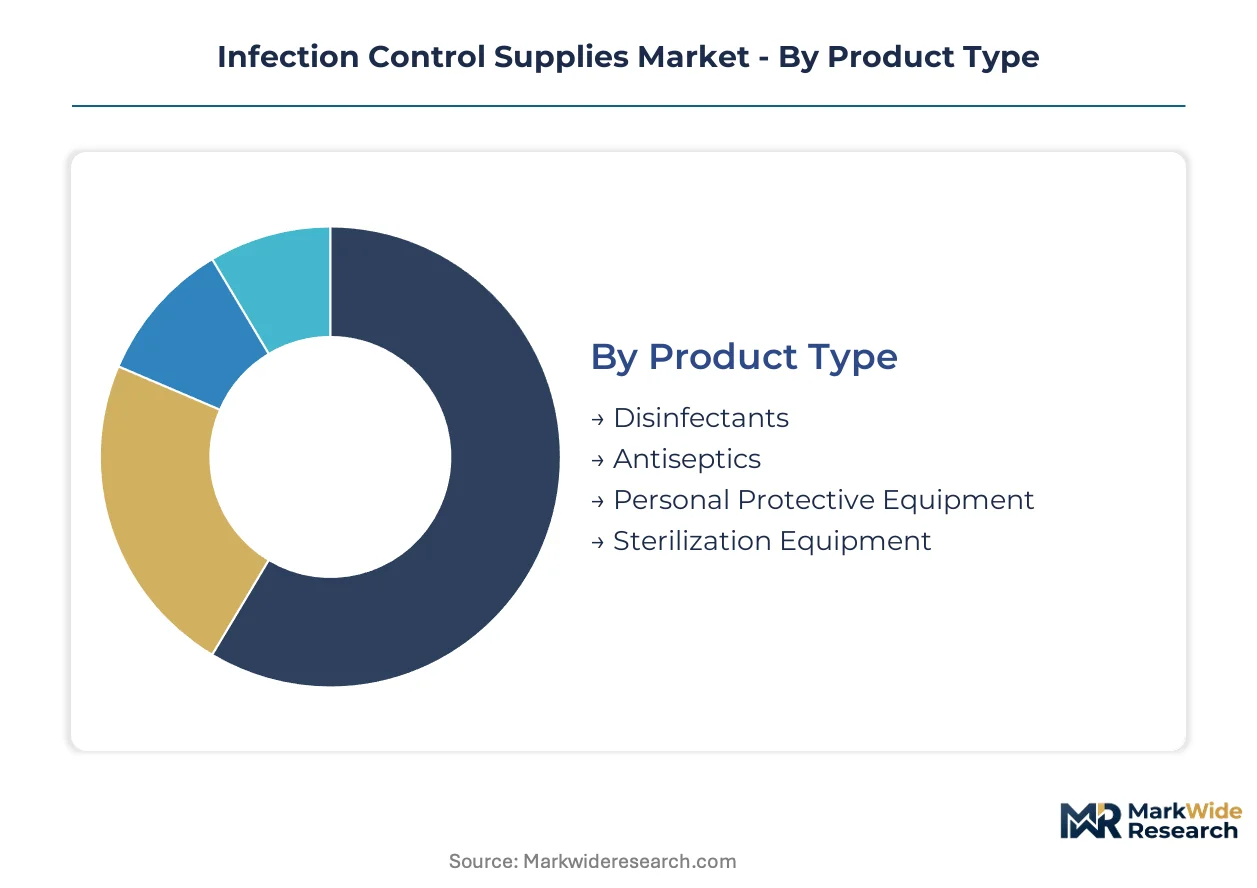
Segmentation in infection control supplies reveals how procurement complexity varies dramatically across product categories. Hospital supply chains must reconcile disposable consumables with capital-intensive sterilization systems under divergent regulatory and service requirements.
Product Type:
After-sales service intensity varies enormously across this category, with sterilization equipment demanding multi-year maintenance contracts while disinfectants require minimal technical support.
- Personal Protective Equipment:Single-use barriers including gloves, gowns, masks, and respirators engineered to ASTM fluid resistance and filtration standards. Demand concentrates in US hospital networks rebuilding strategic stockpiles depleted during the pandemic, with N95 respirator procurement now governed by CDC stockpiling mandates and OSHA fit-testing protocols.
- Sterilization Equipment:Mechanical systems utilizing steam, ethylene oxide, hydrogen peroxide vapor, or ozone to achieve SAL 10^-6 lethality on reusable instruments. German outpatient surgical centers are driving capital purchases of low-temperature alternatives as central sterile supply departments decentralize into ambulatory settings.
- Disinfectants:EPA-registered chemical formulations achieving specified log-reductions against pathogen classes within regulated contact times.
- Antiseptics:Skin-preparation solutions meeting FDA monograph requirements for preoperative and injection-site cleansing.
Personal Protective Equipment holds the largest share; momentum sits with Sterilization Equipment.
Application:
Cost tier stratification separates commodity chemical purchases from validated containment infrastructure investments across these settings.
- Healthcare Facilities:Acute care hospitals, outpatient clinics, and long-term care institutions requiring Joint Commission-compliant infection prevention programs. Demand is concentrating in US health systems consolidating vendor relationships around full-service sterilization contracts that bundle equipment, consumables, and regulatory documentation.
- Laboratories:Diagnostic testing and research facilities retrofitting to BSL-3 specifications. Expansion is climbing the fastest in European molecular diagnostics hubs as post-pandemic surveillance testing volumes stabilize at elevated baselines and biosafety containment requirements tighten.
- Pharmaceuticals:Aseptic manufacturing suites and contract production facilities requiring validated sterilization processes for parenteral products.
- Food Processing:Commercial kitchens and production lines utilizing USDA-compliant sanitizers and hygienic design principles.
Healthcare Facilities dominates current procurement volumes; Laboratories are gaining share fastest.
End User:
Customer type determines whether purchasing authority sits with centralized supply chain headquarters or individual facility managers.
- Hospitals:Acute care networks with 100-plus bed counts operating central sterile supply departments and emergency stockpiles. Demand concentrates in India's tier-2 and tier-3 cities where government health insurance expansion is funding greenfield infrastructure buildouts.
- Long-term Care Facilities:Skilled nursing and assisted living communities adopting automated UV-C surface disinfection with IoT dosage verification. US operators in the Southeast are prioritizing compliance documentation systems that reduce liability exposure and survey deficiency citations.
- Clinics:Physician offices and ambulatory surgery centers with limited storage capacity and just-in-time inventory models.
- Research Institutions:University and corporate laboratories with specialized containment requirements for recombinant DNA work.
Hospitals command the largest procurement budgets; Long-term Care Facilities show the steepest expansion trajectory.
Distribution Channel:
Volume concentration favors direct relationships for high-turnover consumables while specialized equipment migrates through authorized distributors with technical service capabilities.
- Distributors:Regional and national medical-surgical distributors controlling hospital supply chain touchpoints through consolidated delivery networks. Cardinal Health and similar operators leverage density advantages that standalone suppliers cannot replicate.
- Direct Sales:Manufacturer field forces engaging hospital value analysis committees for capital equipment and multi-year service agreements. STERIS anchors market presence through integrated sterilization systems sold directly to acute care networks.
- Online:E-commerce platforms serving smaller facilities and emergency replenishment orders.
- Retail:Pharmacy and big-box channels for consumer-grade PPE and surface disinfectants.
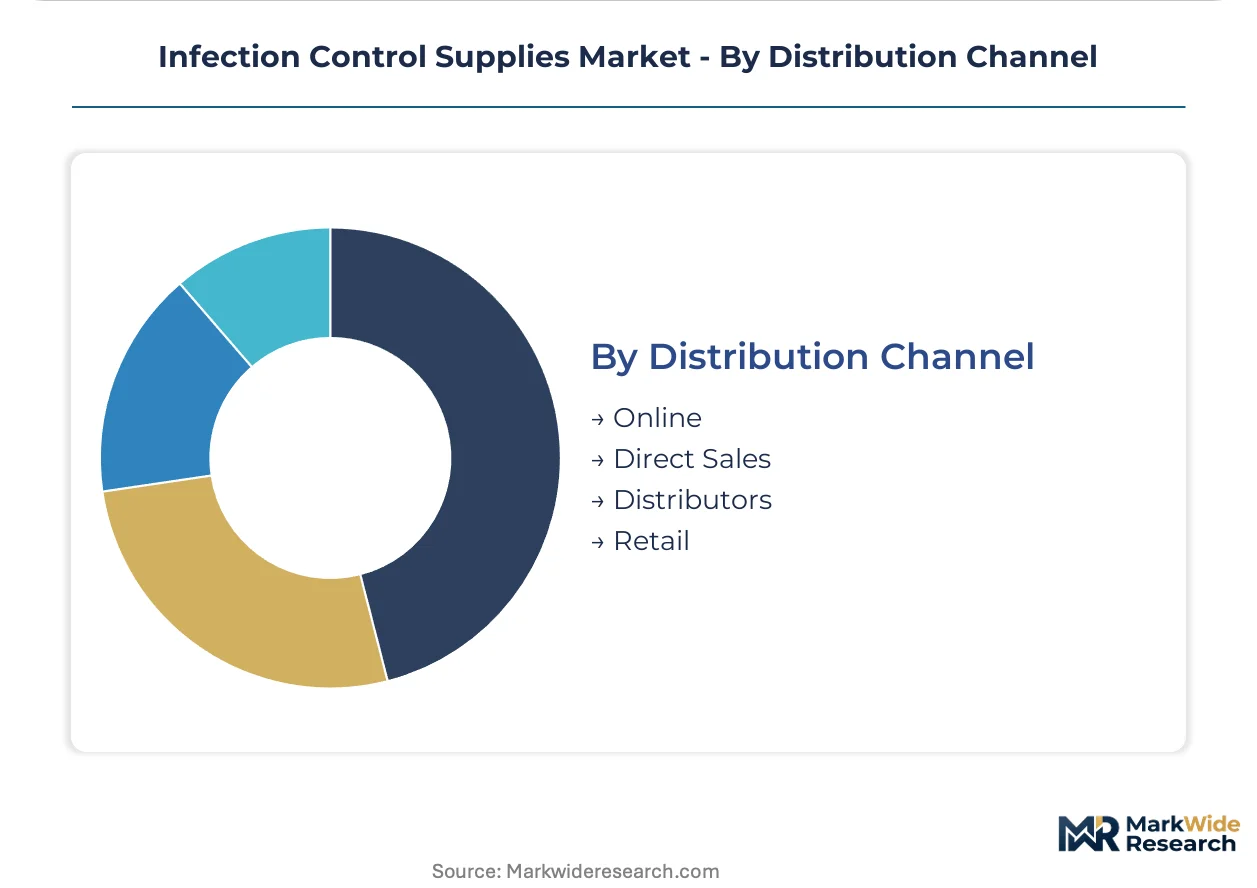
Distributors maintain the largest channel share; Direct Sales is climbing fastest on sterilization equipment attachment rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare procurement policies and hospital infrastructure investments are directing infection control supply demand toward specific national markets with divergent regulatory environments and facility buildout trajectories.
United States
FDA sterilization validation requirements and CDC stockpiling mandates for N95 respirators are driving hospital procurement department consolidation around full-service vendor contracts. OSHA bloodborne pathogen standards and Joint Commission accreditation criteria shape purchasing specifications for personal protective equipment. The southeastern United States concentrates GPO-led procurement centralization among Catholic health system alliances and for-profit hospital chains.
Germany
Outpatient surgical center expansion and ambulatory surgery volume growth concentrate capital equipment purchases for low-temperature sterilization systems. REACH restrictions on per- and polyfluoroalkyl substances force disinfectant formulators to eliminate PFAS-based surfactants from surface cleaning products by 2026. Hospital procurement consortia in Germany and France now require PFAS-free certifications in tender specifications.
India
Government health insurance expansion and medical tourism investments create greenfield demand for central sterile supply departments. The country's national pharmaceutical regulator and hospital accreditation bodies tighten infection prevention program requirements for new facility licensing. Tier-2 and tier-3 cities concentrate infrastructure buildout as procurement authority decentralizes from metropolitan hospital networks.
China
Dual carbon goals and national standards for healthcare facility energy efficiency accelerate replacement cycles for steam sterilizer infrastructure. The national medical products administration enforces stricter post-market surveillance for reusable surgical instruments. Yangtze River Delta pharmaceutical manufacturing clusters adopt hydrogen peroxide vapor systems to avoid ethylene oxide residuals on temperature-sensitive biologics.
Japan
Biosafety level upgrades in diagnostic laboratories and research institutions expand demand for HEPA filtration systems and chemical decontamination protocols. The national regulator for medical devices enforces JIS standards for sterilization equipment validation in pharmaceutical manufacturing cleanrooms. Kanto and Kansai regions concentrate molecular diagnostics hub development as post-pandemic surveillance testing volumes stabilize.
Infection Control Supplies Market Vendor Landscape
On the supply side, the industry is consolidating around integrated service providers capable of bundling equipment, consumables, and regulatory documentation. Three strategic archetypes dominate: diversified materials science conglomerates with premium positioning across multiple product lines, specialized sterilization system manufacturers anchoring market presence through acute care network agreements, and distribution-heavy operators controlling hospital supply chain touchpoints through density advantages. Competitive moves concentrate on multi-year service contract capture and geographic expansion through managed service offerings.
Within the integrated systems tier, STERIS anchors market presence through sterilization equipment and service agreements with hospital networks. 3M exemplifies the materials science conglomerate archetype, sustaining premium positioning across protective barriers and chemical formulations. Cardinal Health occupies the distribution-dominant position, leveraging hospital supply chain density that standalone suppliers struggle to replicate.
| Leading Market Players |
|---|
| 3M |
| STERIS |
| Ecolab |
| Getinge |
| Cardinal Health |
| Fortive |
| Sotera Health |
| Reckitt |
| Kimberly-Clark Corporation |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta manufacturing clusters anchor global capacity for hydrogen peroxide vapor sterilization systems, concentrating equipment assembly and consumable production in a geography that grants incumbent suppliers significant downstream pricing leverage over hospital networks and pharmaceutical cleanroom operators.
Pricing Analysis
Certification level (FDA 510(k)-cleared versus CE-marked versus unrated) creates the primary spread across sterilization equipment tiers, with validated systems commanding substantial premiums over non-validated alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies personal protective equipment, where NIOSH-certified N95 respirators separate from surgical masks and unregulated face coverings. Pricing pressure stems from GPO-led procurement centralization in US hospital networks, compressing margins for standalone disinfectant suppliers. Long-term care facilities exhibit highest price sensitivity due to Medicaid reimbursement constraints, while pharmaceutical manufacturing cleanrooms show lowest sensitivity given validation requirements.
Supply Chain Analysis
Contract manufacturers in China, Malaysia, and Vietnam hold dominant capacity for melt-blown nonwoven production feeding N95 respirator assembly. Polypropylene resin, spunbond fabrics, and ethylene oxide gas feedstock constitute critical input dependencies with concentrated Asian sourcing. Single-source vulnerability runs through ethylene oxide sterilization facilities facing EPA and state-level restrictions in Illinois and Georgia. Distribution runs through regional medical-surgical distributors controlling hospital supply chain touchpoints, with direct sales channels capturing sterilization equipment and multi-year service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as hospital capital expenditure budgets normalize following pandemic-era depletion and outpatient surgical center buildouts accelerate replacement demand for sterilization infrastructure.
For Market Incumbents: Pre-empt emerging low-temperature sterilization modality entrants by accelerating hydrogen peroxide vapor validation investments and locking acute care networks into exclusive multi-year service contracts. Consolidate backward integration into polypropylene nonwoven supply to defend margin position against petrochemical price volatility. Expand technical service headcount in Germany and India to capture ambulatory surgery center decentralization. For New Entrants and Emerging Players: Pursue India's tier-2 and tier-3 city hospital infrastructure buildout as the most penetrable geography, where greenfield central sterile supply departments lack incumbent vendor relationships. Target long-term care facilities in the US Southeast seeking automated UV-C surface disinfection with IoT compliance documentation. Lead with managed service contracts bundling equipment, consumables, and regulatory documentation to bypass GPO procurement barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sterilization equipment manufacturers with consumable attachment sales and multi-year maintenance agreements, offering superior cash flow predictability than commoditized PPE suppliers. Acquisition focus should center on contract sterilization service providers with FDA-validated low-temperature process portfolios, positioned to capture outsourcing demand from EU MDR clinical data requirements. Monitor EPA enforcement actions on ethylene oxide facilities as inflection signal for hydrogen peroxide vapor adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | STERIS and 3M leverage integrated service agreements to lock acute care networks into exclusive multi-year sterilization contracts. |
| CE Marking Pathway | European disinfectant formulators accelerate PFAS-free reformulation investments ahead of REACH substance restrictions. |
| Backward Integration | Cardinal Health deepens upstream control over polypropylene nonwoven supply to defend distribution margin against petrochemical volatility. |
| Software Companion Development | UV-C LED system manufacturers integrate IoT dosage verification to penetrate long-term care facilities seeking automated compliance documentation. |
| Geographic Expansion | Equipment vendors establish technical service presence in India's tier-2 cities to capture greenfield central sterile supply department demand. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with hospital procurement directors, biomedical engineers, GPO contracts managers, and sterilization validation specialists; and secondary validation against FDA 510(k) filings, EPA disinfectant registration databases, hospital procurement contract repositories, and EU MDR technical documentation. Bottom-up triangulation across product-level shipment data and top-down reconciliation against national healthcare expenditure statistics ensured cross-verified volume and value estimates.
Forecast inputs incorporated product type segmentation (personal protective equipment, sterilization equipment, disinfectants, antiseptics), application channel stratification (healthcare facilities, laboratories, pharmaceuticals, food processing), and end-user tiering (hospitals, long-term care, clinics, research institutions). CAGRs were derived from regression analysis of historical procurement patterns projected across the modeling period, with explicit incorporation of EPA sustainability mandate timelines and EU MDR enforcement phase-ins as regulatory shock variables.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, petrochemical input costs, or healthcare reimbursement rates would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution rates. Quarterly review of FDA sterilization guidance updates, EPA enforcement actions on ethylene oxide facilities, and GPO contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Surgical Site Infections Market
Infection Control
Hand Hygiene Products Market
Infection Control
Germicidal UV Lamp Market
Infection Control
Global Hospital Infection Therapeutics Market
Infection Control
Patient Hygiene Aids Market
Infection Control
Middle East and Africa Hand Sanitizer Market
Infection Control
Sterilization Monitoring Market
Infection Control
Intra-Amniotic Infection Treatment Market
Infection Control
Catheter-Related Bloodstream Infections (Crbsis) Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Global Prophylactic Human Vaccine Market
Infection Control
Healthcare Protective Masks Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Intra-Abdominal Infection Treatment Market
Infection Control
Multi-Surface Disinfection Booster Systems with Low QAC Load Market