
 Patient Cleansing Products Market | 2026-2036
Patient Cleansing Products Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Cleansing Products Market Analytics
Hospital-grade antiseptic specification is rotating toward chlorhexidine-alcohol combinations and povidone-iodine alternatives with enhanced persistent activity. Kimberly-Clark leverages its institutional distribution network to sustain contracted supply relationships with integrated delivery networks. Procter & Gamble anchors its position through R&D intensity in rinse-free formulations for immobile patients. 3M differentiates via technology leadership in skin adhesion-compatible prep solutions that reduce surgical drape lift.
Patient cleansing products encompass antimicrobial and non-antimicrobial formulations applied to intact or preoperative skin to reduce bioburden, typically containing chlorhexidine gluconate, benzalkonium chloride, or surfactant-based cleansing agents in pH-balanced vehicles designed to maintain stratum corneum integrity. Foam formats dominate procedural volume due to controlled dosing and reduced splash contamination risk, while wipes capture expanding home care and long-term care facility demand where bedside convenience governs compliance. Solutions retain margin concentration in preoperative surgical prep kits bundled with sterile drapes and instruments.
FDA antiseptic drug monograph revisions and EPA surface disinfectant claims intersect to reshape formulation standards and label indications for skin-applied products. The Joint Commission's National Patient Safety Goals on surgical site infection prevention directly influence hospital procurement specifications and usage audit frequency. Stakeholders must monitor evolving EPA pesticide registration requirements for antimicrobial actives and assess reformulation timelines against contract renewal cycles.
Market Dynamics
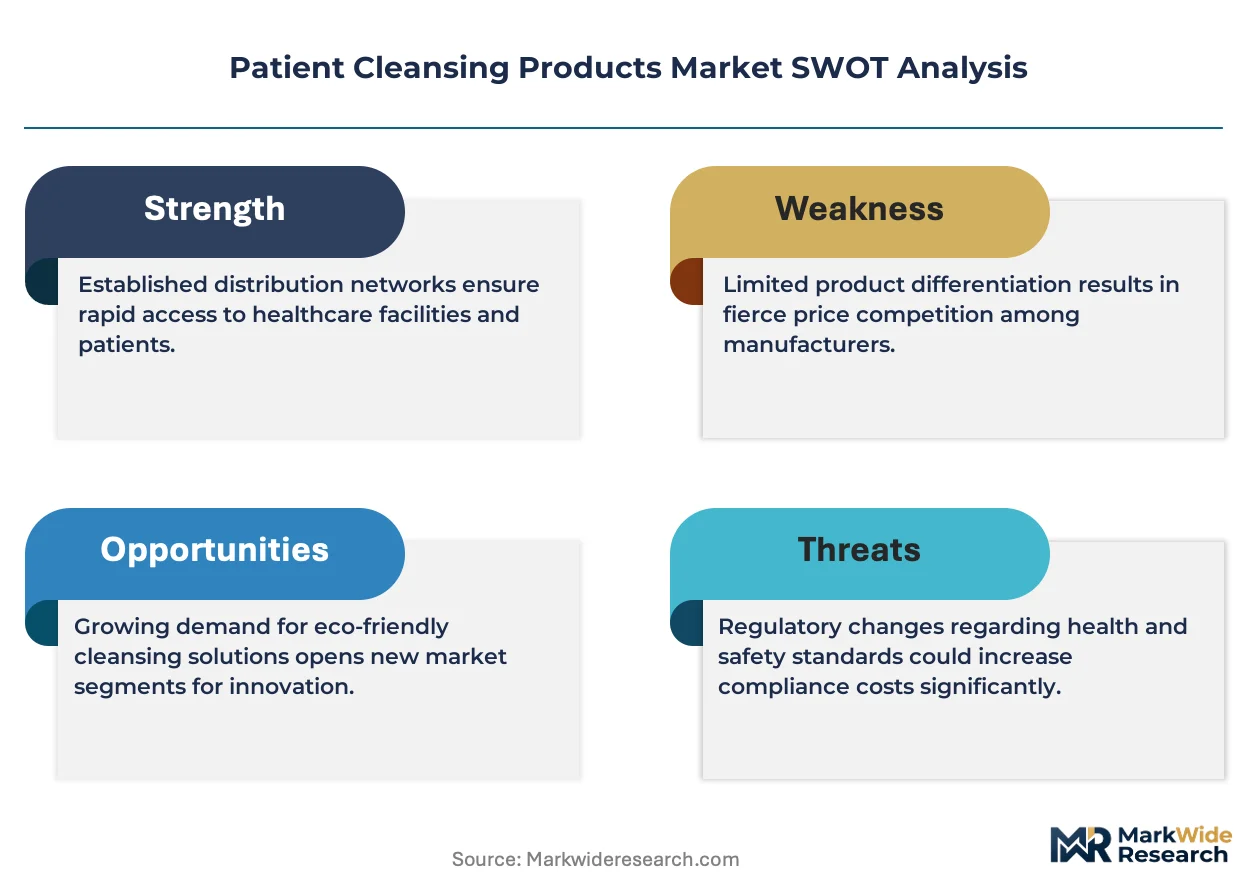
FDA antiseptic drug monograph revisions are forcing wholesale reformulation across chlorhexidine and povidone-iodine portfolios, compressing development timelines while elevating compliance costs for manufacturers serving institutional procurement channels.
Growth Catalysts
- Preoperative Skin Preparation Mandates:The Joint Commission's National Patient Safety Goals on surgical site infection prevention now require documented cleansing protocols in US hospitals, driving standardized volume procurement through integrated delivery networks.
- Chlorhexidine-Alcohol Combination Formulations:Enhanced persistent antimicrobial activity against skin flora is displacing single-agent solutions in high-risk surgical procedures, particularly cardiac and orthopedic interventions.
- Home Care Expansion:Post-acute care discharges in Germany and Japan are generating sustained demand for rinse-free cleansing wipes among immobile patient populations requiring bedside hygiene maintenance.
Market Restraints
- Active Ingredient Supply Concentration:Chlorhexidine gluconate API production concentrates among Chinese and Indian chemical manufacturers, exposing formulators to export licensing volatility and freight cost spikes.
- EPA-FDA Regulatory Intersection:Antimicrobial skin prep products face overlapping pesticide registration and drug monograph requirements, creating label indication restrictions that limit cross-promotional claims.
- Alcohol-Based Substitute Threat:Plain isopropyl alcohol solutions retain preference in resource-constrained settings due to lower unit economics, compressing premium formulation penetration in price-sensitive procurement.
Strategic Opportunities
- Pediatric and Neonatal Formulations:pH-balanced, fragrance-free cleansing vehicles with reduced chlorhexidine concentration are capturing unmet need in neonatal intensive care units where skin barrier immaturity governs product selection.
- Long-Term Care Facility Channel Development:Direct distribution partnerships with nursing home chains bypass hospital-centric group purchasing organizations, enabling margin retention through private-label arrangements.
- ISO 10993 Biocompatibility Certification:Surgical prep solutions with documented skin adhesion compatibility are commanding specification preference in advanced wound closure procedures where drape lift incidents drive litigation exposure.
Industry Challenges
- Formulation Chemistry Talent Scarcity:The intersection of antimicrobial efficacy, stratum corneum integrity, and regulatory compliance requires specialized cosmetic chemists and pharmaceutical formulators in short supply across the industry.
- Legacy Manufacturing Equipment Retrofit Costs:Aseptic foam filling lines and wipe converting equipment require seven-figure capital deployment to meet current good manufacturing practice standards for drug-device combination products.
- Clinical Evidence Generation Timelines:Randomized controlled trials demonstrating superior surgical site infection reduction versus standard of care extend product development cycles by 24-36 months beyond formulation completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Cleansing Products Market |
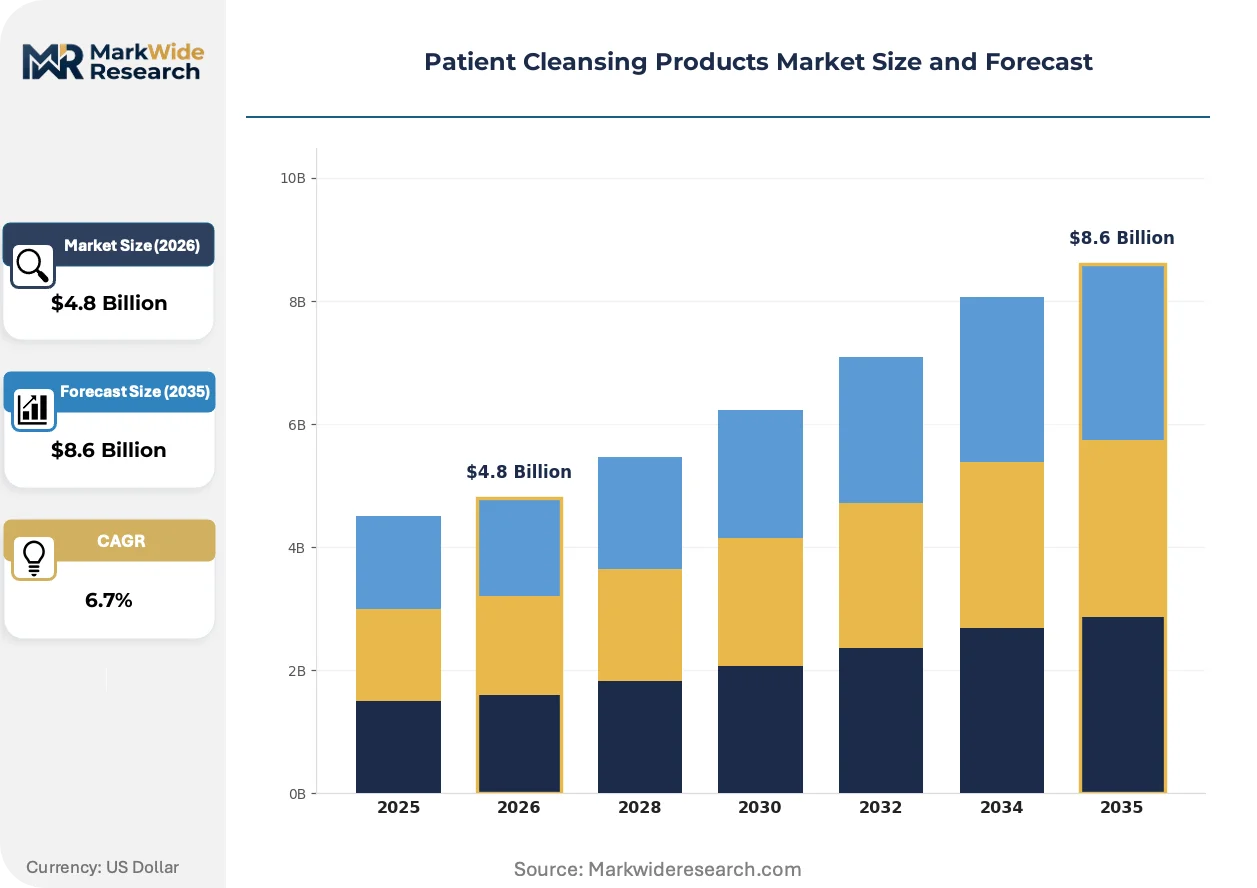
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Wipes, Solutions, Gels Application: Surgical Prep, Daily Hygiene, Skin Care, Infection Control End User: Hospitals, Home Care, Long-term Care Facilities, Clinics Packaging Type: Tubes, Bottles, Pouches, Dispensers |
| Companies Covered | 3M, Kimberly-Clark, Procter & Gamble, Nice-Pak Products, Rockline Industries, The Clorox Company, S.C. Johnson & Son, DuPont, Weiman Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Cleansing Products Market Evolving Landscape
Technology convergence between skin microbiome science and sustained-release polymer chemistry is redefining efficacy benchmarks, while procurement centralization through health system consolidation is compressing vendor counts and elevating performance documentation requirements.
Film-forming polymer systems incorporating chlorhexidine gluconate in hydroalcoholic vehicles are fragmenting the traditional aqueous solution segment. Academic medical centers in the United States and university hospitals in France are specifying these formulations for prolonged antimicrobial persistence during lengthy cardiothoracic procedures. The technology is fragmenting competitive positioning by enabling premium pricing for documented residual activity versus conventional prep solutions that evaporate without protective barrier formation.
The FDA's ongoing antiseptic drug monograph revision process is eliminating triclosan and certain iodophors from acceptable active ingredient lists. Manufacturers holding abbreviated new drug applications face reformulation investments or portfolio discontinuation decisions by enforcement deadlines. Surgical prep kit assemblers in the United States are accelerating qualification audits for alternative active suppliers to ensure continuity in bundled instrument and drape offerings.
Health system procurement departments are consolidating supplier relationships through single-source contracts covering multiple product categories. Hospital materials management in the United Kingdom and integrated delivery networks in California are unbundling traditional distribution intermediaries to negotiate direct manufacturer agreements. The shift concentrates purchasing leverage among three to five national distributors while marginalizing regional players lacking formulary breadth or electronic health record integration capabilities.
Patient Cleansing Products Market Segmentation
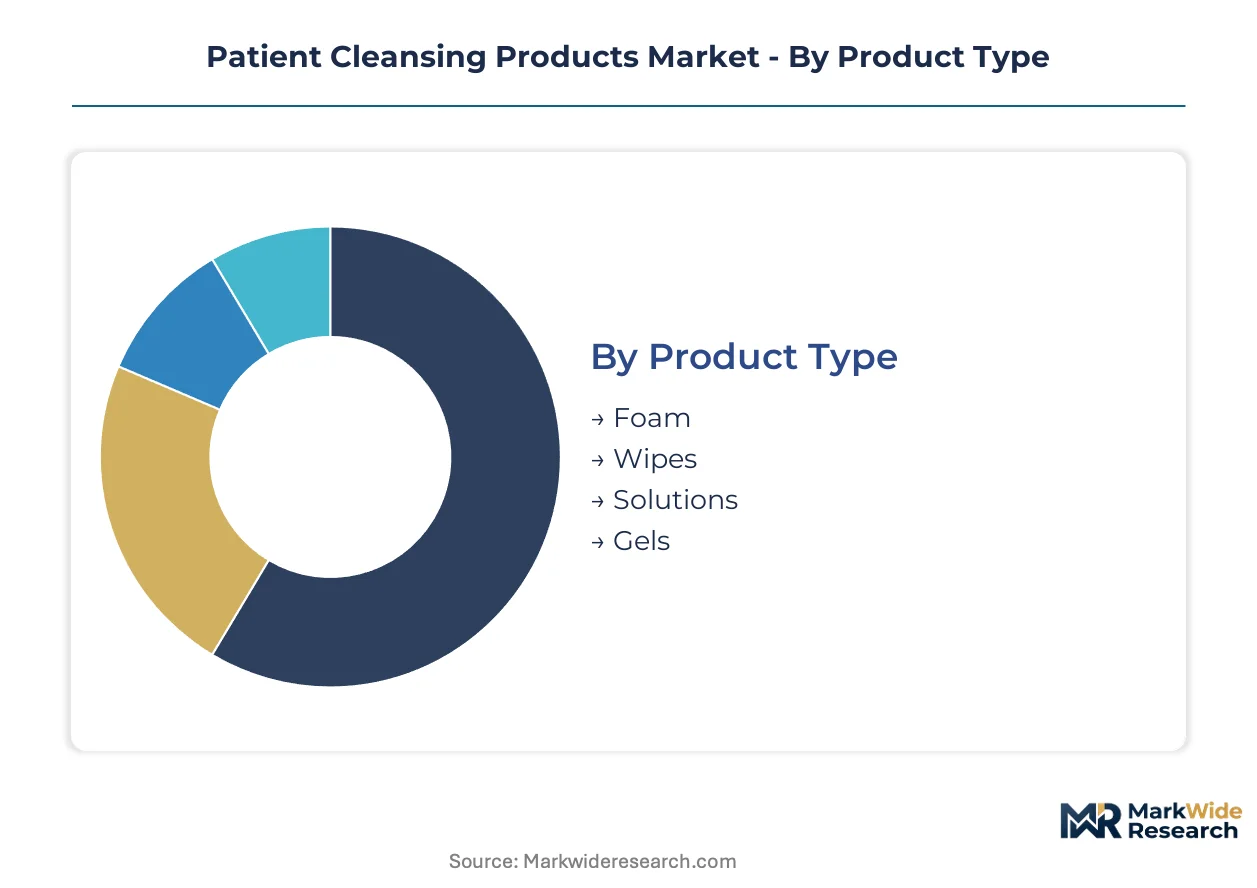
Product differentiation in patient cleansing markets tracks tightly to regulatory pathway complexity and end-use risk stratification. Formulation chemistry, delivery mechanism, and packaging sterility each trigger distinct compliance frameworks that reshape competitive positioning across segment boundaries.
Product Type:
FDA antiseptic drug monograph requirements diverge sharply by delivery format, with foam and solution classifications demanding abbreviated new drug application pathways that wipes and gels often bypass through cosmetic or device regulatory channels.
- Foam:Controlled-dose hydroalcoholic or aqueous formulations with surfactant vehicles dominate procedural volume in US operating rooms. The Joint Commission's surgical site infection documentation requirements drive standardized pump-dispensed procurement through integrated delivery networks, though seven-figure aseptic filling line investments constrain new entrant participation.
- Wipes:Impregnated nonwoven substrates capture expanding home care and long-term care facility demand where bedside convenience governs compliance among immobile patient populations. Japan's post-acute discharge protocols and Germany's community nursing frameworks sustain premium pricing for rinse-free formats despite higher per-use cost versus solutions.
- Solutions:Pour-bottle aqueous preparations retain margin concentration in preoperative surgical prep kits bundled with sterile drapes and instruments.
- Gels:Viscous hydroalcoholic vehicles with film-forming polymers target prolonged antimicrobial persistence during lengthy cardiothoracic procedures.
Established volume favors foam; emerging adoption favors wipes.
Application:
Reimbursement coding density and litigation exposure separate high-specification surgical applications from routine hygiene segments.
- Surgical Prep:Preoperative skin preparation protocols mandate documented chlorhexidine-alcohol or povidone-iodine application with persistent activity claims. US hospital procurement specifications now require ISO 10993 biocompatibility certification for adhesion-compatible formulations that reduce surgical drape lift incidents.
- Infection Control:Outbreak response and isolation room protocols drive institutional volume for broad-spectrum antimicrobial cleansers with 30-second to 2-minute contact time claims.
- Daily Hygiene:Non-antimicrobial surfactant-based formulations serve routine patient bathing in general medical-surgical units where skin barrier preservation outweighs bioburden reduction.
- Skin Care:pH-balanced, fragrance-free vehicles address dermatological sensitivity in oncology and geriatric populations where treatment-induced barrier compromise elevates irritation risk.
Reimbursement intensity concentrates in surgical prep; volume expansion runs through infection control.
End User:
Procurement centralization and formulary control sophistication create tiered access barriers across institutional and community settings.
- Hospitals:Integrated delivery networks and group purchasing organizations consolidate vendor relationships through single-source contracts covering multiple product categories. California health systems and UK National Health Service trusts unbundle traditional distribution intermediaries to negotiate direct manufacturer agreements.
- Long-term Care Facilities:Nursing home chains bypass hospital-centric procurement structures through private-label arrangements with regional formulators, enabling margin retention absent GPO administrative fees.
- Home Care:Durable medical equipment suppliers and community nursing services generate demand for convenience-oriented packaging formats with extended shelf stability.
- Clinics:Ambulatory surgical centers and physician office laboratories balance unit economics against regulatory documentation requirements with lower audit frequency than acute care settings.
Contract leverage peaks in hospitals; margin retention favors long-term care.
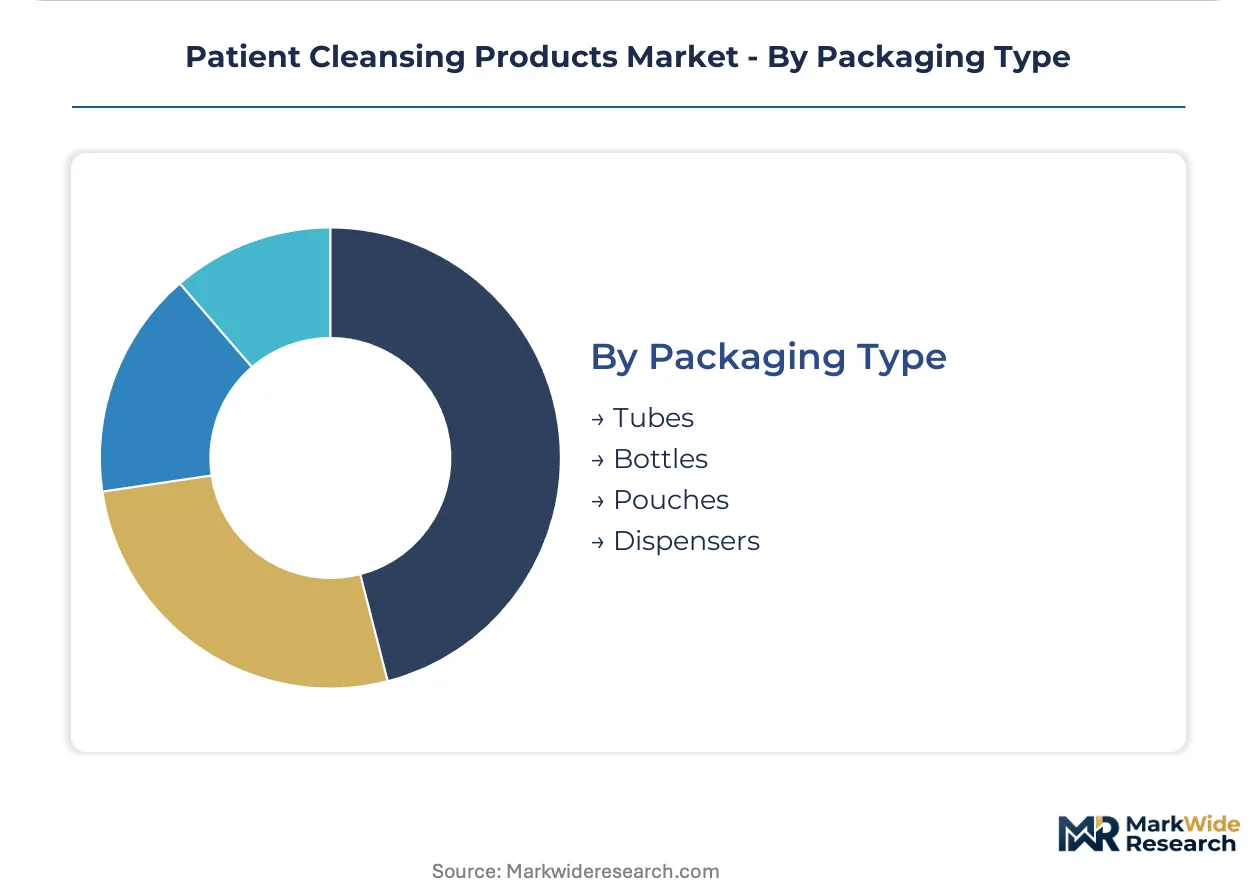
Packaging Type:
Sterility assurance level and dosing precision requirements differentiate single-use disposable formats from multi-dose refillable systems.
- Dispensers:Wall-mounted or countertop pump systems with sealed cartridge refills minimize contamination risk in high-frequency use environments. US hospital materials management specifies touch-free electronic dispensing for infection control units.
- Pouches:Individual unit-dose packaging satisfies surgical prep kit assemblers requiring validated sterility maintenance through terminal sterilization cycles.
- Bottles:Multi-dose containers with flip-top or screw-cap closures serve cost-sensitive daily hygiene applications where aseptic technique is not mandated.
- Tubes:Collapsible aluminum or laminate tubes deliver gel formulations with precise viscosity control for targeted application to intact skin.
Infection control specifications elevate dispensers; kit integration drives pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chlorhexidine gluconate API manufacturing clusters in China and India expose formulators to export licensing volatility, while regulatory tightening across developed healthcare systems drives demand for compliant finished goods in the United States, Germany, and Japan.
United States
The Joint Commission's National Patient Safety Goals mandate documented surgical site infection prevention protocols across acute care hospitals. FDA antiseptic drug monograph revisions are eliminating triclosan and certain iodophors, forcing reformulation investments by domestic manufacturers. Greater Boston's medical device corridor hosts surgical prep kit assemblers accelerating qualification audits for alternative active ingredient suppliers.
Germany
Post-acute care discharge protocols sustain premium pricing for rinse-free cleansing wipes among immobile patient populations. The country's national pharmaceutical regulator enforces stringent biocompatibility documentation under EU Medical Device Regulation frameworks. Bavaria's healthcare manufacturing belt concentrates private-label formulators serving nursing home chains through direct distribution partnerships.
Japan
Community nursing frameworks generate sustained demand for bedside hygiene maintenance products among aging populations. METI standards govern antimicrobial claim substantiation for skin-applied formulations. The Kansai region around Osaka hosts contract manufacturers specializing in pH-balanced vehicles for neonatal intensive care applications.
China
Domestic hospital procurement centralization is elevating specification requirements for preoperative skin preparation products in tier-one cities. The national medical products administration aligns antiseptic monograph standards with international benchmarks. Yangtze River Delta chemical manufacturers dominate chlorhexidine gluconate API production, exposing downstream formulators to freight cost spikes and export licensing delays.
India
Expanding private hospital networks in metropolitan areas are adopting chlorhexidine-alcohol combination formulations for cardiac and orthopedic procedures. The Central Drugs Standard Control Organization oversees abbreviated new drug application pathways for antimicrobial skin preparations. Gujarat's pharmaceutical manufacturing corridor houses active ingredient producers serving both domestic formulation and export markets.
Patient Cleansing Products Market Competitive Landscape
Concentration sits with diversified healthcare conglomerates and institutional supply specialists commanding integrated delivery network contracts. Three to five national distributors now capture the majority of hospital procurement volume, marginalizing regional players lacking formulary breadth. The competitive terrain separates into three archetypes: institutional supply conglomerates with GPO-anchored relationships, consumer goods multinationals leveraging R&D scale, and regional formulators exploiting private-label flexibility. Dominant competitive moves include backward integration into active ingredient sourcing and strategic partnerships with surgical kit assemblers.
Within the institutional supply tier, 3M and Kimberly-Clark occupy positions defined by technology leadership in adhesion-compatible formulations and distribution network density respectively. Procter & Gamble represents the consumer-multinational archetype with rinse-free formulation capabilities. These three entities exemplify how scale-driven R&D investment and contracted supply relationships create defensive positioning against procurement centralization pressures.
| Leading Market Players |
|---|
| 3M |
| Kimberly-Clark |
| Procter & Gamble |
| Nice-Pak Products |
| Rockline Industries |
| The Clorox Company |
| S.C. Johnson & Son |
| DuPont |
| Weiman Products |
| Others |
Value Network & Pricing Analysis
Chlorhexidine-alcohol combination formulations displacing single-agent povidone-iodine solutions are redrawing raw material procurement maps from Indian and Chinese API hubs toward European and North American formulation centers, simultaneously elevating compliance costs and compressing margin pools for manufacturers lacking backward integration into active ingredient supply.
Pricing Analysis
FDA antiseptic drug monograph revisions dictate the pricing tier structure across patient cleansing portfolios. Three-tier pricing structure across premium ISO 10993-certified formulations, standard hospital-grade solutions, and economy alcohol-based substitutes governs contract negotiations. Pricing pressure stems from group purchasing organization consolidation that extracts volume discounts from integrated delivery networks. Ambulatory surgical centers exhibit highest price sensitivity due to unfavorable reimbursement coding density, while cardiac surgery units accept premium positioning for documented drape adhesion compatibility.
Supply Chain Analysis
Inventory buffers for chlorhexidine gluconate API extend lead times for North American and European formulators dependent on Yangtze River Delta and Gujarat production clusters. Finished goods distribution runs through three to five national distributors capturing hospital procurement volume, while long-term care channels bypass intermediaries through direct manufacturer partnerships. Single-source vulnerability concentrates in Chinese export licensing volatility for antimicrobial actives, compounded by freight cost spikes disrupting just-in-time replenishment cycles for aseptic foam filling operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic health record interoperability mandates and surgical site infection documentation platforms are transforming procurement from transactional purchasing into data-integrated supply ecosystems, rewarding vendors with embedded analytics capabilities.
For Market Incumbents: Consolidate GPO-anchored relationships through multi-category single-source contracts spanning prep solutions, drapes, and instrument kits. Deepen backward integration into chlorhexidine gluconate API through strategic offtake agreements with Yangtze River Delta manufacturers, mitigating supply disruption exposure from export licensing volatility.
For New Entrants and Emerging Players: ISO 10993 biocompatibility certification fast-tracks specification entry for adhesion-compatible surgical prep formulations targeting litigation-sensitive cardiothoracic units. Exploit private-label flexibility in German and Japanese long-term care channels where nursing home chains bypass hospital-centric procurement structures, deploying rinse-free wipe formats for immobile patient populations.
For Investors and Strategic Acquirers: The market sits at a procurement centralization phase that favors formulators with captive API supply and EHR integration capabilities. Five-to-ten-year viability hinges on regulatory compliance infrastructure rather than commodity manufacturing scale. Monitor FDA antiseptic drug monograph enforcement timelines as inflection signal for portfolio rationalization opportunities among ANDA-holding manufacturers facing reformulation investment cliffs.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Abbreviated New Drug Application Pathway | Accelerates market entry for chlorhexidine-alcohol formulations under revised monograph standards. |
| Backward Integration into API Supply | Captures margin pool and insulates formulators from Chinese export licensing volatility. |
| ISO 10993 Biocompatibility Certification | Commands specification preference in advanced wound closure procedures with litigation exposure. |
| Long-Term Care Direct Distribution Partnership | Bypasses GPO administrative fees and enables margin retention through private-label arrangements. |
| Electronic Health Record Integration Development | Aligns with procurement centralization and surgical site infection documentation mandates. |
Research Methodology
A spread of perspectives from hospital procurement managers, GPO contracts specialists, biomedical engineers, and regulatory affairs directors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA antiseptic drug monograph filings, The Joint Commission National Patient Safety Goals documentation, hospital procurement databases, and EU Medical Device Regulation implementation guidance. Bottom-up volume modeling triangulated against top-down healthcare expenditure allocation patterns.
Segmentation dimensions modeled span product type, application risk stratification, end-user procurement sophistication, and packaging sterility requirements across the projection horizon. CAGRs derive from regression analysis of historical volume trajectories adjusted for regulatory inflection points and health system consolidation patterns. Forecast inputs incorporate chlorhexidine gluconate API pricing volatility indices and surgical procedure volume projections by specialty.
Decision-makers should treat outputs as directional under assumptions of continued FDA monograph enforcement and stable group purchasing organization consolidation; material deviation in regulatory timelines or healthcare reimbursement policy would warrant model refresh. Specific risk factors include export licensing disruptions from Chinese API manufacturers and accelerated substitution toward plain alcohol solutions in resource-constrained settings. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Elderly Walker Market
Healthcare Products
Medical Products Market
Healthcare Products
North America Adult Incontinence Products Market
Healthcare Products
Menstrual Sponge Market
Healthcare Products
Pressure Ulcer Prevention Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
Consumer Healthcare Market
Healthcare Products
Nursing Products Market
Healthcare Products
Italy Hand Sanitizer Market
Healthcare Products
Global Healthcare Distribution Market
Healthcare Products
Blood and Blood Components Market
Healthcare Products
GCC Healthcare Packaging Market
Healthcare Products
Automatic Hand Sanitizer Dispenser Market
Healthcare Products
Europe Blood and Blood Components Market
Healthcare Products
United States Infrared Sauna Market
Healthcare Products
Global Consumer Healthcare Products Market