
 Global Prophylactic Human Vaccine Market | 2026-2036
Global Prophylactic Human Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Prophylactic Human Vaccine Market Foresight
Bioprocess engineering talent is rotating from small-molecule pharmaceuticals into vaccine manufacturing, expanding fill-finish capacity and cell-culture expertise across the industry. Pfizer Inc. leverages its lipid nanoparticle platform to sustain leadership in mRNA formulation scale-up. Merck & Co. Inc. anchors its position through long-standing dominance in pediatric combination vaccines. GlaxoSmithKline plc differentiates via proprietary adjuvant systems that enhance immunogenicity across its viral and bacterial portfolios.
A prophylactic human vaccine is a biological preparation containing antigenic material—whole inactivated pathogens, live attenuated organisms, purified subunits, or nucleic acid constructs—that stimulates adaptive immunity without causing disease, manufactured under aseptic conditions with cold-chain preservation typically between two and eight degrees Celsius. The primary commercial purpose is population-level disease prevention through mass immunization programs and individual protective vaccination. mRNA and viral vector platforms represent the fastest-expanding technology categories, driven by platform versatility and rapid strain-adaptation capability. Conjugate vaccines retain entrenched positions in pediatric schedules, generating stable, high-margin recurring revenue from multivalent formulations against pneumococcal and meningococcal diseases. Inactivated vaccines maintain broad geographic reach where cold-chain infrastructure remains limited, particularly across tropical climates where thermostability constraints shape procurement decisions.
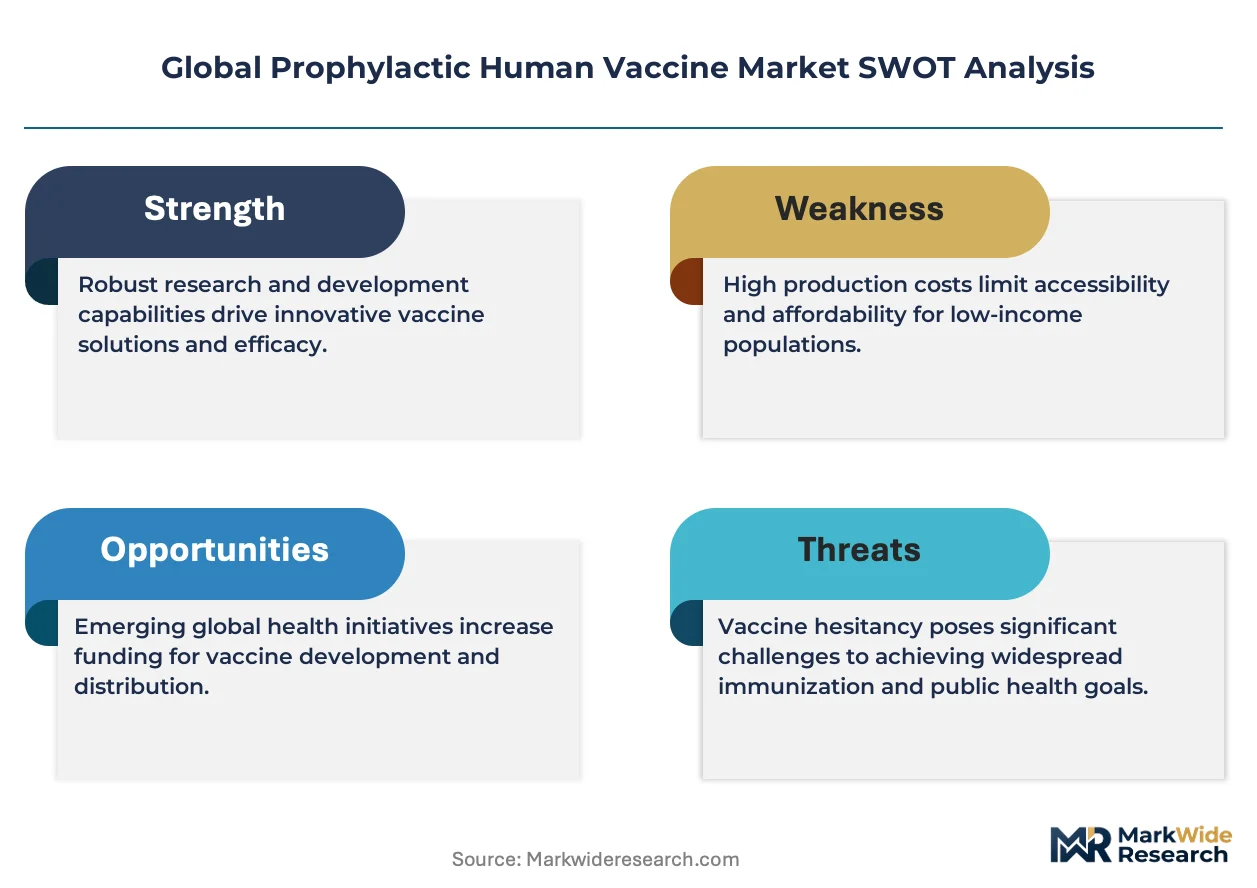
The FDA governs investigational new drug applications and biologics license approvals in the United States, while the EMA enforces centralized marketing authorization and pharmacovigilance standards across European Union member states. India's CDSCO coordinates clinical trial oversight and manufacturing site inspections under the Drugs and Cosmetics Act, with the country's national immunization program serving as the dominant procurement mechanism. WHO prequalification remains essential for access to Gavi and UNICEF purchasing channels, effectively gatekeeping participation in low-income country supply. Stakeholders must monitor how platform patent cliffs and biosimilar entry timelines reshape competitive intensity across both established and emerging vaccine categories.
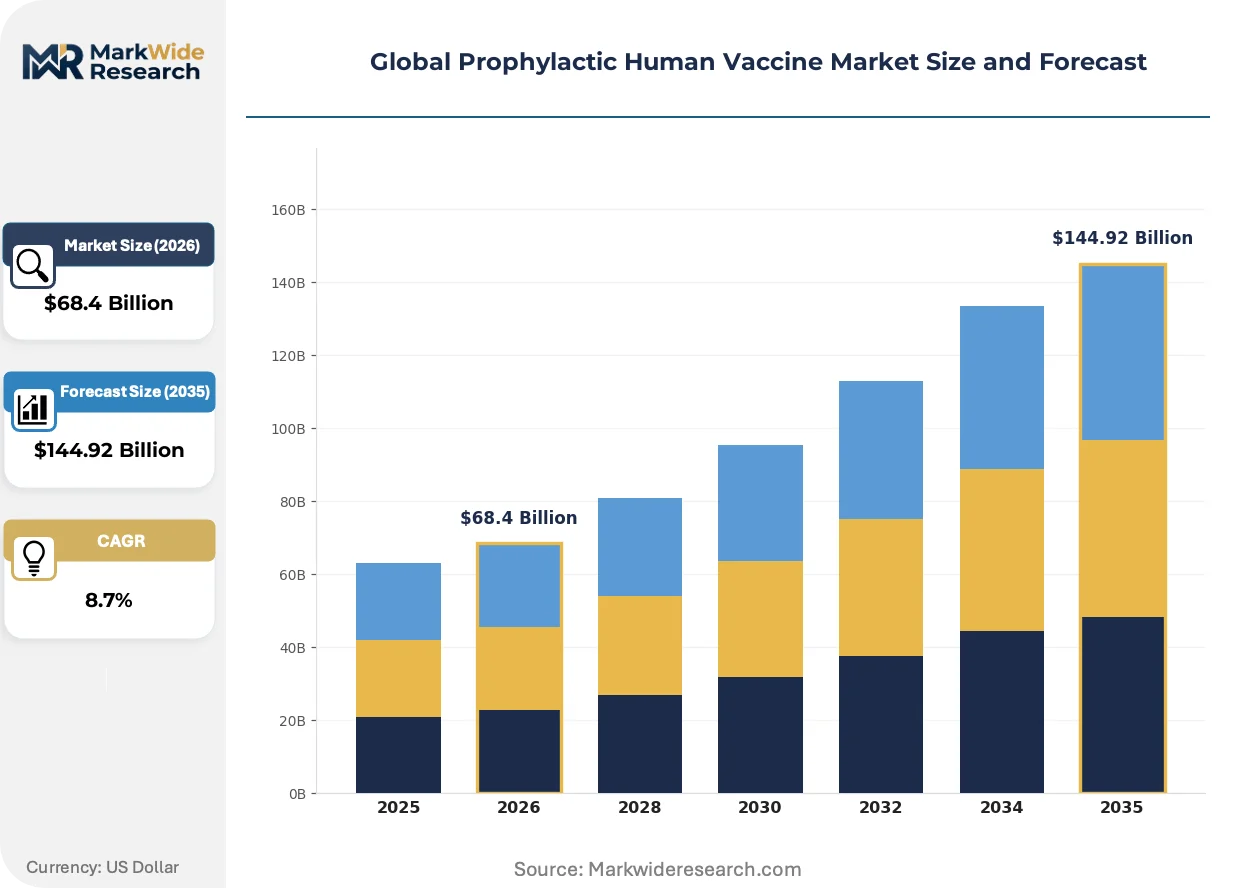
Market Dynamics
The prophylactic human vaccine market is undergoing platform consolidation as mRNA manufacturing infrastructure built during recent public health emergencies repurposes toward endemic disease portfolios, compressing development cycles and reshaping competitive entry barriers.
Growth Catalysts
- WHO Prequalification Expansion:Accelerated prequalification pathways for thermostable formulations are unlocking Gavi and UNICEF procurement channels for manufacturers in India and Southeast Asia.
- Pediatric Schedule Expansion:National immunization programs in low-income countries are adding pneumococcal and rotavirus doses, creating recurring demand for combination vaccines.
- Cell-Culture Platform Maturation:Suspension-based manufacturing is replacing egg-based production for influenza vaccines, improving strain-matching agility and yield consistency.
Market Restraints
- Cold-Chain Infrastructure Gaps:Last-mile distribution in tropical climates limits mRNA vaccine penetration where ultra-low-temperature storage remains unavailable.
- Adjuvant Supply Concentration:Proprietary saponin and oil-in-water adjuvant production concentrates among three specialized chemical suppliers, creating single-source vulnerability.
- Regulatory Divergence:Divergent stability-testing requirements between FDA and EMA force redundant clinical lot release programs, extending approval timelines.
Strategic Opportunities
- Sub-Saharan Africa Penetration:Underimmunized birth cohorts in Nigeria and Democratic Republic of Congo represent addressable demand for pentavalent and hexavalent combination vaccines.
- Self-Administered Delivery:Microneedle patch technologies under evaluation by India's CDSCO could displace clinical administration for booster doses.
- US IRA Price Negotiation Exemption:Vaccines remain excluded from Medicare price-setting mechanisms, preserving premium pricing for novel adult immunizations.
Industry Challenges
- Fill-Finish Bottleneck:Aseptic vial-filling capacity constraints at contract manufacturing organizations delay commercial launch timelines for late-stage pipeline assets.
- Biosimilar Entry Preparation:Patent cliff anticipation for key conjugate vaccines requires reformulation strategies and lifecycle management expertise that current teams lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Prophylactic Human Vaccine Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Inactivated, Live Attenuated, Subunit, Conjugate, mRNA, Viral Vector Target Disease: Influenza, Human Papillomavirus, Hepatitis B, Measles, Meningococcal, Diphtheria End User: Public Health Clinics, Private Hospitals, Immunization Centers, Pharmaceutical Companies, Research Institutes, Travel Medicine Clinics Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Government Supply, Medical Distributors, Nonprofit Organizations |
| Companies Covered | Pfizer Inc., Merck & Co. Inc., GlaxoSmithKline plc, Sanofi, Johnson & Johnson Services, Inc., AstraZeneca plc, Moderna Inc., CSL Limited, Serum Institute of India Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Prophylactic Human Vaccine Market Shifts & Advancements
Platform versatility is compressing the traditional decade-long vaccine development arc into multi-year cycles, while regulatory science advances and procurement centralization reshape how immunization products reach populations.
mRNA lipid nanoparticle formulations are supplanting protein subunit approaches for respiratory syncytial virus and cytomegalovirus candidates. Pfizer and Moderna have advanced these programs into Phase III evaluation, with regulatory submissions anticipated for maternal and elderly populations. The structural consequence is a shift toward modular manufacturing suites that can pivot between infectious disease targets without facility revalidation.
The FDA's Project NextGen initiative is streamlining immunobridging study designs for strain-updated COVID-19 formulations, reducing reliance on large-scale efficacy trials. European manufacturers are adapting clinical development programs to align with these reduced evidence standards. Pediatric combination vaccine developers remain unaffected, as immunogenicity non-inferiority requirements for concomitant administration studies stay unchanged.
National procurement consolidation is concentrating purchasing power through centralized tenders in Brazil, Indonesia, and South Africa. UNICEF's vaccine independence initiative is building direct supplier relationships that bypass traditional distributor networks. The operational shift is most visible in Southeast Asia, where ministry of health warehouses now handle last-mile distribution previously managed by private cold-chain logistics providers.
Global Prophylactic Human Vaccine Market Segmentation
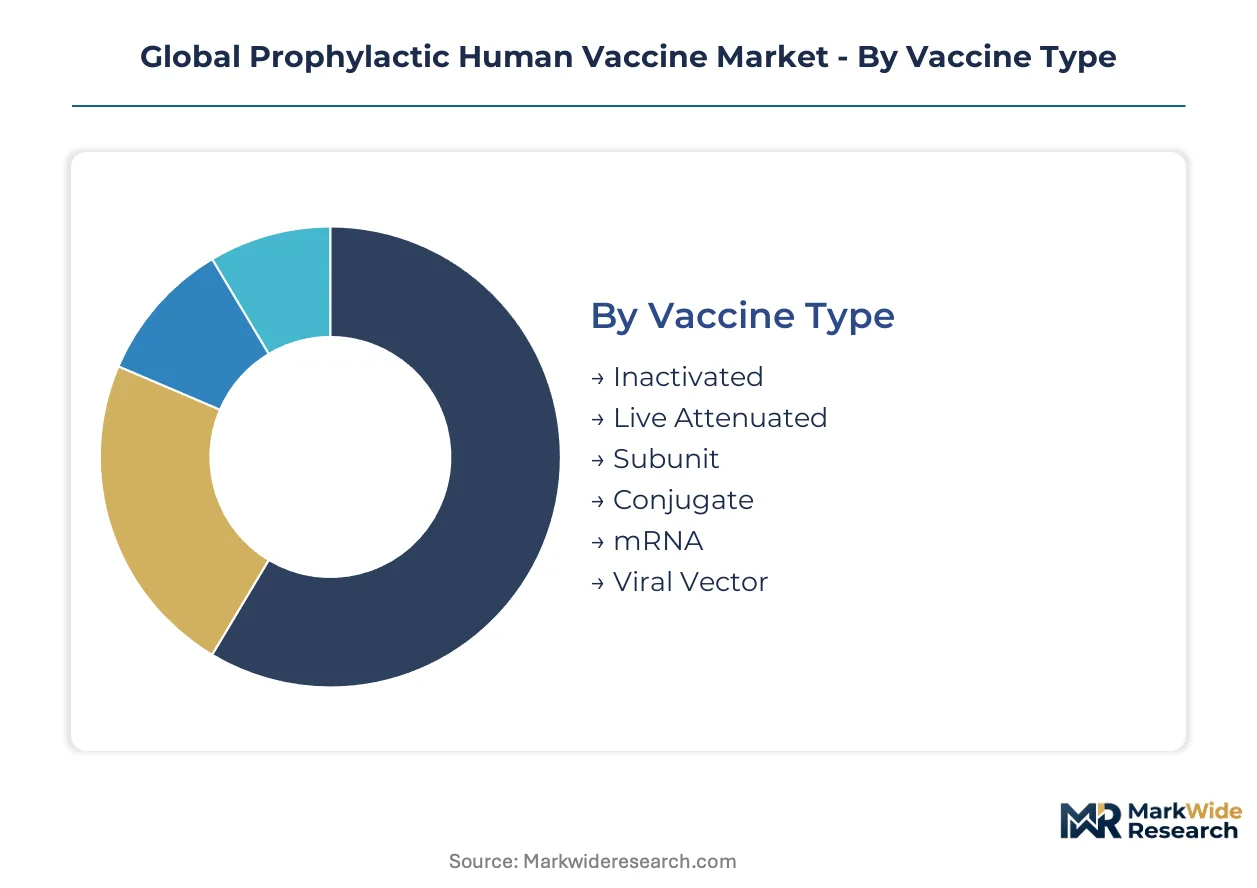
Platform substitution pressures are fragmenting legacy revenue pools across the prophylactic human vaccine market as mRNA and viral vector technologies displace established modalities. Segmentation clarity reveals where incumbents defend entrenched positions versus where agile entrants capture share through manufacturing flexibility and cold-chain independence.
Vaccine Type:
mRNA and viral vector platforms exert the strongest substitution pressure on inactivated and live attenuated formulations, compressing development timelines and reshaping capital allocation across manufacturing networks.
- Inactivated:Whole pathogens chemically or thermally deactivated retain immunogenicity without replication capacity. Demand concentrates in India and Southeast Asia where WHO prequalification unlocks Gavi procurement for tropical deployment without ultra-cold infrastructure.
- Live Attenuated:Weakened pathogen strains induce durable cellular and humoral immunity through limited replication. Measles and yellow fever programs in Nigeria and Democratic Republic of Congo drive volume through single-dose efficacy and thermostable lyophilized presentations.
- Subunit:Purified protein antigens combined with adjuvant systems eliminate replication risk entirely.
- Conjugate:Polysaccharide-protein linkages generate T-cell dependent responses in infant immune systems.
- mRNA:Lipid nanoparticle-encapsulated nucleoside-modified sequences enable rapid strain adaptation for respiratory pathogens.
- Viral Vector:Engineered adenovirus or vesicular stomatitis virus backbones deliver transgenes with potent immunogenicity.
Inactivated vaccines retain volume leadership through established cold-chain compatibility; mRNA holds the steepest expansion curve as manufacturing infrastructure repurposes from emergency response to endemic portfolios.
Target Disease:
Cost-tier stratification separates high-margin adolescent and adult indications from commoditized pediatric schedules where national tenders compress pricing.
- Influenza:Seasonal strain-matching requirements and annual revaccination create recurring manufacturing demand with cell-culture platforms displacing egg-based production for improved antigenic fidelity.
- Human Papillomavirus:Two-dose adolescent schedules in national immunization programs generate stable recurring revenue with nine-valent formulations commanding premium positioning in private markets across Brazil and South Africa.
- Hepatitis B:Birth-dose administration within 24 hours remains the cornerstone of vertical transmission prevention.
- Measles:Second-dose campaigns target elimination thresholds in underimmunized districts.
- Meningococcal:Quadrivalent conjugate vaccines address serogroup diversity in sub-Saharan African belt countries.
- Diphtheria:Tetanus-diphtheria-pertussis combination formulations anchor pediatric schedules globally.
Human Papillomavirus vaccines retain volume leadership through expanded adolescent coverage; influenza holds the steepest expansion curve as mRNA platforms enable pandemic preparedness manufacturing pivots.
End User:
Application concentration varies sharply between population-level public health deployment and individualized clinical administration where reimbursement pathways diverge.
- Public Health Clinics:Government-funded immunization sessions reach rural populations through outreach campaigns.
- Private Hospitals:Fee-for-service administration of premium-priced travel and adult vaccines generates margin.
- Immunization Centers:Dedicated ministry of health facilities handle national program cold-chain logistics.
- Pharmaceutical Companies:Corporate occupational health programs mandate hepatitis B and influenza coverage.
- Research Institutes:Phase III trial sites enroll maternal and elderly cohorts for novel platform evaluation.
- Travel Medicine Clinics:Pre-departure consultation drives yellow fever and typhoid demand among international travelers.
Public Health Clinics retain volume leadership through national program procurement; Travel Medicine Clinics hold the steepest expansion curve as international mobility recovers and destination requirements tighten.
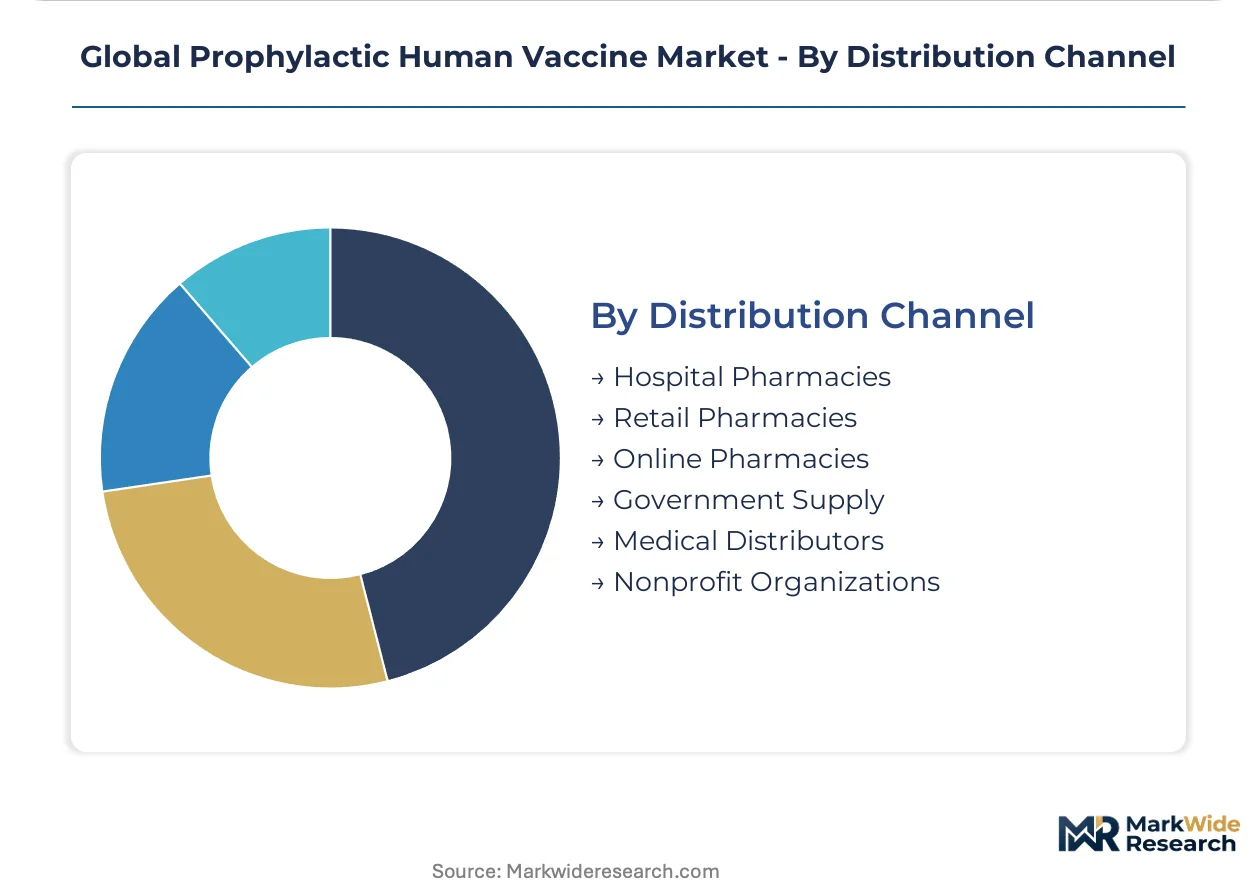
Distribution Channel:
Supply concentration and margin capture diverge between centralized government tenders and fragmented retail pharmacy networks where price transparency pressures manufacturer net revenue.
- Hospital Pharmacies:Institutional procurement of combination vaccines for inpatient pediatric wards.
- Retail Pharmacies:Over-the-counter adult influenza and shingles vaccines in pharmacy-led jurisdictions.
- Online Pharmacies:Direct-to-consumer scheduling platforms emerging in urban Indian markets.
- Government Supply:UNICEF and PAHO pooled procurement mechanisms concentrate purchasing power.
- Medical Distributors:Regional cold-chain logistics providers bridge last-mile gaps in Indonesia and Philippines archipelago geographies.
- Nonprofit Organizations:Gavi-eligible country delivery through civil society immunization partners.
Government Supply retains volume leadership through consolidated tender mechanisms; Medical Distributors hold the steepest expansion curve as decentralized cold-chain investment penetrates archipelago and mountainous geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO oversight coordinates clinical trial frameworks and manufacturing inspections across India, where the Serum Institute of India Pvt. Ltd. anchors global supply volume through WHO prequalified facilities.
United States
FDA accelerated approval pathways compress development timelines for breakthrough vaccine designs. The IRA exempts vaccines from Medicare price negotiation, preserving premium pricing for novel adult immunizations. Massachusetts and Maryland clusters concentrate mRNA formulation expertise and viral vector manufacturing capacity.
India
National immunization program expansion drives demand for pentavalent and hexavalent combination vaccines. CDSCO evaluates microneedle patch technologies for self-administered booster delivery. Pune and Hyderabad house the world's largest vaccine manufacturing facilities by volume, with fill-finish capacity scaling for export markets.
Germany
EMA centralized marketing authorization streamlines pharmacovigilance standards across EU member states. Bavaria hosts specialized adjuvant production facilities serving European formulation networks. Frankfurt and Munich clusters advance cell-culture platform maturation for influenza strain-matching agility.
Brazil
Ministry of health centralized tenders concentrate purchasing power for pneumococcal and rotavirus pediatric schedules. ANVISA clinical trial oversight aligns with WHO prequalification requirements for Gavi procurement access. São Paulo state warehouses manage last-mile distribution previously handled by private cold-chain logistics.
South Africa
National procurement consolidation through centralized tenders addresses underimmunized birth cohorts in sub-Saharan Africa. SAHPRA coordinates manufacturing site inspections under regional harmonization initiatives. Cape Town and Johannesburg clusters serve as distribution hubs for pentavalent vaccines penetrating Nigeria and Democratic Republic of Congo.
Global Prophylactic Human Vaccine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with platform consolidation compressing competitive entry barriers. mRNA manufacturing infrastructure repurposed from emergency response now serves endemic disease portfolios. Three archetypes dominate: lipid nanoparticle platform holders, pediatric combination vaccine incumbents, and adjuvant system specialists. Capacity expansion and strategic technology licensing represent the primary competitive moves reshaping positioning.
Within the integrated multinational tier, Pfizer Inc. and Merck & Co. Inc. exemplify divergent platform strategies, while GlaxoSmithKline plc occupies a position emphasizing proprietary immunogenicity enhancement. Serum Institute of India Pvt. Ltd. anchors volume-driven supply for WHO prequalified markets. These entities represent how manufacturing scale, formulation expertise, and regulatory navigation capability stratify competitive standing across technology categories and geographic procurement channels.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co. Inc. |
| GlaxoSmithKline plc |
| Sanofi |
| Johnson & Johnson Services, Inc. |
| AstraZeneca plc |
| Moderna Inc. |
| CSL Limited |
| Serum Institute of India Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
Fill-finish capacity utilization above eighty percent across Indian and European contract manufacturing organizations creates dual pressure on unit economics and procurement timelines. This concentration of aseptic manufacturing expertise simultaneously elevates price floors for novel platform vaccines and compresses margins for established combination formulations as capacity allocation favors higher-margin mRNA programs.
Pricing Analysis
Price spreads between UNICEF tender rates and private hospital administration in Brazil and South Africa exceed threefold for equivalent pneumococcal conjugate formulations. Three-tier pricing structure across premium, standard, and economy levels separates Gavi-eligible procurement from national program volumes and private travel clinic retail. Cost compression in pediatric combination schedules intensifies as Serum Institute of India and emerging Korean manufacturers expand WHO prequalified capacity. Public health clinics exhibit highest price sensitivity due to fixed national immunization budgets, while corporate occupational health programs show lowest sensitivity for premium adult vaccines.
Supply Chain Analysis
Chokepoint concentration in saponin-derived adjuvant production—centered on Bavarian specialized chemical facilities—creates single-source vulnerability for enhanced immunogenicity formulations. Active pharmaceutical ingredient synthesis draws from India, China, and Switzerland for lipid nanoparticle components and cell-culture media. Glass vial and rubber stopper supply rests on German and Italian specialized packaging manufacturers exposed to energy cost volatility. Distribution runs through UNICEF Copenhagen stockpile and PAHO revolving fund mechanisms for low-income country penetration, with regional medical distributors bridging archipelago last-mile gaps in Indonesia and Philippines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The prophylactic human vaccine market is recovering from pandemic-era demand spikes through normalization of pediatric schedule catch-up campaigns and maternal immunization program expansion.
For Market Incumbents: Compound formulation expertise in lipid nanoparticle stabilization and adjuvant system integration to defend against platform substitution threats from mRNA specialists. Secure backward integration into fill-finish capacity at Hyderabad and Pune manufacturing clusters to reduce contract manufacturing organization dependency. Prioritize CDSCO and WHO prequalification maintenance for Gavi procurement channel retention as Indian competitors scale pentavalent output. For New Entrants and Emerging Players: Self-administered delivery format development represents the most penetrable white-space where incumbents under-serve, particularly microneedle patch technologies for booster dose markets. Target sub-Saharan African pentavalent and hexavalent demand in Nigeria and Democratic Republic of Congo where underimmunized birth cohorts exceed regional manufacturing capacity. Pursue technology licensing partnerships with established adjuvant suppliers rather than de novo immunogenicity platform development. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pediatric combination vaccine incumbents with entrenched national immunization program formulary positions and long-term UNICEF supply agreements. Five-to-ten year viability favors manufacturers with demonstrated thermostable formulation capability and established WHO prequalification track records. Watch for inflection signals in CDSCO microneedle patch approval timelines and Gavi pentavalent tender volume allocation shifts toward Indian suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Serum Institute of India's fill-finish expansion secures WHO prequalified capacity for Gavi procurement dominance. |
| Regulatory Approval Pathway | FDA Project NextGen immunobridging study designs compress strain-updated COVID-19 formulation approval timelines. |
| Licensing Agreement | Adjuvant system technology licensing from Bavarian specialists enables rapid immunogenicity enhancement for subunit platforms. |
| Pipeline Diversification | mRNA platform pivot from COVID-19 to RSV and CMV candidates leverages existing lipid nanoparticle manufacturing infrastructure. |
| Clinical Trial Advancement | Phase III maternal immunization cohort enrollment in Brazil and South Africa accelerates regulatory submission for novel platforms. |
Research Methodology
A standing panel of vaccine development executives, regulatory affairs leads at FDA and EMA, national immunization program managers, and hospital procurement directors provided ongoing calibration across primary fieldwork phases. Secondary validation drew from WHO prequalification listings, CDSCO manufacturing inspection reports, ClinicalTrials.gov protocol registrations, and UNICEF procurement tender databases. Bottom-up volume modeling across platform categories triangulated against top-down national immunization program expenditure data from Gavi and PAHO member states.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by vaccine platform technology, target disease indication, end-user setting, and distribution channel, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs were derived from fitted growth curves incorporating pediatric schedule expansion rates, platform substitution elasticities, and procurement tender volume trajectories. Industry-specific inputs included fill-finish capacity utilization surveys and adjuvant raw material price indices.
Underlying assumptions cover sustained Gavi funding commitments, WHO prequalification pathway stability, and mRNA cold-chain infrastructure penetration rates, with deviation risk concentrated in tropical climate ultra-cold storage deployment delays and biosimilar conjugate vaccine entry timelines. Practitioners should keep alternative scenarios live as CDSCO regulatory science evolution and UNICEF procurement centralization initiatives mature.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Ultrasound Probe Disinfection Market
Infection Control
Catheter-Related Bloodstream Infections (Crbsis) Market
Infection Control
Perianal Infection Treatment Market
Infection Control
Virus Filtration Market
Infection Control
Pertussis Infection Testing Market
Infection Control
Germicidal UV Lamp Market
Infection Control
North America Bloodstream Infection Testing Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
Global Hospital Acquired Infection Control Market
Infection Control
Preventable Vaccines Market
Infection Control
Sterilization Equipment and Disinfectant Market
Infection Control
Dental Infection Treatment Market
Infection Control
Ear Infection Treatment Market
Infection Control
Global Disinfection Robots Market
Infection Control
Surgical Site Infection Control Market
Infection Control
Community Acquired Pneumonia (CAP) Market