
 Global Hospital Infection Therapeutics Market | 2026-2036
Global Hospital Infection Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hospital Infection Therapeutics Market Analysis
The capability gap between large-scale antibiotic manufacturers and niche antiviral developers is collapsing as multidrug-resistant pathogens force portfolio diversification across the industry. Pfizer Inc. leverages its global manufacturing infrastructure to sustain reliable supply of broad-spectrum antibiotics for hospital formularies. Merck & Co., Inc. anchors its position through deep R&D investment in novel antibacterial mechanisms. Johnson & Johnson Services, Inc. differentiates via specialized surgical infection prevention protocols integrated with its device portfolios.
Hospital infection therapeutics comprise pharmaceutical agents designed to treat or prevent pathogenic infections acquired during medical care, typically administered through intravenous infusion for rapid systemic distribution in critical settings. These therapies function primarily to reduce mortality from sepsis, pneumonia, and post-operative complications while limiting pathogen transmission within healthcare facilities. Antibiotics retain the largest revenue share among product types, though antifungals gain structural importance as Candida auris outbreaks strain hospital pharmacies. The intravenous delivery mode dominates acute therapy areas such as sepsis and surgical infections, while oral formulations expand in step-down and long-term care transitions. Hospitals remain the central end-user channel, capturing the majority of value as infection surveillance programs tighten admission-to-discharge monitoring requirements.
The FDA antimicrobial stewardship mandates reshape prescribing volumes and drive demand for narrow-spectrum alternatives, while the EMA's evolving antibacterial guidance accelerates adaptive trial designs for novel mechanisms. WHO's global action plan on antimicrobial resistance influences national reimbursement policies and hospital procurement standards across member states. Stakeholders must monitor regulatory divergence between accelerated approval pathways and post-market surveillance obligations as resistance surveillance data reshapes therapeutic prioritization.
Market Dynamics
The FDA antimicrobial stewardship mandates compress antibiotic prescribing volumes while simultaneously accelerating narrow-spectrum therapeutic development, fundamentally restructuring how hospital formularies balance empiric coverage against resistance containment.
Growth Catalysts
- Stewardship mandates:The FDA antimicrobial stewardship program tightens prescribing protocols across US hospital systems. This regulatory pressure forces adoption of diagnostics-guided therapy selection.
- ICU infrastructure expansion:Tertiary hospitals in India deploy combination antibiotic protocols for sepsis management. Intensive care bed growth drives intravenous antibiotic consumption.
- Resistance surveillance networks:Germany's national health agency integrates real-time pathogen tracking with pharmacy procurement. Data feedback loops prioritize targeted therapeutic acquisition.
Market Restraints
- Active pharmaceutical ingredient concentration:China dominates fermentation-based antibiotic intermediate production. Supply vulnerability constrains European and North American formulation capacity.
- Clinical trial complexity:The EMA adaptive licensing framework demands larger non-inferiority trials for novel mechanisms. Development timelines extend for first-in-class antibacterials.
- Generic substitution pressure:Off-patent broad-spectrum agents capture hospital procurement tenders. Price compression limits branded therapeutic penetration in standard-of-care indications.
Strategic Opportunities
- Step-down oral transitions:Long-term acute care facilities in the United States adopt oral antibiotic protocols for post-ICU recovery. This channel remains underdeveloped relative to inpatient infusion centers.
- Fungal resistance protocols:Candida auris outbreak containment drives investment in novel azole-sparing antifungals. Hospital pharmacy budgets reallocate toward mold-active agents.
- WHO procurement alignment:The WHO Essential Medicines List revision creates reimbursement leverage for national health systems. List inclusion accelerates formulary access across member states.
Industry Challenges
- Specialized microbiology staffing:Clinical pharmacists with infectious disease credentials remain scarce relative to stewardship program mandates. Training pipelines fail to match hospital expansion rates.
- Diagnostic-therapeutic integration:Rapid susceptibility testing platforms require workflow reconfiguration alongside antibiotic switching protocols. Implementation friction delays time-to-appropriate-therapy metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hospital Infection Therapeutics Market |
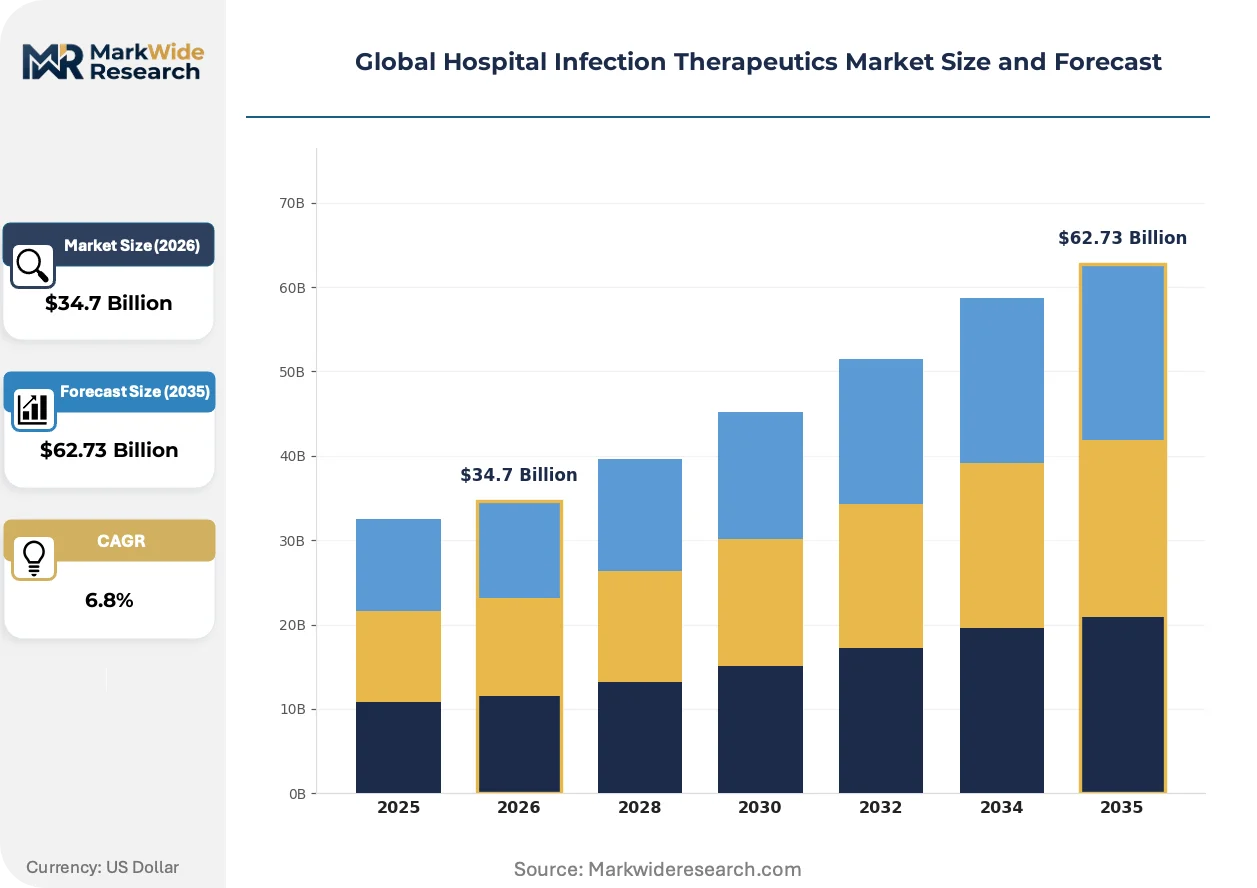
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antifungals, Antivirals, Antiseptics Delivery Mode: Intravenous, Oral, Topical, Inhalation End User: Hospitals, Clinics, Long-term Care Facilities, Labs Therapy Area: Sepsis, Pneumonia, Urinary Tract Infections, Surgical Infections |
| Companies Covered | Merck & Co., Inc., Pfizer Inc., GlaxoSmithKline plc, AstraZeneca plc, Johnson & Johnson Services, Inc., F. Hoffmann-La Roche Ltd, Bayer AG, AbbVie Inc., Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hospital Infection Therapeutics Market Emerging Trajectories
Antimicrobial resistance surveillance is compressing the effective lifespan of empiric antibiotic protocols, forcing simultaneous investment in diagnostic-guided therapy and novel mechanism discovery across hospital systems.
Phage therapy adjuncts for multidrug-resistant Pseudomonas and Acinetobacter infections are decomposing the traditional antibiotic monotherapy model in specialized cystic fibrosis and burn centers. University hospitals in Belgium and the United States pilot compassionate-use programs with engineered bacteriophage cocktails. This convergence of biological and pharmaceutical therapeutics is fragmenting infectious disease treatment pathways into pathogen-specific protocols.
The EMA's PRIME designation for antibacterial medicines accelerates adaptive trial designs and conditional marketing authorizations for novel mechanisms targeting carbapenem-resistant Enterobacteriaceae. European hospital networks participate in post-authorization safety studies as a condition of accelerated access. Smaller biotechnology developers leverage this pathway to bypass traditional phase-three infrastructure requirements.
Hospital procurement committees now unbundle antibiotic acquisition from diagnostic testing contracts, creating separate vendor relationships for susceptibility platforms and therapeutic supply. This purchasing fragmentation shifts negotiating leverage toward integrated diagnostics-pharmaceutical bundles. German and Dutch hospital purchasing cooperatives pilot this model most aggressively, with formulary committees demanding real-time resistance data as a procurement condition.
Global Hospital Infection Therapeutics Market Segmentation
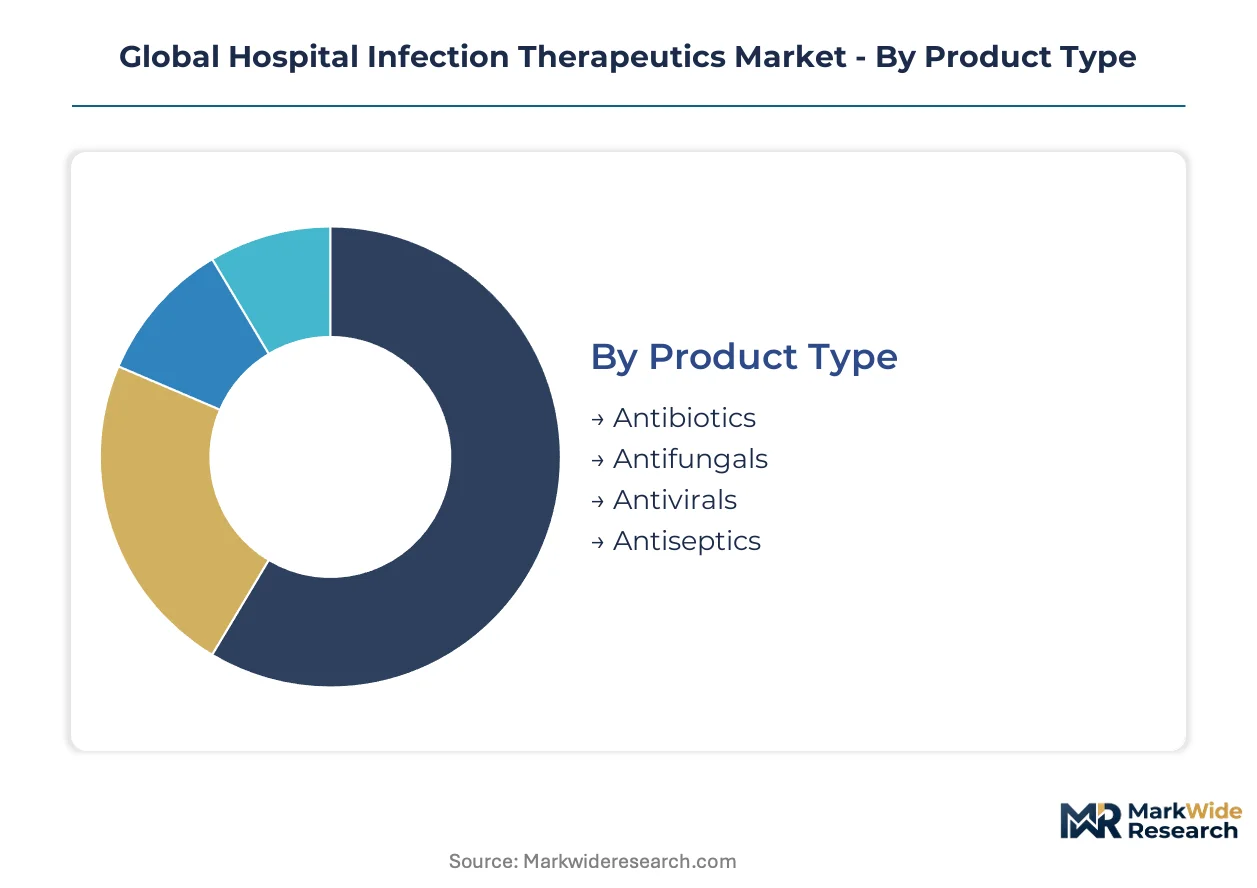
Hospital infection therapeutics fragment across four operational dimensions that determine procurement workflows and margin capture. Product type and delivery mode concentrate revenue in acute care settings, while end-user and therapy area segmentation reveal channel expansion opportunities beyond tertiary hospitals.
Product Type:
Margin pools concentrate in narrow-spectrum antibiotics and novel antifungals as resistance surveillance reshapes formulary premiums.
- Antibiotics:Beta-lactam, carbapenem, and lipopeptide formulations dominate hospital formularies for empiric sepsis coverage. United States tertiary hospitals drive demand for combination protocols targeting multidrug-resistant Gram-negative pathogens under FDA stewardship mandates.
- Antifungals:Echinocandins and mold-active azoles address Candida auris and invasive aspergillosis in immunocompromised patients. German hospital networks prioritize acquisition of azole-sparing alternatives as resistance surveillance data feeds procurement decisions.
- Antivirals:Direct-acting agents for influenza and respiratory syncytial virus serve seasonal outbreak protocols in pediatric and geriatric wards.
- Antiseptics:Chlorhexidine and iodine-based preparations integrate with surgical site infection prevention bundles in pre-operative skin preparation.
Antibiotics hold installed capacity. Antifungals is rotating up the share rankings.
Delivery Mode:
Volume concentration follows the patient journey from ICU stabilization through step-down recovery.
- Intravenous:Continuous infusion and extended-infusion beta-lactam protocols maximize pharmacodynamic exposure in critically ill patients. India's expanding tertiary ICU infrastructure drives consumption of broad-spectrum intravenous agents for sepsis management.
- Oral:Bioavailable fluoroquinolones and oxazolidinones enable transition from inpatient infusion to long-term acute care discharge. United States step-down facilities adopt oral stewardship protocols to reduce central line complications.
- Topical:Ointments and impregnated dressings address localized surgical site infections and catheter exit-site colonization.
- Inhalation:Aerosolized antibiotics serve cystic fibrosis centers and ventilator-associated pneumonia protocols in specialized respiratory units.
Intravenous maintains formulary dominance. Oral is climbing the fastest as care shifts to lower-acuity settings.
End User:
Customer type determines contracting structure and diagnostic-therapeutic integration requirements.
- Hospitals:Tertiary medical centers with intensive care units anchor procurement volume through centralized pharmacy and therapeutics committees. Germany's university hospital networks integrate real-time resistance surveillance with antibiotic stewardship program mandates.
- Clinics:Ambulatory infusion centers and infectious disease practices manage outpatient parenteral antimicrobial therapy for complex infections.
- Long-term Care Facilities:Skilled nursing facilities in the United States adopt oral antibiotic protocols for post-acute recovery, creating underdeveloped channel opportunity relative to inpatient settings.
- Labs:Reference laboratories and hospital microbiology departments influence therapeutic selection through rapid susceptibility testing platform deployment.
Hospitals hold installed capacity. Long-term Care Facilities is rotating up the share rankings.
Therapy Area:
Application severity dictates pricing tolerance and protocol standardization across institutional purchasers.
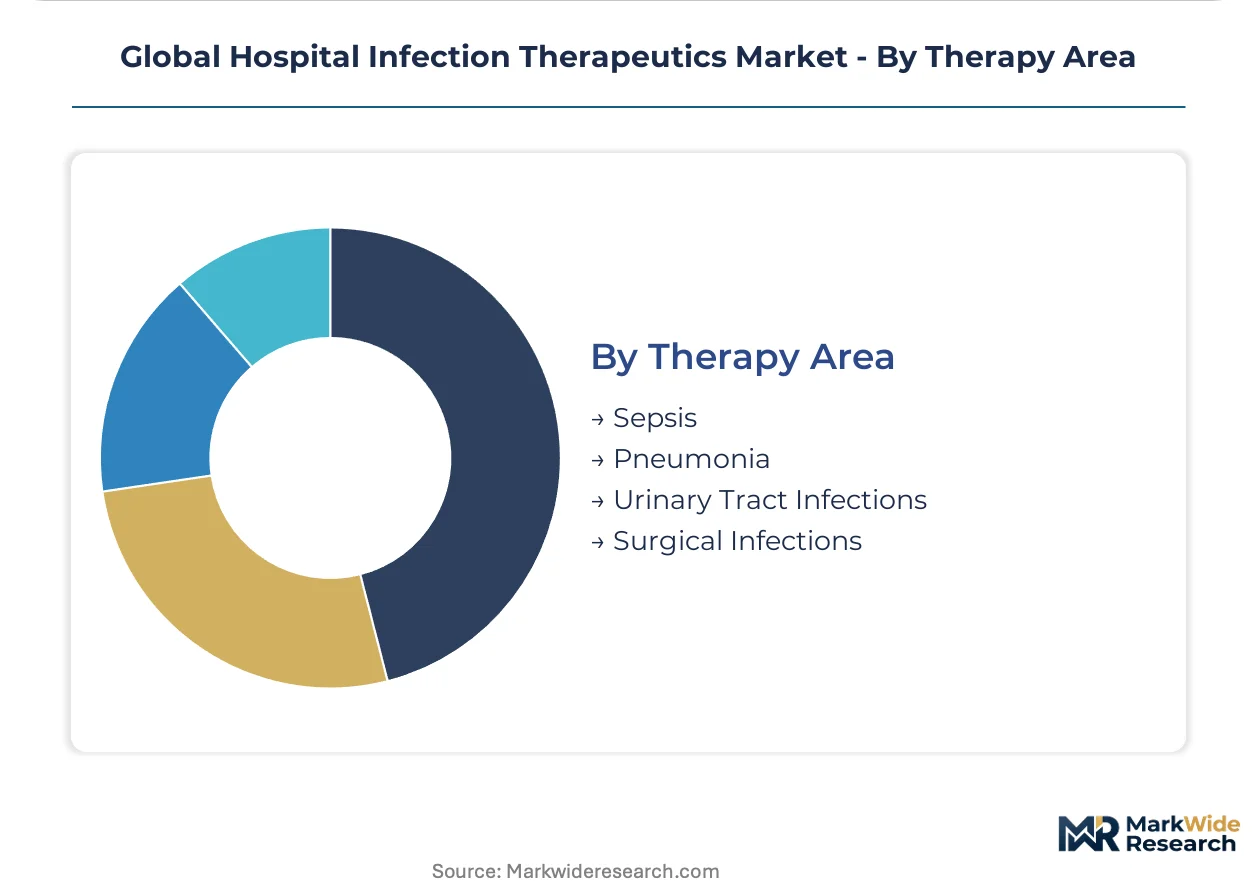
- Sepsis:Time-critical empiric coverage with broad-spectrum agents followed by de-escalation based on culture results defines standard workflow. Indian tertiary hospitals deploy combination antibiotic protocols as ICU bed expansion accelerates consumption.
- Pneumonia:Ventilator-associated and hospital-acquired pneumonia protocols favor antipseudomonal beta-lactams plus adjunctive agents in United States critical care units.
- Urinary Tract Infections:Catheter-associated infections drive fluoroquinolone and cephalosporin utilization in urology and geriatric wards.
- Surgical Infections:Prophylactic and therapeutic protocols for abdominal, orthopedic, and cardiac procedures integrate device-related infection prevention bundles.
Sepsis holds installed capacity. Surgical Infections is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital infection therapeutics demand exhibits stark elasticity variation. India's price-sensitive public procurement constrains branded antibiotic margins. Germany's stewardship-driven formulary premiums sustain narrow-spectrum pricing power.
United States
Tertiary ICU expansion and FDA antimicrobial stewardship mandates drive combination antibiotic protocols. The Centers for Medicare & Medicaid Services ties reimbursement to resistance surveillance compliance. Boston and New York hospital networks integrate rapid diagnostics with therapeutic switching workflows.
Germany
University hospital networks anchor carbapenem consumption for multidrug-resistant Gram-negative coverage. The EMA's PRIME designation accelerates novel antibacterial access. North Rhine-Westphalia purchasing cooperatives unbundle antibiotic procurement from diagnostic testing contracts.
India
ICU bed growth in Delhi and Mumbai accelerates intravenous broad-spectrum antibiotic demand. CDSCO streamlines approval for fixed-dose combination therapies. Maharashtra's tertiary hospitals deploy sepsis management protocols with pharmacodynamic-optimized dosing.
China
National health security initiatives expand hospital infection surveillance infrastructure. NMPA antimicrobial stewardship guidelines reshape provincial procurement standards. Yangtze River Delta medical centers pilot diagnostic-guided de-escalation protocols for pneumonia.
United Kingdom
NHS England's resistance reduction targets compress empiric prescribing volumes. MHRA adaptive licensing frameworks support novel mechanism development. London teaching hospitals integrate phage therapy adjuncts into cystic fibrosis treatment pathways.
Global Hospital Infection Therapeutics Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive architecture. Large pharmaceutical conglomerates leverage global manufacturing infrastructure and hospital formulary relationships. Mid-tier biotechnology developers concentrate on narrow-spectrum mechanisms and adaptive trial designs. The dominant competitive moves involve portfolio diversification into antifungal and antiviral adjacents, alongside strategic partnerships with diagnostic platform developers.
Within the integrated pharmaceutical tier, Pfizer Inc. and Merck & Co., Inc. occupy positions exemplifying scale-driven supply reliability and deep R&D investment in novel antibacterial mechanisms respectively. Johnson & Johnson Services, Inc. anchors the device-therapeutic integration archetype through surgical infection prevention protocols. Among European-headquartered developers, GlaxoSmithKline plc and AstraZeneca plc represent diversified portfolio approaches spanning antiviral and antibacterial domains.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Johnson & Johnson Services, Inc. |
| F. Hoffmann-La Roche Ltd |
| Bayer AG |
| AbbVie Inc. |
| Sanofi S.A. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day fermentation batch cycles for antibiotic active pharmaceutical ingredients concentrate pricing power with Chinese intermediate manufacturers and force European formulators into long-term offtake contracts. This lead-time rigidity amplifies margin pressure when raw material costs fluctuate and limits hospital pharmacy flexibility in switching between generic suppliers.
Pricing Analysis
After-sales revenue from infusion pump service contracts and IV compatibility testing drives lifetime value capture beyond the pharmaceutical unit sale. Three-tier pricing structure across premium narrow-spectrum agents, standard broad-spectrum formulations, and economy generic tenders dominates hospital procurement. Price differentiation rests on FDA Breakthrough Therapy designation and EMA PRIME eligibility as certification premiums. Pricing pressure stems from India's centralized tender system compressing branded margins. Public hospital systems in Delhi and Mumbai exhibit highest price sensitivity, while German university hospitals tolerate premium narrow-spectrum pricing under stewardship mandates.
Supply Chain Analysis
Strait of Malacca transit routes for fermentation-derived antibiotic intermediates expose European and North American formulators to logistics disruption risk. Supply concentrates in China, India, and Italy for active pharmaceutical ingredient synthesis. Raw material dependencies include corn starch for fermentation feedstock, specialized enzyme catalysts, and sterile packaging components. Single-source vulnerability in carbapenem intermediate production constrains formulation flexibility. Distribution runs through hospital purchasing cooperatives in Germany and the Netherlands, group purchasing organizations in the United States, and centralized tender authorities in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital infection therapeutics sits in early-cycle expansion as diagnostic-guided therapy adoption penetrates below 30 percent of standard-of-care protocols. FDA and EMA stewardship mandates accelerate this penetration curve by devaluing empiric prescribing.
For Market Incumbents: Fortify formulary position through backward integration into rapid susceptibility testing platforms, neutralizing the threat of unbundled procurement committees. Deepen captive supply of narrow-spectrum fermentation capacity in India to preempt CDSCO localization incentives. Anchor hospital relationships via integrated stewardship program staffing that locks out competitor switching.
For New Entrants and Emerging Players: Step-down oral transition protocols in United States long-term acute care facilities represent an underserved service layer where incumbents under-serve with legacy IV-centric portfolios. Target skilled nursing facility pharmacy managers with pharmacokinetic-optimized oral antibiotic bundles. Pursue hospital-at-home partnership channels as the most penetrable go-to-market angle, bypassing entrenched tertiary hospital committees.
For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents divesting anti-infective divisions amid portfolio prioritization shifts toward oncology and immunology. The five-to-ten-year viability window favors developers with late-stage novel mechanisms and existing EMA PRIME designations. Watch for Candida auris outbreak declarations as the inflection signal triggering hospital pharmacy budget reallocation toward mold-active antifungals.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA PRIME designation accelerates carbapenem-resistant Enterobacteriaceae therapy access across European hospital networks. |
| Hospital System Partnership | Integrated diagnostics-therapeutics bundles shift procurement leverage toward vendors with real-time resistance data platforms. |
| Pipeline Diversification | Antifungal adjacents capture pharmacy budget reallocation as Candida auris containment protocols strain azole formularies. |
| Manufacturing Scale-Up | Fermentation capacity expansion in India addresses API concentration risk and aligns with CDSCO localization incentives. |
| Reimbursement Strategy | WHO Essential Medicines List inclusion creates national health system leverage accelerating formulary access across member states. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital pharmacy directors, infectious disease clinicians, regulatory affairs specialists at EMA and FDA, and procurement managers at German purchasing cooperatives and refined through secondary validation. Sources included FDA antimicrobial stewardship guidance documents, EMA adaptive licensing framework publications, CDSCO fixed-dose combination approval records, hospital formulary databases, and WHO global action plan implementation reports. Bottom-up demand modeling from ICU bed expansion trajectories and top-down market sizing from pharmaceutical revenue disclosures were triangulated to converge estimates.
Variance decomposition across product type, delivery mode, therapy area severity, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate blending weighted by revenue contribution shares. Forecast inputs incorporated resistance surveillance network expansion timelines, stewardship mandate implementation phases, and diagnostic platform adoption curves throughout the projection horizon.
Forecasts assume regulatory continuity in FDA antimicrobial stewardship programs and EMA PRIME designation criteria; material policy shifts would require re-modeling. Resistance surveillance data quality, generic substitution enforcement intensity, and API supply disruption frequency represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as diagnostic-therapeutic integration workflows and hospital procurement unbundling trends evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Botulism Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Hand Hygiene Market
Infection Control
Global Infection Prevention Devices Market
Infection Control
Infection Control Surveillance Solutions Market
Infection Control
Sanitizers Market
Infection Control
Biological and Chemical Indicators Market
Infection Control
Asia-Pacific Hand Sanitizer Market
Infection Control
Global High Level Disinfection Services Market
Infection Control
Hand Sanitizer Spray Market
Infection Control
Global Dental Infection Control Products Market
Infection Control
Infection Control Supplies Market
Infection Control
Europe Ultrasound Probe Disinfection Market
Infection Control
Antimicrobial Hospital Curtains Market
Infection Control
Staphylococcal Infection Treatment Market
Infection Control
Yeast Infection Market