
 Infant Nutrition Market | 2026-2036
Infant Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Infant Nutrition Market Analysis
Plant-based protein sources is broadening formulation economics as manufacturers reduce dairy dependency in premium infant formula. Danone S.A. anchors its portfolio in specialized hypoallergenic lines across European and Asian markets. Nestlé S.A. leverages extensive backward integration into dairy and plant ingredient supply chains to secure margin control. Abbott Laboratories differentiates through clinical nutrition science ties with pediatric research networks.
Infant nutrition encompasses scientifically formulated products designed to deliver precise macronutrient ratios, essential fatty acids, and micronutrient profiles matching human milk composition or age-appropriate dietary needs, manufactured through spray-drying, wet-mixing, and aseptic blending processes subject to microbiological safety thresholds. The products serve as sole or supplementary nourishment for infants and toddlers where breastfeeding is insufficient or unavailable. Infant formula dominates value generation due to premium pricing and repeat purchase frequency, while hypoallergenic formulations within the formulation type dimension command outsized margins driven by medical necessity and limited supplier pools. Online retail channels within distribution channel segmentation accelerate fastest as subscription models and direct-to-parent platforms displace traditional pharmacy dependence.
FDA enforces infant formula nutrient specifications and Good Manufacturing Practice compliance through facility inspections and recall authority, while EFSA sets EU-wide compositional and labeling standards under general food law, and China's SAMR implements formula registration requirements including clinical trial data for market entry. These frameworks elevate compliance costs but also create barriers protecting validated manufacturers from unqualified entrants. Stakeholders must monitor evolving probiotic and HMO additive approval pathways as regulatory science races ahead of commercial formulation pipelines.
Market Dynamics
Formula registration mandates from China's SAMR are compressing market entry timelines while simultaneously elevating compliance barriers that favor established manufacturers with clinical trial infrastructure over new entrants.
Growth Catalysts
- Dual-income household expansion:Working parents across developed economies prioritize ready-to-feed and liquid concentrate formats that reduce preparation time. This demographic shift sustains premium pricing power for convenience-oriented SKUs.
- EFSA additive pathway evolution:The European regulator's advancing approval frameworks for human milk oligosaccharides and specific probiotic strains enable differentiated positioning in hypoallergenic and gut-health segments.
- Spray-drying automation:Continuous processing technologies reduce batch-to-batch variability while tightening microbiological control, lowering rejection rates at contract manufacturing facilities.
Market Restraints
- Dairy protein input volatility:Whey and casein concentrate prices fluctuate with New Zealand and EU milk powder auction cycles, compressing gross margins for non-vertically integrated blenders.
- Supply concentration in lactose processing:Three European suppliers dominate pharmaceutical-grade lactose refinement, creating single-source vulnerability for manufacturers targeting Chinese registration requirements.
- SAMR clinical trial mandates:China's formula registration rules require domestic infant feeding studies that extend time-to-market by 18-24 months versus historical notification pathways.
Strategic Opportunities
- Sub-Saharan Africa underpenetration:Nigeria, Kenya, and South Africa exhibit rising middle-class formation with limited domestic manufacturing capacity, creating import-dependent demand for powder and ready-to-feed formats.
- Precision fermentation proteins:Microbial-derived dairy proteins from Perfect Day and similar suppliers enable hypoallergenic formulations without animal agriculture supply chain exposure.
- Direct-to-parent subscription platforms:Recurring revenue models bypass pharmacy and grocery intermediaries while capturing first-party consumption data for personalized nutrition recommendations.
Industry Challenges
- Pediatric nutrition specialist scarcity:Formulation scientists with human milk composition expertise command premium compensation while academic pipeline output remains constrained.
- Legacy ERP integration with track-and-trace systems:Manufacturers face multi-year implementation cycles to achieve unit-level serialization compliance across FDA, EFSA, and SAMR divergent requirements.
- Clean-label certification complexity:Organic, non-GMO, and grass-fed claims require distinct audit trails that fragment procurement and complicate supplier qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant Nutrition Market |
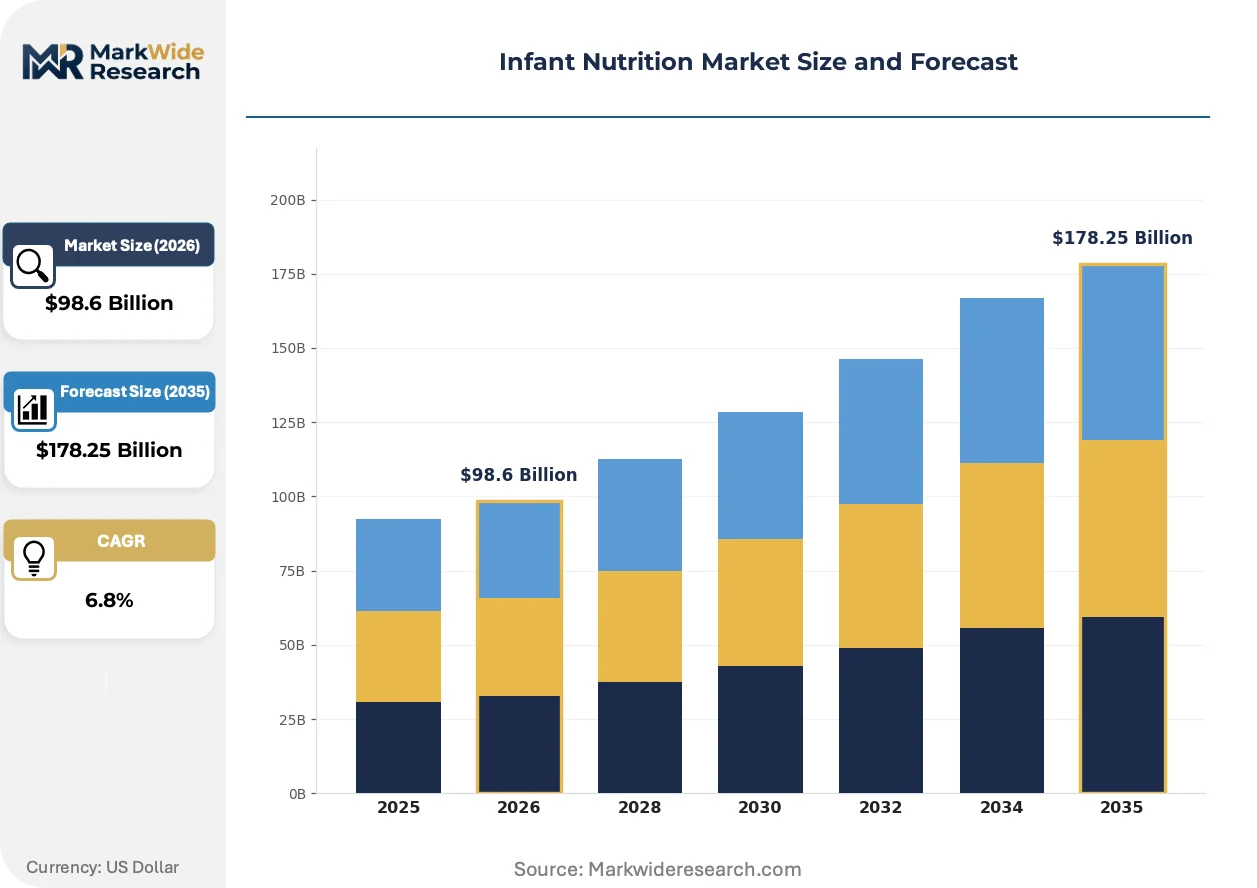
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Formula, Baby Cereals, Snacks, Beverages Age Group: 0-6 Months, 6-12 Months, 1-2 Years, Above 2 Years Formulation Type: Organic, Conventional, Fortified, Hypoallergenic Distribution Channel: Supermarkets, Online Retail, Pharmacies, Specialty Stores |
| Companies Covered | Nestlé S.A., Danone S.A., Reckitt Benckiser, Abbott Laboratories, China Feihe Ltd., Perrigo Company plc, Arla Foods amba, FrieslandCampina, The Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant Nutrition Market Emerging Trajectories
Biotechnology-enabled ingredient sourcing and regulatory science acceleration are converging to reshape competitive differentiation beyond traditional dairy supply chain control.
Continuous manufacturing systems are automating batch release protocols through integrated online near-infrared spectroscopy and automated microbiological sampling. Mid-tier European manufacturers are retrofitting existing spray-drying towers with these sensor arrays to reduce quality hold times from 72 hours to 4 hours. This compression is automating working capital efficiency improvements that previously required greenfield facility investment.
EFSA's novel food approval streamlining for fermented ingredients is accelerating commercialization timelines for precision-derived lipids and proteins. The industrial consequence is a shift from commodity dairy procurement toward biotechnology partnerships with fermentation startups. Specialized hypoallergenic lines in Germany, France, and the Netherlands are most affected, with Danone and Nestlé restructuring R&D budgets toward biofoundry collaborations.
Parent purchasing behavior is fragmenting across channel types as subscription platforms capture trial-to-loyalty conversion previously owned by pharmacy chains. Direct-to-consumer brands in the United Kingdom and Australia are displacing Boots and Chemist Warehouse dependency through personalized nutrition questionnaires and pediatric telehealth integration. This channel rotation is most visible among first-time parents aged 30-35 in metropolitan markets where digital health engagement rates exceed national averages.
Infant Nutrition Market Segmentation
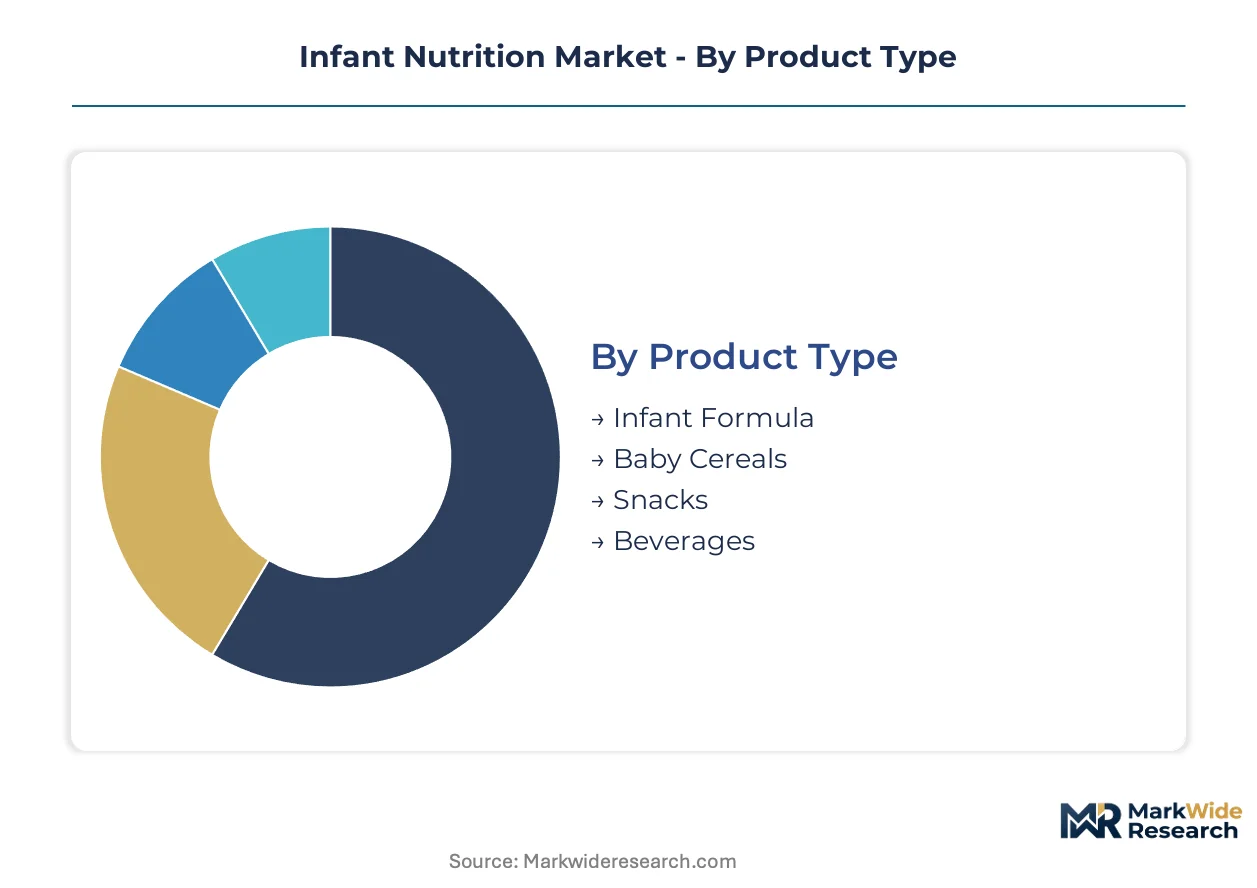
Segmentation in infant nutrition determines manufacturing asset allocation and regulatory compliance pathways. Product format and age targeting dictate formulation complexity, while channel selection shapes margin capture and customer lifetime value economics.
Product Type:
Supply concentration in liquid processing infrastructure favors manufacturers with aseptic filling capabilities over commodity powder blenders.
- Infant Formula:Spray-dried or liquid-concentrate products delivering complete macronutrient profiles matching human milk composition. Demand concentrates in China where SAMR registration requirements favor established manufacturers with clinical trial infrastructure. This segment absorbs the bulk of R&D expenditure and premium pricing power.
- Baby Cereals:Iron-fortified grain-based complementary foods introduced at 4-6 months. European demand through EFSA-monitored channels concentrates in organic variants as clean-label preferences intensify among German and French parents.
- Snacks:Puffed rice, fruit purees, and teething biscuits designed for self-feeding development. Japanese and South Korean parents drive innovation in low-sodium, allergen-free formats through convenience store channels.
- Beverages:Ready-to-drink toddler milks and juice alternatives. Distribution runs through pharmacy chains in Italy and Spain where pediatrician recommendation carries purchase influence.
Infant Formula absorbs the bulk of installed capacity; Online Retail channel expansion is climbing the fastest.
Age Group:
Cost tier differentiation intensifies as manufacturers segment formulation complexity and pack sizes across developmental stages.
- 0-6 Months:Sole nutrition products requiring strict microbiological safety and precise whey-to-casein ratios. Neonatal intensive care units and first-time parents in US metropolitan markets concentrate demand for hypoallergenic variants.
- 6-12 Months:Transitional nutrition bridging exclusive milk feeding to complementary foods. Chinese parents prioritize DHA and ARA fortification levels exceeding baseline regulatory minima.
- 1-2 Years:Growing-up milks with reduced fat content and enhanced micronutrient density. Brazilian and Mexican markets exhibit rising per-capita consumption as breastfeeding duration shortens among urban working mothers.
- Above 2 Years:Preschool nutrition products emphasizing cognitive development claims. Australian and UK retailers are displacing traditional grocery placement with direct-to-parent subscription models.
0-6 Months commands premium pricing; Above 2 Years is gaining share fastest as manufacturers extend brand relationships.
Formulation Type:
Margin stratification separates certification-intensive premium tiers from commodity conventional production.
- Organic:USDA or EU organic certified products with traceable ingredient sourcing and prohibited synthetic additive lists. German bioland and French AB certification standards command shelf price premiums of 40-60% above conventional equivalents.
- Conventional:Standard formulation products meeting baseline FDA or EFSA nutritional specifications. Volume concentration in private-label supply chains serving price-sensitive segments across Southeast Asian markets.
- Fortified:Enhanced micronutrient profiles with added iron, zinc, vitamins A/D, or omega-3 fatty acids. Indian FSSAI regulations mandate specific fortification levels for commercial distribution.
- Hypoallergenic:Extensively hydrolyzed or amino acid-based formulations for cow's milk protein allergy management. Limited supplier pools and medical necessity pricing generate outsized margins in hospital and specialty pharmacy channels.
Conventional formulations dominate volume throughput; Hypoallergenic is expanding most quickly as allergy diagnosis rates rise.
Distribution Channel:
Customer type fragmentation is forcing channel-specific packaging and promotional investment.
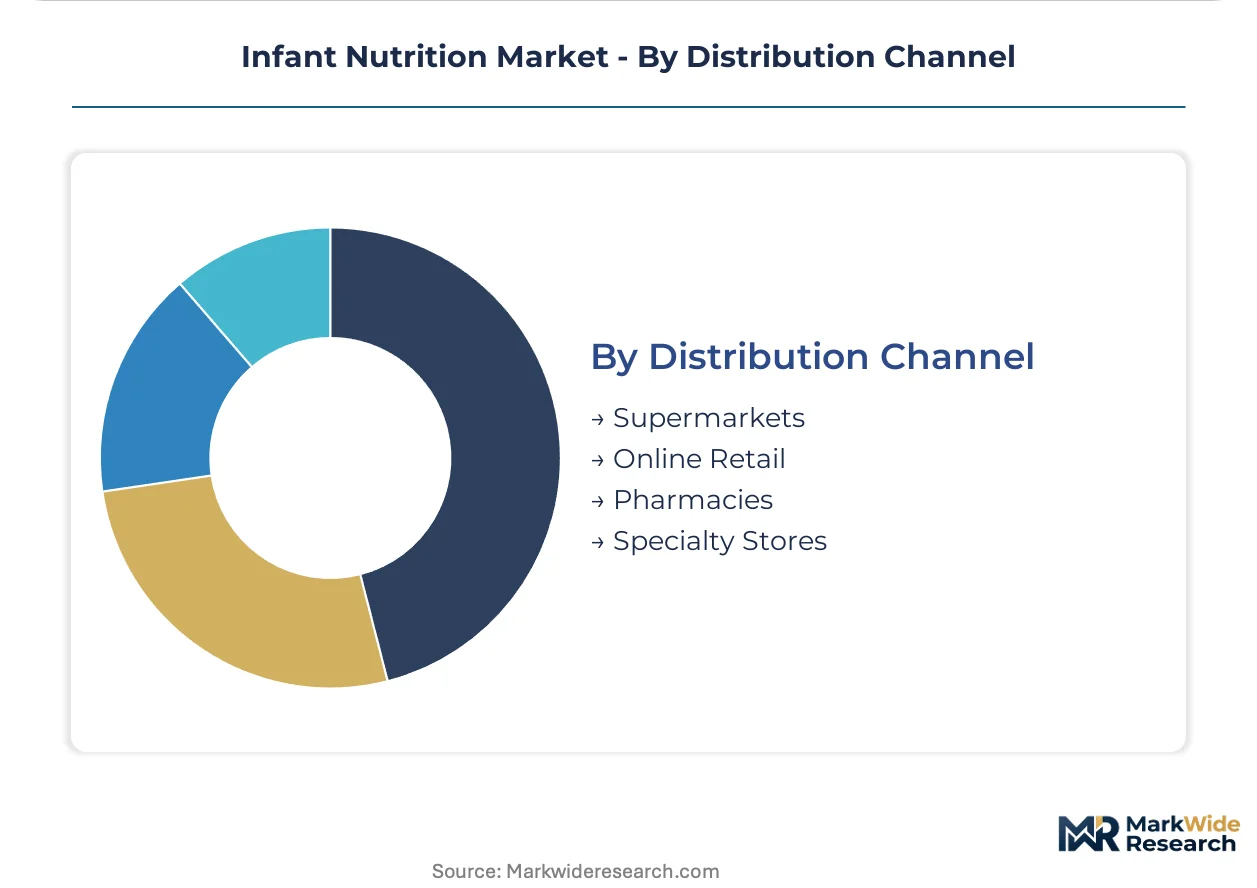
- Supermarkets:Mass-market retail with high-frequency replenishment and promotional pricing cycles. Walmart and Carrefour negotiate exclusive SKUs with volume commitments in North American and European markets.
- Online Retail:Direct-to-parent platforms and marketplace aggregators with subscription mechanics. Tmall and JD.com in China concentrate cross-border demand for imported brands bypassing domestic registration timelines.
- Pharmacies:Professional recommendation-dependent channels with trained staff consultation. Boots in the UK and CVS in the US maintain dietitian-staffed infant nutrition sections driving hypoallergenic conversion.
- Specialty Stores:Organic and natural product retailers with curated assortment and educated consumer base. Whole Foods Market and dm-drogerie markt in Germany prioritize clean-label and biodynamic certifications.
Supermarkets retain the largest transaction volume; Online Retail is accelerating fastest as subscription models capture repeat purchase loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the highest absolute demand volume as SAMR registration requirements reshape competitive access. Dual-income household formation across developed economies sustains premium pricing power for convenience formats.
China
Domestic brands capture share from multinational incumbents through localized formulation and distribution agility. SAMR mandates clinical trial data and facility inspections that extend registration timelines to 24-36 months. Manufacturing clusters concentrate in Heilongjiang and Inner Mongolia where dairy processing infrastructure supports powder production scale.
United States
FDA-enforced nutrient specifications and GMP compliance elevate manufacturing standards while limiting unqualified entrants. Working parents in metropolitan markets drive ready-to-feed and liquid concentrate adoption through pharmacy and subscription channels. Production assets cluster in Wisconsin and Ohio near dairy supply basins and pediatric research networks.
Germany
EFSA novel food approvals for HMOs and probiotics enable differentiated positioning in hypoallergenic segments. Organic certification through bioland and AB standards commands 40-60% shelf price premiums. Industrial concentration in Bavaria and North Rhine-Westphalia hosts spray-drying automation retrofits and biofoundry partnerships.
India
FSSAI-mandated fortification levels for iron, zinc, and vitamins create baseline formulation requirements across commercial distribution. Rising urbanization and shortening breastfeeding duration among working mothers expand addressable market for growing-up milks. Manufacturing activity concentrates in Maharashtra and Gujarat where dairy cooperatives and pharmaceutical-grade lactose access intersect.
Brazil
Per-capita consumption of toddler nutrition products rises as breastfeeding duration shortens among urban working mothers. ANVISA regulatory frameworks align with CODEX standards while permitting regional formulation adaptations. São Paulo and Minas Gerais anchor import-dependent supply chains for powder and ready-to-feed formats.
Infant Nutrition Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers extend from core formula into specialized medical nutrition and direct-to-consumer platforms. The vendor base stratifies across three tiers: multinational dairy conglomerates with backward integration into ingredient supply chains, regional specialists with SAMR registration advantages in China, and direct-to-parent subscription platforms bypassing traditional pharmacy intermediaries. Capacity expansion and biofoundry partnerships constitute the dominant competitive moves, with fermentation-derived protein sourcing reshaping R&D budget allocation.
Within the multinational tier, Nestlé S.A., Danone S.A., and Abbott Laboratories exemplify divergent strategic archetypes. Nestlé S.A. anchors its positioning through captive supply chain control over dairy and plant ingredient sourcing. Danone S.A. occupies a specialized position in hypoallergenic lines across European and Asian markets. Abbott Laboratories represents the clinical nutrition science vector through pediatric research network integration. These three entities collectively illustrate how scale, specialization, and scientific differentiation fragment competitive positioning beyond commodity manufacturing.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone S.A. |
| Reckitt Benckiser |
| Abbott Laboratories |
| China Feihe Ltd. |
| Perrigo Company plc |
| Arla Foods amba |
| FrieslandCampina |
| The Kraft Heinz Company |
| Others |
Supply Flow & Price Mechanics
Spray-drying automation retrofits across European manufacturing clusters are compressing quality hold times from 72 hours to 4 hours, simultaneously reducing working capital requirements and consolidating production among capital-rich incumbents who can fund sensor array integration. This technological transition tightens the link between manufacturing sophistication and margin capture, as batch-to-batch consistency becomes a pricing differentiator in SAMR-registered supply chains serving China.
Pricing Analysis
Volume throughput concentrates in conventional formulations while margin capture skews toward hypoallergenic and organic certifications. Three-tier pricing structure across premium, standard, and economy levels separates bioland-certified German products from EFSA-baseline formulations and private-label Southeast Asian supply. Cost compression in standard tiers is intensifying because dairy protein input volatility from New Zealand auction cycles squeezes non-vertically integrated blenders. Pharmacy-dependent first-time parents in US metropolitan markets exhibit lowest price sensitivity; Southeast Asian private-label buyers face highest elasticity.
Supply Chain Analysis
Ocean freight and cold-chain logistics costs from European lactose refiners to Chinese formulation facilities represent a structural cost layer that favors regional manufacturing investment. Pharmaceutical-grade lactose supply draws from Germany, France, and the Netherlands, while spray-dried powder production clusters in Wisconsin, Heilongjiang, and Bavaria. Single-source vulnerability in lactose processing creates exposure when three European suppliers dominate refinement capacity. Distribution runs through pharmacy chains in Italy and Spain, subscription platforms in the UK and Australia, and Tmall cross-border channels for Chinese import demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's SAMR clinical trial mandates have created a supply-constrained environment where registration timelines of 24-36 months prop pricing power for validated incumbents with existing approvals.
For Market Incumbents: Deepen backward integration into dairy and plant ingredient sourcing to buffer margin compression from New Zealand whey auction volatility. Secure SAMR registration renewals early to defend against domestic Chinese brands gaining distribution agility. Prioritize biofoundry partnerships for precision fermentation proteins that enable hypoallergenic lines without animal agriculture exposure. For New Entrants and Emerging Players: Working parents in Sub-Saharan African metropolitan markets represent an underserved buyer archetype with rising disposable income and limited domestic manufacturing competition. Nigeria, Kenya, and South Africa offer import-dependent demand for ready-to-feed formats where established brands have weak pharmacy channel presence. Direct-to-parent subscription platforms with pediatric telehealth integration provide a go-to-market angle that bypasses traditional retail intermediaries. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational dairy conglomerates seeking SAMR registration assets and regional manufacturing footprints. Long-term viability hinges on clinical trial infrastructure and regulatory science capabilities rather than commodity formulation scale. Watch EFSA novel food approval timelines for HMO and probiotic strains as an inflection indicator for premium tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| SAMR Registration Renewal | Secures 24-36 month market access timelines against domestic Chinese brand encroachment. |
| Biofoundry Partnership | Enables precision fermentation proteins for hypoallergenic lines without dairy supply chain exposure. |
| Direct-to-Consumer Platform Launch | Captures first-party consumption data and subscription recurring revenue from pharmacy-defecting parents. |
| Spray-Drying Automation Retrofit | Compresses quality hold times and working capital requirements at existing European facilities. |
| Sub-Saharan Distribution Buildout | Establishes import-dependent supply chains in underpenetrated Nigerian and Kenyan metropolitan markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with infant nutrition formulation scientists, SAMR registration consultants, pediatric dietitians, and pharmacy category buyers. FDA facility inspection reports, EFSA novel food applications, and Chinese customs import statistics provided cross-validation. Bottom-up demand modeling from age-group and formulation-type consumption patterns was reconciled with top-down value estimates from manufacturer revenue disclosures.
Data-stream reconciliation across production volume surveys, retail audit channels, and regulatory approval databases informed the analytical framework. Segmentation dimensions modeled include product format, age targeting, formulation certification tier, and distribution channel structure across the analysis window. CAGRs were derived from curve-fitting historical growth patterns against demographic and regulatory inflection points. SAMR registration timeline data and EFSA additive approval pathways served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAMR policy shifts, EFSA novel food approval delays, and dairy commodity auction volatility. Forecasts reflect documented assumptions about breastfeeding duration trends, dual-income household formation rates, and regulatory science acceleration timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Anti-Spit Up Formula Market
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
BRIC Organic Baby Food Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
Growing Up Formula Market
Baby Food and Infant Formula
Organic Follow Up Formula Market
Baby Food and Infant Formula
Kids Food and Beverages Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
Infant Formula Market
Baby Food and Infant Formula
Global Oligosaccharides in Infant Nutrition Market
Baby Food and Infant Formula
North America Organic Baby Food Market
Baby Food and Infant Formula
Ready to Use Supplementary Food Market