
 Canada Baby Food Market | 2026-2036
Canada Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Baby Food Market Intelligence
A transition toward multi-source ingredient procurement is restructuring supply chain resilience in the Canadian baby food sector. Nestlé S.A. leverages its extensive global supply network, while Kraft Heinz Company competes through established brand recognition in major supermarkets. Loblaws Inc. differentiates with its private-label President's Choice organic line, challenging established brands.
Baby food comprises commercially prepared food products specifically formulated to meet the nutritional needs of infants and toddlers, typically from four months to two years of age. These products often undergo processes like pureeing and fortification with iron, vitamin D, and other essential nutrients. While purees and cereals remain foundational product types, organic variants and portable snacks represent the fastest-growing segments. Sales through online retailers are expanding rapidly, challenging the dominance of traditional supermarkets and hypermarkets.
Health Canada establishes the regulatory framework, setting strict standards for the nutritional composition, safety, and labeling of baby food products. The Canadian Food Inspection Agency (CFIA) enforces these regulations, ensuring compliance across all domestically produced and imported items. These rules directly influence ingredient sourcing and product claims. Navigating evolving parental preferences for clean ingredients and sustainable packaging remains a central challenge for all manufacturers.
Market Dynamics
The primary force shaping the Canadian baby food market is the consumer demand for clean-label, organic products, which directly interacts with the stringent nutritional and safety framework enforced by Health Canada and the CFIA.
Growth Catalysts
- Parental Health Consciousness:Demand from guardians in urban centers like Toronto and Montreal for organic, non-GMO, and minimal-ingredient products is a primary market accelerator.
- Mandatory Fortification Standards:Health Canada's requirements for iron and vitamin D fortification in infant formulas and cereals create a consistent quality floor and drive product development.
- E-commerce Channel Expansion:The growth of online retail platforms provides greater consumer access to specialty and emerging brands, particularly outside of central Canada.
Market Restraints
- High Input Costs:The price volatility and limited domestic supply of certified organic fruits, vegetables, and grains place upward pressure on production costs for manufacturers.
- Regulatory Compliance Burden:Navigating the CFIA's rigorous import inspections and labeling verification processes for ingredients sourced outside Canada can lead to delays and added expense.
- Climate-Related Supply Risks:Supply chain stability is challenged by the concentration of key agricultural inputs in specific Canadian regions, such as the Prairies, which are vulnerable to drought.
Strategic Opportunities
- Plant-Based Formulations:There is a clear opening for developing and marketing plant-based baby foods, including oat and pea protein variants, to cater to families seeking dairy alternatives.
- Sustainable Packaging:Adopting fully recyclable or compostable packaging, such as glass jars or mono-material pouches, aligns with consumer values and offers a point of differentiation.
- Targeting New Demographics:Products tailored to the nutritional preferences and needs of Canada’s diverse immigrant communities represent a significant, under-served market segment.
Industry Challenges
- Ingredient Traceability:Ensuring end-to-end traceability and verifying organic certification across complex, multi-source global supply chains presents a significant operational hurdle for manufacturers.
- Marketing Claim Restrictions:Companies face the challenge of communicating product benefits effectively while adhering to Health Canada's strict rules against unsubstantiated health or nutrient claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Baby Food Market |
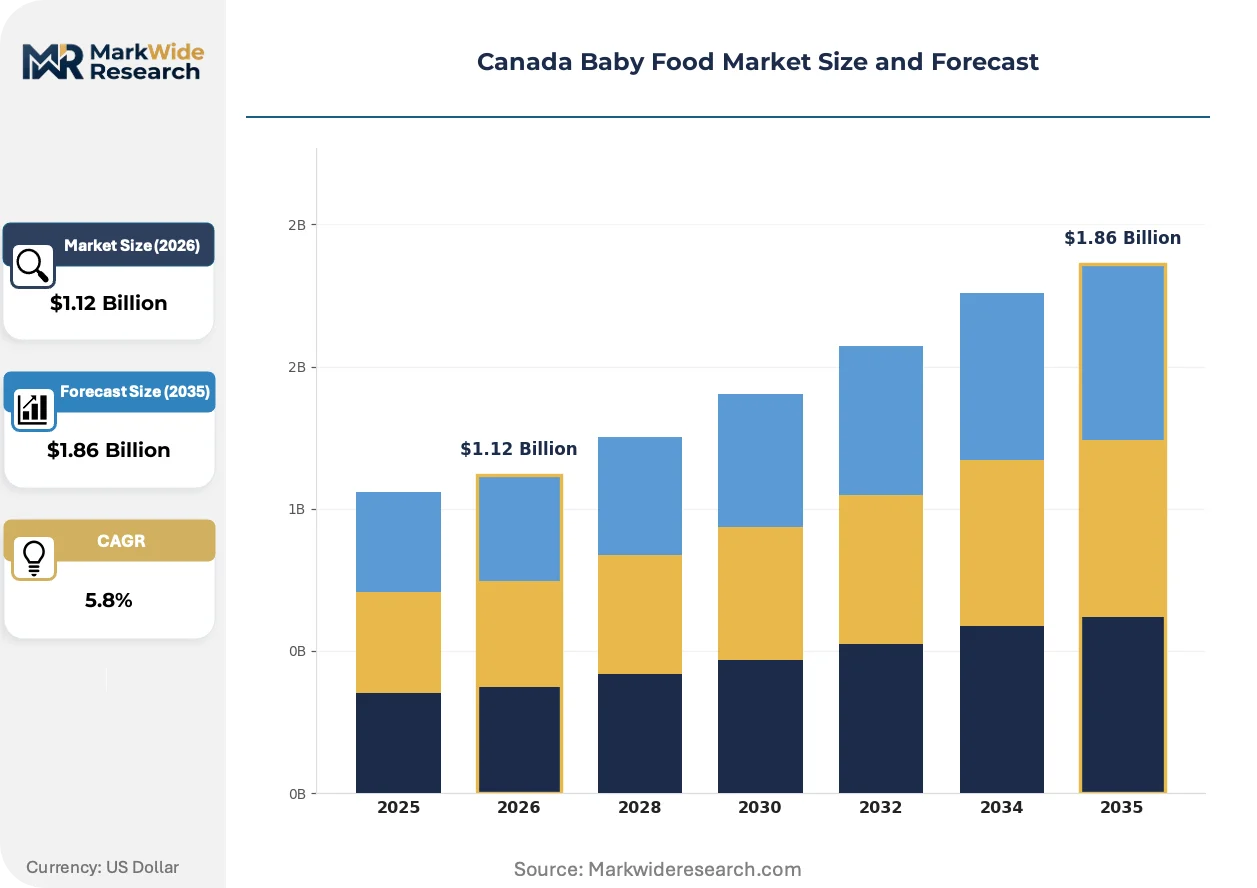
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $1.86 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purees, Cereals, Snacks, Dairy-Based, Juice Drinks, Organic Variants Distribution Channel: Supermarkets & Hypermarkets, Online Retailers, Pharmacies, Specialty Stores, Convenience Stores Packaging Type: Glass Jars, Plastic Pouches, Tetra Packs, Cans, Sachets, Jar Packs Consumer Demographic: Urban Parents, Working Mothers, Caregivers, Grandparents, First-Time Parents, Health-Conscious Guardians |
| Companies Covered | Mead Johnson & Company LLC, Plum, PBC, Nestlé S.A., Kraft Heinz Company, Loblaws Inc., Danone, Hain Celestial, Diana Group, Abbott, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Baby Food Market Strategic Shifts & Innovations
Product development in the Canadian baby food market is increasingly influenced by the intersection of data-driven nutritional science and consumer demand for sustainability. This synthesis is creating new product categories and altering manufacturing priorities.
Advanced formulation software allows for the rapid optimization of ingredient blends to meet specific nutritional targets. R&D teams in the Canadian market are adopting these tools to accelerate the creation of new recipes for purees and snacks. This adoption is automating the complex process of verifying compliance with Health Canada’s nutrient content regulations, reducing development cycles.
Health Canada's proposed front-of-package (FOP) nutrition labeling system is a significant regulatory development for the sector. The policy is forcing manufacturers to evaluate and reformulate products to minimize levels of sodium, sugar, and saturated fat. The organic baby food segment is particularly impacted, balancing the use of natural fruit sugars against the proposed FOP thresholds.
A clear behavioral shift involves parents adopting subscription-based purchasing models for baby food, especially in Canada's major cities. This direct-to-consumer (DTC) channel disrupts the reliance on traditional supermarket sales by offering convenience and personalization. The trend is most visible in technology-forward urban centers like Vancouver and Toronto.
Canada Baby Food Market Segmentation
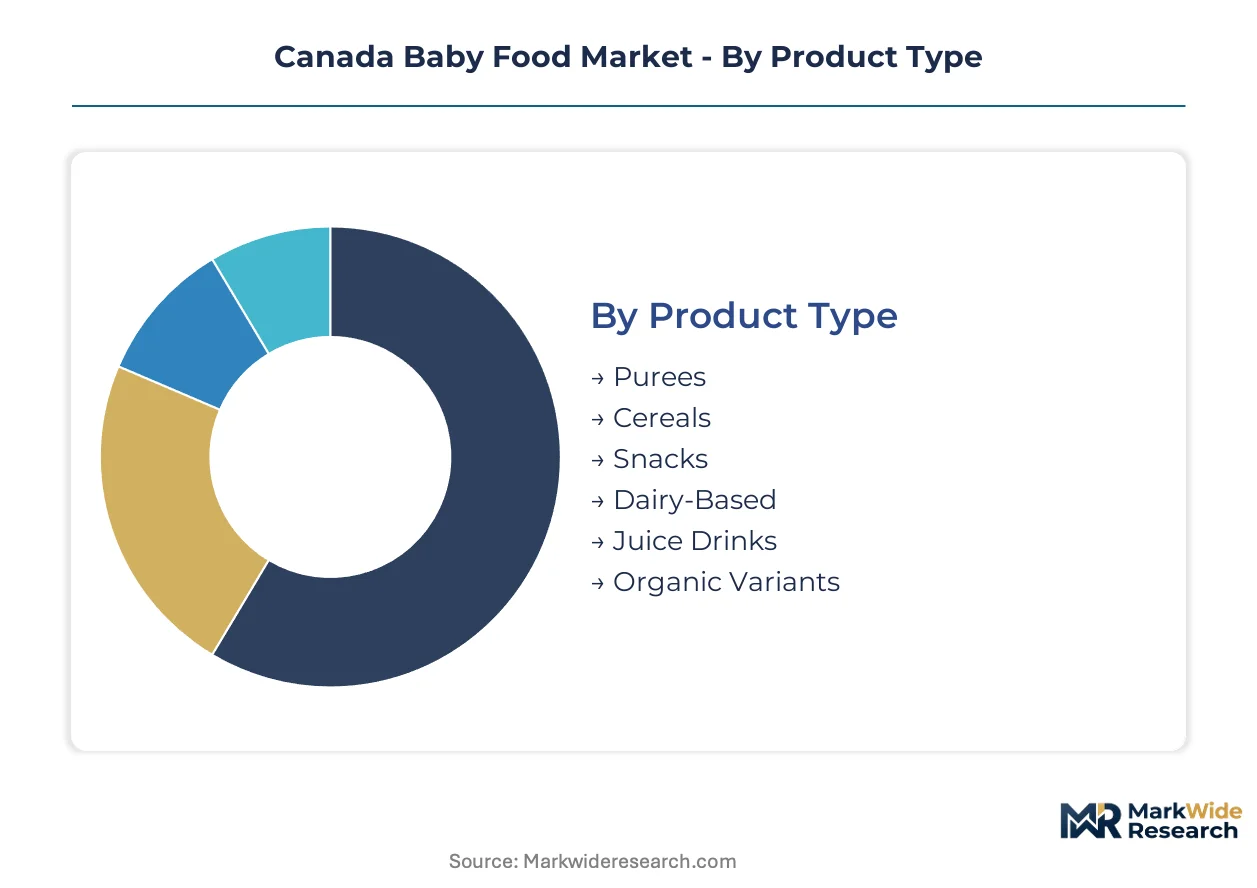
Understanding the Canada baby food market requires segmenting consumer preferences and product attributes. This segmentation illuminates the varied demands driving product development and distribution strategies across Canadian provinces. Manufacturers tailor offerings to specific consumer needs and purchasing behaviors.
Product Type:
Buyers in the Canadian baby food market differentiate products based on their core nutritional composition and intended use.
- Organic Variants:These products are formulated using ingredients grown without synthetic pesticides or fertilizers, appealing to health-conscious guardians. Demand for organic baby food concentrates in urban centers like Toronto and Vancouver, driven by parental health consciousness and clean-label preferences.
- Purees:Comprising single or multi-ingredient blends of fruits, vegetables, or meats, purees are foundational for infant weaning. Sales of purees remain strong across all major Canadian supermarkets, supported by established brand recognition and widespread availability.
- Cereals:Fortified infant cereals, often rice or oat-based, provide essential nutrients for developing babies.
- Snacks:Portable and finger-friendly options like puffs, rusks, and fruit bites cater to toddlers and busy parents.
- Dairy-Based:Products such as infant formula and yogurt-based purees offer crucial protein and calcium for infant development.
- Juice Drinks:Fruit or vegetable juice blends specifically formulated for infants and toddlers provide hydration and vitamins.
Volume sits with Purees; growth tilts toward Organic Variants.
Distribution Channel:
Access to baby food products varies significantly depending on the reach and convenience offered by different retail environments.
- Online Retailers:E-commerce platforms provide extensive product selection and home delivery services, expanding consumer access to specialty brands. This channel is gaining share fastest in technology-forward urban centers, disrupting traditional retail dominance.
- Supermarkets & Hypermarkets:These large-format stores offer a wide array of baby food brands and competitive pricing, serving as the primary purchasing point for most Canadian families. Their extensive geographic footprint ensures broad market penetration across all provinces.
- Pharmacies:Retail pharmacies often stock essential baby food items, particularly infant formula and specialized dietary options.
- Specialty Stores:Organic and natural food stores cater to niche consumer demands for premium and health-focused baby food products.
- Convenience Stores:These smaller outlets provide quick access to basic baby food necessities for on-the-go purchases.
Supermarkets & Hypermarkets generate the largest sales; Online Retailers are expanding most quickly.
Packaging Type:
Consumer preference for baby food packaging is heavily influenced by factors such as convenience, perceived safety, and environmental impact.
- Plastic Pouches:Lightweight, squeezable pouches offer convenience and portability for on-the-go feeding, particularly popular with working mothers. This format sees high demand in urban areas due to its ease of use and reduced mess.
- Glass Jars:Traditional glass jars are favored for their perceived safety and recyclability, often associated with premium and organic products. Health-conscious guardians frequently choose glass jars for their clean aesthetic and inert material properties.
- Tetra Packs:Aseptic carton packaging primarily used for baby juices and milk-based products provides extended shelf life.
- Sachets:Small, single-serving sachets are common for infant cereals and powdered formulas, offering precise portion control.
- Cans:Metal cans are used for certain specialized infant formulas or toddler meals, providing robust protection.
- Jar Packs:Multi-pack options of glass jars offer value and bulk purchasing convenience for regular consumers.
Glass Jars maintain a significant market presence; Plastic Pouches are gaining share fastest.
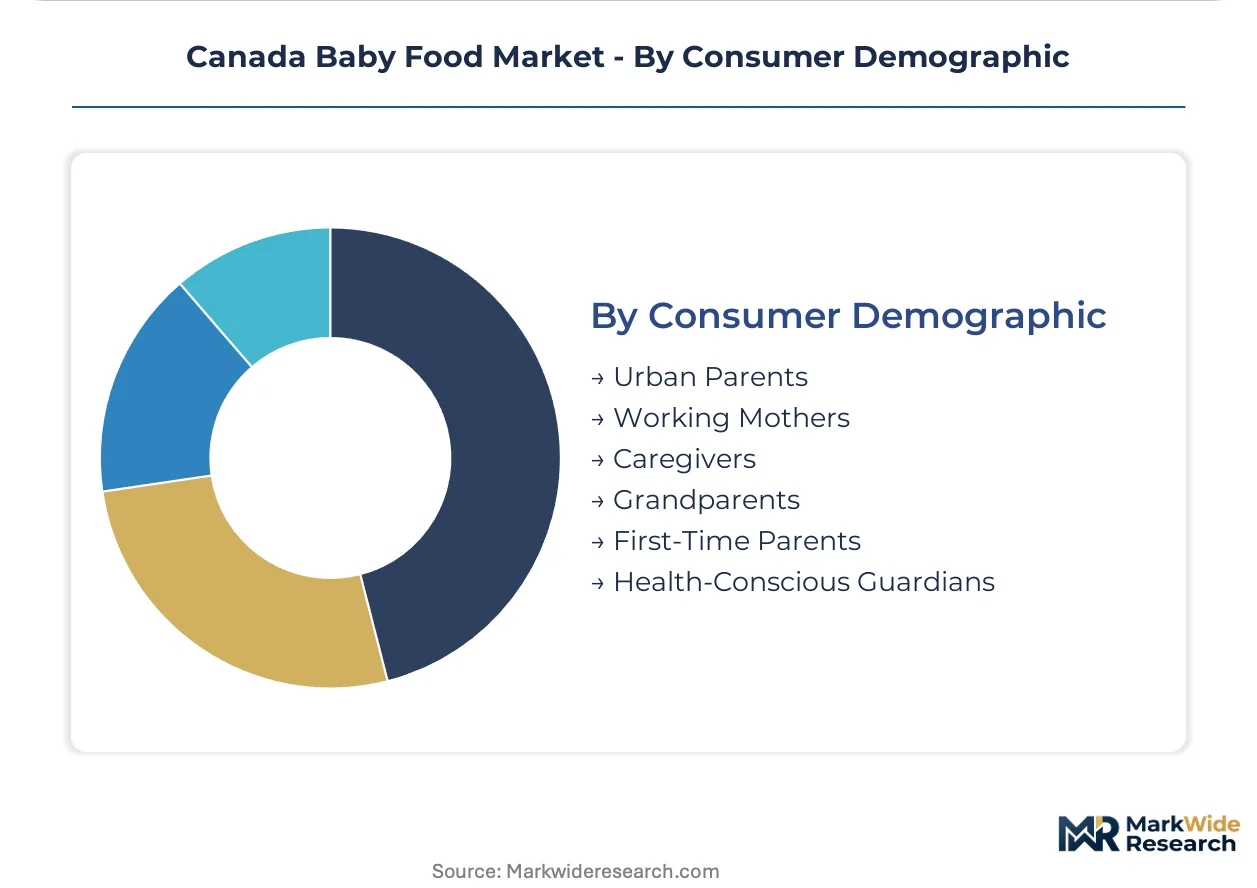
Consumer Demographic:
Different consumer groups approach baby food purchasing with distinct priorities, influencing product innovation and marketing efforts.
- Health-Conscious Guardians:These consumers prioritize organic, non-GMO, and minimal-ingredient products, often researching nutritional labels extensively. Their demand drives the growth of premium and clean-label segments, particularly in affluent urban centers.
- First-Time Parents:New parents often seek guidance and reassurance, opting for well-known brands and products endorsed by pediatricians. This demographic represents a consistent entry point for baby food manufacturers across Canada.
- Urban Parents:City dwellers value convenience, portability, and access to a wider range of specialty and organic options.
- Working Mothers:Time-saving solutions like pre-prepared meals and easy-to-use packaging appeal strongly to this demographic.
- Caregivers:Grandparents and other caregivers often purchase familiar, trusted brands and value clear nutritional information.
- Grandparents:This group often prioritizes traditional, wholesome ingredients and seeks products reminiscent of homemade baby food.
First-Time Parents represent a consistent market entry point; Health-Conscious Guardians show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's vast agricultural landscape anchors the baby food market, with diverse regions contributing essential raw materials. The Prairie provinces, for example, supply grains crucial for infant cereals. This regional specialization influences product availability and supply chain logistics across the country.
Ontario
Demand for organic and clean-label baby food drives significant market activity across Ontario's urban centers. Health Canada's stringent nutritional guidelines shape product formulation and marketing claims for manufacturers operating within the province. Toronto's large, diverse population supports a wide array of specialty and ethnic baby food offerings, reflecting evolving parental preferences.
Quebec
Quebec's strong consumer preference for locally sourced products influences baby food procurement and sales strategies. The provincial government's support for local agriculture indirectly benefits ingredient sourcing for regional baby food brands. Montreal serves as a hub for both established and emerging baby food companies, leveraging its robust distribution networks across Eastern Canada.
British Columbia
British Columbia exhibits high demand for plant-based and sustainable baby food options, reflecting its health-conscious consumer base. The Canadian Food Inspection Agency (CFIA) ensures compliance with food safety and labeling standards for all products sold within the province. Vancouver's technology-forward urban environment fosters rapid expansion of online retail channels, disrupting traditional supermarket dominance.
Alberta
Alberta's growing young family demographic fuels consistent demand for foundational baby food products like purees and cereals. Health Canada's mandatory fortification standards ensure a consistent quality floor for all infant cereals available across the province. Calgary's expanding suburban areas drive sales through large-format supermarkets and hypermarkets, catering to family-oriented purchasing patterns.
Canada Baby Food Market Key Industry Players
Portfolio diversification dominates the current landscape, as companies adapt to evolving parental preferences. The Canada baby food market exhibits a tiered competitive structure, with multinational corporations competing alongside established domestic players and niche organic brands. Strategic archetypes include global food giants, national private-label specialists, and agile e-commerce-focused startups. Geographic expansion and sustainable packaging initiatives are two dominant competitive moves.
At the scale-driven end, Nestlé S.A. exemplifies a global food conglomerate leveraging its extensive supply network for broad product availability. Kraft Heinz Company, a North American food giant, occupies a position anchored by established brand recognition across major supermarkets. Loblaws Inc., a prominent Canadian retailer, represents the growing influence of private-label offerings with its President's Choice organic line, challenging established brands through differentiation. These entities collectively shape the market's competitive dynamics, each employing distinct strategies to address consumer demands and regulatory requirements.
| Leading Market Players |
|---|
| Mead Johnson & Company LLC |
| Plum, PBC |
| Nestlé S.A. |
| Kraft Heinz Company |
| Loblaws Inc. |
| Danone |
| Hain Celestial |
| Diana Group |
| Abbott |
| Others |
Cost & Logistics Intelligence
The certified organic premium in Canada's baby food market creates a distinct pricing tier and necessitates a specialized, often global, supply chain for compliant ingredients. This divergence between organic and conventional products influences procurement strategies and consumer access.
Pricing Analysis
Product quality and safety certifications, particularly for organic and non-GMO claims, significantly influence the pricing structure for Canadian baby food. The dominant pricing model is value-based, reflecting ingredient quality and brand perception. Price differentiation drivers include organic certification level and specialized ingredient sourcing costs. Pricing softness affects conventional purees due to supermarket competition, while premium organic snacks maintain higher margins. Health-conscious guardians exhibit lower price sensitivity for organic products, unlike first-time parents prioritizing affordability in foundational items.
Supply Chain Analysis
Adherence to Health Canada's strict nutritional and safety standards acts as a critical qualification gate for all ingredients entering the baby food supply chain. Geographic supply concentration for organic grains often includes the Canadian Prairies and select US states, while specialty fruits may come from California or Mexico. Raw material dependencies include organic fruits, vegetables, and fortified grains. A structural risk is commodity price volatility for certified organic inputs. Distribution runs through a hybrid model, combining large-format supermarkets with rapidly expanding online retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canadian baby food market is currently a consolidation play, driven by the intense regulatory compliance burden that smaller, undercapitalized brands struggle to meet. This pressure forces weaker players out or into acquisition by larger entities.
For Market Incumbents: Lock in long-term supply contracts for certified organic ingredients to mitigate commodity price volatility. Diversify product portfolios with plant-based formulations to counter the threat of dairy alternatives and evolving dietary preferences. Invest in sustainable packaging R&D to maintain brand relevance against agile e-commerce startups. Leverage extensive distribution networks to outcompete smaller brands in traditional retail channels.
For New Entrants and Emerging Players: Online specialty retailers provide a low-cost entry point for innovative baby food brands seeking direct consumer engagement. Target the urban parent demographic in Vancouver and Toronto with subscription-based models for premium, clean-label snacks. Focus on plant-based formulations and novel protein sources to capture white space. A direct-to-consumer go-to-market angle allows for rapid feedback and product iteration.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated, clean-label specialists with strong e-commerce penetration. Long-term viability over the next decade hinges on brands demonstrating clear differentiation in sustainability and specialized nutrition. Target acquisition archetypes include agile startups focusing on plant-based or ethnic formulations. A signal to watch is the sustained growth rate of subscription-based baby food services in major urban centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Plant-Based Portfolio | Nestlé S.A. can capture dairy-alternative demand from health-conscious guardians. |
| Invest in Sustainable Packaging | Loblaws Inc. can differentiate its President's Choice organic line with compostable materials. |
| Enhance E-commerce Distribution | Kraft Heinz Company can expand reach beyond traditional supermarkets to urban parents. |
| Local Ingredient Sourcing Partnerships | Regional brands can strengthen supply chain resilience against climate-related risks. |
| Develop Ethnic-Specific Formulations | New entrants can target Canada’s diverse immigrant communities with tailored products. |
Research Approach
Document review covered Health Canada guidelines, CFIA enforcement reports, and national retail sales data, complemented by interviews with industry stakeholders. Primary research involved discussions with baby food product development executives, procurement managers, and category buyers at major Canadian retailers. Secondary validation drew from academic nutritional studies, trade association publications, and company annual reports. This approach ensured robust bottom-up and top-down triangulation of market insights.
Volume and value projections were generated through a proprietary analytical framework, leveraging historical market performance and future growth drivers. Segmentation dimensions modeled included product type (purees, organic variants), distribution channel (online, supermarkets), packaging type (pouches, jars), and consumer demographic (health-conscious, first-time parents). Compound Annual Growth Rates (CAGRs) were derived from a regression analysis of identified market accelerators over the projection horizon. Key forecast inputs included birth rates and per capita spending on specialty food items.
Caveats apply where sudden shifts in Health Canada's nutritional mandates or significant changes in consumer purchasing power could materially shift the outlook. Forecasts reflect assumptions regarding stable regulatory environments and consistent parental preferences for clean-label products. A model refresh is warranted upon material change in e-commerce adoption rates or major agricultural input costs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Asia Pacific Organic Baby Food Market
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
A2 Infant Formula Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
Growing Up Formula Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
Kids Food and Beverages Market